
 Italy Plastic Caps and Closures Market | 2026-2036
Italy Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Plastic Caps and Closures Market Insights
Premium-grade closure specifications is unwinding price competition at the lower tiers. Guala Closures S.p.A leverages its wine and spirits heritage to dominate high-value dispensing formats. Bericap Holding GmbH anchors its position through backward integration into resin handling and color masterbatch operations. Bosisio Francesco & C. SpA specializes in custom flip-top designs for regional cosmetic houses.
Plastic caps and closures are injection- or compression-molded sealing devices, typically manufactured from polyolefin resins with thread geometries measured in millimeter pitch tolerances, designed to preserve contents, enable controlled dispensing, and signal tamper evidence across liquid and semi-solid packaging. Polypropylene leads material selection for hot-fill and carbonated applications due to its thermal stability and hinge fatigue resistance, while polyethylene occupies cost-sensitive water and dairy segments where stress-crack resistance matters less. Screw caps retain the largest volume share in Italian wine and edible oil packaging, though flip-top formats are gaining fastest in personal care and household chemicals where one-handed dispensing drives consumer preference.
Italy's Ministry of Health enforces EU Regulation 10/2011 on plastic materials intended for food contact, while EFSA evaluates migration thresholds that directly constrain resin grades and additive packages available to domestic molders. BIS voluntary certifications and CONAI packaging consortium fees further shape material choices and lightweighting incentives for Italian converters. Stakeholders must monitor pending EU Packaging and Packaging Waste Regulation revisions that will mandate recycled content minimums and redesign protocols before committing to new tool investments.
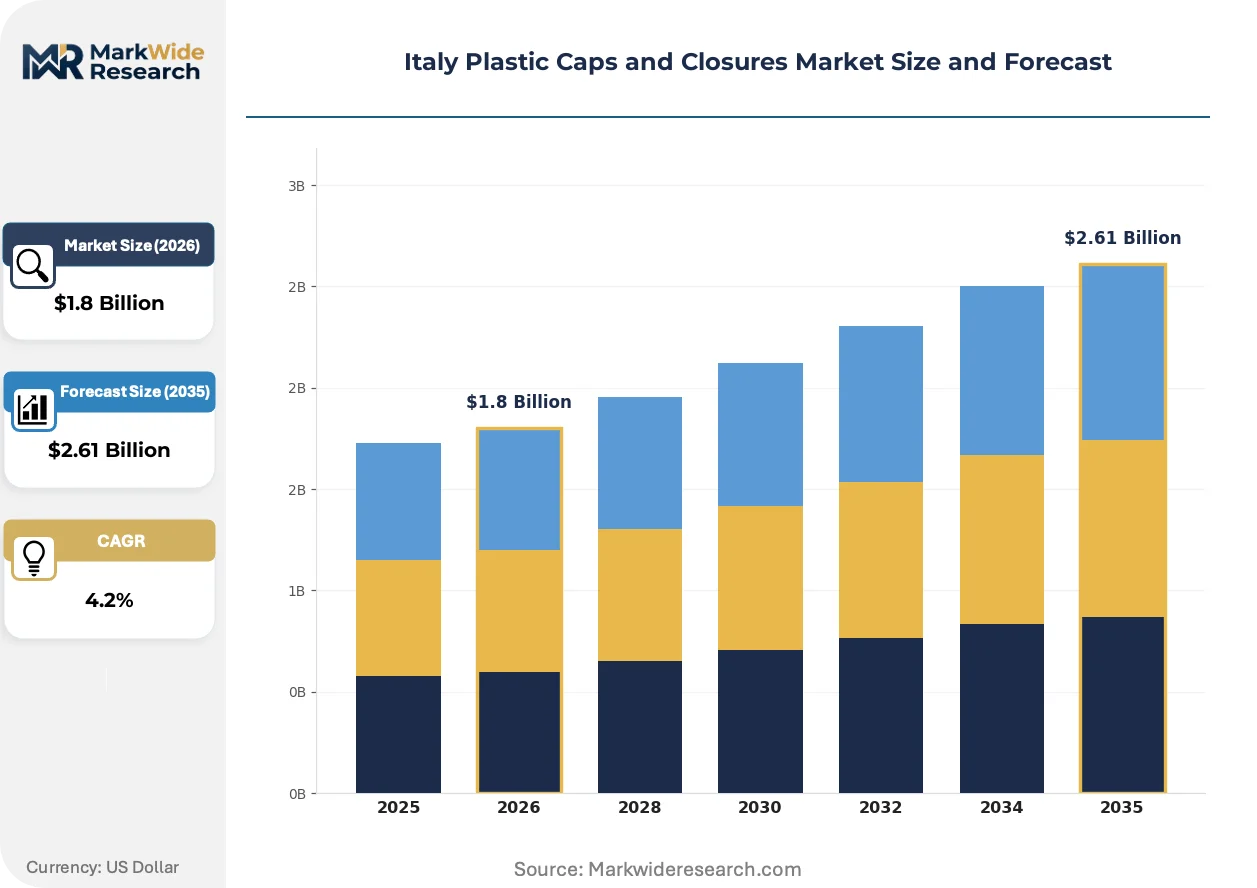
Market Dynamics
EFSA migration limit revisions are compressing resin formulation options for Italian molders, forcing rapid qualification of alternative additive packages while beverage bottlers simultaneously expand tamper-evident closure specifications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Pending recycled content mandates are accelerating tooling investments in post-consumer polypropylene processing lines across Emilia-Romagna.
- Hot-fill beverage expansion:Italian olive oil and tomato sauce exporters are specifying polypropylene screw caps with induction seals for extended shelf stability in North American retail.
- Lombardy injection molding density:Proximity to resin compounders and color masterbatch specialists reduces logistics costs for cosmetic closure converters serving Milan-based personal care brands.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Rotterdam-Antwerp corridor transmit directly to Italian polypropylene contract pricing.
- Single-source tooling dependency:High-cavitation mold fabrication concentrates among German and Austrian suppliers, extending lead times for Italian converters.
- Glass substitution in premium wine:Traditional cork-stopper resurgence in DOCG-tier bottlings constrains screw cap penetration in heritage appellations.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily bottling facilities remain served by northern logistics, creating white space for regional molding capacity.
- Pharmaceutical child-resistant formats:EMA packaging guidelines for oral solid doses are expanding demand for senior-friendly yet compliant closure designs.
- Digital printing convergence:Laser-marking and direct-cap decoration technologies enable lot-traceability without label application, attracting traceability-focused food exporters.
Industry Challenges
- Migration testing backlog:EFSA notification queues for novel additive approvals extend qualification timelines for reformulated resin grades.
- Multi-cavity mold commissioning:Validation protocols for 96-cavity hot-runner systems demand specialized technician availability scarce in Italian toolrooms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Plastic Caps and Closures Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top Caps, Screw Caps, Snap-on Caps, Corks Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Closure Type: Airtight, Tamper-proof, Child-resistant, Dispensing End User: Food & Beverage, Healthcare, Personal Care, Household Products |
| Companies Covered | Giflor Srl, Bericap Holding GmbH, Berry Global Inc., Bosisio Francesco & C. SpA, Sacmi Imola S.C., Aptar Group Inc., Wisecap Group, Guala Closures S.p.A, Pelliconi & C. SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Plastic Caps and Closures Market Trends and Innovations
Italian closure converters are retooling around three concurrent pressures: regulatory migration limits, recycled feedstock integration, and dispensing-format premiumization in personal care.
Mono-material polypropylene designs are decomposing multi-component closure assemblies previously combining polyethylene liners with polypropylene shells. Wine and edible oil bottlers in Tuscany and Piedmont are specifying these simplified formats to meet forthcoming EU recyclability labeling criteria. The shift is compressing demand for separate liner injection molding capacity while expanding investment in hinge-fatigue-optimized homopolymer grades.
EFSA's evolving specific migration limits for mineral oils and photoinitiators are constraining additive packages available to Italian food-contact molders. The industrial consequence is accelerated substitution of conventional nucleating agents with bio-based alternatives qualified under updated EU Regulation 10/2011 positive lists. Small-batch olive oil producers in Liguria are absorbing reformulation costs fastest, pressing compounders for rapid certification turnaround.
Beverage bottlers are consolidating supplier panels and demanding integrated closure-liner-label procurement bundles. This consolidation is displacing standalone closure vendors who lack decoration or logistics capabilities. The pattern is most visible among mineral water brands in Lombardy, where three-buyer concentration now represents a critical threshold for vendor qualification.
Italy Plastic Caps and Closures Market Segmentation
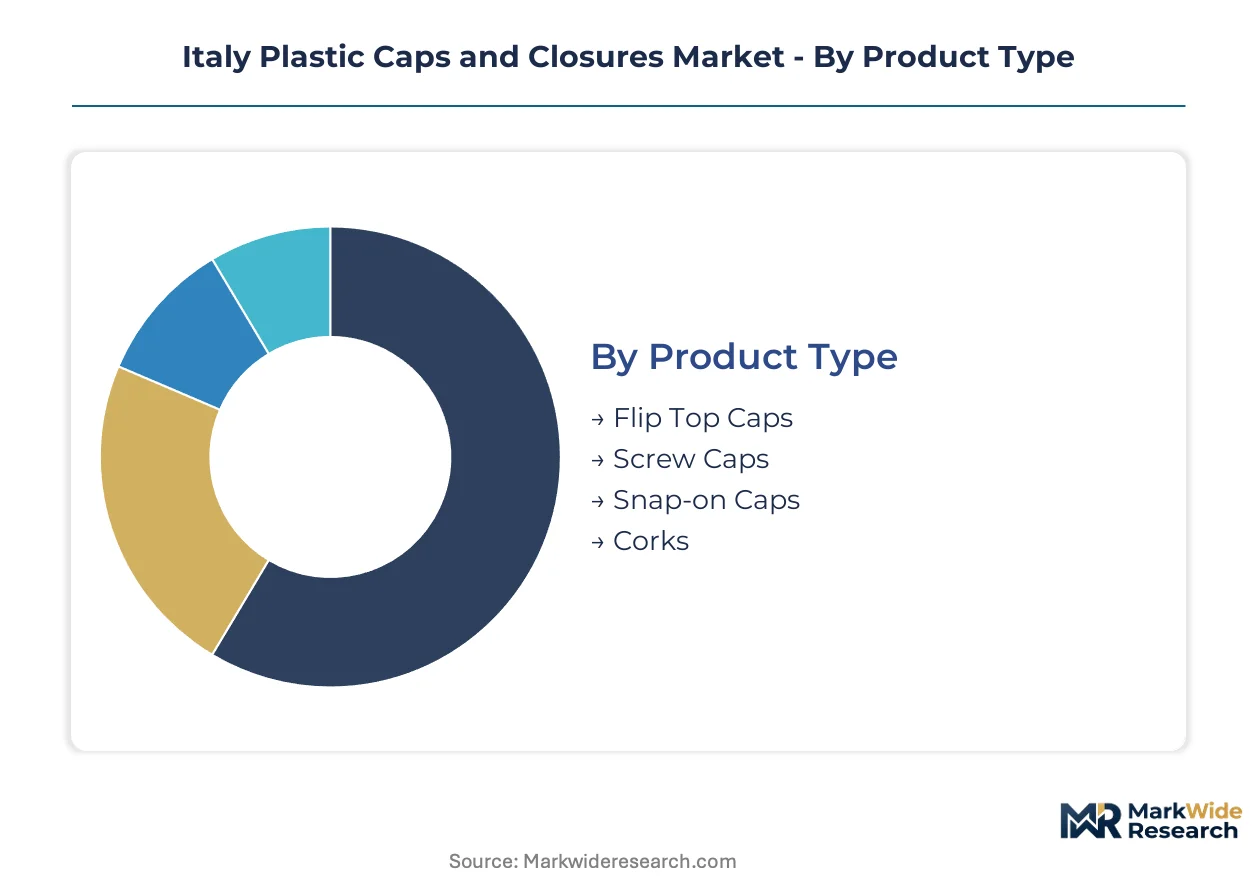
Segmentation in Italy's plastic caps and closures market reveals where substitution threats from alternative packaging formats are reshaping supplier priorities. Closure converters must align tooling investments with the specific performance tiers and regulatory exposures that each segment presents.
Product Type:
Screw caps face the most acute substitution pressure from natural cork in premium wine, while flip-top formats compete against pump dispensers in personal care.
- Screw Caps:Threaded polypropylene or polyethylene designs with standardized neck finishes dominate Italian wine and edible oil packaging. Tuscan and Piedmont bottlers specify these for export markets despite cork's resurgence in DOCG-tier domestic sales.
- Flip Top Caps:Hinged polypropylene constructions enable one-handed dispensing for shampoos and household cleaners. Milan-based cosmetic brands are consolidating procurement around these formats, displacing traditional screw closures in premium personal care lines.
- Snap-on Caps:Compression-fit polyethylene closures serve cost-sensitive water and dairy segments where thread precision adds unnecessary expense.
- Corks:Natural and synthetic stopper alternatives constrain plastic penetration in heritage wine appellations, though screw caps retain volume in commercial table wines.
Screw caps anchor the volume base while flip-top caps gain share at the steepest rate.
Material:
Cost tiers separate commodity resins from performance grades, with thermal stability requirements driving the sharpest differentiation.
- Polypropylene:Homopolymer and random copolymer grades deliver hinge fatigue resistance and hot-fill compatibility. Emilia-Romagna injection molders favor this resin for carbonated beverage and sauce applications where induction sealing is required.
- Polyethylene:HDPE and LDPE variants occupy water and dairy closures where stress-crack resistance is secondary to raw material economy. Lombardy converters serving large-format mineral water brands run dedicated polyethylene lines.
- Polyvinyl Chloride:Specialized plastisol-lined closures persist in niche pharmaceutical and chemical applications despite regulatory scrutiny.
- Polystyrene:Crystal and high-impact grades appear in cosmetic overcaps and display packaging where rigidity and surface gloss outweigh environmental concerns.
Polypropylene commands the highest value per kilogram while polyethylene moves the largest tonnage through Italian compounding channels.
Closure Type:
Application-specific functionality determines which converters can qualify for beverage versus pharmaceutical supply panels.
- Tamper-proof:Break-band or shrink-sleeve integrated designs are expanding fastest as EFSA migration limits tighten and bottlers seek integrated compliance solutions. Northern Italian water brands now mandate these for all retail formats.
- Airtight:Induction-seal compatible thread profiles with liner retention features preserve shelf stability for olive oil and tomato sauce exporters targeting North American retail.
- Child-resistant:Senior-friendly yet compliant push-and-turn mechanisms serve oral solid dose packaging under EMA guidelines, with demand concentrating among Lombardy pharmaceutical contract manufacturers.
- Dispensing:Orifice reducers and flip-top spouts enable controlled flow for household chemicals and personal care products.
Airtight closures retain the broadest end-use coverage while tamper-proof specifications are climbing the fastest.
End User:
Customer-type concentration in northern manufacturing clusters shapes logistics and qualification requirements for converters.
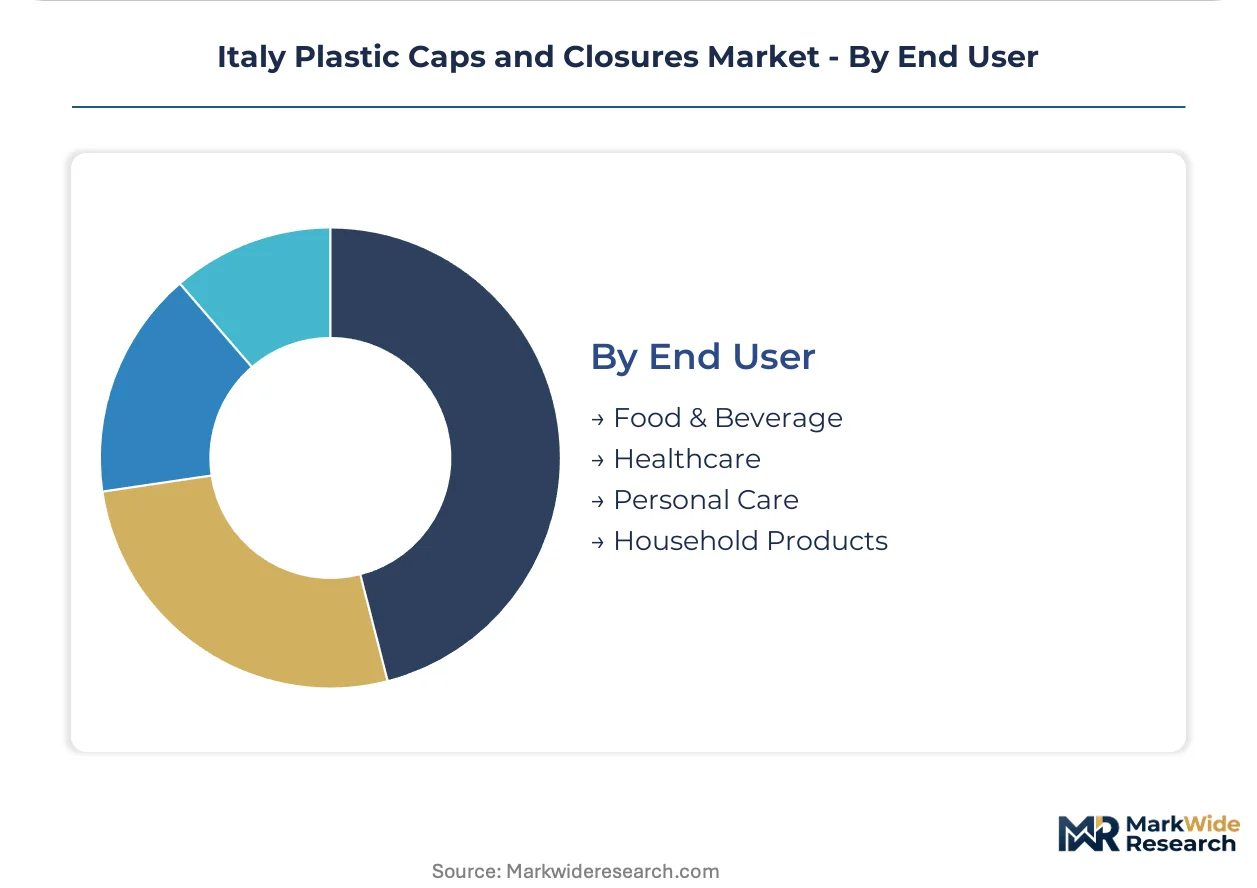
- Food & Beverage:Wine, edible oil, mineral water, and sauce bottlers in Emilia-Romagna and Tuscany drive the largest closure volumes. EU Regulation 10/2011 compliance is non-negotiable for this segment.
- Personal Care:Milan-based cosmetic houses and regional fragrance compounders specify custom colors and surface finishes that demand captive masterbatch operations.
- Healthcare:Pharmaceutical packaging contractors around Lombardy require child-resistant and senior-friendly formats validated under EMA protocols.
- Household Products:Cleaning chemical bottlers prioritize chemical resistance and dispensing control over aesthetic differentiation.
Food and beverage anchors the volume base while personal care commands the steepest premium expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian molders cluster in northern manufacturing belts where resin compounders and beverage bottlers sit within 150-kilometer radii. This proximity compresses logistics costs and accelerates qualification cycles for food-contact closure grades.
Lombardy
Milan-based cosmetic houses drive demand for custom flip-top formats with captive color-matching requirements. BIS voluntary certifications shape material selection for converters serving personal care brands. High-cavitation injection molding lines concentrate around Brescia and Bergamo, where technicians specialize in multi-cavity hot-runner commissioning.
Emilia-Romagna
Tomato sauce and olive oil exporters specify polypropylene screw caps with induction-seal compatibility for North American retail. EU Regulation 10/2011 enforcement by Italy's Ministry of Health constrains additive packages available to Bologna-area compounders. Tooling investments in post-consumer polypropylene processing lines are accelerating across Modena and Parma ahead of recycled content mandates.
Piedmont
Wine bottlers in Alba and Asti balance screw cap volume against cork resurgence in DOCG-tier domestic sales. EFSA migration limit revisions for mineral oils are compressing resin formulation options for local molders. Injection molding infrastructure in Turin's industrial periphery supports both beverage closures and automotive component crossover capacity.
Veneto
Mineral water brands around Verona mandate tamper-evident specifications for all retail formats as compliance requirements tighten. CONAI packaging consortium fees incentivize lightweighting investments among regional converters. Padua-based masterbatch specialists supply color-matched formulations to cosmetic closure producers serving nearby fragrance compounders.
Tuscany
Small-batch olive oil producers in Liguria absorb reformulation costs fastest, pressing compounders for rapid certification turnaround under updated EU Regulation 10/2011 positive lists. EFSA notification queues for novel additive approvals extend qualification timelines for Lucca-area molders. Siena and Florence bottlers specify mono-material polypropylene designs to meet forthcoming EU recyclability labeling criteria.
Italy Plastic Caps and Closures Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium dispensing specialists commanding margin premiums while commodity converters compete on cycle-time efficiency. The vendor base stratifies across three tiers: integrated multinationals with captive resin handling, mid-cap specialists with backward integration into color masterbatch operations, and regional custom houses serving single end-use categories. Dominant competitive moves include supplier panel consolidation by beverage bottlers and accelerated tooling investments for recycled feedstock processing.
Among Italy-based heritage specialists, Guala Closures S.p.A occupies a position exemplifying wine and spirits dispensing expertise, while Bosisio Francesco & C. SpA represents the custom design archetype for regional cosmetic houses. Bericap Holding GmbH anchors the multinational integrated tier with upstream control over resin handling operations. These three entities collectively illustrate how competitive positioning diverges across premium dispensing, custom fabrication, and commodity scale vectors.
| Leading Market Players |
|---|
| Giflor Srl |
| Bericap Holding GmbH |
| Berry Global Inc. |
| Bosisio Francesco & C. SpA |
| Sacmi Imola S.C. |
| Aptar Group Inc. |
| Wisecap Group |
| Guala Closures S.p.A |
| Pelliconi & C. SpA |
| Others |
Pricing and Supply Chain Analysis
High-cavitation injection molding capacity utilization in Emilia-Romagna and Lombardy shapes price floors for Italian converters, compressing margins at sub-scale competitors while rewarding operators with 96-cavity hot-runner systems and backward integration into resin handling. EU Regulation 10/2011 compliance costs and EFSA migration testing fees create tiered entry barriers that stratify pricing power across certification-holding incumbents versus uncertified regional players.
Pricing Analysis
EU Regulation 10/2011 dictates the pricing tier structure across Italian plastic caps and closures, separating food-contact-certified molders from commodity converters lacking Ministry of Health approvals. Three-tier pricing structure across premium dispensing, standard screw-cap, and economy snap-on levels reflects hinge-fatigue performance and induction-seal compatibility rather than resin cost alone. Cost compression in economy polyethylene water closures is intensifying because Lombardy mineral water brands consolidate procurement panels and demand integrated closure-liner-label bundles. Small-batch olive oil producers in Tuscany exhibit highest price sensitivity, while Milan-based cosmetic houses absorb premiums for custom color-matched flip-top formats with captive masterbatch operations.
Supply Chain Analysis
Rotterdam-Antwerp corridor port congestion and container availability fluctuations on the Rhine-Main-Danube inland waterway transmit directly to Italian polypropylene contract pricing, amplifying feedstock volatility for Emilia-Romagna compounders. Raw material sourcing draws from Saudi Arabian and Qatari propylene exports, Belgian naphtha-cracker output, and domestic Bologna-area resin compounders with limited captive supply. Single-source dependency on German and Austrian high-cavitation mold fabricators concentrates tooling risk, extending lead times for 96-cavity hot-runner system commissioning. Distribution runs through northern Italian logistics clusters serving beverage bottlers within 150-kilometer radii, with Campania and Sicily bottling facilities remaining underserved by regional molding capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping supplier-buyer relationships as beverage bottlers demand integrated closure-liner-label procurement bundles, creating interoperability lock-in that favors converters with decoration and logistics capabilities over standalone molders.
For Market Incumbents: Compound defensive positioning by accelerating post-consumer polypropylene processing line investments ahead of EU Packaging and Packaging Waste Regulation recycled content mandates, securing qualification for forthcoming EU recyclability labeling criteria. Deepen backward integration into color masterbatch operations to capture Milan cosmetic house premiums and defend against supplier panel consolidation by Lombardy mineral water brands.
For New Entrants and Emerging Players: Southern Italy logistics gaps present the most penetrable white space, with Campania and Sicily bottling facilities currently served by northern trucking networks at elevated cost. Target pharmaceutical child-resistant format qualification under EMA guidelines, where Lombardy contract manufacturers face capacity constraints and senior-friendly design expertise remains scarce. Pursue digital printing convergence partnerships with laser-marking equipment suppliers to offer lot-traceability without label application, differentiating against incumbent decoration-limited molders.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with captive masterbatch operations and long-term supply agreements to Milan-based cosmetic houses and Emilia-Romagna sauce exporters. Acquisition targets should display EU Regulation 10/2011 certification depth, 96-cavity hot-runner operational capability, and established relationships with northern Italian beverage bottlers. Monitor EFSA notification queue clearance rates for novel additive approvals as the inflection indicator for reformulation cost pass-through capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer PP Processing Investment | Qualifies converters for EU recycled content mandates ahead of competitor tooling cycles. |
| Masterbatch Operation Backward Integration | Captures color-matching premiums from Milan cosmetic houses while compressing resin logistics costs. |
| Pharmaceutical Child-Resistant Format Development | Opens EMA-guided Lombardy contract manufacturing segment with specialized push-and-turn mechanisms. |
| Digital Printing Convergence Partnership | Enables lot-traceability offerings for Ligurian olive oil exporters without standalone label application. |
| Southern Italy Regional Capacity Buildout | Reduces logistics costs for Campania and Sicily bottlers currently served by northern trucking networks. |
Research Methodology
Operator-level perspectives from injection molding plant managers, resin compounder technical directors, beverage bottler procurement leads, and cosmetic house packaging engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Regulation 10/2011 enforcement records, EFSA migration limit notification databases, CONAI packaging consortium fee schedules, and Italian customs data on polypropylene resin imports. Bottom-up capacity estimates from Emilia-Romagna and Lombardy molding facilities were triangulated against top-down demand projections from food and beverage export statistics.
Sensitivity analysis framed volume and value outputs across the projection horizon, modeling segmentation dimensions including closure type (screw, flip-top, snap-on, tamper-evident), material grade (polypropylene homopolymer, random copolymer, polyethylene variants), end-use category (food and beverage, personal care, pharmaceutical, household), and regional production cluster density. CAGRs were derived from segment-level growth rate synthesis calibrated to tooling investment cycles and regulatory compliance timelines. Forecast inputs incorporated EFSA additive approval queue dynamics, EU Packaging and Packaging Waste Regulation implementation pacing, and northern Italian beverage bottler procurement consolidation patterns.
Forecasts assume regulatory continuity in EU food-contact material regimes and EMA pharmaceutical packaging guidelines; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated glass substitution in DOCG-tier wine appellations, propylene feedstock disruptions from Rotterdam-Antwerp corridor naphtha-cracker outages, and extended EFSA notification backlogs for novel additive qualifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Snap-On Closures Market