
 Thailand Lubricants Market | 2026-2036
Thailand Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Lubricants Market Analytics
Modular packaging formats are decoupling bulk lubricant procurement from traditional drum-and-tote bundles, giving Thai fleet operators flexibility to match order sizes with workshop throughput. Shell plc leverages its Rayong blending facility to sustain just-in-time delivery networks across the Eastern Seaboard. PTT Lubricants anchors its position through captive feedstock access from parent refinery operations. Chevron Corporation competes on industrial fluid specialization for Thailand's precision manufacturing sector.
Lubricants comprise formulated oils and greases engineered from base stocks and additive packages, typically blended to achieve specific viscosity grades such as SAE 5W-30 or ISO VG 68, designed to reduce friction, dissipate heat, and prevent wear in mechanical systems. Engine Oils command the dominant value share given Thailand's substantial on-road vehicle population and mandated drain intervals. Industrial Oils and Hydraulic Fluids expand faster from automated machinery deployment in Thai manufacturing zones. Transmission Fluids generate premium margin pools as original equipment specifications tighten for dual-clutch and continuously variable transmissions.
Thailand's Ministry of Industry enforces TISI standards for lubricant labeling and performance claims, while the Department of Industrial Works monitors waste oil disposal under hazardous substance protocols. The country's national petroleum regulator shapes import quotas for base oil feedstocks, directly affecting domestic blending economics. Stakeholders must monitor bio-based lubricant certification pathways and circular economy mandates that could redefine product portfolios and collection infrastructure requirements.
Market Dynamics
Thailand's lubricant sector is restructuring around TISI-mandated base oil quality thresholds that force blenders to abandon Group I stocks and absorb reformulation costs across their product portfolios.
Growth Catalysts
- Eastern Economic Corridor manufacturing:Precision machinery deployment in Rayong and Chonburi industrial zones generates sustained demand for hydraulic fluids and metalworking lubricants with extended drain intervals.
- Dual-clutch transmission proliferation:Thai automotive assembly plants are integrating DCT and CVT architectures that require specialized factory-fill and service-fill fluids with OEM-specific additive packages.
- Automotive fleet expansion:Commercial vehicle parc growth across Bangkok logistics corridors and provincial freight routes sustains engine oil consumption through mandated service intervals.
Market Restraints
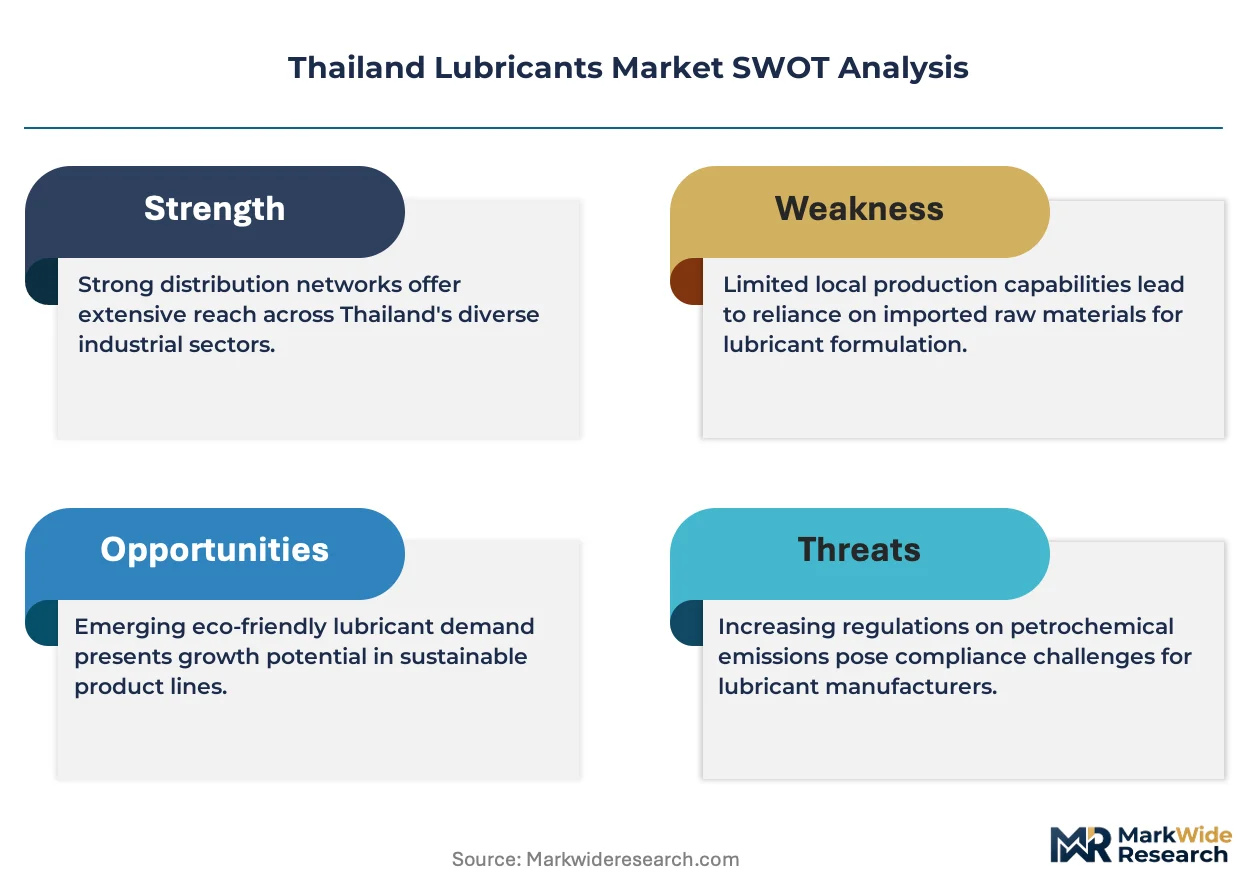
- Group II/III base oil import dependency:Domestic refiners lack hydrocracking capacity, forcing blenders to source higher-grade feedstocks from Singapore and South Korea at volatile premium spreads.
- Used lubricant collection infrastructure gaps:Thailand's Department of Industrial Works hazardous substance protocols outpace licensed waste oil processing facility capacity, creating compliance bottlenecks for service stations.
- Bio-based lubricant cost premiums:Vegetable oil ester formulations remain priced above mineral alternatives, limiting uptake in price-sensitive agricultural and marine segments despite biodegradability advantages.
Strategic Opportunities
- Chiang Mai and Khon Kaen distribution penetration:Upcountry commercial vehicle workshops outside Bangkok-Eastern Seaboard corridors remain underserved by just-in-time delivery networks, favoring regional blending satellite investments.
- Circular economy mandates:Extended producer responsibility frameworks under Thailand's national sustainable development agenda could mandate producer-funded waste oil collection, creating reverse logistics revenue streams.
- Industrial IoT integration:Sensor-enabled condition monitoring systems are converging with lubricant analytics platforms to enable predictive drain interval optimization for manufacturing customers.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for high-performance industrial fluids concentrates in Bangkok and Rayong, constraining regional blender technical service capabilities.
- TISI certification timeline compression:New product registration protocols require extended laboratory testing and documentation, delaying time-to-market for reformulated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Lubricants Market |
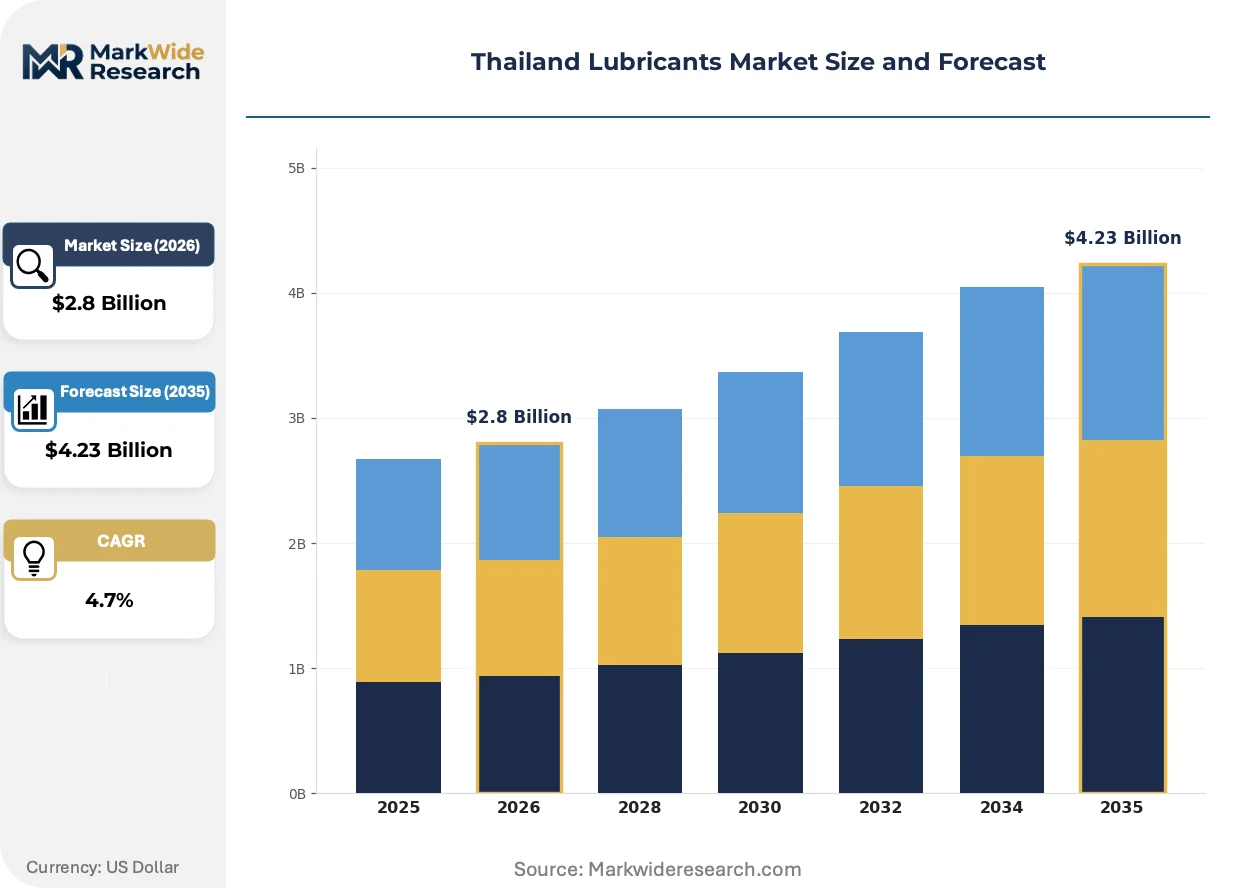
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Industrial Oils, Hydraulic Fluids, Transmission Fluids End User: Automotive, Manufacturing, Construction, Marine Application: Automotive Maintenance, Equipment Operation, Machinery Lubrication, Vehicle Performance Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Bulk Supply |
| Companies Covered | Shell plc, Exxon Mobil Corporation, Chevron Corporation, PTT Lubricants, Bangchak Corporation, BP plc (Castrol), TotalEnergies, PETRONAS Chemicals Group Berhad, ENEOS Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Lubricants Market Evolving Landscape
Formulation science and distribution logistics are converging to compress product development cycles and relocate inventory positioning closer to consumption points across Thailand's industrial geography.
Synthetic polyalphaolefin (PAO) and ester base stock blends are unifying thermal stability and low-temperature flow properties in single formulations. Thai commercial fleet operators are adopting these grades for mixed climate operations spanning Bangkok heat and northern highland routes. This unification is compressing the traditional mineral-synthetic product tiering that structured distributor portfolios for decades.
Thailand's TISI labeling and performance claim standards are tightening documentation requirements for viscosity grade assertions and additive content disclosures. Blenders must now maintain certified test data for every marketed SKU, elevating quality assurance overhead. Industrial oil segments face the steepest compliance burden due to the diversity of ISO VG specifications and application-specific performance claims.
Fleet maintenance contracts are unbundling lubricant supply from bundled service packages, enabling direct procurement relationships between vehicle operators and blenders. Independent workshops in the Eastern Seaboard corridor are displacing authorized dealer networks as primary fluid purchase points. This channel shift is most visible among logistics contractors operating dedicated routes between Laem Chabang port and Bangkok distribution centers.
Thailand Lubricants Market Segmentation
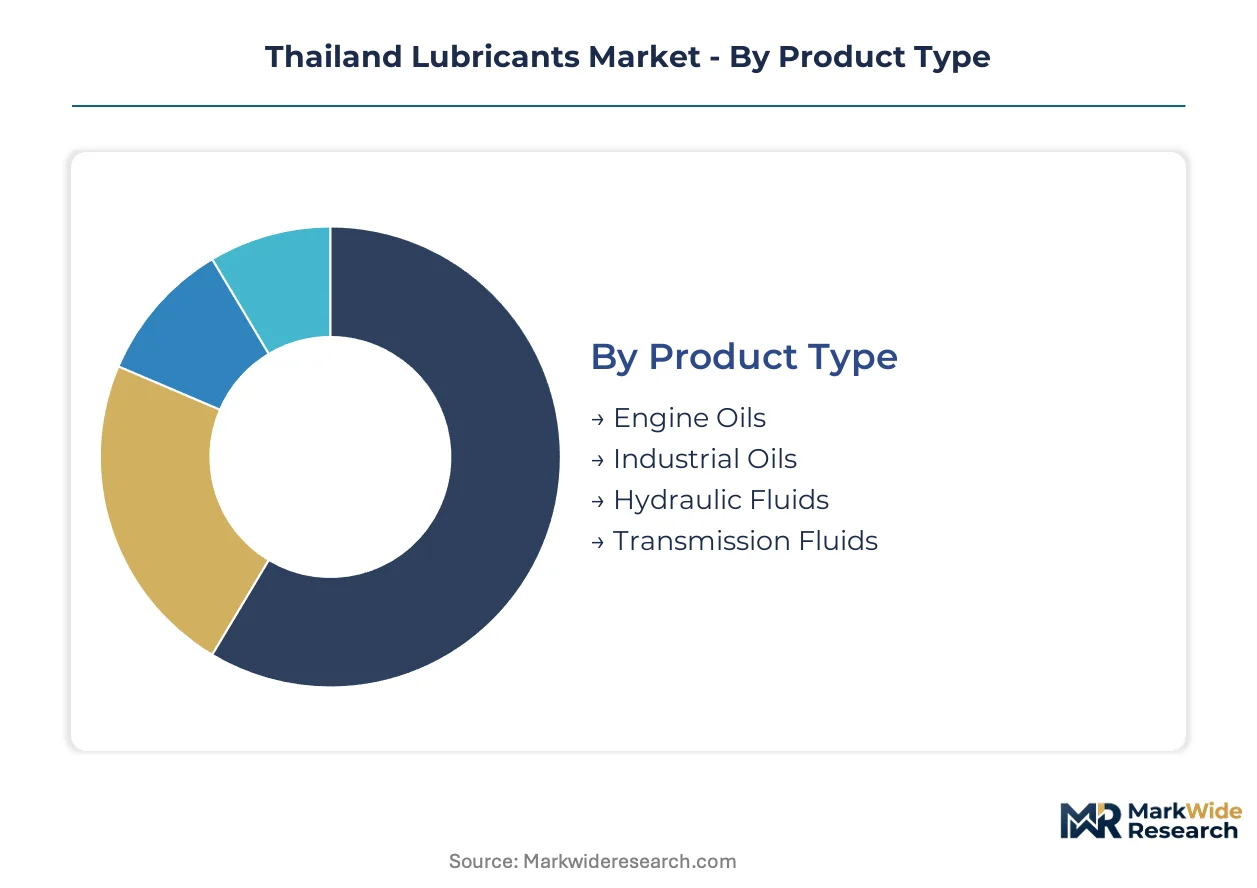
Thailand's lubricant market segments reflect divergent technical requirements across automotive assembly, precision manufacturing, and heavy infrastructure. Specification complexity varies sharply between consumer-facing engine oils and industrial hydraulic formulations governed by TISI standards.
Product Type:
Formulation chemistry and base stock quality tiers differentiate lubricant categories, with viscosity grade ranges and additive packages calibrated to specific mechanical stress profiles.
- Engine Oils:Blends from Group II/III base stocks with detergent-dispersant additive packages meet SAE viscosity specifications for passenger cars and commercial vehicles. Bangkok's dense vehicle parc and mandated drain intervals sustain volume concentration in this category, though reformulation costs from TISI quality thresholds compress blender margins.
- Industrial Oils:ISO VG-graded formulations for compressors, turbines, and gear systems prioritize oxidation stability and extended service life. Rayong and Chonburi manufacturing zones in the Eastern Economic Corridor generate concentrated demand from automated machinery deployments requiring predictive maintenance compatibility.
- Hydraulic Fluids:Anti-wear additive systems protect high-pressure hydraulic circuits in construction and logistics equipment.
- Transmission Fluids:OEM-specific additive packages for dual-clutch and continuously variable transmissions command premium positioning.
Engine Oils leads on scale; Transmission Fluids leads on momentum.
End User:
Customer procurement sophistication spans from fleet-scale tender contracts to individual workshop spot purchases, with specification authority residing differently across segments.
- Automotive:Authorized dealer networks and independent workshops service Thailand's expanding passenger car and commercial vehicle fleet through mandated maintenance intervals. Bangkok logistics corridors and provincial freight routes sustain bulk procurement relationships with direct blender engagement.
- Manufacturing:Precision machinery operators in the Eastern Economic Corridor specify industrial lubricants with condition monitoring compatibility and extended drain intervals. TISI certification requirements and ISO VG specification diversity elevate technical service demands.
- Construction:Mobile equipment fleets require hydraulic fluids and engine oils with contamination tolerance and wide temperature operability.
- Marine:Biodegradable formulations face cost barriers despite regulatory pressure on port emissions and waterway protection.
Automotive dominates absolute volume; Manufacturing climbs the fastest on specification upgrading.
Application:
Usage context determines performance validation protocols, with field testing requirements varying between consumer vehicle service and industrial equipment integration.
- Automotive Maintenance:Scheduled drain intervals and OEM warranty compliance drive specification adherence for passenger cars and commercial fleets. Bangkok-area fleet operators increasingly unbundle lubricant procurement from bundled service contracts, shifting volume toward direct blender relationships.
- Equipment Operation:Continuous-duty machinery in manufacturing and logistics demands thermal stability and contamination resistance under sustained load.
- Machinery Lubrication:Metalworking and precision equipment applications require tailored viscosity grades and additive packages for specific tooling interfaces.
- Vehicle Performance:High-load and racing applications specify synthetic base stocks for extreme temperature and shear stability.
Automotive Maintenance anchors volume concentration; Equipment Operation gains share fastest on industrial automation expansion.
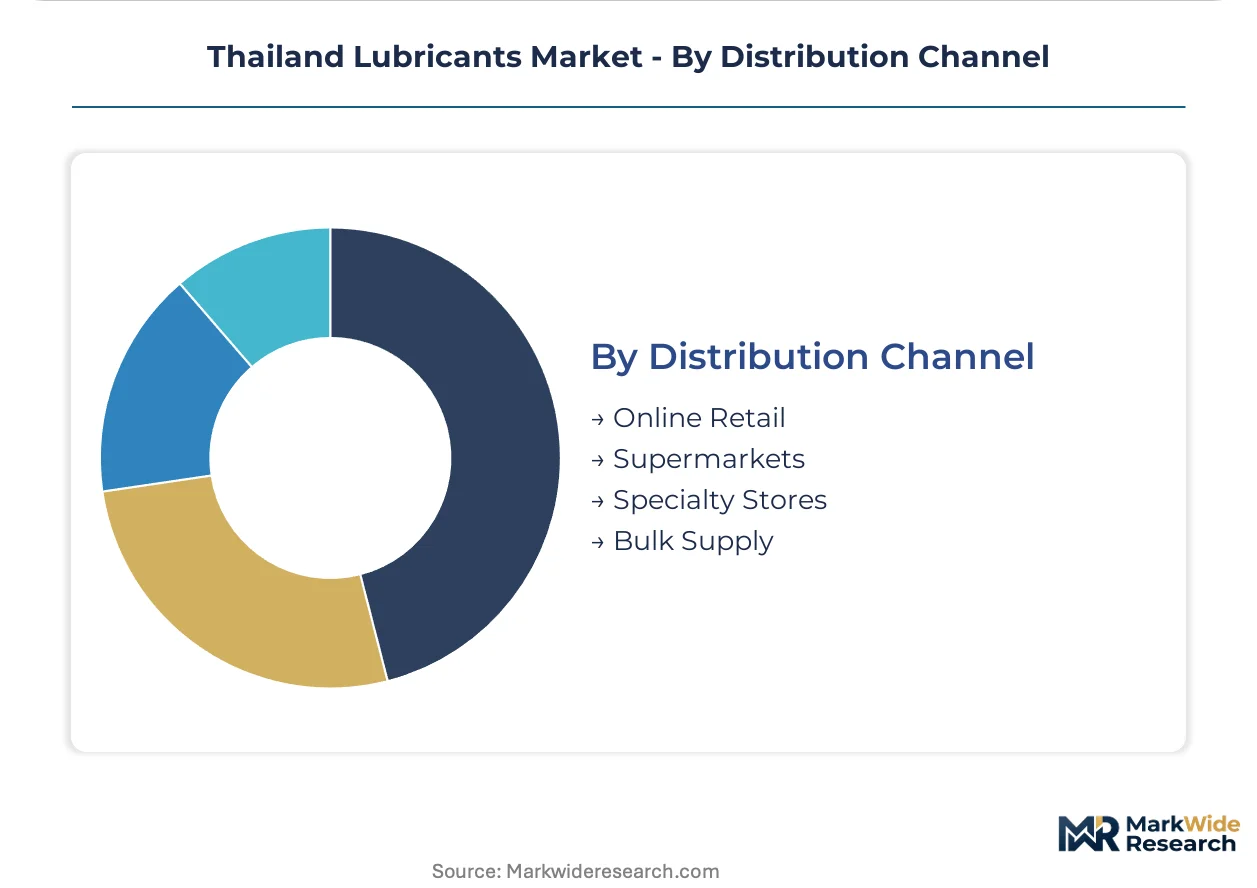
Distribution Channel:
Channel economics reflect order scale, delivery velocity requirements, and technical support intensity across customer segments.
- Online Retail:E-commerce platforms serve DIY consumers and small workshops with packaged lubricants, though technical specification guidance remains limited compared to direct sales channels.
- Supermarkets:Mass-market engine oils in standard viscosity grades reach individual vehicle owners through retail shelf presence.
- Specialty Stores:Technical distributors provide specification consulting and inventory management for independent workshops and small fleets.
- Bulk Supply:Direct blender relationships with fleet operators and manufacturing customers enable just-in-time delivery and customized formulation. Eastern Seaboard industrial clusters favor this channel for hydraulic fluid and industrial oil procurement at scale.
Bulk Supply commands margin concentration; Online Retail expands most quickly on workshop digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's lubricant industry traces its modern scale to the 1990s petrochemical buildout along the Eastern Seaboard, when integrated refinery-blending complexes established the foundation for today's formulation capabilities and distribution networks serving domestic and export markets.
Bangkok Metropolitan Region
Dense commercial vehicle parc and mandated service intervals sustain engine oil consumption across logistics corridors radiating from the capital. Thailand's Ministry of Industry enforces TISI labeling standards that elevate quality assurance overhead for blenders serving this volume concentration. Pathum Thani and Samut Prakan industrial zones concentrate bulk supply relationships with fleet operators unbundling procurement from dealer service packages.
Eastern Economic Corridor
Rayong and Chonburi manufacturing zones generate sustained demand for hydraulic fluids and metalworking lubricants from automated machinery deployment. The Department of Industrial Works monitors waste oil disposal under hazardous substance protocols that outpace licensed processing capacity. Laem Chabang port logistics operations anchor just-in-time delivery networks for industrial fluid procurement at scale.
Northern Region
Chiang Mai and Lamphun commercial vehicle workshops remain underserved by just-in-time distribution networks concentrated on the Eastern Seaboard. Provincial freight routes through mountainous terrain demand synthetic formulations with thermal stability across temperature extremes. Regional blending satellite investments face formulation expertise scarcity concentrated in Bangkok and Rayong.
Northeastern Region
Khon Kaen and Nakhon Ratchasima serve as distribution nodes for upcountry agricultural and construction equipment lubricant demand. Bio-based lubricant cost premiums limit uptake in price-sensitive agricultural segments despite biodegradability advantages for waterway protection. The national petroleum regulator shapes import quotas affecting domestic blending economics throughout this corridor.
Southern Region
Songkhla and Surat Thani marine operations face regulatory pressure on port emissions favoring biodegradable formulations. Vegetable oil ester formulations remain priced above mineral alternatives in coastal fishing and coastal freight segments. Circular economy mandates under Thailand's sustainable development agenda could mandate producer-funded waste oil collection creating reverse logistics infrastructure requirements.
Thailand Lubricants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and technical service intensity in Thailand's lubricant sector. International oil companies with integrated refinery-blending assets compete against national champions with captive feedstock access and regional specialists on industrial fluid customization. Three archetypes dominate: global majors with Eastern Seaboard manufacturing presence, Thai national oil companies leveraging parent refinery integration, and Asia-Pacific regional blenders competing on price-aggressive bulk supply. Competitive moves center on distribution network densification in upcountry corridors and formulation partnerships for OEM-specific transmission fluid approvals.
Among global majors with Thai manufacturing presence, Shell plc and Chevron Corporation exemplify the premium-tier archetype through Eastern Seaboard blending infrastructure and industrial specialization. PTT Lubricants anchors the national champion position through captive feedstock access from parent refinery operations in Rayong. These three occupy distinct competitive vectors: Shell plc sustains just-in-time delivery networks, Chevron Corporation competes on precision manufacturing fluid technical service, and PTT Lubricants leverages backward integration into base oil supply.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| PTT Lubricants |
| Bangchak Corporation |
| BP plc (Castrol) |
| TotalEnergies |
| PETRONAS Chemicals Group Berhad |
| ENEOS Corporation |
| Others |
Value Network & Pricing Analysis
State-backed refinery operators and family-owned blending specialists share Thailand's lubricant supply base, with PTT's captive feedstock access and Shell's Rayong integration creating divergent cost structures that discipline pricing across Group II/III import-dependent competitors. Bangkok fleet operators and Eastern Economic Corridor manufacturers exploit this supply fragmentation through unbundled procurement contracts that compress distributor markups.
Pricing Analysis
Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined levels dominates Thailand's lubricant trade, with TISI certification grade and volume scale as the primary differentiation drivers. Pricing pressure stems from Singapore and South Korean base oil import premiums that squeeze blender margins on reformulated grades. Fleet-scale buyers in Bangkok logistics corridors exhibit the lowest price sensitivity due to warranty compliance requirements, while provincial agricultural operators remain the most price-sensitive segment.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Rayong blending clusters to Bangkok metropolitan workshops and Eastern Seaboard manufacturing zones, with satellite stocking points in Chiang Mai and Khon Kaen serving northern corridors. Thailand's supply chain draws from Singapore, South Korea, and Japan for Group II/III base oil feedstocks due to domestic hydrocracking capacity gaps. Single-source vulnerability concentrates in Singapore Strait logistics chokepoints affecting just-in-time delivery commitments. Distribution runs through bulk tanker direct delivery for industrial accounts and packaged goods through specialty distributor networks for workshop spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's lubricant sector represents a late-cycle quality story as TISI-mandated base oil upgrades and dual-clutch transmission fluid specifications shift demand toward premium formulation tiers. The transition from Group I to Group II/III stocks rewards blenders with technical service depth and OEM certification relationships.
For Market Incumbents: Hedge against Singapore base oil import volatility through backward integration into regional storage capacity or long-term offtake agreements with South Korean suppliers. Defend Bangkok-Eastern Seaboard corridor dominance by embedding condition monitoring analytics into fleet maintenance contracts, displacing independent workshop spot purchasing. Channel control through direct procurement relationships represents the critical lever against price-aggressive regional blenders. For New Entrants and Emerging Players: E-commerce platform routes into upcountry commercial vehicle workshops offer the most penetrable white-space target, as Chiang Mai and Khon Kaen operators remain underserved by just-in-time networks concentrated on the Eastern Seaboard. Specialty distributor partnerships for bio-based lubricant certification provide a second entry angle as circular economy mandates mature. A digital-first go-to-market with technical specification databases addresses the specification guidance gap in current online retail channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blending specialists with TISI certification capabilities but limited distribution reach beyond Bangkok-Rayong corridors. The five-to-ten year viability framing favors acquisition targets with OEM transmission fluid approvals and industrial IoT integration partnerships. The signal to watch is circular economy mandate implementation timing, which would reverse-logistics infrastructure requirements and reshape collection economics for early-positioned players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Storage | Mitigates Singapore import premium volatility for Rayong blenders serving Eastern Economic Corridor demand. |
| OEM Transmission Fluid Certification | Locks in factory-fill relationships with Thai automotive assembly plants adopting DCT and CVT architectures. |
| Industrial IoT Platform Partnership | Enables predictive drain interval optimization for manufacturing customers in Chonburi precision machinery zones. |
| Regional Distribution Satellite Investment | Captures underserved Chiang Mai and Khon Kaen commercial vehicle workshop volume outside Bangkok corridors. |
| Bio-based Lubricant Certification Program | Positions for circular economy mandates under Thailand's national sustainable development agenda. |
Research Methodology
Multiple input streams — blending plant operations data, customs trade records, and TISI certification registries — were reconciled against primary interviews with lubricant formulation chemists, fleet procurement managers at Bangkok logistics operators, Eastern Economic Corridor manufacturing maintenance directors, and specialty distributor channel partners. Secondary validation drew from Thailand's Department of Industrial Works hazardous substance protocols, Ministry of Industry trade statistics, base oil import quota disclosures, and refinery capacity reports. Bottom-up volume modeling across product grades and end-use segments was cross-checked against top-down market sizing from petrochemical consumption trends.
Historical consumption patterns were cross-referenced against panel input from industry participants to construct the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, distribution channel format, and regional consumption cluster. CAGRs were derived from trend extrapolation adjusted for TISI regulatory phase-in effects and automotive fleet expansion trajectories. Forecast inputs incorporated Eastern Economic Corridor manufacturing automation rates and commercial vehicle parc maintenance interval compliance data.
The model assumes a particular technology adoption path for synthetic base stock penetration; alternative pathways for bio-based ester formulations would alter the outlook if circular economy mandates accelerate beyond baseline assumptions. Forecasts reflect documented assumptions around TISI enforcement timing and import quota stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Agricultural Lubricants Market
Lubricants
Europe Marine Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Global Engineered Fluids Market
Lubricants
Chile Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Malaysia Lubricants Market