
 Pediatric Telemedicine Market | 2026-2036
Pediatric Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Telemedicine Market Analytics
Direct-to-consumer virtual care channels for pediatric populations is fragmenting as parents seek alternatives to emergency department visits for after-hours concerns. Teladoc Health leverages its enterprise health system partnerships to sustain volume across acute and chronic pediatric conditions. American Well anchors its position through health plan integrations that cover dependent populations. TytoCare differentiates through proprietary examination peripherals that extend remote physical assessment capabilities beyond standard video visits.
Pediatric telemedicine encompasses the remote delivery of clinical services to patients from birth through adolescence via synchronous video, asynchronous messaging, and connected diagnostic devices, requiring HIPAA-compliant infrastructure with encryption standards matching in-person care workflows. Its primary commercial purpose is to reduce geographic barriers to pediatric subspecialty access while enabling continuous monitoring of chronic conditions such as asthma and diabetes. Consultation services dominate current revenue as the entry point for most virtual encounters, while remote sensors represent the fastest-expanding technology category as reimbursement frameworks mature for physiologic data transmission. Pediatric hospitals capture the deepest margin pools due to their ability to bill facility fees alongside professional services for complex telehealth encounters.
FDA oversight of Software as a Medical Device and HIPAA privacy requirements govern platform architecture and data handling across the United States, with state-level telehealth parity laws creating a patchwork of reimbursement eligibility that shapes market access. The Centers for Medicare & Medicaid Services periodically updates physician fee schedules to define covered telehealth services for pediatric populations, directly influencing provider adoption thresholds. Stakeholders must monitor evolving state licensure compacts and payer credentialing standards to determine optimal geographic expansion sequencing without building redundant compliance infrastructure.
Market Dynamics
Rural health systems in the United States are accelerating virtual pediatric consultations to address specialist shortages, compressing the traditional referral pipeline and forcing platform providers to redesign workflow integration for hospital networks.
Growth Catalysts
- State Telehealth Parity Laws:Reimbursement mandates across multiple US states eliminate payment barriers for virtual pediatric encounters, expanding provider participation.
- Mobile Penetration:Smartphone saturation in India enables direct-to-consumer pediatric consultations through government-backed telehealth infrastructure.
- Remote Patient Monitoring:FDA guidance on digital health devices validates physiologic data transmission for chronic pediatric conditions.
Market Restraints
- State Licensure Fragmentation:The patchwork of interstate medical licensing compacts creates redundant compliance costs for multi-state platform operators.
- HIPAA Infrastructure Burden:Encryption standards matching in-person workflows demand capital-intensive security architecture from emerging entrants.
- Facility Fee Dependency:Pediatric hospitals capture margin pools through complex encounter billing that standalone virtual platforms cannot replicate.
Strategic Opportunities
- Asynchronous Messaging:Store-and-forward pediatric subspecialty consultations address after-hours demand without synchronous clinician availability.
- Connected Diagnostic Peripherals:Integration of otoscopes and stethoscopes with video visits extends physical assessment beyond standard telehealth encounters.
- Health Plan Dependent Coverage:Employer-sponsored insurance integrations for family plans create captive volume channels for acute and chronic pediatric conditions.
Industry Challenges
- Pediatric-Specific Clinical Workflows:Platform developers must adapt adult-centric telehealth interfaces for developmental assessment and guardian-mediated communication.
- Reimbursement Code Alignment:CMS physician fee schedule updates lag technology capabilities, creating billing ambiguity for novel service modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Telemedicine Market |
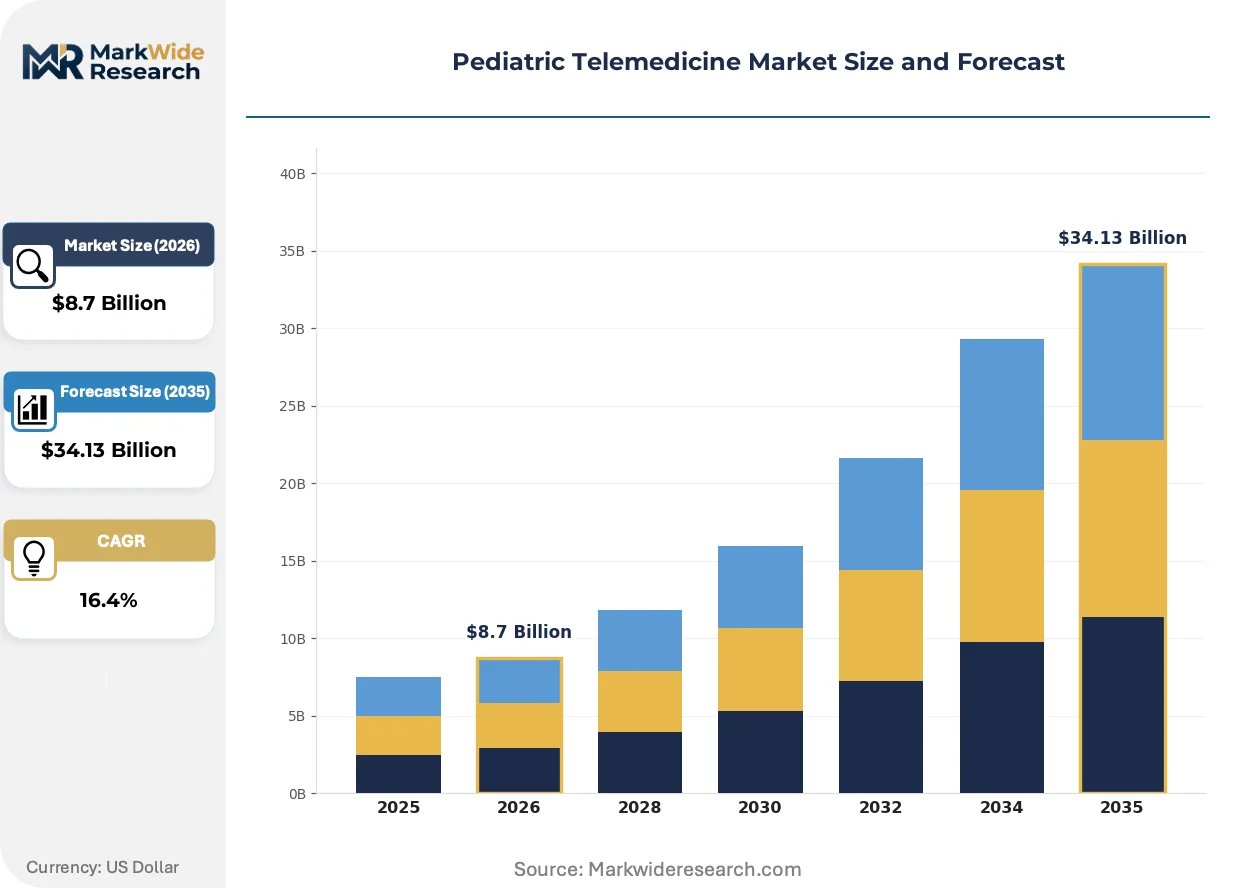
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Monitoring, Follow-up, Emergency Care Technology: Video Conferencing, Mobile Apps, Remote Sensors, AI Chatbots End User: Pediatricians, Pediatric Clinics, Hospitals, Family Care Centers Delivery Mode: Synchronous, Asynchronous, Hybrid, On-Demand |
| Companies Covered | Teladoc Health, American Well, MDLIVE, AMD Global Telemedicine, Koninklijke Philips, Vivify Health, TytoCare, KiddieRX, Anytime Pediatrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Telemedicine Market Evolving Landscape
Platform architecture is pivoting from video-first encounters toward integrated diagnostic ecosystems, embedding physical examination capabilities into remote workflows. This shift demands reconfiguration of both hardware supply chains and clinical training protocols.
Artificial intelligence triage algorithms are collapsing the gap between initial symptom presentation and appropriate care escalation in pediatric populations. Primary care networks are deploying these tools for after-hours routing decisions. The structural consequence is compression of unnecessary emergency department utilization for low-acuity pediatric concerns.
FDA Software as a Medical Device oversight is reshaping validation requirements for algorithmic diagnostic support in pediatric telemedicine platforms. Developers must submit clinical evidence for age-specific performance across neonatal through adolescent populations. US-based vendors are restructuring quality management systems to accommodate pediatric subpopulation stratification.
Parents are consolidating pediatric care access through single-platform subscriptions that bundle acute consultations, chronic condition monitoring, and developmental screening. Health system-affiliated virtual care channels are losing share to direct-to-consumer alternatives with transparent pricing. This behavioral shift concentrates in suburban markets with limited local pediatric subspecialty availability.
Pediatric Telemedicine Market Segmentation
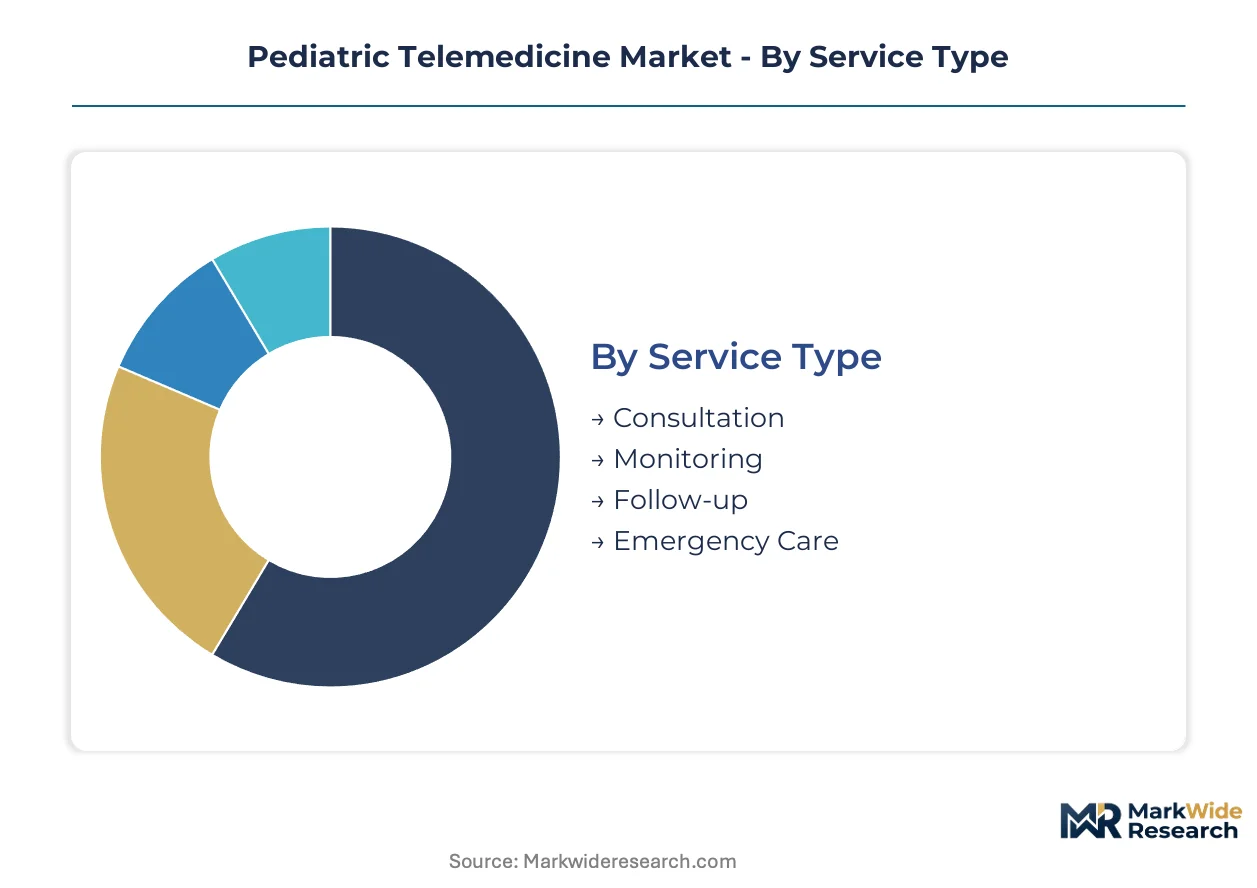
Pediatric telemedicine segments around distinct clinical workflows and reimbursement pathways. Understanding how service types, technologies, and delivery modes intersect reveals where platform investments concentrate and where margin pools form.
Service Type:
Cost tier stratification separates episodic encounters from continuous engagement models with recurring revenue profiles.
- Consultation:Synchronous video encounters for acute symptom assessment generate the highest per-session revenue. Demand concentrates in after-hours channels across US suburban markets where parents seek alternatives to emergency department visits.
- Monitoring:Continuous physiologic data transmission for chronic conditions such as asthma and diabetes operates on subscription-based pricing. Rural health systems in India deploy this service tier through government telehealth infrastructure to address specialist shortages.
- Follow-up:Post-discharge check-ins and medication management adherence programs.
- Emergency Care:Triage and stabilization guidance for high-acuity presentations requiring rapid escalation protocols.
Consultation commands the established base. The steepest expansion runs through Monitoring.
Technology:
Application maturity varies sharply between established communication infrastructure and emerging diagnostic modalities.
- Video Conferencing:HIPAA-compliant synchronous platforms remain the backbone of reimbursed telehealth encounters. Health plan integrations in the United States drive volume through dependent coverage benefits.
- Remote Sensors:Connected otoscopes, stethoscopes, and vital sign monitors extend physical assessment capabilities beyond standard video. FDA guidance on Software as a Medical Device is reshaping validation requirements for age-specific performance.
- Mobile Apps:Direct-to-consumer interfaces for appointment scheduling and asynchronous messaging.
- AI Chatbots:Algorithmic triage tools for initial symptom routing and care escalation decisions.
Video Conferencing anchors current revenue. Remote Sensors are climbing the fastest as reimbursement frameworks mature for physiologic data transmission.
End User:
Customer type determines billing complexity and margin capture potential across the care continuum.
- Hospitals:Pediatric hospitals bill facility fees alongside professional services for complex telehealth encounters, capturing the deepest margin pools. Enterprise health system partnerships sustain volume across acute and chronic conditions.
- Pediatric Clinics:Independent specialty practices leverage virtual platforms to extend geographic reach without physical expansion. State telehealth parity laws eliminate payment barriers for these encounters.
- Pediatricians:Individual practitioners integrating virtual visits into existing practice workflows.
- Family Care Centers:Primary care networks deploying telehealth for after-hours routing decisions.
Hospitals retain the highest yield per encounter. Pediatric Clinics are gaining share fastest through platform-enabled geographic extension.
Delivery Mode:
Volume concentration shifts toward flexible models that accommodate both scheduled and unscheduled demand patterns.
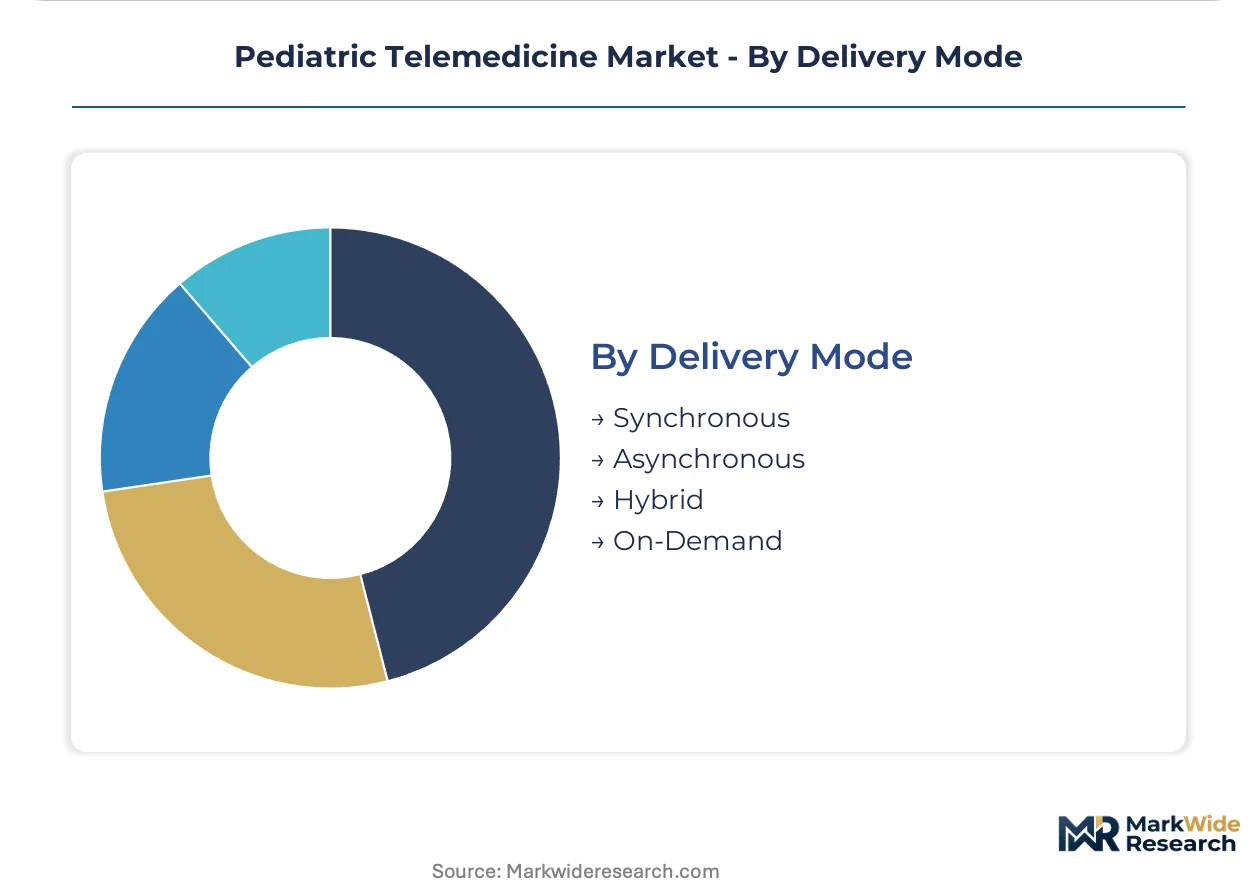
- Synchronous:Real-time video encounters requiring immediate clinician availability.
- Asynchronous:Store-and-forward consultations enabling subspecialty review without concurrent scheduling. This mode addresses after-hours demand in markets with limited pediatric subspecialty availability.
- Hybrid:Blended approaches combining initial AI triage with escalated human consultation.
- On-Demand:Immediate access models for urgent concerns with sub-15-minute response targets.
Synchronous encounters dominate current reimbursement. Asynchronous delivery is expanding most quickly through store-and-forward subspecialty workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Health Stack underwrites India's emergence as the primary demand center for pediatric telemedicine, connecting rural health sub-centers to metropolitan pediatric specialists through interoperable digital infrastructure.
United States
Rural health systems in Texas and Mississippi deploy virtual pediatric consultations to bridge specialist shortages in neonatology and pediatric cardiology. FDA guidance on Software as a Medical Device reshapes validation requirements for remote diagnostic peripherals. The Boston-Seattle corridor concentrates platform development, with enterprise health system partnerships sustaining volume across acute and chronic conditions.
India
Smartphone saturation exceeding 750 million devices enables direct-to-consumer pediatric consultations through government-backed telehealth infrastructure. The country's national health regulator validates connected diagnostic devices under streamlined digital health pathways. Maharashtra and Karnataka host the deepest platform development clusters, where mobile-first interfaces address after-hours subspecialty demand in tier-2 and tier-3 cities.
Germany
Employer-sponsored family health plans drive reimbursement for virtual pediatric encounters through statutory health insurance integrations. EMA oversight of digital health applications shapes clinical evidence requirements for algorithmic triage tools. The Munich-Berlin axis anchors health plan platform partnerships, with pediatric clinics leveraging asynchronous messaging to extend geographic reach.
United Kingdom
NHS England's digital-first primary care mandate accelerates adoption of store-and-forward pediatric subspecialty consultations. MHRA guidance on Software as a Medical Device governs AI triage algorithm deployment in primary care networks. The London-Oxford-Cambridge triangle concentrates health technology procurement, where integrated care systems consolidate virtual pediatric access channels.
Australia
Remote Indigenous community health services deploy satellite-enabled pediatric telemedicine to address specialist access gaps across the Northern Territory and Western Australia. TGA oversight of medical device software validates remote examination peripherals for pediatric populations. The Sydney-Melbourne corridor anchors platform development, with rural health networks integrating connected diagnostic devices into fly-in-fly-out clinical workflows.
Pediatric Telemedicine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying examination peripherals and encryption infrastructure. The vendor base concentrates around three strategic archetypes: enterprise health system partners, direct-to-consumer channels, and connected device manufacturers. Consolidation pressures favor platforms with captive health plan relationships over standalone virtual consult providers. Dominant competitive moves include health system partnership expansion and proprietary peripheral development.
Within the enterprise partnership tier, Teladoc Health and American Well exemplify platform integrators anchoring volume through health system and payer relationships. TytoCare occupies a position among component specialists, representing the connected diagnostic archetype through proprietary examination peripherals that extend remote physical assessment capabilities.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| MDLIVE |
| AMD Global Telemedicine |
| Koninklijke Philips |
| Vivify Health |
| TytoCare |
| KiddieRX |
| Anytime Pediatrics |
| Others |
Value Network & Pricing Analysis
Boston-Seattle corridor platform developers leverage proximity to enterprise health system headquarters to command premium pricing for integrated telemedicine deployments. Their capacity concentration enables volume-tiered contracting that compresses margins for emerging entrants lacking hospital network anchorage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates pediatric telemedicine platform contracting. Premium tiers bundle FDA-cleared remote examination peripherals with synchronous video infrastructure, while standard offerings rely on HIPAA-compliant video alone. Price differentiation hinges on certification grade and after-sales clinical training intensity. Pricing pressure stems from health plan procurement consolidation, which forces standalone virtual consult providers toward subscription-based SaaS models. Family care centers exhibit highest price sensitivity; pediatric hospitals demonstrate lowest due to facility fee capture mechanisms.
Supply Chain Analysis
Contract manufacturing for connected diagnostic peripherals concentrates among Taiwan-based EMS providers and select Shenzhen facilities with medical device ISO 13485 certification. Hardware assembly draws from South Korean sensor suppliers and Japanese optical component specialists. Supply chain risk centers on single-source vulnerability for FDA-validated otoscope imaging modules. Distribution runs through health system GPO contracts and direct-to-consumer e-commerce channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health plan consolidation and pediatric hospital system mergers, shifting negotiation leverage toward organizations commanding dependent population volume. This fragmentation among platform customers demands differentiated positioning strategies.
For Market Incumbents: Build regulatory moats through FDA Software as a Medical Device pre-certification for AI triage algorithms. Deepen enterprise health system partnerships to lock in multi-year platform subscriptions. Defend against emerging connected device manufacturers by acquiring proprietary peripheral developers. Anchor capacity addition in Maharashtra and Karnataka to capture Indian government telehealth infrastructure procurement.
For New Entrants and Emerging Players: Establish a beachhead in asynchronous messaging for pediatric subspecialty consultations, where incumbent workflow integration lags. Target tier-2 and tier-3 Indian cities with mobile-first interfaces bypassing legacy hospital system sales cycles. Deploy direct-to-consumer transparent pricing to capture suburban US parents consolidating care access through single-platform subscriptions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with captive health plan relationships over standalone virtual consult providers. Long-term viability hinges on reimbursement framework maturation for remote physiologic data transmission. Acquisition target archetype: connected diagnostic peripheral developers with FDA validation for age-specific pediatric performance. Monitor CMS physician fee schedule updates as inflection indicator for provider adoption thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Pre-certification for AI triage algorithms validates age-specific performance across neonatal through adolescent populations. |
| Hospital System Partnership Expansion | Enterprise anchorage sustains volume across acute and chronic conditions while capturing facility fee billing. |
| Proprietary Peripheral Development | Connected otoscopes and stethoscopes extend physical assessment beyond standard video encounters. |
| Health Plan Integration | Dependent coverage benefits create captive volume channels for family plan subscribers. |
| Geographic Expansion into India | National Health Stack infrastructure enables direct-to-consumer access through government-backed telehealth channels. |
Research Methodology
Desk research of FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records preceded structured interviews with pediatric telemedicine platform executives, health system CIOs, and GPO contracts managers. Primary fieldwork with biomedical engineers and payer access specialists validated secondary findings on technology adoption patterns. Bottom-up sizing of installed platform bases was triangulated against top-down health expenditure allocation models.
Assumptions held fixed across the projection horizon include current FDA Software as a Medical Device oversight timelines and state telehealth parity law coverage expansions. Variables stress-tested encompass CMS physician fee schedule revision frequency and interstate medical licensure compact adoption rates. Segmentation dimensions modeled include service type, technology modality, end-user facility category, and delivery mode. CAGRs were derived from logistic diffusion curves fitted to historical adoption benchmarks in comparable digital health categories.
Stress conditions across reimbursement code alignment lag, HIPAA infrastructure capital requirements, and pediatric-specific clinical workflow adaptation costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and acknowledge that regulatory acceleration or deceleration in India or the United States could materially revise trajectory. Quarterly review of CMS fee schedule proposals and state licensure compact ratification is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
5G Telemedicine Platform Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Teledermatology Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telehealth Services Market
Telemedicine
Telemedicine Service Market
Telemedicine
US Telemedicine Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Remote Healthcare Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Telemedicine Cart Market