
 United States Telehealth Postpartum Services Market | 2026-2036
United States Telehealth Postpartum Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Telehealth Postpartum Services Market Insights
Hospital systems and employer health plans is rebalancing toward home-based virtual postpartum support. Major Care leverages its platform infrastructure to anchor virtual care delivery across multiple states. NayaCare specializes in culturally tailored lactation and mental health counseling for underserved communities. Ovia Health sustains strong channel control through direct employer and payer partnerships.
United States Telehealth Postpartum Services encompasses remote clinical and non-clinical support delivered to mothers during the twelve-month period following childbirth, typically via synchronous video, asynchronous messaging, and connected monitoring devices that track vital signs, mood indicators, and infant feeding patterns. The primary purpose is to extend obstetric continuity of care beyond hospital discharge while reducing readmission risk and addressing maternal mental health conditions. Virtual Care Platforms leads service type revenue due to recurring subscription models and payer integration, while AI Chatbots within the technology dimension represents the fastest-expanding segment as natural language processing improves triage accuracy. Rural Residents within user demographic constitutes a concentrated demand pocket where geographic barriers make facility-based follow-up impractical.
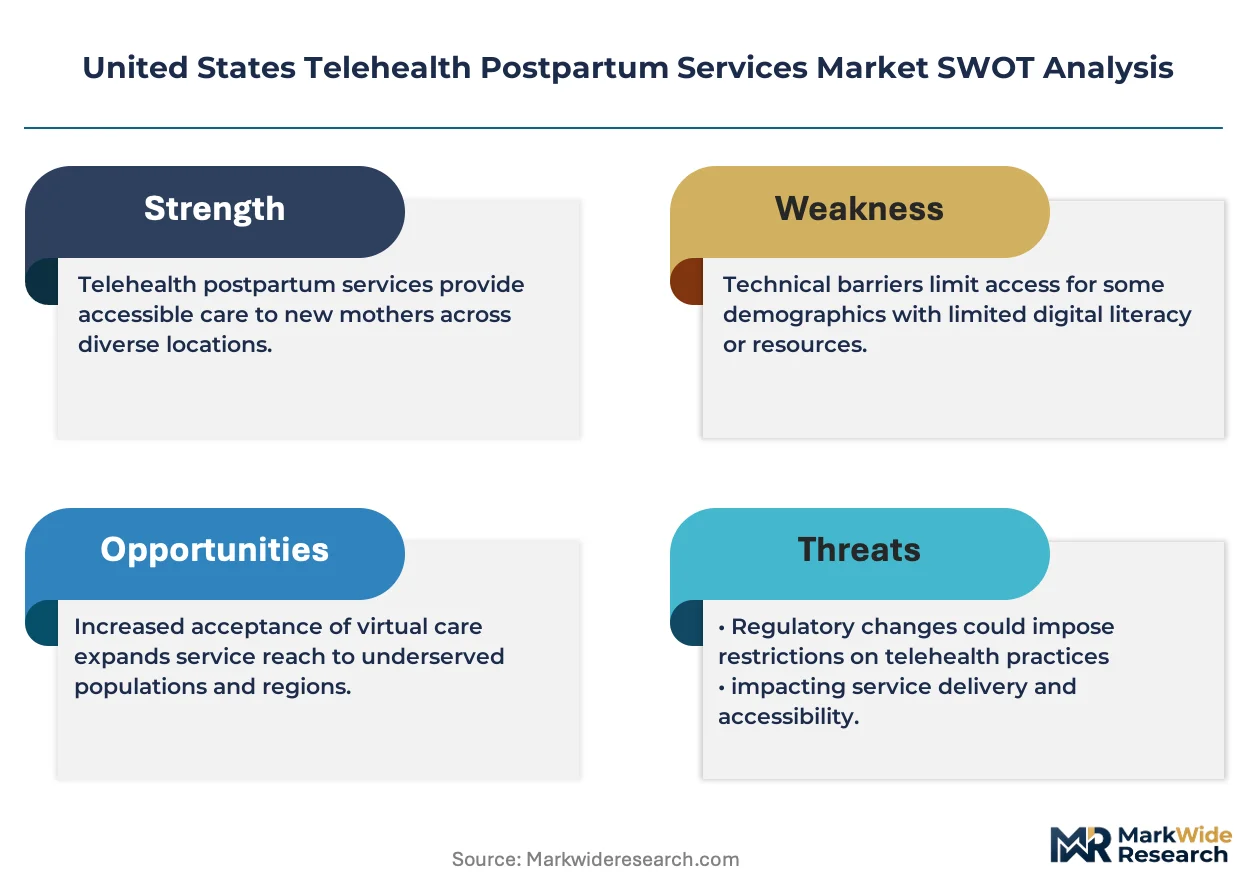
FDA oversight of Software as a Medical Device governs diagnostic algorithms embedded in postpartum monitoring applications, while HIPAA frameworks mandate encryption and access controls for all maternal health data transmitted through commercial platforms. CMS telehealth reimbursement policies determine provider participation incentives and directly shape platform viability in Medicare and Medicaid populations. Stakeholders must monitor state-level scope-of-practice expansions for nurse midwives and lactation consultants operating across state lines via telehealth modalities.
Market Dynamics
CMS reimbursement parity rules have permanently restructured provider economics in United States Telehealth Postpartum Services, shifting clinical delivery from facility-based follow-up to home-based virtual platforms. This regulatory anchor now dictates platform viability across Medicare and Medicaid populations.
Growth Catalysts
- CMS Reimbursement Parity:Permanent telehealth coverage parity under Medicare and Medicaid removes financial barriers for rural patients accessing postpartum mental health and lactation support.
- Maternal Health Deserts:Geographic concentration of care gaps in Texas and Florida drives enrollment surges where facility-based follow-up is impractical.
- Employer Benefit Expansion:Large employer health plans now underwrite virtual postpartum mental health visits as a covered benefit, creating direct-to-consumer demand channels.
Market Restraints
- State Licensure Fragmentation:Nurse midwives and lactation consultants face scope-of-practice restrictions when operating across state lines via telehealth modalities.
- HIPAA Compliance Costs:Encryption and access control mandates for maternal health data transmission impose ongoing infrastructure burdens on platform operators.
- Rural Broadband Gaps:Inadequate connectivity infrastructure in Appalachian and Southwestern regions limits synchronous video adoption for high-acuity postpartum monitoring.
Strategic Opportunities
- AI-Enhanced Triage:Natural language processing integration with synchronous video platforms improves symptom routing accuracy and reduces clinician burnout.
- Medicaid Expansion States:States adopting expanded Medicaid eligibility present enrollment growth corridors for subsidized virtual postpartum services.
- Connected Device Integration:Blood pressure cuffs and mood-tracking wearables bundled with platform subscriptions create recurring revenue attachment opportunities.
Industry Challenges
- FDA SaMD Classification:Diagnostic algorithms embedded in postpartum monitoring applications face lengthy premarket review timelines that delay product launches.
- Cross-State Credentialing:Platforms must maintain redundant provider licensing across multiple jurisdictions, inflating administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Telehealth Postpartum Services Market |
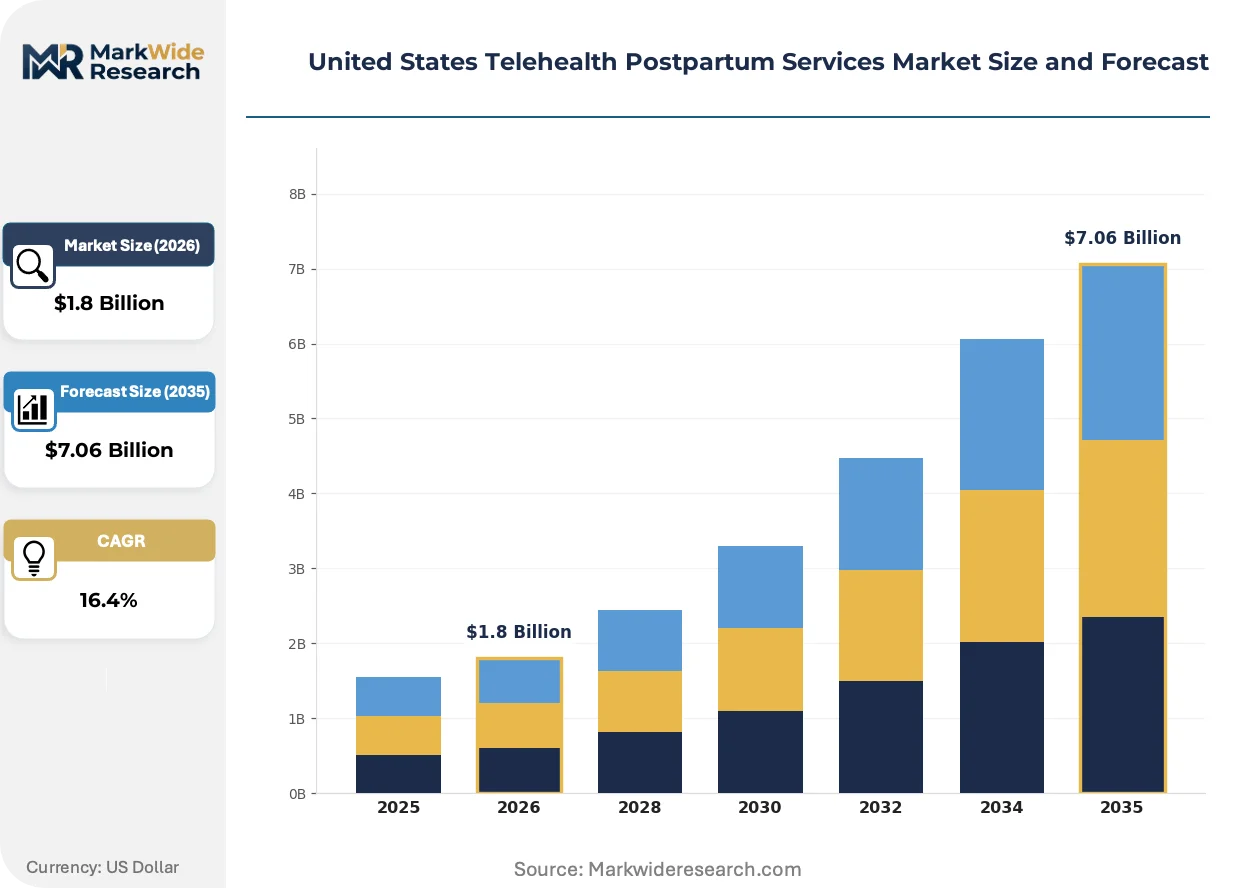
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Counseling, Virtual Care Platforms, Health Monitoring, Medication Management Care Setting: Home Care, Remote Clinics, Hospital Follow-up, Specialized Support User Demographic: First-time Mothers, High-Risk Patients, Rural Residents, Urban Families Technology: Mobile Apps, Wearable Devices, Video Conferencing, AI Chatbots |
| Companies Covered | Major Care, NayaCare, Homewatch CareGivers, The Cradle Company, CLEBaby, Inova, Postpartum Support International, Ovia Health, HealthTap, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Telehealth Postpartum Services Market Trends and Innovations
Technology convergence and regulatory permanence are compressing the traditional postpartum care delivery model from episodic hospital visits to continuous remote monitoring. Platform operators now compete on integration depth rather than connectivity alone.
AI-powered chatbot triage systems are overtaking traditional nurse hotlines as the first point of clinical contact for postpartum symptom assessment. Rural health systems in Texas and Florida deploy these tools to manage after-hours volume surges. The technology compresses time-to-clinical-escalation from hours to minutes while reducing labor costs.
FDA Software as a Medical Device oversight now governs diagnostic algorithms that flag postpartum hypertension or mood disorder risk from patient-reported data. Platform developers must submit premarket notifications for algorithm updates, slowing iteration cycles. This regulatory friction most affects startups targeting remote patient monitoring with predictive analytics.
Direct employer contracting is displacing traditional payer-channel distribution for virtual postpartum benefits. Large self-insured employers in technology and professional services sectors now procure platform access through population health vendors rather than health plan intermediaries. This channel shift concentrates demand in metropolitan employment clusters including Austin, Seattle, and Boston.
United States Telehealth Postpartum Services Market Segmentation
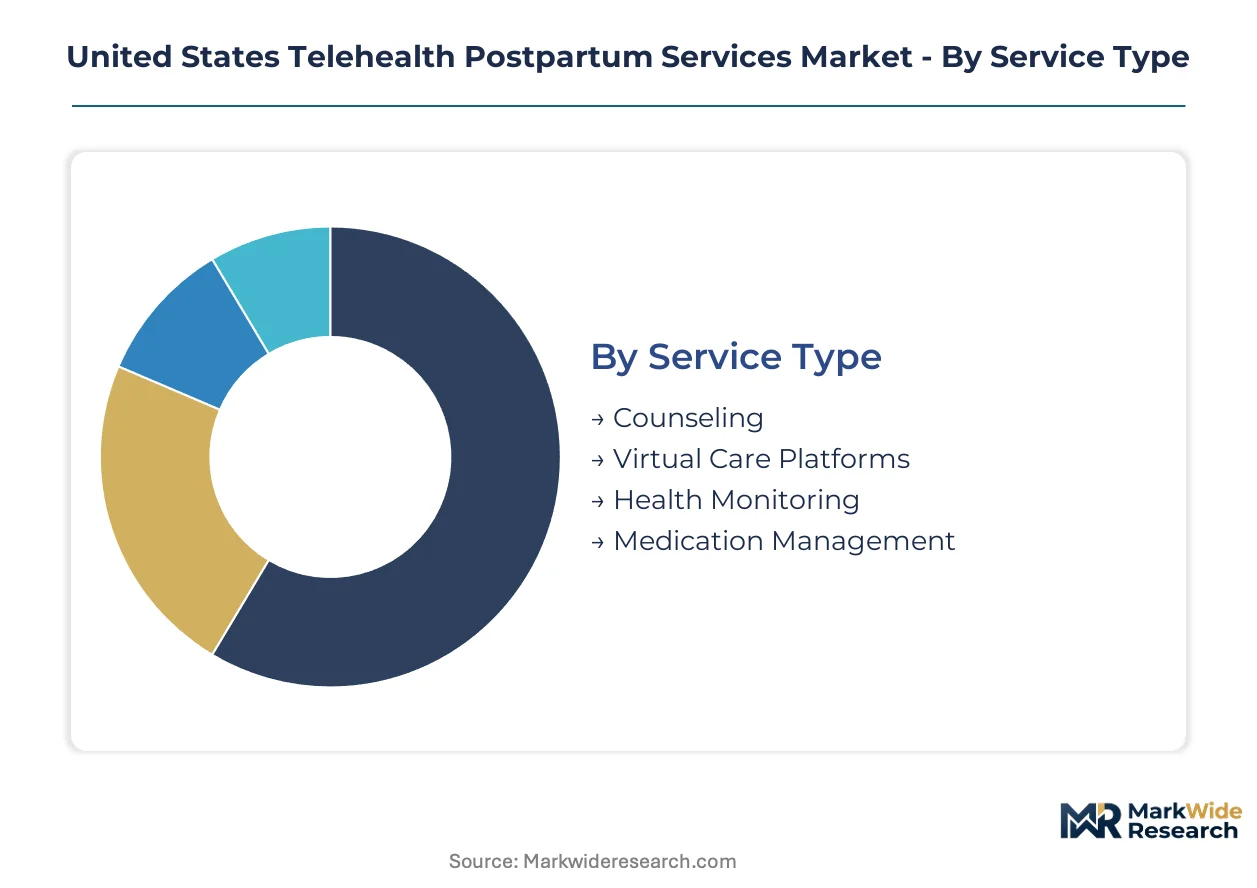
Segmentation in United States Telehealth Postpartum Services reveals how reimbursement pathways, geographic barriers, and clinical risk profiles fragment demand across distinct service configurations. Platform operators must align service mix with Medicaid eligibility corridors and employer benefit structures to capture volume.
Service Type:
Cost tier differentiation separates episodic clinical encounters from subscription-based continuous care models.
- Virtual Care Platforms:Cloud-based infrastructure delivers synchronous video visits, asynchronous messaging, and care coordination through recurring subscription models integrated with payer networks. Demand concentrates in Texas and Florida maternal health deserts where facility-based follow-up requires travel exceeding 60 miles.
- Counseling:Licensed mental health professionals provide remote therapy for postpartum depression and anxiety through HIPAA-compliant video sessions. Employer-sponsored health plans in Austin, Seattle, and Boston now underwrite this benefit as standard coverage.
- Health Monitoring:Connected devices track maternal vital signs and infant feeding patterns with automated alerts to care teams.
- Medication Management:Remote psychiatric consultation and prescription oversight for postpartum mood disorders.
Volume sits with Virtual Care Platforms; growth tilts toward Counseling as employer benefit expansion accelerates.
Care Setting:
Application context determines technology requirements and reimbursement eligibility for each delivery mode.
- Home Care:Services delivered directly to patients in residential settings through mobile applications and connected devices. Rural Residents in Appalachian and Southwestern regions drive enrollment where broadband limitations force asynchronous-first delivery models.
- Hospital Follow-up:Scheduled virtual visits replacing in-person postpartum appointments within 72 hours of discharge. CMS reimbursement parity rules mandate coverage parity for these encounters across Medicare and Medicaid populations.
- Remote Clinics:Hub-and-spoke models connecting rural patients to urban specialist capacity.
- Specialized Support:Condition-specific programs for gestational diabetes recovery or NICU graduate families.
Revenue concentrates in Hospital Follow-up; expansion is climbing fastest in Home Care as remote patient monitoring technology matures.
User Demographic:
Clinical risk stratification and geographic isolation create distinct service intensity requirements across patient populations.
- Rural Residents:Mothers in federally designated maternal health deserts where obstetric facility closures exceed 150 since 2011. Texas and Florida counties with zero obstetric services generate disproportionate enrollment in asynchronous messaging and store-and-forward diagnostic platforms.
- High-Risk Patients:Women with pre-existing hypertension, diabetes, or prior cesarean delivery requiring intensive monitoring protocols. Connected blood pressure cuffs and mood-tracking wearables bundle with platform subscriptions for this cohort.
- First-time Mothers:Primiparous women seeking lactation support and newborn care guidance.
- Urban Families:Metropolitan-area mothers prioritizing convenience over clinical necessity.
Platform investment targets Rural Residents for volume; High-Risk Patients command premium pricing through device integration.
Technology:
Customer technical sophistication and connectivity infrastructure shape adoption curves for each delivery mechanism.
- AI Chatbots:Natural language processing systems conduct initial symptom triage and escalate to human clinicians based on risk scoring. Rural health systems deploy these tools to manage after-hours volume surges, compressing time-to-clinical-escalation from hours to minutes.
- Mobile Apps:Smartphone-based platforms delivering educational content, appointment scheduling, and secure messaging. First-time Mothers in metropolitan employment clusters including Austin and Boston drive download velocity through employer-sponsored benefit activation.
- Video Conferencing:Synchronous audiovisual consultation requiring broadband connectivity.
- Wearable Devices:Physiological sensors transmitting continuous biometric data to care teams.
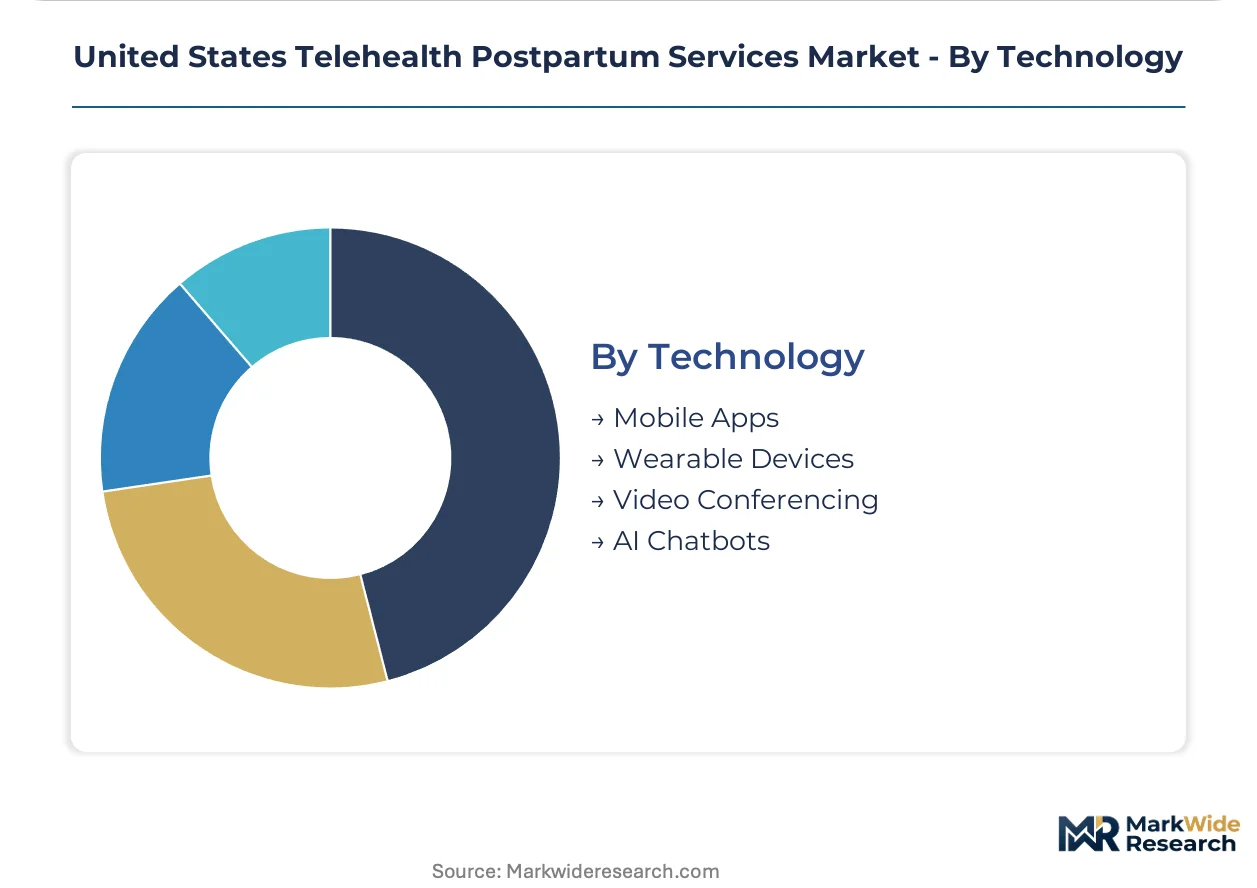
Deployment scale favors Mobile Apps; the steepest expansion trajectory belongs to AI Chatbots as natural language processing accuracy improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform deployment concentrates in states with acute maternal care access gaps, while reimbursement policy divergence creates uneven adoption corridors. Texas and Florida generate disproportionate enrollment due to obstetric facility closures exceeding 150 since 2011. CMS parity rules anchor federal coverage, yet state Medicaid expansion status fragments commercial viability.
Texas
Rural maternal health deserts in the Panhandle and West Texas drive asynchronous-first platform adoption where travel distances exceed 60 miles to nearest obstetric facilities. State Medicaid managed care contracts increasingly mandate telehealth lactation support as a covered benefit. Austin employment clusters anchor direct employer contracting for virtual postpartum mental health through technology sector benefit programs.
Florida
Obstetric unit closures in northern and central counties concentrate demand for remote blood pressure monitoring and mood disorder screening. State licensure compacts for nurse midwives remain incomplete, forcing platforms to maintain redundant credentialing systems. Miami-Dade and Tampa metropolitan areas host employer-sponsored program rollouts through hospitality and healthcare sector health plans.
California
Medi-Cal expansion and commercial payer integration create the deepest reimbursement environment for continuous remote monitoring subscriptions. Department of Managed Health Care mandates for postpartum depression screening accelerate platform deployment in Los Angeles and San Francisco Bay Area health systems. Sacramento policy corridors shape scope-of-practice legislation for lactation consultants operating via telehealth.
New York
Downstate hospital system consolidation pushes virtual follow-up adoption as a readmission reduction strategy for Medicaid populations. State parity laws predate federal CMS rules, establishing precedent for commercial payer reimbursement of mental health tele visits. New York City health system density supports hub-and-spoke models connecting urban specialists to Hudson Valley and North Country patients.
Massachusetts
Greater Boston employer density concentrates demand for premium-tier virtual care platforms bundled with connected devices. MassHealth reimbursement policies for remote patient monitoring exceed federal minimums, attracting platform operators targeting high-risk patient cohorts. Cambridge and Route 128 technology corridors drive AI chatbot triage deployment for after-hours symptom assessment.
United States Telehealth Postpartum Services Market Competitive Landscape
Top-tier vendors anchor multi-state platform infrastructure, while regional specialists and employer-channel pure-plays occupy distinct competitive tiers. The vendor base stratifies across three archetypes: virtual care platforms with payer integration, culturally specialized counseling services, and direct-to-employer population health vendors. Consolidation pressure favors scale operators with CMS certification, while niche players defend position through demographic targeting and care model differentiation. Dominant competitive moves include geographic licensing expansion and connected device bundling to capture recurring revenue attachment.
Within the infrastructure-heavy tier, Major Care exemplifies multi-state platform deployment with cloud-based delivery systems. NayaCare occupies a position representing culturally tailored service specialization for underserved community segments. Ovia Health anchors the direct employer contracting archetype through population health vendor relationships. These three company structures illustrate how reimbursement pathway alignment determines competitive positioning across Medicaid, commercial payer, and self-insured employer channels.
| Leading Market Players |
|---|
| Major Care |
| NayaCare |
| Homewatch CareGivers |
| The Cradle Company |
| CLEBaby |
| Inova |
| Postpartum Support International |
| Ovia Health |
| HealthTap |
| Others |
Pricing and Supply Chain Analysis
Premium platform certification tiers versus basic messaging-only offerings bifurcate both reimbursement pathways and vendor procurement strategies across the United States Telehealth Postpartum Services ecosystem. HIPAA-compliant infrastructure investments and CMS certification status separate vendors who capture Medicaid managed care contracts from those restricted to direct-pay consumer channels.
Pricing Analysis
Short lead-time deployment premiums reward vendors with pre-certified infrastructure stacks ready for rapid health system onboarding. Three-tier pricing structure across enterprise, mid-market, and direct-to-consumer levels reflects integration depth with electronic health records and payer networks. Price differentiation hinges on FDA Software as a Medical Device classification status and synchronous video capacity versus asynchronous-only delivery. Cost compression in the direct-to-consumer tier intensifies because employer benefit administrators negotiate volume discounts. Medicaid managed care organizations exhibit highest price sensitivity; self-insured employers in technology sectors show least.
Supply Chain Analysis
Regional data center distribution patterns anchor platform latency performance for synchronous video encounters across Texas and Florida maternal health deserts. Cloud infrastructure concentrates in the United States through AWS, Microsoft Azure, and Google Cloud availability zones. Raw material dependencies span biometric sensor components from Taiwan, semiconductor chips from South Korea, and lithium-ion batteries from China for connected monitoring devices. Single-source vulnerability in FDA-cleared algorithm development partners creates bottleneck risk for predictive analytics features. Distribution runs through direct health system procurement and population health vendor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Telehealth Postpartum Services market sits in a technology-transition phase where AI-powered triage systems displace legacy nurse hotline infrastructure as the first clinical contact point.
For Market Incumbents: Anticipate margin compression from AI-native entrants targeting asynchronous-first rural markets with lower operational overhead. Consolidate position through backward integration into connected device manufacturing to capture recurring hardware revenue attachment. Prioritize CMS certification maintenance as regulatory friction intensifies for Software as a Medical Device classifications. For New Entrants and Emerging Players: Begin with culturally specialized counseling services in Medicaid expansion states where incumbent platform coverage remains thin. Texas Panhandle and Florida central counties present the most penetrable geography given obstetric facility closures exceeding 150 since 2011. Pursue direct employer contracting through benefits administrators rather than payer intermediaries to bypass credentialing complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by health systems seeking virtual care infrastructure. Long-term viability favors vendors with durable CMS reimbursement alignment and multi-state licensure infrastructure already deployed. Watch FDA premarket notification timelines for diagnostic algorithm updates as the inflection signal for platform iteration speed.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Premarket clearance for hypertension and mood disorder algorithms accelerates competitive differentiation against unregulated triage tools. |
| Medicaid Managed Care Contracting | State-level procurement wins in Texas and Florida lock in recurring revenue from maternal health desert populations. |
| Connected Device Bundling | Blood pressure cuffs and mood-tracking wearables create subscription attachment and improve clinical outcome data capture. |
| Cross-State Licensure Expansion | Nurse midwife and lactation consultant credentialing across multiple jurisdictions reduces administrative overhead for platform operators. |
| Direct Employer Partnership | Technology sector benefit programs in Austin, Seattle, and Boston bypass payer intermediaries and accelerate enrollment velocity. |
Research Methodology
Independent corroboration across platform engineering leads, Medicaid managed care contracting officers, and employer benefits administrators underwrites the qualitative findings in this study. Primary interviews with telehealth operations directors, clinical workflow designers, and GPO contracts managers combined with secondary validation from CMS Medicare data, state Medicaid enrollment reports, and hospital procurement databases. Bottom-up enrollment modeling and top-down reimbursement flow analysis triangulate volume estimates.
Rate-of-change decomposition across service type, care setting, user demographic, and technology dimensions structures the analytical framework over the projection horizon. Segmentation modeling incorporates virtual care platform integration complexity, counseling licensure requirements, and rural broadband infrastructure quality as industry-specific forecast inputs. CAGRs derive from enrollment velocity trends and reimbursement policy permanence assumptions.
Underlying measurement precision varies by segment; Virtual Care Platforms and AI Chatbots carry tighter precision than emerging wearable device categories. Forecasts reflect documented assumptions regarding CMS parity rule durability and state Medicaid expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
North America Telemedicine Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Telehealth Services Market
Telemedicine
India Telemedicine Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Remote Healthcare Market
Telemedicine
Telemedicine Service Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
India Telehealth Services Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Teledermatology Market