
 Telehealth Software Market | 2026-2036
Telehealth Software Market Size, Share, and Industry Trends Forecast 2026-2036
Telehealth Software Market Outlook
Subscription-based SaaS licensing is reconfiguring capital deployment across the telehealth software competitive landscape, enabling mid-sized providers to enter without heavy infrastructure spend. Teladoc Health Inc. leverages its direct-to-employer channel relationships to sustain recurring revenue density. American Well Corporation anchors its position through payer partnerships that embed virtual care into insurance workflows. Epic Systems Corporation dominates hospital system EHR integration, controlling the clinical data layer that telehealth modules must access.
Telehealth software comprises digital platforms enabling synchronous video consultation, asynchronous store-and-forward diagnostics, and remote patient monitoring data exchange through HL7 FHIR interoperability standards. These systems serve the primary commercial purpose of extending clinical reach beyond physical facility boundaries while maintaining care documentation fidelity. Cloud-based deployment leads segment economics by reducing client-side IT overhead and enabling elastic scaling during demand surges. AI-driven technology represents the fastest-growing capability layer, where diagnostic decision support and automated triage algorithms concentrate development investment and margin expansion potential.
FDA Software as a Medical Device guidance, HIPAA security rule provisions, and state-level telemedicine practice regulations collectively shape product architecture, data handling protocols, and interstate licensing requirements for platform operators. The Centers for Medicare and Medicaid Services reimbursement parity rules directly influence provider willingness to adopt virtual modalities as standard care channels. Stakeholders must monitor evolving state medical board definitions of physician-patient relationship establishment, as these determinations control whether asynchronous consults qualify for reimbursement across jurisdictions.
Market Dynamics
HL7 FHIR interoperability standards are compressing integration timelines for virtual care platforms, forcing vendors to rebuild core architecture around open data exchange protocols rather than proprietary clinical repositories.
Growth Catalysts
- CMS reimbursement parity rules:The Centers for Medicare and Medicaid Services mandates equivalent payment for virtual and in-person visits, eliminating the financial penalty that previously constrained provider adoption across United States health systems.
- Cloud-native deployment architectures:Elastic infrastructure scaling enables mid-sized hospitals to absorb patient volume surges without capital-intensive server procurement, lowering entry barriers for rural and community facilities.
- India's eSanjeevani platform:The central government's national telemedicine infrastructure is aggregating demand across 28 states, creating standardized procurement specifications that domestic software vendors must meet.
Market Restraints
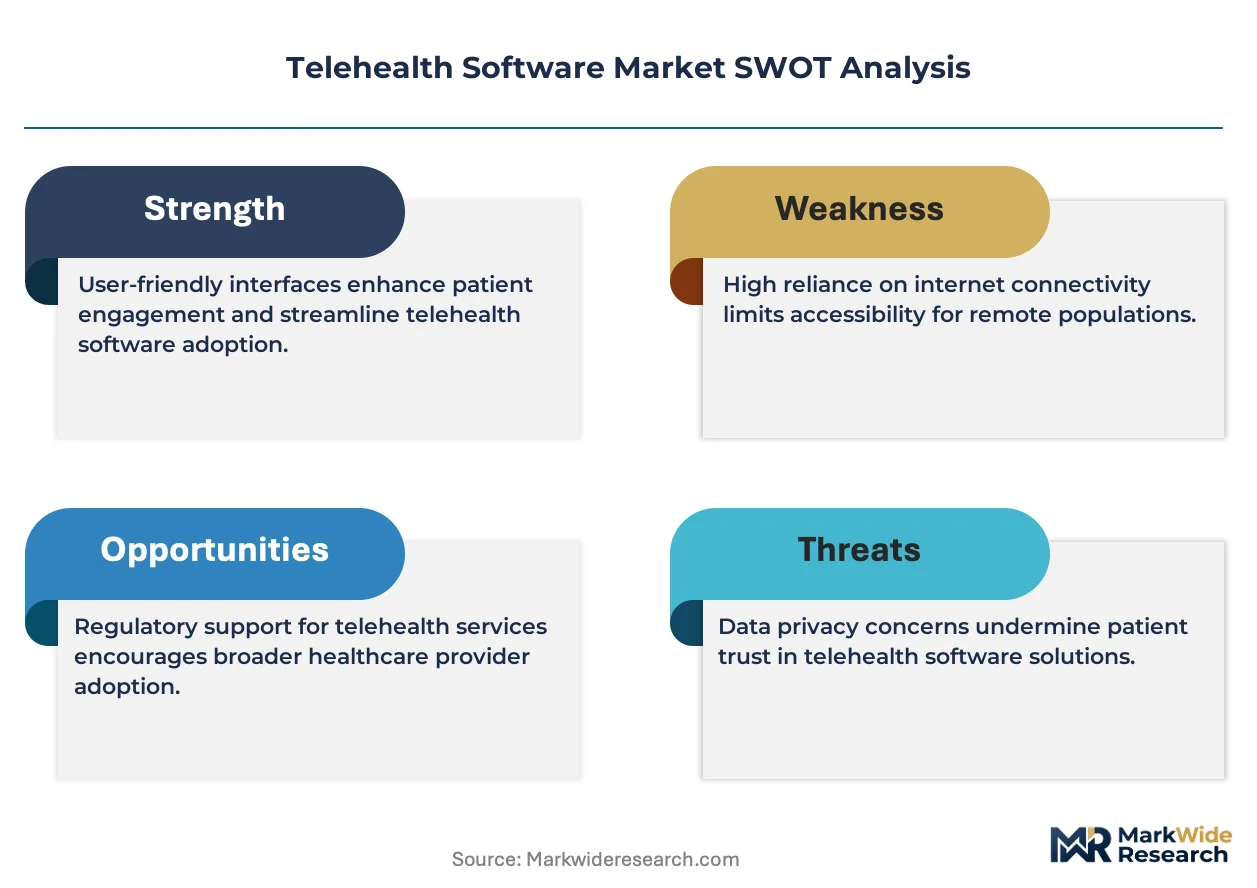
- State medical board licensing fragmentation:Interstate practice regulations require physicians to hold active licenses in each patient location, multiplying compliance overhead for multi-state virtual care networks.
- HIPAA security rule technical safeguards:Encryption, access control, and audit trail requirements impose substantial engineering costs on platforms serving Medicare and Medicaid populations.
- Legacy EHR integration complexity:Epic Systems Corporation's dominance of hospital data layers forces telehealth vendors into expensive custom API development for clinical workflow embedding.
Strategic Opportunities
- Asynchronous store-and-forward diagnostics:Dermatology and radiology applications in underserved United States counties bypass real-time bandwidth constraints while maintaining reimbursable care documentation.
- AI-driven diagnostic decision support:Automated triage algorithms reduce specialist consultation load, opening margin expansion in primary care verticals previously resistant to virtual modalities.
- FDA Software as a Medical Device pathway expansion:Clarified premarket guidance for algorithm-based diagnostic tools accelerates regulatory approval timelines for platforms incorporating predictive analytics.
Industry Challenges
- HL7 FHIR implementation expertise scarcity:Health informatics specialists capable of mapping proprietary data structures to interoperable standards command premium compensation, constraining vendor scaling velocity.
- Physician-patient relationship establishment protocols:State-level definitions of valid clinical encounter initiation vary widely, forcing platforms to maintain jurisdiction-specific workflow configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telehealth Software Market |
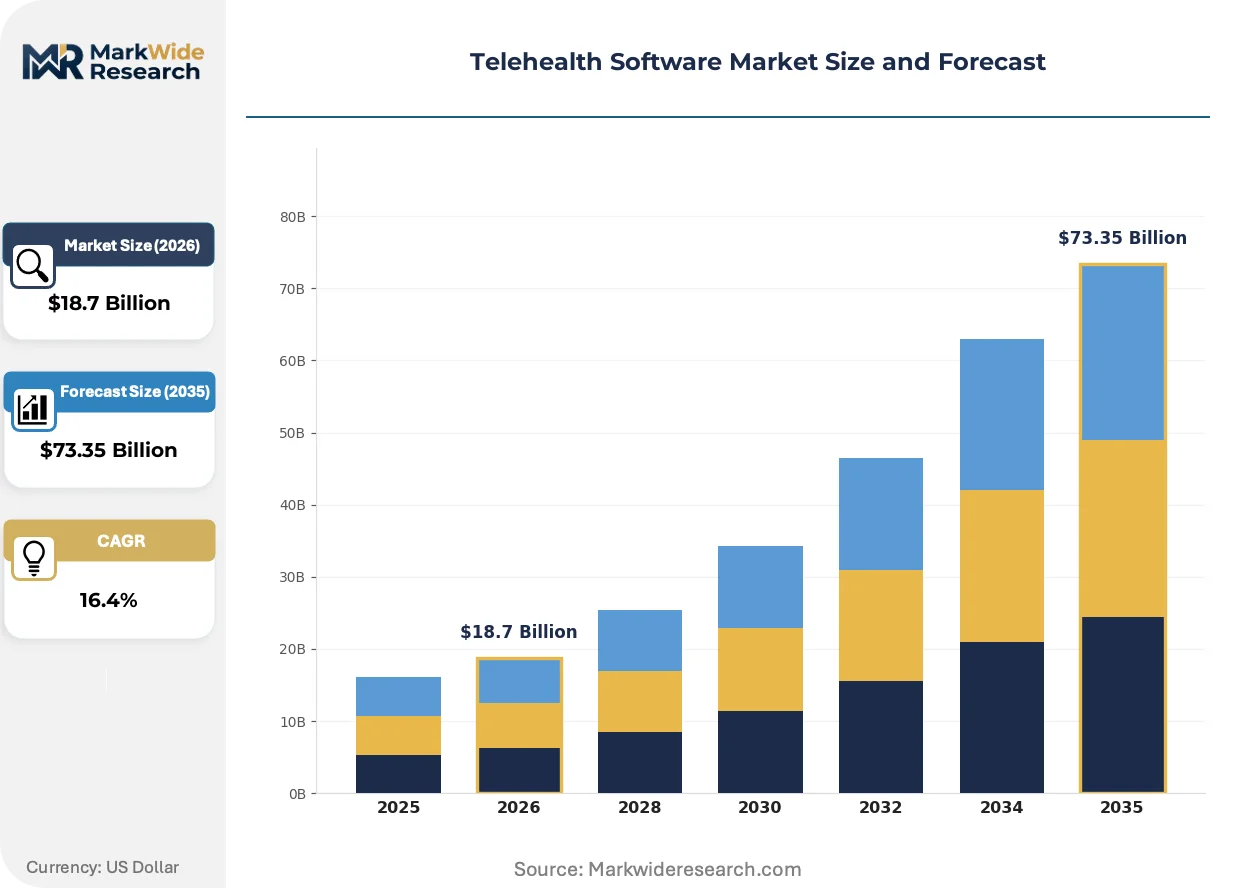
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Conferencing, Patient Management, Consultation, Billing Software End User: Clinics, Hospitals, Patients, Insurance Providers Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Technology: AI-Driven, Blockchain, IoT, Telemonitoring |
| Companies Covered | Teladoc Health Inc., American Well Corporation, Medtronic Inc., GE Healthcare, Koninklijke Philips N.V., Epic Systems Corporation, Oracle Corporation, Allscripts Healthcare LLC, Zoom Video Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telehealth Software Market Strategic Shifts
Artificial intelligence integration is compressing the diagnostic layer of virtual care, shifting competitive advantage from connectivity infrastructure to clinical decision support capabilities.
Machine learning algorithms trained on multimodal patient data are digitizing preliminary symptom assessment and triage routing. Large health systems in the United States are deploying these tools across emergency department overflow and primary care access bottlenecks. The technology is digitizing the front-end clinical encounter, reducing specialist consultation volume by automating low-acuity case resolution.
The FDA's evolving Software as a Medical Device guidance is reclassifying diagnostic algorithms as regulated medical products. Platforms incorporating predictive analytics must now navigate premarket submission pathways previously reserved for physical devices. Vendors with existing 510(k) clearance infrastructure are capturing early-mover advantage in algorithm-based remote monitoring segments.
Direct-to-employer contracting is displacing traditional payer-channel distribution for virtual primary care. Self-insured corporations in manufacturing and logistics verticals are procuring standalone telehealth subscriptions outside insurance benefit structures. This pattern concentrates in the United States Midwest, where employer-sponsored coverage dominates and narrow network designs frustrate employee access to physical specialists.
Telehealth Software Market Segmentation
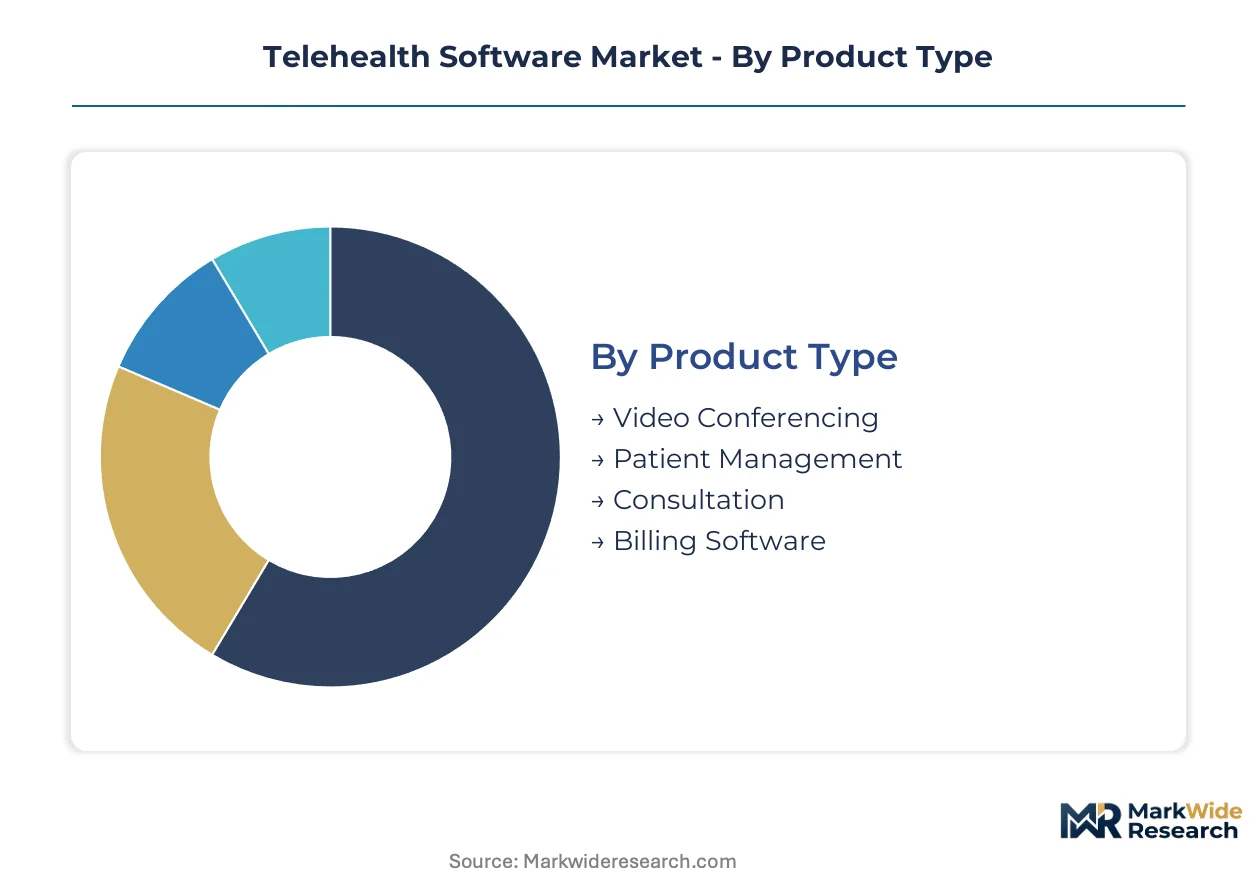
Telehealth software segmentation reveals divergent procurement cycles across product architectures. Cloud-native platforms refresh every 18-24 months while on-premise installations persist for 5-7 years, creating dual-velocity revenue recognition patterns for vendors.
Product Type:
Video conferencing modules turn over fastest as bandwidth standards and UI expectations shift quarterly, whereas billing software exhibits the longest replacement cycles tied to regulatory compliance windows.
- Video Conferencing:Real-time audiovisual infrastructure with end-to-end encryption and low-latency transmission protocols. United States hospital systems are consolidating vendor relationships around platforms integrating with Epic EHR workflows, driven by CMS reimbursement documentation requirements.
- Patient Management:Scheduling, intake, and longitudinal record coordination systems. India's eSanjeevani platform specifications are standardizing feature requirements across 28 states, compressing vendor differentiation to API flexibility.
- Consultation:Clinical workflow tools enabling synchronous and asynchronous provider-patient encounters.
- Billing Software:Claims processing and revenue cycle management with payer-specific coding automation.
Video conferencing anchors the volume base while AI-enhanced consultation modules gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise hospital deployments from lean clinic implementations, with insurance providers representing the highest per-seat expenditure due to compliance overhead.
- Hospitals:Enterprise-grade platforms requiring HL7 FHIR interoperability and multi-department workflow orchestration. United States health systems prioritize Epic-integrated solutions, constrained by legacy EHR migration costs and physician training requirements.
- Insurance Providers:Population-scale analytics and utilization management systems with fraud detection layers. Self-insured employers in the United States Midwest are procuring direct contracts outside traditional payer channels, bypassing benefit structure limitations.
- Clinics:Lightweight platforms emphasizing rapid deployment and minimal IT staffing.
- Patients:Consumer-facing applications with symptom triage and appointment booking functionality.
Hospitals anchor the volume base while insurance provider deployments expand most quickly through employer direct contracting.
Deployment:
Volume concentration favors cloud architectures, though hybrid models are capturing security-sensitive workloads requiring on-premise data residency.
- Cloud-Based:Elastic infrastructure with subscription pricing and automatic security patching. Rural United States health systems are absorbing patient surges without capital expenditure, enabled by CMS reimbursement parity eliminating financial penalties for virtual modalities.
- Hybrid:Split architecture keeping PHI on-premise while leveraging cloud compute for analytics. German hospital networks are deploying this model to satisfy GDPR data localization requirements while accessing AI diagnostic tools.
- On-Premise:Self-hosted servers with full operational control and compliance audit trails.
- Mobile:Native iOS and Android applications with offline capability and push notification triage.
Cloud-based deployment anchors the volume base while hybrid configurations climb the fastest among security-regulated European installations.
Technology:
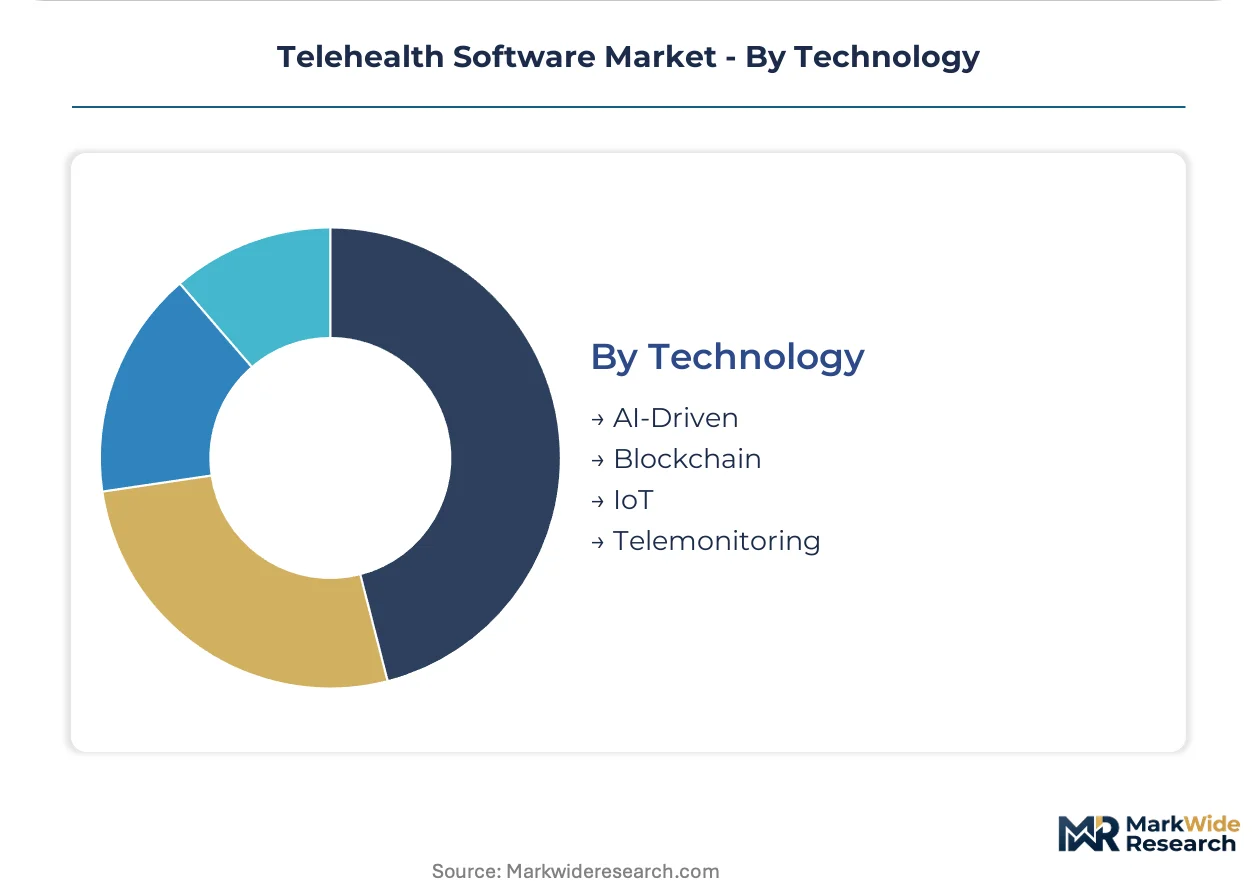
Margin tiering separates AI-driven platforms commanding premium pricing from commodity connectivity layers, with IoT integration representing the highest engineering cost structure.
- AI-Driven:Machine learning diagnostic support and automated triage routing. United States emergency departments are deploying these tools across overflow bottlenecks, reducing specialist consultation volume through low-acuity case resolution.
- IoT:Connected device ecosystems capturing biometric streams and medication adherence signals. FDA Software as a Medical Device guidance is reclassifying predictive algorithms as regulated products, extending premarket timelines for vendors lacking 510(k) infrastructure.
- Blockchain:Distributed ledger systems for credential verification and prescription integrity.
- Telemonitoring:Continuous vital sign transmission with threshold-based alert escalation.
AI-driven technology anchors the volume base while IoT-enabled platforms gain share at the steepest rate through remote patient monitoring reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and self-insured employers drive procurement concentration, with government telemedicine platforms accelerating standardization in emerging markets. Regulatory reimbursement parity and EHR integration requirements shape vendor selection criteria across jurisdictions.
United States
CMS reimbursement parity rules and Epic Systems EHR dominance steer hospital procurement toward integrated virtual care modules. HIPAA security rule technical safeguards impose engineering overhead on platforms serving Medicare populations. The Midwest employer corridor concentrates direct-to-employer contracting outside traditional payer channels.
India
The central government's eSanjeevani platform aggregates demand across 28 states, standardizing procurement specifications for domestic vendors. CDSCO medical device regulations and state-level telemedicine guidelines shape product architecture requirements. Karnataka and Telangana host domestic software development clusters serving national infrastructure deployment.
Germany
German hospital networks deploy hybrid cloud architectures to satisfy GDPR data localization requirements while accessing AI diagnostic tools. The EU AI Act and MDR medical device regulations extend premarket timelines for algorithm-based platforms. The North Rhine-Westphalia medical technology corridor concentrates vendor development activity.
United Kingdom
NHS England procurement frameworks prioritize HL7 FHIR interoperability for virtual care platform selection. UK GDPR and MHRA Software as a Medical Device guidance reshape regulatory compliance architecture. The London-Southeast health technology cluster concentrates startup development and health system pilot programs.
Japan
PMDA digital therapeutics guidance and METI telemedicine reimbursement expansion accelerate hospital adoption of remote patient monitoring platforms. JIS standards and pharmaceutical law amendments govern software classification as medical devices. The Tokyo-Kanto metropolitan corridor concentrates health system consolidation and vendor headquarters placement.
Telehealth Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across three structural tiers. Consolidation pressures concentrate around EHR-integrated platforms and direct-to-employer distribution networks. Two dominant archetypes emerge: connectivity infrastructure providers anchoring video conferencing volume, and clinical workflow specialists embedding virtual care into documentation systems. Competitive moves center on payer partnership expansion and AI diagnostic capability acquisition.
Within the EHR-integrated tier, Epic Systems Corporation and Oracle Corporation exemplify platform consolidation through health system data layer control. Teladoc Health Inc. occupies a position representing direct-to-employer channel specialization, while American Well Corporation sits within the payer-embedded workflow archetype.
| Leading Market Players |
|---|
| Teladoc Health Inc. |
| American Well Corporation |
| Medtronic Inc. |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Epic Systems Corporation |
| Oracle Corporation |
| Allscripts Healthcare LLC |
| Zoom Video Communications Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud infrastructure regions is compressing compute pricing for telehealth vendors, enabling aggressive SaaS subscription rates while forcing suppliers to differentiate through AI capability layers rather than raw connectivity.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared diagnostic modules commanding substantial premiums over uncertified workflow tools. The dominant pricing structure is subscription-based SaaS with tiered seat licensing, though per-consultation transactional models persist in direct-to-employer channels. Price differentiation rests on HL7 FHIR integration depth and AI diagnostic capability maturity. Cost compression in the mid-market tier is intensifying because Epic-integrated alternatives reduce switching flexibility for hospital buyers. Rural health systems exhibit the highest price sensitivity due to constrained IT budgets, while self-insured employers in manufacturing verticals show lowest sensitivity when virtual care reduces specialist network leakage.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers are reshaping vendor working capital requirements, with AWS and Azure supply-chain finance facilities enabling smaller platforms to defer infrastructure costs. Geographic supply concentration centers on the United States for EHR integration expertise, India for software development talent, and Ireland for European data residency compliance. Raw material dependencies include GPU compute clusters for AI training, encrypted video codec licenses, and biometric sensor hardware for remote monitoring modules. Single-source vulnerability in Epic Systems API access creates supply chain risk for workflow-embedded platforms. Distribution runs through health system GPO contracts, payer benefit administrators, and direct-to-employer procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth software is fundamentally a service-attach opportunity, with AI diagnostic subscriptions and remote monitoring data analytics expanding faster than core video conferencing licenses.
For Market Incumbents: Pre-empt margin erosion in the connectivity layer by acquiring FDA-cleared diagnostic algorithm startups before they achieve independent distribution. Consolidate position through exclusive payer partnerships that embed virtual care into prior authorization workflows, neutralizing the threat of standalone AI triage platforms. Deepen vertical integration into remote patient monitoring hardware to capture recurring device data fees.
For New Entrants and Emerging Players: Rural United States counties with broadband infrastructure expansion represent the most penetrable geography, bypassing Epic-integrated incumbent strongholds. Target asynchronous store-and-forward specialties like dermatology and radiology where real-time bandwidth requirements are minimal. Pursue direct contracting with self-insured manufacturing employers in the Midwest corridor, outside traditional payer channel gatekeeping.
For Investors and Strategic Acquirers: Capital is best deployed toward clinical workflow specialists with existing 510(k) clearance infrastructure and hospital system pilot contracts. Long-term viability favors platforms that control the diagnostic decision layer rather than commodity video connectivity. Watch for FDA Software as a Medical Device guidance expansion as the signal indicating which algorithm-based tools will capture reimbursable care pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Premarket clearance for diagnostic algorithms unlocks CMS reimbursement parity and hospital procurement eligibility. |
| Epic EHR Integration Partnership | Workflow embedding through HL7 FHIR APIs secures access to hospital system clinical data layers. |
| Direct-to-Employer Contracting Expansion | Bypassing payer channels captures self-insured corporations in manufacturing and logistics verticals. |
| AI Diagnostic Capability Acquisition | Machine learning triage tools reduce specialist consultation volume and expand margin in primary care. |
| Remote Patient Monitoring Data Strategy | Continuous biometric streams create recurring revenue through reimbursement-eligible RPM codes. |
Study Parameters
Operator-level perspectives from telehealth platform CTOs, hospital system CMIOs, payer digital health directors, and FDA regulatory affairs consultants anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement rulemaking dockets, hospital GPO contract disclosures, and Epic Systems integration partner directories. Bottom-up sizing of vendor subscription revenues triangulated against top-down health system IT spending surveys.
Scenario-bracketing around CMS reimbursement parity durability and HL7 FHIR adoption velocity framed the projection horizon. Segmentation modeling spanned deployment architecture, end-user organization type, technology capability layer, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and vendor revenue recognition patterns. Forecast inputs included state medical board telemedicine licensing expansion rates and employer-sponsored health benefit design shifts.
Practitioners should monitor FDA Software as a Medical Device guidance revisions and state-level physician-patient relationship definition changes for early signals. Forecasts reflect assumptions about reimbursement parity maintenance and EHR integration cost trajectories. Macroeconomic pressure on employer health spending, regulatory restriction of asynchronous consult reimbursement, or breakthrough AI diagnostic accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Remote Healthcare Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Teledermatology Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
US Telemedicine Market
Telemedicine
Global Telehealth Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Telestroke Services Market