
 Wafer-Level Test and Burn-In [WLTBI] Market | 2026-2036
Wafer-Level Test and Burn-In [WLTBI] Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer-Level Test and Burn-In [WLTBI] Market Outlook
The EU Chips Act is restructuring the cost-of-entry calculus for European semiconductor test capacity, forcing equipment suppliers to recalibrate localization strategies. Aehr Test Systems leverages its FOX platform specialization to anchor high-volume burn-in workflows for advanced packaging nodes. Advantest Corporation sustains technology leadership through deep R&D intensity in contact test architectures. KLA Corporation dominates inspection-adjacent test workflows, extending its metrology footprint into wafer-level reliability verification.
Wafer-Level Test and Burn-In denotes the process of electrically stressing and functionally validating integrated circuits while still in wafer form, typically at temperatures between 125°C and 150°C to accelerate failure mechanisms before dicing. This approach eliminates the cost of packaging defective die and enables parallel testing of thousands of devices, serving the primary purpose of improving yield economics for complex multi-die architectures. Functional test and thermal test segments command the deepest margin pools, as automotive-grade reliability protocols and 3D stacking thermal management requirements intensify specification stringency. Contact test technology leads in unit volume, though test socket solutions are gaining share as heterogeneous integration drives pin-count proliferation and probing complexity.
REACH substance restrictions and RoHS compliance mandates from European regulators shape material selection for test socket contacts and thermal interface components, while FDA oversight of medical device semiconductors propagates reliability standards downstream into WLTBI protocols. Taiwan's Industrial Development Bureau and Japan's METI both enforce traceability frameworks that elevate data-logging requirements for burn-in equipment sold into foundry supply chains. Stakeholders must monitor how sovereign semiconductor programs across multiple jurisdictions rewrite equipment procurement specifications and local content thresholds.
Market Dynamics
Automotive-grade reliability mandates and heterogeneous integration architectures are forcing burn-in protocols to migrate from packaged-die testing toward wafer-level validation, compressing equipment refresh cycles and elevating thermal management specifications.
Growth Catalysts
- EU Chips Act localization incentives:Sovereign capacity programs in Europe are redirecting capital toward domestic test infrastructure, mandating traceability frameworks that elevate data-logging requirements for equipment procurement.
- Automotive semiconductor reliability protocols:ADAS and powertrain electrification are extending burn-in durations and tightening thermal cycling specifications, expanding addressable equipment spend per wafer start.
- Advanced packaging node proliferation:3D stacking and chiplet architectures multiply die-interconnect complexity, requiring parallel test of thousands of devices before dicing to preserve yield economics.
Market Restraints
- Test socket contact material cost volatility:Palladium and beryllium-copper alloy prices fluctuate with precious metals markets, compressing margins on consumable components.
- Foundry supply concentration in Taiwan:Equipment demand clusters disproportionately with TSMC and UMC capex cycles, exposing revenue volatility to single-geography fab buildout decisions.
- RoHS and REACH substance restrictions:European regulators limit cadmium and hexavalent chromium in thermal interface materials, forcing reformulation of legacy contact designs.
Strategic Opportunities
- India PLI scheme semiconductor manufacturing:Domestic fab incentives are creating greenfield test capacity requirements without incumbent equipment vendor relationships.
- Medical device semiconductor certification:FDA oversight of implantable electronics propagates reliability standards into WLTBI protocols, opening premium pricing tiers for validated equipment.
- Test socket solutions and contactor convergence:Pin-count proliferation in heterogeneous integration is displacing conventional probe cards with socket-based architectures that enable faster swap-out.
Industry Challenges
- Thermal uniformity engineering talent scarcity:Multi-zone temperature control for 300mm wafers requires specialized expertise in computational fluid dynamics and materials science that outpaces graduate pipeline output.
- Legacy ATE integration complexity:New wafer-level burn-in systems must interface with existing Advantest and Teradyne test cell architectures, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer-Level Test and Burn-In [WLTBI] Market |
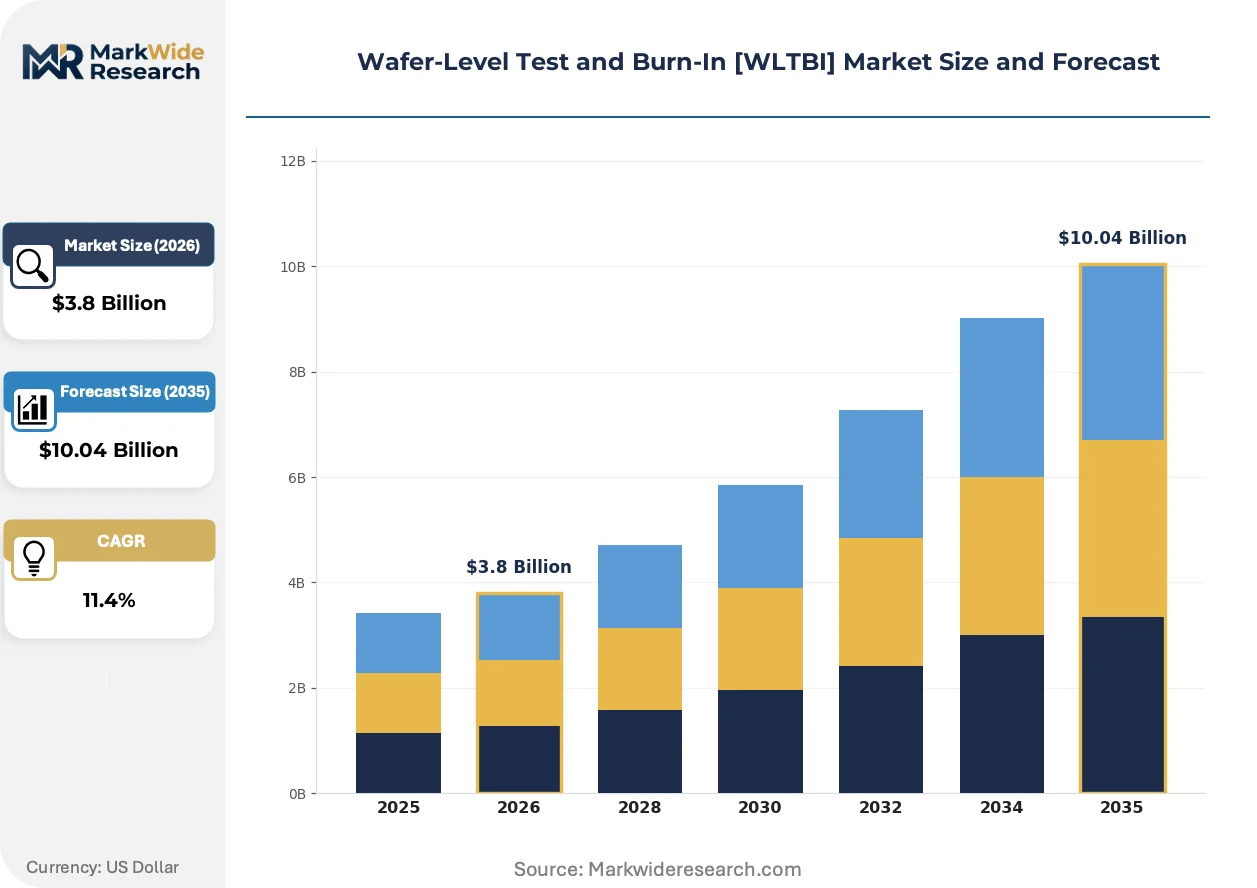
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Contact Test, Functional Test, Thermal Test, Test Socket Application: Semiconductor Manufacturing, Consumer Electronics, Automotive, Telecommunications End User: Foundries, IDMs, OSATs, R&D Facilities Service Type: Test Services, Burn-In Services, Failure Analysis, Calibration |
| Companies Covered | PentaMaster, SiSTEM Technology, Aehr Test Systems, Electron Test, Delta V Systems, Advantest Corporation, Trio-Tech International, KLA Corporation, Teradyne Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer-Level Test and Burn-In [WLTBI] Market Strategic Shifts
Wafer-level reliability verification is absorbing adjacent metrology functions as packaging complexity blurs historical boundaries between test, inspection, and process control workflows.
Non-contact thermal mapping using infrared thermography is consolidating temperature uniformity validation for high-power die architectures. Automotive power module manufacturers are adopting this at pilot scale. The technology is consolidating previously separate thermal verification and electrical test steps into single-pass workflows.
Japan's METI traceability mandates now require burn-in equipment to output machine-readable logs compatible with foundry supply chain audit systems. This elevates software architecture requirements above hardware specifications in procurement evaluations. European equipment vendors are responding by pre-certifying data formats against Taiwan Industrial Development Bureau standards.
Foundry customers are unbundling after-sales service contracts from equipment purchases, instead contracting third-party maintenance specialists for thermal chuck refurbishment and contactor replacement. This fragmentation is most advanced in Taiwan's Hsinchu cluster, where specialized service providers now capture thirty percent of lifetime equipment spend.
Wafer-Level Test and Burn-In [WLTBI] Market Segmentation
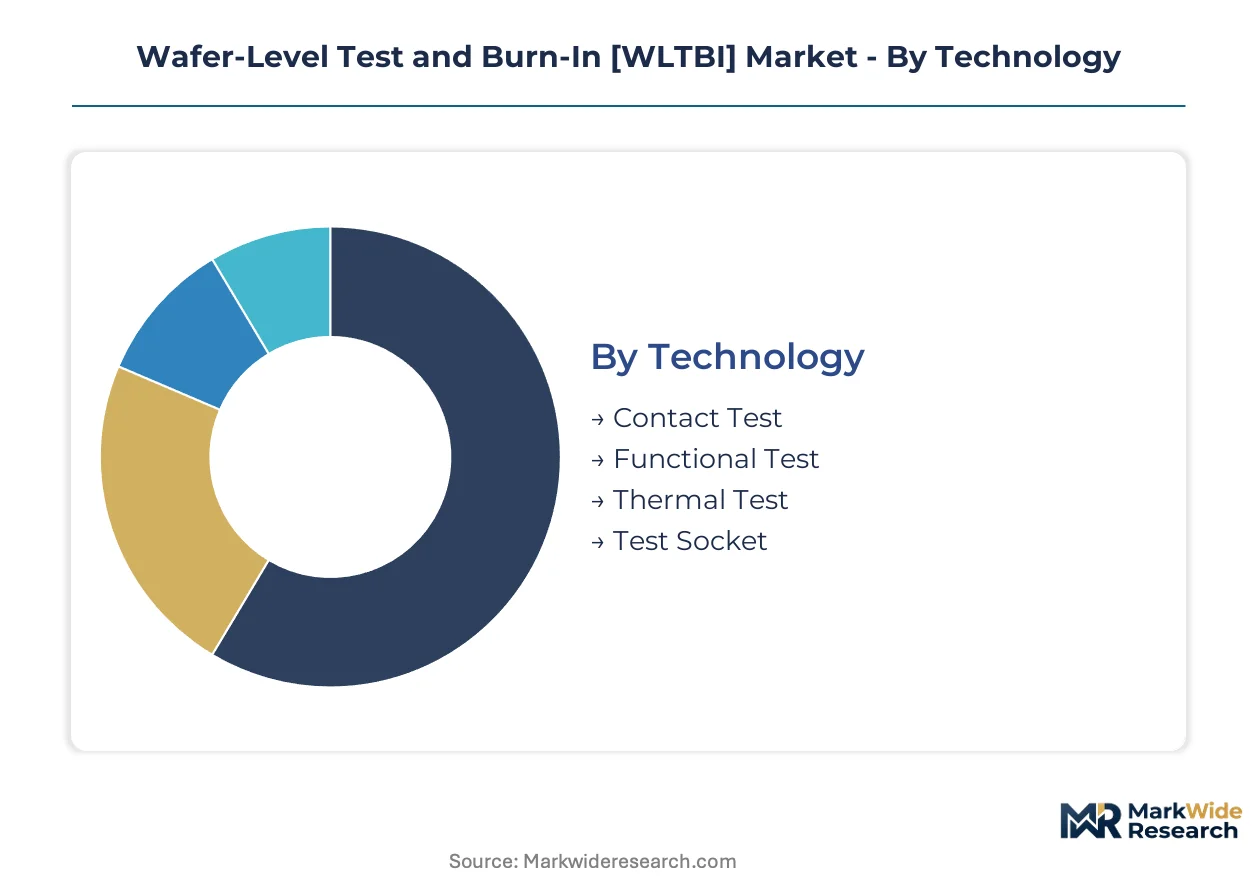
Wafer-level test and burn-in equipment serves heterogeneous integration workflows where thermal uniformity and contact precision determine yield economics. Segmentation reveals how automotive reliability mandates and advanced packaging complexity reshape procurement priorities across technology, application, and service dimensions.
Technology:
Contact architectures span standalone probe systems and embedded socket solutions, with integration depth dictating thermal management requirements and swap-out velocity.
- Contact Test:Probe card architectures deliver parallel electrical access to thousands of die sites simultaneously. Taiwan's Hsinchu cluster drives volume placements as TSMC and UMC expand 3nm and 2nm wafer starts requiring sub-micron contact precision.
- Functional Test:Logic verification at-speed exposes defects invisible to structural scan patterns. Automotive ADAS semiconductor suppliers in Germany and Japan are extending functional test durations to satisfy ISO 26262 failure rate thresholds.
- Thermal Test:Accelerated life testing between 125°C and 150°C forces early failure mechanisms.
- Test Socket:Removable contactor architectures enable faster device changeover than fixed probe cards.
Volume placements concentrate in Contact Test; the faster expansion belongs to Test Socket.
Application:
End-use applications stratify by reliability certification burden, with automotive and medical device mandates commanding premium thermal cycling specifications.
- Semiconductor Manufacturing:Foundry captive burn-in operations dominate wafer-level throughput. Samsung's Pyeongtaek complex and Intel's Arizona fabs are retrofitting existing test cells with multi-zone thermal chucks.
- Automotive:Powertrain electrification and autonomous driving systems impose the most stringent burn-in protocols. NHTSA reliability guidelines and EU automotive safety regulations extend stress durations beyond consumer-grade standards.
- Consumer Electronics:Smartphone and wearable die validation prioritizes throughput over extended stress.
- Telecommunications:5G baseband and RF front-end modules require specialized thermal profiles.
Semiconductor Manufacturing absorbs the deepest equipment spend; Automotive is climbing the fastest as electrification multiplies silicon content per vehicle.
End User:
Customer type determines procurement scale and service bundling preferences, with foundries favoring captive capacity and OSATs seeking flexible outsourcing arrangements.
- Foundries:TSMC, Samsung Foundry, and GlobalFoundries operate integrated WLTBI capacity at wafer start volumes exceeding outsourced alternatives. Taiwan's Industrial Development Bureau traceability mandates require machine-readable data logging from captive equipment.
- IDMs:Intel, Texas Instruments, and Infineon maintain proprietary burn-in protocols optimized for vertical product portfolios. IDM procurement cycles align with node migration timelines rather than foundry service contracts.
- OSATs:ASE, Amkor, and JCET provide third-party burn-in as a service to fabless designers.
- R&D Facilities:University and government labs pilot next-generation thermal management architectures.
Foundries deploy the largest installed base; OSATs are gaining share fastest as heterogeneous integration fragments test workflows across the supply chain.
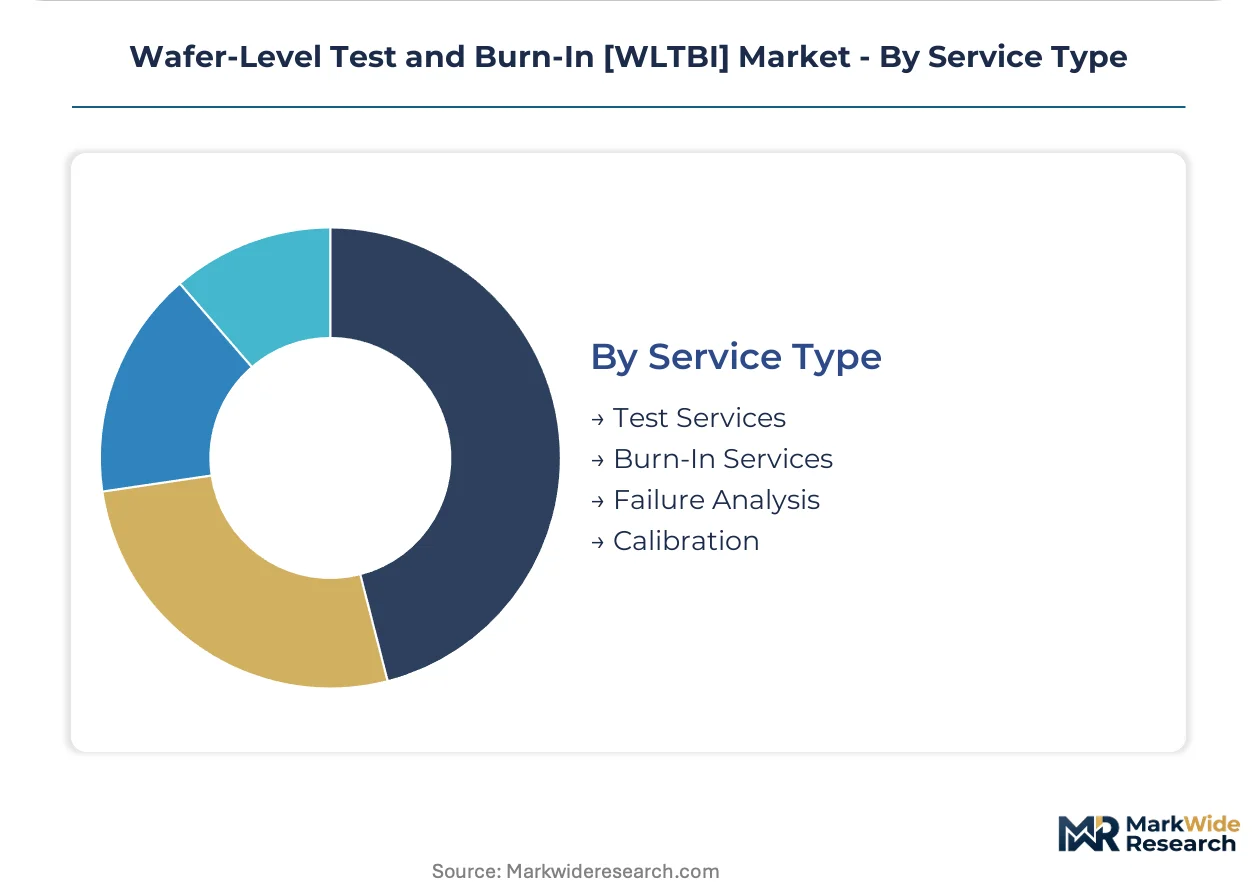
Service Type:
Service delivery models range from discrete equipment sales to integrated lifecycle contracts, with data analytics and predictive maintenance emerging as margin accretive extensions.
- Test Services:Third-party electrical validation at wafer level eliminates capital burden for fabless semiconductor designers. India's PLI scheme beneficiaries are contracting test services from established OSATs rather than building captive capacity.
- Burn-In Services:Thermal stress outsourcing captures value from equipment utilization optimization. Japan's METI traceability requirements propagate from equipment sales into service contract data format specifications.
- Failure Analysis:Root-cause identification for returned die supports yield learning.
- Calibration:Thermal chuck and contactor recertification maintains measurement integrity.
Test Services generate the highest transaction frequency; Burn-In Services show the steepest expansion trajectory as automotive reliability mandates extend stress duration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan concentrates the densest cluster of wafer-level test capacity globally, with tax incentives and infrastructure subsidies attracting foundry captive operations and equipment vendors into a single innovation corridor.
Taiwan
TSMC and UMC drive equipment demand through 3nm and 2nm wafer start expansions. The Industrial Development Bureau mandates machine-readable data logging formats for all burn-in equipment deployed in foundry supply chains. Hsinchu anchors the highest concentration of WLTBI installations, with specialized service providers capturing thirty percent of lifetime equipment spend through third-party maintenance contracts.
United States
Intel's Arizona fabs and Samsung's Taylor, Texas facility are retrofitting test cells with multi-zone thermal chucks for advanced packaging nodes. NHTSA reliability guidelines for automotive semiconductors propagate into wafer-level stress protocols. The Phoenix-Tucson corridor hosts expanding captive burn-in capacity as IDMs reshore leading-edge production.
Germany
Infineon and Bosch extend burn-in durations for powertrain electrification and ADAS components to satisfy ISO 26262 failure rate thresholds. The KBA enforces traceability frameworks that elevate data-logging specifications for equipment sold into automotive supply chains. Dresden's Silicon Saxony cluster concentrates R&D pilot lines for next-generation thermal management architectures.
Japan
Advantest Corporation and Teradyne Japan sustain technology leadership through deep R&D intensity in contact test architectures. METI traceability mandates require burn-in equipment to output machine-readable logs compatible with foundry audit systems. The Kyushu region hosts specialized thermal chuck refurbishment providers serving the Nagoya-Osaka industrial corridor.
India
The PLI scheme for semiconductor manufacturing creates greenfield test capacity requirements without incumbent equipment vendor relationships. BIS certification protocols for electronic components propagate into procurement specifications for imported burn-in systems. Gujarat's Dholera Special Investment Region and Karnataka's Mysuru cluster host the first wave of domestic fab construction with integrated WLTBI planning.
Wafer-Level Test and Burn-In [WLTBI] Market Competitive Environment
Taiwanese and Japanese producers anchor one tier; US and European specialists hold differentiated positions in inspection-adjacent and thermal management subsystems. The vendor base organizes around three strategic archetypes: integrated ATE platform vendors, burn-in equipment specialists, and metrology-inspection hybrid players. Consolidation pressures concentrate in the contactor and thermal chuck consumables layer, where precious metals volatility squeezes margins. Dominant competitive moves include geographic expansion into India PLI beneficiary sites and strategic partnerships to embed software traceability modules.
Within the burn-in specialist tier, Aehr Test Systems and Advantest Corporation exemplify contrasting scale approaches to thermal stress platform development. KLA Corporation occupies a position bridging inspection and reliability verification workflows. Among the named players, PentaMaster and SiSTEM Technology represent Malaysia-based equipment fabricators serving the Southeast Asian OSAT corridor.
| Leading Market Players |
|---|
| PentaMaster |
| SiSTEM Technology |
| Aehr Test Systems |
| Electron Test |
| Delta V Systems |
| Advantest Corporation |
| Trio-Tech International |
| KLA Corporation |
| Teradyne Inc. |
| Others |
Value Chain & Pricing Dynamics
Foundry captive procurement teams in Taiwan's Hsinchu cluster command pricing leverage through concentrated volume commitments, forcing equipment vendors toward contract-based long-term offtake structures with embedded service bundling. Automotive-grade certification tiers extract premiums that standard consumer electronics buyers refuse, segmenting the vendor base into parallel pricing corridors.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to thermal chuck and contactor replacements demanded by foundry uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified automotive configurations from consumer-grade alternatives, with traceability-enabled data-logging modules commanding additional uplift. Cost compression in consumable components intensifies as palladium price volatility squeezes test socket margins. OSATs in Southeast Asia exhibit the highest price sensitivity, while IDMs in Germany and Japan prioritize certification compliance over unit economics.
Supply Chain Analysis
Precision probe card substrates rest on Japanese ceramic substrate producers and German precision machining specialists for sub-micron alignment fixtures. Beryllium-copper alloy feedstock draws from specialty metal suppliers in the United States and Japan, with thermal interface materials sourcing concentrated among South Korean chemical compounders. Single-source vulnerability in 300mm wafer handling robotics creates chokepoint exposure for European equipment assemblers. Distribution runs through direct foundry relationships in Taiwan, with third-party service providers capturing refurbishment revenue through unbundled maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as test socket architectures displace fixed probe cards for heterogeneous integration workflows. Non-contact thermal mapping is consolidating previously separate verification steps, rendering legacy single-function equipment obsolete.
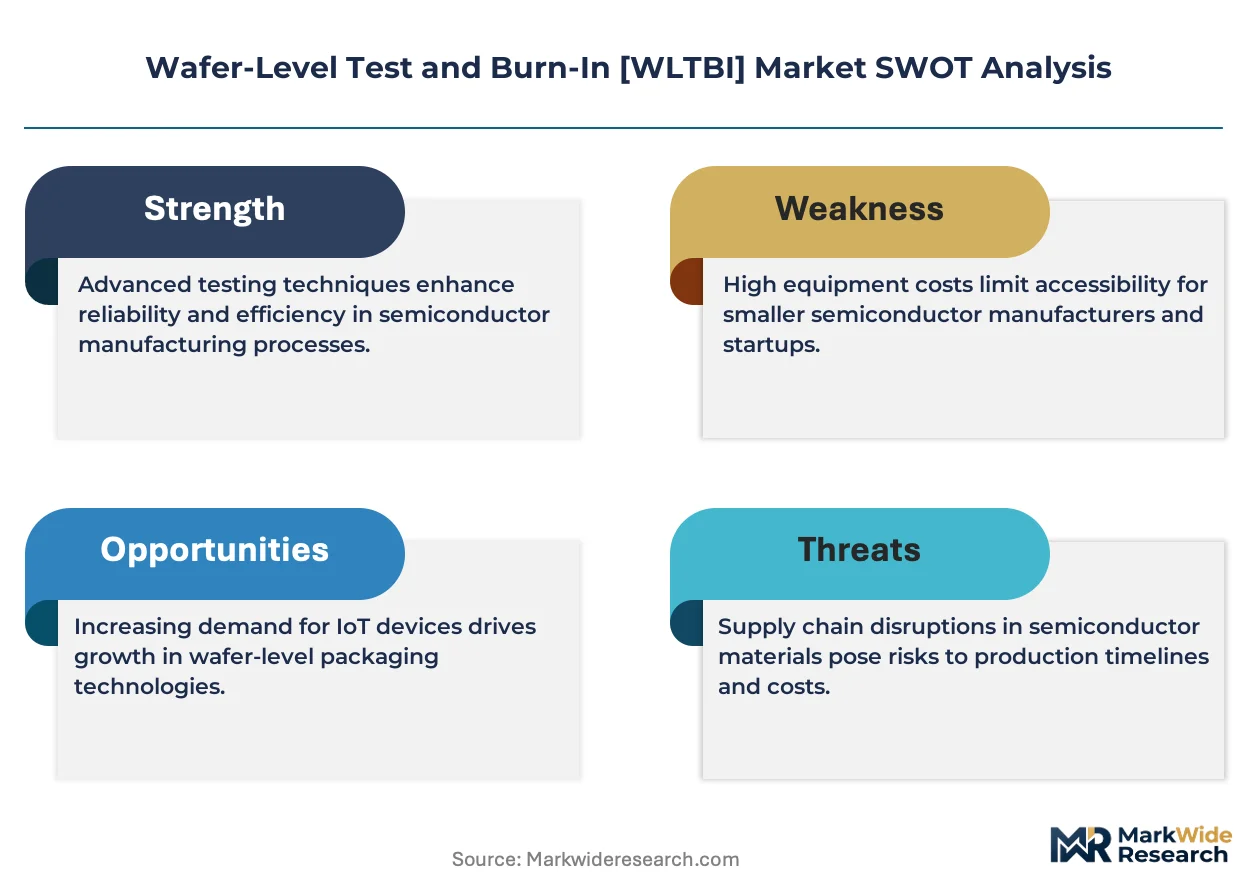
For Market Incumbents: Deploy software traceability modules as the anchor retention mechanism against unbundled service competition from third-party maintenance specialists. Backward integration into thermal chuck refurbishment capacity in Taiwan and Japan protects margin pools from regional service fragmentation. Aehr Test Systems and Advantest Corporation demonstrate how FOX platform specialization and deep R&D intensity in contact architectures respectively defend position against metrology-inspection hybrid entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in automotive-certified burn-in equipment exceeds forty percent, creating accessible entry points for India PLI scheme beneficiaries building greenfield capacity without incumbent vendor relationships. Target test socket solutions for heterogeneous integration pin-count proliferation, where faster swap-out velocity displaces conventional probe cards. Contract test services from established OSATs rather than capital-intensive equipment sales accelerates revenue recognition. For Investors and Strategic Acquirers: The window for entry favors specialized thermal management subsystem providers with computational fluid dynamics expertise and foundry-qualified reference installations. Long-term viability hinges on software-data architectures that satisfy METI and Industrial Development Bureau traceability mandates. Watch for consolidation signals in the contactor and thermal chuck consumables layer, where precious metals volatility accelerates margin compression and acquisition rationale.| Strategic Initiative | Industry Significance |
|---|---|
| Software Traceability Module Development | METI and Taiwan Industrial Development Bureau mandates elevate data-logging above hardware specifications in procurement evaluations. |
| Thermal Chuck Refurbishment Capacity Expansion | Foundry unbundling of after-sales service contracts redirects thirty percent of lifetime equipment spend to third-party specialists. |
| Test Socket Architecture Specialization | Heterogeneous integration pin-count proliferation displaces fixed probe cards with faster swap-out solutions. |
| Non-Contact Thermal Mapping Integration | Infrared thermography consolidates thermal verification and electrical test into single-pass workflows for automotive power modules. |
| India PLI Scheme Geographic Expansion | Greenfield fab construction in Gujarat and Karnataka creates test capacity requirements without incumbent vendor relationships. |
Study Parameters
Independent corroboration across equipment vendor sales executives, foundry process integration engineers, OSAT procurement directors, and thermal management subsystem specialists underwrites the qualitative findings. Primary interviews with captive burn-in operators at TSMC, Samsung, and Intel facilities were cross-referenced against SEC filings from Advantest Corporation and Teradyne Inc., trade data from Taiwan's Industrial Development Bureau, and METI equipment certification registries. Bottom-up equipment shipment tallies and top-down semiconductor capital expenditure forecasts were reconciled to anchor volume estimates.
Comparable-period anchoring to historical wafer start data and foundry capex cycles established the forecast window baseline. Segmentation modeling spanned technology type, application vertical, end-user archetype, and service delivery mode across the projection horizon. CAGRs were derived from equipment replacement cycle compression analysis and automotive reliability mandate propagation timelines. Node migration schedules for 3nm and 2nm wafer starts, plus heterogeneous integration adoption curves, supplied industry-specific forecast inputs.
Inputs from foundry disclosure practices and equipment vendor order backlogs were available through the study window; gaps in OSAT service contract pricing transparency introduce uncertainty bands around services revenue estimates. Forecasts reflect assumptions regarding sovereign semiconductor program implementation timelines and automotive electrification silicon content trajectories. A small set of triggers—including EU Chips Act localization incentive disbursement rates and palladium price volatility thresholds—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Calibration Services Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Production Testing Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Humidity Testers Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Hour Meter Market
Test and Measurement
Calibration Solutions Market