
 Torsion Tester Market | 2026-2036
Torsion Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Torsion Tester Market Outlook
ASTM E143 torque calibration standards are reorganizing procurement priorities across materials laboratories. ZwickRoell leverages its German manufacturing base to dominate European certification-grade installations. Shimadzu Corporation anchors Asian demand through electromechanical platform specialization. ADMET competes in North American quality control segments with modular benchtop configurations.
A torsion tester applies controlled rotational force to specimens to measure shear modulus, yield strength, and ultimate torsional stress, typically operating at angular displacement rates from 0.1 to 60 degrees per minute for metals, polymers, and composites. Digital torsion testers now lead revenue contribution as laboratories replace analog dial indicators with USB-interfaced load cells and automated data acquisition. Electromechanical technology is displacing hydraulic actuation below 5,000 Nm torque ranges due to cleaner operation and reduced maintenance intervals. Portable units remain a narrow segment serving field inspection of installed shafts and fasteners.
FDA device fatigue protocols, ASTM E143 torsional standards, and ISO 6892-2 metallic test methods collectively determine equipment specification sheets and validation documentation requirements. The EU Machinery Directive through CE marking mandates emergency stop integration and guarding for automated torsion systems above specified energy thresholds. Stakeholders must monitor evolving battery-electric vehicle drivetrain specifications where novel rotor materials require expanded torsional fatigue databases.
Market Dynamics
ASTM E143 torque calibration revisions are forcing materials laboratories into accelerated equipment replacement cycles, compressing the installed base renewal timeline from typical ten-year intervals toward seven-year cycles as compliance documentation requirements tighten.
Growth Catalysts
- Battery-electric drivetrain validation:Automotive OEMs in Germany require expanded torsional fatigue databases for novel rotor materials, pulling demand for high-capacity electromechanical testers.
- REACH substance restrictions:European polymer compounders face mandatory shear modulus verification for recycled-content resins, expanding laboratory testing volumes.
- Composite shaft proliferation:Aerospace manufacturers in France and Italy are extending testing protocols to lightweight carbon-fiber torque tubes, requiring multi-axis torsion-tension systems.
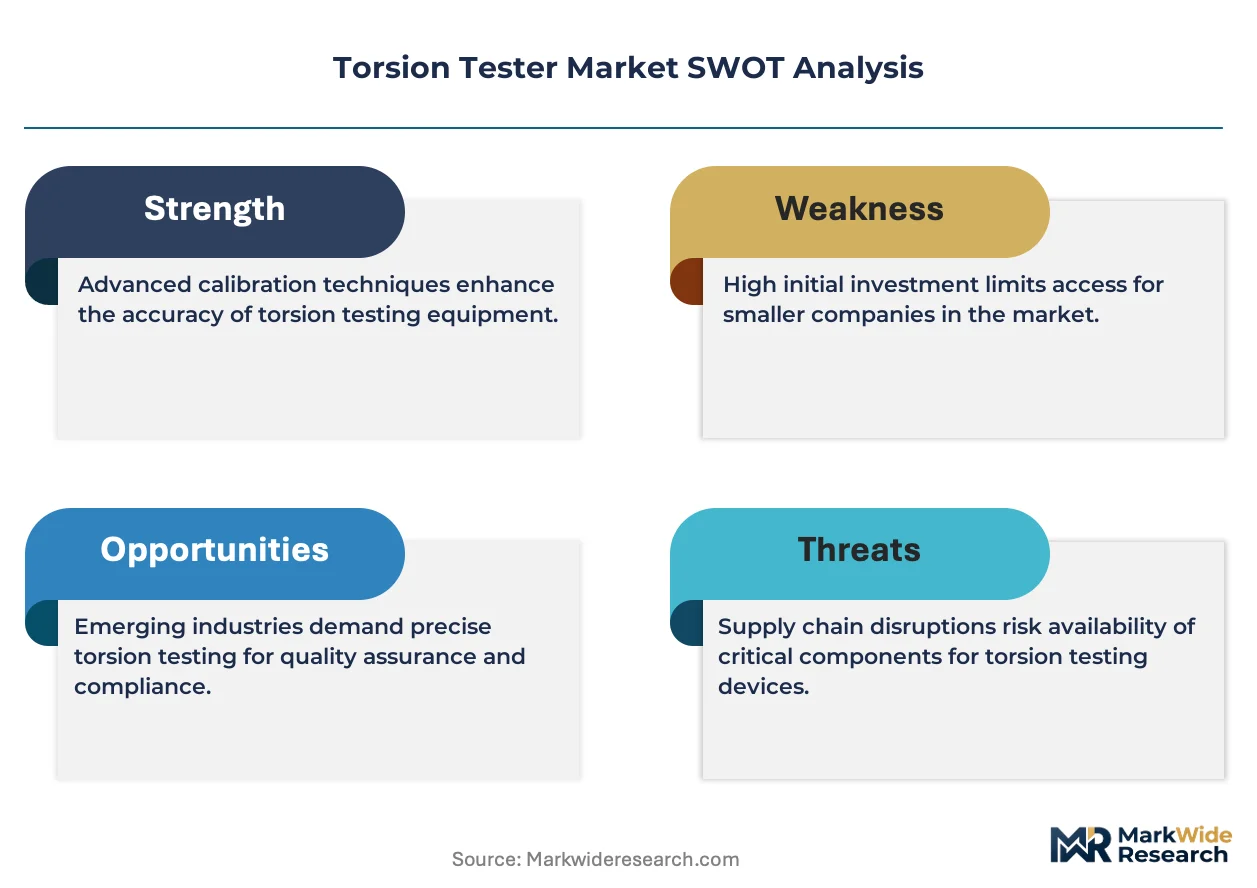
Market Restraints
- Load cell supply concentration:Strain gauge manufacturing clusters in Japan create single-source vulnerability for precision torque measurement subassemblies.
- CE marking cost escalation:EU Machinery Directive compliance for automated torsion systems above specified energy thresholds adds fifteen to twenty percent to system pricing.
- Calibration labor scarcity:Certified metrology technicians capable of ASTM E143 traceability documentation command premium wages, constraining service network expansion.
Strategic Opportunities
- Indian automotive supplier certification:BIS standards alignment with ISO 6892-2 creates first-mover positioning for test equipment vendors establishing local calibration partnerships.
- Field inspection services:Portable torsion verification units for installed wind turbine shafts and offshore fastener audits represent an underdeveloped service revenue stream.
- Digital twin integration:Convergence of USB-interfaced load cells with predictive maintenance platforms enables outcome-based equipment performance contracts.
Industry Challenges
- Legacy analog system migration:Laboratories face eighteen-month recertification timelines when replacing dial-indicator torsion testers with digital platforms, disrupting testing schedules.
- Multi-standard harmonization:ISO 6892-2 metallic test methods and ASTM E143 torque protocols maintain divergent calibration intervals, complicating equipment specification for multinational facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torsion Tester Market |
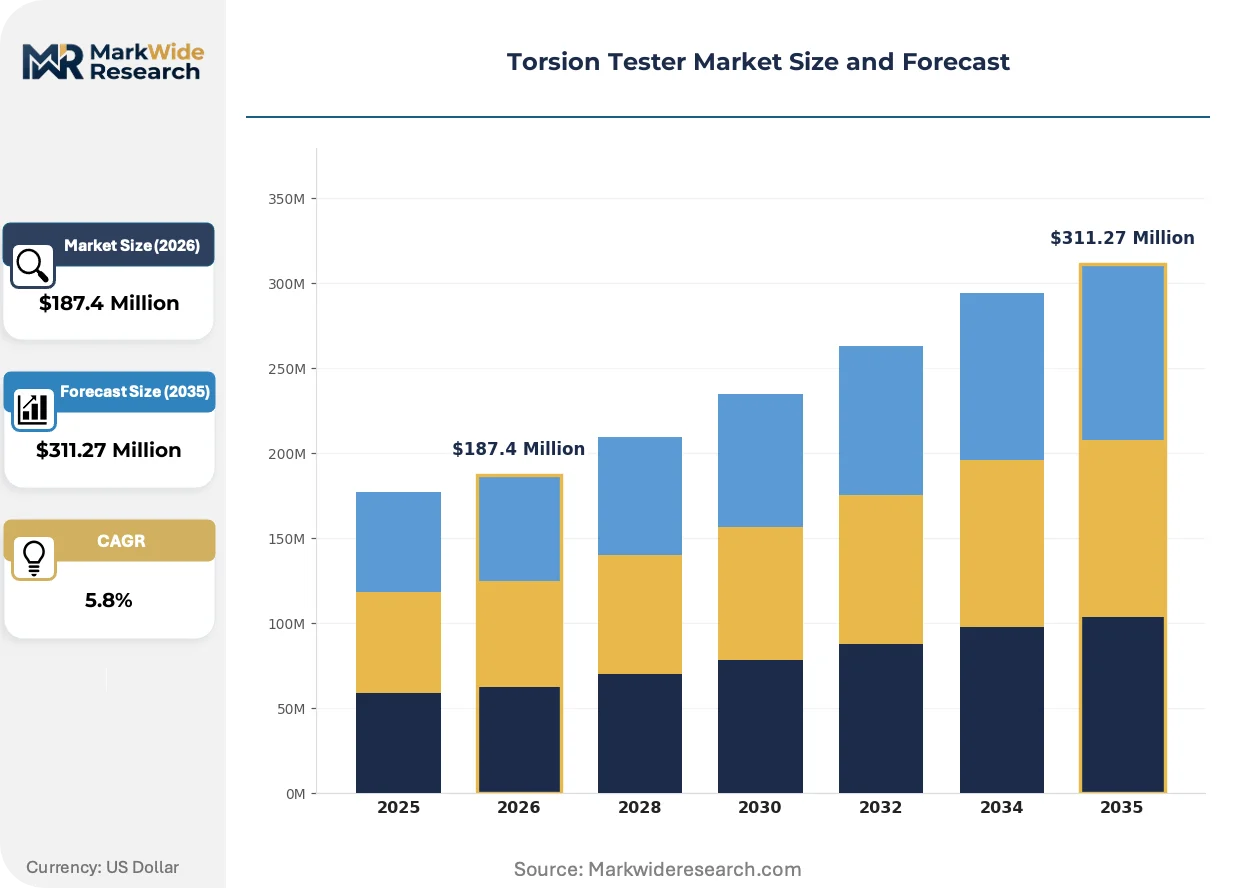
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Torsion Tester, Mechanical Torsion Tester, Portable Torsion Tester, Custom Torsion Tester Application: Material Testing, Quality Control, Research & Development, Product Development End User: Aerospace, Automotive Manufacturing, Construction, Electronics Technology: Hydraulic, Pneumatic, Electromechanical, Manual |
| Companies Covered | ZwickRoell, Shimadzu Corporation, ADMET, Instron, Tinius Olsen, FORM+TEST GmbH, Gotech Testing Machines Inc., Qualitest International Inc., MTS Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torsion Tester Market Strategic Shifts
Electromechanical actuation architectures are rewriting equipment procurement criteria across torque ranges below five thousand Newton-meters, while regulatory documentation requirements are compressing the acceptable lag between standard publication and laboratory compliance.
Digital torsion testers with USB-interfaced load cells and automated data acquisition are decomposing the traditional technician-mediated testing workflow. Automotive Tier-1 suppliers in Germany and Japan are adopting these platforms at replacement-cycle pace rather than waiting for full depreciation. This shift is decomposing the aftermarket calibration service model by embedding self-diagnostic routines that reduce external metrology dependency.
The EU Machinery Directive through CE marking mandates emergency stop integration and guarding for automated torsion systems above specified energy thresholds. Equipment manufacturers must redesign safety enclosures and control architectures to satisfy these provisions. Laboratories in France, Italy, and Spain are prioritizing pre-certified platforms to avoid extended commissioning timelines.
Specification-driven procurement is consolidating purchasing authority within centralized metrology departments, displacing the historical pattern of individual laboratory managers selecting equipment. Distributor relationships are yielding to direct manufacturer engagement for complex multi-station installations. This concentration is most visible among German automotive OEMs operating dense supplier networks for drivetrain component validation.
Torsion Tester Market Segmentation
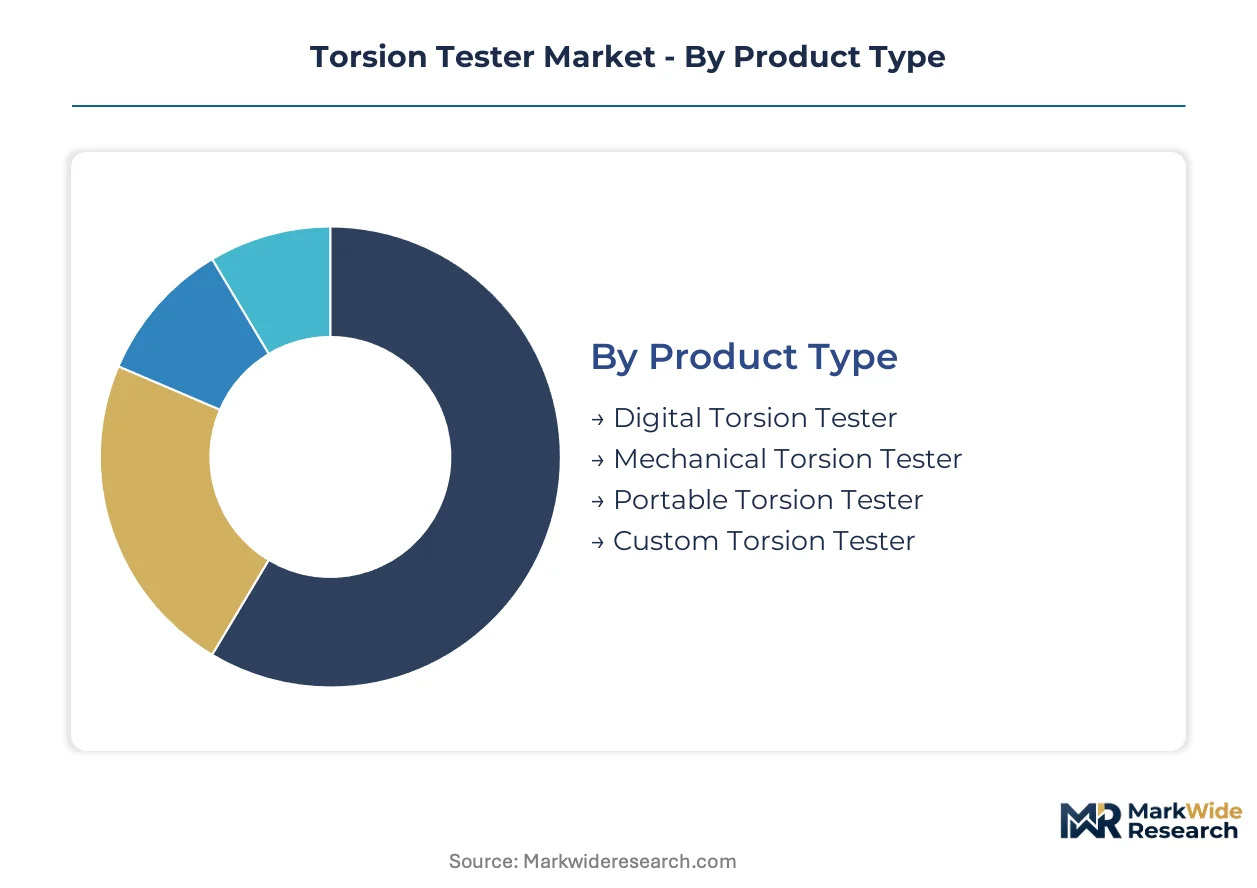
Torsion tester procurement patterns diverge sharply across product architectures and end-use requirements. Laboratories prioritize calibration-grade precision while field operations demand portability, creating distinct competitive arenas within the same technical category.
Product Type:
Portable units face the most acute substitution pressure from smartphone-mounted torque sensors and wireless strain gauges, forcing incumbent vendors to defend through certified traceability documentation.
- Digital Torsion Tester:USB-interfaced load cells with automated data acquisition dominate laboratory installations. German automotive OEMs specify these platforms for drivetrain component validation networks, accelerating replacement of analog dial-indicator systems.
- Mechanical Torsion Tester:Dial-indicator configurations with manual angular displacement measurement persist in budget-constrained educational institutions. Extended recertification timelines—up to eighteen months—constrain migration rates toward digital platforms.
- Portable Torsion Tester:Battery-powered units serve wind turbine shaft inspections and offshore fastener audits. Narrow segment limited by calibration drift in field conditions.
- Custom Torsion Tester:Multi-axis torsion-tension systems engineered for carbon-fiber torque tube protocols in aerospace applications. Long sales cycles tied to specification development with prime contractors.
Digital torsion testers anchor the volume base while portable units gain share at the steepest rate through emerging field inspection service models.
Application:
Cost tier stratification separates capital-intensive R&D installations from high-throughput quality control floors, with procurement authority concentrating in centralized metrology departments for the former.
- Material Testing:Shear modulus and ultimate torsional stress characterization for metals, polymers, and composites. REACH substance restrictions in Europe mandate expanded testing volumes for recycled-content resin verification.
- Quality Control:Production-line verification of shaft and fastener specifications. Battery-electric drivetrain validation requirements in Germany pull demand for high-capacity electromechanical systems.
- Research & Development:Novel rotor material fatigue database development for next-generation electric vehicle architectures. Extended procurement cycles with specification-driven purchasing authority.
- Product Development:Prototype validation for lightweight composite shafts in aerospace supply chains. Multi-axis capability requirements differentiate vendor selection.
Quality control applications command the largest installed base while research and development applications expand most quickly through OEM vertical integration of testing capabilities.
End User:
Customer type concentration in Germany's automotive supplier networks creates geographic clustering effects that reshape distributor relationships toward direct manufacturer engagement.
- Automotive Manufacturing:Dense supplier networks for drivetrain component validation concentrate demand in Germany. Specification harmonization across Tier-1 suppliers compresses equipment replacement cycles.
- Aerospace:Carbon-fiber torque tube testing protocols in France and Italy require multi-axis torsion-tension systems. Extended qualification timelines with prime contractors.
- Construction:Structural fastener and rebar torsion verification for infrastructure projects. Price-sensitive procurement with limited calibration documentation requirements.
- Electronics:Miniature component and connector testing with sub-Newton-meter torque ranges. Specialized load cell requirements limit vendor pool.
Automotive manufacturing anchors the volume base while aerospace gains share fastest through composite shaft proliferation in next-generation airframe designs.
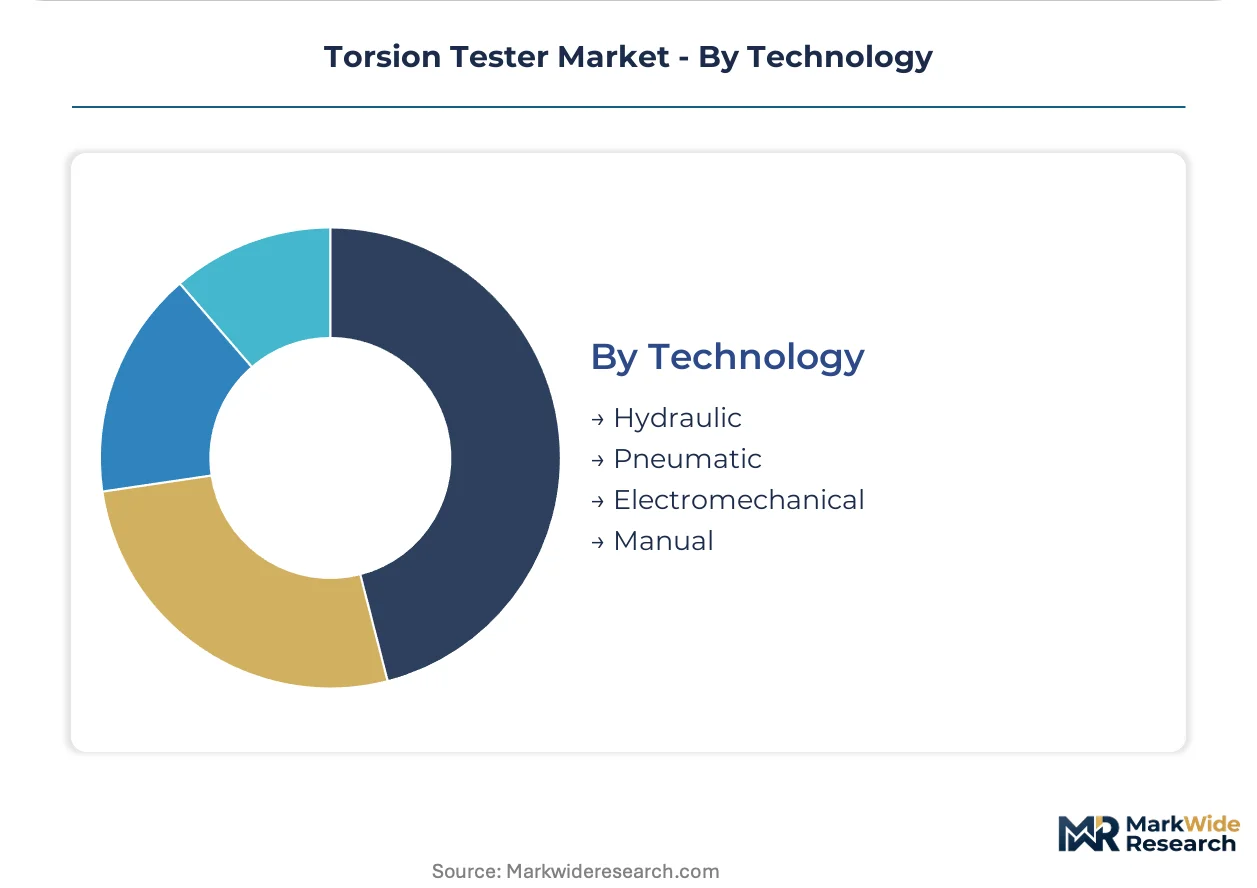
Technology:
Supply concentration in Japanese strain gauge manufacturing creates single-source vulnerability for precision torque measurement subassemblies across all technology categories.
- Electromechanical:Servo motor-driven actuation with closed-loop torque control dominates below 5,000 Nm ranges. Cleaner operation and reduced maintenance intervals displace hydraulic alternatives in laboratory environments.
- Hydraulic:High-capacity systems for large-diameter shaft and structural component testing. Energy threshold triggers for EU Machinery Directive CE marking compliance add cost escalation.
- Pneumatic:Compressed air actuation for explosive atmosphere installations in chemical processing facilities. Limited precision constrains application scope.
- Manual:Hand-cranked systems for educational demonstrations and low-volume prototype testing. Minimal calibration infrastructure requirements.
Electromechanical technology anchors the volume base while hydraulic systems retain position in the steepest expansion trajectory for offshore and heavy infrastructure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for calibration-grade systems, while construction sectors in India and Brazil prioritize cost minimization over documentation rigor. This divergence fragments vendor pricing power across geographies.
Germany
Automotive OEMs operate dense supplier networks for drivetrain component validation, pulling demand for high-capacity electromechanical testers. The KBA enforces strict type-approval documentation that compresses equipment replacement cycles toward seven-year intervals. Stuttgart and Munich host concentrated metrology service clusters serving Tier-1 supplier certification programs.
United States
Aerospace manufacturers in Seattle and Wichita expand testing protocols for lightweight composite shafts, requiring multi-axis torsion-tension capability. The FAA mandates traceable fatigue data for airframe certification, elevating documentation requirements above commercial standards. California's battery-electric vehicle startups drive novel rotor material database development through captive R&D facilities.
Japan
Strain gauge manufacturing clusters in Nagano and Yamanashi prefectures create single-source vulnerability for precision torque measurement subassemblies. METI promotes domestic calibration infrastructure through JIS standard harmonization with ISO protocols. Toyota City and Hiroshima maintain vertically integrated testing facilities for supplier network quality enforcement.
India
BIS standards alignment with ISO 6892-2 creates first-mover positioning for test equipment vendors establishing local calibration partnerships. The PLI scheme for automotive component manufacturing accelerates supplier certification requirements. Pune and Chennai automotive clusters drive demand for mid-range electromechanical systems with simplified documentation packages.
France
Aerospace supply chains in Toulouse and Nantes extend testing protocols to carbon-fiber torque tubes for next-generation airframe programs. The ANSM enforces medical device fatigue protocols that elevate equipment specification requirements. Lyon and Grenoble polymer research institutes face REACH-mandated shear modulus verification for recycled-content resin development.
Torsion Tester Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision calibration-grade systems commanding premium positioning against modular benchtop configurations. The vendor base organizes around three strategic tiers: German-engineered certification platforms, Asian electromechanical specialists, and North American quality-control modularists. Consolidation pressure concentrates among mid-scale European fabricators facing CE marking cost escalation. Competitive moves center on calibration partnership networks and direct manufacturer engagement displacing distributor relationships.
Among German precision-engineering houses, ZwickRoell and FORM+TEST GmbH exemplify the certification-grade archetype through domestic manufacturing footprints and dense automotive OEM relationships. Shimadzu Corporation anchors Asian demand positioning through electromechanical platform specialization. ADMET occupies the North American modular benchtop segment competing on configuration flexibility for quality control floors. These three players represent distinct geographic-technology positioning without overlapping core competencies.
| Leading Market Players |
|---|
| ZwickRoell |
| Shimadzu Corporation |
| ADMET |
| Instron |
| Tinius Olsen |
| FORM+TEST GmbH |
| Gotech Testing Machines Inc. |
| Qualitest International Inc. |
| MTS Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
ASTM E143 torque calibration standards gate both supplier qualification and price differentiation simultaneously, compressing equipment replacement cycles while stratifying vendor tiers by traceability documentation depth. Laboratories in Germany and Japan absorb premium pricing for certified-grade systems, while construction buyers in India and Brazil prioritize cost minimization over calibration rigor.
Pricing Analysis
After-sales revenue from calibration contracts and extended service agreements drives lifetime value more than initial equipment sales. Pricing stratifies across certification-grade, standard laboratory, and field-portable tiers, with ASTM E143 traceability commanding substantial premiums. Cost compression in mid-range electromechanical systems is intensifying because electromechanical architectures below 5,000 Nm displace hydraulic alternatives. Automotive OEMs in Germany demonstrate lowest price sensitivity, while educational institutions in emerging markets face acute budget constraints.
Supply Chain Analysis
Extended lead times for precision strain gauge subassemblies stretch equipment delivery schedules, particularly for high-capacity systems. Manufacturing concentrates in Germany, Japan, and the United States, with strain gauge fabrication anchored in Nagano and Yamanashi prefectures. Supply chains draw from specialized load cell components, servo motor drives, and safety enclosure systems. Single-source vulnerability in Japanese strain gauge manufacturing creates systemic risk. Distribution runs through direct manufacturer engagement for complex installations, displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as battery-electric vehicle drivetrain validation requirements force accelerated equipment replacement across automotive supplier networks.
For Market Incumbents: Secure calibration partnership networks in India before BIS standards alignment with ISO 6892-2 closes first-mover windows. Deepen backward integration into strain gauge sourcing to mitigate Japanese supply concentration. Invest in self-diagnostic firmware that reduces external metrology dependency, defending against emerging modular benchtop competitors. For New Entrants and Emerging Players: Lead with portable torsion verification units for wind turbine shaft inspections and offshore fastener audits, the most penetrable white-space segment. Target field inspection service contracts rather than capital equipment sales, bypassing entrenched laboratory procurement relationships. Partner with regional calibration laboratories to overcome traceability documentation barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electromechanical platform manufacturing as servo motor costs decline and production scales. Over the medium-term horizon, acquisition targets should emphasize German-engineered certification platforms with dense automotive OEM relationships. Watch for inflection when battery-electric drivetrain specifications stabilize and rotor material fatigue databases reach saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Partnership Network Expansion | BIS alignment with ISO 6892-2 in India creates first-mover positioning for traceability documentation. |
| Backward Integration into Strain Gauge Sourcing | Japanese manufacturing concentration in Nagano and Yamanashi creates single-source vulnerability. |
| Digital Twin Platform Integration | USB-interfaced load cells converge with predictive maintenance platforms for outcome-based contracts. |
| Portable Unit Service Model Development | Wind turbine shaft inspections and offshore fastener audits represent underdeveloped revenue streams. |
| Multi-Axis Torsion-Tension System Engineering | Carbon-fiber torque tube protocols in aerospace supply chains require custom specification development. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with laboratory managers, metrology service technicians, automotive Tier-1 procurement officers, and aftermarket calibration specialists inform demand-side dynamics. Secondary sources include ASTM and ISO standard documentation, KBA type-approval records, EU Machinery Directive compliance databases, and customs trade data for equipment imports. Bottom-up equipment installation counts triangulate against top-down market sizing from supplier revenue disclosures.
Sensitivity analysis across torque range thresholds, technology substitution rates, and regulatory compliance timelines shapes the analytical framework. Segmentation dimensions include product architecture, actuation technology, application purpose, and end-user industry vertical. CAGRs derive from equipment replacement cycle compression, standard revision impacts, and emerging drivetrain validation requirements. Battery-electric vehicle production trajectories and composite shaft proliferation in aerospace programs constitute key forecast inputs.
Underlying assumptions cover standard harmonization timelines, supplier certification adoption curves, and technology substitution elasticities, with deviation risk concentrated in regulatory revision schedules and raw material supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Hipot Tester Market
Test and Measurement
State Transition Testing Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Diamond Tester Market