
 Global SS7 Market | 2026-2036
Global SS7 Market Size, Share, and Industry Trends Forecast 2026-2036
Global SS7 Market Foresight
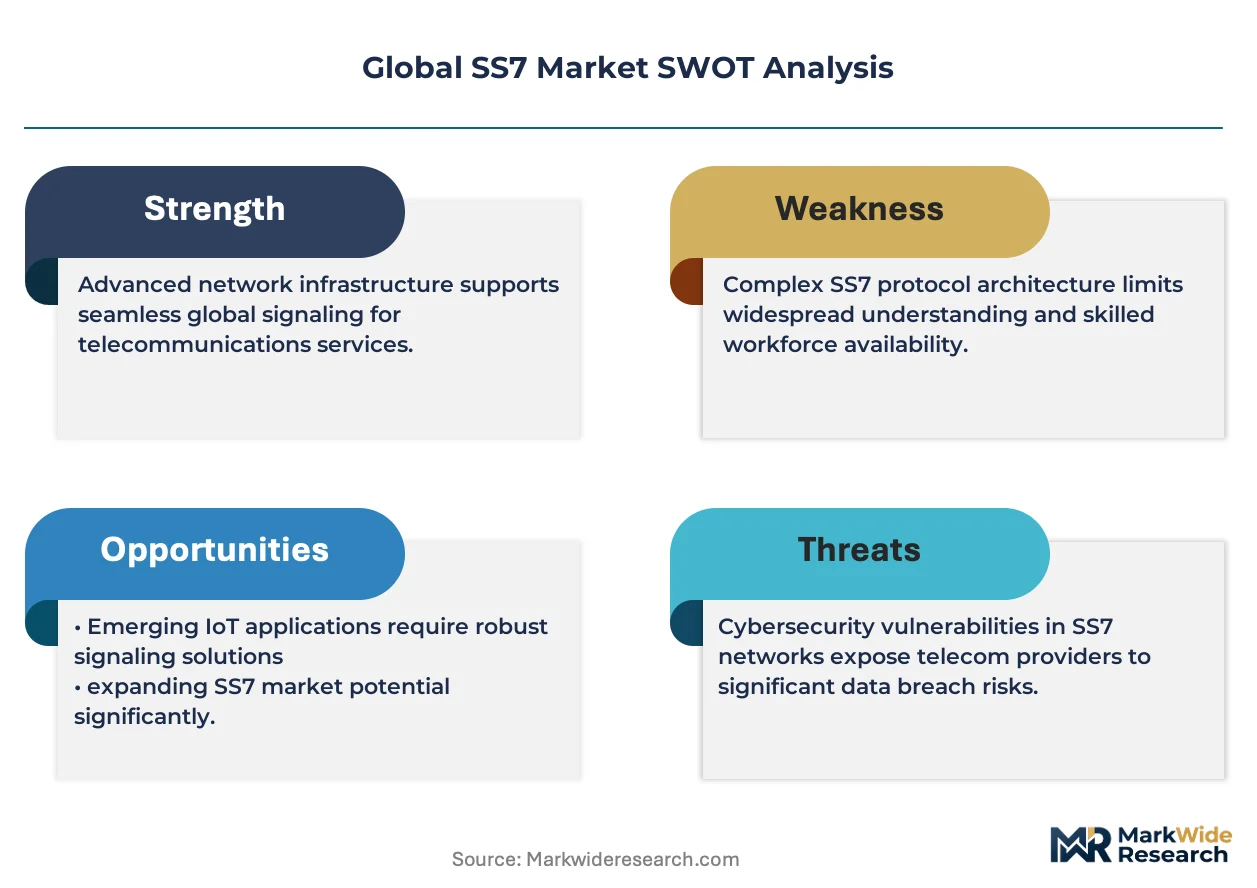
The FCC's SS7 security mandates is rebalancing the cost-of-entry calculus for North American carriers, forcing vendors to demonstrate protocol-layer encryption and filtering capabilities before procurement approval. Ericsson AB leverages its STP gateway portfolio to anchor contracts with tier-1 operators requiring compliant replacements. Huawei Technologies Co., Ltd. competes on manufacturing scale across emerging markets where price sensitivity dominates procurement decisions. Nokia Corporation differentiates through its SIGTRAN migration services, helping carriers transition from TDM-based signaling without service disruption.
SS7 (Signaling System No. 7) constitutes a packet-switched telecommunications protocol suite operating over 56 kbps or 64 kbps digital channels, enabling call setup, routing, and control across public switched telephone networks and modern IP interworking environments. The protocol stack handles non-voice signaling for voice telephony, SMS messaging, and roaming management through message transfer parts and user parts including ISUP, TCAP, and SCCP layers. Traditional SS7 components still dominate installed base revenue due to carrier reluctance to retire proven TDM infrastructure, while SIGTRAN technology represents the fastest-growing segment as operators migrate signaling traffic over IP networks to reduce operational costs. Voice telephony applications retain the largest share of ongoing maintenance spending, though fraud detection is gaining share as SS7 vulnerability exploitation drives investment in signaling firewalls and monitoring systems.
The FCC in the United States and the UK's National Cyber Security Centre enforce SS7 security frameworks that compel operators to deploy signaling firewalls and monitoring systems, directly expanding the addressable market for security-integrated STP solutions. India's TRAI mandates number portability and interconnection standards that sustain demand for SS7-based mediation equipment among domestic operators. Stakeholders must weigh the residual utility of legacy TDM infrastructure against the operational savings of full SIGTRAN migration, as regulatory pressure for security hardening accelerates replacement cycles regardless of protocol choice.
Market Dynamics
The migration from TDM-based signaling to SIGTRAN over IP architectures is compressing replacement cycles and forcing carriers to reconcile operational cost savings against security hardening mandates from multiple national regulators.
Growth Catalysts
- TRAI Interconnection Mandates:India's telecom regulator enforces number portability and interconnection standards that sustain procurement of SS7 mediation equipment among domestic mobile operators expanding into tier-2 cities.
- FCC Security Frameworks:The United States regulator compels North American carriers to deploy signaling firewalls and monitoring systems, expanding the addressable market for security-integrated STP solutions.
- SMS Banking Infrastructure:Mobile money services across Southeast Asia require legacy signaling expansion to handle authentication and transaction messaging volumes.
Market Restraints
- Copper and TDM Equipment Input Costs:Specialized legacy hardware components face supply concentration among a shrinking vendor base, inflating maintenance expenditures for carriers deferring full IP migration.
- Carrier Reluctance to Retire Proven Infrastructure:The residual utility of functioning TDM switches creates organizational inertia that delays SIGTRAN capital commitments regardless of operational savings projections.
- SS7 Vulnerability Exploitation:Protocol-layer security flaws enable fraud and surveillance intrusions that damage carrier reputation and trigger regulatory penalties, constraining pricing power for basic signaling services.
Strategic Opportunities
- Rural India Network Expansion:Reliance Jio and Bharti Airtel are modernizing interconnection networks in tier-1 cities while adjacent tier-2 and tier-3 markets remain underpenetrated for advanced SIGTRAN gateways.
- GSMA Security Guidelines:The industry association's SS7 security frameworks are reshaping procurement criteria globally, creating first-mover advantage for vendors with pre-certified firewall integrations.
- IP Convergence with 5G Core:The intersection of SIGTRAN migration and 5G standalone deployment enables unified signaling management across legacy and next-generation network elements.
Industry Challenges
- SS7-to-SIGTRAN Protocol Translation Expertise:The scarcity of engineers proficient in both TDM signaling and IP transport layers extends integration timelines and inflates professional services costs for tier-2 operators.
- Regulatory Compliance Timeline Compression:The UK's National Cyber Security Centre and FCC mandates impose overlapping certification requirements that strain vendor development resources and carrier testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SS7 Market |
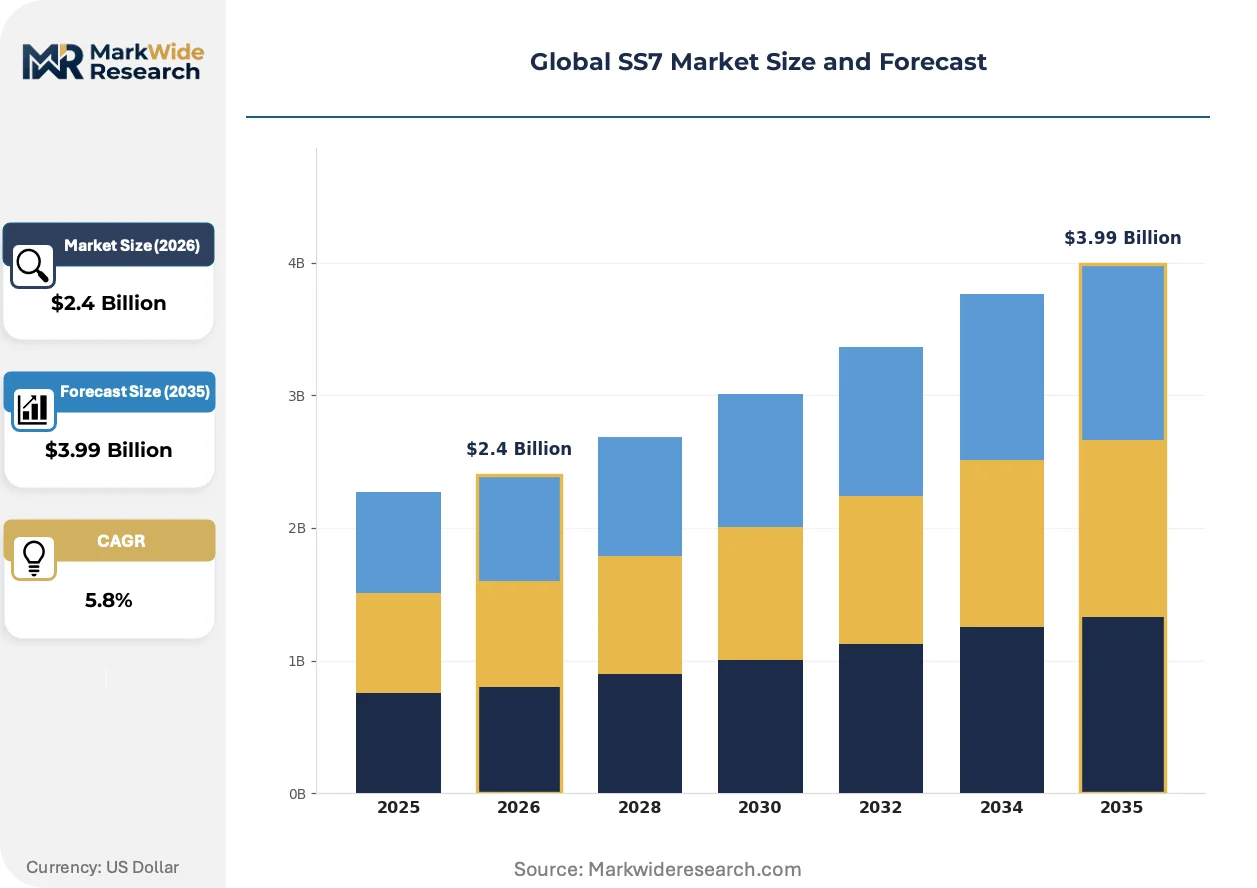
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
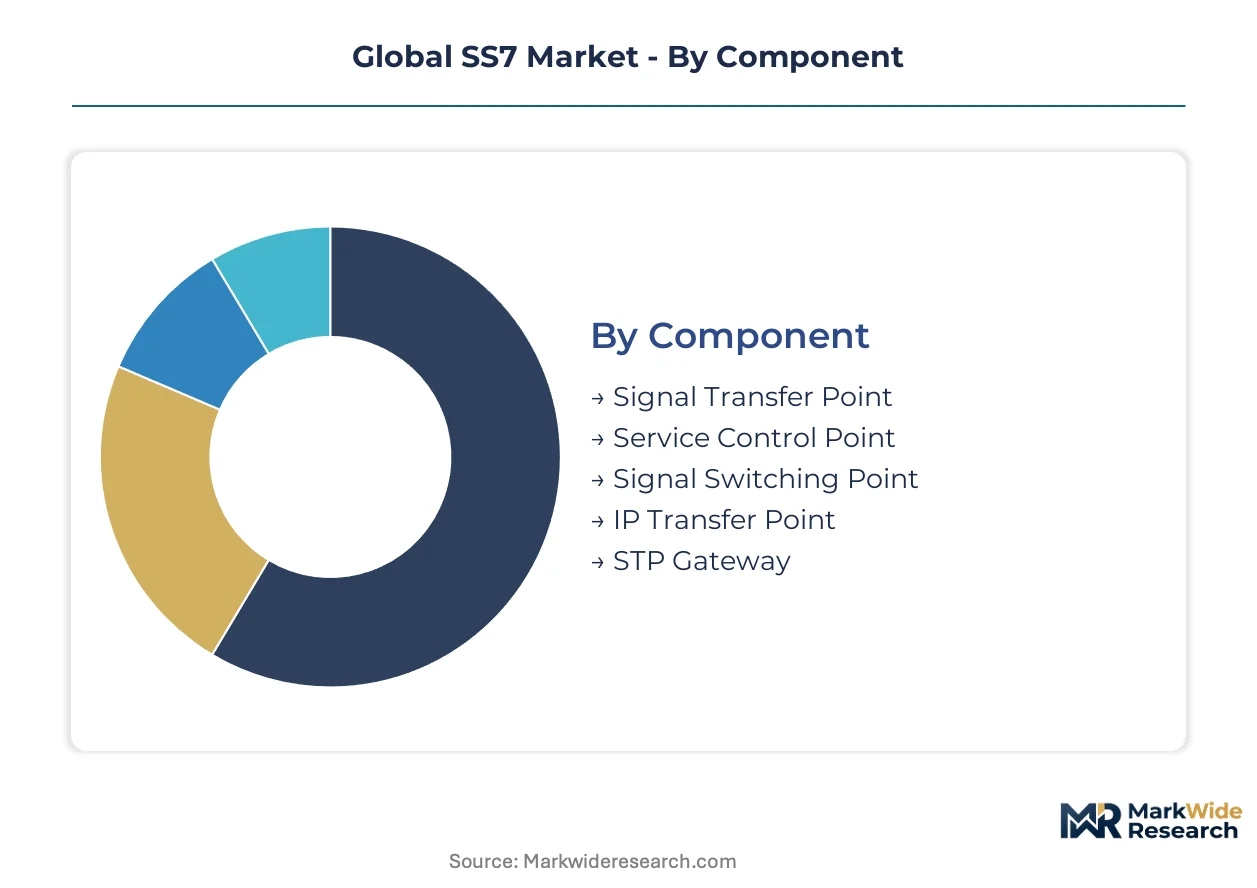
| Segmentation | Component: Signal Transfer Point, Service Control Point, Signal Switching Point, IP Transfer Point, STP Gateway Technology: Traditional SS7, SIGTRAN, SIP-T, VoIP Interworking, Diameter Interworking Application: Voice Telephony, SMS Messaging, Number Portability, Fraud Detection, Roaming Management End User: Mobile Network Operators, Telecom Equipment Vendors, Managed Service Providers, Third-Party Integrators |
| Companies Covered | Huawei Technologies Co., Ltd., Ericsson AB, Nokia Corporation, Cisco Systems, Inc., ZTE Corporation, Oracle Corporation, Ribbon Communications, Dialogic Corporation, Juniper Networks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SS7 Market Shifts & Advancements
SIGTRAN protocol stacks are displacing traditional MTP-based signaling at the network edge, while regulatory security mandates and procurement model evolution reshape how carriers evaluate vendor relationships.
SIGTRAN technology is integrating SCTP and M3UA layers to transport SS7 messages over standard IP networks, eliminating dedicated 56/64 kbps circuits. Tier-1 operators in India and the United States are deploying these gateways at interconnection points to reduce leased line expenditures. This convergence is compressing the addressable market for pure TDM equipment while expanding demand for hybrid STP solutions.
The FCC's SS7 security mandates and the UK's National Cyber Security Centre frameworks are compelling operators to embed signaling firewalls within STP infrastructure. Carriers must now demonstrate protocol-layer encryption and filtering capabilities before procurement approval, elevating security engineering to a primary vendor selection criterion. North American tier-1 operators are responding by requiring security certifications as contractual preconditions.
Carrier procurement of signaling infrastructure is consolidating around multi-year managed service agreements rather than discrete equipment purchases. European and Asia-Pacific operators are unbundling hardware acquisition from ongoing monitoring and threat response services. This behavioral shift is most visible in Germany and Japan, where operators prioritize vendors with integrated security operations centers over standalone gateway suppliers.
Global SS7 Market Segmentation
SS7 market segmentation reveals how procurement decisions split between legacy infrastructure maintenance and IP migration investments. Component selection, technology architecture, application priority, and end-user capability each create distinct commercial configurations that reshape vendor positioning and pricing power.
Component:
Standardization dominates hardware procurement for core switching elements, while customization intensity rises at network boundaries where security integration and protocol translation create specification variability.
- Signal Transfer Point:The central packet switch routes signaling messages between network nodes using MTP and SCCP protocols. Demand concentrates among tier-1 carriers in India and the United States modernizing interconnection points to meet FCC and TRAI security mandates.
- STP Gateway:Hybrid devices bridge TDM-based SS7 networks with SIGTRAN over IP, enabling phased migration without service disruption. Bharti Airtel and Reliance Jio deploy these at tier-1 city interconnects to reduce leased circuit costs while maintaining backward compatibility.
- Service Control Point:Database nodes handling 800-number translation and calling card services.
- Signal Switching Point:Edge switches originating and terminating signaling links to external networks.
- IP Transfer Point:Pure-IP signaling routers for fully migrated SIGTRAN environments.
Leading the category by volume: Signal Transfer Point. Expanding most quickly: STP Gateway.
Technology:
Cost tier segmentation separates mature TDM infrastructure with depreciated capital bases from IP-native architectures requiring fresh investment but delivering operational savings.
- Traditional SS7:MTP-based signaling over dedicated 56/64 kbps circuits remains entrenched where carriers defer replacement cycles. India's tier-2 mobile operators sustain procurement for SMS banking authentication traffic despite SIGTRAN availability.
- SIGTRAN:SCTP and M3UA protocol layers transport SS7 messages over standard IP networks, eliminating circuit leasing costs. North American tier-1 operators prioritize this technology at interconnection points to satisfy FCC security frameworks requiring embedded firewall integration.
- SIP-T:Interworking protocol between ISUP and SIP for voice over IP transition.
- VoIP Interworking:Gateway functions connecting packet voice with circuit-switched networks.
- Diameter Interworking:Translation between SS7 MAP and Diameter for 4G/5G core integration.
Traditional SS7 still dominates installed base revenue. SIGTRAN posts the steepest expansion trajectory as regulatory pressure accelerates replacement timelines.
Application:
Customer type segmentation distinguishes maintenance-driven voice services from growth-oriented security and mobility applications with diverging margin profiles.
- Fraud Detection:Signaling firewalls and monitoring systems analyze SS7 message patterns to intercept location tracking, interception, and billing fraud attempts. FCC and UK National Cyber Security Centre mandates are expanding procurement among North American and European operators.
- Voice Telephony:Call setup, routing, and teardown signaling retains the largest maintenance spending share. Carriers across India sustain investment in ISUP-based infrastructure where SMS banking and mobile money services generate transaction volume.
- SMS Messaging:Short message service signaling for person-to-person and application-to-person traffic.
- Number Portability:Signaling support for subscriber number transfers between operators.
- Roaming Management:Location update and authentication signaling for mobile subscribers visiting foreign networks.
Voice Telephony leads category spending. Fraud Detection gains share fastest as vulnerability exploitation drives security procurement.
End User:
Supply concentration shapes how procurement authority distributes between operators with in-house engineering depth and intermediaries managing technical complexity.
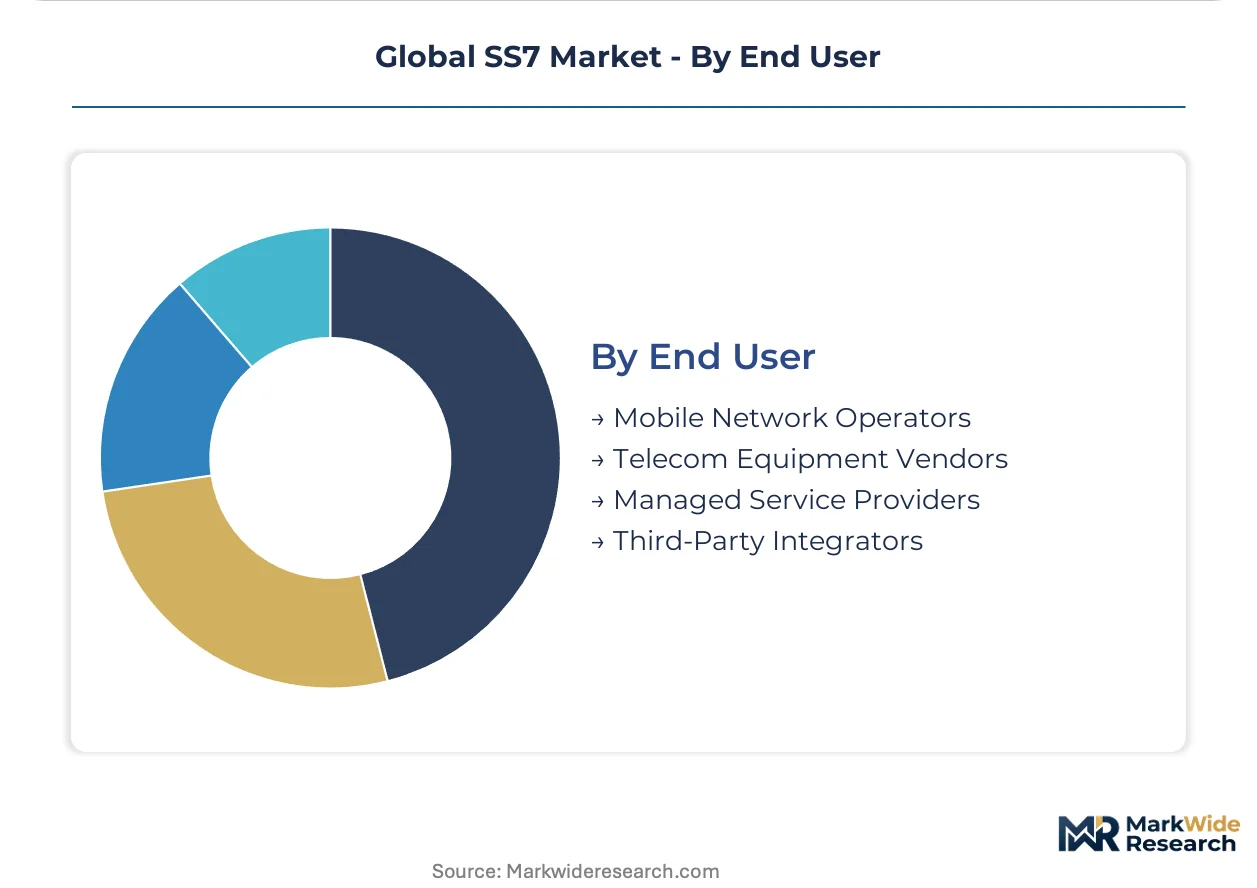
- Mobile Network Operators:Tier-1 carriers in India and the United States dominate direct procurement, leveraging scale to negotiate multi-year managed service agreements bundling hardware, monitoring, and threat response.
- Managed Service Providers:Third-party operators assume signaling infrastructure management for tier-2 carriers lacking SS7 engineering expertise. European and Asia-Pacific operators in Germany and Japan increasingly unbundle hardware acquisition from ongoing security operations.
- Telecom Equipment Vendors:Original manufacturers supplying integrated network solutions.
- Third-Party Integrators:Specialist firms bridging protocol translation and migration services.
Mobile Network Operators command the largest procurement volume. Managed Service Providers are climbing fastest as SIGTRAN expertise scarcity drives outsourcing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India's telecom corridor concentrate SS7 infrastructure investment, with Chennai, Bengaluru, and Hyderabad forming a manufacturing and R&D cluster that anchors regional procurement patterns for signaling equipment.
United States
Tier-1 carriers modernize interconnection networks under FCC security mandates requiring embedded signaling firewalls. The regulator's SS7 framework compels protocol-layer encryption demonstrations before procurement approval. Dallas-Fort Worth and Northern Virginia data center clusters host the densest deployments of SIGTRAN-enabled STP gateways serving nationwide roaming traffic.
India
TRAI interconnection standards sustain demand for SS7 mediation equipment as Reliance Jio and Bharti Airtel expand into tier-2 cities. The regulator's number portability mandates force continuous signaling infrastructure refresh. Mumbai and Delhi-NCR dominate installed base maintenance, while Hyderabad and Pune emerge as SIGTRAN migration hubs for southern operators.
Germany
Deutsche Telekom and Vodafone Deutschland unbundle hardware acquisition from managed security services under EU cybersecurity directives. The country's national telecom regulator enforces GSMA-aligned SS7 security frameworks. Munich and Frankfurt anchor procurement decision-making, with Düsseldorf-based operators driving multi-year service agreement consolidation.
Japan
NTT Docomo and SoftBank prioritize SIGTRAN integration with 5G standalone core deployments under METI industrial guidance. The ministry's telecom infrastructure standards accelerate IP convergence timelines. Tokyo-Osaka corridor operators concentrate procurement authority, while Nagoya-based equipment integrators manage protocol translation complexity for regional carriers.
Brazil
Vivo and Claro sustain TDM infrastructure for SMS banking authentication traffic while evaluating phased SIGTRAN migration. ANATEL's interconnection quality standards preserve SS7 equipment procurement despite IP alternatives. São Paulo anchors vendor sales operations, with Rio de Janeiro and Belo Horizonte carriers deferring replacement cycles amid currency volatility.
Global SS7 Market Competitive Landscape
European producers anchor one tier in premium security-integrated STP solutions; Chinese specialists hold manufacturing scale advantages in emerging markets where price sensitivity dominates procurement. The vendor base splits between consolidated telecom infrastructure conglomerates and niche signaling firewall developers. Three archetypes define positioning: full-stack network vendors, security-integrated gateway specialists, and managed service operators. Competitive moves concentrate on SIGTRAN certification racing and multi-year service contract bundling.
Among full-stack network vendors, Huawei Technologies Co., Ltd., Ericsson AB, and Nokia Corporation exemplify divergent geographic anchoring strategies. Huawei occupies a position manufacturing scale-driven tier for emerging market carriers. Ericsson AB sits within the regulatory compliance-focused segment serving North American and European operators. Nokia Corporation represents the SIGTRAN migration services archetype, bridging TDM retirement with IP infrastructure deployment. Each anchors procurement discussions through distinct capability positioning rather than overlapping segment contention.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ericsson AB |
| Nokia Corporation |
| Cisco Systems, Inc. |
| ZTE Corporation |
| Oracle Corporation |
| Ribbon Communications |
| Dialogic Corporation |
| Juniper Networks, Inc. |
| Others |
Supply & Pricing Matrix
Scarcity of engineers proficient in both TDM signaling and IP transport layers across India's telecom corridor widens pricing-tier spreads between premium-certified and economy-grade STP solutions. Labor-cost differentials between Hyderabad's R&D clusters and tier-2 city integration sites compress margins for carriers deferring full SIGTRAN migration while elevating premiums for vendors with protocol-translation expertise.
Pricing Analysis
Short lead-time premiums for security-integrated STP gateways command pricing spreads of 15-25% above standard delivery schedules as FCC and UK National Cyber Security Centre mandates compress certification timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by firewall integration depth and GSMA pre-certification status. Price differentiation hinges on embedded encryption capabilities and after-sales monitoring bundling. Pricing pressure stems from Huawei's manufacturing scale advantages in emerging markets where Reliance Jio and Bharti Airtel negotiate volume discounts. Tier-2 operators in Brazil and Southeast Asia exhibit highest price sensitivity due to currency volatility and deferred replacement cycles.
Supply Chain Analysis
Dual-sourcing requirements from North American tier-1 carriers mandate multi-supplier qualification for signaling firewall chipsets and SCTP protocol stack components, fragmenting procurement authority. Manufacturing concentrates in China, Germany, and the United States for specialized TDM-to-IP gateway hardware. Raw material dependencies include high-reliability printed circuit boards, precision timing oscillators, and cryptographic processor modules. Supply chain risk centers on single-source vulnerability for legacy MTP interface chipsets as vendor consolidation shrinks the qualified supplier base. Distribution runs through direct carrier procurement teams for tier-1 operators and managed service provider intermediaries for tier-2 markets lacking in-house SS7 engineering depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SS7 market functions as a cost-of-compliance story where FCC security frameworks and GSMA guidelines erect barrier-to-entry moats favoring vendors with pre-certified firewall integrations and demonstrated protocol-layer encryption capabilities.
For Market Incumbents: Lock in multi-year managed service agreements with tier-1 carriers before SIGTRAN expertise scarcity drives outsourcing decisions toward managed service providers. Defensive consolidation should prioritize backward integration into signaling firewall software development to capture security-integrated STP margins and counter emerging entrants offering cloud-native signaling solutions. Capacity addition in India's tier-2 cities anchors procurement relationships as TRAI interconnection mandates sustain equipment refresh cycles. For New Entrants and Emerging Players: Cloud-native signaling-as-a-service platforms offer a technology-first wedge into tier-2 operator segments lacking capital for on-premise STP deployments. White-space targets include Brazil's deferred replacement market and Southeast Asia's SMS banking infrastructure expansion where price sensitivity exceeds brand loyalty. The most penetrable segment sits with managed service providers in Germany and Japan unbundling hardware from security operations. Go-to-market execution should emphasize subscription-based pricing to bypass incumbent advantages in capital-intensive equipment financing. For Investors and Strategic Acquirers: Re-rating potential sits with security-integrated gateway specialists given FCC and UK National Cyber Security Centre mandate acceleration expanding the addressable market for signaling firewalls. Long-term viability across the forecast horizon favors vendors with demonstrated SIGTRAN migration expertise and GSMA pre-certification status. Acquisition target archetype: niche signaling firewall developers with embedded encryption IP and carrier testing relationships. The signal to watch is TRAI's enforcement timeline for tier-2 city interconnection standards, which would trigger infrastructure refresh spending beyond tier-1 maintenance cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Security Certification Pre-Investment | GSMA-aligned firewall integration accelerates FCC procurement approval timelines for North American carriers. |
| SIGTRAN Migration Service Bundling | Protocol-translation expertise captures tier-2 operator spending deferred from full infrastructure replacement. |
| Managed Security Operations Center Launch | Threat response unbundling aligns with Deutsche Telekom and Vodafone Deutschland procurement consolidation patterns. |
| Tier-2 India Geographic Expansion | Hyderabad and Pune hub positioning captures Reliance Jio and Bharti Airtel interconnection modernization. |
| Cloud-Native Signaling Platform Development | Subscription delivery bypasses capital constraints constraining Brazilian and Southeast Asian tier-2 operators. |
Research Methodology
Independent corroboration across network engineering executives, carrier procurement officers, regulatory compliance leads, and signaling equipment vendor sales directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FCC enforcement actions, TRAI interconnection orders, GSMA security guideline publications, and carrier capital expenditure disclosures. Bottom-up equipment shipment analysis triangulates against top-down regulatory mandate impact modeling across the projection horizon.
Comparable-period anchoring to legacy TDM replacement cycles and SIGTRAN adoption trajectories structured the forecast window. The analytical framework segments by component type, technology architecture, application priority, and end-user capability across the modeling period. CAGRs derive from equipment procurement pipeline analysis and carrier modernization schedule disclosures. Industry-specific forecast inputs include TRAI number portability enforcement timelines and FCC security framework compliance deadlines.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions affecting Huawei's market access, abrupt copper and TDM component supply disruptions, and carrier bankruptcy cascades in emerging markets. Forecasts reflect assumptions regarding regulatory enforcement consistency and vendor certification timeline adherence. Deviation in FCC or UK National Cyber Security Centre mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Software Defined Radio Market
Telecommunications
Chile Telecom Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Global LTE Market
Telecommunications
MVNO Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Indonesia ICT Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Global IP Phone Market
Telecommunications
France Telecom Market
Telecommunications
Kuwait Telecom Market