
 Tax Management Market | 2026-2036
Tax Management Market Size, Share, and Industry Trends Forecast 2026-2036
Tax Management Market Intelligence
The growing complexity of corporate tax management is rebalancing the market away from a primary focus on individual tax preparation. This shift favors platforms designed for business compliance and reporting. Intuit leverages its strong brand in the small business space with its QuickBooks ecosystem. Thomson Reuters dominates the large enterprise and legal professional segment with its ONESOURCE suite. Meanwhile, Xero competes effectively by integrating tax functions directly into its cloud accounting platform for SMEs.
Tax management encompasses software solutions and services that automate the processes of tax calculation, compliance, and reporting. These systems function by integrating with a company's financial data sources, such as ERPs, to apply constantly updated jurisdictional tax rules. Cloud-based deployment models are the fastest-growing segment due to their scalability and lower upfront costs. Within solution offerings, tax compliance remains the foundational and largest category, while tax analytics emerges as a high-growth area.
Regulatory frameworks from the IRS in the United States and the EU's VAT in the Digital Age (ViDA) initiative mandate digital submission formats. The OECD's Pillar Two model rules further compel multinational corporations to adopt sophisticated tax reporting software. These global and national requirements directly shape software functionality and market access. Vendor selection will increasingly depend on a platform's ability to manage a fragmented and evolving landscape of real-time reporting obligations.
Market Dynamics
The global shift toward mandatory digital tax reporting, driven by intergovernmental frameworks like the OECD's BEPS 2.0, is the central force restructuring the tax management market. This regulatory pressure compels corporations to abandon manual processes for automated, data-driven platforms.
Growth Catalysts
- Mandatory E-Invoicing:Government mandates for electronic invoicing and real-time reporting, exemplified by initiatives in Brazil and the EU's VAT in the Digital Age (ViDA) framework, directly create demand for compliant software solutions among businesses operating in these jurisdictions.
- OECD Pillar Two Rules:The implementation of the OECD's global minimum tax rules requires multinational enterprises to perform complex new calculations and reporting, accelerating adoption of specialized enterprise-grade tax software to manage compliance and assess financial impact.
- Cloud Solution Scalability:The adoption of cloud-based tax management platforms is accelerating due to their ability to scale across multiple jurisdictions, integrate with diverse ERP systems, and provide continuous updates for evolving tax codes without significant capital expenditure.
Market Restraints
- High Total Cost of Ownership:Enterprise-level tax management suites involve significant subscription fees, implementation costs, and expenses for specialized consulting, creating a substantial financial barrier for small and mid-sized enterprises with less complex tax profiles.
- Legacy System Integration:The difficulty and expense of integrating modern tax software with outdated or highly customized legacy ERP and financial systems remain a primary technical hurdle, delaying or complicating adoption projects for many organizations.
- Data Security and Sovereignty:Storing sensitive corporate financial data on third-party cloud platforms raises significant concerns regarding cybersecurity threats and compliance with data sovereignty laws like the GDPR, requiring vendors to make substantial investments in security infrastructure.
Strategic Opportunities
- Predictive Tax Analytics:Developing advanced analytics modules that use AI to model the tax implications of future business scenarios, such as M&A or supply chain restructuring, represents a significant value-add opportunity beyond core compliance functions.
- Mid-Market Solutions:There is a distinct opportunity for platforms tailored to the mid-market, offering a scalable feature set that bridges the gap between basic accounting software and the high complexity of enterprise-grade suites like ONESOURCE.
- ESG and Tax Transparency Reporting:Integrating environmental, social, and governance (ESG) reporting capabilities with tax transparency data provides a new avenue for growth, addressing investor and regulatory demands for public country-by-country reporting (CbCR).
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals who possess a hybrid skillset combining tax law, data analytics, and IT systems expertise creates an operational bottleneck for both companies seeking to implement solutions and vendors needing to build them.
- Pace of Regulatory Change:The constant stream of amendments to tax laws, digital submission formats, and reporting standards across hundreds of global jurisdictions requires vendors to invest heavily and continuously in R&D just to maintain baseline compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tax Management Market |
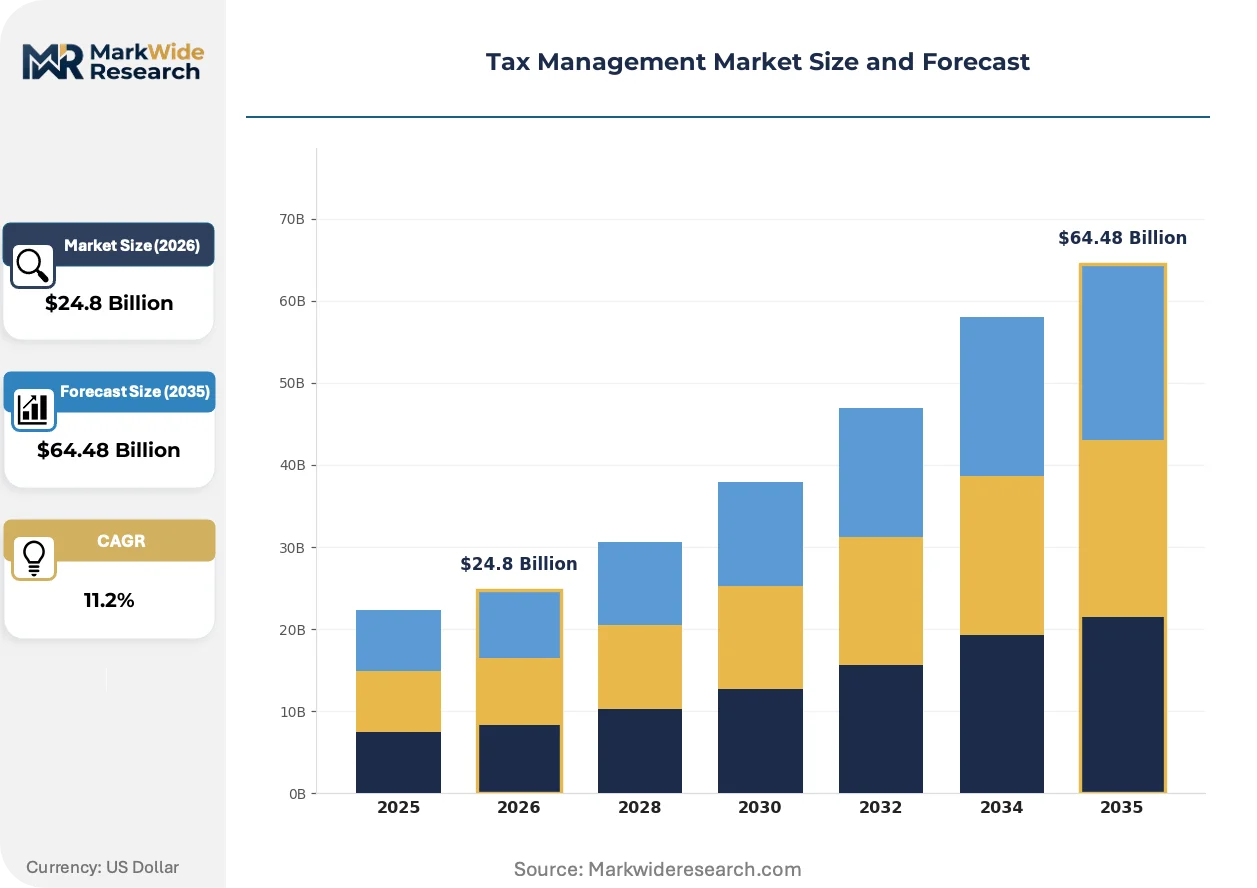
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $64.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Tax Compliance, Tax Reporting, Tax Audit, Tax Planning, Transfer Pricing, Tax Risk Management Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Small & Medium Enterprises, Large Enterprises, Accounting Firms, Government Agencies, Tax Consultants Application: Corporate Tax Management, Indirect Tax Management, Personal Tax Management, Compliance Automation, Tax Analytics |
| Companies Covered | Drake Software, H&R Block, Intuit, Xero, TaxAct, Thomson Reuters, TaxSlayer, TaxDome, CCH (Wolters Kluwer), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tax Management Market Strategic Shifts & Innovations
The market's evolution is defined by a push beyond basic automation toward integrated, real-time data platforms. This transition is driven by regulatory demands for greater transparency and the corporate need for strategic tax planning capabilities in a more complex global environment.
Tax analytics software provides the core function of modeling complex tax scenarios and identifying potential compliance risks using historical and real-time data. Large multinational corporations are the primary adopters, driven by the immediate need to manage their global tax exposure under frameworks like the OECD's Pillar Two. This technology is expanding into strategic business planning, where its insights influence fundamental decisions on supply chain configuration, legal entity structure, and M&A targeting.
In the United States, the Inflation Reduction Act (IRA) introduced a complex web of new tax credits and a corporate alternative minimum tax. This legislation directly increases compliance burdens and compels corporations, particularly in the energy and manufacturing sectors, to acquire sophisticated software. Affected companies are now forced to re-evaluate their tax technology stacks to accurately calculate eligibility for credits and model the impact of the new minimum tax on their financial statements.
A notable shift in buying behavior sees corporate finance and tax departments moving away from single-point software procurement. They now favor unified platforms that integrate tax compliance and reporting directly with broader financial planning and analysis (FP&A) and ESG disclosure tools. This disrupts the market for standalone tax calculation engines, creating an advantage for vendors who offer comprehensive suites that plug into major ERP ecosystems. This trend is most visible in large enterprises across North America and Europe.
Tax Management Market Segmentation
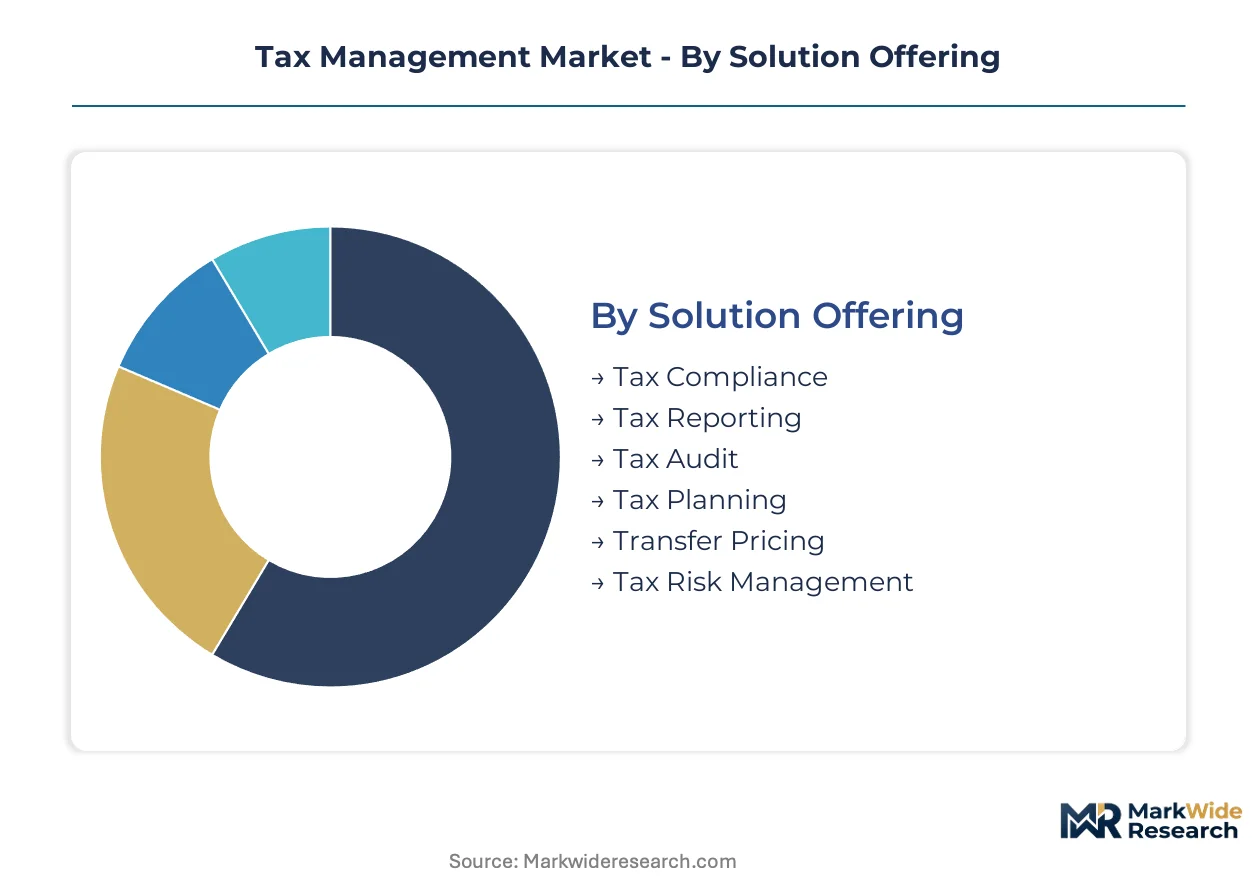
Market segmentation clarifies the distinct needs and purchasing behaviors across the diverse landscape of tax management. Understanding these specialized requirements enables vendors to develop targeted solutions and optimize their market penetration strategies. This differentiation highlights where demand is most concentrated and identifies areas ripe for future development.
Solution Offering:
The supply of tax management solutions increasingly concentrates on platforms offering comprehensive functionality rather than standalone tools.
- Tax Compliance:This foundational category includes software and services designed to ensure adherence to all applicable tax laws and regulations, encompassing calculations, filing, and reporting. Demand for these solutions is concentrating in countries with mandatory digital reporting, such as Brazil and India, driven by stringent regulatory frameworks.
- Tax Analytics:These advanced tools leverage data science and AI to model complex tax scenarios, identify risks, and optimize tax strategies, often integrated with financial planning systems. Large multinational corporations are the primary adopters, driven by the immediate need to manage global tax exposure under frameworks like the OECD's Pillar Two.
- Tax Reporting:Solutions focused on generating and submitting accurate tax reports to various tax authorities, supporting diverse formats and jurisdictional requirements.
- Tax Audit:Systems designed to prepare for, manage, and respond to tax audits, often incorporating document management and data validation features.
- Transfer Pricing:Specialized software aiding multinational enterprises in setting and documenting prices for intercompany transactions to comply with global tax rules.
- Tax Risk Management:Tools that identify, assess, and mitigate potential tax exposures and penalties through proactive monitoring and scenario planning.
Today's leader: Tax Compliance. Tomorrow's challenger: Tax Analytics.
Deployment:
The maturity of deployment models reflects varying levels of technological integration and infrastructure investment by businesses.
- Cloud-Based:These solutions are hosted remotely and accessed via the internet, offering scalability, lower upfront costs, and continuous updates. Demand is accelerating across all enterprise sizes, especially in regions with intricate tax codes, due to operational flexibility.
- Hybrid:This model combines elements of both on-premises and cloud-based deployments, allowing organizations to maintain sensitive data locally while leveraging cloud services for other functions. Large enterprises with existing legacy systems often adopt hybrid models to manage integration complexities.
- On-Premises:Software installed and run on a company's own servers and infrastructure, providing maximum control over data and customization. Organizations with strict data sovereignty requirements or extensive legacy IT infrastructure frequently prefer this deployment method.
- Managed Services:Third-party providers manage the tax software, infrastructure, and often the tax processes themselves, offering expertise and reducing internal IT burden.
Cloud-Based solutions are gaining share fastest, driven by scalability demands.
End User:
Customer type directly influences the feature set and complexity required from tax management platforms.
- Large Enterprises:Corporations with extensive operations, complex cross-border transactions, and significant global tax obligations. These entities require sophisticated platforms capable of managing OECD Pillar Two rules and diverse jurisdictional reporting.
- Small & Medium Enterprises:Businesses with simpler tax profiles but a growing need for automated compliance and reporting solutions. Platforms like Xero integrate tax functions directly into cloud accounting for these businesses.
- Accounting Firms:Professional service providers that use tax management software to serve multiple clients, requiring robust multi-entity and multi-jurisdictional capabilities.
- Government Agencies:Public sector entities that utilize tax management systems for internal compliance, budgeting, and sometimes for managing tax collection processes.
- Tax Consultants:Individual practitioners or small firms offering specialized tax advice and preparation services, often leveraging advanced analytical tools.
Large Enterprises currently dominate expenditure, but Small & Medium Enterprises represent a significant volume opportunity.
Application:
The volume of transactions and regulatory mandates defines the primary application areas for tax management software.
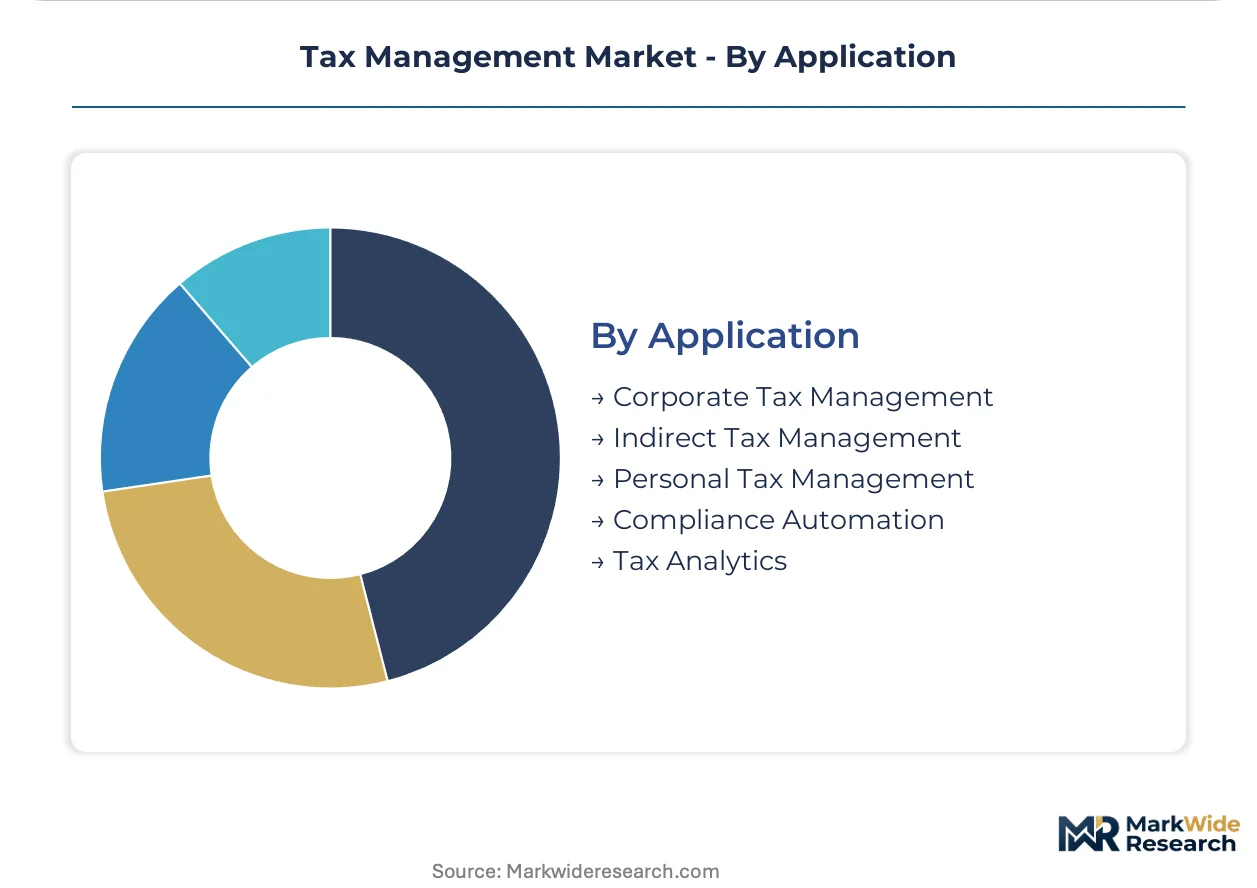
- Corporate Tax Management:Solutions specifically designed to handle the tax obligations of businesses, including income tax, VAT/GST, and other corporate levies. This area is expanding due to the global shift towards mandatory digital tax reporting.
- Compliance Automation:Software that automates the processes of tax calculation, reporting, and submission to ensure adherence to regulatory requirements. Demand for compliance automation is concentrated in countries with intricate tax codes like Brazil and India.
- Tax Analytics:Tools that provide insights into tax data, aiding in strategic planning, risk assessment, and scenario modeling for various business decisions. Multinational corporations are using these tools to navigate the Inflation Reduction Act's complex tax credits in the United States.
- Indirect Tax Management:Systems focused on managing taxes such as VAT, GST, and sales tax, which are levied on goods and services. The EU's VAT in the Digital Age (ViDA) initiative is driving demand in this segment.
- Personal Tax Management:Software designed for individuals to prepare and file their personal income tax returns.
Corporate Tax Management remains foundational, while Tax Analytics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage, where production migrates due to varying cost-of-compliance gaps, is reshaping the tax management market. Countries with stringent digital reporting mandates and complex tax frameworks are compelling businesses to invest in sophisticated software solutions. This dynamic creates concentrated demand for compliant platforms in specific jurisdictions.
United States
Demand for corporate tax management software in the United States stems from the Inflation Reduction Act's complex tax credits and the corporate alternative minimum tax. The IRS mandates specific digital submission formats for various tax filings. New York, Chicago, and Houston serve as key financial and industrial centers where large enterprises actively seek advanced tax analytics for strategic planning.
Germany
Compliance automation and indirect tax management are primary demand drivers in Germany. The EU's VAT in the Digital Age (ViDA) initiative directly impacts German businesses, requiring new software functionalities. Frankfurt, Munich, and Berlin, as major financial and technological hubs, see significant adoption of cloud-based platforms for pan-European tax compliance.
Brazil
Brazil exhibits strong demand for digital reporting and compliance automation solutions. Government mandates for electronic invoicing and real-time tax reporting are exceptionally stringent. São Paulo, Rio de Janeiro, and Brasília are critical centers for businesses navigating the country's intricate and frequently updated tax codes.
India
India's market for cloud-based compliance automation is expanding rapidly due to its complex tax codes and the Goods and Services Tax (GST) network. The government's push for digital transactions and reporting compels businesses to adopt modern tax software. Bengaluru, Mumbai, and Delhi-NCR are major tech and financial centers where enterprises are upgrading their tax technology stacks.
Singapore
Strategic tax analytics and transfer pricing solutions are in high demand in Singapore, driven by its role as a global financial hub for multinational corporations. The OECD's Pillar Two rules compel many regional headquarters to implement advanced reporting software. Singapore's financial district, hosting numerous APAC HQs, focuses on optimizing global tax exposure and ensuring regulatory adherence.
Tax Management Market Key Industry Players
Strategic partnerships to integrate tax solutions with broader enterprise ecosystems dominate the current landscape, especially for vendors targeting large enterprises. The market structure is tiered, with distinct offerings for multinational corporations, mid-sized businesses, and small enterprises. Enterprise suite providers, cloud-native SME platforms, and specialized compliance tools represent key strategic archetypes. Portfolio diversification into tax analytics and geographic expansion are common competitive moves.
Within the enterprise software tier, Thomson Reuters exemplifies a provider offering comprehensive suites like ONESOURCE for large corporations and legal professionals. Intuit occupies a strong position in the small business space, anchoring its offerings around the QuickBooks ecosystem. Meanwhile, Xero represents the cloud-native platform archetype by integrating tax functions directly into its accounting software for small and medium-sized enterprises.
| Leading Market Players |
|---|
| Drake Software |
| H&R Block |
| Intuit |
| Xero |
| TaxAct |
| Thomson Reuters |
| TaxSlayer |
| TaxDome |
| CCH (Wolters Kluwer) |
| Others |
Cost & Logistics Intelligence
Large enterprises, with their complex global tax obligations, often engage in value-based pricing for comprehensive tax management suites. This model reflects the highly customized implementation and ongoing support required for sophisticated cross-border compliance.
Pricing Analysis
Direct-to-customer SaaS subscription models dominate tax management software pricing, especially for cloud-based solutions. Pricing stratifies across premium, standard, and economy tiers based on feature sets, user count, and integration complexity. Geographic delivery costs and the depth of specialized consulting required also drive price differentiation. Pricing softness stems from intense competition in the SME segment, while large enterprises exhibit lower price sensitivity for mission-critical compliance.
Supply Chain Analysis
Mandating multi-supplier qualification remains uncommon in tax management software, though enterprises often evaluate multiple vendors for best-fit solutions. The supply of core software development talent centers heavily in the United States and India, with cloud infrastructure primarily hosted in global data centers like those in Ireland. Key dependencies include specialized IT talent and robust cloud computing services. A structural risk involves the scarcity of professionals combining tax law, data analytics, and IT systems expertise. Distribution runs through direct sales teams and strategic partnerships with accounting firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tax Management Market acts as a stable compounder, with sustained growth driven by the relentless pace of global regulatory change. Digital tax reporting mandates compel continuous investment, ensuring consistent demand for advanced solutions.
For Market Incumbents: Acquire specialized tax analytics firms to deepen AI capabilities and predictive modeling functionalities. Incumbents must integrate tightly with major ERP ecosystems to counter the threat from agile cloud-native platforms. Investing in R&D for real-time reporting solutions ensures compliance with evolving frameworks like the EU's VAT in the Digital Age initiative. This strategy defends market share against new entrants offering simplified, cost-effective solutions.
For New Entrants and Emerging Players: Accounting firm partnerships offer a direct channel to penetrate the underserved mid-market segment. New entrants should focus on delivering highly scalable, cloud-native solutions for countries with intricate tax codes, such as Brazil and India. An API-first integration strategy with existing financial planning and analysis tools provides a compelling go-to-market angle. This approach allows rapid deployment and lower total cost of ownership for businesses seeking compliance automation.
For Investors and Strategic Acquirers: Private equity firms are the most active acquirers in this space, seeking platform plays with strong recurring revenue. The market exhibits long-term viability over the next 5-10 years, underpinned by persistent regulatory complexity. Acquisition targets should include niche tax analytics providers and regional compliance specialists with deep jurisdictional expertise. Consolidation among mid-market solution providers signals a maturing segment and potential for larger strategic exits.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies tax compliance with broader financial planning and analysis systems for large enterprises. |
| AI-Powered Tax Analytics Development | Models complex scenarios and identifies compliance risks under evolving frameworks like OECD Pillar Two. |
| Geographic Expansion into High-Complexity Jurisdictions | Captures demand for mandatory e-invoicing solutions in markets such as Brazil and India. |
| Cloud-Native Solution Development | Offers scalable, lower-cost compliance automation to small and medium-sized enterprises. |
| Talent Development in Hybrid Skillsets | Addresses the scarcity of professionals combining tax law, data analytics, and IT systems expertise. |
Research Approach
Bottom-up corporate tax management modeling reconciled against top-down software vendor revenue tracking forms the analytical core. This approach integrates primary interviews with tax directors, CFOs, IT procurement officers, and accounting firm partners. Secondary validation draws from IRS filings, EU VAT directives, OECD BEPS reports, and public financial statements of software companies. This dual-perspective triangulation ensures robust data integrity.
Historical trendline analysis projects market trajectories across the analysis window, incorporating regulatory and technological shifts. The forecast segments by solution offering, deployment model, end-user type, application area, and regional regulatory cluster. Compound annual growth rates derive from historical growth rates, anticipated regulatory pipelines, and technology adoption curves. Key inputs include the rollout of e-invoicing mandates and the implementation of OECD Pillar Two rules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to the pace of regulatory change and geopolitical stability. These forecasts reflect current assumptions regarding technology adoption and market dynamics. Deviation in the global regulatory landscape would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
Global Auditing Services Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
Global Tax and Accounting Software Market