
 Accounting Services Market | 2026-2036
Accounting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Accounting Services Market Analysis
Advisory distribution through multinational networks is tilting toward technology-integrated delivery models. Deloitte leverages proprietary AI audit tools to sustain quality differentiation across engagements. PwC anchors its competitive stance through deep specialization in regulatory compliance and risk advisory. EY dominates sustainability reporting services as CSRD and ISSB frameworks expand disclosure obligations.
Accounting services encompass independent professional activities involving the measurement, processing, and communication of financial information for decision-making, governed by technical standards including GAAP, IFRS, and ISA audit protocols. These services verify financial integrity, ensure tax compliance, and enable capital allocation across commercial and institutional entities. Tax preparation and audit services command the largest revenue pools, though consulting margins expand fastest as clients seek integrated ESG and digital transformation guidance. Cloud accounting deployment within the technology use dimension reshapes client acquisition economics, lowering onboarding costs while raising recurring revenue predictability through subscription-based engagement models.
The SEC mandates PCAOB oversight for public company audits, while the EU's CSRD and GDPR frameworks impose layered disclosure requirements that expand advisory scope. IRS code complexity and OECD pillar-two tax reforms simultaneously deepen compliance demand across multinational client portfolios. Stakeholders must monitor how generative AI tools reshape staff-to-revenue ratios and whether regulatory bodies codify algorithmic audit standards before competitive positioning locks in.
Market Dynamics
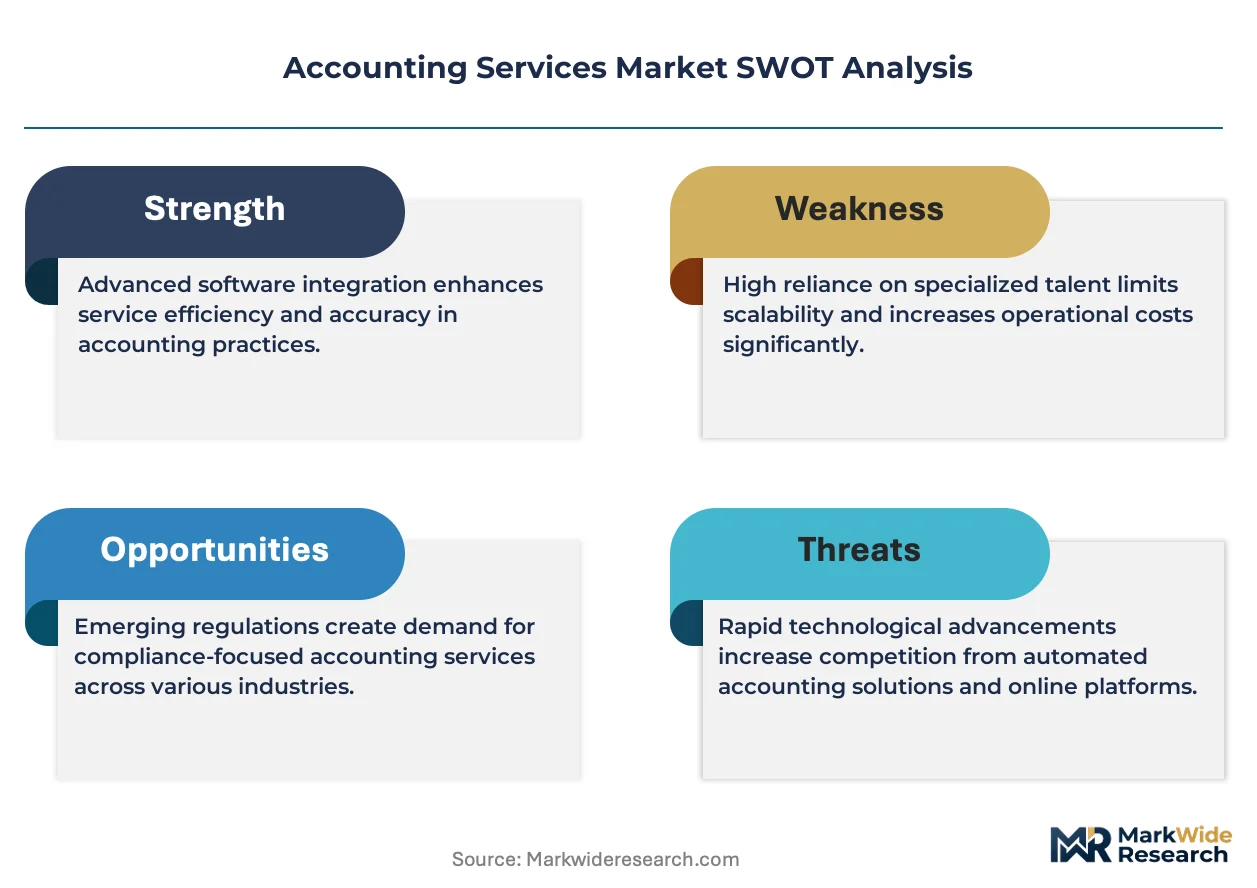
Generative AI deployment is compressing staff-to-revenue ratios across audit and tax engagements, forcing firms to restructure talent models while regulatory bodies deliberate algorithmic audit standards.
Growth Catalysts
- CSRD Mandates:The EU's Corporate Sustainability Reporting Directive expands disclosure obligations for in-scope entities, extending advisory scope into carbon accounting and supply chain due diligence.
- Cloud Accounting Platforms:Small business adoption of automated bookkeeping software accelerates client acquisition economics through subscription-based engagement models.
- OECD Pillar-Two Reforms:Minimum tax rate implementations deepen compliance demand across multinational portfolios, sustaining premium transfer pricing and tax controversy practices.
Market Restraints
- PCAOB Inspection Intensity:Heightened scrutiny of audit quality deficiencies elevates professional liability premiums and engagement oversight costs for public company practices.
- Talent Pipeline Constraints:Declining accounting program enrollments in the United States compress partner-to-staff leverage ratios and elevate compensation inflation.
- Technology Capital Requirements:Proprietary AI tool development demands sustained R&D investment that mid-tier firms struggle to fund without network affiliation.
Strategic Opportunities
- ISSB Framework Alignment:Jurisdictions adopting International Sustainability Standards Board disclosure rules create advisory white space in climate risk quantification and scenario analysis.
- India Market Expansion:SEBI's tightening corporate governance codes and GST complexity sustain demand for Big Four network expansion into tier-two cities.
- Embedded Finance Convergence:Accounting software APIs integrating with banking and payment infrastructure enable real-time advisory services at point-of-transaction.
Industry Challenges
- Algorithmic Audit Standards:Absence of codified PCAOB or IAASB guidance on AI-assisted evidence evaluation creates liability ambiguity and engagement documentation complexity.
- Legacy System Integration:Client ERP heterogeneity obstructs standardized data extraction for automated analytics, requiring costly custom connector development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accounting Services Market |
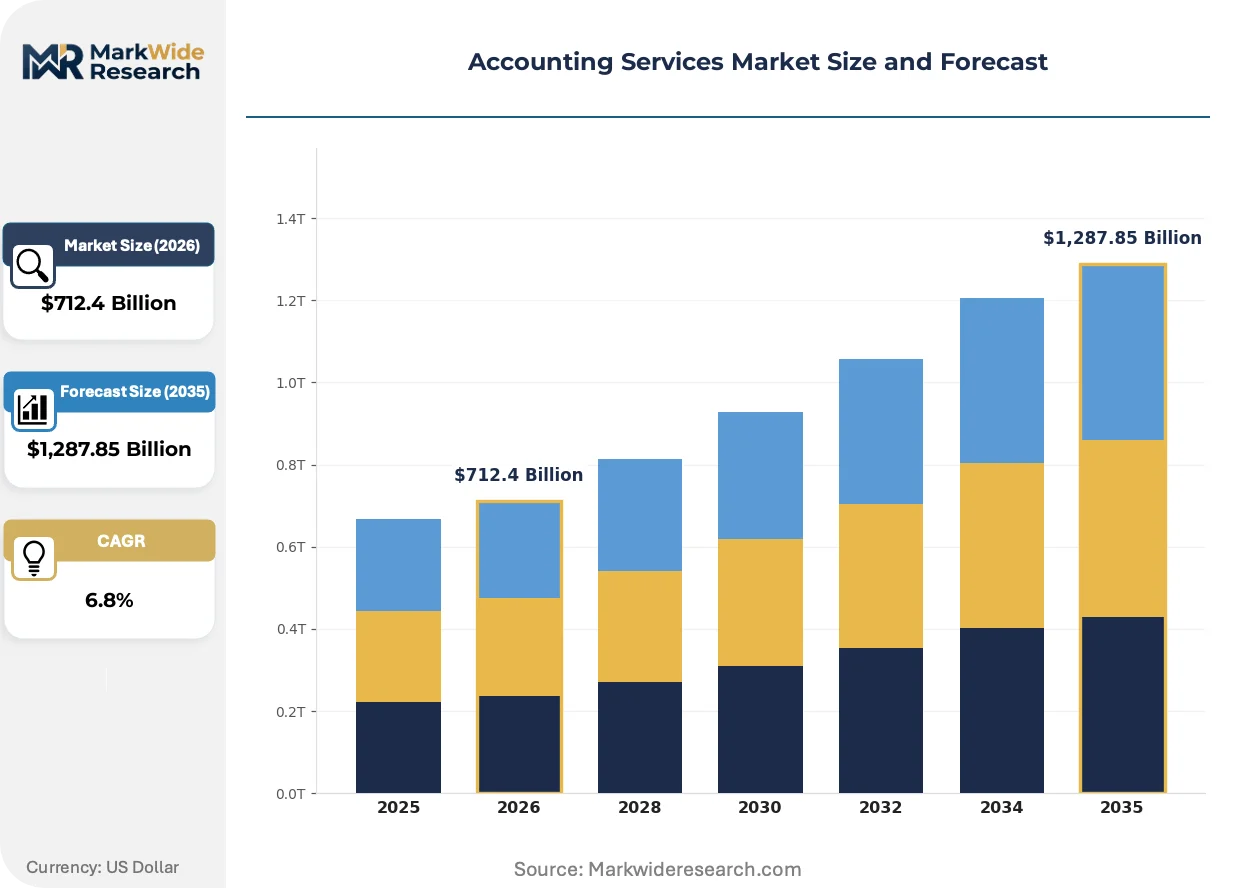
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,287.85 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tax Preparation, Audit Services, Bookkeeping, Consulting Client Type: Small Businesses, Corporations, Non-Profits, Individuals Engagement Model: Hourly Billing, Fixed Price, Retainer, Contingency Technology Use: Cloud Accounting, Automated Software, AI Analytics, ERP Systems |
| Companies Covered | KPMG, RSM International, Deloitte, Baker Tilly International, Grant Thornton, PwC, BDO, Plante Moran, EY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accounting Services Market Emerging Trajectories
Service delivery models are fragmenting between technology-augmented efficiency plays and relationship-intensive advisory specialization, with competitive advantage accruing to firms that integrate both capabilities.
Audit methodology is hybridizing as natural language processing tools ingest entire document populations rather than statistical samples, compressing fieldwork timelines while elevating anomaly detection coverage. Mid-market firms adopting these capabilities from network-shared platforms narrow the quality gap with developed proprietary systems. The structural consequence is a bifurcation between technology-enabled scale players and boutique specialists.
The SEC's climate disclosure rules, currently stayed pending litigation, nonetheless shape preparatory advisory spending as registrants model scenario disclosures and attestation readiness. This regulatory anticipation sustains ESG advisory growth even absent enforcement. Technology and energy sector issuers dominate early compliance investment.
Subscription pricing for compliance services is displacing hourly billing in small business segments, compressing realized rates per engagement while extending client lifetime value and cross-sell attach rates. Cloud-native accounting software vendors are capturing this transition through embedded professional services marketplaces. This pattern concentrates in English-speaking markets with mature SaaS penetration.
Accounting Services Market Segmentation
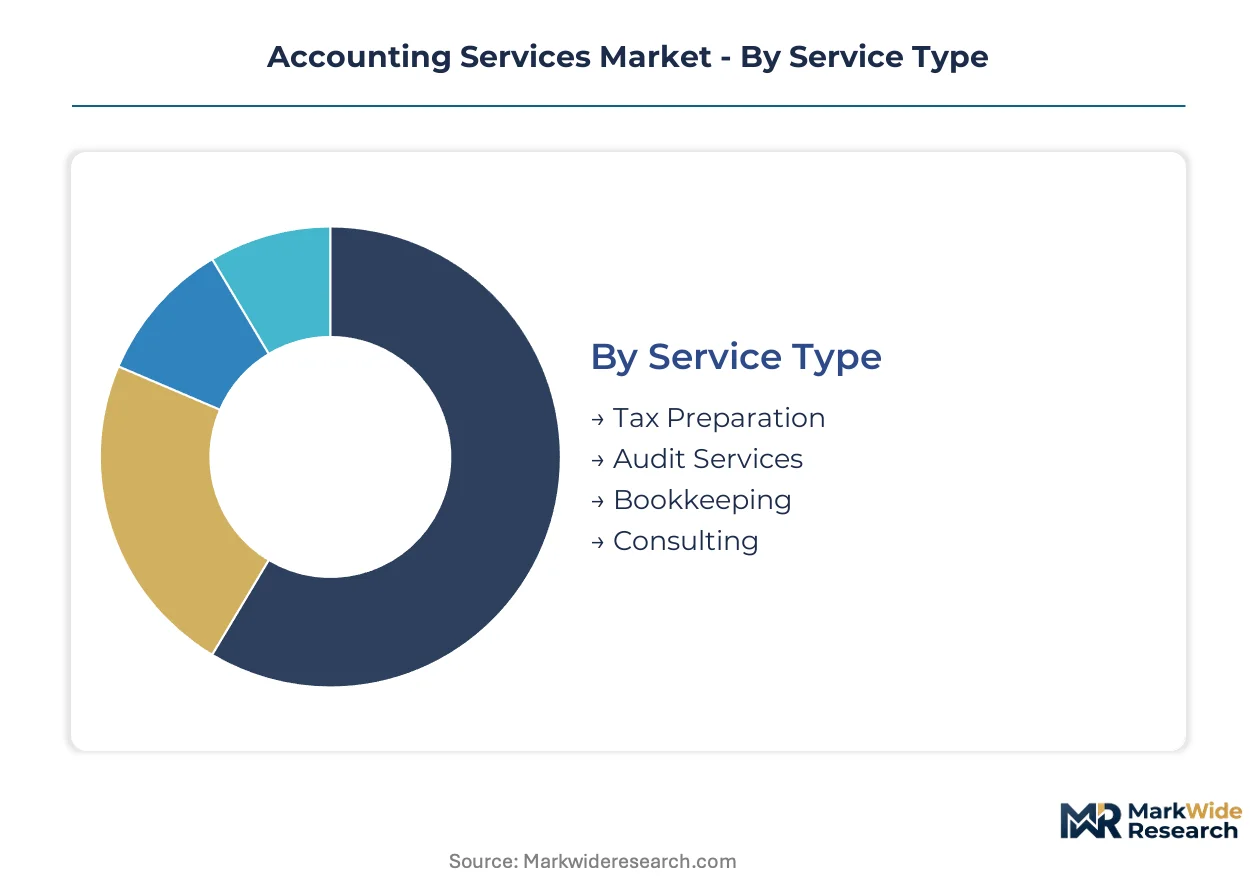
Service differentiation in accounting markets tracks closely to regulatory complexity and client sophistication tiers. Segment boundaries blur as cloud platforms enable hybrid delivery models that span traditional service categories.
Service Type:
Tax preparation and audit services operate on annual compliance cycles with predictable revenue recognition, while consulting engagements stretch across multi-year transformation timelines with lumpy milestone payments.
- Tax Preparation:Encompasses individual income filing, corporate tax compliance, and international transfer pricing documentation. Demand concentrates among multinational corporations navigating OECD Pillar-Two minimum tax implementations across Germany, Japan, and the United States. IRS code complexity and simultaneous state-level obligations sustain premium pricing for specialized practices.
- Audit Services:Statutory financial statement attestation governed by PCAOB standards for SEC registrants and ISA protocols for cross-listed entities. Public company practices in the United States face elevated professional liability premiums as inspection intensity rises, compressing partner-to-staff leverage ratios.
- Bookkeeping:Transaction recording and reconciliation services migrating to subscription-based cloud platforms.
- Consulting:Advisory spanning ESG disclosure readiness, digital transformation, and risk management.
Tax preparation anchors the volume base while consulting gains share at the steepest rate.
Client Type:
Cost tier stratification separates relationship-intensive advisory from standardized compliance, with small businesses driving platform economics and corporations sustaining bespoke engagement premiums.
- Small Businesses:Entities with limited in-house finance functions purchasing bundled compliance and advisory through SaaS marketplaces. Cloud accounting adoption accelerates in the United States and United Kingdom as digital filing mandates reshape procurement priorities. Subscription pricing displaces hourly billing, extending client lifetime value while compressing realized rates per engagement.
- Corporations:Complex entities requiring integrated audit, tax, and advisory across multiple jurisdictions. CSRD disclosure obligations in the European Union and SEC climate rules in the United States expand advisory scope into carbon accounting and scenario analysis.
- Non-Profits:Mission-driven organizations with specialized fund accounting and donor reporting requirements.
- Individuals:High-net-worth persons and family offices seeking wealth transfer and private client services.
Corporations anchor the volume base while small businesses expand most quickly.
Engagement Model:
Margin profiles diverge sharply between time-and-materials risk transfer and outcome-based pricing that aligns firm compensation with client value realization.
- Hourly Billing:Traditional time-based pricing dominant in audit and litigation support engagements. Talent pipeline constraints in the United States elevate rate pressure as firms compete for limited CPA-qualified professionals.
- Fixed Price:Scope-defined contracts common in recurring compliance services and standardized bookkeeping engagements.
- Retainer:Recurring monthly or annual fees for ongoing advisory access and priority service capacity.
- Contingency:Success-based compensation tied to tax controversy outcomes or transaction closing, concentrated in M&A tax structuring and transfer pricing defense.
Hourly billing anchors the volume base while retainer structures climb the fastest.
Technology Use:
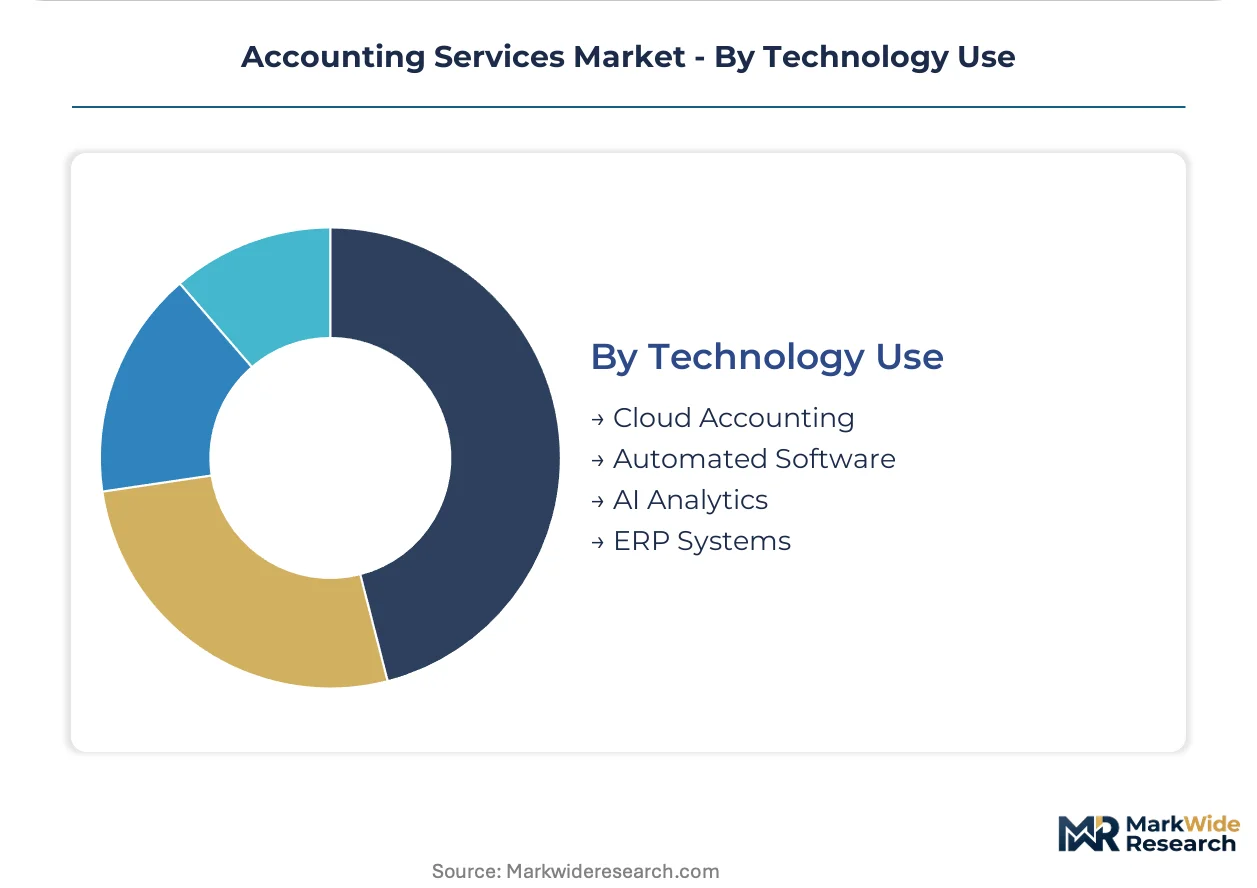
Application intensity separates legacy-dependent practices from cloud-native competitors, with AI deployment compressing fieldwork timelines while elevating capital requirements.
- Cloud Accounting:Browser-based platforms enabling real-time collaboration and automated bank reconciliation. Small business adoption accelerates client acquisition economics through API-integrated banking and payment infrastructure.
- Automated Software:Rule-based processing for data entry, categorization, and preliminary reconciliation. Mid-market firms leverage network-shared platforms to narrow quality gaps with proprietary systems.
- AI Analytics:Natural language processing for document population review and anomaly detection in audit engagements. Absence of codified PCAOB guidance on algorithmic evidence evaluation creates liability ambiguity.
- ERP Systems:Enterprise resource planning integration for standardized data extraction and automated analytics pipeline construction.
Cloud accounting anchors the volume base while AI analytics follows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure mandates and PCAOB oversight requirements anchor United States demand for premium advisory services. Regulatory complexity across multiple jurisdictions sustains cross-border service expansion.
United States
Public company audit practices face elevated professional liability premiums as PCAOB inspection intensity rises. The SEC's climate disclosure rules, currently stayed pending litigation, nonetheless shape preparatory advisory spending. New York and Chicago sustain the densest concentrations of Big Four network offices serving Fortune 500 compliance needs.
Germany
CSRD implementation expands advisory scope into carbon accounting and supply chain due diligence for in-scope entities. The country's national corporate governance regulator enforces stringent sustainability reporting timelines. Frankfurt and Munich anchor the highest density of ESG advisory practices serving DAX-listed corporations.
United Kingdom
Digital filing mandates reshape small business procurement priorities toward cloud accounting platforms. The Financial Conduct Authority maintains oversight of audit quality for listed entities. London's Square Mile concentration sustains premium rates for cross-border tax structuring and transfer pricing documentation.
India
SEBI's tightening corporate governance codes and GST complexity sustain demand for Big Four network expansion. The country's national securities regulator mandates enhanced disclosure for listed entities. Mumbai and Bangalore drive tier-one city advisory growth, while tier-two expansion accelerates in Pune and Hyderabad.
Japan
OECD Pillar-Two minimum tax implementations deepen compliance demand across multinational corporate portfolios. METI guidance shapes sustainability disclosure expectations for domestic issuers. Tokyo's Marunouchi district concentrates the largest advisory practices serving keiretsu-affiliated corporations.
Accounting Services Market Vendor Landscape
Multinational network firms and mid-tier affiliated practices split the market into consolidated premium tiers and fragmented service layers. The vendor base stratifies across three strategic archetypes: technology-integrated global networks, relationship-intensive regional specialists, and cloud-native platform operators. Dominant competitive moves include proprietary AI tool development and subscription-based engagement model expansion.
Within the technology-integrated tier, Deloitte, PwC, and EY exemplify archetypes competing through deep specialization in regulatory compliance, risk advisory, and sustainability reporting respectively. These network-affiliated entities occupy positions where proprietary audit methodology and cross-border coordination capabilities sustain premium pricing power against mid-market challengers.
| Leading Market Players |
|---|
| KPMG |
| RSM International |
| Deloitte |
| Baker Tilly International |
| Grant Thornton |
| PwC |
| BDO |
| Plante Moran |
| EY |
| Others |
Supply Flow & Price Mechanics
PCAOB inspection intensity as a regulatory chokepoint determines both the widening spread between premium advisory rates and commoditized compliance pricing and the geographic consolidation of audit practices into liability-insurance-accessible jurisdictions. Firms absorb elevated professional liability premiums by concentrating partner-level talent in United States coastal corridors while pushing standardized bookkeeping toward cloud-native platforms with subscription economics.
Pricing Analysis
The customization-premium spread separates bespoke multi-jurisdiction advisory from standardized SaaS-delivered compliance. Subscription pricing for cloud accounting platforms anchors the economy tier, while CSRD-aligned sustainability reporting and OECD Pillar-Two tax structuring command premium rates. Pricing pressure stems from mid-market firms leveraging network-shared AI tools to narrow quality gaps with proprietary systems. Small businesses exhibit highest price sensitivity, migrating rapidly to automated software with embedded professional services marketplaces; corporations show lowest sensitivity, prioritizing regulatory defensibility and cross-border coordination capabilities.
Supply Chain Analysis
Tariff exposure between the United States and trading partners with digital services tax regimes dominates supply chain risk for multinational advisory networks. Talent concentration rests on the United States, United Kingdom, and India as primary sourcing pools for CPA-qualified professionals and technology-enabled delivery centers. Proprietary AI audit tools and cloud infrastructure subscriptions constitute critical input dependencies. Single-source vulnerability concentrates in hyperscaler cloud platforms hosting client data and analytics pipelines. Distribution runs through multinational network affiliations for enterprise clients and SaaS marketplaces for small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accounting services represent a service-attach opportunity where recurring advisory subscriptions expand faster than transactional compliance engagements, with ESG disclosure readiness and digital transformation consulting sustaining margin expansion beyond traditional audit economics.
For Market Incumbents: Build switching-cost moats through deep ERP system integration and proprietary AI-assisted audit methodology that elevates documentation standards clients cannot replicate internally. Consolidate position by acquiring cloud-native bookkeeping platforms to capture small business subscription economics. Address the threat of generative AI compressing staff-to-revenue ratios through accelerated proprietary tool deployment. Leverage vertical integration into sustainability data verification to capture CSRD and ISSB advisory white space. For New Entrants and Emerging Players: Mid-market corporations in Germany and Japan navigating simultaneous OECD Pillar-Two implementation and CSRD disclosure timelines represent the most penetrable entry point for specialized tax and ESG advisory boutiques. Target tier-two Indian cities where SEBI governance code complexity outpaces Big Four expansion capacity. Pursue embedded finance convergence through accounting software APIs integrating real-time advisory at point-of-transaction as the primary go-to-market angle. For Investors and Strategic Acquirers: The SEC's eventual codification of climate disclosure attestation standards reshapes the acquisition landscape toward firms with established carbon accounting methodologies and scenario analysis capabilities. Long-term viability favors practices combining technology-augmented efficiency with relationship-intensive regulatory specialization. Target acquisition archetypes include regional specialists with deep jurisdiction-specific compliance expertise and cloud-native platforms with proven small business retention metrics. Monitor PCAOB algorithmic audit standards deliberations as the signal for when AI-assisted methodology becomes a defensible competitive moat versus a liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Audit Tool Development | Deloitte's methodology investments compress fieldwork timelines while elevating anomaly detection coverage beyond sampling-based approaches. |
| CSRD-Aligned Service Expansion | EY's sustainability reporting specialization captures carbon accounting demand as EU disclosure obligations extend to supply chain due diligence. |
| Cloud Platform Acquisition | Network-affiliated firms absorb SaaS bookkeeping providers to secure small business subscription economics and cross-sell attach rates. |
| India Tier-Two Geographic Expansion | Big Four practices in Pune and Hyderabad address SEBI governance complexity outpacing domestic advisory capacity. |
| Embedded Finance API Integration | Real-time advisory services at point-of-transaction reshape client acquisition economics through banking and payment infrastructure convergence. |
Methodological Framework
Desk research of SEC regulatory filings, PCAOB inspection reports, EU CSRD implementation guidance, and OECD tax policy documentation preceded structured interviews with Big Four engagement partners, mid-tier firm managing directors, cloud accounting software product managers, and corporate tax directors at multinational corporations. Primary fieldwork combined with secondary validation across trade association publications, professional liability insurance market data, and accounting program enrollment statistics. Bottom-up service line revenue modeling triangulated against top-down market sizing from regulatory mandate coverage expansion.
Assumptions held fixed include continued PCAOB oversight of public company audits, progressive CSRD phase-in timelines across EU member states, and sustained OECD Pillar-Two minimum tax implementation. Variables incorporated technology adoption curves for AI-assisted audit tools, cloud accounting platform penetration rates by client segment, and regulatory anticipation spending ahead of enforcement deadlines. CAGRs derived from segment-level growth rate blending across service types, client categories, and technology use dimensions. Forecast inputs included partner-to-staff leverage ratios, subscription pricing displacement rates, and ESG advisory attach rates to traditional compliance engagements.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting corporate capital allocation to advisory services or regulatory enforcement budget constraints would shift the trajectory. Forecasts reflect documented assumptions subject to revision from algorithmic audit standards codification, generative AI capability advances, or multinational tax policy coordination failures. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Global Tax and Accounting Software Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Trust Accounting Software Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
AI in Accounting Market
Accounting and Taxation Services
Small Business Accounting Software Market