
 China Accounting Software Market | 2026-2036
China Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
China Accounting Software Market Insights
Software distribution through state-backed industrial cloud platforms is rewriting how accounting vendors reach mid-market buyers in China. Kingdee International Software Group Company Limited leverages its longstanding channel partnerships with provincial SOEs to sustain deployment volumes across manufacturing hubs. Yonyou Network Technology Co., Ltd. anchors its position through deep integration with China's electronic invoice infrastructure and tax bureau systems. SAP SE competes selectively, navigating compliance complexity by localizing its core financial modules for joint-venture headquarters in Beijing and Shenzhen.
China accounting software comprises enterprise-grade applications that automate general ledger, accounts payable and receivable, payroll, tax reporting, and regulatory compliance workflows, typically integrating with banking APIs and government tax platforms through standardized data exchange protocols. Cloud-based Solutions now lead new deployments as MIIT-mandated enterprise digitization drives SaaS procurement across state-affiliated supply chains. SME-oriented segments represent the fastest expansion pool, where subscription pricing and pre-configured tax templates reduce implementation friction for first-time adopters. Desktop Solutions retain residual share in remote inland provinces with unreliable connectivity, though margin pools have shifted decisively toward recurring-revenue SaaS models.
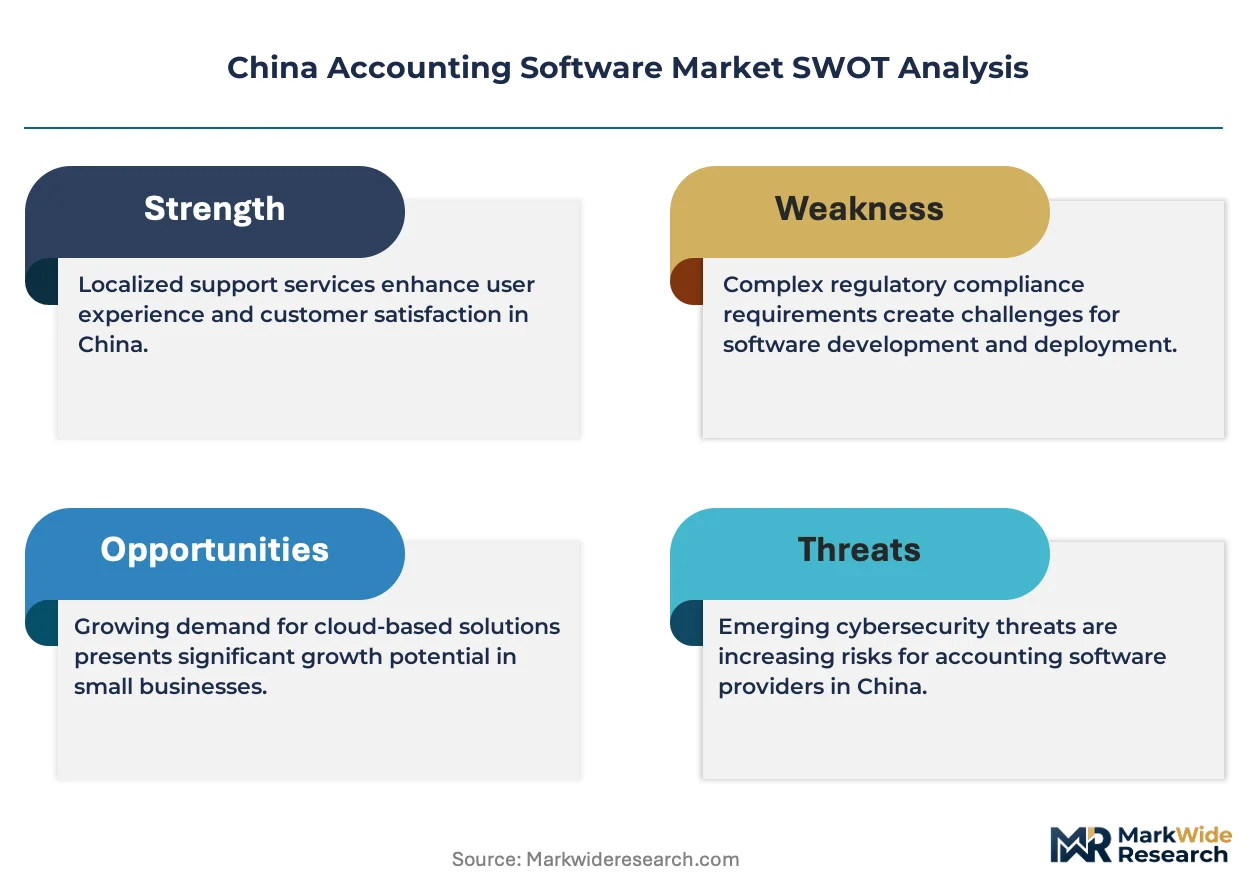
SAMR enforces data localization requirements that restrict cross-border data flows for financial records, compelling foreign vendors to establish domestic cloud infrastructure or partner with licensed local operators. GB standards for accounting information systems, alongside MIIT's cybersecurity classification framework, shape product architecture decisions and market access timelines. Stakeholders must monitor how upcoming revisions to China's data security law affect multi-tenant SaaS architectures and customer segmentation strategies.
Market Dynamics
MIIT's enterprise digitization mandates are compressing deployment timelines for domestic accounting software vendors while forcing foreign suppliers into costly localization partnerships. State-affiliated manufacturing groups now require cloud-native financial systems as a procurement condition, rewiring competitive access rules.
Growth Catalysts
- Yangtze River Delta SME Density:Shanghai and Hangzhou host China's highest concentration of first-time cloud accounting adopters, creating a self-reinforcing ecosystem of implementation expertise and vendor support infrastructure.
- MIIT 14th Five-Year Plan Mandates:State-owned enterprise procurement rules now prioritize SaaS financial solutions, accelerating replacement of on-premise legacy systems across provincial manufacturing supply chains.
- Electronic Invoice Infrastructure:Nationwide fapiao digitization requires real-time tax platform integration, pulling mid-market buyers toward certified software vendors with pre-built government API connections.
Market Restraints
- SAMR Data Localization Requirements:Cross-border financial data flow restrictions compel foreign vendors to establish domestic cloud infrastructure, inflating operational costs and extending market entry timelines.
- GB Standards Compliance Burden:Accounting information system certification demands specialized engineering resources that smaller domestic vendors struggle to allocate, concentrating supply among well-capitalized incumbents.
- Inland Connectivity Gaps:Unreliable broadband infrastructure in western provinces sustains residual demand for desktop solutions, fragmenting vendor R&D priorities between cloud and legacy architectures.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area:Cross-border trade finance complexity creates demand for multi-currency, multi-jurisdiction accounting modules that domestic vendors have yet to fully address.
- Carbon Accounting Module Integration:Dual carbon goals are forcing industrial enterprises to track emissions alongside financials, opening a product extension path for ERP-anchored accounting platforms.
- Industrial Cloud Platform Distribution:State-backed manufacturing clouds operated by provincial SOEs offer pre-qualified vendor slots that bypass traditional enterprise sales cycles.
Industry Challenges
- Multi-Tenant Architecture Redesign:GB cybersecurity classification frameworks require SaaS vendors to reengineer data isolation protocols, consuming engineering capacity that would otherwise fund feature development.
- Legacy System Integration Complexity:State-owned enterprises operate decades-old financial databases with non-standard data formats, forcing costly custom middleware development for each major deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Accounting Software Market |
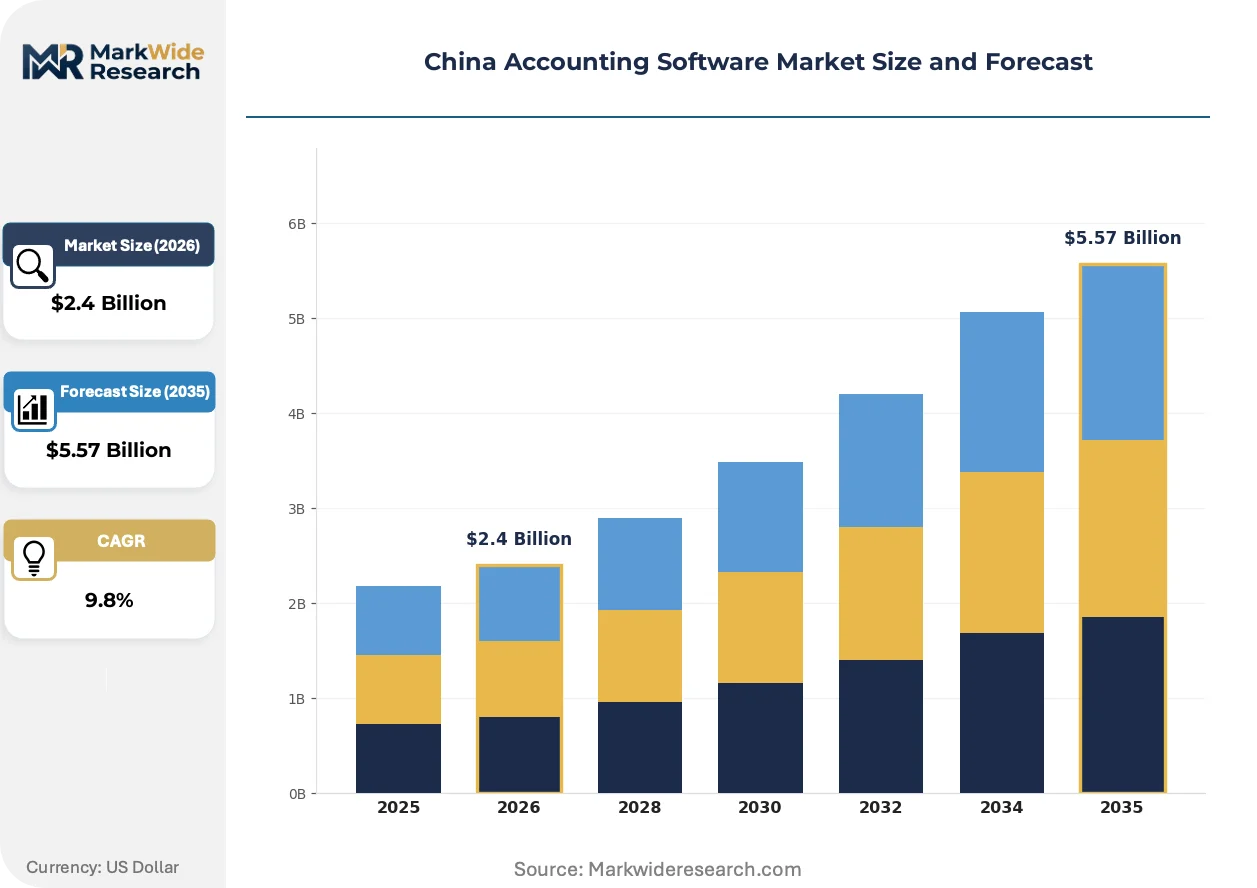
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.57 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Solutions, Cloud-based Solutions, Mobile Applications, Hybrid Solutions End User: SMEs, Large Enterprises, Freelancers, Non-profit Organizations Deployment: On-premises, SaaS, Managed Services, Open Source Compliance Standard: Tax Compliance, IFRS, GAAP, Others |
| Companies Covered | Kingdee International Software Group Company Limited, Yonyou Network Technology Co., Ltd., SAP SE, Oracle Corporation, Microsoft Corporation, Zoho Corporation, Xero Limited, FreshBooks, Tally Solutions Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Accounting Software Market Trends and Innovations
Cloud-native architectures are displacing monolithic deployments across China's finance function stack. Vendors now compete on integration depth with government tax platforms rather than standalone feature breadth.
Containerized microservices architecture is hybridizing deployment models across the China accounting software market. Mid-market manufacturers in Jiangsu and Zhejiang are adopting modular financial systems that combine core ledger functions with plug-in tax compliance modules. This technical approach is compressing implementation timelines from quarters to weeks while forcing vendors to standardize API documentation.
GB standards for accounting information systems are tightening data retention and audit trail requirements. Industrial consequences include mandatory blockchain-verified transaction logging for large enterprises and automated regulatory reporting interfaces. Joint-venture headquarters in Beijing and Shenzhen are responding by demanding localized versions of multinational ERP systems with domestic compliance modules pre-installed.
Subscription pricing models are displacing perpetual license sales across SME segments. First-time adopters in Hangzhou and Suzhou now expect pre-configured industry templates with monthly billing rather than upfront capital expenditure. This behavioral shift is visible most acutely in manufacturing supply chains where state-affiliated anchor buyers require cloud financial transparency from tier-two suppliers.
China Accounting Software Market Segmentation
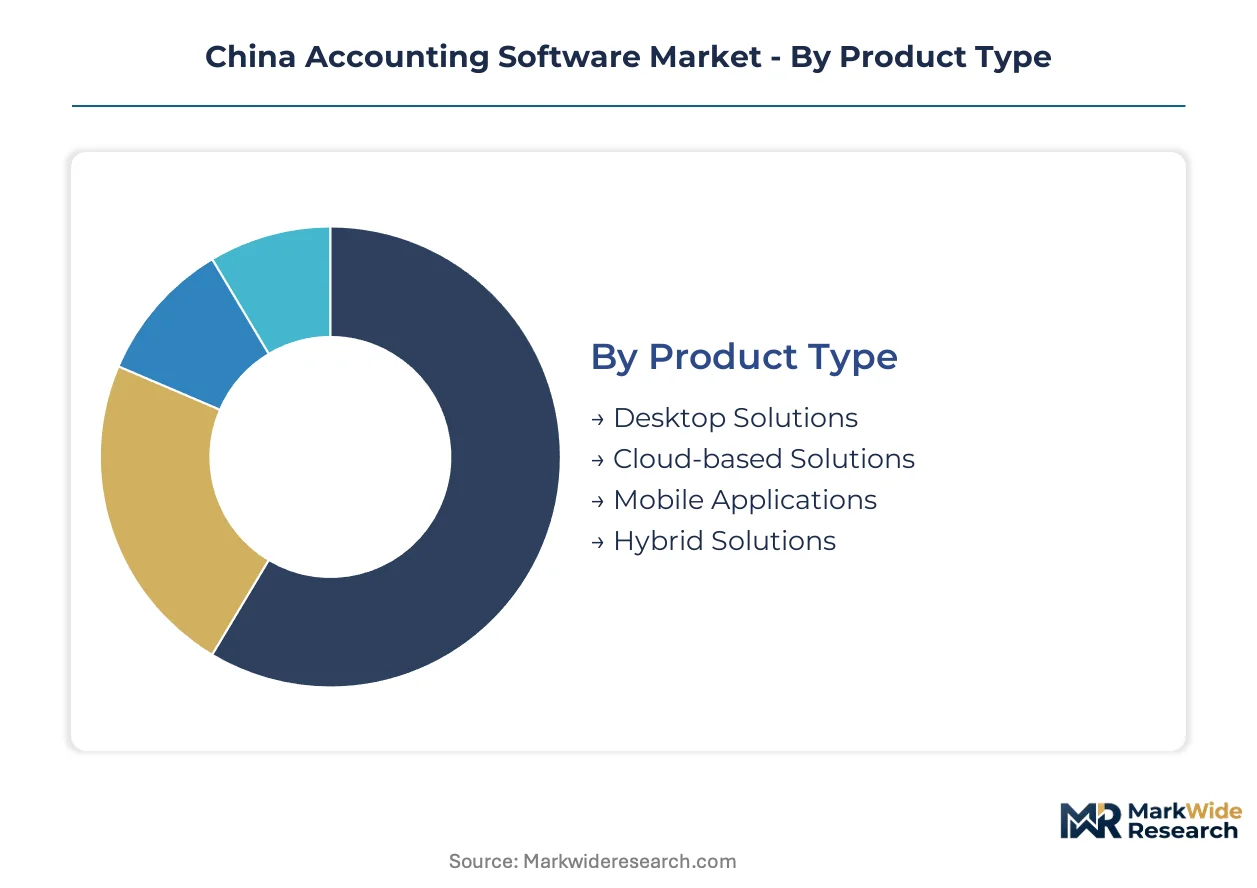
Segmentation in the China accounting software market reveals how procurement priorities diverge across buyer sophistication levels and regulatory exposure. Vendors configure sales teams and support infrastructure around these fault lines, with service intensity varying dramatically by deployment complexity and compliance burden.
Product Type:
After-sales-service intensity escalates with deployment complexity, as cloud migrations demand continuous integration support while desktop implementations require reactive break-fix coverage.
- Cloud-based Solutions:Multi-tenant SaaS architectures automate general ledger, accounts payable, and tax reporting workflows through browser-based interfaces with automatic GB standards updates. Demand concentrates in Shanghai and Hangzhou manufacturing clusters where MIIT-mandated enterprise digitization forces state-affiliated buyers toward subscription models with real-time government API integration.
- Desktop Solutions:Perpetual-license software installed on local servers retains dominance in western provinces with unreliable broadband infrastructure. Sichuan and Gansu procurement officers prioritize offline functionality and one-time capital expenditure over recurring operational costs, sustaining residual vendor R&D investment in legacy codebases.
- Mobile Applications:Lightweight iOS and Android tools for expense capture and approval workflows target field sales teams and distributed workforces.
- Hybrid Solutions:Containerized architectures combining on-premise core ledgers with cloud tax modules serve joint-venture headquarters navigating data localization requirements.
By volume, Desktop Solutions leads. By growth pace, Cloud-based Solutions is ahead.
End User:
Cost tier stratification separates buyers by implementation budget and internal IT capability, with premium consulting bundles reserved for complex enterprise deployments.
- SMEs:Hangzhou and Suzhou manufacturing supply chains drive first-time adoption through pre-configured industry templates with monthly subscription billing. State-affiliated anchor buyers now mandate cloud financial transparency from tier-two suppliers, compressing sales cycles and expanding addressable base.
- Large Enterprises:Provincial SOEs and private manufacturing groups operate decades-old financial databases requiring costly custom middleware for cloud migration. Beijing and Shenzhen joint-venture headquarters demand localized ERP modules with pre-installed domestic compliance features.
- Freelancers:Individual practitioners and micro-businesses purchase stripped-down invoicing and tax filing tools through app store distribution.
- Non-profit Organizations:Social enterprises and charitable foundations seek donor-restricted fund accounting with simplified audit trail generation.
SMEs dominate unit volume. Large Enterprises capture the steepest expansion trajectory as MIIT procurement mandates accelerate replacement timelines.
Deployment:
Application maturity varies sharply, with SaaS offerings commanding premium pricing for automatic compliance updates while open-source alternatives attract engineering-capable buyers.
- SaaS:Browser-delivered financial systems with automatic GB standards synchronization and blockchain-verified audit trails. Jiangsu and Zhejiang mid-market manufacturers adopt modular microservices architectures compressing implementation from quarters to weeks.
- On-premises:Legacy server installations persist in defense-adjacent industries and remote western provinces where data sovereignty concerns override cloud convenience.
- Managed Services:Outsourced infrastructure operation with vendor-managed security patching and backup recovery for buyers lacking internal IT capacity.
- Open Source:Community-developed platforms with customizable codebases attract technology-forward buyers willing to self-support compliance integration.
On-premises retains installed base leadership. SaaS is climbing the fastest as state procurement rules rewrite access conditions.
Compliance Standard:
Margin concentration follows regulatory complexity, with multi-standard certification commanding premium pricing from cross-border operators.
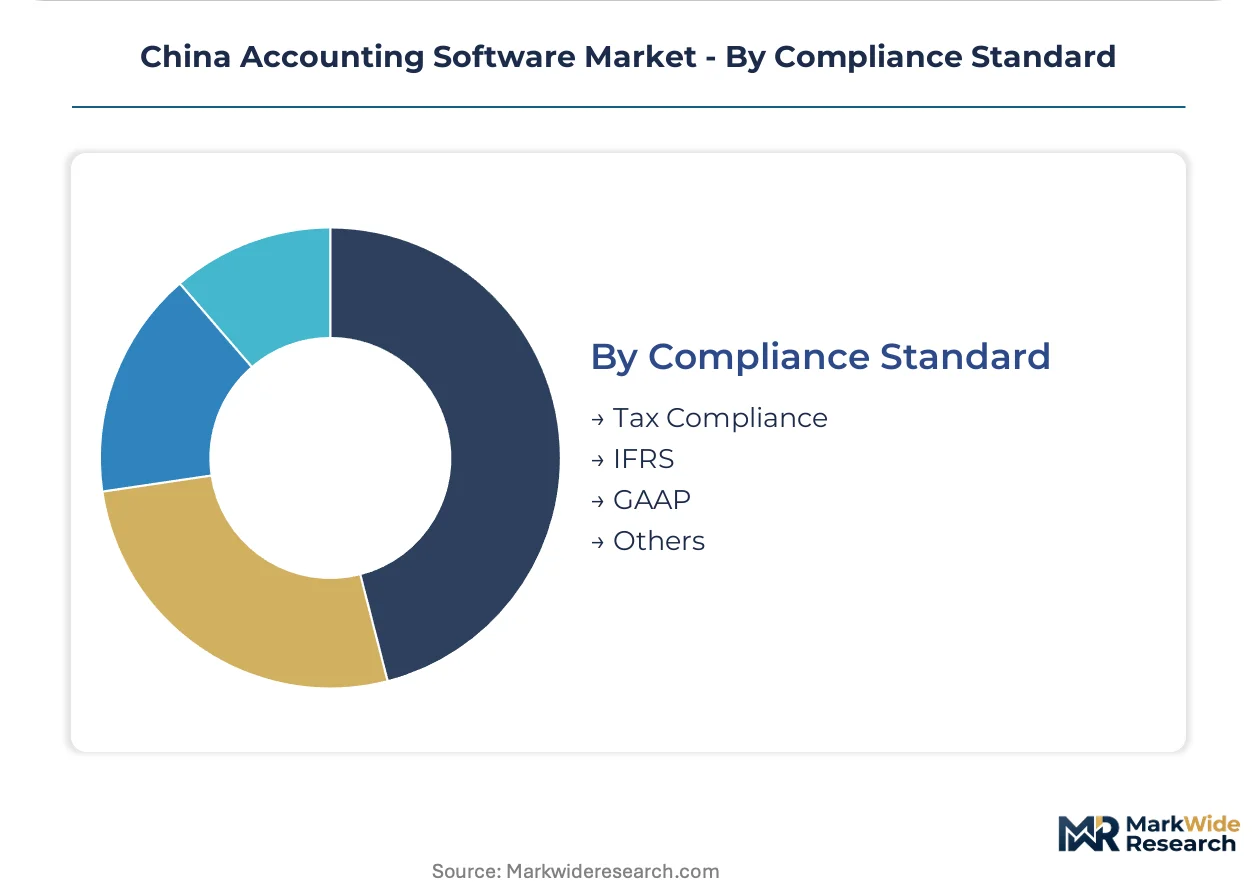
- Tax Compliance:Real-time fapiao digitization and automated SAR reporting through certified government API connections. Nationwide electronic invoice infrastructure pulls mid-market buyers toward pre-built tax platform integrations.
- IFRS:International Financial Reporting Standards modules serve dual-listed enterprises and foreign-invested joint ventures with consolidated group reporting requirements.
- GAAP:US Generally Accepted Accounting Principles configurations support subsidiaries of American multinationals with parent-company reporting obligations.
- Others:Industry-specific frameworks including construction contract accounting and agricultural cooperative standards.
Tax Compliance leads by deployment volume. IFRS is gaining share fastest among Guangdong-Hong Kong-Macao Greater Bay Area cross-border operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Guangzhou-Shenzhen high-speed rail corridor stitches together China's three dominant software demand poles, compressing vendor service radii and enabling same-day implementation support across the eastern seaboard.
Yangtze River Delta
Shanghai and Hangzhou host China's densest concentration of SME cloud accounting deployments, driven by state-affiliated manufacturing groups mandating financial transparency from tier-two suppliers. MIIT's enterprise digitization directives under the 14th Five-Year Plan accelerate replacement of legacy on-premise systems across Jiangsu and Zhejiang industrial clusters. Suzhou's precision manufacturing hub generates sustained demand for modular microservices architectures with pre-configured tax compliance templates.
Pearl River Delta
Shenzhen's electronics supply chains and Guangzhou's automotive component networks pull mid-market buyers toward SaaS solutions with real-time fapiao digitization. SAMR data localization requirements compel foreign vendors to establish domestic cloud infrastructure in the Greater Bay Area. Dongguan's factory automation ecosystem drives adoption of carbon accounting modules integrated with core financial ledgers.
Beijing-Tianjin-Hebei
State-owned enterprise headquarters in Beijing command premium ERP deployments with blockchain-verified audit trails and automated regulatory reporting interfaces. GB standards compliance certification concentrates engineering resources among well-capitalized domestic vendors. Tianjin's port logistics sector generates specialized demand for multi-currency trade finance modules.
Sichuan-Chongqing
Unreliable broadband infrastructure in western provinces sustains residual demand for desktop accounting solutions with offline functionality. Chongqing's automotive manufacturing base adopts hybrid architectures combining on-premise core ledgers with cloud tax modules. Chengdu's electronics assembly clusters pull first-time adopters toward subscription pricing with provincial SOE procurement support.
Shandong Peninsula
Qingdao's industrial machinery manufacturers and Yantai's chemical processing plants drive demand for compliance-heavy accounting systems with specialized industry templates. MIIT-mandated cybersecurity classification frameworks require SaaS vendors to reengineer data isolation protocols for large enterprise deployments. Jinan's logistics hub generates cross-border trade finance complexity that domestic vendors have yet to fully address.
China Accounting Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream serving niche compliance modules. The vendor base stratifies between cloud-native SaaS providers with state-backed distribution channels and legacy desktop incumbents defending residual inland markets. Three archetypes dominate: MIIT-certified domestic platforms with SOE procurement access, foreign ERP localizers navigating SAMR data restrictions, and agile SaaS challengers targeting SME subscription growth. Competitive intensity concentrates on M&A-driven capability consolidation and strategic partnerships with provincial industrial cloud operators.
Among domestic platform specialists, Kingdee International Software Group Company Limited and Yonyou Network Technology Co., Ltd. occupy positions anchoring the certified vendor tier through deep government system integration. SAP SE represents the foreign localizer archetype, navigating compliance complexity through selective joint-venture headquarters targeting. These three exemplify how competitive positioning depends on regulatory access depth rather than standalone feature differentiation.
| Leading Market Players |
|---|
| Kingdee International Software Group Company Limited |
| Yonyou Network Technology Co., Ltd. |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Zoho Corporation |
| Xero Limited |
| FreshBooks |
| Tally Solutions Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta cloud infrastructure is compressing SaaS vendor margins while forcing tier-two domestic players toward aggressive subscription discounting to maintain utilization rates. This utilization squeeze simultaneously erodes pricing power among mid-market specialists and accelerates consolidation toward MIIT-certified platforms with state-backed procurement access.
Pricing Analysis
Volume-discount tiering separates enterprise SOE deployments from SME subscriptions across three distinct pricing bands. Premium tiers bundle blockchain-verified audit trails and dedicated implementation support for Beijing headquarters, while standard SME offerings in Hangzhou and Suzhou compete on pre-configured tax template availability. Cost compression in the mid-market intensifies as provincial industrial clouds aggregate buyer demand and extract collective pricing concessions. First-time adopters in western provinces exhibit highest price sensitivity, preferring perpetual desktop licenses over recurring SaaS commitments.
Supply Chain Analysis
Contract manufacturing concentration for accounting software infrastructure rests with domestic cloud operators including Alibaba Cloud, Huawei Cloud, and Tencent Cloud, which host the majority of vendor deployments under MIIT cybersecurity classification frameworks. Engineering talent pools concentrate in Beijing, Shenzhen, and Hangzhou, where specialized compliance integration skills command premium compensation. Single-source vulnerability emerges from reliance on SAMR-licensed data centers for financial record localization. Distribution runs through state-backed industrial cloud platforms operated by provincial SOEs, bypassing traditional enterprise software channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting toward ecosystem lock-in as MIIT-mandated government API integration creates switching costs that cement incumbent positions. Interoperability requirements with electronic fapiao infrastructure are consolidating vendor tiers around certified integration depth rather than standalone feature differentiation.
For Market Incumbents: Harden data isolation architectures against upcoming GB cybersecurity classification revisions to preempt compliance-driven customer churn. Deepen vertical integration into provincial industrial cloud distribution channels to defend against SaaS challengers exploiting MIIT procurement aggregation. Prioritize carbon accounting module development as industrial SOEs face dual carbon goal reporting mandates. For New Entrants and Emerging Players: Cross-border trade finance complexity in the Guangdong-Hong Kong-Macao Greater Bay Area represents the most penetrable entry point, where multi-currency requirements exceed domestic vendor capabilities. Inland western provinces with residual desktop demand offer second-mover expansion potential as connectivity infrastructure improves. Partner with licensed local cloud operators to satisfy SAMR data localization requirements without capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SaaS infrastructure compliance as GB standards mandate blockchain-verified transaction logging and reengineered multi-tenant architectures. Acquisition targets should display pre-built government API integration depth and existing provincial SOE procurement relationships. Monitor MIIT procurement rule revisions for early signals of certification tier consolidation that would elevate compliant platforms above subscale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep government tax API connectivity locks in SOE buyers and creates defensible switching costs. |
| Strategic Partnership | Provincial industrial cloud slots bypass traditional enterprise sales cycles and accelerate deployment velocity. |
| Acquisition of Specialist Firm | Carbon accounting module capabilities address dual carbon goal reporting requirements for industrial enterprises. |
| Product Launch | Hybrid architectures combining on-premise ledgers with cloud tax modules serve joint-venture data localization needs. |
| Geographic Expansion | Greater Bay Area cross-border finance complexity demands multi-jurisdiction capabilities domestic vendors underserve. |
Research Methodology
Desk research of MIIT policy directives, SAMR regulatory filings, and provincial SOE procurement databases preceded structured interviews with CTOs at manufacturing enterprises, IT procurement officers at joint-venture headquarters, platform engineers at domestic cloud operators, and integration specialists at certified software vendors. Secondary validation drew from GB standards documentation, electronic fapiao infrastructure technical specifications, and cybersecurity classification framework disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing derived from subscription pricing benchmarks across tiered customer segments.
Assumptions regarding MIIT mandate enforcement timelines, SAMR data localization interpretation consistency, and provincial industrial cloud platform rollout schedules were held fixed across baseline scenarios while sensitivity analysis varied SME adoption velocity and foreign vendor market access conditions. Segmentation modeling incorporated deployment model, organization size by employee count, vertical industry classification, integration complexity tier, and regional adoption pattern. CAGRs were derived from logistic diffusion curves fitted to historical cloud migration rates and projected forward based on procurement rule change impact assessments.
Practitioners should monitor MIIT procurement rule revisions, SAMR cross-border data flow enforcement actions, and GB standards update cadence for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained state-affiliated buyer cloud migration momentum and stable regulatory interpretation of data localization requirements. Quarterly review of provincial SOE procurement announcement volumes and certified vendor list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Trust Accounting Software Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Corporate Tax Service Market