
 Global Strategy Consulting Market | 2026-2036
Global Strategy Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Strategy Consulting Market Outlook
Healthcare provider networks is consolidating advisory spending as regulatory complexity and operational restructuring reshape procurement priorities. McKinsey & Company leverages its institutional knowledge in payer-provider convergence to sustain retainer relationships with large hospital systems. Boston Consulting Group anchors its position through specialized healthcare value-based care transformation units that compete directly with generalist advisory offerings.
Strategy consulting encompasses structured advisory services that diagnose competitive positioning, design operating models, and implement performance improvement programs across organizations. These engagements typically deploy proprietary analytical frameworks, primary research methodologies, and cross-functional team structures to translate board-level objectives into executable initiatives. Strategy Development commands premium pricing due to C-suite access and transformational scope, while Operational Consulting extends across longer durations with recurring revenue characteristics. Project-Based engagements dominate technology sector assignments, whereas Retainer structures prevail in financial advisory relationships with private equity sponsors.
The EU AI Act and GDPR impose algorithmic accountability and data governance standards that reshape compliance-related consulting demand across European operations. The SEC's climate disclosure rules and the IRA's domestic content requirements similarly generate advisory workload for U.S.-based corporate strategy functions. Stakeholders must monitor how regulatory fragmentation between jurisdictions affects cross-border engagement pricing and talent deployment models.
Market Dynamics
Healthcare provider networks are consolidating advisory spending as regulatory complexity and operational restructuring reshape procurement priorities. The EU AI Act and GDPR compliance obligations intensify across European operations, while technology sector restructuring and federal infrastructure investment drive sustained consultant utilization in the United States.
Growth Catalysts
- EU AI Act mandates:Algorithmic accountability requirements across European healthcare and financial services generate sustained demand for compliance architecture and governance framework design.
- Healthcare payer-provider convergence:Value-based care transformation requires specialized advisory support for hospital systems navigating risk-bearing contract structures and population health management.
- US federal infrastructure investment:IRA domestic content requirements and IIJA implementation create project-based advisory workload across energy, transportation, and manufacturing clients.
Market Restraints
- Talent scarcity in specialized domains:Shortage of consultants with dual expertise in healthcare operations and AI governance limits firm capacity to capture regulatory-driven demand.
- Client procurement centralization:Large corporate buyers consolidate vendor panels and compress fee structures through competitive bidding and outcome-based contracting.
- Regulatory fragmentation:Divergent compliance timelines between the EU AI Act, US SEC climate disclosure rules, and emerging national AI frameworks increase cross-border engagement complexity.
Strategic Opportunities
- India's digital health infrastructure:Ayushman Bharat expansion and CDSCO regulatory modernization create advisory white space for operational transformation and quality certification support.
- Climate transition advisory:CSRD implementation and EU Green Deal alignment requirements open new service lines in emissions accounting, supply chain decarbonization, and circular economy strategy.
- Generative AI integration:Convergence of large language models with proprietary consulting methodologies enables automated research synthesis and accelerates diagnostic phase delivery.
Industry Challenges
- Knowledge codification and retention:Senior partner departure and proprietary framework leakage threaten firm differentiation as talent mobility increases across competitors.
- Technology-enabled disintermediation:Self-service analytics platforms and AI-powered strategy tools compress margins on traditional diagnostic and benchmarking engagements.
- Client capability building:Corporate strategy functions internalize former consulting talent, reducing reliance on external advisory for recurring operational support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Strategy Consulting Market |
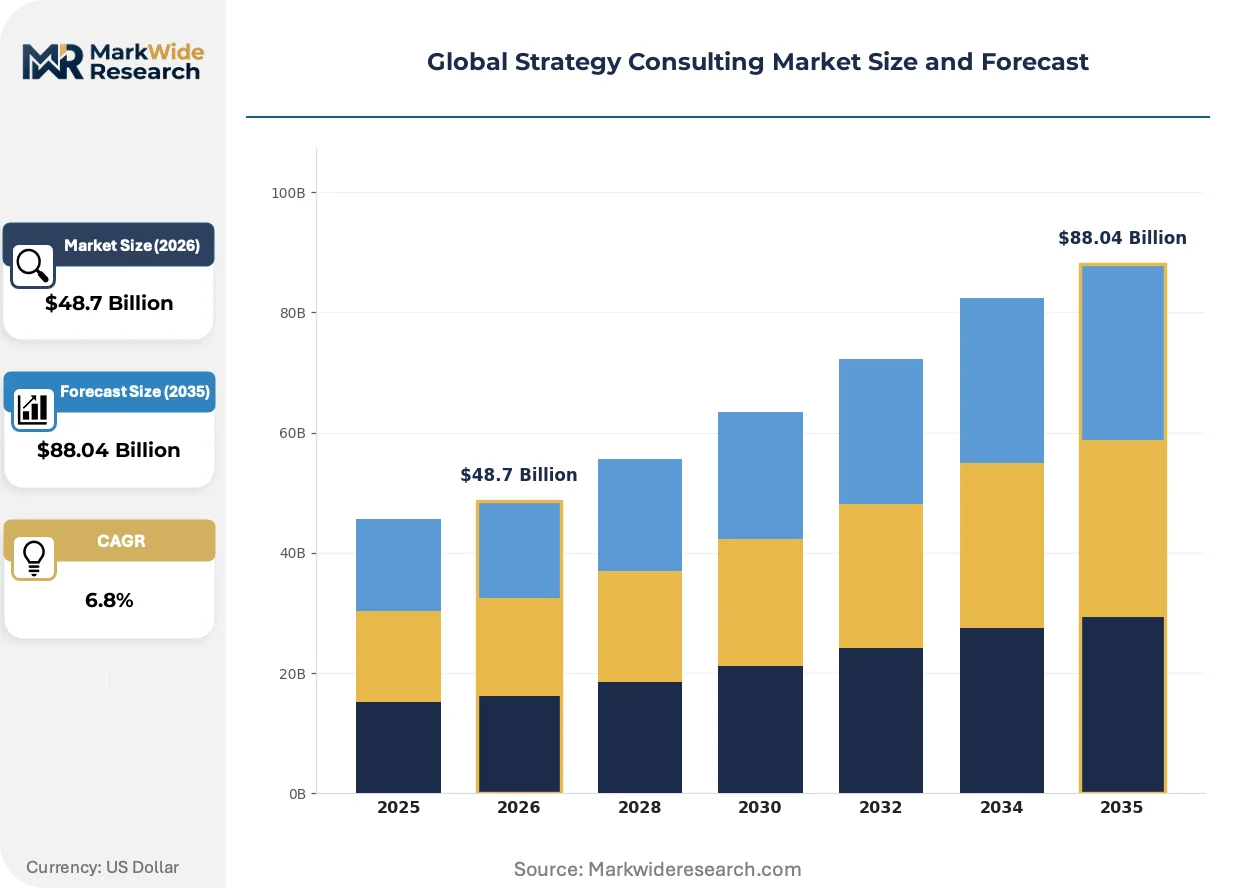
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Operational Consulting, Financial Advisory, Strategy Development, Risk Management Engagement Model: Project-Based, Retainer, Advisory, Interim Management Client Type: Corporations, Governments, Nonprofits, Startups Industry Vertical: Technology, Healthcare, Manufacturing, Energy |
| Companies Covered | Accenture Strategy, PwC Strategy&, McKinsey & Company, EY Parthenon, Oliver Wyman, Boston Consulting Group, Deloitte Consulting, L.E.K. Consulting, Bain & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Strategy Consulting Market Strategic Shifts
Advisory delivery models are transforming as generative AI capabilities mature and regulatory complexity demands specialized expertise. Three developments are restructuring competitive positioning and value capture mechanisms across the sector.
Generative AI is automating research synthesis, financial modeling, and scenario generation across strategy development engagements. Large hospital systems and private equity sponsors now expect AI-augmented deliverables that compress project timelines from twelve weeks to four. This technology is automating junior analyst functions and forcing firms to restructure team compositions toward senior-heavy, judgment-intensive advisory.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk AI applications in healthcare and financial services. Industrial consequence includes mandatory conformity assessments and post-market monitoring obligations that reshape advisory scope. European healthcare providers and German automotive suppliers are responding by embedding compliance architecture into product development cycles rather than retrofitting post-deployment.
Corporate buyers are unbundling strategy advisory from implementation support, creating separate procurement streams for diagnostic and execution phases. Large technology companies and US-based infrastructure investors now source strategy development from elite boutiques while contracting operational transformation to mid-tier firms or captive consulting units. This pattern is most visible in Silicon Valley and Texas energy corridors where buyer sophistication and vendor familiarity enable granular service decomposition.
Global Strategy Consulting Market Segmentation
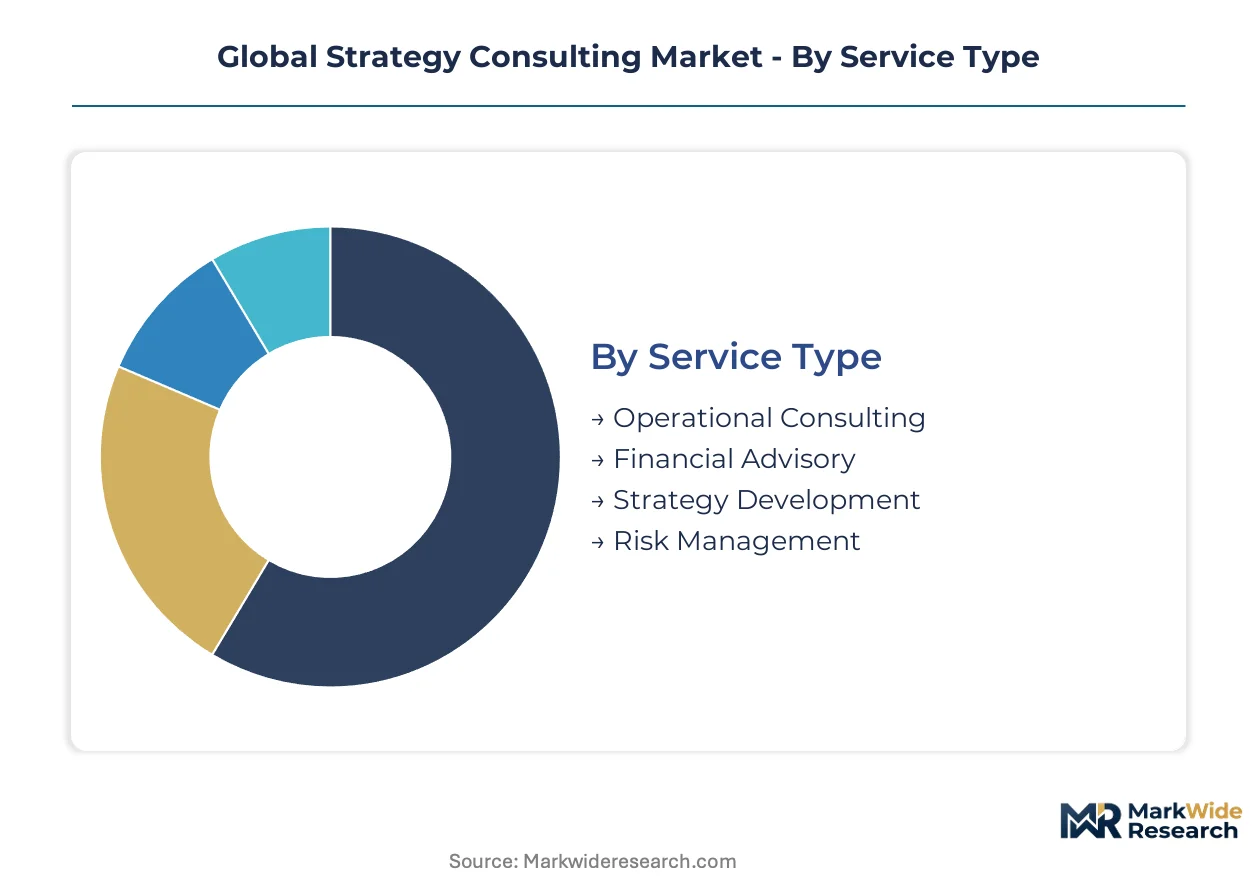
Strategy consulting engagements vary sharply in pricing power, duration, and talent deployment based on service architecture and client procurement maturity. Segmentation reveals where premium capture concentrates and which engagement models face commoditization pressure from technology-enabled alternatives.
Service Type:
Cost tier separates diagnostic advisory from implementation-heavy support, with pricing multiples widening between strategy formulation and operational execution.
- Strategy Development:C-suite-facing engagements diagnose competitive positioning and design operating models using proprietary analytical frameworks. Hospital systems in Germany and technology platforms in the United States sustain premium pricing for board-level transformation mandates.
- Operational Consulting:Performance improvement programs deploy cross-functional teams across extended durations with recurring revenue characteristics. Manufacturing clients in Japan and energy operators in Texas favor multi-year contracts for supply chain and cost restructuring.
- Financial Advisory:Transaction support and valuation services for private equity sponsors and corporate development functions.
- Risk Management:Regulatory compliance architecture and governance framework design for EU AI Act and SEC disclosure obligations.
Volume sits with Operational Consulting; growth tilts toward Risk Management.
Engagement Model:
Application context determines whether clients seek discrete deliverables or embedded advisory capacity, reshaping firm staffing models and margin structures.
- Project-Based:Defined-scope engagements with fixed deliverables and timelines dominate technology sector assignments. Silicon Valley restructuring mandates and IIJA infrastructure implementations in the United States compress from twelve-week cycles to four through generative AI augmentation.
- Retainer:Continuous advisory relationships prevail in financial services and private equity sponsor coverage. Large hospital systems in the United States maintain multi-year agreements for payer-provider convergence support.
- Advisory:On-demand expertise for specific decisions without ongoing relationship infrastructure.
- Interim Management:Embedded executive placement for turnaround and transition scenarios.
Retainer structures capture the most predictable revenue; project-based formats are expanding most quickly.
Client Type:
Procurement sophistication and internal capability depth create divergent service expectations across buyer categories.
- Corporations:Large enterprise buyers consolidate vendor panels and unbundle strategy from implementation. US-based infrastructure investors and German automotive suppliers now source diagnostics from elite boutiques while contracting execution to mid-tier firms.
- Governments:Public sector procurement emphasizes compliance architecture and federal program implementation. IRA domestic content requirements and EU Green Deal alignment generate sustained advisory workload.
- Nonprofits:Mission-driven organizations with constrained procurement flexibility.
- Startups:Venture-backed companies seeking rapid scaling support with equity-aligned compensation structures.
Corporations dominate current spending; governments show the steepest expansion trajectory.
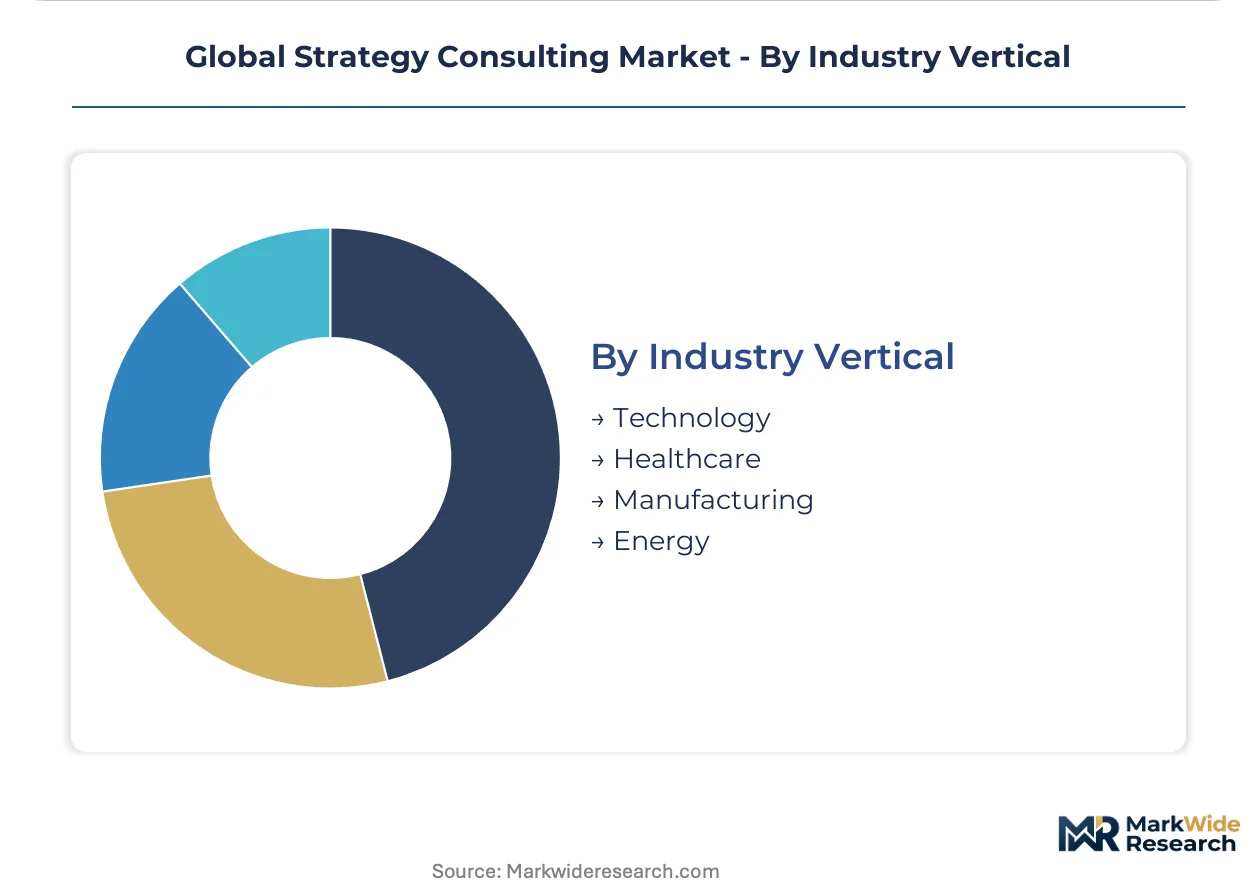
Industry Vertical:
Regulatory intensity and technology disruption velocity determine advisory pricing power and engagement duration across sectors.
- Healthcare:Value-based care transformation and EU AI Act compliance drive specialized demand. Provider networks in France and the United States embed governance architecture into product development cycles rather than retrofitting post-deployment.
- Technology:Sector restructuring and generative AI integration create project-based workload. Platform companies in California and Texas energy corridors unbundle procurement streams for diagnostic and execution phases.
- Manufacturing:Supply chain decarbonization and CSRD implementation requirements.
- Energy:IRA implementation and circular economy strategy for utilities and renewable developers.
Healthcare commands premium pricing; technology verticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and federal tax incentives drive consulting firm concentration across strategic metropolitan clusters. The United States, Germany, United Kingdom, India, and Japan anchor regional demand through distinct regulatory and industrial catalysts.
United States
Technology sector restructuring and IRA domestic content requirements sustain elevated advisory utilization. SEC climate disclosure rules and IIJA implementation generate compliance architecture workload. Silicon Valley and Texas energy corridors host unbundled procurement patterns where diagnostics and execution phases separate.
Germany
EU AI Act risk-based classification mandates reshape advisory scope for automotive and healthcare clients. GDPR enforcement intensifies data governance requirements across industrial operations. Bavaria and Baden-Württemberg concentrate specialized compliance architecture demand among Mittelstand exporters.
United Kingdom
Financial services regulatory modernization and post-Brexit trade alignment sustain London-based advisory demand. FCA operational resilience requirements and CSRD preparation generate governance framework workload. The City of London and Canary Wharf cluster retain retainer relationships with private equity sponsors.
India
Ayushman Bharat digital health expansion and CDSCO regulatory modernization create operational transformation white space. PLI scheme implementation across manufacturing sectors drives supply chain advisory. Mumbai and Bangalore concentrate project-based engagements for technology and healthcare clients.
Japan
Corporate governance reform and METI carbon neutrality roadmaps sustain strategy development demand. PMDA regulatory harmonization requirements reshape pharmaceutical advisory scope. Tokyo and Osaka anchor retainer structures with diversified industrial conglomerates.
Global Strategy Consulting Market Competitive Environment
Top-tier vendors anchor premium-tier advisory, while mid-tier specialists and boutique firms populate execution-heavy segments. The market structures around reputation-based differentiation and proprietary methodology ownership. Three archetypes dominate: diversified professional services networks, pure-play strategy boutiques, and technology-enabled advisory platforms. Consolidation through lateral partner hiring and capability-focused acquisitions reshapes competitive positioning.
Among diversified networks, Accenture Strategy, Deloitte Consulting, and PwC Strategy& exemplify scale-driven service integration. These firms occupy positions spanning diagnostic through implementation phases. McKinsey & Company and Boston Consulting Group anchor the pure-play tier where judgment-intensive advisory commands premium pricing. The competitive dynamic forces restructuring toward senior-heavy team compositions as generative AI compresses traditional research functions.
| Leading Market Players |
|---|
| Accenture Strategy |
| PwC Strategy& |
| McKinsey & Company |
| EY Parthenon |
| Oliver Wyman |
| Boston Consulting Group |
| Deloitte Consulting |
| L.E.K. Consulting |
| Bain & Company |
| Others |
Value Chain & Pricing Dynamics
Generative AI deployment across research synthesis and financial modeling functions is compressing project delivery timelines from twelve weeks to four, simultaneously reducing labor cost intensity and concentrating premium pricing power among firms with proprietary algorithmic capabilities. This technology shift forces restructuring toward senior-heavy team compositions while algorithmic accountability mandates under the EU AI Act create new cost layers for compliance architecture.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent diagnostic mandates from standard-cycle engagements, with Silicon Valley technology platforms and Texas infrastructure investors paying premiums for compressed four-week delivery windows. Three-tier pricing structure across partner-led transformation, director-managed implementation, and manager-executed benchmarking reflects expertise gradient and client procurement maturity. Pricing pressure stems from client unbundling of strategy and execution phases, with corporate buyers sourcing diagnostics from elite boutiques and contracting operational work to mid-tier firms. Private equity sponsors show lowest price sensitivity due to transaction urgency, while healthcare provider networks negotiate hardest on retainer renewals.
Supply Chain Analysis
IRA domestic content requirements and EU Green Deal local-content rules are reshaping talent deployment models, forcing advisory firms to build country-specific compliance capabilities rather than serving European and US clients from centralized hubs. Supply concentration rests on the United States, Germany, and the United Kingdom for premium-tier advisory, with India and Poland emerging as delivery centers for operational implementation support. Raw material inputs comprise specialized healthcare operations expertise, AI governance certification, and climate transition methodology. Single-source vulnerability concentrates in partner-level talent with dual expertise in regulatory compliance and sector operations. Distribution runs through direct partner relationships for C-suite mandates and procurement-managed vendor panels for operational engagements.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global strategy consulting market functions as a cost-of-compliance story where EU AI Act algorithmic accountability mandates and SEC climate disclosure rules erect barrier-to-entry moats favoring firms with established governance architecture capabilities.
For Market Incumbents: Extend proprietary methodology ownership through targeted acquisition of boutique AI governance specialists and climate transition advisory practices. Consolidate position against technology-enabled disintermediation by embedding generative AI tools into client-facing platforms while maintaining partner judgment as the differentiated layer. Build captive delivery capabilities in India to capture Ayushman Bharat operational transformation demand.
For New Entrants and Emerging Players: Begin with narrow vertical specialization in EU AI Act compliance architecture for German automotive suppliers or CDSCO regulatory modernization for Indian pharmaceutical manufacturers. Target the Risk Management service segment where talent scarcity limits incumbent capacity expansion. Pursue partnership-based go-to-market models with established firms seeking execution capacity without competitive threat.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified professional services networks seeking healthcare or climate advisory capabilities. Long-term viability favors firms with retainer-based revenue structures and proprietary data assets rather than project-dependent boutiques. Watch lateral partner mobility rates as the inflection signal for firm stability and client retention risk.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Practice Buildout | Captures EU AI Act compliance demand from German automotive and French healthcare clients. |
| Climate Transition Advisory Launch | Addresses CSRD implementation and EU Green Deal alignment requirements for industrial conglomerates. |
| Healthcare Payer-Provider Convergence Unit | Supports US hospital systems navigating risk-bearing contract structures and population health mandates. |
| India Delivery Center Expansion | Captures Ayushman Bharat digital health and PLI scheme manufacturing advisory workload. |
| Generative AI Platform Integration | Compresses research synthesis timelines while preserving partner judgment as premium differentiation. |
Study Parameters
Multi-period observation of advisory firm headcount trajectories, client procurement pattern shifts, and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with strategy consulting partners, healthcare system chief strategy officers, private equity operating partners, and EU regulatory affairs directors. Secondary validation drew from SEC filings of diversified professional services networks, EU AI Act implementation guidance documents, CMS Medicare reimbursement data, and hospital procurement database records. Bottom-up engagement volume estimates triangulated against top-down market sizing derived from firm revenue disclosures and industry association benchmarks.
Input-output matrices mapped service type, engagement model, client vertical, and geographic demand clusters across the projection horizon. Segmentation dimensions modeled include strategy development versus operational consulting intensity, project-based versus retainer structure, healthcare versus technology versus energy vertical concentration, and US versus European versus Asia-Pacific demand distribution. CAGRs were derived from regression analysis of historical advisory spending against regulatory implementation schedules and infrastructure investment cycles. Forecast inputs incorporated EU AI Act enforcement phase transitions and IRA domestic content requirement rollouts.
Regulatory implementation delays, faster-than-expected client internalization of advisory capabilities, and generative AI disruption of junior analyst functions are the dominant revision risks to the analytical framework. Forecasts reflect assumptions regarding compliance timeline adherence and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Europe Strategy Consulting Market