
 Forensic Accounting Market | 2026-2036
Forensic Accounting Market Size, Share, and Industry Trends Forecast 2026-2036
Forensic Accounting Market Analysis
Insurance sector demand is decoupling from traditional banking-driven engagement patterns as healthcare fraud investigations expand. KPMG leverages its multidisciplinary fraud investigation platform across insurance and healthcare verticals. PwC anchors its forensic practice in regulatory response capabilities, particularly around SEC enforcement and PCAOB inspection remediation. Ernst & Young differentiates through technology-enhanced audit analytics that accelerate fraud detection timelines.
Forensic accounting applies specialized accounting, auditing, and investigative skills to legal disputes, fraud allegations, and financial irregularities, employing data analytics, financial modeling, and evidence-gathering protocols that satisfy evidentiary standards in civil and criminal proceedings. Its primary commercial purpose is to quantify economic damages, trace asset flows, and reconstruct financial records for litigation support, regulatory compliance, and internal corporate investigations. Fraud investigation services lead the service type category as white-collar enforcement intensifies, while project-based engagement models capture the fastest growth as corporations shift from fixed retainers to outcome-specific procurement. Law firms represent the most concentrated client type by margin pool, given their role as intermediaries in high-stakes litigation.
The SEC, PCAOB, and DOJ shape market demand through enforcement priorities that mandate specialized financial investigation capabilities, with SEC whistleblower program expansions directly increasing corporate forensic audit mandates. The FCPA and False Claims Act enforcement frameworks require multinational corporations to maintain investigative readiness that only specialized forensic accounting providers can deliver. Stakeholders must monitor how AI-powered document review tools reshape the labor intensity—and pricing power—of traditional forensic engagement models.
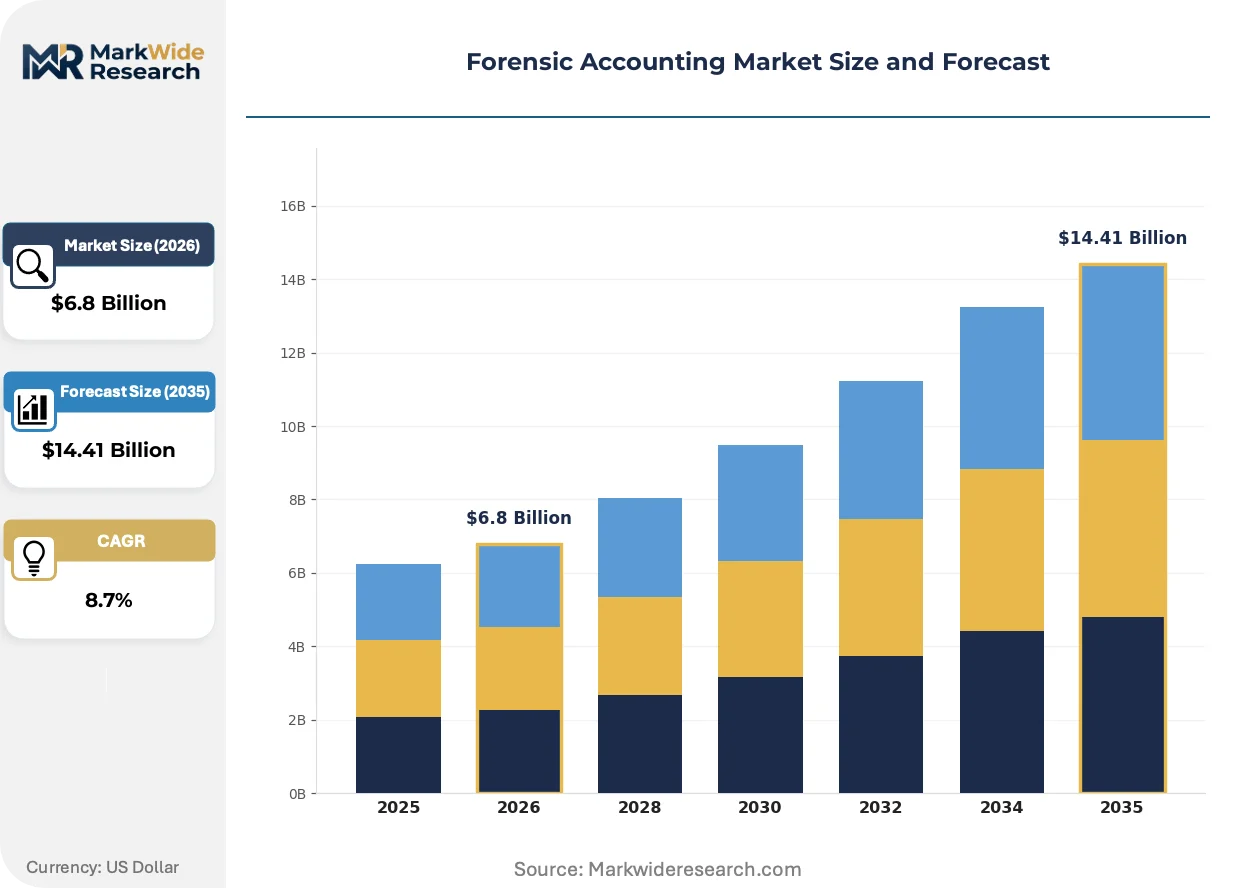
Market Dynamics
SEC whistleblower program expansions and PCAOB audit inspection reforms are forcing corporate legal departments to maintain standing forensic capabilities rather than episodic engagements, compressing procurement cycles and elevating provider technical standards.
Growth Catalysts
- SEC Enforcement Intensification:Whistleblower award expansion drives mandatory forensic audit mandates at publicly traded corporations, creating recurring revenue streams for specialized providers.
- Healthcare Fraud Surge:Medicare and Medicaid billing investigations generate sustained demand from federal and state agencies, decoupling forensic accounting from traditional banking-centric engagement patterns.
- AI-Powered Document Review:Machine learning classification tools reduce investigation timelines from months to weeks, enabling providers to handle higher case volumes without proportional staff expansion.
Market Restraints
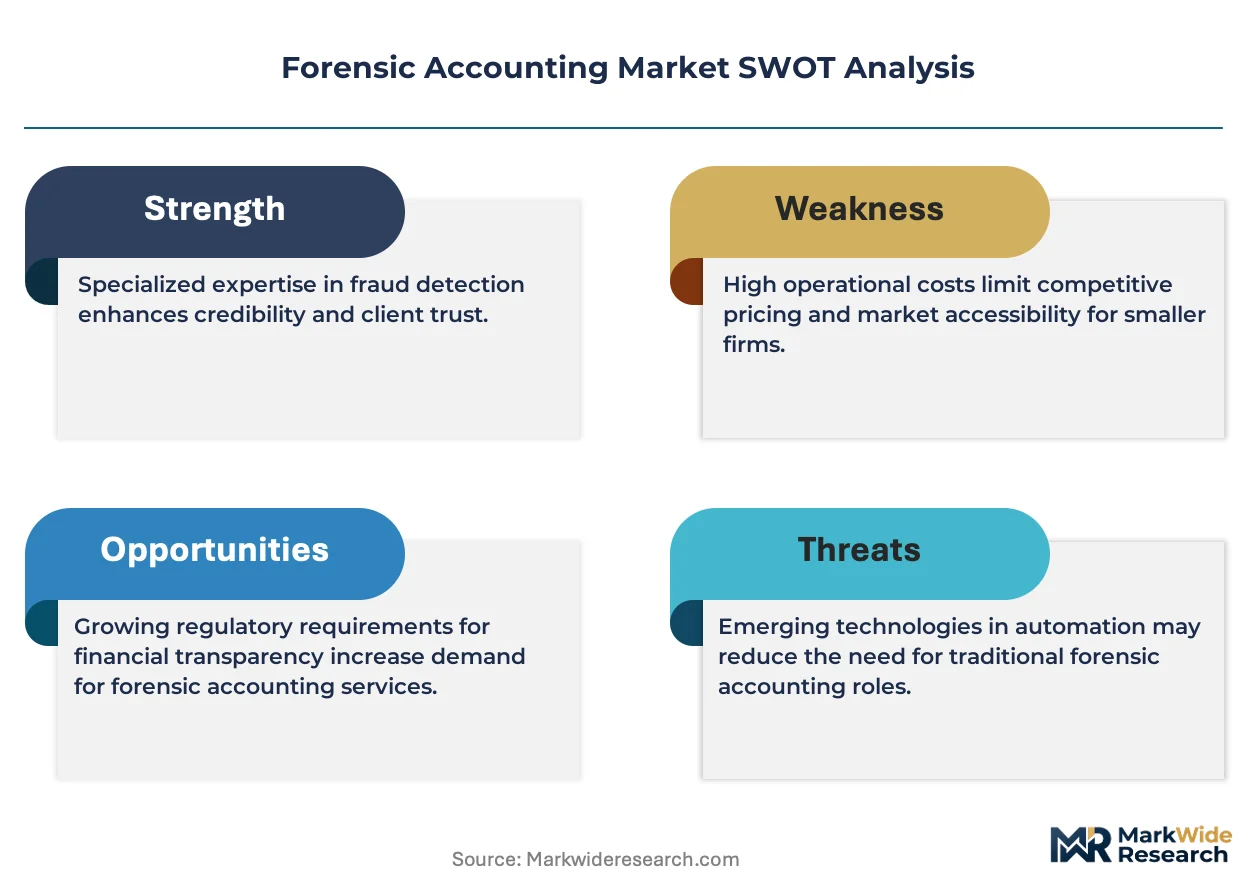
- Specialized Talent Scarcity:CPA-licensed investigators with dual litigation support and data analytics expertise command premium compensation, compressing margin structures for mid-tier providers.
- Evidence Admissibility Risk:Daubert standard challenges in federal court create liability exposure when automated analytical methods face judicial scrutiny.
- Client Concentration:Am Law 100 firms intermediate the majority of high-value engagements, concentrating pricing power among a narrow buyer base.
Strategic Opportunities
- Mid-Market Corporate Underpenetration:Private companies below $500 million revenue lack standing forensic capabilities, representing an underserved segment for subscription-based investigation readiness programs.
- Cyber-Forensic Convergence:Ransomware incident response and cryptocurrency tracing create demand for investigators with blockchain analytics and dark web intelligence competencies.
- False Claims Act Expansion:DOJ healthcare fraud settlements exceeding $2 billion annually sustain qui tam investigation demand from relator law firms and defendant corporations.
Industry Challenges
- Cross-Border Data Sovereignty:GDPR and China's PIPL impose conflicting jurisdictional requirements on multinational investigations, fragmenting evidence collection protocols.
- Judicial Technology Literacy Gap:Federal judges demonstrate inconsistent acceptance of algorithmic damage calculation models, creating outcome uncertainty in high-stakes litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forensic Accounting Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fraud Investigation, Financial Litigation, Forensic Audit, Expert Witness Client Type: Corporations, Law Firms, Government Agencies, Non-Profits Industry Vertical: Insurance, Banking, Real Estate, Healthcare Engagement Model: Retainer, Project-Based, Hourly Rate, Contingency Fee |
| Companies Covered | KPMG, MDD Forensic Accountants, PwC, PKF International, BDO, Deloitte, Grant Thornton, Kessler International, Ernst & Young, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forensic Accounting Market Emerging Trajectories
Forensic accounting is transitioning from labor-intensive document review to algorithmic pattern detection, with provider differentiation increasingly anchored in proprietary data infrastructure and vertical-specific investigative protocols.
Continuous monitoring analytics is overtaking periodic forensic audits as the preferred corporate control mechanism. These systems ingest ERP and communication data in real-time, flagging anomalous transactions before they compound into material fraud. Fortune 500 legal departments deploy such platforms to satisfy board-level governance expectations and reduce reactive investigation costs. The technology is compressing the traditional forensic engagement model from project-based discovery to embedded risk surveillance.
The SEC's climate disclosure rules and PCAOB's enhanced auditor scrutiny of internal controls over sustainability reporting are mandating forensic-grade verification of ESG claims. Corporations must now subject carbon offset purchases and supply chain emissions data to the same evidentiary standards as financial statements. This regulatory expansion is pulling environmental consultants and traditional forensic accountants into direct competition for attestation engagements.
General counsel offices are unbundling forensic services from full-service law firm retainers, establishing direct relationships with specialized accounting providers. This disintermediation reflects cost transparency demands and the desire for in-house control over investigation scope and timing. The shift is most pronounced in the technology and healthcare sectors, where frequent regulatory interaction has normalized standing forensic vendor panels outside traditional legal procurement channels.
Forensic Accounting Market Segmentation
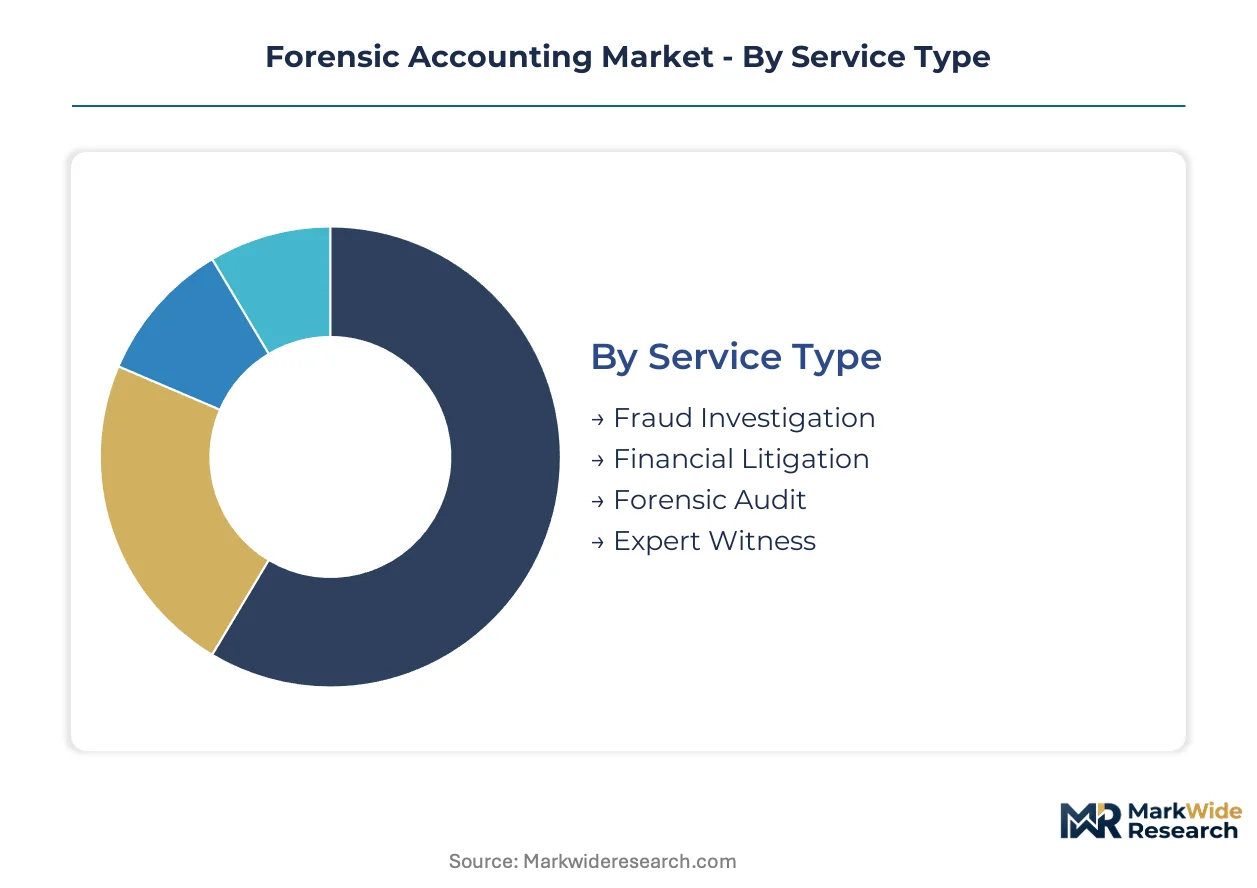
Forensic accounting providers structure their service portfolios around distinct risk profiles and procurement patterns. Segmentation reveals how regulatory intensity, litigation volume, and organizational scale reshape demand concentration across service categories.
Service Type:
Fraud investigation commands the highest volume, while expert witness engagements capture premium pricing through court-admissible testimony requirements.
- Fraud Investigation:Encompasses asset misappropriation, financial statement fraud, and corruption detection using transaction tracing and digital forensics. Corporations in the United States drive sustained demand as SEC whistleblower filings mandate independent forensic audits. Specialized CPA-licensed investigators with dual data analytics expertise command premium compensation.
- Financial Litigation:Quantifies economic damages in securities fraud, breach of contract, and intellectual property disputes through financial modeling and loss calculation. Law firms in high-stakes litigation concentrate procurement here, with Daubert standard challenges creating liability exposure for automated analytical methods.
- Forensic Audit:Reconstructs financial records for regulatory compliance and internal control assessment. Banking regulators require these capabilities for PCAOB inspection remediation.
- Expert Witness:Provides court testimony on accounting standards, valuation methodologies, and industry practices. Judicial technology literacy gaps create outcome uncertainty in federal proceedings.
Mature deployment sits with fraud investigation. Newer deployment is concentrated in expert witness services as algorithmic damage models face expanding judicial scrutiny.
Client Type:
Procurement authority separates standing forensic capabilities from episodic engagements, with intermediaries capturing margin concentration.
- Law Firms:Am Law 100 firms intermediate the majority of high-value engagements, concentrating pricing power through litigation funding control. General counsel offices increasingly unbundle forensic services from full-service retainers.
- Corporations:Fortune 500 legal departments deploy continuous monitoring analytics to satisfy board-level governance expectations. Mid-market companies below $500 million revenue lack standing capabilities.
- Government Agencies:DOJ healthcare fraud settlements exceeding $2 billion annually sustain qui tam investigation demand from federal and state enforcement divisions.
- Non-Profits:Grant compliance and donor stewardship requirements generate specialized attestation needs.
Law firms anchor premium-margin procurement. Corporations are expanding fastest as subscription-based investigation readiness programs penetrate mid-market accounts.
Industry Vertical:
Healthcare decouples from banking-centric patterns as Medicare billing investigations intensify regulatory scrutiny.
- Healthcare:Medicare and Medicaid billing investigations generate sustained demand from federal agencies and qui tam relators. False Claims Act enforcement requires specialized investigative readiness.
- Insurance:Healthcare fraud investigations and claims verification reshape traditional engagement patterns. Multidisciplinary fraud investigation platforms span property-casualty and life insurance verticals.
- Banking:Securities litigation and internal fraud investigations drive corporate legal department budget expansion. PCAOB audit inspection reforms mandate specialized financial investigation capabilities.
- Real Estate:Valuation disputes and construction cost overruns require asset tracing and damage quantification expertise.
Banking retains mature forensic infrastructure. Healthcare is climbing fastest as billing complexity and enforcement intensity reshape provider specialization.
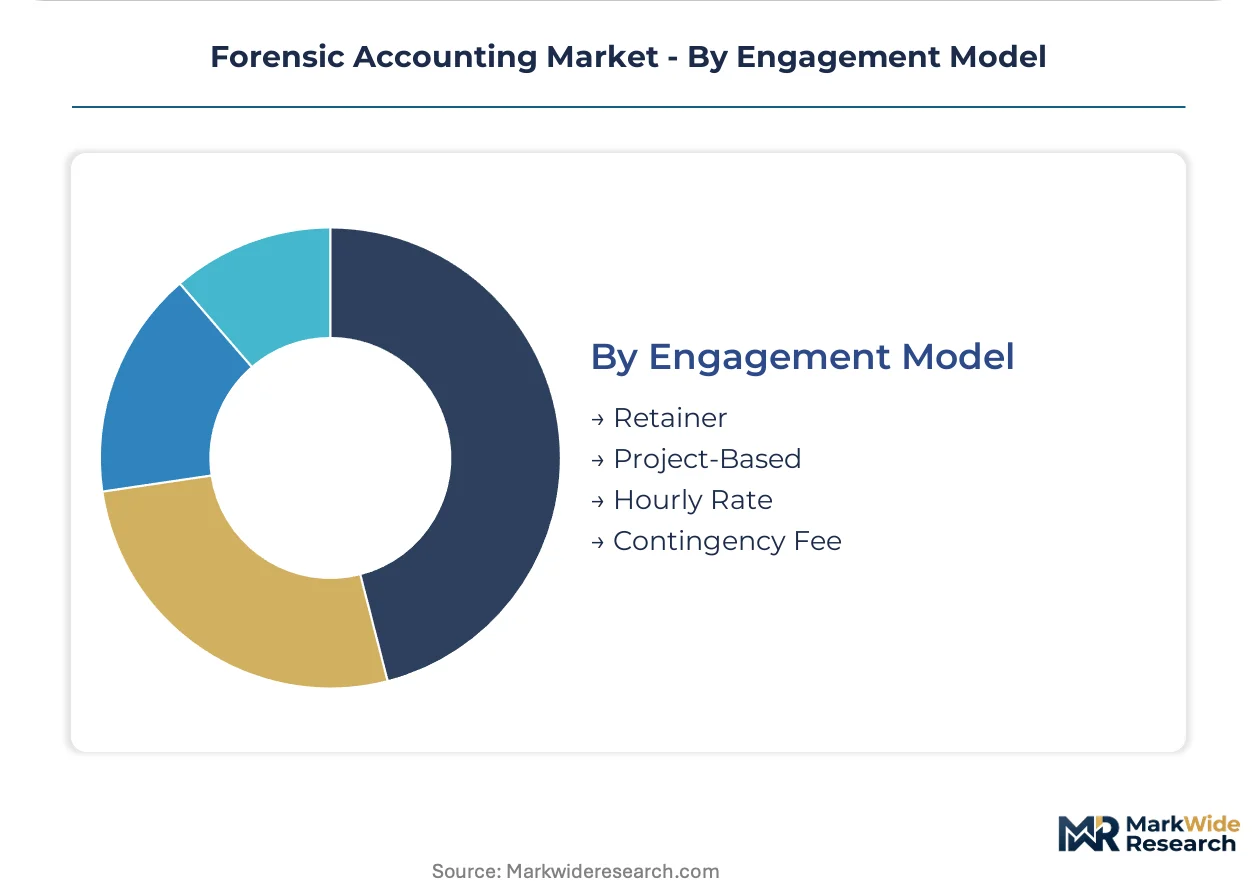
Engagement Model:
Outcome specificity is displacing time-based billing as corporations demand cost transparency and scope control.
- Project-Based:Outcome-specific procurement captures expanding share as corporations shift from fixed retainers. Technology and healthcare sectors normalize standing vendor panels outside traditional legal channels.
- Retainer:Standing forensic capabilities satisfy SEC whistleblower program mandates and board governance expectations. Compression of procurement cycles elevates provider technical standards.
- Hourly Rate:Time-based billing persists in complex investigations with undefined scope boundaries.
- Contingency Fee:Aligns provider compensation with recovery outcomes in asset tracing and fraud recovery engagements.
Retainer structures dominate enterprise accounts. Project-based contracting is gaining share fastest as procurement functions assert direct vendor relationship control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cayman Islands Special Economic Zone attracts forensic accounting firms serving cross-border litigation funds, creating jurisdictional clustering for asset tracing operations. Tax transparency initiatives in Luxembourg and Singapore generate parallel demand centers for financial investigation services.
United States
Securities litigation volume and SEC whistleblower program expansions drive sustained demand for forensic audit capabilities. The PCAOB mandates specialized financial investigation competencies for auditor inspection remediation. New York and Washington DC legal markets concentrate high-value expert witness engagements.
United Kingdom
Serious Fraud Office investigations and Financial Conduct Authority enforcement actions sustain corporate forensic mandates. The Economic Crime and Corporate Transparency Act imposes new verification requirements on company formations. London's legal district anchors European dispute resolution and asset recovery operations.
Germany
Wirecard scandal aftermath and BaFin regulatory reforms intensify internal control verification needs. The German Corporate Sanctions Act mandates compliance program effectiveness assessments. Frankfurt's financial center generates banking sector fraud investigation demand.
China
CSRC enforcement intensification and cross-border securities litigation reshape investigative readiness requirements. The Personal Information Protection Law fragments multinational evidence collection protocols. Shanghai and Beijing legal markets develop specialized forensic capabilities for state-owned enterprise restructuring.
India
SEBI insider trading investigations and Insolvency and Bankruptcy Code proceedings expand forensic audit mandates. The Prevention of Money Laundering Act compliance requirements sustain corporate due diligence spending. Mumbai and Delhi legal markets concentrate dispute resolution and valuation expertise.
Forensic Accounting Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service professional networks capturing enterprise accounts while boutique firms dominate high-stakes litigation support. The market structure concentrates around four global networks and a fragmented tier of specialized practitioners. Strategic archetypes include multidisciplinary audit platforms, litigation-focused boutiques, and technology-enhanced analytics providers. Competitive moves center on vertical specialization in healthcare and insurance fraud, plus AI-powered document review capability acquisition.
Among the Big Four networks, KPMG and PwC exemplify divergent positioning strategies within forensic accounting. KPMG represents the multidisciplinary platform archetype, spanning insurance and healthcare verticals through integrated fraud investigation capabilities. PwC anchors the regulatory response specialization, particularly around SEC enforcement and PCAOB inspection remediation. Ernst & Young occupies a technology-enhanced position, differentiating through audit analytics that accelerate fraud detection timelines. These three firms collectively illustrate how scale, specialization, and technology investment define competitive positioning in this services market.
| Leading Market Players |
|---|
| KPMG |
| MDD Forensic Accountants |
| PwC |
| PKF International |
| BDO |
| Deloitte |
| Grant Thornton |
| Kessler International |
| Ernst & Young |
| Others |
Supply Flow & Price Mechanics
CPA-licensed investigators with dual litigation support and data analytics expertise in the United States command premium compensation that compresses margin structures for mid-tier providers, creating labor-cost differentials that stratify pricing across premium forensic practices and standard audit-adjacent offerings.
Pricing Analysis
Expedited engagement timelines carry material premiums, with corporations paying substantial markups for forensic teams mobilized within 48-72 hours versus standard procurement cycles. Project-based outcome-specific contracting now dominates over fixed retainers, with price differentiation anchored in certification grade (CPA-licensed investigators versus non-licensed analysts) and vertical specialization depth. Pricing pressure stems from AI-powered document review tools compressing investigation timelines and enabling higher case volumes without proportional staff expansion. Mid-market corporations below $500 million revenue exhibit highest price sensitivity, while Am Law 100 firms demonstrate lowest sensitivity given litigation funding control.
Supply Chain Analysis
Professional qualification requirements—CPA licensure, CFE certification, and court-admissible testimony credentials—gate entry and concentrate supply among established professional networks in the United States, United Kingdom, and Germany. Talent pipelines draw from Big Four audit alumni, federal enforcement veterans, and specialized graduate programs in forensic accounting and fraud examination. Supply chain risk centers on specialized talent scarcity as demand outstrips qualified investigator availability. Distribution runs through direct corporate procurement channels and law firm intermediation, with standing vendor panels displacing episodic engagements in technology and healthcare sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forensic accounting operates as a supply-constrained market where CPA-licensed investigators with dual data analytics expertise represent the binding capacity bottleneck, sustaining pricing power for qualified providers despite technology-driven efficiency gains.
For Market Incumbents: Deploy continuous monitoring analytics platforms to embed forensic capabilities within client ERP systems, converting project-based discovery into recurring subscription revenue. Acquire boutique healthcare fraud specialists to capture False Claims Act investigation demand. Counter AI-powered document review commoditization by developing proprietary vertical-specific investigative protocols that resist automation.
For New Entrants and Emerging Players: Begin with mid-market corporate accounts below $500 million revenue, where standing forensic capabilities remain underpenetrated and procurement functions seek cost transparency outside traditional law firm channels. Target subscription-based investigation readiness programs in technology and healthcare verticals. Establish direct relationships with general counsel offices that have unbundled forensic services from full-service retainers.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-enhanced analytics providers given AI-powered document review capability acquisition demand. Long-term viability favors firms with embedded continuous monitoring platforms and healthcare vertical specialization. Watch SEC whistleblower program expansion rates as inflection indicator for mandatory forensic audit mandate volume.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Document Review Acquisition | Machine learning classification tools compress investigation timelines from months to weeks without proportional staff expansion. |
| Healthcare Vertical Specialization | Medicare and Medicaid billing investigations generate sustained demand decoupled from traditional banking-centric patterns. |
| Continuous Monitoring Platform Deployment | Real-time ERP data ingestion converts project-based discovery into embedded risk surveillance subscriptions. |
| Mid-Market Subscription Program Launch | Private companies below $500 million revenue lack standing forensic capabilities and seek cost-transparent procurement. |
| Cyber-Forensic Capability Integration | Ransomware incident response and cryptocurrency tracing demand blockchain analytics and dark web intelligence competencies. |
Methodological Framework
Multi-period observation of SEC whistleblower filing volumes, PCAOB inspection remediation mandates, and healthcare fraud settlement trends anchored the trend analysis, supplemented by interviews with forensic practice leaders at Big Four networks, general counsel at Fortune 500 corporations, Am Law 100 litigation partners, federal enforcement officials, and healthcare compliance officers. Secondary validation incorporated SEC enforcement action databases, DOJ False Claims Act settlement records, PCAOB inspection reports, and professional certification body membership data. Bottom-up service line revenue estimation triangulated against top-down market sizing across the analysis window.
Segment-weighting applied differential growth assumptions across service types, client categories, industry verticals, and engagement models. The analytical framework modeled fraud investigation, financial litigation, forensic audit, and expert witness services separately, with cross-segment interaction effects captured through correlation matrices. CAGRs derived from regression analysis against enforcement intensity indices, litigation volume trends, and regulatory mandate expansion rates. Healthcare fraud investigation demand and AI adoption curves served as primary forecast sensitivity inputs.
Regulatory enforcement priority shifts, judicial acceptance of algorithmic damage models, and cross-border data sovereignty rulings are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding sustained SEC whistleblower program expansion and PCAOB audit inspection reform implementation. A model refresh is warranted upon material change in federal healthcare fraud settlement volumes or judicial precedent on automated analytical method admissibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Global Auditing Services Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
UAE Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
Trust Accounting Software Market