
 Bookkeeper Software Market | 2026-2036
Bookkeeper Software Market Size, Share, and Industry Trends Forecast 2026-2036
Bookkeeper Software Market Outlook
North American SaaS infrastructure is restructuring how bookkeeping platforms deliver real-time financial automation to distributed workforces. Intuit leverages its tax-software heritage to anchor small-business workflows across the United States and Canada. Xero competes aggressively on API openness, sustaining developer ecosystems that extend its core ledger into vertical applications. Sage dominates European mid-market penetration, operating localized compliance engines for VAT and Making Tax Digital obligations.
Bookkeeper software comprises cloud-native and on-premise applications that automate double-entry accounting, bank reconciliation, and statutory reporting through standardized data formats such as XBRL or OFX. These systems serve commercial enterprises by reducing manual ledger maintenance and ensuring audit-ready financial records. Cloud-based deployment leads absolute growth as subscription economics displace perpetual licenses, while hybrid architectures persist among enterprises with legacy ERP investments. The freelancer segment within target audience categories represents the fastest-expanding addressable pool, though medium enterprises generate the deepest margin concentration due to multi-entity consolidation needs.
FDA oversight applies indirectly where bookkeeping software intersects with clinical-trial financial management, while SEC rules mandate audit-trail integrity for publicly traded clients using these platforms. GDPR and the EU AI Act impose data-residency and algorithmic-transparency requirements on vendors serving European accountants. Stakeholders must monitor how ISO 27001 certification evolves from competitive differentiator to table stakes as cyber-insurance underwriters tighten coverage terms for financial-technology providers.
Market Dynamics
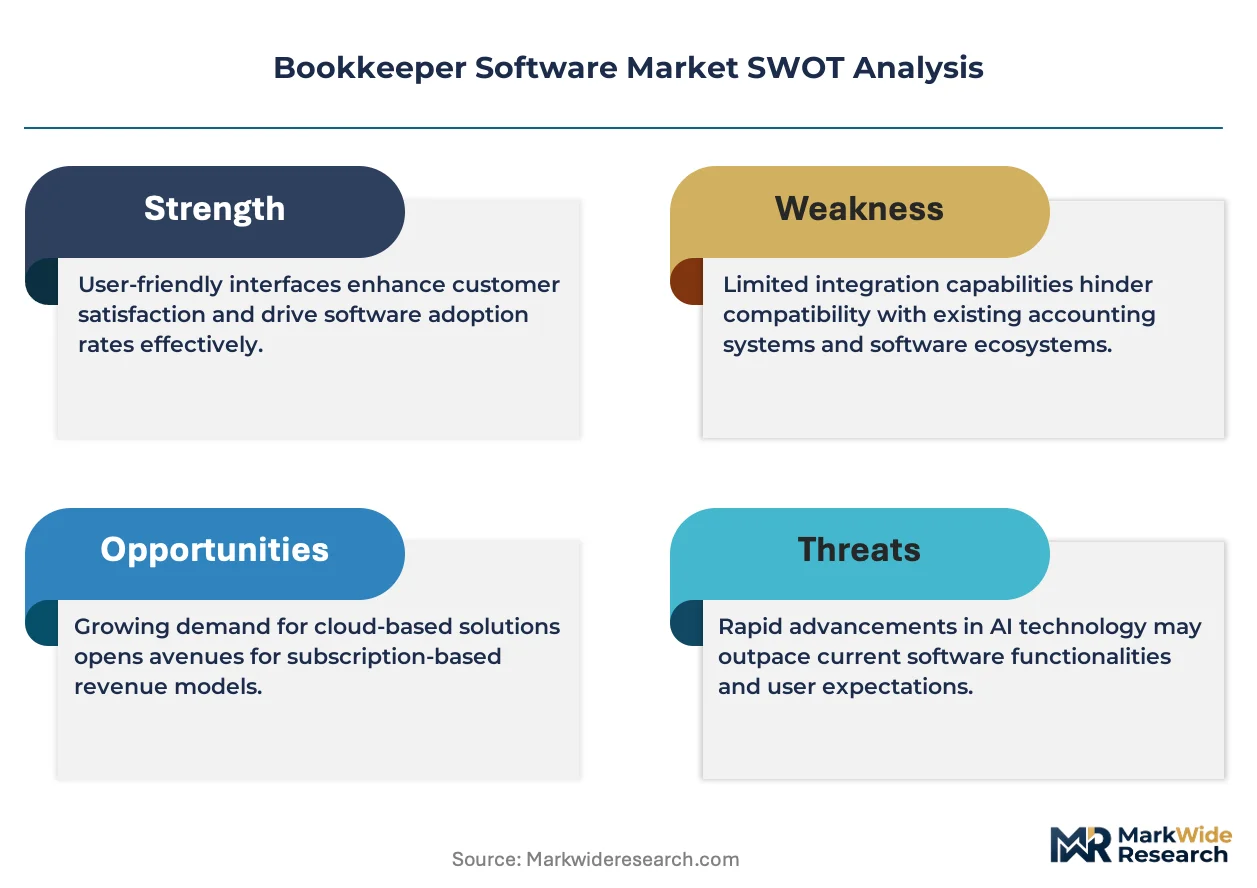
Cloud migration is compressing deployment timelines for bookkeeping platforms as small businesses abandon perpetual-license desktop suites. This infrastructure shift is restructuring vendor economics and forcing compliance architecture redesigns across multiple jurisdictions.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European accountants now require audit-ready AI decision logs, creating certified-software demand that vendors are racing to satisfy with explainable automation modules.
- API-first ecosystem expansion:Developer communities are embedding ledger functions into vertical SaaS stacks for construction and healthcare, extending addressable use cases beyond traditional accounting departments.
- Freelancer segment concentration:Solo practitioners and gig-economy workers in the United States and United Kingdom are adopting lightweight cloud subscriptions at rates outpacing mid-market consolidation.
Market Restraints
- GDPR data-residency compliance costs:Vendors must maintain sovereign cloud instances for European clients, fragmenting infrastructure investment and constraining margin expansion.
- Legacy ERP integration complexity:Hybrid deployments bridging on-premise Oracle and SAP systems with cloud-native tools create implementation friction that elongates sales cycles.
- Cyber-insurance underwriting tightening:ISO 27001 certification has shifted from competitive advantage to coverage prerequisite, raising operational barriers for smaller software providers.
Strategic Opportunities
- India PLI scheme for financial technology:Production-linked incentives for software exports are attracting bookkeeping vendors to establish development centers and localized compliance engines.
- Real-time payment convergence:Open banking APIs and instant settlement rails are enabling embedded finance features that transform bookkeeping platforms into working-capital management hubs.
- CSRD sustainability reporting integration:European corporate sustainability disclosure requirements are creating demand for carbon-accounting modules that interface directly with general ledgers.
Industry Challenges
- XBRL taxonomy expertise scarcity:Filing-ready statutory reports require specialized knowledge that accounting firms struggle to staff, creating implementation bottlenecks for automated reporting features.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of SOC 2, ISO 27001, and regional data-protection seals extends product launch windows by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bookkeeper Software Market |
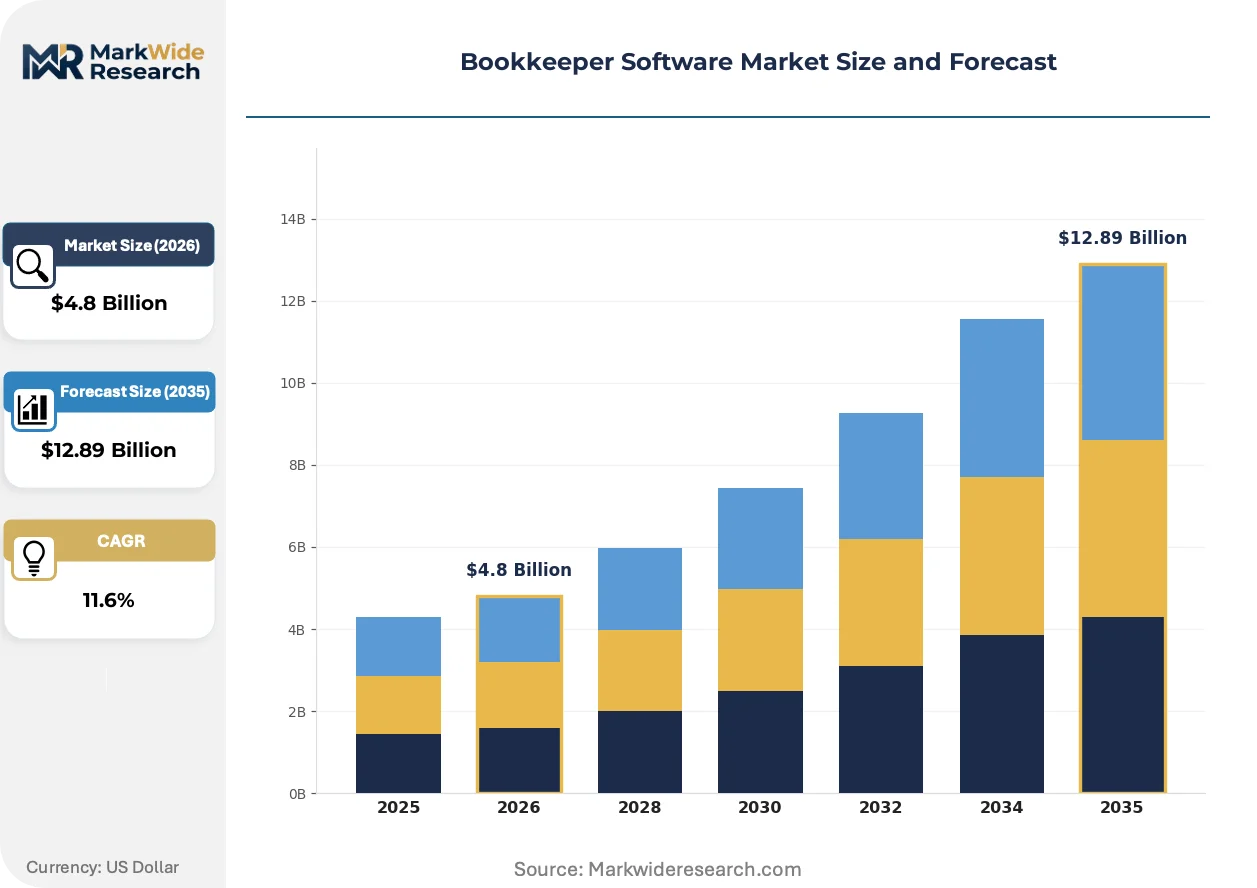
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based Target Audience: Small Businesses, Freelancers, Medium Enterprises, Accountants Feature Set: Invoicing, Expense Tracking, Reporting, Tax Calculation Pricing Model: Subscription, One-Time Purchase, Freemium, Tiered Pricing |
| Companies Covered | Intuit, Xero, Sage, Oracle, Zoho Books, FreshBooks, Wave, Microsoft, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bookkeeper Software Market Strategic Shifts
Automation architecture is fragmenting across bookkeeping platforms as vendors compete on workflow depth rather than feature breadth. Three developments are restructuring how financial data flows between enterprises, regulators, and capital providers.
Blockchain-anchored audit trails are decentralizing transaction verification for publicly traded clients. SEC-mandated record-integrity requirements are driving adoption among US-listed companies that must demonstrate tamper-evident financial histories. This shift is compressing reliance on centralized ledger databases while elevating cryptographic proof standards for quarterly filings.
REACH chemical-substance disclosure rules are indirectly pressuring bookkeeping software used by EU manufacturing clients. Industrial firms must trace supply-chain chemical costs through their general ledgers, forcing vendors to enhance cost-center granularity and substance-tracking modules. German automotive suppliers and French chemical processors are demanding these capabilities as a procurement prerequisite.
Subscription unbundling is fragmenting buyer commitment patterns across mid-market accounting firms. Firms are rejecting all-in-one suites in favor of modular API connections that let them swap reconciliation engines or tax modules without platform migration. This behavior is most visible in Australia and Canada, where Xero's open architecture has conditioned buyers to expect composable financial stacks.
Bookkeeper Software Market Segmentation
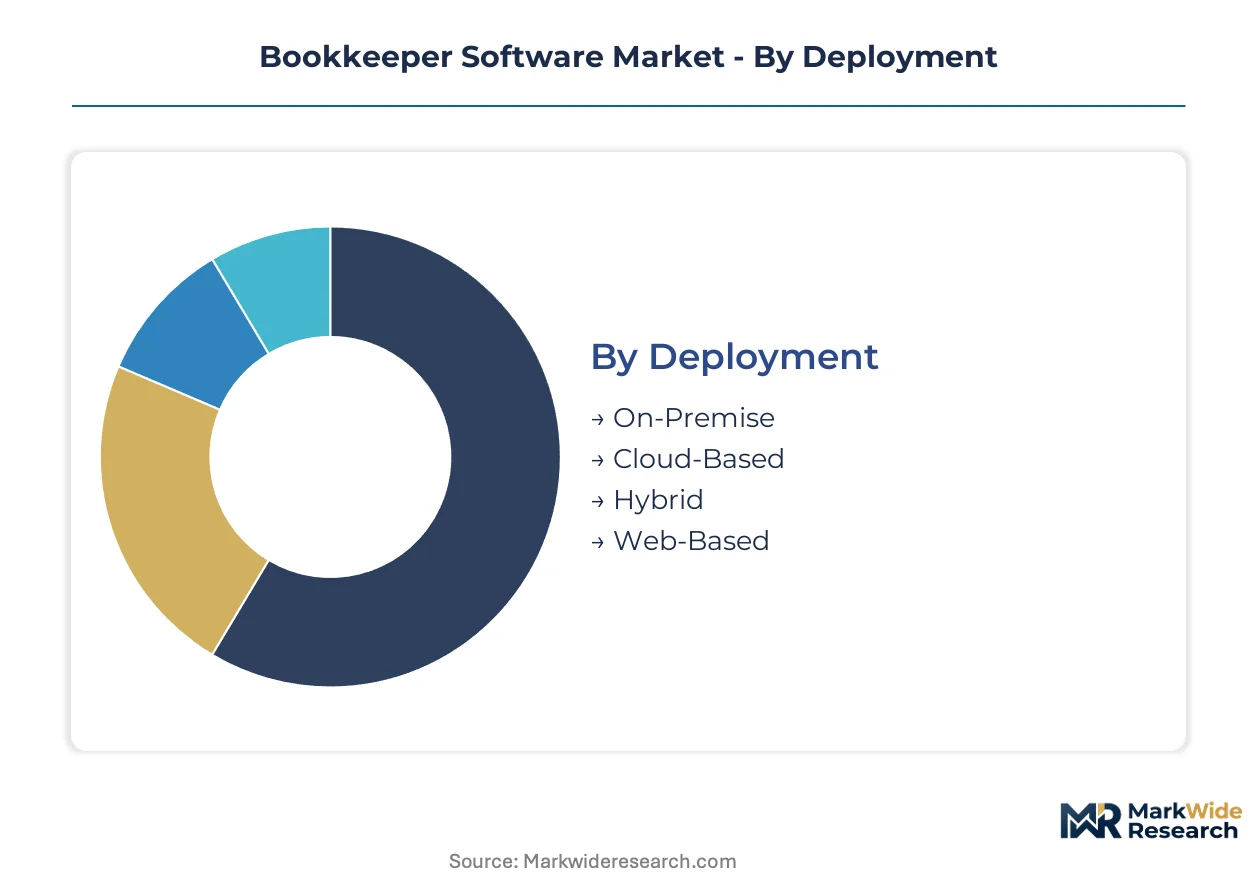
Bookkeeper software segmentation reveals how deployment infrastructure, user sophistication, and commercial models intersect to determine vendor strategy. Understanding these divides clarifies where cloud-native architectures displace legacy systems and which customer profiles justify premium feature development.
Deployment:
Upgrade cycles vary dramatically by infrastructure type, with cloud migrations compressing replacement timelines from years to months while hybrid deployments extend decision windows through ERP integration complexity.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling through AWS, Azure, or Google Cloud infrastructure. Demand concentrates among United States small businesses seeking real-time collaboration and reduced IT overhead, driven by SEC audit-trail requirements for publicly traded clients that favor centralized data governance.
- Hybrid:Split architectures maintain sensitive ledger data on-premise while routing non-critical workflows to cloud instances. German automotive suppliers and French chemical processors favor this model to satisfy GDPR data-residency mandates without sacrificing API connectivity, constrained by the complexity of bridging Oracle or SAP systems with modern reconciliation engines.
- On-Premise:Perpetual-license software installed on local servers persists among Japanese manufacturing conglomerates with legacy compliance investments.
- Web-Based:Browser-accessible single-tenant solutions serve Canadian rural accounting practices with intermittent connectivity.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as enterprises navigate regulatory fragmentation.
Target Audience:
Customer type determines pricing tolerance and feature depth, with solo practitioners demanding simplicity while multi-entity operations require consolidation engines that justify substantial subscription premiums.
- Freelancers:Solo practitioners and gig-economy workers prioritize mobile-first interfaces and automated bank feeds over advanced reporting. United Kingdom and United States independent contractors are expanding most quickly, attracted by lightweight subscriptions that displace spreadsheet-based bookkeeping.
- Medium Enterprises:Multi-entity organizations require intercompany eliminations, consolidated dashboards, and role-based access controls. Demand clusters among Australian professional services firms and Canadian construction companies, driven by CSRD sustainability reporting obligations that mandate carbon-accounting integration with general ledgers.
- Small Businesses:Owner-operated entities with 10-50 employees seek invoice automation and payroll connectivity.
- Accountants:Client-serving practices need white-label capabilities and bulk data import tools for practice management.
Medium Enterprises capture the deepest margin concentration, with Freelancers gaining share fastest.
Feature Set:
Functional specialization separates commodity offerings from platforms that anchor financial workflows, with automation depth becoming the primary competitive battleground.
- Tax Calculation:Jurisdiction-aware engines automate VAT, GST, and income tax computations with audit-ready documentation. United States mid-market firms and European Making Tax Digital participants drive demand, constrained by XBRL taxonomy expertise scarcity that creates implementation bottlenecks for automated filing features.
- Reporting:Customizable dashboards and statutory report generators transform raw ledger data into decision-ready insights. Indian software exporters and Brazilian agricultural cooperatives are expanding most quickly, attracted by RBI and SEBI compliance requirements that mandate structured financial disclosures.
- Invoicing:Automated bill generation with payment gateway integration accelerates cash conversion cycles.
- Expense Tracking:Receipt capture and categorization through OCR and mobile apps reduces manual data entry.
Tax Calculation commands premium pricing, with Reporting showing the steepest expansion trajectory.
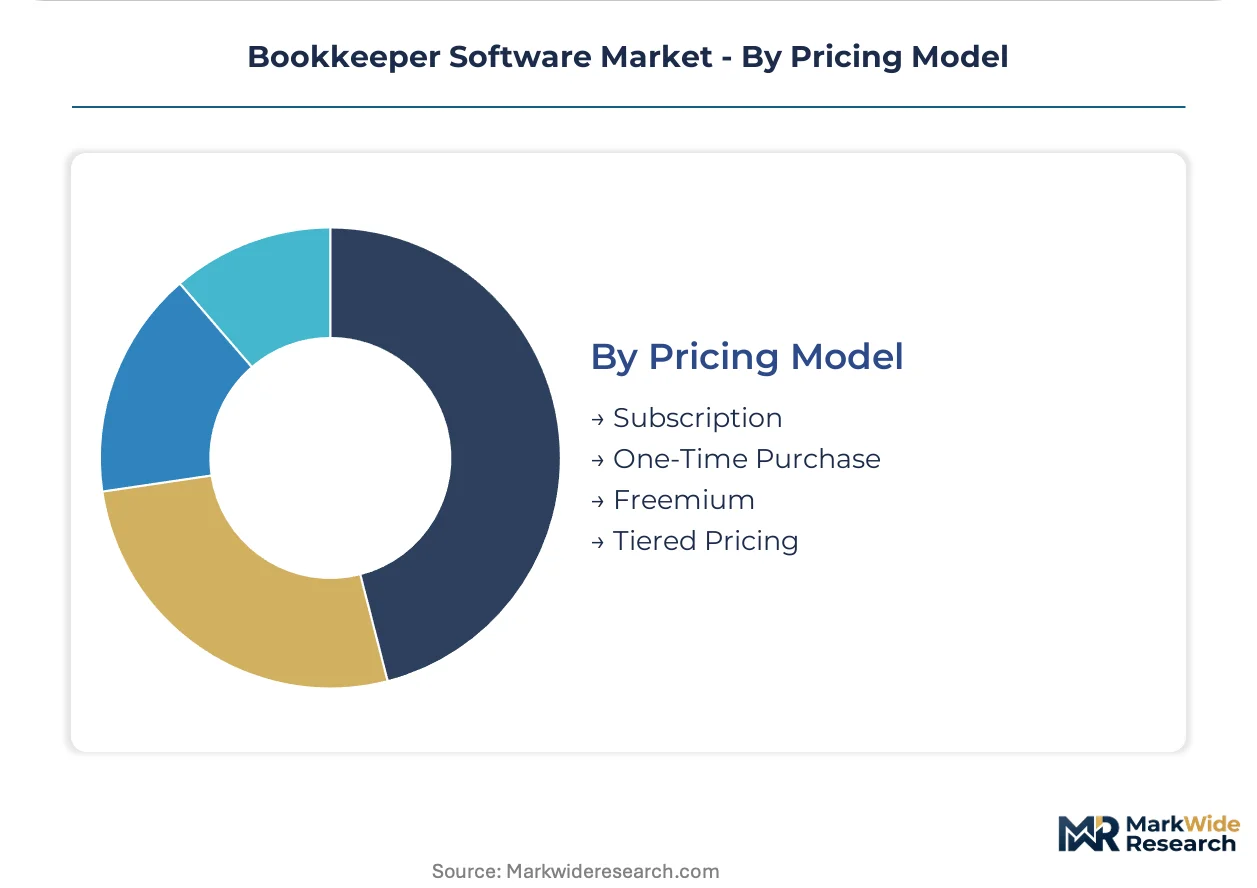
Pricing Model:
Revenue architecture shapes customer lifetime value and churn exposure, with subscription economics displacing perpetual licenses while freemium tiers create conversion funnels.
- Subscription:Recurring monthly or annual payments bundle software access with continuous updates and support. United States venture-backed fintech integrations and United Kingdom open banking deployments concentrate demand, driven by real-time payment convergence that transforms bookkeeping platforms into working-capital management hubs.
- Freemium:Zero-cost entry tiers with feature-gated upgrades convert solo practitioners to paid plans. Indian PLI scheme beneficiaries and Australian Xero-conditioned buyers are climbing fastest, attracted by API-first ecosystems that enable modular stack composition without upfront commitment.
- One-Time Purchase:Perpetual licenses with optional maintenance contracts persist among legacy-dependent Japanese enterprises.
- Tiered Pricing:Feature-stratified plans segment customers by user count, transaction volume, or module access.
Subscription dominates revenue contribution, with Freemium converting most efficiently among new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States venture-backed fintech integration outpaces United Kingdom open banking adoption in premium feature penetration, while German mid-market consolidation and Indian software export incentives reshape vendor investment priorities across distinct regulatory environments.
United States
Mid-market accounting firms in California and New York Metro drive premium subscription uptake through real-time payment convergence and embedded finance integration. SEC audit-trail mandates for publicly traded clients elevate cryptographic proof standards and blockchain-anchored verification modules. Austin and Boston SaaS clusters concentrate developer talent for API-first ecosystem expansion into vertical applications.
United Kingdom
Freelancer segment expansion in London and Manchester accelerates lightweight cloud adoption as Making Tax Digital obligations automate VAT compliance workflows. GDPR data-residency requirements force sovereign cloud infrastructure investments that fragment vendor margin structures. Edinburgh and Bristol fintech corridors host specialized compliance engine development for EU market access.
Germany
Automotive suppliers in Bavaria and chemical processors in North Rhine-Westphalia demand hybrid deployment architectures bridging Oracle ERP systems with cloud-native reconciliation tools. REACH chemical-substance disclosure rules mandate enhanced cost-center granularity for supply-chain traceability. Frankfurt financial services cluster anchors mid-market penetration for localized VAT and sustainability reporting modules.
India
Software export beneficiaries in Karnataka and Maharashtra leverage PLI scheme incentives to establish development centers and localized compliance engines for RBI and SEBI disclosure mandates. Tier-2 accounting practices in Gujarat and Tamil Nadu convert rapidly from spreadsheet-based systems to freemium cloud subscriptions. Hyderabad and Chennai technology parks concentrate API development talent for modular financial stack composition.
Australia
Professional services firms in New South Wales and construction companies in Victoria drive medium enterprise consolidation through CSRD-aligned sustainability reporting integration with general ledgers. Xero-conditioned buyers in Sydney and Melbourne reject all-in-one suites for modular API connections that enable component swapping without platform migration. Brisbane emerging fintech cluster experiments with real-time payment rail embedding for working-capital management hubs.
Bookkeeper Software Market Competitive Environment
United States producers anchor one tier; United Kingdom and European specialists hold differentiated positions through regulatory compliance depth. The vendor base organizes around three strategic archetypes: tax-software heritage platforms leveraging workflow anchoring, API-first challengers sustaining developer ecosystems, and legacy ERP incumbents bridging hybrid architectures. Competitive moves concentrate on M&A for vertical capability acquisition and geographic expansion through localized compliance certification.
Within the heritage-platform tier, Intuit exemplifies tax-software lineage extension into small-business workflow anchoring across North America. Xero occupies a position as the archetypal API-first challenger, with its open architecture conditioning buyer expectations for composable financial stacks in Australia and Canada. Sage represents European mid-market specialization, with localized compliance engines for VAT and Making Tax Digital obligations serving as its competitive anchor. These three entities collectively illustrate how regulatory geography shapes sustainable differentiation in an increasingly modular market.
| Leading Market Players |
|---|
| Intuit |
| Xero |
| Sage |
| Oracle |
| Zoho Books |
| FreshBooks |
| Wave |
| Microsoft |
| Infor |
| Others |
Value Chain & Pricing Dynamics
Venture-backed SaaS consolidators and private-equity-rolled-up bookkeeping specialists anchor supply-side ownership patterns, compressing pricing discipline through subscription-economy scale while fragmenting infrastructure investment across GDPR-mandated sovereign cloud instances. This ownership concentration enables aggressive freemium-to-paid conversion tactics that reshape margin structures for smaller API-first challengers.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for mid-market cloud deployments as PLI scheme beneficiaries absorb development costs through export incentives. Subscription tiers stratify across premium compliance-engine bundles, standard multi-entity consolidation packages, and economy freelancer-grade mobile interfaces, with ISO 27001 certification grade serving as the primary differentiation driver alongside vertical integration depth in tax-calculation modules. Pricing pressure stems from cyber-insurance underwriting tightening that raises operational barriers for uncertified providers. Freelancers exhibit highest price sensitivity, while medium enterprises tolerate premium positioning for CSRD-aligned sustainability reporting integration.
Supply Chain Analysis
Reverse-logistics flows for on-premise license decommissioning and legacy ERP data migration services create secondary revenue streams for implementation partners as cloud migrations accelerate. Supply concentrates in the United States for fintech-integrated development, the United Kingdom for Making Tax Digital compliance engines, and India for PLI-supported export software production. Raw material dependencies center on AWS, Azure, and Google Cloud hyperscaler infrastructure, open banking API access, and cryptographic certificate authority services. Single-source vulnerability in hyperscaler concentration threatens continuity for multi-tenant architectures. Distribution runs through direct self-service portals for freelancers, value-added reseller networks for mid-market accounting firms, and systems integrator partnerships for hybrid enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's PLI-subsidized development costs and Europe's premium compliance-engine pricing creates sustainable margin expansion opportunities for vendors with dual-hemisphere delivery capabilities.
For Market Incumbents: Hedge against API-first ecosystem fragmentation by acquiring vertical-specialist reconciliation engines in construction and healthcare, while accelerating ISO 27001 certification investment to preempt cyber-insurance coverage prerequisites that threaten smaller competitors. Defend position through backward integration into open banking infrastructure rather than relying on third-party payment rail access. For New Entrants and Emerging Players: Blockchain-anchored audit trail modules offer a technology-first wedge into SEC-regulated publicly traded client segments where cryptographic proof standards remain underdeveloped among heritage platforms. Target Australian professional services firms conditioned by Xero's open architecture to expect modular stack composition, penetrating through CSRD carbon-accounting integration gaps before incumbents complete product roadmaps. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists bridging Oracle ERP systems with cloud-native tools, as implementation friction elongates sales cycles and compresses near-term multiples. Long-term viability over the coming decade rests on regulatory certification breadth rather than feature depth, with acquisition priority flowing to vendors holding simultaneous SOC 2, ISO 27001, and GDPR seals. Monitor EU AI Act algorithmic transparency enforcement timelines as inflection indicator for explainable automation module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first ecosystems extend ledger functions into vertical SaaS stacks for construction and healthcare. |
| Acquisition of Specialist Firm | Vertical capability acquisition accelerates entry into CSRD-aligned sustainability reporting segments. |
| Geographic Expansion | Localized compliance certification for VAT and Making Tax Digital obligations unlocks European mid-market penetration. |
| Product Launch | Explainable automation modules satisfy EU AI Act algorithmic transparency mandates for audit-ready decision logs. |
| Strategic Partnership | Open banking API convergence transforms bookkeeping platforms into working-capital management hubs. |
Study Parameters
Multiple input streams — structured interviews with SaaS product executives, IT procurement officers at mid-market accounting firms, and platform integration specialists — were reconciled against SEC filings, hyperscaler capex disclosures, and open banking adoption statistics. Bottom-up triangulation across deployment model penetration rates and top-down validation through venture funding flow analysis anchored market sizing. Secondary sources included GDPR enforcement action databases, EU AI Act implementation guidance, and RBI software export licensing records.
Data-stream reconciliation across subscription revenue recognition patterns, freemium conversion funnel metrics, and certification timeline benchmarks structured the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed deployment infrastructure, organization size tier, vertical application, integration complexity with legacy ERP systems, and regional regulatory adoption pattern. CAGRs derived from elasticity-adjusted pricing trajectories and capacity expansion schedules, with particular weighting applied to cyber-insurance underwriting evolution and real-time payment rail deployment timelines.
The model holds under sustained cloud migration momentum and stable regulatory certification cost structures; deviation in hyperscaler pricing volatility or accelerated EU AI Act enforcement would shift vendor margin projections. Practitioners should monitor open banking API standardization progress and ISO 27001 certification backlog durations for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Europe Forensic Accounting Market