
 Tax Preparation Services Market | 2026-2036
Tax Preparation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Tax Preparation Services Market Analytics
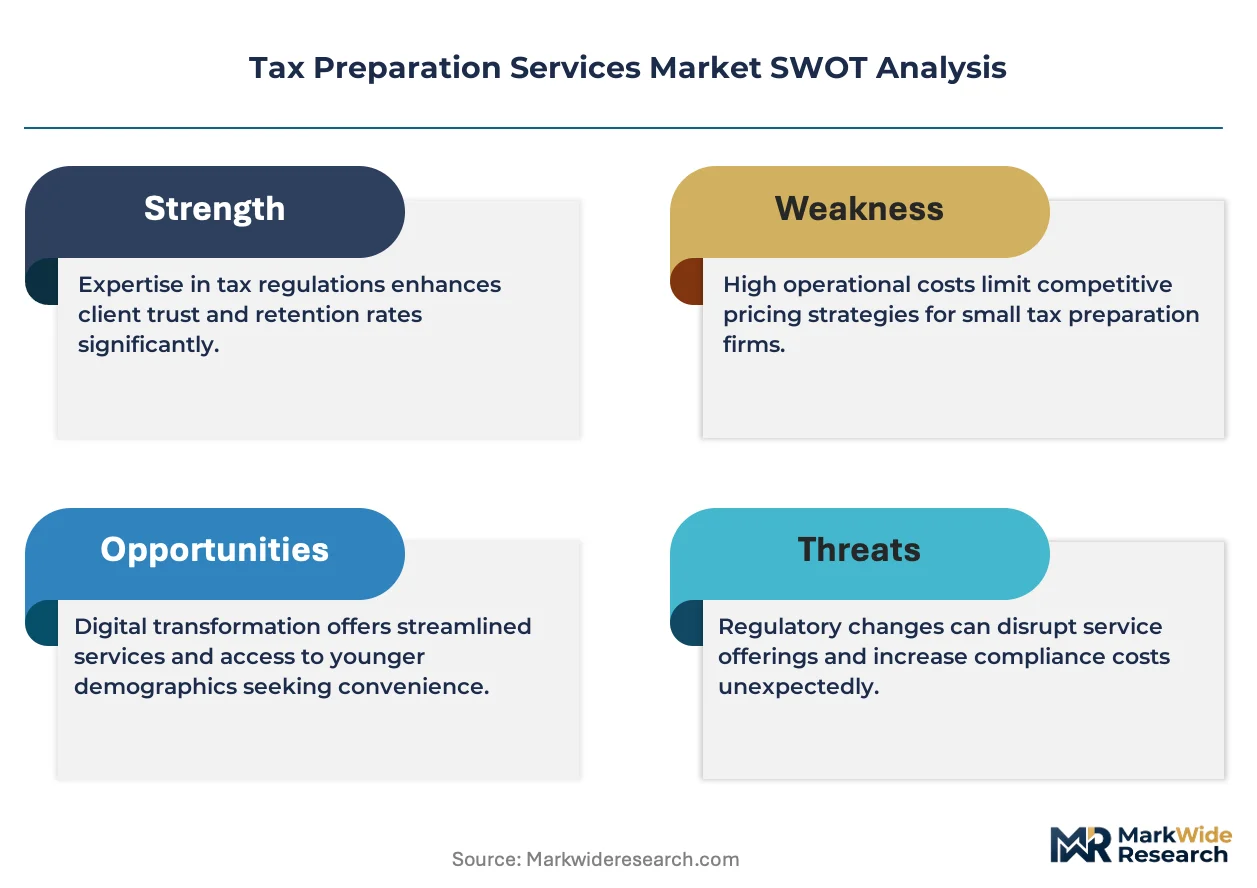
Small business buyer demand is consolidating around full-service advisory bundles rather than transactional compliance. PwC leverages its technology infrastructure to capture complex cross-border filings. EY sustains premium positioning through specialized industry tax practices. Baker Tilly competes aggressively in the middle-market segment where price sensitivity meets regulatory sophistication.
Tax preparation services encompass the compilation, calculation, and filing of federal, state, and local tax returns using specialized software platforms that integrate with accounting systems and government e-file protocols. These services reduce taxpayer liability exposure, ensure regulatory compliance, and optimize refund timing for individuals and entities. The individual service category remains the volume anchor, while business and corporate segments generate disproportionate margin pools due to complexity premiums. Online delivery mode is expanding fastest as encrypted document portals and video consultation tools replace traditional office visits, though hybrid models retain sticky high-net-worth relationships.
The IRS enforces electronic filing thresholds and preparer identification requirements that directly shape service provider certification and technology investment. State revenue departments layer additional compliance obligations that fragment operational requirements across jurisdictions. The SEC and PCAOB impose disclosure standards on publicly traded clients that cascade into preparer workload intensity. Stakeholders must monitor how real-time reporting pilots and AI-assisted audit selection reshape the value proposition of human preparer judgment.
Market Dynamics
The IRS's phased electronic filing mandates and real-time reporting pilots are compressing preparation timelines while forcing technology infrastructure upgrades across the service provider base.
Growth Catalysts
- Small Business Regulatory Complexity:Layered federal, state, and local obligations create sustained demand for professional navigation of multi-jurisdiction compliance requirements.
- E-filing Infrastructure Mandates:IRS thresholds for electronic submission are accelerating preparer certification and platform investment across the United States.
- Cross-Border Activity Expansion:Remote work arrangements and digital nomadism are proliferating multi-state and international filing scenarios requiring specialized expertise.
Market Restraints
- Certification Cost Burden:Preparer Tax Identification Number requirements and continuing education obligations impose fixed operational costs that disadvantage independent practitioners.
- Software Licensing Concentration:Dominant platform providers control encrypted document portal and e-file protocol integrations, creating vendor lock-in risk.
- DIY Substitution Threat:Consumer-grade tax software with AI-assisted guidance captures price-sensitive individual filers below complexity thresholds.
Strategic Opportunities
- Middle-Market Advisory Bundling:Small business owners seek integrated compliance, planning, and entity structuring beyond transactional return preparation.
- Video Consultation Channel Expansion:Hybrid service models combining encrypted document portals with synchronous advisory sessions retain high-net-worth relationships without physical office overhead.
- Real-Time Reporting Pilots:IRS experiments with continuous tax position monitoring create demand for ongoing client engagement models replacing annual filing cycles.
Industry Challenges
- Seasonal Workforce Scaling:The compressed January-April filing window creates acute talent acquisition and training pressure for qualified preparers.
- Legacy System Integration Friction:Client accounting platforms vary widely in data export compatibility, requiring manual reconciliation workflows that erode margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tax Preparation Services Market |
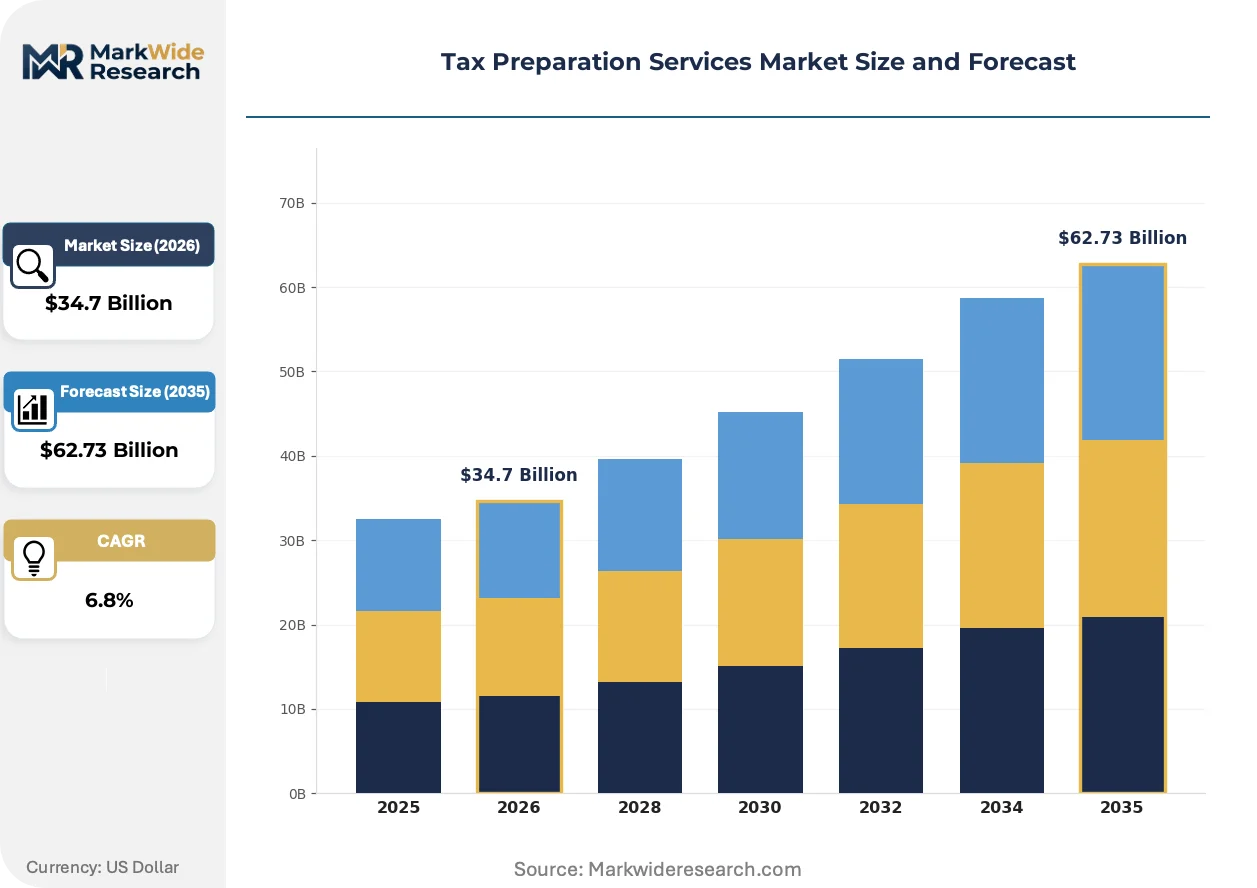
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Individual, Business, Corporate, Self-Employed Pricing Model: Hourly, Flat Fee, Percentage of Refund, Subscription Delivery Mode: In-Person, Online, Hybrid, Mobile Customer Type: Individuals, Small Businesses, Enterprises, Non-Profits |
| Companies Covered | BDO USA, Baker Tilly, PwC, Plante Moran, CohnReznick, EY, RSM US, PKF O'Connor Davies, KPMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tax Preparation Services Market Evolving Landscape
Artificial intelligence and automated document processing are restructuring how preparers allocate judgment versus computation, compressing turnaround times while elevating advisory content.
Machine learning platforms with natural language document ingestion are overtaking manual data entry workflows in high-volume preparation shops. Mid-market accounting firms deploy these tools to absorb seasonal demand spikes without proportional headcount expansion. The technology is overtaking traditional staff augmentation models by enabling fixed-cost infrastructure to absorb variable workload intensity.
IRS real-time reporting pilots and continuous transaction monitoring requirements are extending preparer engagement cycles beyond annual filing windows. Service providers must reconfigure pricing models and client touchpoint architectures to capture recurring advisory revenue. Small business segments in California and New York face the steepest compliance adaptation curves due to concurrent state-level digital filing mandates.
Buyer preference is consolidating around subscription-based advisory relationships rather than per-return transactional pricing. High-net-worth individuals and complex entity structures are shifting toward continuous tax position management with quarterly planning checkpoints. This behavioral pivot is most pronounced in metropolitan corridors with elevated state and local tax layering.
Tax Preparation Services Market Segmentation
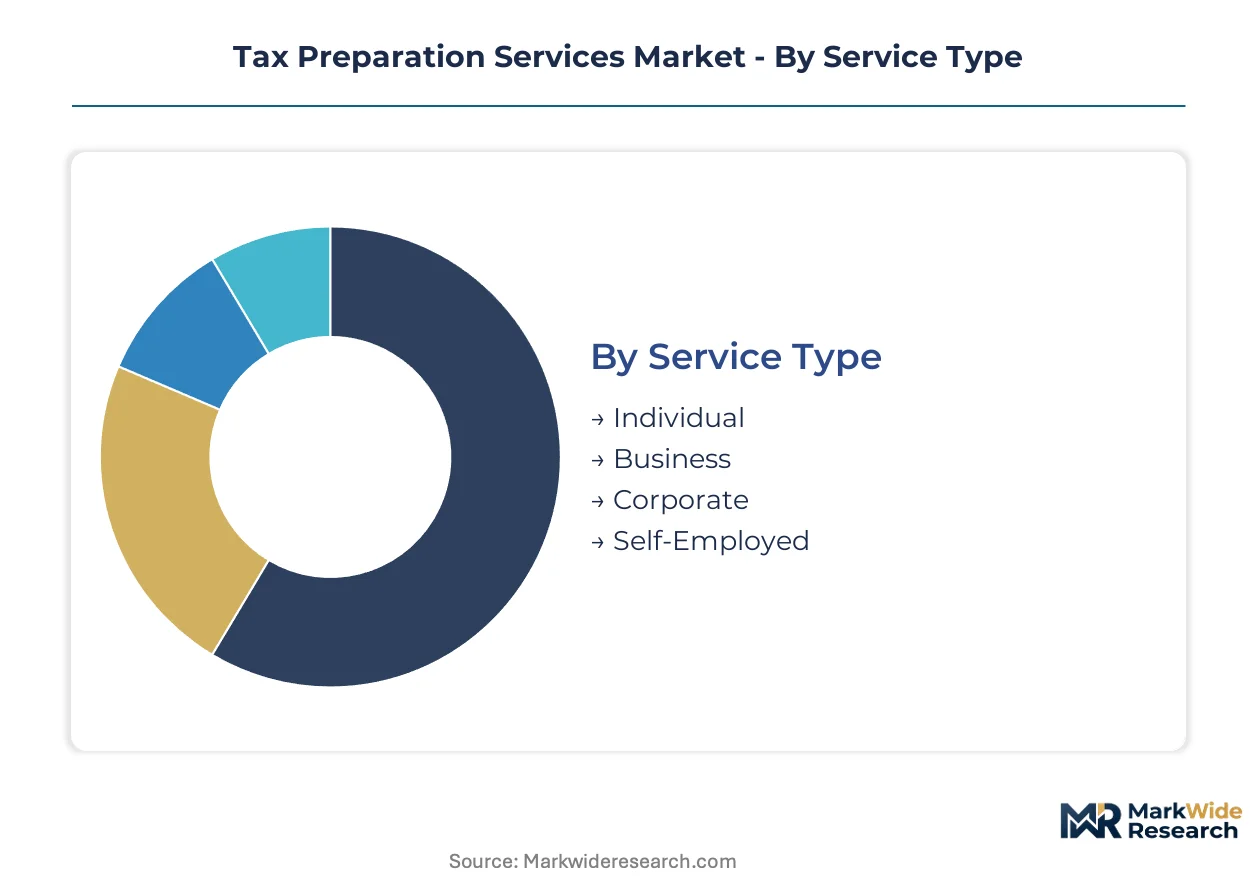
Tax preparation services fragment across four distinct dimensions that reshape how providers configure technology infrastructure, talent deployment, and pricing architectures. Each segmentation axis reveals divergent margin profiles and client retention mechanics that determine competitive positioning.
Service Type:
Complexity gradients separate buyers by the volume of regulatory touchpoints and cross-jurisdiction exposure they must navigate.
- Individual:Standardized federal and state return preparation for W-2 wage earners and basic investment income. Demand concentrates among filers in California, Texas, and New York where state-level obligations layer atop federal requirements; IRS e-filing mandates compress service windows while elevating platform automation.
- Business:Pass-through entity returns, partnership allocations, and Schedule C filings for unincorporated operations. Small business owners in multi-state metropolitan corridors drive volume as remote work arrangements proliferate nexus complications; quarterly estimated payment tracking extends engagement cycles beyond annual filings.
- Corporate:C-corp and consolidated group returns with transfer pricing, R&D credit optimization, and state apportionment calculations. Multinational headquarters in Delaware and Illinois generate disproportionate advisory revenue through cross-border compliance and audit defense preparation.
- Self-Employed:Hybrid personal-business return integration for gig economy participants and independent contractors. Platform workers in Florida and Arizona create concentrated demand for expense categorization and quarterly filing navigation.
Individual filings anchor volume today; Business services are gaining share fastest as regulatory layering deepens.
Pricing Model:
Fee structures align preparer incentives with client risk exposure and engagement duration.
- Hourly:Time-based billing for complex advisory engagements with indeterminate scope. High-net-worth individuals and litigation-contingent returns in Connecticut and Massachusetts accept rate premiums for specialized expertise access.
- Flat Fee:Fixed-price commoditization for standardized return categories. National retail chains deploy this structure to capture price-sensitive individual filers through transparent upfront quoting.
- Percentage of Refund:Contingent compensation tied to refund magnitude. This model concentrates in refund anticipation loan arrangements where preparers capture interest spread alongside preparation fees.
- Subscription:Recurring annual contracts with quarterly checkpoints and year-round advisory access. Small business owners in Washington and Colorado shift toward this structure as real-time reporting pilots extend compliance obligations beyond traditional filing seasons.
Flat Fee arrangements dominate transaction volume; Subscription models are expanding most quickly as buyer preference shifts from episodic to continuous tax management.
Delivery Mode:
Channel selection reflects client comfort with document security protocols and the necessity of synchronous advisory interaction.
- In-Person:Traditional office-based consultation with physical document exchange. Elderly filers and complex entity structures in rural Pennsylvania and Ohio retain preference for face-to-face relationship continuity.
- Online:Fully asynchronous preparation through encrypted portals and chat-based support. Tech-native individual filers under complexity thresholds migrate to this channel for convenience and cost reduction.
- Hybrid:Document upload portals combined with scheduled video consultation sessions. Affluent suburban clients in Virginia and North Carolina favor this architecture for advisory depth without geographic constraint.
- Mobile:Smartphone-native application interfaces with photo-based document capture. Younger demographics and gig workers prioritize this channel for on-the-fly expense tracking and instant refund estimation.
In-Person retains sticky high-net-worth relationships; Hybrid delivery is climbing the fastest as encrypted video infrastructure matures.
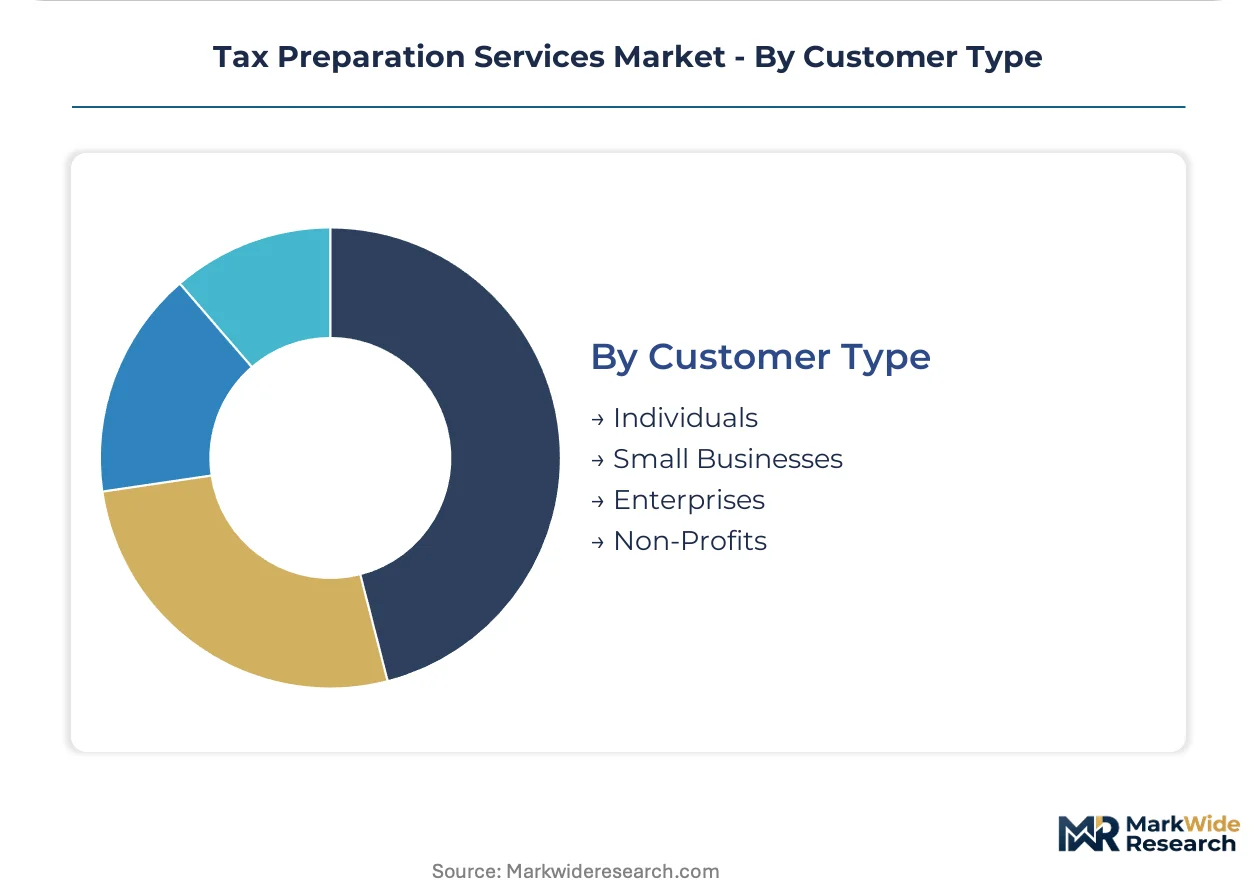
Customer Type:
Entity scale determines the intensity of regulatory oversight and the sophistication of internal accounting capabilities.
- Individuals:Personal income tax obligations spanning wage, investment, and property income. Filers in high-tax states like New Jersey and Illinois generate premium pricing through multi-jurisdiction complexity.
- Small Businesses:Pass-through entities with limited internal tax expertise and high sensitivity to compliance penalty exposure. Restaurant and retail operators in Texas and Georgia drive seasonal demand spikes.
- Enterprises:Public and large private companies with dedicated tax departments outsourcing specialized functions. SEC registrants require PCAOB-aligned disclosure standards that cascade into preparer workload specifications.
- Non-Profits:Exempt organizations navigating unrelated business income, Form 990 transparency requirements, and donor-advised fund compliance. Religious and educational institutions in the Midwest sustain steady year-round advisory relationships.
Individuals constitute the volume base; Small Businesses show the steepest expansion trajectory as regulatory complexity outpaces internal capability development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher tax preparation service revenue per capita than Canada, reflecting deeper regulatory layering across federal, state, and local jurisdictions. Service demand concentrates in metropolitan corridors with elevated compliance complexity. National revenue departments and sub-national authorities shape preparer certification requirements and technology investment patterns.
United States
Small business owners in Texas and Florida drive volume expansion as multi-state nexus rules complicate pass-through entity filings. The IRS enforces phased electronic filing thresholds and Preparer Tax Identification Number requirements that elevate platform investment costs. Manhattan and Los Angeles financial districts sustain premium advisory demand for high-net-worth individuals with cross-border exposure.
Canada
Self-employed platform workers in Ontario and British Columbia create concentrated demand for hybrid personal-business return integration. The Canada Revenue Agency administers digital filing mandates through NETFILE certification protocols that shape preparer software selection. Toronto's technology corridor anchors subscription-based advisory model adoption among gig economy participants.
United Kingdom
Small professional services firms in London and Manchester seek bundled compliance and entity structuring support beyond transactional filing. HM Revenue & Customs operates Making Tax Digital pilots that compress preparation timelines and demand real-time data integration. The Southeast England corridor exhibits fastest uptake of continuous tax position management subscriptions.
Germany
Mittelstand manufacturers in Bavaria and Baden-Württemberg outsource complex cross-border VAT and transfer pricing documentation. The Bundesfinanzministerium implements real-time reporting experiments through ELSTER infrastructure upgrades that reshape preparer engagement models. Stuttgart's industrial cluster drives demand for quarterly advisory checkpoints replacing annual compliance cycles.
Australia
Sole traders and micro-enterprises in New South Wales and Victoria generate volume demand for mobile-first expense categorization tools. The Australian Taxation Office enforces Single Touch Payroll expansion that integrates payroll and tax position monitoring. Sydney's fintech corridor accelerates adoption of encrypted document portals with asynchronous advisory support.
Tax Preparation Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. The market exhibits consolidated leadership at the premium advisory segment alongside fragmented mid-market competition. Three archetypes dominate: global network firms with cross-border infrastructure, national full-service providers with regional density, and technology-enabled specialists with platform automation. Competitive moves center on advisory bundling expansion and encrypted portal infrastructure deployment.
Within the global network tier, PwC and EY exemplify premium positioning through specialized industry tax practices and complex filing capabilities. Baker Tilly occupies a position in the middle-market segment where price sensitivity intersects with regulatory sophistication. These three firms anchor the competitive structure, representing divergent scale and specialization strategies across individual, business, and corporate service categories.
| Leading Market Players |
|---|
| BDO USA |
| Baker Tilly |
| PwC |
| Plante Moran |
| CohnReznick |
| EY |
| RSM US |
| PKF O'Connor Davies |
| KPMG |
| Others |
Value Network & Pricing Analysis
Preparer certification cost indices and software licensing benchmarks cascade through the tax preparation supply chain into pricing stratification across advisory tiers, with IRS-mandated PTIN requirements and continuing education obligations compressing margins for independent practitioners while elevating platform-dependent cost structures for mid-market consolidators.
Pricing Analysis
Capacity additions in hybrid delivery infrastructure across the United States are reshaping price floors for advisory bundles as encrypted portal investments amortize across expanding client bases. Three-tier pricing structure across premium, standard, and economy levels separates white-glove high-net-worth advisory from automated individual filing and DIY-substitute basic compliance, with certification level and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from consumer-grade software capturing filers below complexity thresholds. Small business owners show moderate price sensitivity; high-net-worth individuals with cross-border exposure demonstrate minimal elasticity.
Supply Chain Analysis
Preparer Tax Identification Number certification and IRS e-file protocol compliance create gating barriers that concentrate qualified supply among platform-integrated firms. Software development concentrates in the United States, India, and Ireland; preparer talent pools concentrate domestically with seasonal scaling from accounting programs. Raw material dependencies include cloud infrastructure subscriptions, encryption licensing, and specialized tax code databases. Single-source vulnerability runs through dominant e-file protocol providers. Distribution runs through direct-to-consumer portals and advisory firm networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through advisory bundling as buyers shift from transactional compliance to subscription-based continuous tax management, with platform automation reducing per-return labor intensity.
For Market Incumbents: Cement hybrid delivery dominance by integrating video consultation channels with encrypted document portals before DIY software vendors close the advisory gap. Acquire regional mid-market specialists to absorb PTIN-certified preparer capacity and defend against platform-native entrants. IRS real-time reporting pilots represent the critical regulatory shift requiring infrastructure pre-positioning.
For New Entrants and Emerging Players: Enter via mobile-first expense categorization tools targeting gig economy participants in Florida and Arizona where personal-business return integration remains underserved. White-space concentrates in self-employed segment advisory bundles below corporate complexity thresholds. Go-to-market leverage: partnership with fintech payroll platforms for embedded tax position monitoring.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology-enabled mid-market specialists possessing IRS e-file infrastructure and scalable encrypted portal architecture. Long-term viability hinges on recurring revenue ratio and advisory attach rates rather than seasonal filing volume. Signal to watch: IRS acceleration of real-time reporting pilots into mandatory frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Advisory Bundle Expansion | Captures subscription revenue from small business owners seeking continuous compliance management beyond annual filings. |
| Hybrid Delivery Infrastructure | Retains high-net-worth relationships through video consultation without Manhattan or Los Angeles physical office overhead. |
| Platform Integration Partnership | Embeds tax position monitoring within fintech payroll systems for Single Touch Payroll expansion compliance. |
| PTIN-Certified Preparer Acquisition | Absorbs qualified talent pools ahead of seasonal demand spikes and IRS electronic filing threshold escalations. |
| Real-Time Reporting Capability Buildout | Positions for IRS pilot conversion into mandatory continuous transaction monitoring across California and New York state mandates. |
Research Methodology
Bottom-up small business and individual filer modeling reconciled against top-down preparer capacity and platform investment tracking forms the analytical core of this study. Primary interviews with tax practice partners, IRS regulatory affairs specialists, fintech platform engineers, and accounting program administrators combined with secondary validation against SEC 10-K disclosures of listed advisory firms, IRS e-file statistics, state revenue department compliance reports, and software industry trade filings. Triangulation across demand-side behavioral shifts and supply-side certification constraints ensures coverage of both volume drivers and margin mechanics.
Historical trendline analysis of filing volume, pricing model migration, and delivery mode adoption established baseline trajectories across the projection horizon. Segmentation dimensions modeled include service type complexity tier, pricing model structure, delivery mode channel, and customer entity scale, with CAGRs derived from regression against regulatory mandate timelines and technology diffusion curves. Forecast inputs incorporated IRS electronic filing threshold schedules and state-level digital mandate pilot expansions.
Inputs from IRS statistical releases and state revenue department filings were available through the study window; gaps in real-time reporting pilot conversion timing introduce uncertainty bands around advisory revenue timing. Forecasts reflect documented assumptions regarding regulatory implementation pace and buyer behavioral inertia. A model refresh is warranted upon material change in IRS mandatory e-filing thresholds or accelerated real-time reporting adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
Canada Forensic Accounting Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
Japan Forensic Accounting Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
South Africa Forensic Accounting Market