
 Small Business Accounting Software Market | 2026-2036
Small Business Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Small Business Accounting Software Market Intelligence
The shortage of qualified bookkeepers across North America and Western Europe is unwinding traditional barriers to automated software adoption. Intuit QuickBooks leverages its dominant brand recognition and extensive accountant partner network to sustain market presence across English-speaking economies. Xero differentiates through bank-grade API infrastructure and real-time multi-currency reconciliation. FreshBooks specializes in service-based workflows, particularly time-tracking and project-centric billing for creative professionals.
Small business accounting software encompasses cloud-deployed, on-premise, and hybrid platforms that automate ledger maintenance, accounts payable and receivable, payroll tax computation, and regulatory financial reporting through double-entry bookkeeping engines with GAAP or IFRS compliance modules. Cloud-based deployment leads current adoption curves due to lower total cost of ownership and automatic regulatory update pipelines. The invoicing and bookkeeping solution categories capture established margin pools, while expense tracking is gaining traction among mobile-first freelancers and field-service startups. E-commerce customer types are expanding fastest as platform-native integrations with Shopify, Amazon, and Stripe become standard procurement requirements.
The Internal Revenue Service mandates electronic filing thresholds and quarterly estimated tax protocols that shape feature roadmaps for US-targeted products. India's Central Board of Direct Taxes enforces GST invoice matching and e-way bill compliance, forcing vendors to localize reporting engines. The EU's GDPR and the Digital Operational Resilience Act constrain cross-border data residency architectures. Stakeholders must monitor how open-banking API mandates from the UK's Financial Conduct Authority and India's Reserve Bank reshape bank-feed reliability and customer acquisition economics.
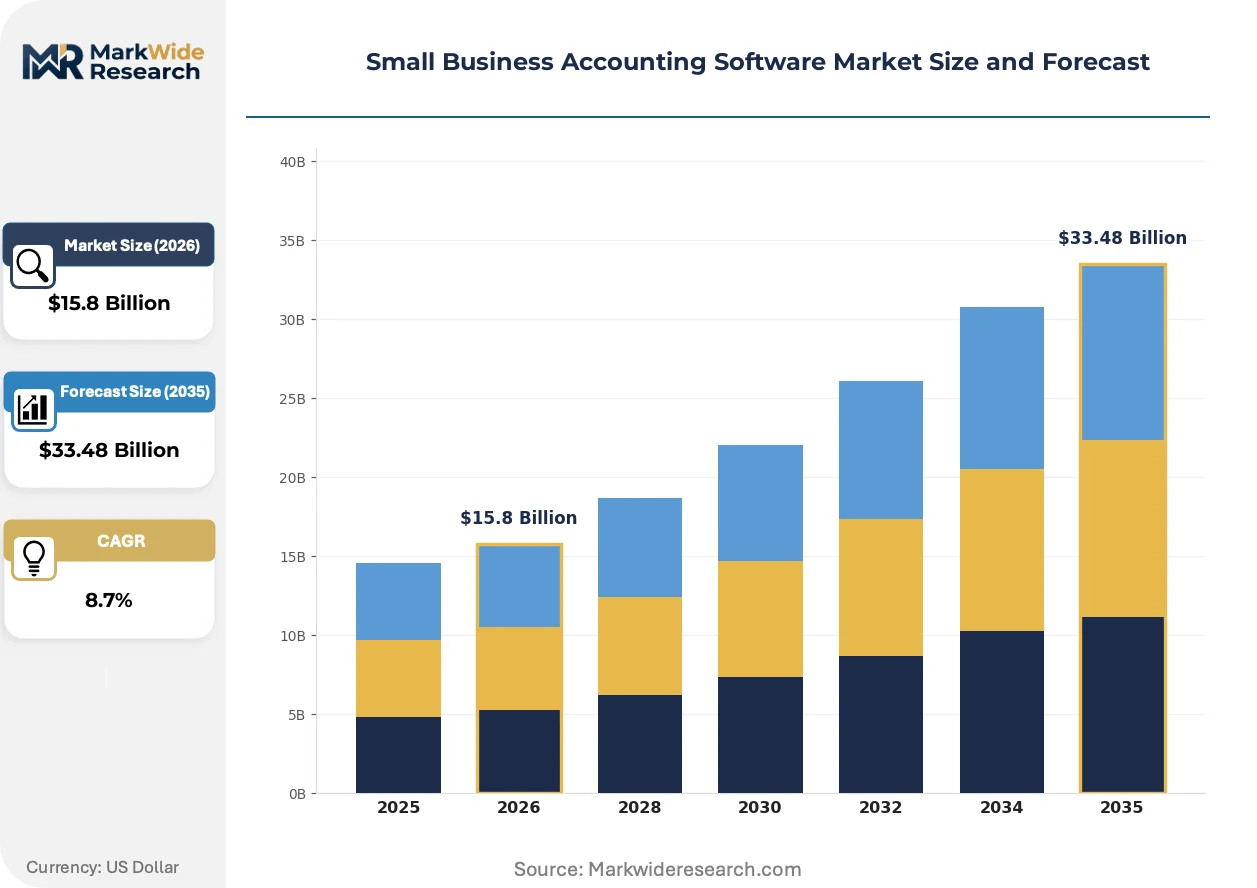
Market Dynamics
Cloud migration is decomposing the traditional on-premise software stack across small business accounting, as API-first architectures enable modular procurement and real-time bank reconciliation becomes a baseline expectation rather than a premium feature.
Growth Catalysts
- India's GST invoice matching mandate:The Central Board of Direct Taxes enforces e-way bill compliance and automated tax reporting, compelling small enterprises to adopt compliant accounting platforms.
- Open banking API proliferation:The UK's Financial Conduct Authority mandates standardized bank feeds, reducing manual data entry friction and accelerating customer acquisition for cloud-native vendors.
- Freelancer workforce expansion:Platform-native integrations with Shopify, Amazon, and Stripe are becoming standard procurement requirements for e-commerce operators seeking unified financial visibility.
Market Restraints
- Cross-border data residency constraints:The EU's GDPR and Digital Operational Resilience Act impose architectural complexity on vendors serving multi-jurisdictional small business clients.
- Qualified bookkeeper scarcity:North American and Western European labor markets face persistent shortages of accounting professionals capable of configuring advanced automation workflows.
- Legacy system integration friction:On-premise ERP installations in established small enterprises resist cloud migration due to customized chart-of-accounts configurations and historical data migration costs.
Strategic Opportunities
- Embedded finance convergence:The intersection of accounting software with payment processing and lending APIs creates white space for unified cash-flow management platforms targeting field-service startups.
- United States regulatory tailwinds:Internal Revenue Service electronic filing thresholds and quarterly estimated tax protocols shape feature roadmaps that favor automated tax computation modules.
- Mobile-first expense tracking:Underpenetrated segments among gig economy workers and remote creative professionals demand specialized time-tracking and receipt-capture functionality.
Industry Challenges
- Multi-currency reconciliation complexity:Real-time foreign exchange rate management and IFRS compliance for cross-border small traders require sophisticated engine development.
- API reliability variance:Bank-feed instability across regional financial institutions disrupts automated reconciliation workflows and erodes user trust in cloud platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Business Accounting Software Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $33.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, SaaS Solution: Invoicing, Bookkeeping, Expense Tracking, Financial Reporting End User: Freelancers, Startups, SMEs, Nonprofits Customer Type: Retail, Service-based, E-commerce, Manufacturing |
| Companies Covered | FreshBooks, Sage 50cloud, Intuit QuickBooks, Kashoo, OneUp, Xero, Wave, Tipalti, Zoho Books, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Business Accounting Software Market Strategic Shifts & Innovations
Artificial intelligence and machine learning capabilities are embedding deeply into core accounting workflows, transforming routine data entry and anomaly detection from manual processes into automated background operations.
Machine learning-powered anomaly detection is decomposing traditional audit and reconciliation workflows. Freelancers and micro-SMEs are adopting these capabilities fastest as they lack dedicated finance staff. The technology is compressing error-correction cycles from monthly closes to real-time flagging, reducing professional service dependencies for routine oversight.
The EU's Digital Operational Resilience Act imposes strict operational continuity requirements on financial software providers serving European small businesses. Vendors must demonstrate automated backup protocols and incident response capabilities to maintain market access. Cloud-native platforms with built-in redundancy architectures are capturing share from legacy providers struggling to retrofit compliance infrastructure.
Subscription fatigue among small business owners is fragmenting bundled software procurement. Buyers increasingly unbundle accounting from adjacent services like payroll and CRM, selecting best-of-breed point solutions with superior API connectivity. This pattern concentrates among United States and United Kingdom service-based businesses with technical staff capable of integration management.
Small Business Accounting Software Market Segmentation
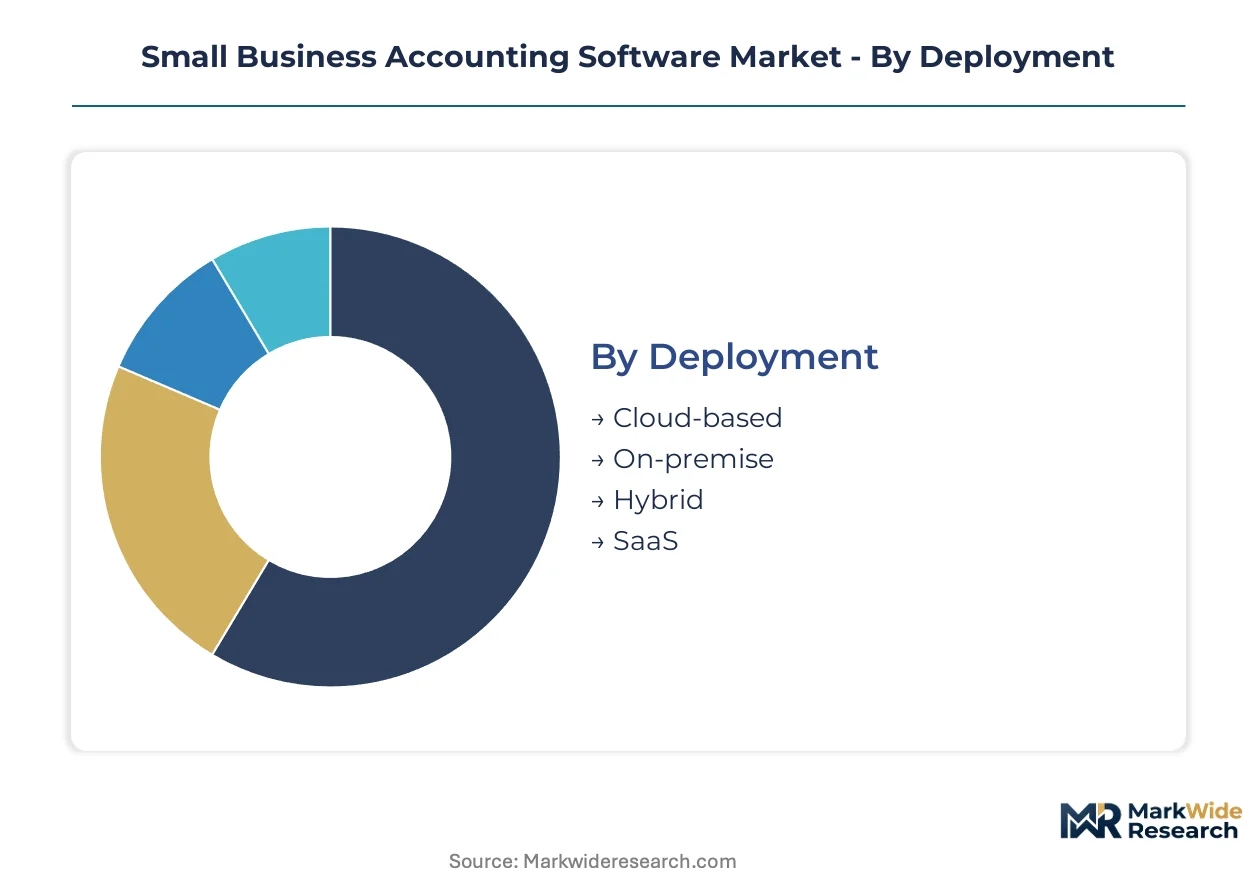
Segmentation reveals how procurement patterns diverge across technical architectures, functional modules, and buyer maturity levels. Understanding these splits enables vendors to align pricing, localization, and integration roadmaps with distinct customer economics and compliance requirements.
Deployment:
Cloud-based platforms dominate domestic adoption in digitally mature markets, while hybrid architectures persist in export-dependent economies with data residency mandates.
- Cloud-based:Multi-tenant architectures with automatic regulatory update pipelines eliminate infrastructure overhead for micro-SMEs. Demand concentrates among United States and United Kingdom freelancers seeking mobile accessibility and real-time collaboration with accountants. India's GST invoice matching mandate accelerates adoption among small traders requiring automated compliance.
- On-premise:Single-tenant installations with localized database control serve established manufacturers with customized chart-of-accounts configurations. Deployment persists in German Mittelstand firms and Japanese family-owned enterprises resisting data migration costs.
- Hybrid:Split architectures with sensitive payroll data on-premise and transactional workflows in cloud balance control with flexibility. Adoption spreads among Canadian and Australian mid-market SMEs with sector-specific audit requirements.
- SaaS:Subscription-native delivery with API-first integration stacks enables modular procurement of adjacent services like payment processing. Traction builds among Indian and Brazilian field-service startups prioritizing cash-flow visibility over capital expenditure.
Cloud-based deployment holds the largest share; momentum sits with SaaS as embedded finance convergence reshapes procurement criteria.
Solution:
Functional modules vary in margin structure, with core ledger maintenance commanding premium pricing and peripheral capabilities competing on volume.
- Invoicing:Automated receivables workflows with multi-currency support and payment gateway integration reduce days-sales-outstanding for cross-border traders. Demand clusters among United Kingdom service exporters and Indian e-commerce operators on Amazon and Flipkart marketplaces.
- Bookkeeping:Double-entry engines with GAAP or IFRS compliance modules form the technical foundation of all platforms. Penetration is deepest among United States micro-SMEs facing IRS electronic filing thresholds and quarterly estimated tax obligations.
- Expense Tracking:Mobile-first receipt capture and mileage logging with machine-learning categorization targets gig economy workers. Growth accelerates among remote creative professionals and delivery fleet operators in France and Spain.
- Financial Reporting:Customizable dashboarding with stakeholder-ready export formats serves investor-facing startups and grant-dependent nonprofits. Adoption rises among German and Dutch SMEs navigating CSRD sustainability disclosure requirements.
Bookkeeping commands the deepest penetration; expense tracking is climbing the fastest as freelancer workforce expansion outpaces traditional SME formation.
End User:
Buyer sophistication spans from solo operators requiring zero-configuration onboarding to multi-entity nonprofits with fund-accounting complexity.
- Freelancers:Sole proprietors with simplified tax obligations and minimal reconciliation volume prioritize time-tracking and project billing over full general-ledger functionality. This cohort expands most quickly across United States, India, and United Kingdom platform economies.
- Startups:Venture-backed companies with investor reporting requirements and burn-rate visibility needs demand cap-table integration and runway forecasting. Concentration is highest in Silicon Valley, Bangalore, and London venture ecosystems.
- SMEs:Established small enterprises with 10-100 employees require payroll tax computation, multi-user permissions, and inventory costing. Procurement concentrates among Italian and Mexican family-owned manufacturers with multi-generational operations.
- Nonprofits:Grant-funded organizations with restricted fund accounting and donor reporting mandates need specialized compliance modules. Demand localizes in United States and Canadian markets with dense philanthropic infrastructure.
SMEs contribute the largest revenue base; freelancers are gaining share fastest as platform-native business formation accelerates.
Customer Type:
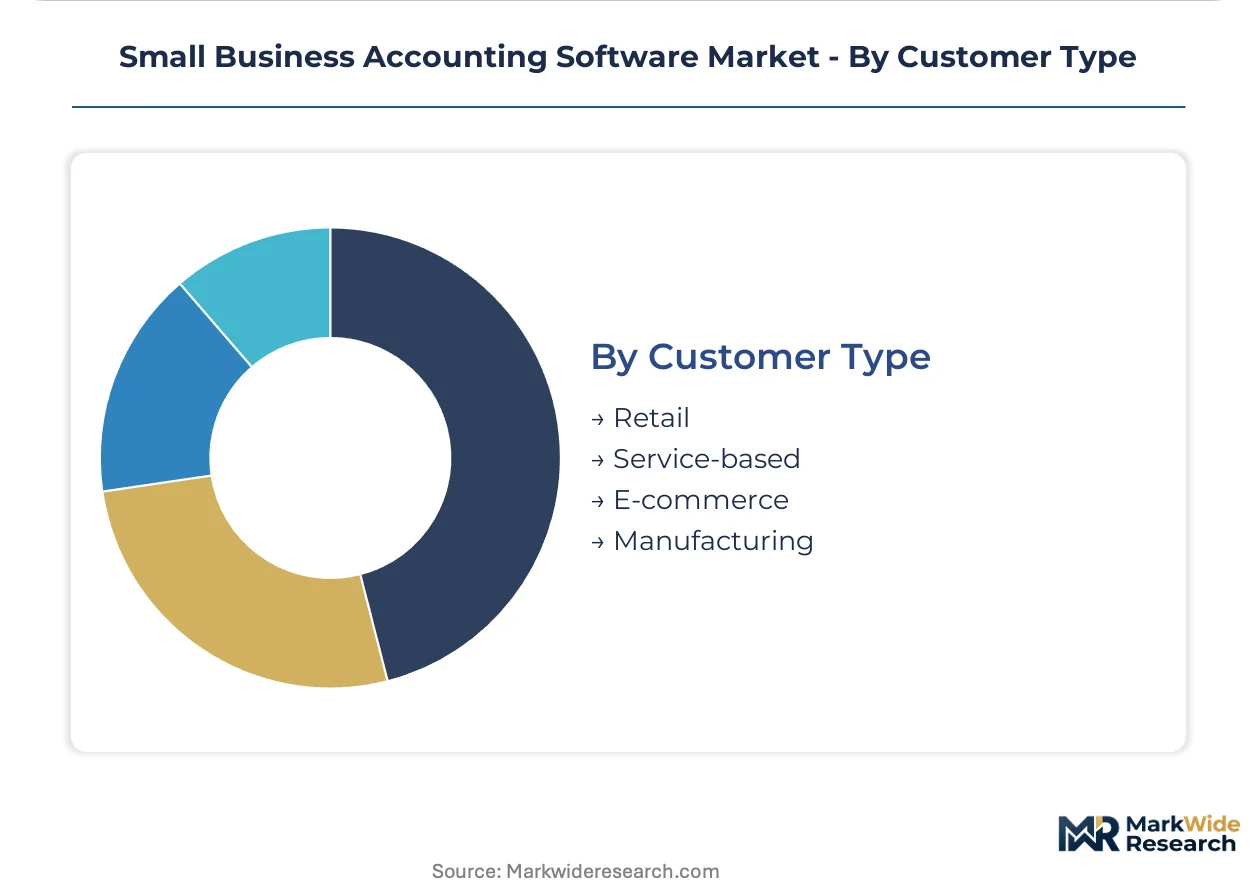
Vertical-specific workflows drive divergent integration priorities, with inventory-heavy sectors demanding ERP-grade capabilities and service sectors optimizing for time-based billing.
- Retail:Brick-and-mortar and omnichannel sellers require point-of-sale integration, inventory valuation, and sales tax automation across jurisdictions. United States and Indian multi-location retailers drive procurement as state-level tax complexity increases.
- Service-based:Consultancies, agencies, and professional practices prioritize project profitability tracking and utilization rates. Penetration is deepest among United Kingdom and Australian knowledge-economy clusters.
- E-commerce:Platform-native sellers on Shopify, Amazon, and Stripe demand unified reconciliation across payment processors and marketplace fees. This vertical is expanding most rapidly among direct-to-consumer brands in United States and Chinese cross-border traders.
- Manufacturing:Job-shop and light industrial producers need bill-of-materials costing, work-in-progress tracking, and shop-floor integration. Adoption concentrates among German, Japanese, and South Korean precision manufacturers.
Service-based customers hold the largest installed base; e-commerce is on the steepest expansion trajectory as platform selling becomes default entrepreneurship pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Internal Revenue Service anchors the United States as the dominant geography, with electronic filing thresholds and quarterly estimated tax protocols shaping vendor feature roadmaps. Cloud-native platforms capture share fastest where open-banking mandates reduce manual data entry friction.
United States
Solo proprietors and venture-backed startups drive cloud adoption across Silicon Valley, Austin, and New York City clusters. The IRS mandates electronic filing thresholds above specific revenue bands, forcing automation upgrades. Atlanta and Denver field-service startups prioritize embedded finance convergence for unified cash-flow visibility.
United Kingdom
Freelancers and creative agencies demand real-time multi-currency reconciliation for service exports. The Financial Conduct Authority mandates standardized open-banking APIs, accelerating bank-feed reliability improvements. London's fintech corridor and Manchester's digital agency cluster host the densest vendor competition.
India
Small traders and Amazon marketplace sellers require automated GST invoice matching and e-way bill compliance. The Central Board of Direct Taxes enforces strict e-invoicing protocols, compelling legacy ledger migration. Bangalore's SaaS ecosystem and Delhi-NCR's trading hubs concentrate platform-native adoption.
Germany
Mittelstand manufacturers resist full cloud migration due to customized chart-of-accounts configurations and audit trail requirements. The Digital Operational Resilience Act imposes strict operational continuity mandates on financial software serving European small businesses. Bavaria's precision engineering cluster and Baden-Württemberg's automotive suppliers maintain hybrid deployments.
Australia
Mid-market SMEs with sector-specific audit requirements favor split architectures balancing payroll control with transactional cloud flexibility. The Australian Taxation Office enforces single-touch payroll reporting standards. Sydney's professional services corridor and Melbourne's creative economy drive mobile-first expense tracking adoption.
Small Business Accounting Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with brand recognition and accountant partner networks defending incumbency against API-native challengers. The market structure concentrates among English-speaking economies where cloud migration has decomposed traditional on-premise stacks. Two strategic archetypes dominate: vertically integrated platforms bundling adjacent services, and modular specialists optimizing single workflows. Competitive moves center on embedded finance partnerships and mobile-first feature expansion.
Within the integrated leader tier, Intuit QuickBooks and Xero exemplify contrasting architectural philosophies, while FreshBooks occupies a position among service-centric specialists. Zoho Books anchors the emerging-market challenger archetype with localization depth. These three entities collectively represent the competitive vectors reshaping procurement criteria across freelancer, startup, and established SME segments.
| Leading Market Players |
|---|
| FreshBooks |
| Sage 50cloud |
| Intuit QuickBooks |
| Kashoo |
| OneUp |
| Xero |
| Wave |
| Tipalti |
| Zoho Books |
| Others |
Cost & Logistics Intelligence
Subscription-based annual contracts lock in recurring revenue visibility while insulating SaaS vendors from churn-driven price erosion. This contract structure binds United States freelancers and United Kingdom micro-SMEs into multi-year commitments that fund continuous API infrastructure investment.
Pricing Analysis
United States pricing sits at a premium to Indian and Brazilian markets due to embedded compliance automation for IRS protocols. The dominant model is tiered SaaS subscription separating freelancer plans from multi-user SME configurations. Price differentiation rests on bank-feed reliability SLAs and multi-currency engine sophistication. Pricing pressure stems from subscription fatigue driving unbundling of payroll and CRM adjacent services. Freelancers exhibit highest price sensitivity while venture-backed startups prioritize feature depth over cost.
Supply Chain Analysis
The United States and India anchor cloud infrastructure provisioning for accounting software delivery, with Ireland and Singapore serving as data residency hubs for European and Asia-Pacific compliance. The supply chain draws from hyperscaler compute capacity, open-banking API aggregators, and machine-learning inference engines. Single-source vulnerability concentrates in bank-feed providers where regional financial institution coverage gaps disrupt reconciliation workflows. Distribution runs through direct digital sales channels supplemented by accountant partner networks in English-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small business accounting software sits in early-cycle expansion as freelancer workforce formation outpaces traditional SME growth and platform-native business creation accelerates adoption curves.
For Market Incumbents: Secure accountant partner network exclusivity through co-developed certification programs that embed QuickBooks and Xero into professional education pipelines. Deepen API infrastructure investment to defend against modular specialists unbundling expense tracking and invoicing workflows. The priority lever is bank-feed reliability engineering to neutralize open-banking mandate advantages held by cloud-native challengers. For New Entrants and Emerging Players: Anchor in mobile-first expense tracking for gig economy workers in France and Spain where incumbent penetration remains shallow. Target field-service startups in Atlanta and Denver seeking embedded finance convergence unmet by vertically integrated platforms. The optimal go-to-market angle is vertical specialization for Shopify-native e-commerce operators requiring unified marketplace fee reconciliation. For Investors and Strategic Acquirers: Capital is best deployed toward API-first modular specialists with proven integration stacks and regional localization depth. The five-to-ten year viability window favors vendors capturing freelancer segment economics before platform economies mature. The signal to watch is open-banking API mandate expansion beyond the United Kingdom and India as customer acquisition cost inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Shopify and Stripe reconciliation captures e-commerce customer acquisition from service-based incumbents. |
| Geographic Expansion | India GST compliance localization opens small trader segments underpenetrated by English-market leaders. |
| Strategic Partnership | Open-banking aggregator alliances accelerate bank-feed coverage in markets with FCA or RBI mandates. |
| Product Launch | Mobile-first expense tracking with machine-learning categorization targets gig economy workforce expansion. |
| Acquisition of Specialist Firm | Embedded finance capabilities from payment processing specialists create unified cash-flow platforms. |
Research Approach
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented compliance requirements. The analysis draws from conversations with SaaS product managers, open-banking integration specialists, freelance platform operators, and accounting firm technology officers. Secondary sources include IRS electronic filing threshold publications, RBI open-banking API specifications, FCA regulatory notices, and vendor SEC disclosure filings. Bottom-up segment sizing triangulates against top-down cloud software spending estimates.
Sensitivity analysis across deployment model adoption curves and freelancer workforce growth scenarios shapes the analytical framework. The model segments by cloud versus hybrid architecture, organization size tier, vertical customer type, and regional regulatory cluster. CAGRs derive from penetration rate trajectories and average revenue per user expansion patterns across the projection horizon. Forecast inputs include GST mandate enforcement timelines and open-banking API standardization velocity.
Underlying assumptions cover regulatory mandate adherence rates and cloud infrastructure cost trajectories, with deviation risk concentrated in cross-border data residency constraint tightening and bank-feed reliability variance. Recalibration cycles align with material shifts in open-banking mandate geography and freelance platform economy formation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Canada Forensic Accounting Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
Canada Accounting Software Market
Accounting and Taxation Services
Trust Accounting Software Market