
 South Korea Accounting & Budgeting Software Market | 2026-2036
South Korea Accounting & Budgeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Accounting & Budgeting Software Market Insights
South Korea's Corporate Sustainability Reporting Directive alignment under K-ESG standards is recalibrating how domestic firms budget and disclose environmental liabilities. SAP SE leverages deep integration with ERP modules to anchor enterprise-grade financial planning for chaebol subsidiaries. Oracle Corp. competes through specialized database architecture that sustains real-time consolidation across multi-entity Korean conglomerates. Microsoft Corp. differentiates by embedding AI-driven forecasting within familiar productivity suites that dominate Korean office workflows.
Accounting and budgeting software encompasses systems that automate ledger management, variance analysis, and capital allocation through rule-based engines and predictive algorithms. Cloud-based deployment now leads product type adoption as Korean SMEs abandon legacy on-premise servers, while hybrid architectures retain traction among financial institutions requiring air-gapped tax management functionality. Large corporations dominate end-user spending, though small enterprises represent the fastest-expanding segment as government digitization subsidies lower SaaS entry barriers. Public cloud deployment captures volume, but private cloud instances command premium pricing for clients subject to MFDS data sovereignty requirements in healthcare-adjacent accounting.
MFDS data localization rules intersect with National Tax Service e-invoicing mandates to shape vendor certification requirements and cloud infrastructure placement. KISA cybersecurity frameworks and BIS cloud service standards further constrain which platforms qualify for public sector and regulated industry procurement. Stakeholders must monitor whether upcoming Personal Information Protection Commission enforcement actions force architectural redesigns of cross-border financial data pipelines.
Market Dynamics
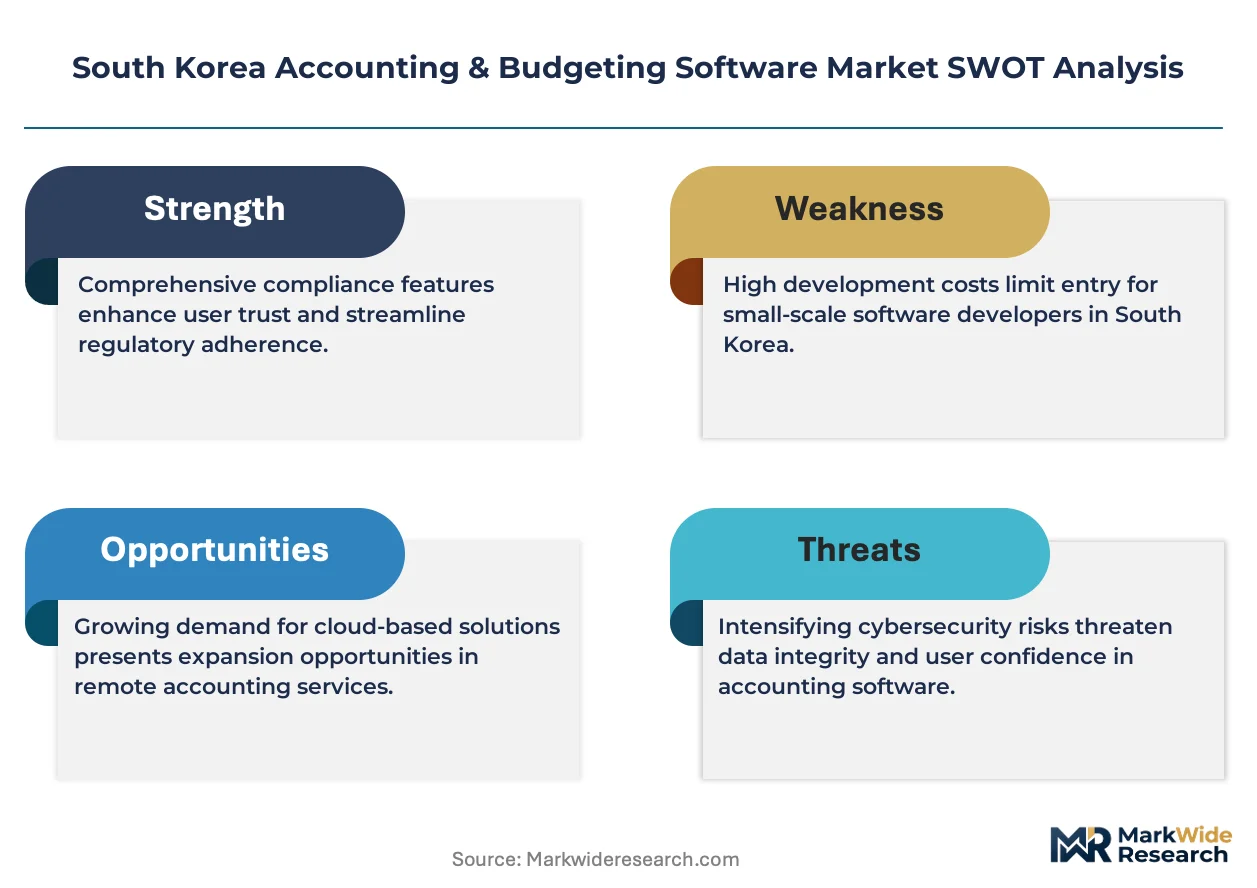
K-ESG disclosure mandates are forcing Korean conglomerates to rebuild budgeting workflows around carbon liability tracking and supply chain emissions accounting, compressing procurement cycles for compliant platforms.
Growth Catalysts
- Personal Information Protection Act Revision:The amended PIPC framework mandates encrypted cloud storage for financial records, accelerating SME migration from on-premise servers to certified SaaS accounting platforms.
- Mid-sized Manufacturing:Korean industrial firms with 100-500 employees are automating variance analysis and capital allocation through rule-based engines to compete with chaebol-tier operational efficiency.
- National Tax Service E-Invoicing:Mandatory electronic tax document submission requires API-integrated accounting systems, pulling laggard enterprises into compliant software ecosystems.
Market Restraints
- MFDS Data Localization:Healthcare-adjacent accounting systems must maintain air-gapped private cloud instances, doubling infrastructure costs versus public cloud deployments for medical device distributors.
- Legacy ERP Entrenchment:Decades-old on-premise installations at family-controlled conglomerates resist cloud migration due to customization debt and internal IT fiefdoms.
- Cybersecurity Certification Bottlenecks:KISA framework compliance timelines stretch 8-14 months, freezing vendor eligibility for public sector procurement windows.
Strategic Opportunities
- Busan-Ulsan Industrial Corridor:Port logistics and shipbuilding clusters outside Seoul remain underserved by enterprise-grade accounting platforms, offering first-mover expansion terrain.
- AI-Native Forecasting Convergence:Machine learning modules embedded in spreadsheet interfaces are unifying predictive analytics with familiar productivity workflows for finance teams.
- Regional Government Digitization Subsidies:Provincial SME support programs in Gyeonggi and Incheon lower SaaS entry barriers for micro-enterprises previously priced out of automated systems.
Industry Challenges
- Cross-Border Data Pipeline Complexity:Multinational Korean firms face architectural redesigns as PIPC enforcement actions target financial data transfers to overseas parent entities.
- Hybrid Integration Talent Scarcity:Technical specialists capable of bridging legacy on-premise tax modules with modern cloud general ledgers command premium compensation that mid-market vendors struggle to fund.
- Certification Stacking Burden:Platforms must simultaneously satisfy BIS cloud standards, KISA cybersecurity tiers, and NTS API specifications, fragmenting engineering roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Accounting & Budgeting Software Market |
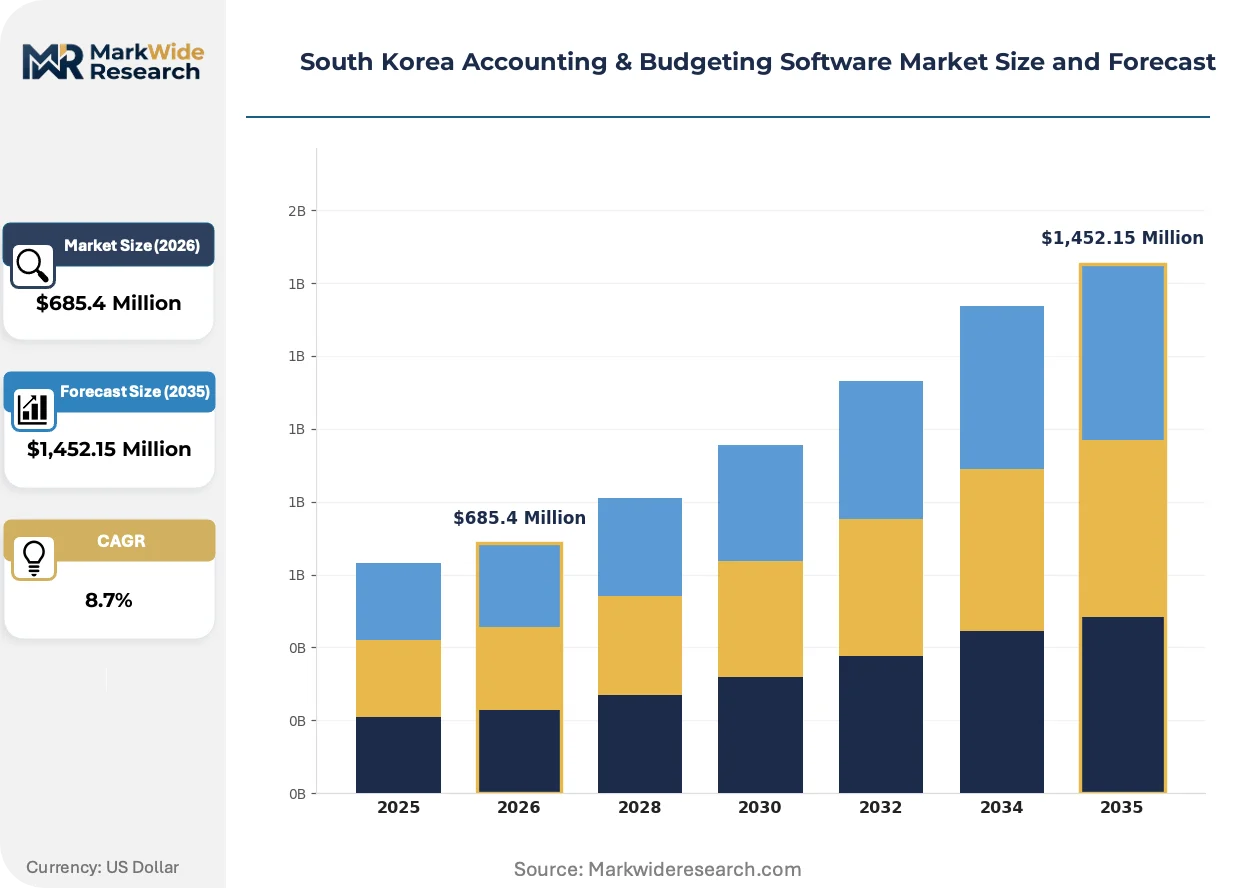
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Nonprofits Deployment: Public Cloud, Private Cloud, Virtual Server, Local Server Functionality: Expense Tracking, Financial Reporting, Budget Planning, Tax Management |
| Companies Covered | SAP SE, Oracle Corp., Microsoft Corp., Intuit Inc., Sage Group Plc, Xero Ltd., Zoho Corp., FreshBooks, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Accounting & Budgeting Software Market Trends and Innovations
Embedded intelligence and compliance automation are compressing the traditional separation between transaction recording and strategic financial planning across Korean enterprise software stacks.
Natural language processing interfaces are unifying conversational query capabilities with core ledger functions, allowing finance teams to extract variance reports through voice commands rather than structured menu navigation. Mid-market manufacturers in Gyeonggi Province are piloting these systems at triple the rate of large conglomerates. The technology is unifying operational data capture with executive dashboard generation, collapsing reporting latency from days to minutes.
Personal Information Protection Commission enforcement guidelines are tightening consent requirements for AI-driven expense categorization algorithms that process employee behavioral data. Financial institutions must now maintain audit trails for every automated classification decision affecting tax liability calculations. Securities firms in Yeouido face the steepest compliance rebuilds as their client transaction monitoring systems fall under expanded biometric data protections.
Subscription bundling is displacing perpetual license arrangements as Korean software resellers consolidate vendor relationships into single procurement contracts. Small enterprises previously purchasing point solutions for invoicing, payroll, and tax filing now demand unified platforms through regional IT service providers. This consolidation is most visible in Daejeon and Daegu, where government-backed digitization centers aggregate demand for negotiated SaaS packages.
South Korea Accounting & Budgeting Software Market Segmentation
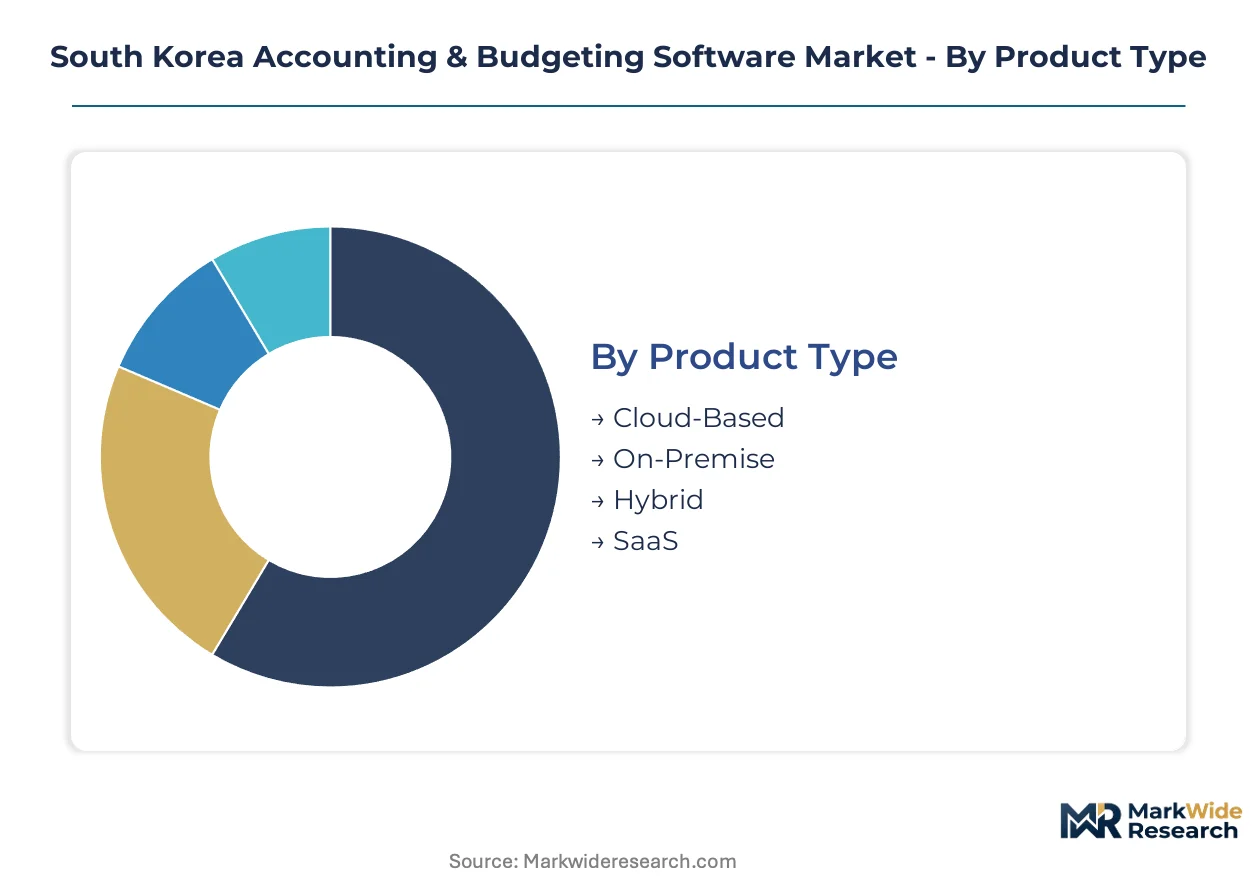
Korean accounting software purchasing splits sharply between standardized SaaS packages for compliance-driven SMEs and heavily customized enterprise deployments for chaebol-tier consolidation requirements. Segmentation reveals how regulatory fragmentation across MFDS, KISA, and NTS mandates forces architectural specialization that resists simple tiering.
Product Type:
Customization intensity varies from zero-config SaaS to bespoke hybrid stacks, with compliance requirements often overriding cost optimization in procurement decisions.
- Cloud-Based:Multi-tenant architectures with automatic patch deployment dominate SME adoption in Seoul's Gangnam district, where NTS e-invoicing API integration has become a non-negotiable procurement filter. MFDS certification requirements for healthcare-adjacent firms push these buyers toward private cloud variants despite 40-60% cost premiums.
- On-Premise:Legacy client-server installations persist at family-controlled conglomerates with decades of customization debt, particularly in Yeouido financial clusters where air-gapped tax modules satisfy historical audit protocols. IT fiefdoms at these entities resist cloud migration despite escalating maintenance overhead.
- Hybrid:Split architectures maintain sensitive payroll data on local servers while pushing general ledger functions to certified public cloud instances, a configuration favored by mid-sized manufacturers in Gyeonggi Province navigating PIPC encryption mandates.
- SaaS:Browser-native platforms with subscription pricing lower entry barriers for micro-enterprises in Daejeon and Daegu digitization centers, where government subsidies aggregate demand into negotiated reseller bundles.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
End User:
Organizational scale determines compliance burden complexity and integration depth with existing ERP ecosystems.
- Small Enterprises:Under-50-employee firms in regional manufacturing clusters adopt lightweight invoicing-tax bundles through IT service provider consolidations, with Gyeonggi and Incheon subsidy programs compressing procurement cycles.
- Medium Enterprises:Korean industrial firms with 100-500 employees drive variance analysis automation, embedding rule-based capital allocation engines to match chaebol-tier operational metrics. Busan-Ulsan shipbuilding corridors remain underserved by enterprise-grade platforms.
- Large Corporations:Chaebol subsidiaries demand real-time multi-entity consolidation across hundreds of legal entities, with database architecture latency requirements measured in milliseconds for treasury operations.
- Nonprofits:Grant-dependent organizations in Seoul prioritize donor transparency reporting modules, though this segment commands minimal vendor engineering attention due to constrained procurement budgets.
Large Corporations capture premium spending per seat. Medium Enterprises show steepest expansion trajectory as manufacturing digitization accelerates.
Deployment:
Infrastructure placement decisions hinge on data sovereignty requirements and cross-border pipeline restrictions under evolving PIPC enforcement.
- Public Cloud:Shared infrastructure delivers cost efficiency for standardized workloads, dominating volume among non-regulated SMEs with no MFDS or financial sector exposure.
- Private Cloud:Single-tenant instances command pricing premiums from healthcare device distributors and securities firms facing air-gapped requirements, with infrastructure costs doubling versus public equivalents.
- Virtual Server:Partitioned physical hardware offers middle-ground isolation for mid-market manufacturers transitioning from on-premise legacy, particularly in Gyeonggi Province pilot programs.
- Local Server:Rack-mounted hardware in corporate data centers persists where KISA cybersecurity certification timelines stretch 8-14 months, freezing cloud eligibility for public sector procurement windows.
Public Cloud leads by deployment count. Private Cloud gains share fastest as PIPC enforcement tightens consent requirements for financial data processing.
Functionality:
Module selection reflects organizational maturity, with basic record-keeping giving way to predictive capabilities as finance teams digitize.
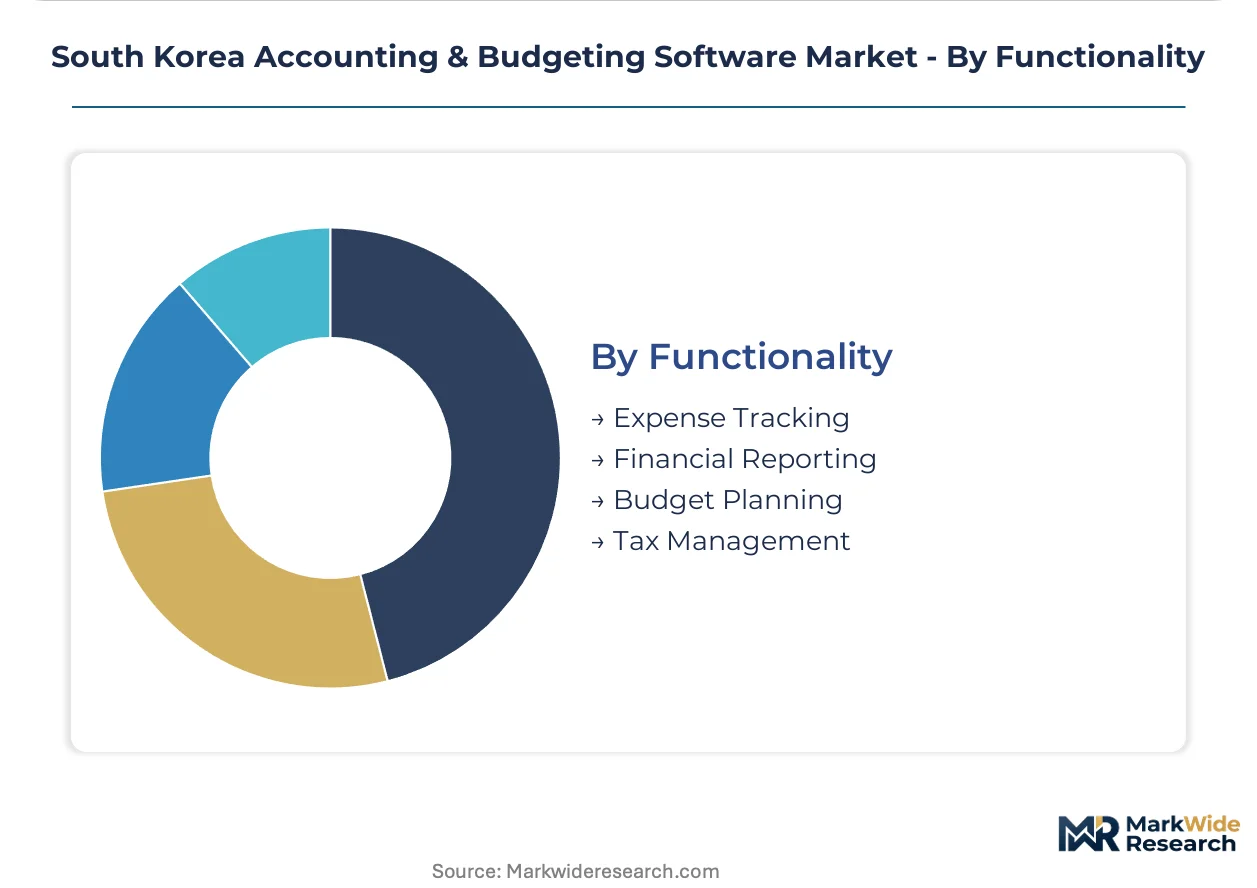
- Expense Tracking:AI-driven categorization algorithms process employee behavioral data, triggering PIPC audit trail requirements for every automated classification decision affecting tax liability. Securities firms in Yeouido face steepest compliance rebuilds.
- Financial Reporting:Real-time dashboard generation collapses reporting latency from days to minutes, with natural language processing interfaces enabling voice-command variance extraction at mid-market manufacturers in Gyeonggi.
- Budget Planning:K-ESG disclosure mandates force carbon liability tracking and supply chain emissions accounting into capital allocation workflows, compressing procurement cycles for compliant platforms.
- Tax Management:NTS e-invoicing API integration has become table stakes, pulling laggard enterprises into compliant software ecosystems regardless of other functionality priorities.
Tax Management anchors mandatory procurement. Budget Planning climbs fastest as ESG compliance reshapes forecasting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam and Yeouido commercial districts concentrate the heaviest demand for enterprise accounting platforms, where corporate headquarters and financial institutions cluster around premium-grade cloud deployments.
Seoul Capital Area
Chaebol subsidiaries and securities firms in Gangnam and Yeouido drive real-time multi-entity consolidation requirements. K-ESG disclosure mandates under the Financial Services Commission reshape capital allocation workflows for conglomerate treasury operations. The district's density of financial institutions sustains premium pricing for private cloud instances with millisecond latency specifications.
Busan-Ulsan Industrial Corridor
Shipbuilding clusters and port logistics operators in this southeastern corridor remain underserved by enterprise-grade platforms. Mid-sized manufacturers with 100-500 employees automate variance analysis to match chaebol-tier efficiency metrics. Government-backed digitization subsidies in adjacent Gyeongnam Province lower SaaS entry barriers for industrial SMEs.
Gyeonggi Province
Manufacturing SMEs in Suwon and Seongnam pilot AI-driven natural language processing interfaces for financial reporting. Provincial SME support programs compress procurement cycles for micro-enterprises adopting unified invoicing-tax bundles. The region's density of mid-market industrial firms drives fastest-expanding segment growth.
Daejeon-Sejong
Government-backed digitization centers aggregate demand for negotiated SaaS packages among small enterprises. Public sector procurement windows favor vendors with completed KISA cybersecurity certifications. The Sejong administrative city concentration creates captive demand for compliant cloud accounting among state-affiliated entities.
Daegu-Gyeongbuk
Regional IT service providers consolidate vendor relationships into single procurement contracts for textile and machinery SMEs. Subscription bundling displaces perpetual license arrangements as resellers unify invoicing, payroll, and tax filing platforms. The area's industrial base lags Seoul in cloud migration but shows accelerating SaaS adoption under subsidy programs.
South Korea Accounting & Budgeting Software Market Competitive Landscape
The competitive structure tilts toward ERP-anchored enterprise suites with deep integration capabilities. Chaebol-tier consolidation requirements favor vendors sustaining millisecond database latency across hundreds of legal entities. Two strategic archetypes dominate: full-stack ERP incumbents with modular financial planning extensions, and cloud-native specialists with rapid SME deployment cycles. Competitive moves concentrate on API ecosystem expansion and AI-driven forecasting module integration.
Among Germany-based enterprise software conglomerates, SAP SE anchors the full-stack archetype with deep ERP module integration. Oracle Corp. and Microsoft Corp. occupy positions emphasizing database architecture and productivity suite embedding respectively. These three exemplify how vendor differentiation converges on compliance automation and predictive algorithm deployment rather than core ledger functionality alone.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corp. |
| Microsoft Corp. |
| Intuit Inc. |
| Sage Group Plc |
| Xero Ltd. |
| Zoho Corp. |
| FreshBooks |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
K-ESG disclosure mandates gate both qualified supply and premium-tier pricing access, as vendors must embed carbon liability tracking modules to serve chaebol treasury operations while certification stacking for MFDS, KISA, and NTS compliance doubles engineering overhead passed through to enterprise buyers.
Pricing Analysis
Value-based pricing anchored to audit trail completeness and real-time consolidation throughput dominates enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels separates air-gapped private cloud instances from multi-tenant SaaS bundles. Cost compression in the mid-market tier is intensifying because regional IT service providers aggregate demand into negotiated reseller packages. Small enterprises in Daejeon and Daegu digitization centers show highest price sensitivity, while Yeouido securities firms accept premium positioning for millisecond latency specifications.
Supply Chain Analysis
Freight costs for on-premise server hardware from Taiwan, Japan, and the United States elevate total cost of ownership for legacy-dependent conglomerates. Cloud infrastructure draws from hyperscaler data centers in South Korea, Singapore, and Japan, with API integration modules resting on software development talent concentrated in Seoul and Bangalore. Single-source vulnerability around KISA-certified cybersecurity engineering creates procurement bottlenecks stretching certification timelines. Distribution runs through regional IT service providers consolidating vendor relationships into unified procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification stacking burdens are forcing architectural fragmentation that favors well-capitalized incumbents with dedicated compliance engineering teams, squeezing mid-market vendors unable to sustain parallel BIS, KISA, and NTS qualification roadmaps.
For Market Incumbents: Anchor market position through backward integration into KISA-certified cybersecurity audit services, capturing recurring compliance revenue streams. Deepen ERP module entrenchment at chaebol subsidiaries by embedding AI-driven forecasting within existing treasury workflows. The threat of cloud-native specialists with rapid SME deployment cycles demands defensive API ecosystem expansion to lock in integration switching costs. For New Entrants and Emerging Players: Launch via government-backed digitization centers in Busan-Ulsan and Daegu-Gyeongbuk, where industrial corridor demand remains underserved by enterprise-grade platforms. Target mid-sized manufacturers with 100-500 employees through vertical-specific variance analysis modules. The most penetrable segment is Gyeonggi Province manufacturing SMEs piloting natural language processing interfaces for financial reporting. For Investors and Strategic Acquirers: KISA cybersecurity certification completion announcements are the leading indicator that a vendor has unlocked public sector procurement eligibility and defensible revenue visibility. Long-term viability favors platforms with hybrid architecture capabilities bridging legacy on-premise tax modules with certified cloud general ledgers. Acquisition target archetype: regional IT service providers with consolidated reseller bundles and captive SME customer bases.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP module entrenchment locks chaebol subsidiaries into switching-cost-heavy ecosystems. |
| Acquisition of Specialist Firm | KISA-certified cybersecurity boutiques unlock public sector procurement windows frozen by certification bottlenecks. |
| Geographic Expansion | Busan-Ulsan industrial corridor penetration captures underserved shipbuilding and port logistics demand. |
| Strategic Partnership | Regional IT service provider alliances aggregate SME demand into defensible reseller revenue streams. |
| Product Launch | AI-native forecasting modules embedded in spreadsheet interfaces unify predictive analytics with familiar Korean office workflows. |
Research Methodology
Independent corroboration across primary interviews with CFOs, IT procurement officers, platform engineers, and channel partners, combined with secondary validation through MFDS certification databases, KISA cybersecurity framework disclosures, NTS e-invoicing API specifications, and hyperscaler capex filings, underwrites the qualitative findings. Bottom-up segment sizing triangulates against top-down market envelope estimates derived from government digitization subsidy disbursement records.
Comparable-period anchoring to historical adoption curves across the projection horizon informs the analytical framework. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity with legacy ERP systems, and regional adoption pattern within South Korea. CAGRs derive from fitted growth curves incorporating PIPC enforcement trajectory assumptions and K-ESG mandate implementation pace. Industry-specific inputs encompass chaebol subsidiary procurement cycle timing and regional government subsidy allocation patterns.
PIPC enforcement action severity, KISA certification timeline compression, and K-ESG disclosure mandate scope expansion are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
UAE Forensic Accounting Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Accounting Services Market