
 Global Tax and Accounting Software Market | 2026-2036
Global Tax and Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tax and Accounting Software Market Foresight
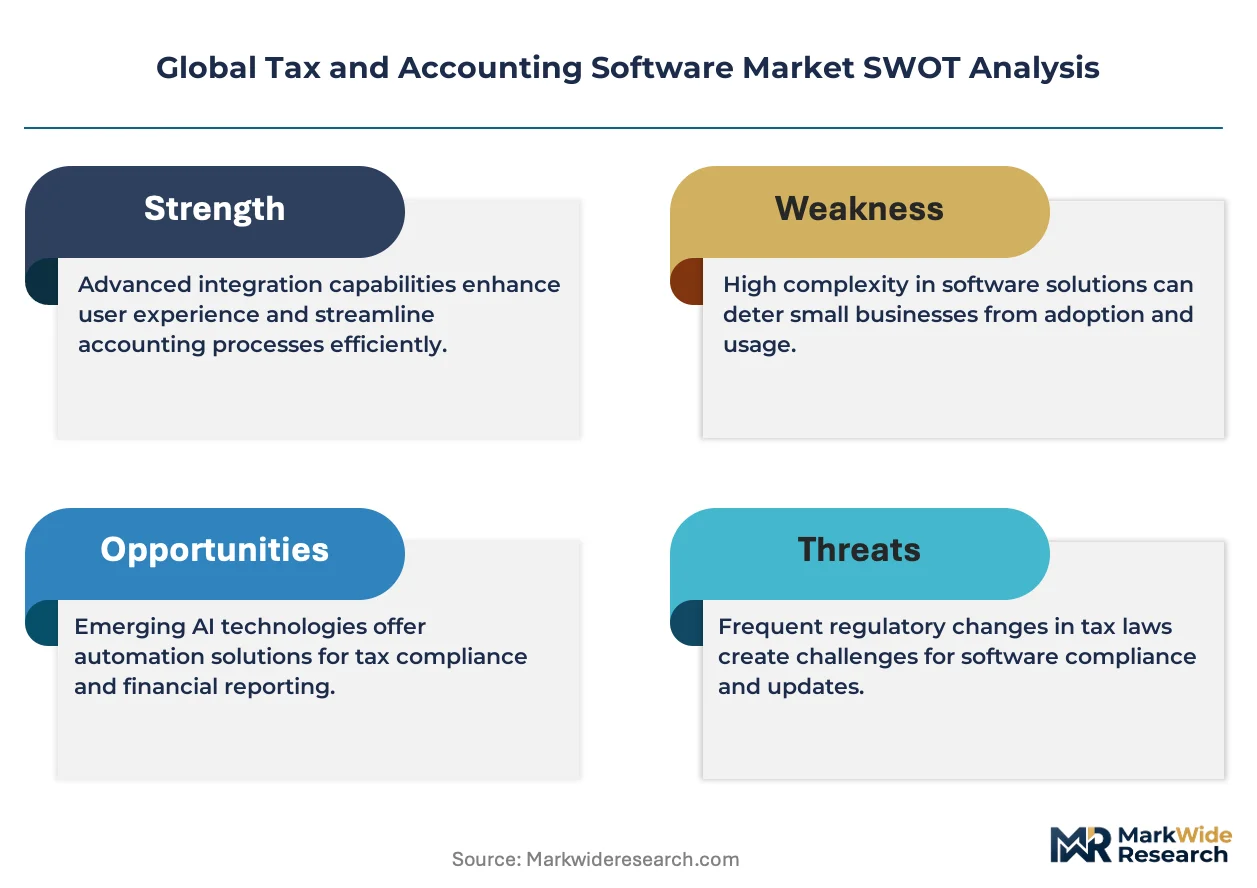
Certified public accountant shortages across developed economies is reorganizing how enterprises source financial compliance, pushing demand toward platforms that automate complex workflows. Intuit leverages its consumer-to-small-business channel density to cross-sell advanced tax modules. Thomson Reuters anchors professional-grade research and compliance content directly into its accounting suites. SAP dominates enterprise resource planning integrations that feed general ledger data into tax engines.
Tax and accounting software comprises modular applications that perform automated ledger reconciliation, multi-jurisdiction tax computation, and regulatory report generation using rule-based engines and structured data protocols. These systems process transactional records through chart-of-account hierarchies to produce statutory filings and management dashboards. Cloud-based deployment leads volume as accounting firms abandon server maintenance for browser-accessible platforms with automatic regulatory patch updates. Payroll software sustains premium pricing due to its direct tie to employment law penalties and real-time filing deadlines. Financial analytics modules within accounting management software represent the fastest-expanding feature category as controllers demand predictive cash-flow modeling.
The IRS in the United States, HMRC in the United Kingdom, and the EU's VAT Information Exchange System collectively shape product roadmaps by mandating digital submission formats and audit trail standards. India's GST Network and Brazil's Nota Fiscal Eletronica impose similarly granular e-invoice rules that vendors must encode into compliance logic. Stakeholders should monitor which jurisdictions next mandate continuous transaction controls, as these regimes determine where software localization investments yield captive market positions.
Market Dynamics
Real-time compliance mandates from revenue authorities are compressing software refresh cycles, forcing enterprises to abandon legacy on-premise installations for continuously updated cloud architectures that embed regulatory logic at the infrastructure layer.
Growth Catalysts
- EU CSRD Mandates:Corporate Sustainability Reporting Directive disclosure rules require granular emissions and social metric tracking, expanding module attach rates for environmental accounting suites.
- India GST Network:E-invoice matching and automated return pre-population create captive demand for certified GST software among mid-market enterprises.
- Embedded AI Engines:Machine learning anomaly detection for transaction classification reduces manual reconciliation hours, accelerating controller adoption of intelligent automation platforms.
Market Restraints
- Cloud Concentration Risk:Three hyperscale providers dominate secure hosting for financial data, creating single-point-of-failure exposure for compliance continuity.
- Localization Cost Burden:Jurisdiction-specific tax code maintenance requires dedicated engineering pods, elevating total cost of ownership for multi-country deployments.
- API Standard Fragmentation:Incompatible data exchange protocols between ERP systems and tax engines force expensive custom integration projects.
Strategic Opportunities
- Brazil Nota Fiscal Eletrônica Expansion:Mandated e-invoice adoption across state governments creates whitespace for compliance software vendors with embedded digital certificate management.
- Continuous Transaction Controls:Real-time VAT reporting regimes in Italy, Spain, and Poland reward vendors that pre-integrate with national clearance platforms.
- Embedded Finance Convergence:Banking-as-a-Service APIs merging with accounting workflows enable automated reconciliation for neobanks and fintech lenders.
Industry Challenges
- CPA Talent Scarcity:Shrinking qualified accountant pools in the United States, United Kingdom, and Germany strain vendor implementation and support capacity.
- Legacy ERP Migration Friction:Decades-old general ledger systems resist API-based connectivity, prolonging deployment timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tax and Accounting Software Market |
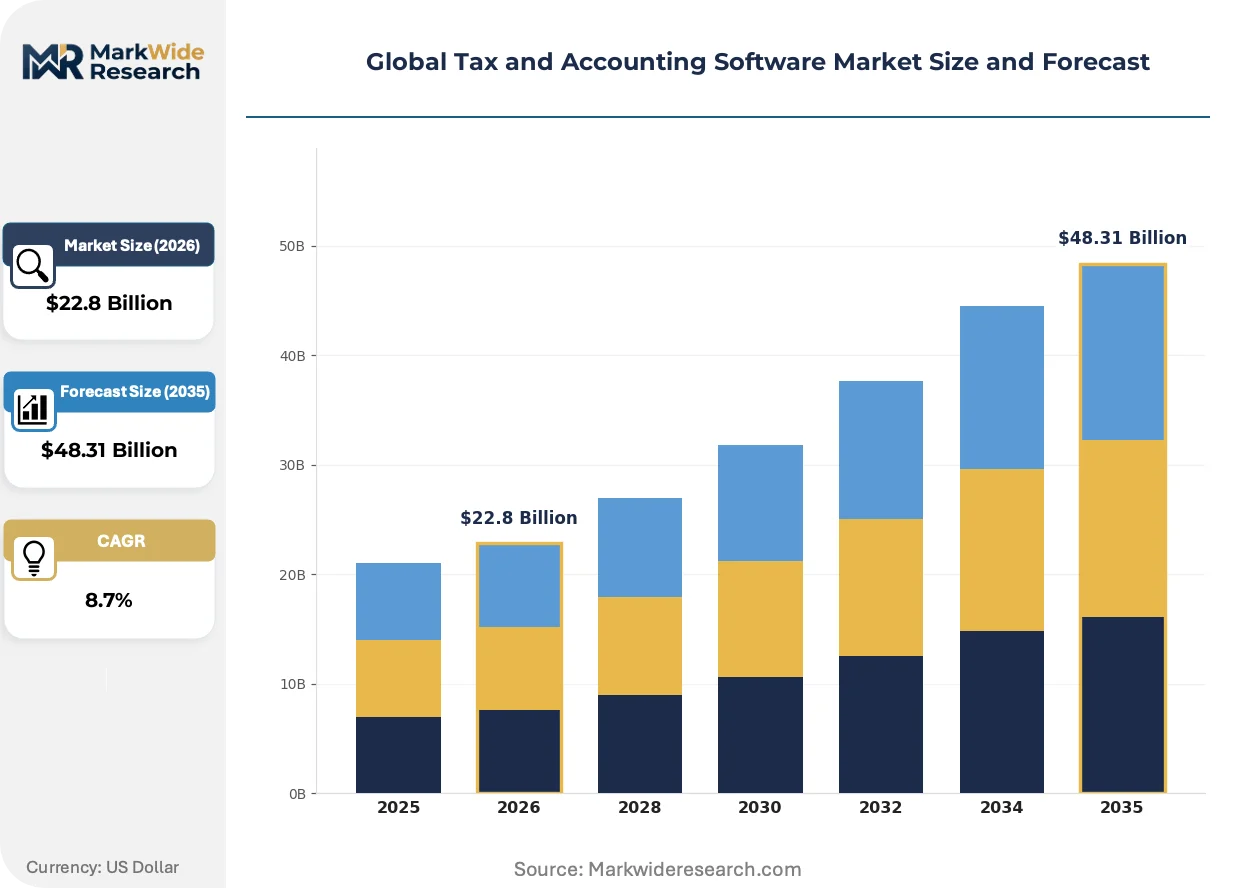
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $48.31 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tax Compliance Software, Accounting Management Software, Payroll Software, Audit Software, Financial Reporting Software Deployment: Cloud-Based, On-Premise, Hybrid, Hosted End User: Small & Medium Enterprises, Accounting Firms, Corporations, Non-Profit Organizations, Freelancers Feature: Automated Tax Filing, Financial Analytics, Multiple Currency Support, Integration Capabilities, Real-Time Updates |
| Companies Covered | Wolters Kluwer, Xero, Intuit, TaxSlayer, Vertex, Avalara, SAP, Microsoft, Thomson Reuters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tax and Accounting Software Market Shifts & Advancements
Artificial intelligence architectures are compressing the latency between transaction capture and compliance decision-making, while regulatory digitization programs embed software vendors deeper into state revenue infrastructure.
Natural language processing for contract analysis is miniaturizing the extraction of tax-relevant clauses from unstructured documents. Mid-market accounting firms in Germany and the United States are deploying these tools to accelerate due diligence and transfer pricing documentation. This capability is compressing the billable hour model for compliance advisory services.
CSRD sustainability disclosure rules from the European Commission mandate machine-readable XBRL tagging for environmental metrics. Software vendors must embed ESG data collection modules directly into general ledger workflows. Enterprise controllers in France and the Netherlands are prioritizing platforms with pre-built CSRD report templates.
Subscription pricing for compliance modules is displacing perpetual license arrangements among accounting firms with variable client loads. Tiered usage models tied to transaction volume or entity count reduce upfront capital requirements. This shift is most visible in the United Kingdom and Australia where mid-tier practices face margin pressure from automated competitor offerings.
Global Tax and Accounting Software Market Segmentation
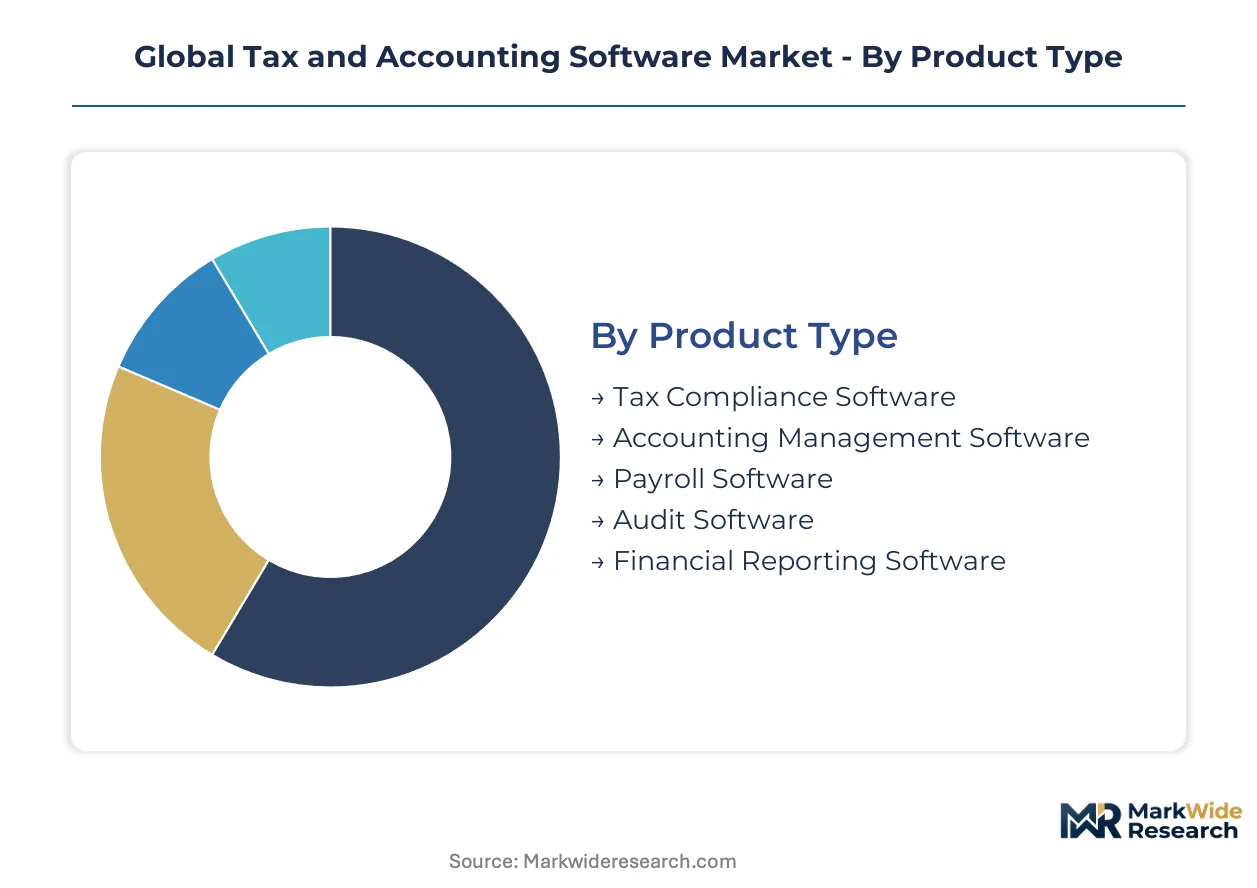
Tax and accounting software segments diverge sharply by buyer sophistication and regulatory exposure. Deployment choices determine refresh cycles, while feature priorities reflect jurisdictional complexity and staff technical capacity.
Product Type:
Domestic compliance dominates volume in the United States, Germany, and India where local tax code density rewards specialized modules. Export-led demand concentrates in audit and financial reporting suites serving multinational clients.
- Tax Compliance Software:Rule-based engines compute multi-jurisdiction liabilities using embedded regulatory logic updated via cloud patches. Demand concentrates among mid-market enterprises in India and Brazil facing real-time VAT digitization mandates and penalty exposure for filing errors.
- Accounting Management Software:General ledger platforms with chart-of-account hierarchies process transactional records into statutory filings and management dashboards. German and United States accounting firms deploy these systems to offset CPA talent scarcity through automated reconciliation workflows.
- Payroll Software:Employment law compliance modules with real-time filing deadlines.
- Audit Software:Anomaly detection and documentation tools for external assurance.
- Financial Reporting Software:XBRL-tagged disclosure generation for investor and regulatory audiences.
Accounting Management Software holds the largest share; momentum sits with Tax Compliance Software as real-time reporting regimes expand.
Deployment:
Cost tier stratification separates hyperscale cloud subscriptions from capital-intensive on-premise installations requiring dedicated IT staff.
- Cloud-Based:Browser-accessible platforms with automatic regulatory patch updates eliminate server maintenance overhead. United Kingdom and Australian mid-tier accounting firms favor this model for variable client load flexibility and reduced upfront capital requirements.
- On-Premise:Locally installed systems with direct data sovereignty control. Financial institutions in Germany and Switzerland maintain these deployments for GDPR-sensitive ledger data and custom integration with legacy core banking systems.
- Hybrid:Split architectures keeping sensitive payroll data on-premise while routing analytics to cloud.
- Hosted:Third-party managed infrastructure with single-tenant isolation.
Cloud-Based deployments command volume leadership; Hybrid architectures are climbing the fastest among regulated sectors.
End User:
Customer type determines feature depth, with corporations demanding ERP integration and freelancers prioritizing mobile accessibility.
- Corporations:Enterprise-grade platforms with multi-entity consolidation and transfer pricing documentation. French and Dutch controllers prioritize these systems for CSRD sustainability disclosure compliance and pre-built ESG report templates.
- Accounting Firms:Practice management suites with client portal access and billable hour tracking. Mid-market firms in Germany and the United States deploy AI-powered contract analysis to compress due diligence timelines.
- Small & Medium Enterprises:Simplified modules with automated bank reconciliation.
- Non-Profit Organizations:Fund accounting with grant compliance and donor restriction tracking.
- Freelancers:Mobile-first expense capture and quarterly estimated tax calculators.
Corporations drive premium pricing; Accounting Firms represent the steepest expansion trajectory as CPA shortages deepen outsourcing demand.
Feature:
Maturity varies by capability, with basic automation commoditized and predictive analytics emerging as a differentiation layer.
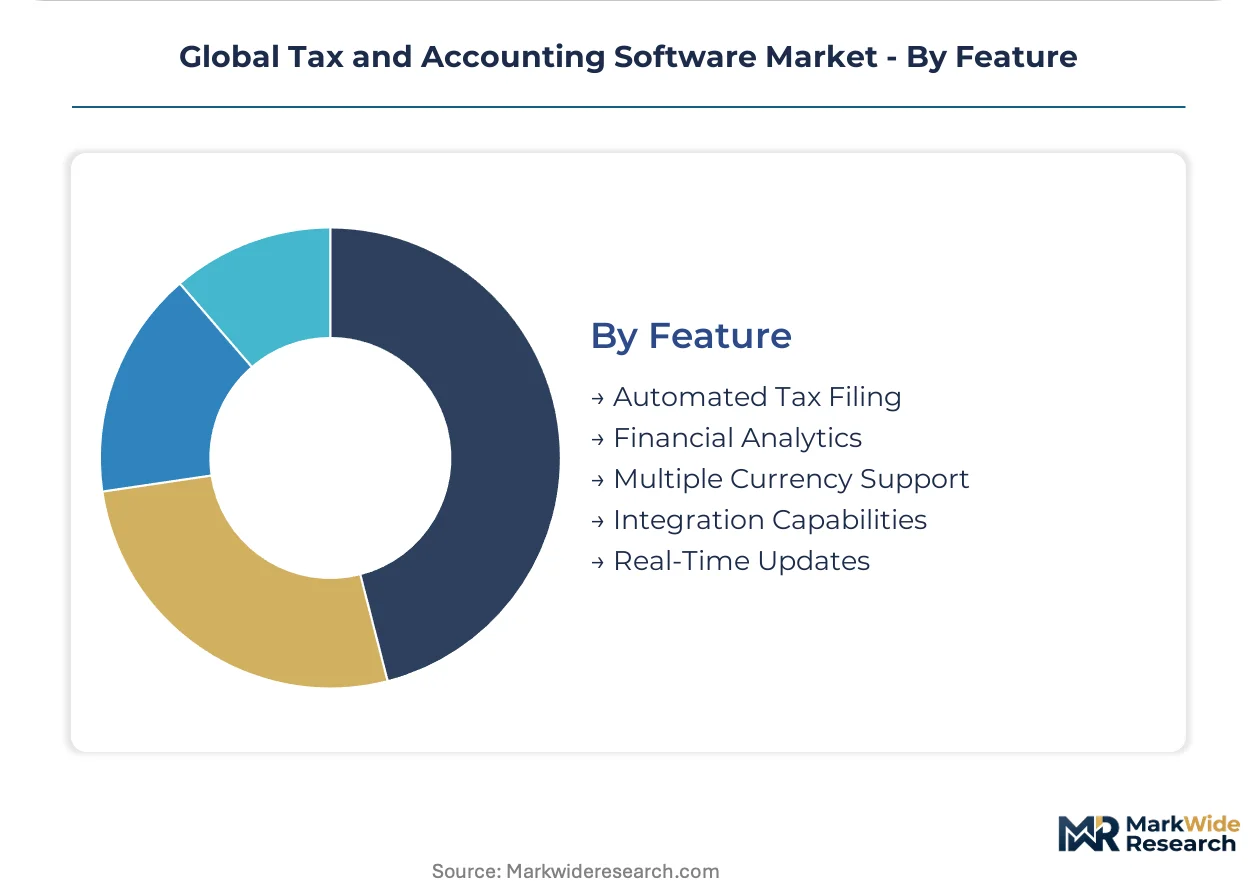
- Financial Analytics:Predictive cash-flow modeling and variance analysis using machine learning on historical ledger patterns. Controllers in the United States and Germany prioritize these modules for working capital optimization and scenario planning.
- Automated Tax Filing:Direct API submission to IRS, HMRC, and EU VAT Information Exchange System with audit trail generation. Indian mid-market enterprises require this capability for GST Network e-invoice matching and automated return pre-population.
- Multiple Currency Support:Real-time exchange rate feeds and hedging impact calculations.
- Integration Capabilities:Pre-built connectors to SAP, Oracle, and Salesforce ecosystems.
- Real-Time Updates:Continuous regulatory logic deployment without version migration.
Automated Tax Filing anchors baseline expectations; Financial Analytics is gaining share fastest as controllers demand forward-looking intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRS mandates digital submission formats and audit trail standards that anchor software product roadmaps across the United States. Revenue authorities in Germany, India, Brazil, and the United Kingdom impose similarly granular compliance rules that determine where localization investments yield captive market positions.
United States
Mid-market enterprises and accounting firms drive cloud migration to offset CPA talent scarcity. The IRS mandates direct API submission protocols and machine-readable audit trails. Silicon Valley and New York City host dense clusters of fintech-accounting convergence startups embedding automated reconciliation into banking workflows.
Germany
Financial institutions and industrial manufacturers prioritize on-premise deployments for GDPR-sensitive ledger data. The GoBD principles mandate immutable audit trails and digital document retention standards. Frankfurt and Munich concentrate enterprise software vendors pre-integrating CSRD sustainability modules for EU disclosure compliance.
India
Mid-market enterprises face captive demand for certified GST software due to e-invoice matching mandates. The GST Network imposes automated return pre-population and real-time transaction reporting. Bangalore and Hyderabad anchor SaaS development clusters serving domestic compliance automation and export-oriented accounting platforms.
Brazil
State governments expand mandated e-invoice adoption, creating whitespace for compliance vendors with embedded digital certificate management. The Nota Fiscal Eletrônica system requires granular transaction-level clearance before commercial issuance. São Paulo concentrates both legacy ERP system integrators and emerging cloud-native tax engine providers.
United Kingdom
Mid-tier accounting practices adopt subscription pricing models to reduce upfront capital requirements amid margin pressure. HMRC mandates Making Tax Digital protocols for VAT-registered businesses above threshold turnover. London anchors professional services technology clusters deploying AI-powered contract analysis for due diligence compression.
Global Tax and Accounting Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the market structure. The vendor base stratifies into three tiers: hyperscale cloud platforms with embedded regulatory logic, specialized tax engine providers with jurisdiction-specific compliance depth, and verticalized accounting suites serving practice management workflows. Dominant competitive moves include strategic partnerships with national clearance platforms and portfolio diversification into ESG reporting modules.
Among Netherlands-based professional information services groups, Wolters Kluwer exemplifies the specialized compliance content archetype. New Zealand-founded Xero and United States-based Intuit occupy positions within the cloud-native accounting suite tier, representing the shift toward browser-accessible platforms with automatic regulatory patch updates. These anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across the technology-cost spectrum.
| Leading Market Players |
|---|
| Wolters Kluwer |
| Xero |
| Intuit |
| TaxSlayer |
| Vertex |
| Avalara |
| SAP |
| Microsoft |
| Thomson Reuters |
| Others |
Supply & Pricing Matrix
Cloud-native infrastructure substitution for legacy on-premise deployments simultaneously relocates supply geography toward hyperscale data center clusters in the United States, Ireland, and Singapore while compressing pricing economics through elimination of perpetual license premiums and server maintenance overhead.
Pricing Analysis
Geographic price spreads between North American and South Asian markets reach three-to-one multiples for equivalent compliance modules. Subscription SaaS-tiered pricing dominates as accounting firms abandon capital-intensive perpetual licenses for usage-based models tied to transaction volume or entity count. Price differentiation rests on certification depth—GST Network-certified engines in India command premiums over uncertified alternatives—and vertical integration with national clearance platforms. Pricing pressure stems from mid-market margin compression in the United Kingdom and Australia, where automated competitor offerings force subscription rate reductions. Small and medium enterprises exhibit highest price sensitivity, while multinational corporations absorbing CSRD compliance costs show lowest elasticity.
Supply Chain Analysis
API standard fragmentation between ERP systems and tax engines creates integration chokepoints that prolong deployment timelines and inflate professional services costs. Engineering talent concentrates in India, Ireland, and Poland, where regulatory technology development clusters feed product localization pipelines. Raw material dependencies center on cloud compute capacity from hyperscale providers, cryptographic digital certificate infrastructure for e-invoice clearance, and machine learning training data for anomaly detection engines. Supply chain risk manifests as single-source vulnerability: three hyperscale providers dominate secure financial data hosting. Distribution runs through direct enterprise sales for large implementations, channel partners for mid-market penetration, and self-serve platforms for freelance and micro-business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on banking-as-a-service API convergence with accounting workflows, where interoperability standards determine which vendors capture automated reconciliation value from neobanks and fintech lenders.
For Market Incumbents: Secure regulatory certification moats by pre-integrating with national clearance platforms in Italy, Spain, and Poland before continuous transaction controls expand. Defend against cloud-native entrants by embedding AI-powered contract analysis into existing client workflows, raising switching costs for German and United States accounting firms facing CPA talent scarcity. Prioritize backward integration into ESG data collection modules as CSRD sustainability disclosure mandates attach environmental accounting to core general ledger systems. For New Entrants and Emerging Players: Lead with whitespace targeting of Brazil's Nota Fiscal Eletrônica expansion across state governments, where embedded digital certificate management capabilities remain undersupplied by legacy ERP integrators. Concentrate on mid-market enterprises in India facing captive demand for certified GST software due to e-invoice matching mandates. Deploy API-first architectures that bypass custom integration friction plaguing incumbent offerings. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed tax engine specialists holding jurisdiction-specific compliance depth but lacking cloud-native delivery infrastructure. Long-term viability across a five-to-ten year window favors vendors with embedded regulatory logic at the infrastructure layer rather than application-layer compliance tools. Acquisition target archetype: specialized providers with pre-built CSRD report templates and EU VAT Information Exchange System connectivity. Monitor which revenue authorities next mandate real-time transaction reporting as the inflection indicator for localization investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Banking-as-a-Service API convergence enables automated reconciliation capture from neobanks and fintech lenders. |
| Regulatory Certification Investment | GST Network certification in India and Nota Fiscal Eletrônica clearance in Brazil create captive market positions. |
| Strategic Partnership | Pre-integration with national clearance platforms in Italy, Spain, and Poland rewards continuous transaction control readiness. |
| Acquisition of Specialist Firm | ESG data collection module providers gain value as CSRD mandates embed environmental accounting into general ledger workflows. |
| Geographic Expansion | Localization engineering pods in India, Ireland, and Poland reduce jurisdiction-specific tax code maintenance costs. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers at mid-market accounting firms, IT procurement officers at multinational corporations, platform engineers at cloud-native software vendors, and integration specialists at ERP system implementers, then refined against secondary validation from SEC filings, hyperscaler capex disclosures, App Annie enterprise software adoption data, and EU regulatory mandate documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from customs records and professional services trade data.
Variance decomposition across the projection horizon isolates growth contributions from deployment model shifts, regulatory mandate timing, and AI capability adoption curves. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional adoption pattern. CAGRs were derived from logistic diffusion curves fitted to historical cloud migration rates and regulatory compliance deadline clustering. Forecast inputs center on IRS digital submission protocol mandates, EU CSRD disclosure phase-in schedules, and India GST Network e-invoice penetration trajectories.
Underlying assumptions cover sustained CPA talent scarcity in developed economies, hyperscale cloud provider market stability, and regulatory digitization program continuity, with deviation risk concentrated in abrupt API standard unification, single-source cloud infrastructure failures, or revenue authority mandate delays. Practitioners should keep alternative scenarios live as continuous transaction control regime expansion and banking-as-a-service interoperability standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
UAE Forensic Accounting Market
Accounting and Taxation Services
AI in Accounting Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Tax Management Software Market