
 China Accounting & Budgeting Software Market | 2026-2036
China Accounting & Budgeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
China Accounting & Budgeting Software Market Insights
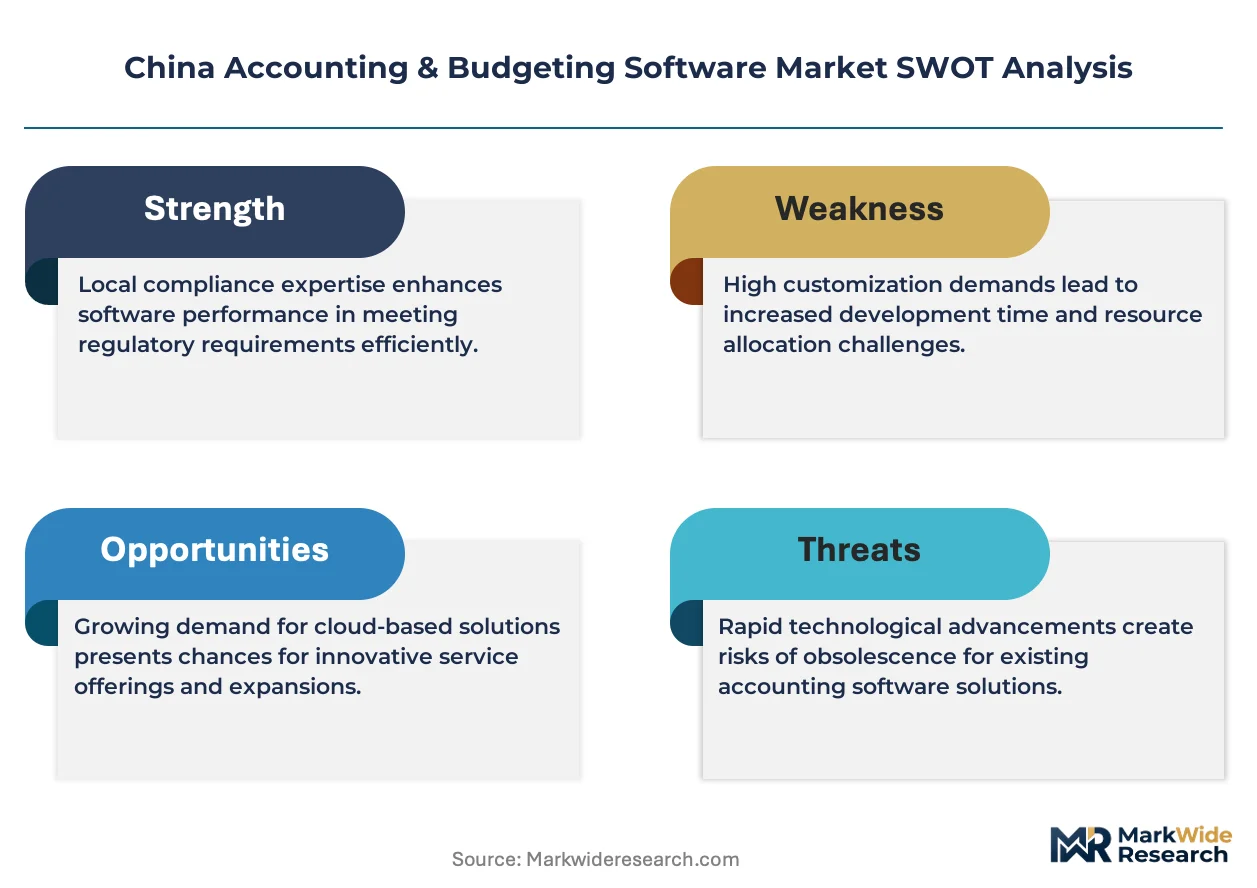
Cloud infrastructure is restructuring on-premise software economics across China's accounting software sector. Kingdee International Software Group Company Limited leverages its SaaS-native architecture to dominate mid-market conversions. Yonyou Network Technology Co., Ltd. anchors government and SOE contracts through deep localization. SAP SE competes at the multinational subsidiary tier where cross-border reporting complexity demands international compliance engines.
Accounting and budgeting software comprises modular enterprise applications that automate general ledger consolidation, real-time budget variance analysis, and multi-entity financial reporting through API-connected databases. Cloud-based deployment leads revenue contribution as MIIT cloud computing directives push state-linked firms off legacy servers. SME-targeted functionality represents the fastest-expanding segment because tax compliance automation reduces manual filing burdens for smaller entities with limited in-house finance staff.
MIIT cloud computing guidelines, SAMR data security standards, and GB/T financial software certification collectively shape product roadmaps and market access requirements for domestic vendors. Foreign suppliers must navigate SAMR cybersecurity review processes before deploying cloud-hosted accounting platforms within mainland infrastructure. Stakeholders should monitor evolving cross-border data flow restrictions that could bifurcate product architectures between domestic-only and international-compatible editions.
Market Dynamics
MIIT cloud computing directives are compressing deployment timelines for state-owned enterprises, forcing legacy on-premise accounting systems toward SaaS-native architectures within mandated windows. This regulatory pressure cascade is restructuring vendor competitive dynamics across procurement cycles.
Growth Catalysts
- MIIT Digital Transformation Mandates:State-owned enterprises face compulsory cloud migration timelines, creating immediate procurement pull for compliant accounting platforms. SOE IT budgets are reallocating toward SaaS-native vendors.
- Tax Compliance Automation:SME demand concentrates in automated VAT filing and real-time invoice verification modules. Smaller entities with limited finance staff prioritize reduction of manual filing burdens.
- Shanghai-Shenzhen Financial District Concentration:Enterprise software procurement budgets have expanded most aggressively in these clusters, driving regional vendor salesforce deployment and localized feature development.
Market Restraints
- SAMR Cybersecurity Review Friction:Foreign cloud-hosted accounting platforms face mandatory pre-deployment review processes, extending sales cycles and creating compliance cost asymmetry against domestic vendors.
- Cross-Border Data Flow Restrictions:Evolving rules on financial data localization are bifurcating product architectures, forcing vendors to maintain separate domestic-only and international-compatible codebases.
- GB/T Certification Requirements:Domestic vendors must achieve national financial software certification standards, creating fixed compliance costs that disadvantage smaller entrants against established players.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area:Cross-border financial reporting complexity in this sub-region creates demand for multi-currency, multi-entity consolidation tools with simplified Chinese-traditional Chinese interface flexibility.
- Carbon Accounting Module Integration:Dual carbon goals are extending budgeting software scope into emissions tracking and carbon cost allocation, opening adjacent functionality expansion.
- API-First Ecosystem Architecture:Open banking interfaces and tax bureau direct connection protocols are enabling vertical solution stacking, allowing specialized vendors to embed accounting modules within industry-specific workflows.
Industry Challenges
- Legacy System Integration Complexity:SOE finance departments operate decades-old ERP installations with custom data schemas, requiring expensive middleware development for cloud platform connectivity.
- Cross-Functional Talent Scarcity:Implementation teams must combine accounting domain expertise with cloud architecture skills, a combination that remains undersupplied in regional labor markets outside tier-one cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Accounting & Budgeting Software Market |
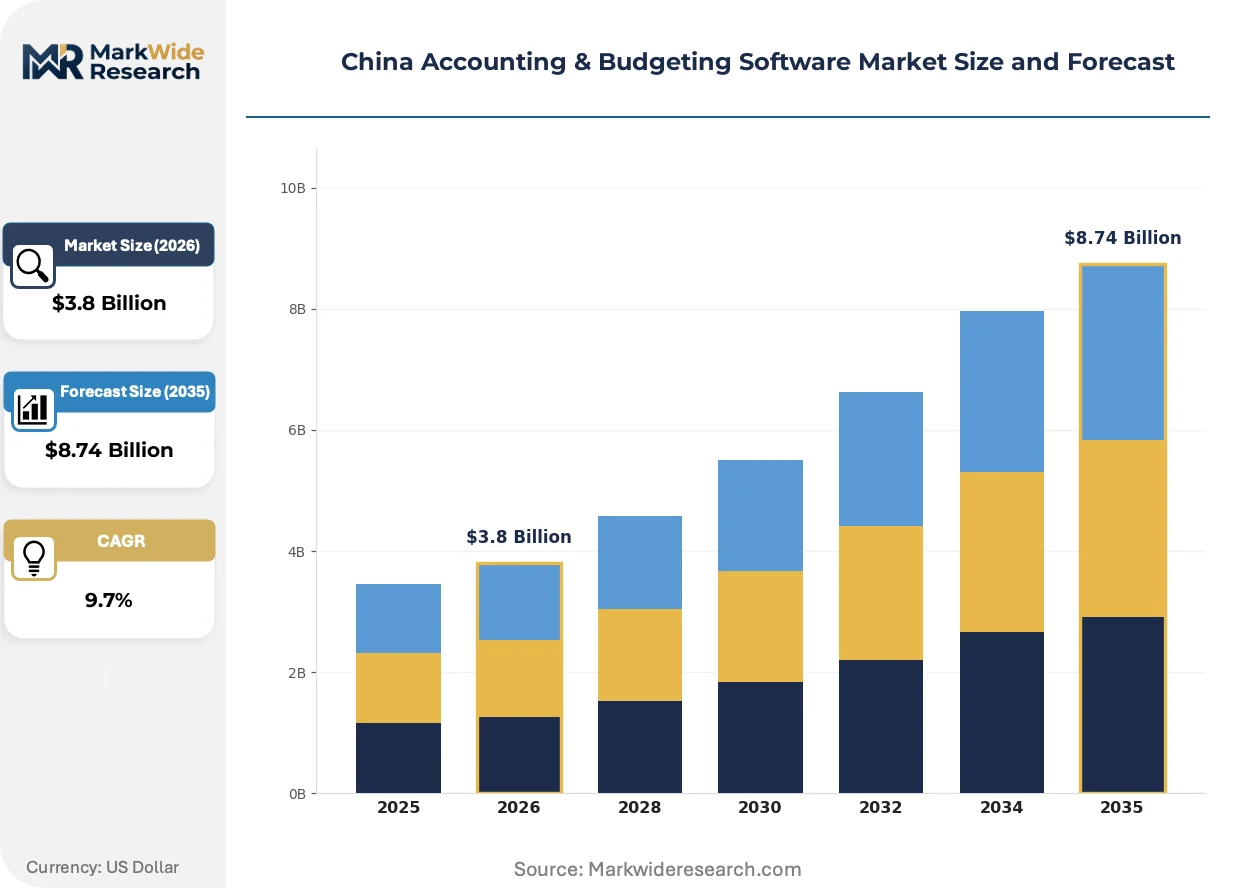
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-premise, Cloud-based, Hybrid, Web-based Target User: SMEs, Large Enterprises, Freelancers, Accounting Firms Functionality: Expense Management, Payroll Processing, Financial Reporting, Tax Compliance Regulatory Compliance: GAAP, IFRS, Local Regulations, Tax Codes |
| Companies Covered | Kingdee International Software Group Company Limited, Yonyou Network Technology Co., Ltd., Inspur, SAP SE, Oracle Corporation, Microsoft Corporation, Zoho Corporation, Xero Limited, Intuit Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Accounting & Budgeting Software Market Trends and Innovations
Artificial intelligence is embedding into core accounting workflows, compressing the traditional month-end close cycle and automating variance analysis that previously required manual intervention. This technological infusion is redrawing feature differentiation and pricing power across vendor tiers.
Natural language processing is electrifying invoice processing and contract review workflows. Mid-market finance teams are adopting intelligent document extraction at accelerating rates, replacing manual data entry with automated GL coding. This capability compression is collapsing the traditional advantage of large in-house accounting departments.
SAMR data security standards are tightening audit trail and encryption requirements for cloud-hosted financial platforms. Vendors must implement enhanced logging architectures and domestic key escrow mechanisms to maintain operational licenses. Foreign multinational subsidiaries are most affected, driving demand for international-compliant editions with segregated data residency.
Subscription pricing is displacing perpetual license models across buyer segments, unbundling implementation and support services into separate line items. SME procurement teams are favoring monthly payment structures that align software costs with cash flow cycles. This preference shift is most visible in Jiangsu and Zhejiang manufacturing clusters where working capital management dominates software evaluation criteria.
China Accounting & Budgeting Software Market Segmentation
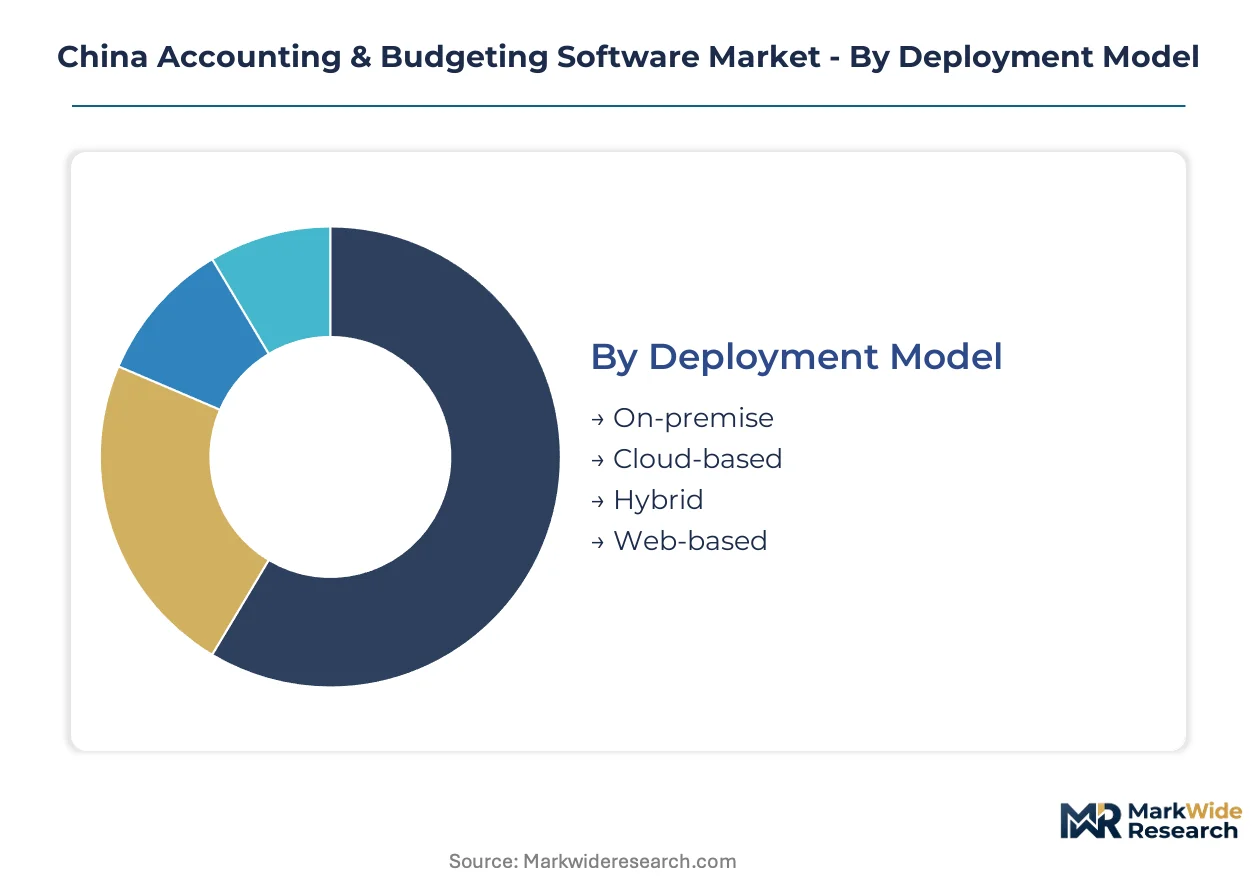
Segmentation in China's accounting software sector reveals how MIIT cloud directives and SAMR certification requirements create divergent compliance burdens across deployment architectures. Procurement patterns bifurcate sharply between state-owned enterprises facing mandatory SaaS migration and private firms retaining legacy flexibility.
Deployment Model:
MIIT cloud computing guidelines impose distinct certification timelines: cloud-native platforms require SAMR cybersecurity review before deployment, while on-premise installations face GB/T financial software standards but bypass cross-border data flow restrictions.
- On-premise:Legacy server installations persist in defense-related SOEs and classified government units where data sovereignty mandates physical infrastructure control. Beijing and Chengdu aerospace clusters maintain these deployments despite rising maintenance costs.
- Cloud-based:SaaS-native architectures dominate new procurement under MIIT digital transformation mandates, with vendors hosting on domestic Alibaba Cloud or Tencent Cloud infrastructure to satisfy data localization requirements. Shanghai financial district firms are converting fastest due to compressed regulatory deadlines.
- Hybrid:Mixed deployments segment sensitive general ledger functions on-premise while routing payroll and expense modules through cloud pipelines. Manufacturing clusters in Jiangsu favor this architecture for operational continuity during network interruptions.
- Web-based:Browser-accessible platforms without full cloud backend integration serve micro-enterprises and individual practitioners seeking low-friction entry points. These lack SAMR certification for SOE procurement eligibility.
Leading the category by volume: Cloud-based. Expanding most quickly: Hybrid.
Target User:
Cost tier stratification separates enterprise-grade platforms with implementation services from self-serve offerings, with pricing multiples spanning an order of magnitude across user categories.
- SMEs:Automated VAT filing and invoice verification modules reduce manual compliance burdens for finance teams with under five staff. Zhejiang manufacturing SMEs prioritize monthly subscription pricing to align software costs with working capital cycles.
- Large Enterprises:Multi-entity consolidation and cross-border reporting engines serve multinational subsidiaries and listed SOEs. These buyers mandate API connectivity to existing ERP investments and domestic key escrow for encryption compliance.
- Freelancers:Solo practitioners and micro-businesses utilize stripped-down bookkeeping tools with direct tax bureau filing integration. Guangdong individual service providers drive demand for mobile-first interfaces.
- Accounting Firms:Practice management platforms with client portal architectures and multi-tenant data segregation support outsourced bookkeeping services. Shenzhen-based firms serving Hong Kong cross-border clients require simplified-traditional Chinese interface flexibility.
Volume concentration: Large Enterprises. Fastest climb: SMEs.
Functionality:
Application maturity varies sharply, with tax compliance modules achieving near-universal adoption while carbon accounting extensions remain nascent.
- Expense Management:Real-time spend tracking with corporate card integration and automated receipt capture. Beijing tech sector firms are adopting these tools fastest for distributed workforce reimbursement.
- Payroll Processing:Social insurance contribution calculations and individual income tax withholding automation tied to local HR bureau systems. Mandatory in all jurisdictions but requiring city-specific rule updates.
- Financial Reporting:General ledger consolidation, budget variance analysis, and multi-dimensional profitability reporting. Listed companies require these modules for CSRC disclosure compliance.
- Tax Compliance:Automated VAT invoice verification, real-time filing to Golden Tax System III, and audit trail documentation. This functionality achieves highest penetration due to regulatory enforcement pressure.
Widest deployment: Tax Compliance. Steepest expansion trajectory: Expense Management.
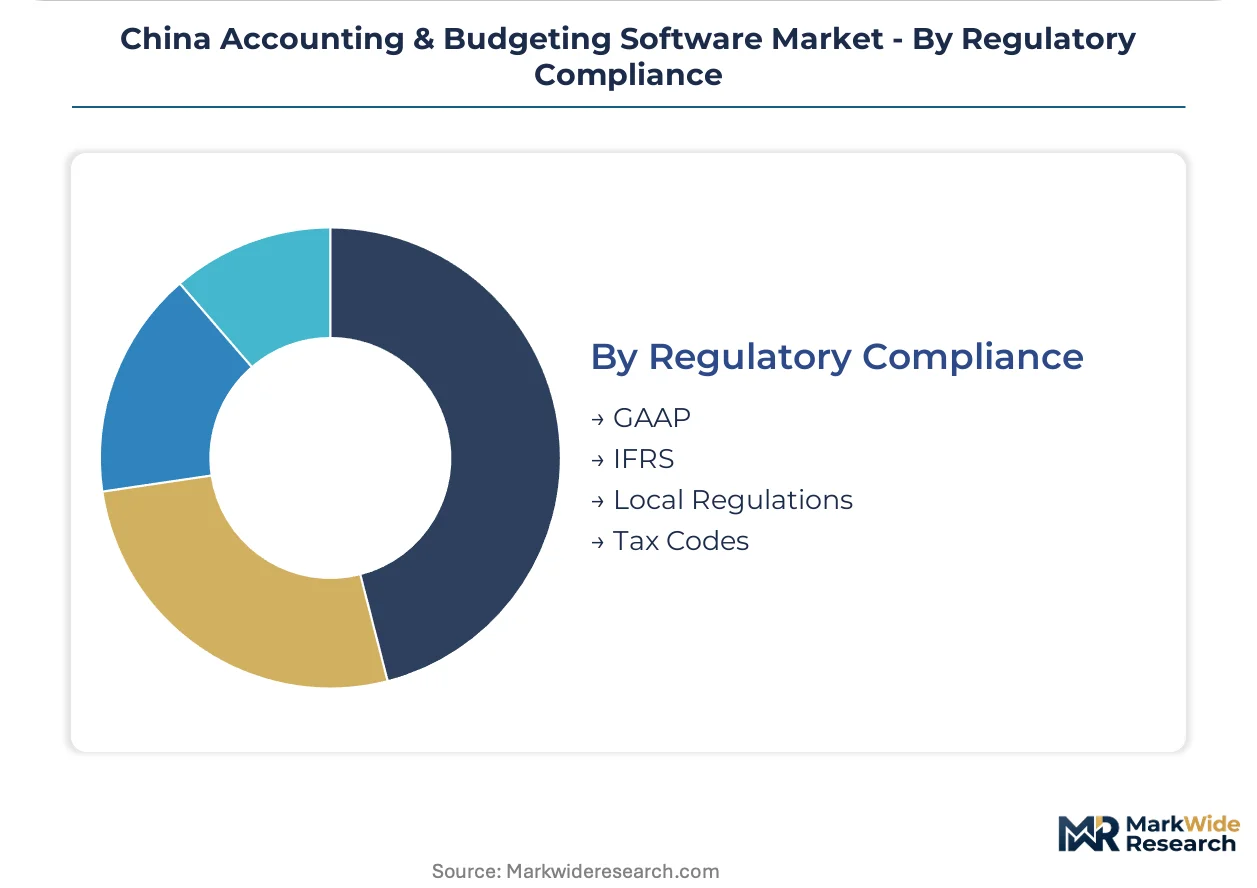
Regulatory Compliance:
Customer type determines which standards architecture buyers must satisfy, with listed entities and SOEs facing the most stringent multi-standard requirements.
- GAAP:Chinese Accounting Standards alignment for domestic financial statement preparation and CSRC filing requirements. All domestic vendors achieve this certification as table stakes.
- IFRS:International Financial Reporting Standards compatibility for dual-listed enterprises and multinational subsidiaries. Foreign vendors emphasize this capability for cross-border consolidation.
- Local Regulations:Provincial and municipal tax bureau system integrations, social insurance contribution rules, and industry-specific reporting formats. Vendors maintain regional implementation teams for these variations.
- Tax Codes:Golden Tax System III connectivity, e-fapiao processing protocols, and evolving VAT rate structures. SAMR mandates direct API certification for cloud-hosted platforms.
Universal requirement: Local Regulations. Gaining priority fastest: Tax Codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software procurement concentrates in China's coastal financial centers where MIIT cloud mandates and SOE digital transformation budgets intersect most densely.
Shanghai
Multinational headquarters and state-owned financial institutions drive demand for IFRS-compliant consolidation platforms. MIIT cloud computing directives compress deployment timelines for SOE finance departments. Lujiazui and Zhangjiang Hi-Tech Park host the densest vendor salesforce deployment in the country.
Shenzhen
Technology IPO pipelines and cross-border RMB settlement create demand for multi-entity reporting with Hong Kong interface flexibility. SAMR cybersecurity review processes shape vendor selection for cloud-hosted platforms. Nanshan District anchors the highest concentration of SaaS-native accounting deployments.
Beijing
Central government procurement and defense-related SOEs sustain hybrid deployment architectures despite cloud migration pressure. GB/T financial software certification requirements filter vendor eligibility for state contracts. Zhongguancun software clusters specialize in middleware for legacy ERP integration.
Guangdong Province
Manufacturing SME clusters in Foshan and Dongguan prioritize tax compliance automation and monthly subscription pricing. Golden Tax System III integration mandates drive module standardization across vendor offerings. The Greater Bay Area cross-border reporting complexity creates niche demand for multi-currency functionality.
Jiangsu Province
Export-oriented manufacturers in Suzhou and Wuxi favor hybrid architectures that segment sensitive GL functions on-premise while routing payroll through cloud pipelines. Working capital management dominates software evaluation criteria in these clusters. Local tax bureau system integrations require city-specific rule maintenance from vendors.
China Accounting & Budgeting Software Market Competitive Landscape
Cloud migration mandates dominate the current landscape, compressing procurement cycles and restructuring vendor competitive dynamics. The market exhibits tiered concentration with domestic SaaS-native vendors, legacy localization specialists, and multinational compliance engines occupying distinct strata. Three archetypes prevail: MIIT-compliant cloud platforms, SOE-anchored on-premise incumbents, and international-standard subsidiaries serving cross-border reporting needs. Strategic partnerships with domestic cloud infrastructure providers and API ecosystem expansion constitute the dominant competitive moves.
Among the domestic SaaS-native tier, Kingdee International Software Group Company Limited and Yonyou Network Technology Co., Ltd. occupy positions shaped by divergent customer anchoring. Kingdee exemplifies mid-market conversion velocity through cloud-native architecture, while Yonyou represents SOE and government contract concentration via deep localization capabilities. SAP SE sits within the multinational subsidiary tier where cross-border reporting complexity demands international compliance engines.
| Leading Market Players |
|---|
| Kingdee International Software Group Company Limited |
| Yonyou Network Technology Co., Ltd. |
| Inspur |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Zoho Corporation |
| Xero Limited |
| Intuit Inc. |
| Others |
Pricing and Supply Chain Analysis
State-owned enterprise procurement concentration anchors pricing discipline across China's accounting software sector, with MIIT cloud migration mandates compressing vendor negotiation timelines while domestic infrastructure providers capture recurring hosting revenue. SaaS-native vendors leverage this buyer consolidation to enforce subscription pricing that aligns with SOE budget cycles, while legacy on-premise incumbents face margin compression from middleware integration costs.
Pricing Analysis
Volume concentrates in mid-market SaaS tiers where Kingdee and Yonyou compete on monthly subscription rates, while premium enterprise contracts with multinational subsidiaries sustain higher per-seat pricing through IFRS compliance bundling. Price differentiation hinges on SAMR certification tier and API integration depth, with unbundled implementation services commanding separate fees. Cost compression in the freelancer and micro-enterprise segment is intensifying because browser-accessible platforms lack SOE procurement eligibility, forcing vendors toward volume-dependent economics. SME procurement teams in Zhejiang manufacturing clusters exhibit highest price sensitivity, prioritizing monthly payment structures that preserve working capital; large SOE finance departments show lowest sensitivity, mandating domestic key escrow and custom middleware regardless of cost.
Supply Chain Analysis
Regional distribution centers in Shanghai and Shenzhen anchor software delivery, with vendor salesforce deployment clustering in Lujiazui and Nanshan District to compress implementation timelines. Development resources concentrate in China, with secondary engineering presence in Singapore and Bangalore supporting international edition localization. Cloud infrastructure draws from Alibaba Cloud and Tencent Cloud domestic data centers, while open-source database components and AI inference chips create import dependency exposure. Single-source vulnerability in domestic cloud infrastructure creates concentration risk for foreign multinational subsidiaries facing SAMR data localization mandates. Distribution runs through direct enterprise sales teams for large SOE contracts, with channel partners and API marketplaces serving SME self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's accounting software sector sits in a SaaS-transition phase, with cloud-native architectures displacing decades-old on-premise ERP installations under MIIT directive pressure. This technology replacement cycle compresses vendor competitive windows and restructures procurement authority toward centralized IT governance.
For Market Incumbents: Anchor SOE relationships through GB/T certification maintenance and legacy ERP middleware development, defending against SaaS-native challengers by embedding deeply in custom data schemas that resist cloud migration. Prioritize vertical integration into domestic cloud infrastructure partnerships with Alibaba Cloud and Tencent Cloud to preserve hosting revenue capture and satisfy SAMR data residency requirements. For New Entrants and Emerging Players: Capture carbon accounting module white space as dual carbon goals extend budgeting software scope into emissions tracking, where established vendors lack feature maturity. Target Guangdong-Hong Kong-Macao Greater Bay Area cross-border reporting complexity with multi-currency, simplified-traditional Chinese interface flexibility, penetrating through API-first ecosystem architecture that embeds accounting modules within industry-specific vertical workflows. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market SaaS specialists with MIIT-compliant cloud architectures in Shanghai and Shenzhen, where compressed regulatory deadlines accelerate procurement velocity. Long-term viability hinges on API ecosystem expansion and vertical solution stacking capability. Watch MIIT cloud computing guideline enforcement consistency as the inflection indicator—accelerated mandate timelines signal expanded addressable market; relaxation risks prolonging legacy system persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable embedding within Golden Tax System III workflows for SME tax compliance automation. |
| Strategic Partnership | Domestic cloud infrastructure alliances with Alibaba Cloud satisfy SAMR data localization for multinational subsidiary deployments. |
| Product Launch | Carbon accounting modules capture dual carbon goal compliance demand from listed SOEs requiring emissions cost allocation. |
| Geographic Expansion | Greater Bay Area salesforce deployment addresses cross-border RMB settlement complexity with Hong Kong interface flexibility. |
| Acquisition of Specialist Firm | Middleware developers with legacy ERP integration expertise compress SOE cloud migration timelines and reduce implementation risk. |
Research Methodology
MIIT policy circulars, SAMR certification databases, and vendor SEC filings formed the secondary backbone, supplemented by customs records of software licensing imports and hyperscaler capex disclosures revealing cloud infrastructure deployment scale. Primary interviews with SOE finance directors, IT procurement officers at multinational subsidiaries, API integration specialists, and channel partners in Shanghai and Shenzhen validated deployment timeline assumptions and pricing sensitivity thresholds. Bottom-up and top-down triangulation reconciled vendor-reported subscription metrics with aggregate procurement budget allocations from state-owned asset supervision commissions.
Bottom-up modeling segmented revenue by deployment architecture, organization size tier, and vertical industry concentration, while top-down validation cross-checked against aggregate enterprise software spending patterns in coastal financial districts. Segmentation dimensions included cloud-native versus hybrid deployment, SOE versus private enterprise ownership, and Golden Tax System III integration complexity. CAGRs were derived from regression analysis of procurement budget growth rates against MIIT mandate enforcement intensity, incorporating tax compliance automation adoption curves and carbon accounting module penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border data flow restriction evolution and potential MIIT cloud mandate relaxation. Forecasts reflect documented assumptions regarding SOE digital transformation budget continuity and SAMR cybersecurity review processing timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Japan Forensic Accounting Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
Trust Accounting Software Market
Accounting and Taxation Services
Corporate Tax Service Market