
 Global Auditing Services Market | 2026-2036
Global Auditing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Auditing Services Market Analysis
Artificial intelligence is pivoting audit economics by displacing manual sampling with continuous transaction monitoring across enterprise ERP systems. Deloitte Touche Tohmatsu Limited leverages machine-learning anomaly detection to sustain premium pricing on large-cap engagements. PricewaterhouseCoopers International Limited anchors its competitive position through proprietary AI platforms that automate control testing for multinational clients.
Auditing services encompass independent examination of financial statements, internal controls, and operational processes to provide reasonable assurance on accuracy, compliance, and risk exposure, typically following International Standards on Auditing or country-specific equivalents with mandatory rotation requirements for lead engagement partners. Financial audit engagements dominate fee pools among publicly listed clients, while operational audit demand accelerates fastest as supply-chain resilience scrutiny intensifies across manufacturing and retail verticals. Compliance audit work for healthcare sector clients generates durable recurring revenue given HIPAA, FDA quality system regulations, and state-level Medicaid integrity requirements in the United States.
The U.S. SEC enforces auditor independence rules and climate-related disclosure standards that expand assurance scope beyond traditional financial statements. The EU CSRD mandates limited assurance on sustainability reports, creating new service lines across the Big Four and mid-tier networks. India's SEBI and RBI circulars on statutory audit quality and concurrent bank audits tighten eligibility criteria, reshaping market access for domestic and global firms. Stakeholders must monitor how jurisdictional regulatory divergence affects cross-border engagement staffing models and technology platform investments.
Market Dynamics
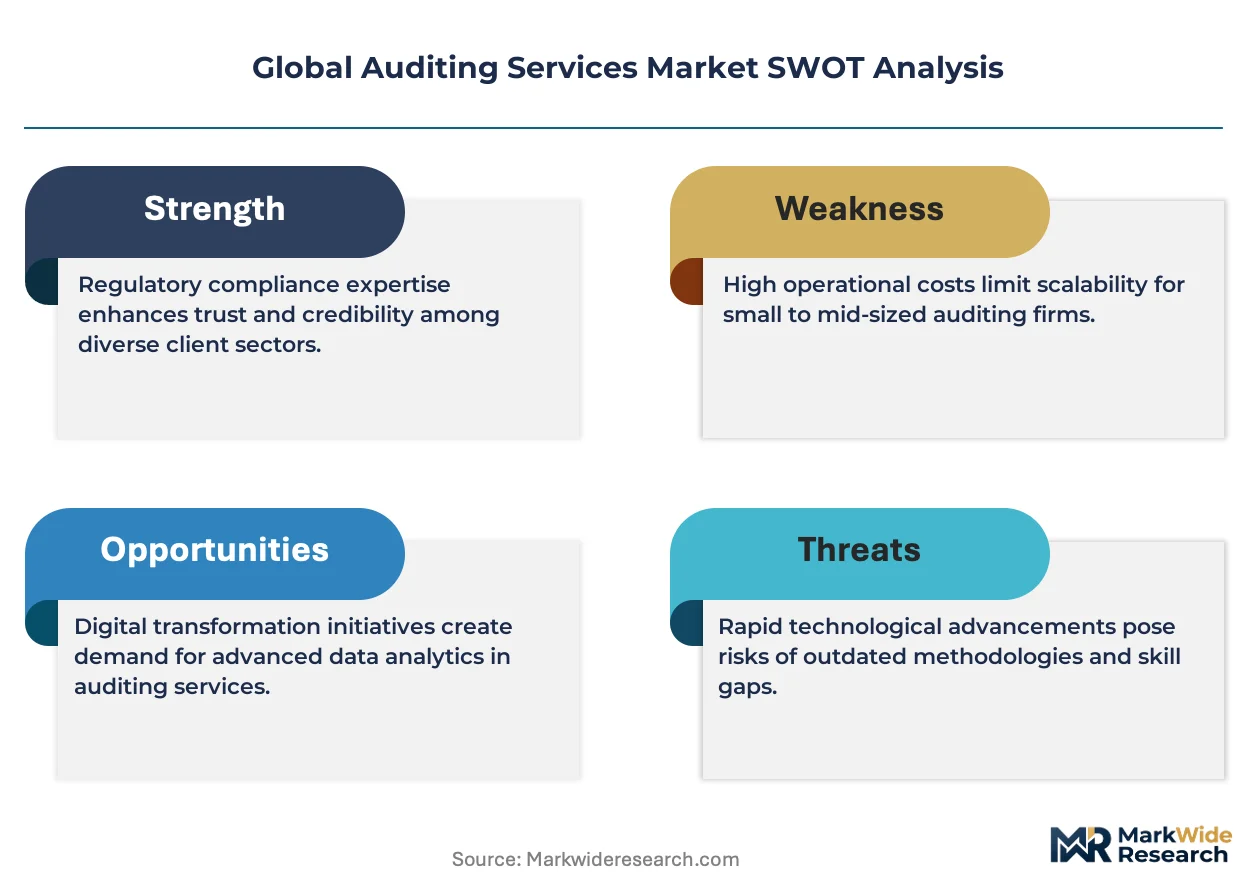
AI-powered continuous monitoring is compressing audit cycle times while expanding assurance scope beyond financial statements into operational and sustainability domains. This technology shift is forcing incumbent networks to retrain engagement teams and rebuild pricing models around subscription-based delivery rather than project-based billing.
Growth Catalysts
- EU CSRD limited assurance mandates:Sustainability reporting requirements under the EU Corporate Sustainability Reporting Directive create mandatory service expansion for assurance providers across European publicly listed entities.
- Cloud ERP proliferation:Enterprise migration to SAP S/4HANA and Oracle Cloud Infrastructure generates demand for specialized controls testing around automated financial workflows.
- India:SEBI circulars on statutory audit quality and RBI concurrent bank audit requirements tighten eligibility criteria, concentrating demand among qualified domestic and global networks.
Market Restraints
- Partner talent scarcity:The pipeline of professionals holding both CPA credentials and data analytics expertise remains constrained across the United States, Germany, and United Kingdom.
- Regulatory fragmentation:Divergent SEC climate disclosure timelines versus EU CSRD implementation dates force networks to maintain parallel methodology libraries and jurisdiction-specific training programs.
- AI tooling capex intensity:Proprietary machine-learning platforms require sustained investment in computational infrastructure and specialized engineering talent without immediate fee recovery.
Strategic Opportunities
- Brazil:ANVISA quality system regulations for pharmaceutical manufacturing create durable compliance audit demand as domestic production scales under import substitution policies.
- Blockchain-ERP convergence:Immutable ledger integration with enterprise resource planning systems enables real-time verification of supply-chain transactions for manufacturing clients.
- Assurance-as-a-service models:Continuous control monitoring delivered through subscription platforms replaces periodic project-based engagements for mid-market technology clients.
Industry Challenges
- Methodology standardization gaps:Absence of unified International Standards on Auditing guidance for AI-assisted evidence evaluation creates liability exposure across cross-border engagements.
- Legacy system interoperability:Client environments mixing on-premise Oracle E-Business Suite with cloud-native Workday Financial Management complicate data extraction and normalization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Auditing Services Market |
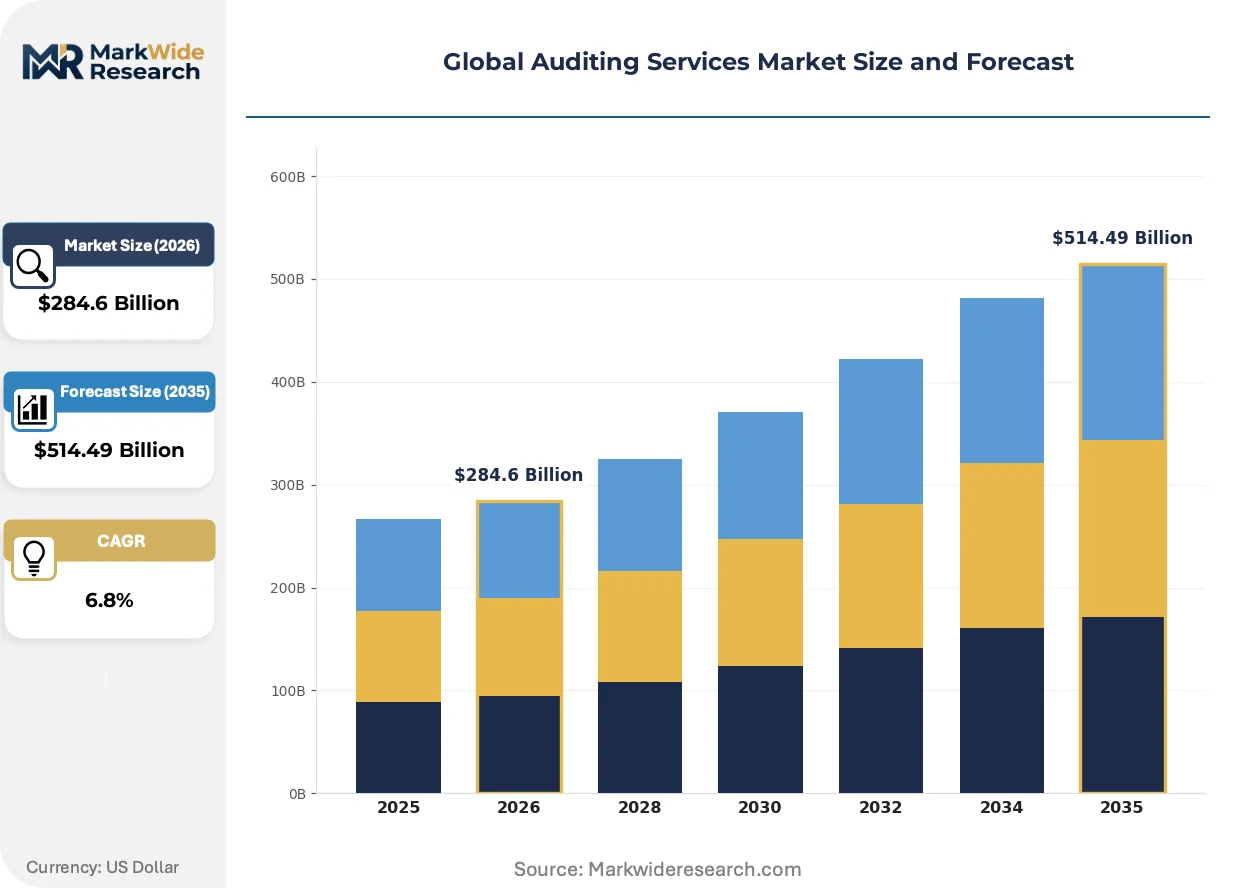
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $514.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Internal Audit, Financial Audit, Compliance Audit, Operational Audit Client Type: Corporations, Government Agencies, Nonprofits, SMEs Industry Vertical: Healthcare, Manufacturing, Retail, Technology Engagement Model: Fixed Fee, Time and Material, Performance-Based, Project-Based |
| Companies Covered | Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers International Limited, Ernst & Young Global Limited, KPMG International Limited, Grant Thornton International Ltd., BDO, RSM International Association, Baker Tilly International Limited, Mazars Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Auditing Services Market Emerging Trajectories
Audit delivery models are pivoting from retrospective sampling to prospective risk sensing, embedding assurance capabilities directly into client transaction flows. This transformation redefines professional skepticism and recalibrates fee structures around value delivered rather than hours consumed.
Natural language processing engines are integrating with enterprise email and contract management systems to flag anomalous vendor relationships and revenue recognition judgments in real time. Large-cap technology and telecommunications clients in the United States and Ireland are deploying these tools across quarterly close processes. The technology is integrating control testing into operational workflows rather than treating assurance as a discrete post-hoc validation layer.
The EU CSRD mandates limited assurance on sustainability disclosures starting with fiscal periods, expanding mandatory service lines beyond traditional financial statement audits. This regulatory pressure forces networks to build carbon accounting expertise and lifecycle assessment capabilities. European industrial and energy sector clients face the steepest compliance ramps, driving co-sourcing arrangements with specialized environmental consultancies.
Chief audit executives at Fortune 500 manufacturing conglomerates are consolidating vendor relationships from multiple specialist firms to single-network strategic partnerships. This concentration replaces competitive tendering for individual engagements with multi-year framework agreements spanning financial, operational, and ESG assurance. The pattern is most pronounced among German automotive and Japanese electronics conglomerates with complex subsidiary structures across dozens of jurisdictions.
Global Auditing Services Market Segmentation
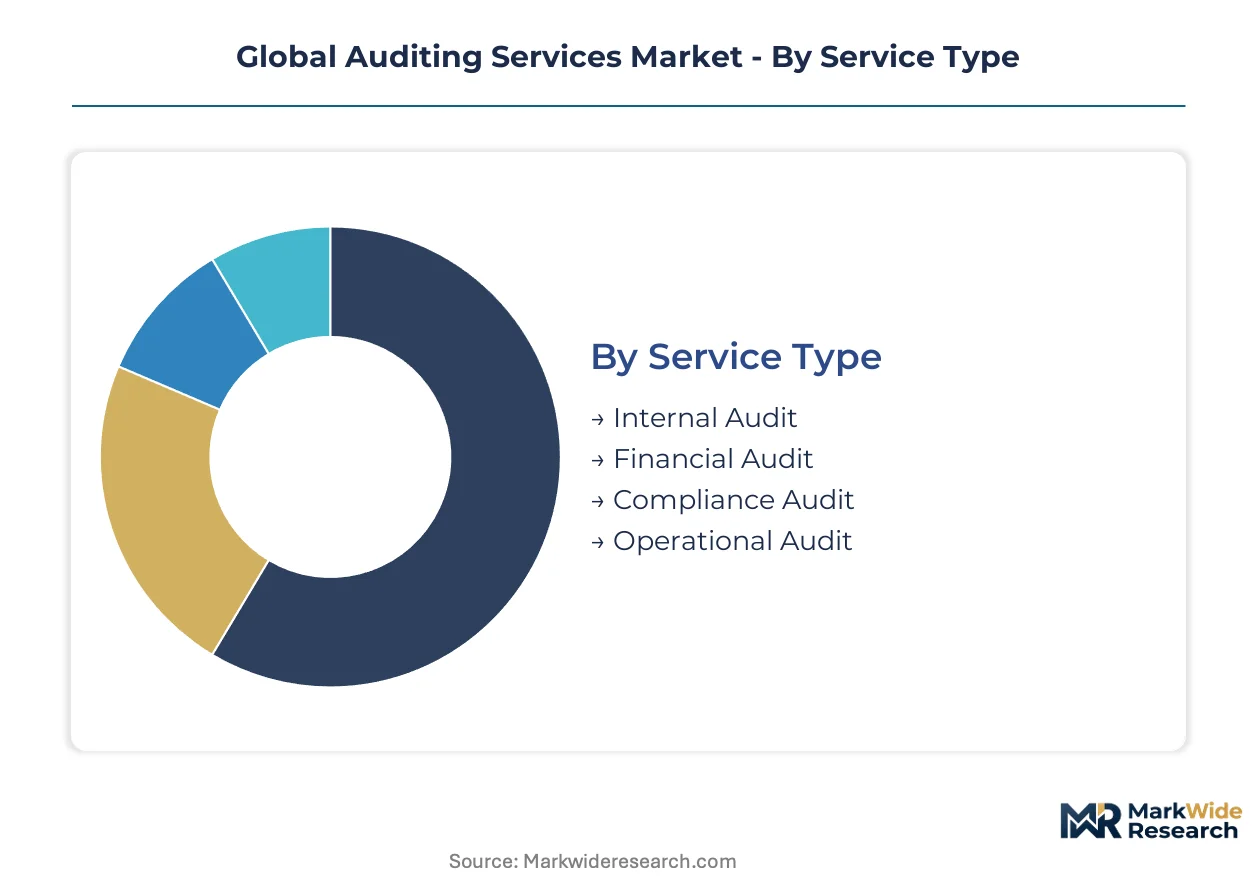
Segmentation reveals how audit service providers allocate capital across divergent delivery models and client risk profiles. Service type and engagement structure determine pricing power, while client scale and industry vertical shape technology platform investments.
Service Type:
Replacement cycles for audit methodologies accelerate as AI tools displace manual sampling, forcing networks to rebuild service architectures around continuous monitoring capabilities.
- Financial Audit:Independent examination of financial statements against IFRS or US GAAP standards generates the largest fee pools among publicly listed clients. Demand concentrates in technology sector engagements where revenue recognition complexity around cloud subscriptions and software licensing requires specialized assurance expertise.
- Internal Audit:Embedded evaluation of risk management and governance processes shifts from periodic reviews to real-time control monitoring. Manufacturing conglomerates in Germany and Japan are consolidating internal audit functions under single-network partnerships spanning financial, operational, and ESG domains.
- Compliance Audit:Verification against regulatory requirements including HIPAA, FDA quality systems, and EU CSRD sustainability disclosures creates durable recurring revenue streams.
- Operational Audit:Assessment of efficiency and effectiveness in supply-chain and production workflows gains traction as procurement resilience scrutiny intensifies across retail and industrial clients.
Volume placements concentrate in Financial Audit; the faster expansion belongs to Operational Audit.
Client Type:
Cost tier stratification separates premium assurance budgets from constrained procurement frameworks across the client base.
- Corporations:Large-cap publicly traded entities drive methodology innovation through multi-year framework agreements that bundle financial, operational, and sustainability assurance. SEC climate disclosure mandates and EU CSRD requirements expand scope beyond traditional financial statements for US and European filers.
- Government Agencies:Public sector audit mandates emphasize fraud detection and program integrity across federal, state, and municipal levels with rigid procurement protocols.
- Nonprofits:Donor transparency requirements and grant compliance obligations generate steady demand for specialized assurance around restricted fund management.
- SMEs:Mid-market clients increasingly adopt subscription-based continuous monitoring platforms rather than periodic project-based engagements.
Revenue concentration sits with Corporations; SME adoption of assurance-as-a-service models is climbing the fastest.
Industry Vertical:
Application-specific risk profiles dictate staffing specialization and technology tooling investments across sector teams.
- Technology:Cloud ERP migrations and SaaS revenue recognition complexity require controls testing expertise around automated financial workflows. Ireland and United States technology clusters generate concentrated demand for IPO readiness and SOX compliance engagements.
- Healthcare:HIPAA privacy rules, FDA quality system regulations, and state Medicaid integrity programs create layered compliance obligations with severe penalty exposure.
- Manufacturing:Supply-chain resilience audits and ANVISA quality system requirements for pharmaceutical production in Brazil drive operational assurance expansion.
- Retail:Inventory valuation, vendor rebate programs, and omnichannel revenue recognition generate seasonal engagement peaks.
Fee generation peaks in Technology; Manufacturing operational audits are gaining share fastest.
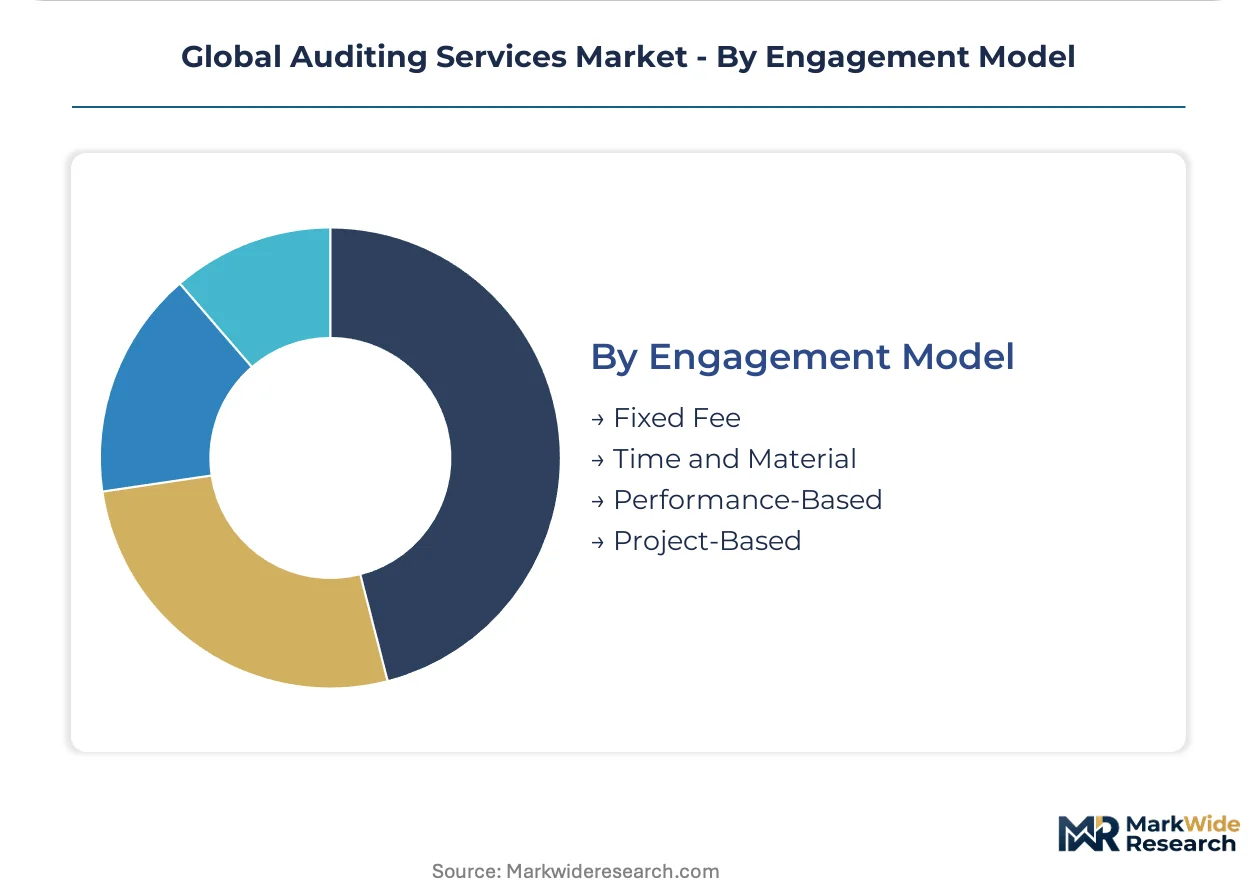
Engagement Model:
Margin structures diverge sharply between fixed-scope deliverables and outcome-contingent arrangements.
- Fixed Fee:Predetermined pricing for defined scope engagements dominates statutory audit relationships with publicly listed clients, transferring methodology efficiency risk to the service provider.
- Time and Material:Hourly billing persists in advisory and forensic investigations where scope uncertainty prevents fixed pricing.
- Performance-Based:Fees tied to identified cost recoveries or risk mitigation outcomes remain limited to specialized fraud examination and contract compliance engagements.
- Project-Based:Discrete deliverable structures face displacement by continuous monitoring subscriptions among mid-market technology clients.
Contract volume clusters in Fixed Fee; Performance-Based structures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Ireland and Singapore concentrate audit service delivery for technology multinationals seeking favorable tax treatment alongside Big Four presence. These jurisdictions anchor regional delivery hubs that serve cross-border assurance mandates.
United States
SEC climate disclosure rules and SOX compliance mandates drive demand among Silicon Valley technology firms and Wall Street financial institutions. The PCAOB enforces auditor independence standards that expand engagement scope for publicly traded clients. New York and San Francisco metropolitan areas host the densest concentrations of Big Four partners serving large-cap audit engagements.
Germany
EU CSRD limited assurance requirements and supply-chain due diligence laws reshape service delivery for automotive and industrial conglomerates headquartered in Bavaria and Baden-Württemberg. The Federal Financial Supervisory Authority enforces statutory audit quality standards that tighten network eligibility. Stuttgart and Munich clusters concentrate specialized assurance teams serving DAX-listed manufacturers.
India
SEBI circulars on statutory audit quality and RBI concurrent bank audit requirements concentrate demand among qualified domestic and global networks. The Institute of Chartered Accountants of India governs professional standards while BIS sustainability reporting guidelines expand assurance scope. Mumbai and Bangalore financial districts anchor delivery centers serving both domestic listed companies and multinational shared service operations.
Brazil
ANVISA quality system regulations for pharmaceutical manufacturing create durable compliance audit demand as domestic production scales under import substitution policies. The country's securities regulator enforces audit independence rules for B3-listed entities. São Paulo state concentrates assurance providers serving manufacturing conglomerates with complex subsidiary structures across Latin America.
United Kingdom
Financial Reporting Council audit reforms and UK-specific sustainability disclosure requirements reshape engagement economics for FTSE 350 clients. The Prudential Regulation Authority supervises audit quality for banking sector engagements. London's Square Mile hosts the largest concentration of cross-border assurance teams serving multinational headquarters and private equity portfolio companies.
Global Auditing Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with the Big Four networks commanding premium pricing on large-cap statutory engagements while mid-tier associations compete for mid-market share through differentiated sector expertise. Market structure tilts toward oligopoly at the top tier, with four global networks capturing the majority of publicly listed client relationships. Three archetypes dominate: full-service global networks, sector-specialized mid-tier associations, and technology-enabled challenger firms. Consolidation through network mergers and proprietary AI platform development represent the primary competitive vectors reshaping positioning.
Within the full-service global network tier, Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers International Limited, and Ernst & Young Global Limited exemplify the scale-driven archetype that anchors premium-market positioning through multi-year framework agreements spanning financial, operational, and ESG assurance. These entities occupy positions where methodological investment in continuous monitoring capabilities and carbon accounting expertise creates differentiation against mid-tier competitors.
| Leading Market Players |
|---|
| Deloitte Touche Tohmatsu Limited |
| PricewaterhouseCoopers International Limited |
| Ernst & Young Global Limited |
| KPMG International Limited |
| Grant Thornton International Ltd. |
| BDO |
| RSM International Association |
| Baker Tilly International Limited |
| Mazars Group |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up mid-tier audit networks anchor supply behavior through aggressive pricing discipline on fixed-fee statutory engagements, compressing margins across the Big Four's project-based billing legacy while concentrating partner talent in premium-tier assurance segments.
Pricing Analysis
Short lead-time engagements command premium pricing from corporate clients facing accelerated SEC filing deadlines or EU CSRD sustainability disclosure windows, while spot-market procurement of interim audit support trades at discounted rates. Subscription-based continuous monitoring platforms stratify across premium, standard, and economy tiers based on ERP integration complexity and control automation depth. Cost compression in mid-market statutory audits intensifies as AI tooling capex demands fee recovery through volume scaling. Large-cap publicly traded entities show lowest price sensitivity given regulatory penalty exposure, while SME technology adopters drive hardest bargain negotiations on assurance-as-a-service contracts.
Supply Chain Analysis
Freight costs for cross-border engagement staffing—particularly partner travel between London, New York, and Singapore delivery hubs—feed directly into project margin calculations and offshore center utilization decisions. Supply concentrates in the United States, United Kingdom, and India, where Big Four networks maintain dense partner concentrations and specialized sector teams. Raw material dependencies include CPA-credentialed professionals, data analytics engineering talent, and proprietary machine-learning platform licenses. Single-source vulnerability around AI tooling vendors creates concentration risk as networks build proprietary capabilities. Distribution runs through multi-year framework agreements with Fortune 500 conglomerates, replacing competitive tendering for individual engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The auditing services market sits in a technology-transition phase, with AI-powered continuous monitoring displacing manual sampling methodologies and forcing wholesale reconstruction of pricing models and professional training architectures.
For Market Incumbents: Deepen vertical integration into proprietary AI development by acquiring specialized machine-learning engineering teams in Bangalore and Dublin, insulating against margin erosion from mid-tier challengers deploying open-source anomaly detection tools. Reinforce partner retention through equity participation structures addressing talent scarcity in data analytics credentials. For New Entrants and Emerging Players: Begin with underserved mid-market technology clients in Brazil and Southeast Asia, where cloud ERP proliferation outpaces Big Four coverage capacity and subscription-based continuous monitoring platforms face limited competition. Target pharmaceutical manufacturing assurance under ANVISA quality system regulations, leveraging lower cost structures to undercut incumbent pricing on compliance audit engagements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier associations with established sector specialization in healthcare or manufacturing verticals across Germany and Japan, where regulatory complexity sustains durable fee premiums. Monitor AI platform deployment velocity as inflection indicator—networks demonstrating measurable audit cycle compression through machine-learning integration will capture disproportionate share in the next consolidation wave.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Platform Development | Machine-learning anomaly detection sustains premium pricing on large-cap engagements against mid-tier competition. |
| Carbon Accounting Capability Buildout | EU CSRD limited assurance mandates create mandatory service expansion across European industrial and energy clients. |
| Multi-Year Framework Agreement Consolidation | Single-network partnerships spanning financial, operational, and ESG assurance replace competitive tendering for German automotive conglomerates. |
| Subscription-Based Continuous Monitoring Launch | Real-time control monitoring platforms displace periodic project-based engagements among mid-market technology clients. |
| Specialized Sector Talent Acquisition | Healthcare compliance expertise around HIPAA and FDA quality systems generates durable recurring revenue streams. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with audit committee chairs, chief financial officers, Big Four engagement partners, and procurement leads at Fortune 500 manufacturing conglomerates. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level demand estimates across service type, client scale, and industry vertical dimensions.
Granularity-level modeling applied service-type splits at the country level, with technology sector engagements further disaggregated by cloud ERP deployment stage and revenue recognition complexity tier. CAGRs derived from historical fee pool trajectories and projected regulatory mandate expansion, incorporating PCAOB enforcement intensity, EU CSRD implementation pace, and SEBI audit quality circular adoption as industry-specific forecast inputs.
Underlying measurement precision varies by segment; financial audit services carry tighter precision than emerging sustainability assurance lines given established reporting standards. Forecasts reflect assumptions around AI tooling adoption curves and regulatory timeline adherence that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
US Auditing Services Market