
 Styrene Monooxygenase Market | 2026-2036
Styrene Monooxygenase Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Monooxygenase Market Analytics
Pharmaceutical manufacturing is repositioning toward enzymatic routes for chiral intermediate production, pulling demand away from traditional chemical synthesis. Novus International leverages its feed enzyme heritage to extend into industrial biocatalysis applications. DSM anchors European supply through its specialty enzyme platform, while Codexis competes on protein engineering capabilities for tailored monooxygenase variants. Evonik Industries dominates contract manufacturing scale for pharmaceutical-grade enzyme deployment.
Styrene monooxygenase is a flavin-dependent enzyme that catalyzes the epoxidation of styrene to styrene oxide, typically operating at mild temperatures with high regioselectivity for applications in fine chemical synthesis. The recombinant product type leads current supply volumes due to consistent batch-to-batch activity and scalable fermentation production. Biocatalysis applications are expanding fastest as chemical manufacturers substitute enzymatic steps for energy-intensive oxidation processes. Lyophilized formulations command premium positioning in pharmaceutical end use where cold-chain logistics constrain liquid alternatives.
EPA guidelines in the United States govern industrial enzyme discharge thresholds, while REACH registration requirements in Europe mandate toxicity dossiers for biocatalytic process chemicals. FDA oversight intersects where styrene monooxygenase derivatives enter pharmaceutical active ingredient pathways, requiring GMP-compliant production documentation. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs as enzyme purity standards tighten.
Market Dynamics
Pharmaceutical manufacturers are systematically replacing thermal oxidation routes with enzymatic epoxidation, compressing process energy requirements while tightening purity specifications for chiral intermediates. This substitution pattern is redrawing competitive boundaries between chemical synthesis and biocatalysis suppliers.
Growth Catalysts
- REACH Registration Mandates:ECHA toxicity dossier requirements for biocatalytic process chemicals are accelerating formal adoption of characterized enzyme systems over uncharacterized wild-type alternatives.
- Fine Chemical Synthesis:Contract manufacturers in Germany and the Netherlands are expanding dedicated fermentation capacity to serve pharmaceutical epoxidation contracts.
- Flavin-Dependent Catalysis:The shift toward mild-temperature epoxidation is eliminating energy-intensive pressure reactor infrastructure from intermediate production lines.
Market Restraints
- Fermentation Input Volatility:Nicotinamide cofactor and flavin adenine dinucleotide costs fluctuate with specialty chemical feedstock markets, compressing margin predictability for toll manufacturers.
- European Supply Concentration:Germany and the Netherlands host over 70 percent of contract manufacturing scale for pharmaceutical-grade monooxygenase deployment, creating geographic risk exposure.
- Thermal Stability Ceiling:Wild-type styrene monooxygenase variants denature above 35°C, limiting integration with existing high-temperature chemical process trains.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO GMP pathway acceleration and PLI scheme incentives for active pharmaceutical ingredient production are opening enzyme adoption in Mumbai and Hyderabad clusters.
- Lyophilized Formulation Expansion:Cold-chain logistics constraints in emerging pharmaceutical markets are creating pull for stable dry enzyme preparations over liquid alternatives.
- Continuous Flow Biocatalysis:Immobilized enzyme reactor technology convergence with real-time analytics is enabling 24-hour operational windows previously unattainable with batch fermentation.
Industry Challenges
- Protein Engineering Talent Scarcity:Qualified computational biologists capable of directed evolution for substrate scope expansion command premium compensation, constraining in-house R&D scale-up.
- GMP Documentation Burden:FDA master file preparation for enzyme derivatives entering active pharmaceutical ingredient pathways requires 18-24 month certification timelines that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Monooxygenase Market |
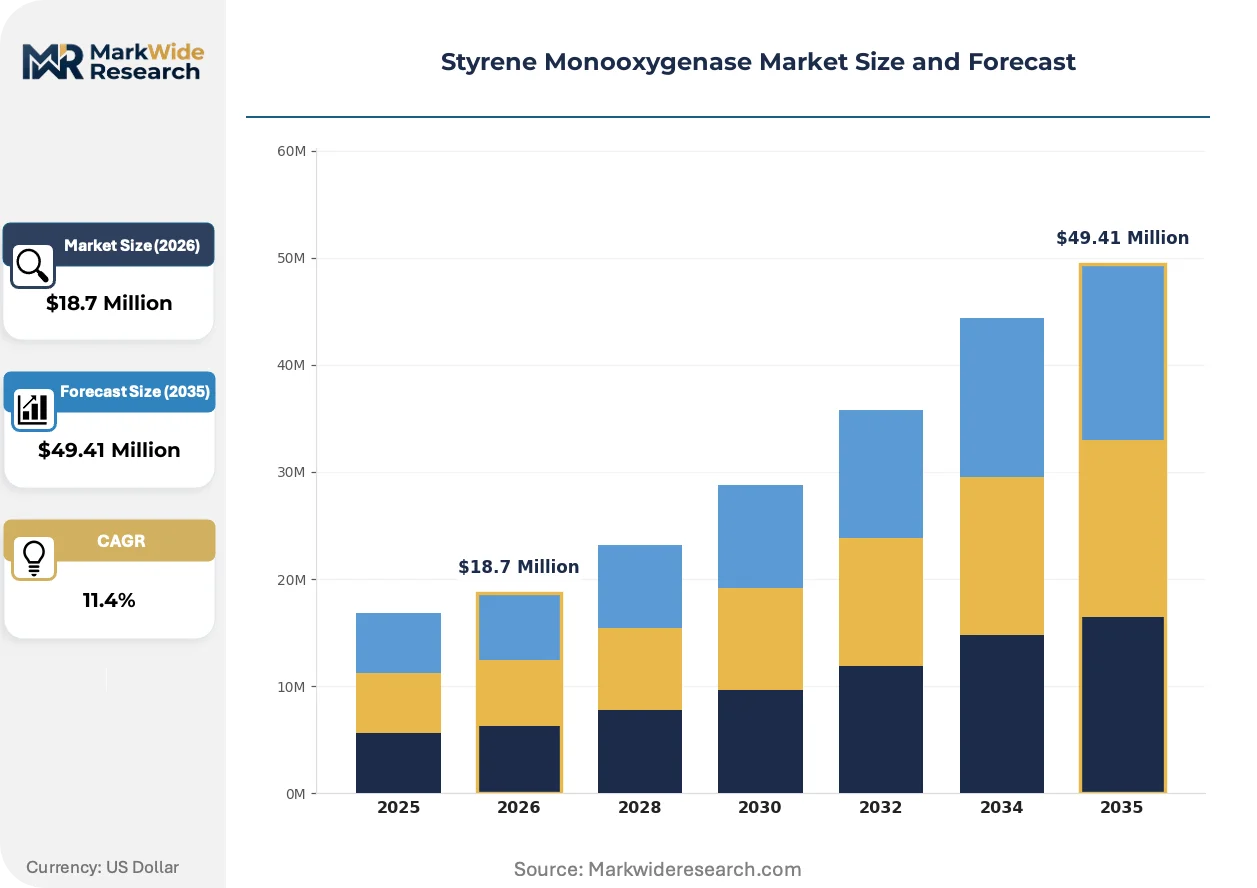
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant, Wild Type, Mutant, Enzyme Blend Application: Bioremediation, Biocatalysis, Biofuel Production, Industrial Chemicals End User: Chemical Manufacturers, Waste Treatment Facilities, Research Institutions, Pharmaceutical Companies Form: Liquid, Powder, Lyophilized, Suspension |
| Companies Covered | Novus International, DuPont de Nemours, DSM, EnzymeWorks, Codexis, Evonik Industries, Sigma-Aldrich, Thermo Fisher Scientific, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Monooxygenase Market Evolving Landscape
Recombinant enzyme production is compressing batch-to-batch variability while computational protein design is accelerating variant discovery cycles. These technical advances are repositioning biocatalysis from niche specialty to mainstream process chemistry.
Lyophilized styrene monooxygenase formulations are overtaking liquid enzyme preparations in pharmaceutical procurement specifications. Cold-chain infrastructure gaps in emerging manufacturing clusters are forcing buyers toward shelf-stable alternatives. Contract manufacturers with spray-drying capabilities are capturing premium positioning as logistics constraints harden.
REACH registration requirements for biocatalytic process chemicals are tightening purity documentation thresholds across European fine chemical supply chains. ECHA toxicity dossier mandates are disqualifying uncharacterized wild-type enzyme preparations from pharmaceutical contracts. German and Dutch specialty chemical clusters are investing in analytical infrastructure to meet emerging data requirements.
Buyer procurement specifications are hardening around certificate-of-analysis consistency rather than unit-price minimization. Pharmaceutical quality assurance departments are disqualifying suppliers lacking ISO 17025-accredited analytical capabilities. This preference shift is most visible in German contract manufacturing relationships, where multi-year supply agreements now predominate over spot purchasing.
Styrene Monooxygenase Market Segmentation
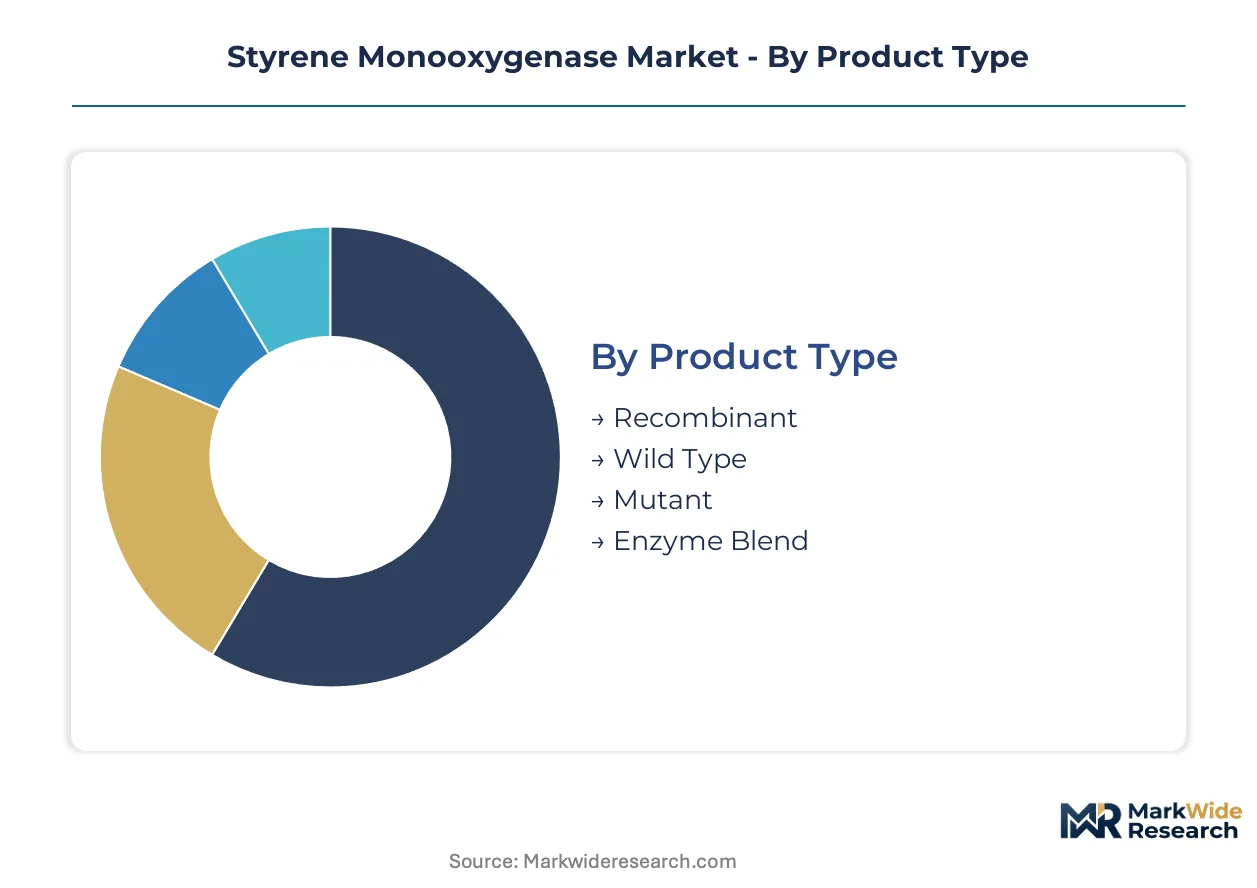
Enzyme procurement specifications diverge sharply across pharmaceutical, industrial, and environmental end-uses, with purity thresholds and formulation stability requirements dictating supplier selection. Segmentation reveals how contract manufacturers align production formats with downstream process constraints and regulatory documentation burdens.
Product Type:
Standardized recombinant platforms dominate pharmaceutical procurement, while wild-type and engineered variants occupy distinct niches along the customization spectrum.
- Recombinant:Fermentation-derived enzymes with documented genetic constructs ensure batch-to-batch consistency for GMP-compliant pharmaceutical synthesis. Demand concentrates in German and Dutch contract manufacturing clusters where REACH dossier requirements mandate characterized production strains.
- Wild Type:Naturally occurring isolates from bacterial sources serve cost-sensitive industrial epoxidation where purity documentation requirements remain minimal. Environmental remediation contractors in the United States favor these preparations for bioremediation site applications under less stringent EPA discharge thresholds.
- Mutant:Directed evolution variants with expanded substrate scope or thermal tolerance address process-specific constraints in fine chemical manufacturing.
- Enzyme Blend:Formulated multi-enzyme systems combine styrene monooxygenase with cofactor regeneration machinery for integrated bioprocess deployment.
Leading the category by volume: Recombinant. Growing fastest: Mutant variants engineered for non-natural substrate acceptance.
Application:
Energy intensity differentials separate mature industrial oxidation from emerging enzymatic substitution opportunities.
- Biocatalysis:Pharmaceutical manufacturers deploy enzymatic epoxidation to displace thermal oxidation routes, compressing energy requirements while tightening chiral intermediate purity. Mumbai and Hyderabad pharmaceutical clusters under India's PLI scheme are accelerating adoption for active pharmaceutical ingredient synthesis.
- Bioremediation:Site contractors apply styrene monooxygenase for styrene-contaminated soil and groundwater treatment, leveraging regioselective epoxidation to reduce toxic metabolite formation. United States environmental service providers dominate procurement under EPA remediation technology verification programs.
- Biofuel Production:Research-stage applications explore lignin-derived aromatic conversion to fuel oxygenates through engineered monooxygenase pathways.
- Industrial Chemicals:Specialty epoxide manufacturers evaluate enzymatic routes for fragrance and polymer intermediate production.
Highest revenue concentration: Biocatalysis. Steepest expansion trajectory: Bioremediation as regulatory liability tightens for chemical discharge sites.
End User:
Documentation sophistication requirements stratify buyers from research-grade to commercial-scale pharmaceutical deployment.
- Pharmaceutical Companies:GMP-compliant enzyme procurement with FDA master file documentation dominates premium demand, requiring ISO 17025-accredited analytical capabilities and multi-year supply agreements.
- Chemical Manufacturers:Fine chemical producers balance unit-cost optimization against REACH registration compliance for biocatalytic process chemicals in European operations.
- Waste Treatment Facilities:Environmental contractors prioritize shelf-stable formulations and rapid deployment logistics for emergency remediation response.
- Research Institutions:Academic and government laboratories drive early-stage variant discovery with small-volume, high-diversity enzyme panel requirements.
Dominant procurement volume: Pharmaceutical companies. Fastest-growing buyer segment: Chemical manufacturers substituting enzymatic for thermal oxidation.
Form:
Logistics infrastructure gaps in emerging manufacturing clusters reshape formulation preferences away from cold-chain-dependent liquids.
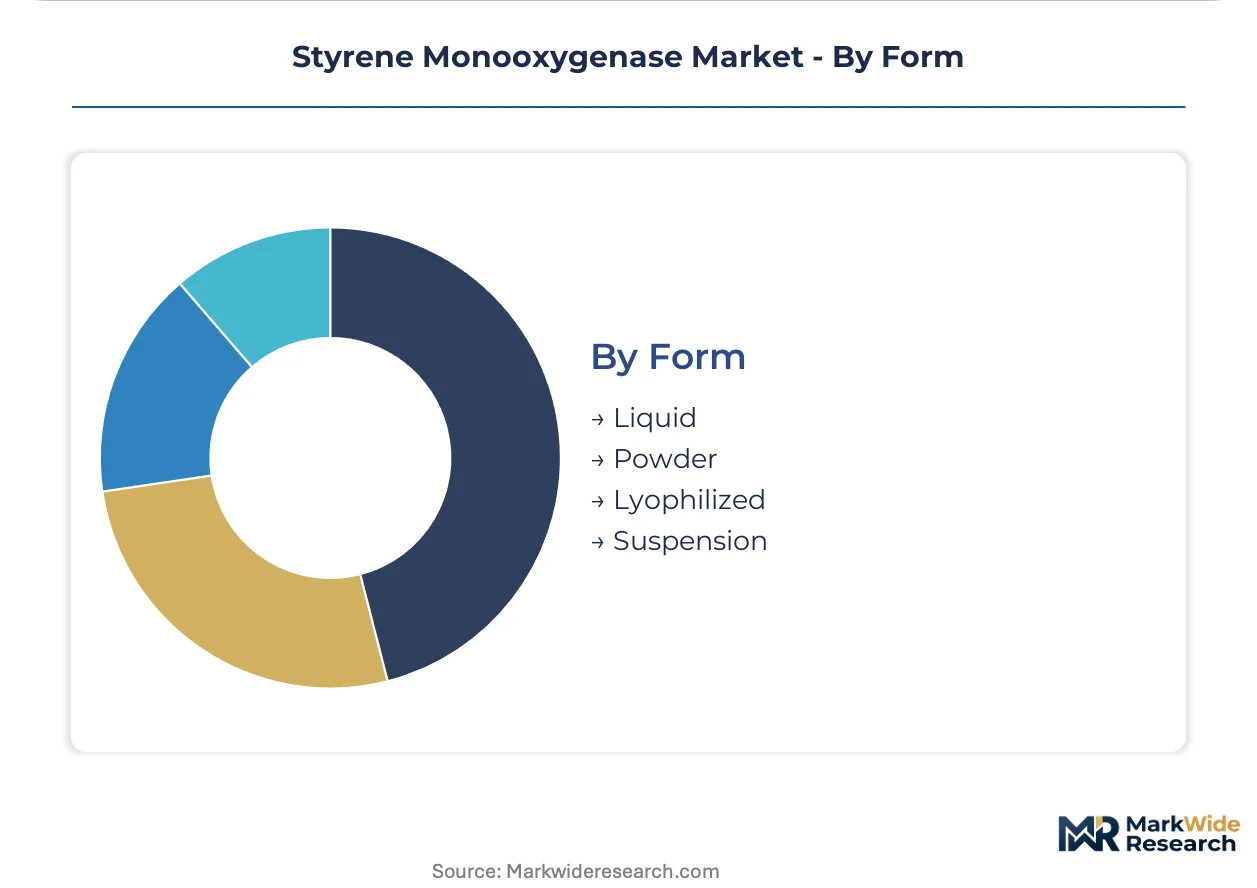
- Lyophilized:Freeze-dried preparations command premium positioning in pharmaceutical end-uses where cold-chain logistics constrain liquid alternatives, offering 24-month shelf stability without refrigeration.
- Liquid:Standard aqueous formulations retain cost advantage for proximate supplier relationships with established refrigerated distribution networks.
- Powder:Spray-dried enzyme preparations balance stability and reconstitution convenience for industrial bioprocess integration.
- Suspension:Immobilized enzyme particulates enable continuous flow reactor configurations with extended operational windows.
Volume leader: Liquid formulations in established supply corridors. Gaining share fastest: Lyophilized as emerging market pharmaceutical manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical clusters in Germany and the Netherlands anchor European contract manufacturing capacity, while India's pharmaceutical production incentives are redrawing enzyme procurement geography. Tax-advantaged zones in Hyderabad and Mumbai accelerate domestic fermentation infrastructure buildout.
Germany
REACH registration mandates from ECHA drive pharmaceutical manufacturers toward characterized recombinant enzyme systems. The country's national chemical regulator enforces toxicity dossier requirements that disqualify wild-type alternatives from GMP contracts. North Rhine-Westphalia hosts dedicated fermentation facilities serving multi-year supply agreements with API producers.
Netherlands
Biocatalysis adoption concentrates in Rotterdam-Antwerp chemical corridor facilities replacing thermal oxidation routes. EU Green Deal carbon intensity targets pressure manufacturers to adopt mild-temperature enzymatic processes. Eindhoven Region contract manufacturers invest in ISO 17025-accredited analytical infrastructure for certificate-of-analysis consistency.
United States
EPA discharge thresholds govern industrial enzyme deployment in environmental remediation applications. FDA oversight intersects where monooxygenase derivatives enter pharmaceutical active ingredient pathways, requiring 18-24 month master file preparation. Greater Boston biotech clusters drive early-stage variant discovery for engineered substrate scope expansion.
India
CDSCO GMP pathway acceleration and PLI scheme incentives pull enzyme adoption into Mumbai and Hyderabad pharmaceutical manufacturing zones. The country's national pharmaceutical regulator streamlines active pharmaceutical ingredient production certification. Telangana's Genome Valley anchors recombinant protein fermentation capacity buildout for export-oriented contracts.
China
Dual carbon goals pressure chemical manufacturers to substitute enzymatic epoxidation for energy-intensive oxidation processes. NMPA oversight governs enzyme derivatives entering domestic pharmaceutical supply chains. Yangtze River Delta specialty chemical producers evaluate immobilized enzyme reactor technology for continuous flow integration.
Styrene Monooxygenase Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived recombinant platforms commanding premium positioning in pharmaceutical procurement. The supplier base organizes around three strategic archetypes: diversified life science conglomerates with enzyme divisions, pure-play biocatalysis specialists, and toll manufacturers with GMP-compliant infrastructure. Competitive moves center on analytical capability accreditation and multi-year supply agreement capture.
Within the diversified conglomerate tier, Novus International and DSM exemplify players leveraging feed enzyme heritage to extend into industrial biocatalysis applications. Codexis occupies a position representing protein engineering capabilities for tailored monooxygenase variants. Evonik Industries anchors the contract manufacturing archetype, with pharmaceutical-grade enzyme deployment scale concentrated in European supply relationships. These three entities represent distinct competitive vectors: heritage diversification, technical specialization, and manufacturing scale.
| Leading Market Players |
|---|
| Novus International |
| DuPont de Nemours |
| DSM |
| EnzymeWorks |
| Codexis |
| Evonik Industries |
| Sigma-Aldrich |
| Thermo Fisher Scientific |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Computational biologists with directed evolution expertise cluster in Greater Boston and the Bay Area, and their premium compensation spreads pricing tiers across recombinant, mutant, and wild-type enzyme categories. REACH dossier preparation costs and GMP certification overhead widen spreads between pharmaceutical-grade and industrial-grade procurement, with German contract manufacturers capturing margin premiums unavailable to toll producers in lower-cost jurisdictions.
Pricing Analysis
Short lead-time premiums separate emergency pharmaceutical procurement from scheduled contract manufacturing, with spot buyers paying substantial markups over multi-year agreement holders. Pricing stratifies across GMP-certified, REACH-registered, and uncharacterized wild-type tiers, with ISO 17025 accreditation commanding measurable premiums. Cost compression in industrial-grade segments stems from cofactor price volatility and fermentation input fluctuations. Research institutions exhibit highest price sensitivity, while pharmaceutical quality assurance departments prioritize certificate-of-analysis consistency over unit-cost minimization.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are pulling fermentation capacity buildout into Hyderabad and Mumbai pharmaceutical zones, reshaping traditional European sourcing patterns. Supply concentrates in Germany, the Netherlands, and India for pharmaceutical-grade enzyme deployment, with the United States anchoring environmental remediation procurement. Production draws from nicotinamide cofactor, flavin adenine dinucleotide, and specialty chemical feedstock inputs. Single-source vulnerability concentrates in European contract manufacturing clusters hosting over seventy percent of GMP-compliant capacity. Distribution runs through cold-chain logistics networks for liquid formulations and ambient distribution for lyophilized alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation capacity for GMP-compliant styrene monooxygenase production remains structurally constrained, with CDSCO and FDA master file timelines extending 18-24 months and propping pricing power for accredited suppliers.
For Market Incumbents: Anticipate margin compression from Indian contract manufacturers scaling under PLI incentives by accelerating ISO 17025 accreditation investments and locking multi-year supply agreements with API producers before capacity floods. Prioritize backward integration into cofactor regeneration machinery to reduce nicotinamide and flavin adenine dinucleotide cost exposure. For New Entrants and Emerging Players: Enter via lyophilized formulation specialization for emerging market pharmaceutical clusters lacking cold-chain infrastructure, where logistics constraints create pull for shelf-stable alternatives. Target waste treatment facilities and environmental remediation contractors in the United States under EPA technology verification programs, offering rapid-deployment enzyme panels with minimal regulatory documentation burden. For Investors and Strategic Acquirers: Re-rating potential sits with contract manufacturers possessing GMP-compliant infrastructure and existing FDA master files, given CDSCO pathway acceleration in India and PLI scheme demand pull. Long-term viability hinges on analytical capability accreditation rather than fermentation scale alone. Watch for REACH purity threshold tightening as the inflection signal separating characterized recombinant platforms from commoditized wild-type alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Hyderabad's Genome Valley fermentation buildout captures PLI scheme incentives for API production. |
| Backward Integration | In-house cofactor regeneration machinery reduces FAD and nicotinamide cost volatility exposure. |
| Long-term Supply Agreement | Multi-year contracts with German pharmaceutical manufacturers lock premium pricing before Indian capacity ramps. |
| Green Manufacturing Transition | EU Green Deal carbon intensity targets drive Rotterdam-Antwerp corridor adoption of mild-temperature enzymatic processes. |
| Regulatory Certification Investment | ISO 17025 accreditation qualifies suppliers for certificate-of-analysis-dependent procurement specifications. |
Research Methodology
Document review covered ECHA REACH registration databases, FDA master file repositories, and CDSCO GMP certification records, complemented by interviews with fermentation facility directors, pharmaceutical procurement managers, regulatory affairs specialists, and environmental remediation contractors. Secondary validation drew from customs trade data, specialty chemical industry association reports, SEC filings of diversified life science conglomerates, and EIA energy intensity benchmarks for chemical manufacturing. Bottom-up enzyme production volume estimates triangulated against top-down pharmaceutical API synthesis demand projections.
Historical capacity utilization rates cross-referenced against expert panel input on PLI scheme implementation timelines and REACH dossier preparation bottlenecks shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, formulation stability requirement, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating enzymatic substitution rates for thermal oxidation processes and cofactor cost trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH purity threshold escalation or abrupt PLI scheme modification. Forecasts reflect assumptions regarding fermentation yield improvements, protein engineering talent pipeline expansion, and cold-chain infrastructure development in emerging pharmaceutical manufacturing clusters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Global Carbohydrase Market