
 Global Monoclonal Antibodies (Mabs) Market | 2026-2036
Global Monoclonal Antibodies (Mabs) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monoclonal Antibodies (Mabs) Market Intelligence
Switzerland is narrowing its capacity gap in biologics manufacturing through expanded Basel-region fermentation facilities. F. Hoffmann-La Roche leverages its heritage in oncology mAbs to sustain high-margin therapeutic franchises. AbbVie anchors its portfolio in immunology with manufacturing scale that dominates supply chains for chronic disease treatment.
Monoclonal antibodies are recombinant proteins engineered from single B-cell clones, produced via mammalian cell culture in bioreactors exceeding ten thousand liters, designed to bind specific antigens for therapeutic or diagnostic intervention. Fully human constructs now lead clinical pipelines due to reduced immunogenicity risk versus chimeric formats. Oncology remains the deepest therapy area by development spend, while autoimmune applications occupy expanding label indications. Subcutaneous delivery modes are capturing fastest-growing preference as patients and payers prioritize administration convenience.
FDA, EMA, and WHO prequalification programs collectively shape mAb approval timelines, manufacturing standards, and market access in regulated jurisdictions. Biosimilar interchangeability rules in the United States and reference product exclusivity cliffs in Europe are redirecting investment toward complex generic development. Stakeholders must monitor evolving pharmacovigilance obligations and manufacturing technology transfers as capacity regionalization accelerates.
Market Dynamics
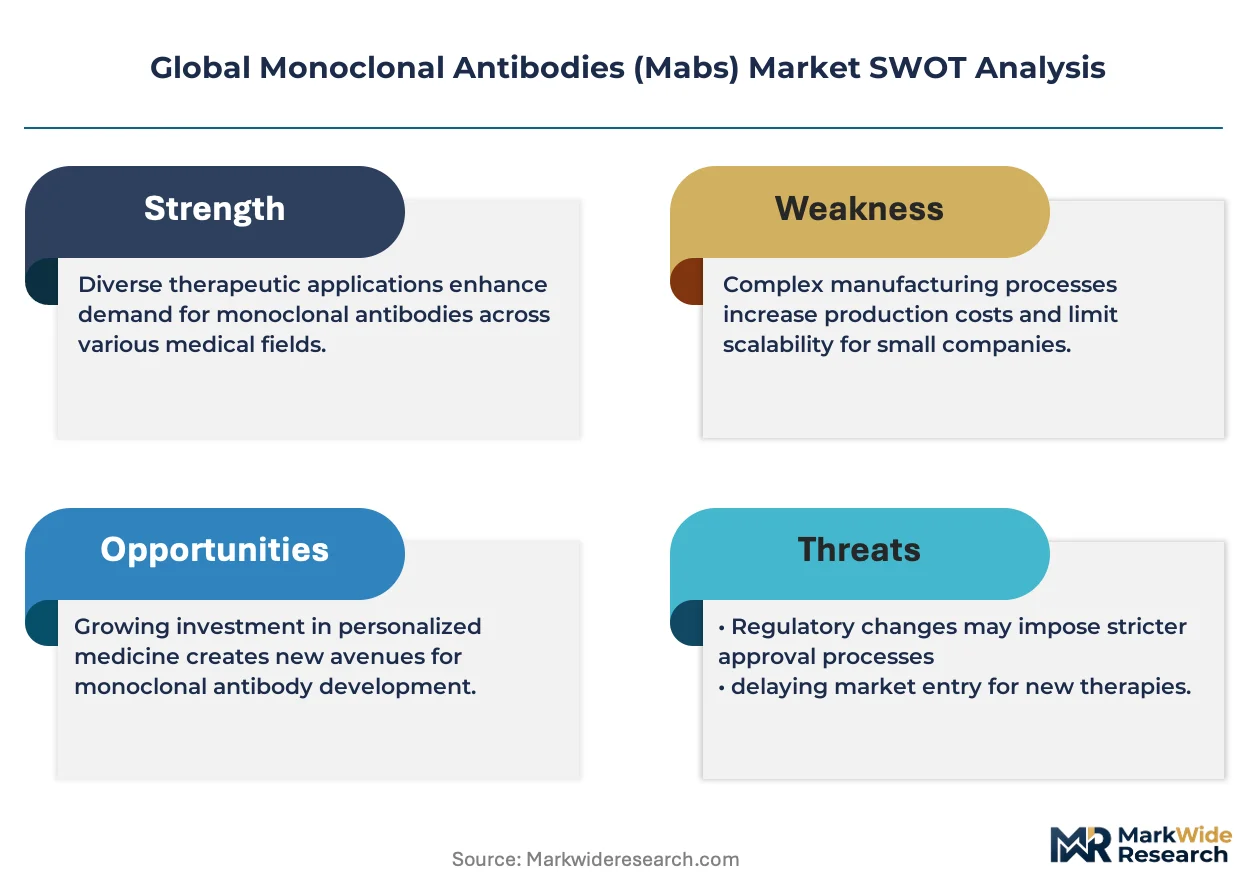
The monoclonal antibodies market is undergoing structural compression as biosimilar pathways mature and reference product exclusivity cliffs accelerate competitive entry. Manufacturing scale concentration in mammalian cell culture platforms now determines margin sustainability.
Growth Catalysts
- Subcutaneous delivery engineering:Patient administration preference for self-injection devices is expanding addressable populations beyond infusion centers. Chronic immunology indications are capturing the fastest label expansion as a result.
- FDA biosimilar interchangeability guidance:Streamlined approval criteria for automatic substitution at pharmacy level are compressing commercialization timelines. Payer formularies are increasingly favoring interchangeable products.
- Oncology protocol expansion:Academic medical centers in the United States are integrating mAb-based combination regimens into first-line treatment standards. Companion diagnostic pairing is deepening therapeutic penetration.
Market Restraints
- CHO cell culture input concentration:Chinese Hamster Ovary cell line supply and specialized media components face bottleneck risks from single-source suppliers. Fermentation capacity expansion requires 36-48 month lead times.
- EMA reference product exclusivity complexity:Data protection periods and patent linkage mechanisms in European jurisdictions create unpredictable market entry windows. Biosimilar developers face litigation exposure.
- Protein aggregation technical limits:Long-term stability challenges for subcutaneous formulations constrain shelf-life extension and cold chain simplification efforts. Formulation science gaps persist for high-concentration products.
Strategic Opportunities
- India domestic manufacturing scale-up:CDSCO regulatory harmonization with ICH guidelines is attracting contract development investments. Indigenous fermentation capacity is expanding to serve emerging market demand.
- Bispecific antibody platform convergence:Dual-targeting architectures combining checkpoint inhibition with tumor microenvironment modulation are opening solid tumor categories previously resistant to monotherapy.
- IRA Medicare price negotiation provisions:Selected drug pricing mechanisms are creating first-mover advantages for therapies launching ahead of negotiation eligibility windows. Strategic launch sequencing is capturing protected pricing periods.
Industry Challenges
- Cell line development talent scarcity:Mammalian cell engineering and clone selection expertise concentrates among a limited pool of specialists. Compensation inflation is compressing R&D budgets.
- Multi-product facility contamination risk:Campaign changeover protocols and viral clearance validation requirements extend downtime between product runs. cGMP compliance costs are escalating.
- Legacy quality system integration:Paper-based batch records and disconnected manufacturing execution systems impede real-time release testing adoption. Digital transformation capex demands compete with capacity expansion priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monoclonal Antibodies (Mabs) Market |
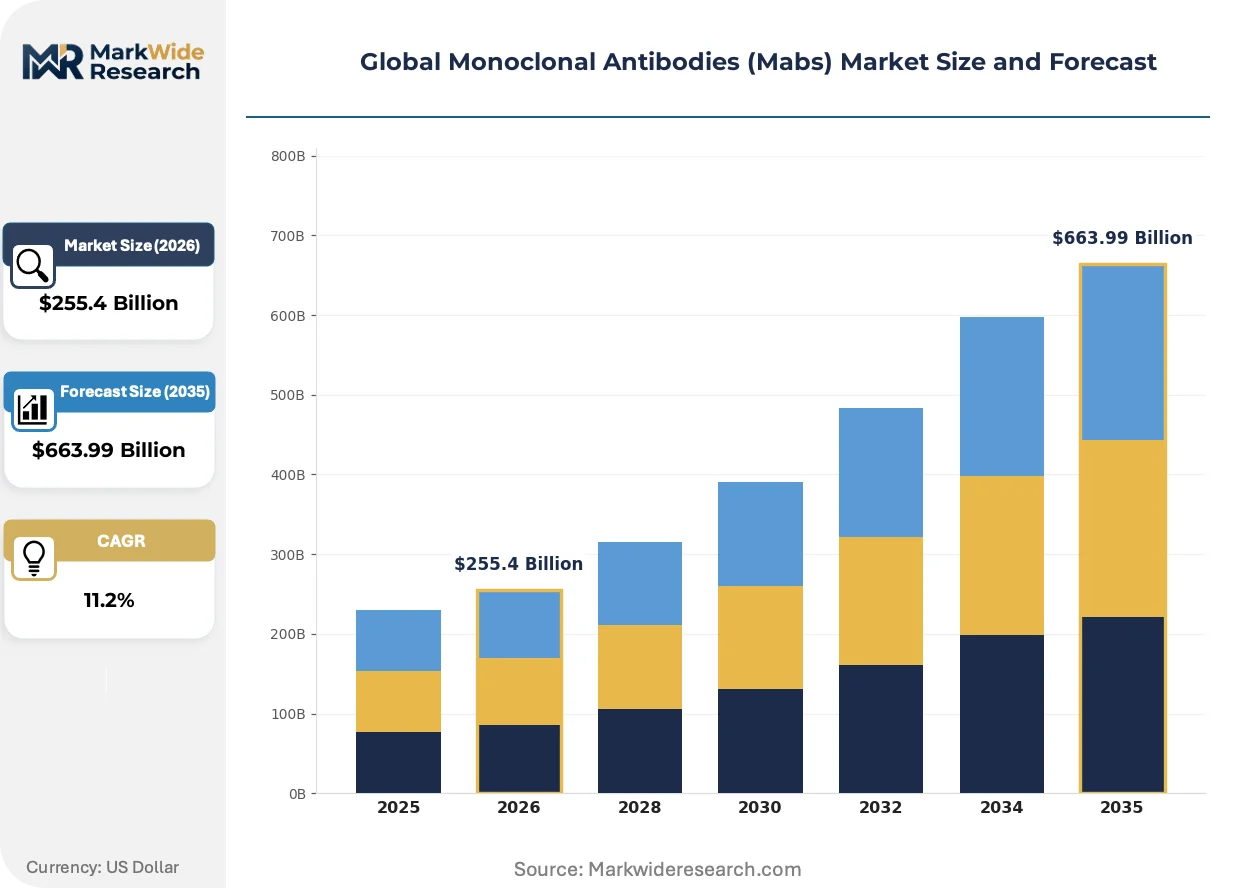
| Market Size in 2026 | $255.4 Billion |
| Market Size in 2035 | $663.99 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chimeric, Humanized, Fully Human, Murine Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Neurological Conditions End User: Biopharmaceutical Companies, Research Institutes, Contract Manufacturing Organizations, Diagnostics Labs Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | F. Hoffmann-La Roche, AbbVie, Johnson & Johnson, Merck & Co., Bristol Myers Squibb, Amgen, Novartis AG, Eli Lilly and Company, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monoclonal Antibodies (Mabs) Market Strategic Shifts & Innovations
Continuous manufacturing modalities and single-use bioreactor technologies are compressing batch cycle times while reducing cross-contamination risks. These shifts are redrawing competitive advantage around operational agility rather than scale alone.
Perfusion bioreactor systems with integrated online analytics are rendering obsolete traditional fed-batch processes dependent on manual sampling and offline testing. Contract manufacturers in Switzerland and Singapore are adopting these platforms to shorten client timelines. The technology is compressing working capital requirements and enabling smaller-footprint facilities.
EMA's revised GMP Annex 1 for sterile manufacturing is mandating barrier isolation technology and enhanced environmental monitoring across European production sites. Facility retrofit costs are diverting capital from greenfield expansion. Aseptic processing for fill-finish operations is experiencing the most intensive compliance investment.
Hospital and infusion center purchasing is consolidating through group purchasing organizations and integrated delivery networks, displacing traditional distributor relationships. Contracting sophistication is shifting margin capture toward logistics and data services rather than product markup. The United States exhibits the most pronounced concentration of buying power among three national GPOs.
Global Monoclonal Antibodies (Mabs) Market Segmentation
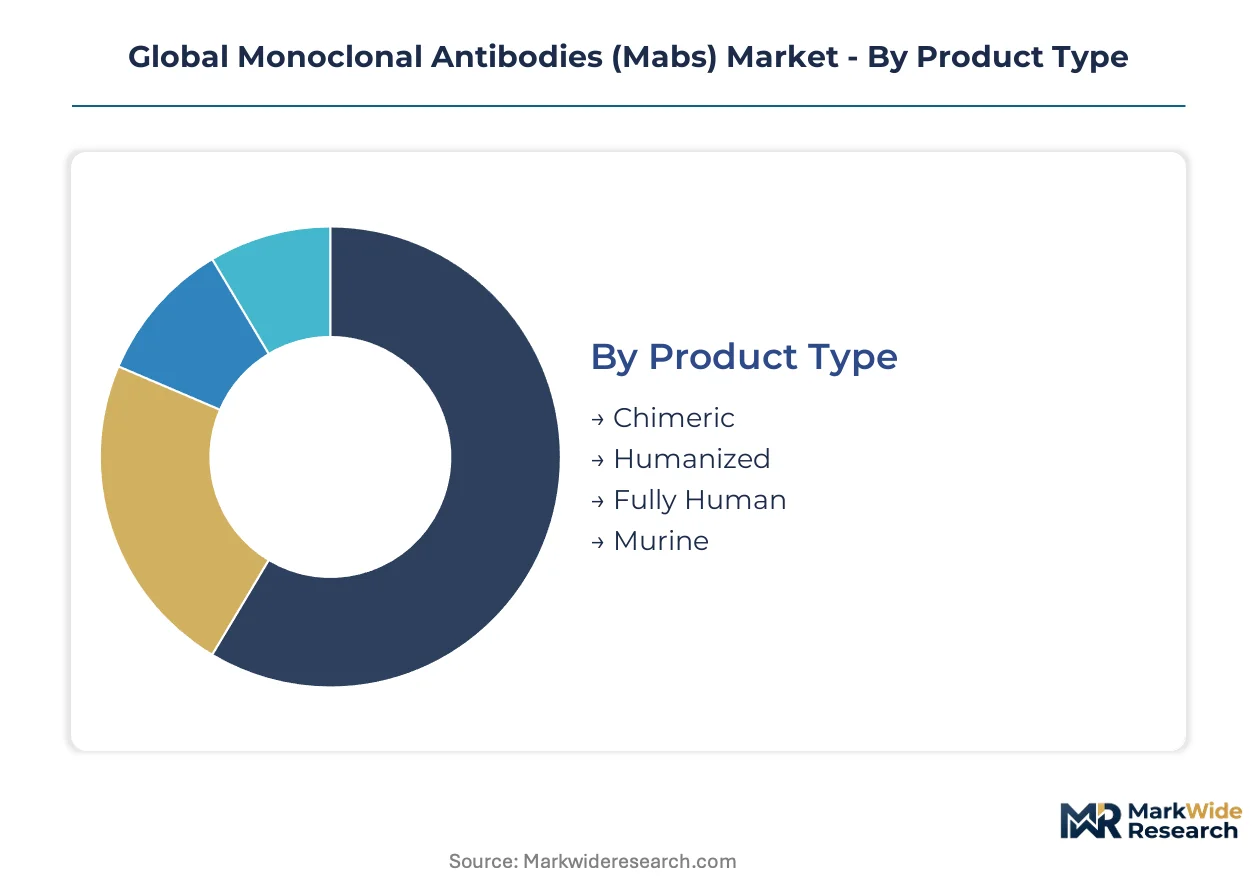
Monoclonal antibody market segmentation reveals distinct technology maturity curves and therapeutic application boundaries. Each dimension—molecular architecture, disease target, customer workflow, and administration pathway—carries unique margin profiles and regulatory complexity that reshape investment allocation across the value chain.
Product Type:
Engineered immunogenicity profiles span the full spectrum from murine origins to fully human constructs, with each tier commanding differentiated clinical positioning and manufacturing economics.
- Fully Human:Recombinant DNA techniques eliminate murine sequences entirely, yielding the lowest immunogenicity risk profile in chronic administration scenarios. Demand concentrates in United States Medicare-eligible populations for rheumatoid arthritis and psoriasis maintenance therapy, where anti-drug antibody formation would compromise long-term efficacy.
- Humanized:Complementarity-determining regions retain murine-derived antigen-binding specificity while framework regions are human-sequence grafted. Japanese PMDA approvals favor this format for oncology applications where tumor penetration kinetics outweigh immunogenicity concerns.
- Chimeric:Heavy and light chain variable regions fused to human constant domains deliver cost-efficient production with moderate immunogenicity trade-offs.
- Murine:Fully mouse-derived constructs now occupy niche diagnostic imaging and ex vivo research applications.
The dominant share belongs to Fully Human, while Humanized is closing the gap fastest through solid tumor bispecific expansion.
Therapy Area:
Clinical development spend distributes unevenly across disease categories, with reimbursement intensity and addressable patient pools determining pipeline prioritization.
- Oncology:Checkpoint inhibitors and antibody-drug conjugates target programmed cell death pathways with companion diagnostic requirements. United States academic medical centers drive protocol adoption through NCCN guideline integration.
- Autoimmune Disorders:TNF-alpha and interleukin pathway blockers command the highest per-patient annual therapy costs. European EMA label expansions for pediatric Crohn's disease and hidradenitis suppurativa are widening prescriber bases.
- Infectious Diseases:Post-exposure prophylaxis and resistant pathogen indications attract BARDA and CEPI funding.
- Neurological Conditions:Blood-brain barrier penetration challenges limit current utility to peripherally acting targets.
Oncology captures the steepest expansion trajectory through combination regimen approvals, though Autoimmune Disorders maintains the most durable pricing power.
End User:
Customer workflows fragment across discovery, clinical manufacturing, and commercial supply phases, with procurement sophistication varying sharply by organizational scale.
- Biopharmaceutical Companies:Integrated R&D-through-commercial organizations internalize cell line development and process characterization. FDA BLA submission volumes from top-20 sponsors concentrate manufacturing capacity reservations.
- Contract Manufacturing Organizations:Multi-product facilities in Switzerland and Singapore offer perfusion platform access without capital commitment. CDSCO harmonization is attracting Indian CMO investments.
- Research Institutes:NIH-funded academic centers license discovery-stage clones through technology transfer offices.
- Diagnostics Labs:IVD manufacturers source labeled antibodies for immunoassay kit production.
Biopharmaceutical Companies anchor demand volume, while Contract Manufacturing Organizations are expanding most quickly through sponsor outsourcing acceleration.
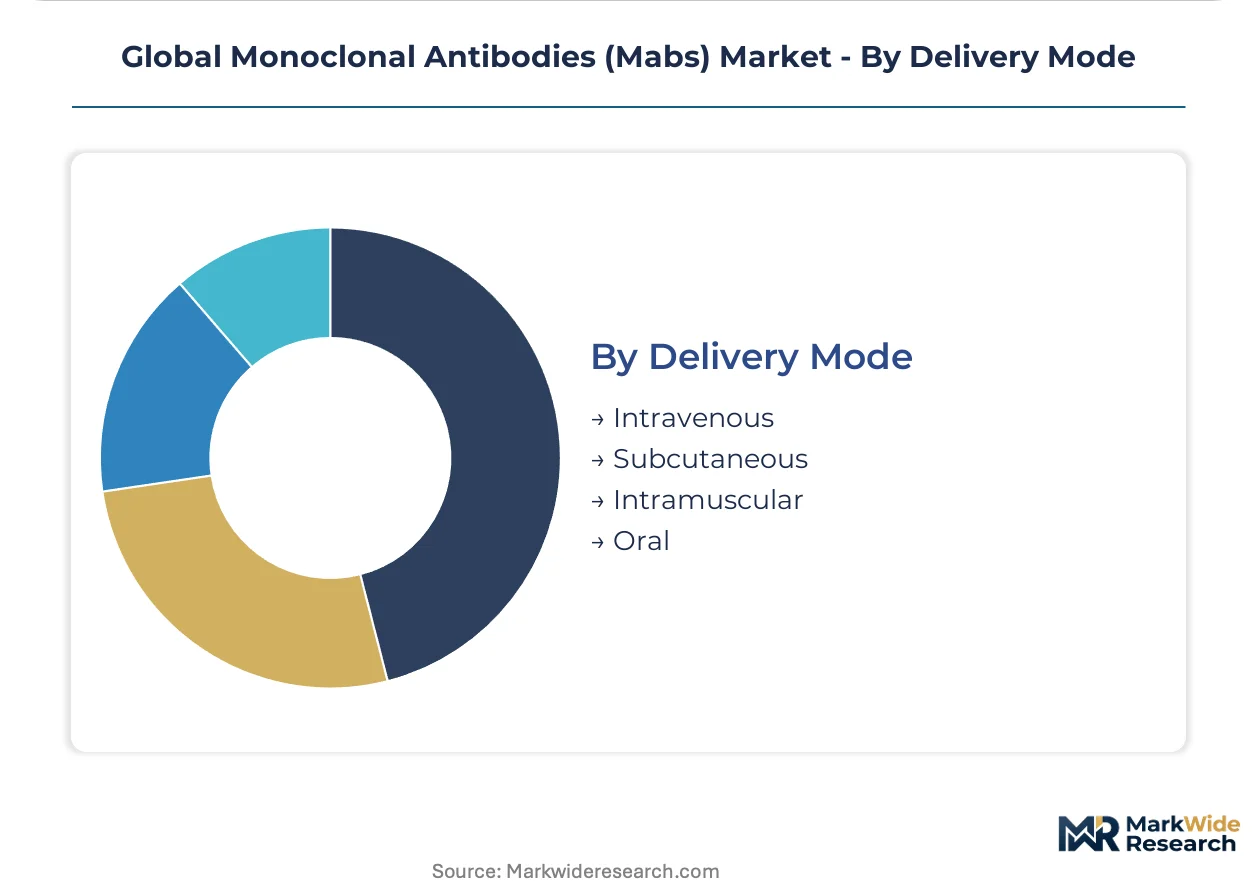
Delivery Mode:
Administration pathway selection reshapes formulation science requirements, cold chain economics, and site-of-care economics across patient populations.
- Subcutaneous:High-concentration protein formulations in prefilled syringes and auto-injector devices enable home administration. United States payer preference for reduced infusion center utilization is driving label conversions.
- Intravenous:Hospital and infusion center administration retains dominance for oncology loading doses and hypersensitivity monitoring requirements.
- Intramuscular:Rapid depot formation suits post-exposure prophylaxis applications.
- Oral:Gastrointestinal degradation barriers constrain current feasibility to research-stage mucosal delivery platforms.
Intravenous retains installed infrastructure dominance, while Subcutaneous is gaining share fastest through patient preference and total cost-of-care reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement frameworks and Medicare policy mechanics anchor United States prescribing volumes for infused mAb therapies. Manufacturing capacity regionalization now spans Basel-region fermentation clusters, Indian CDSCO-aligned facilities, and Singaporean perfusion platforms.
United States
Academic medical centers in Boston and New York Metro integrate mAb combination regimens into NCCN first-line oncology protocols. IRA Medicare price negotiation provisions create protected pricing windows for therapies launching ahead of eligibility cliffs. The Greater Boston corridor concentrates contract research organizations supporting BLA submission volumes from top-20 sponsors.
Switzerland
Basel-region fermentation facilities narrow biologics capacity gaps through expanded mammalian cell culture platforms. Swissmedic manufacturing standards align with EMA GMP Annex 1 sterile processing mandates. The Basel-Liestal corridor anchors high-margin therapeutic franchise production for chronic immunology indications.
India
CDSCO regulatory harmonization with ICH guidelines attracts contract development investments from Western sponsors. PLI scheme incentives accelerate indigenous fermentation capacity expansion for emerging market supply. The Hyderabad-Bengaluru corridor hosts multi-product CMO facilities adopting single-use bioreactor technologies.
Germany
EMA reference product exclusivity periods and patent linkage mechanisms create complex biosimilar entry windows for developers. REACH-compliant specialized media component supply chains face concentration risks from single-source suppliers. The Rhine-Main biotech cluster concentrates process characterization expertise for high-concentration subcutaneous formulations.
Singapore
Perfusion bioreactor platforms with integrated online analytics compress batch cycle times for Asia-Pacific contract manufacturing demand. EMA-equivalent GMP standards enable dual-approval pathway efficiency for European market access. The Tuas Biomedical Park anchors regional fill-finish capacity for prefilled syringe and auto-injector device assembly.
Global Monoclonal Antibodies (Mabs) Market Key Industry Players
Integrated biopharmaceutical conglomerates and specialized immunology anchors split the market between oncology checkpoint dominance and chronic disease maintenance therapy. Manufacturing scale concentration in mammalian cell culture platforms determines margin sustainability across both archetypes. Consolidation pressures intensify as reference product exclusivity cliffs accelerate biosimilar competitive entry. Dominant competitive moves include strategic capacity reservations at multi-product CMO facilities and portfolio diversification into bispecific antibody architectures.
Among Swiss-anchored heritage players, F. Hoffmann-La Roche exemplifies the oncology-focused conglomerate archetype through its Basel-region therapeutic franchise concentration. AbbVie occupies a position within the immunology-specialist tier, leveraging manufacturing scale that dominates supply chains for chronic disease treatment. Johnson & Johnson represents the diversified healthcare conglomerate archetype, sitting within a portfolio structure that spans pharmaceutical, medical device, and consumer health segments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| AbbVie |
| Johnson & Johnson |
| Merck & Co. |
| Bristol Myers Squibb |
| Amgen |
| Novartis AG |
| Eli Lilly and Company |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
CHO cell line single-source dependency compresses margin structures across both originator and biosimilar tiers while forcing supply chain regionalization into Switzerland, Singapore, and India. This input bottleneck simultaneously widens price spreads between fully human constructs and legacy formats while accelerating backward integration strategies among top-20 sponsors.
Pricing Analysis
United States Medicare reimbursement spreads diverge sharply from European tender pricing, with IRA negotiation eligibility windows creating protected premium periods for therapies launching ahead of cliffs. Pricing stratifies across fully human premium, humanized standard, and chimeric economy tiers based on immunogenicity profile and manufacturing complexity. Cost compression in the chimeric tier intensifies as biosimilar entry accelerates. Academic medical centers exhibit lowest price sensitivity due to protocol-driven purchasing, while emerging market governments drive hardest bargain through centralized procurement.
Supply Chain Analysis
Lonza, Samsung Biologics, and Boehringer Ingelheim anchor mammalian cell culture capacity across Basel-region, Singaporean, and Korean facilities. Fermentation supply concentrates in Switzerland, Singapore, and India as CDSCO harmonization attracts sponsor investment. Raw material dependencies center on Chinese Hamster Ovary cell lines, specialized chemically-defined media, and single-use bioreactor components. Single-source vulnerability in CHO cell line supply threatens campaign continuity. Distribution runs through integrated delivery networks and group purchasing organizations that displace traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital and infusion center purchasing consolidation through three dominant United States GPOs has shifted negotiating leverage toward buyers, compressing product markups and redirecting margin capture toward data and logistics services.
For Market Incumbents: Build manufacturing scale moats through perfusion platform adoption and Basel-region capacity reservations. Secure multi-year CHO cell line supply agreements to insulate against single-source disruption. Anchor formulary position through companion diagnostic bundling that raises switching costs for biosimilar challengers. For New Entrants and Emerging Players: Build out subcutaneous formulation capabilities to capture fastest-growing administration preference among United States payers. Target autoimmune maintenance therapy for price-sensitive Medicare populations underserved by infusion-dependent incumbents. Pursue CDSCO-aligned Indian manufacturing partnerships to serve emerging market tender demand. For Investors and Strategic Acquirers: FDA biosimilar interchangeability guidance reshapes the acquisition landscape by elevating substitutable product valuations above mere bioequivalent alternatives. Long-term viability hinges on pipeline depth in bispecific architectures and cell line development talent retention. Target contract manufacturers with perfusion platform adoption and EMA-equivalent GMP certification. Watch IRA Medicare price negotiation calendar as inflection signal for protected pricing window closures.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Platform Adoption | Compresses batch cycle times for Basel-region and Singaporean contract manufacturers serving sponsor demand. |
| Companion Diagnostic Bundling | Locks in oncology protocol adoption at United States academic medical centers through NCCN guideline integration. |
| CDSCO-Aligned Manufacturing Scale-Up | Captures emerging market tender volume through Indian PLI scheme incentives and regulatory harmonization. |
| Subcutaneous Formulation Conversion | Reduces infusion center utilization costs for United States payers while expanding patient self-administration. |
| Bispecific Antibody Pipeline Expansion | Opens solid tumor categories resistant to monotherapy through dual-targeting checkpoint and microenvironment modulation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA BLA submissions, EMA GMP Annex 1 revisions, ClinicalTrials.gov protocol registrations, and Medicare formulary databases. Bottom-up therapeutic area demand modeling was cross-checked against top-down manufacturer capacity utilization estimates to ensure convergence.
Calibration against historical approval timelines and capacity expansion announcements anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions spanned molecular architecture, therapy area, end-user workflow phase, and administration pathway. CAGRs were derived from patent cliff sequencing, biosimilar entry probability weighting, and regional reimbursement elasticity differentials. Forecast inputs incorporated CHO cell line supply constraints and perfusion technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich technology conglomerates or sovereign wealth funds into biologics manufacturing would shift outcomes beyond modeled ranges. Regulatory acceleration in India or trade restriction escalation in specialized media components represent revision triggers. Quarterly review of FDA biosimilar approval velocity and IRA negotiation eligibility calendar is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Global Carboprost Tromethamine Market