
 China Ready-To-Drink (RTD) Coffee Market | 2026-2036
China Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
China Ready-To-Drink (RTD) Coffee Market Outlook
Multi-pack bundling of smaller-format aluminum cans is expanding consumer trial rates across convenience-store channels. Nestle S.A. leverages its soluble-coffee supply infrastructure to anchor RTD production economics in Greater China. Suntory Holdings Ltd. competes through Japanese-origin positioning and premium glass-bottle formats in coastal cities. Tingyi Holding Corp. dominates mass-market shelf space via deep distribution into lower-tier city networks.
Ready-to-drink coffee comprises pre-brewed, shelf-stable or refrigerated coffee beverages sealed in aluminum, glass, or plastic containers, typically formulated with milk solids, sweeteners, and stabilizers to deliver consistent flavor and caffeine content without on-site preparation. The bottled segment sustains the largest revenue base due to broader retail availability and consumer familiarity, while cold brew captures the fastest growth trajectory as extraction methods improve and premium positioning resonates with younger buyers. Aluminum can packaging concentrates margin advantages through lighter logistics costs and recycling infrastructure scale.
SAMR enforces GB 7101 beverage standards and nutrition-labeling rules that constrain additive use and mandate disclosure, directly elevating reformulation costs for imported and domestic brands alike. NMPA-aligned food-contact material regulations for packaging further filter which container technologies gain market access. China's dual carbon goals from MEE pressure energy-intensive sterilization and aseptic filling processes, favoring capital-heavy producers with cleaner production lines. Stakeholders must weigh cold-chain investment against ambient-stable formulation trade-offs as regulatory and climatic constraints tighten in parallel.
Market Dynamics
Urban white-collar workers in Shanghai and Beijing are compressing consumption into commute windows, forcing manufacturers to optimize cold-chain logistics and ambient-stable formulations simultaneously.
Growth Catalysts
- GB 7101 beverage standards:SAMR-mandated formulation transparency is accelerating cleaner-label R&D investments across domestic production facilities.
- Cold brew extraction methods:Premium positioning among younger buyers is pulling capital toward aseptic filling lines and extended shelf-life technologies.
- Yangtze River Delta corridor:Convenience-store density and refrigerated logistics infrastructure are outpacing other domestic regions in per-capita RTD velocity.
Market Restraints
- Arabica price volatility:Input cost swings from Brazilian and Colombian harvest cycles compress margin predictability for mid-tier producers.
- MEE dual carbon goals:Energy-intensive sterilization processes face escalating compliance costs and carbon-intensity caps.
- Fresh coffee substitution:Luckin Coffee and Manner Coffee storefront proliferation threatens RTD trial rates among urban professionals.
Strategic Opportunities
- Lower-tier city networks:Distribution gaps in tier-three and tier-four municipalities create whitespace for ambient-stable, price-optimized formats.
- MIIT smart manufacturing incentives:Automation subsidies favor capital-heavy producers upgrading to IoT-enabled filling and quality-control systems.
- Glass-bottle premium channel:Coastal city convenience stores and specialty grocers are expanding shelf space for Japanese-origin positioning.
Industry Challenges
- Food-contact material certification:NMPA-aligned packaging regulations extend approval timelines for novel aluminum alloys and recycled-content plastics.
- Aseptic technician scarcity:Qualified operators for ultra-high-temperature processing lines command wage premiums that inflate unit economics.
- Cold-chain capex intensity:Refrigerated last-mile infrastructure demands upfront investment that ambient competitors avoid.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ready-To-Drink (RTD) Coffee Market |
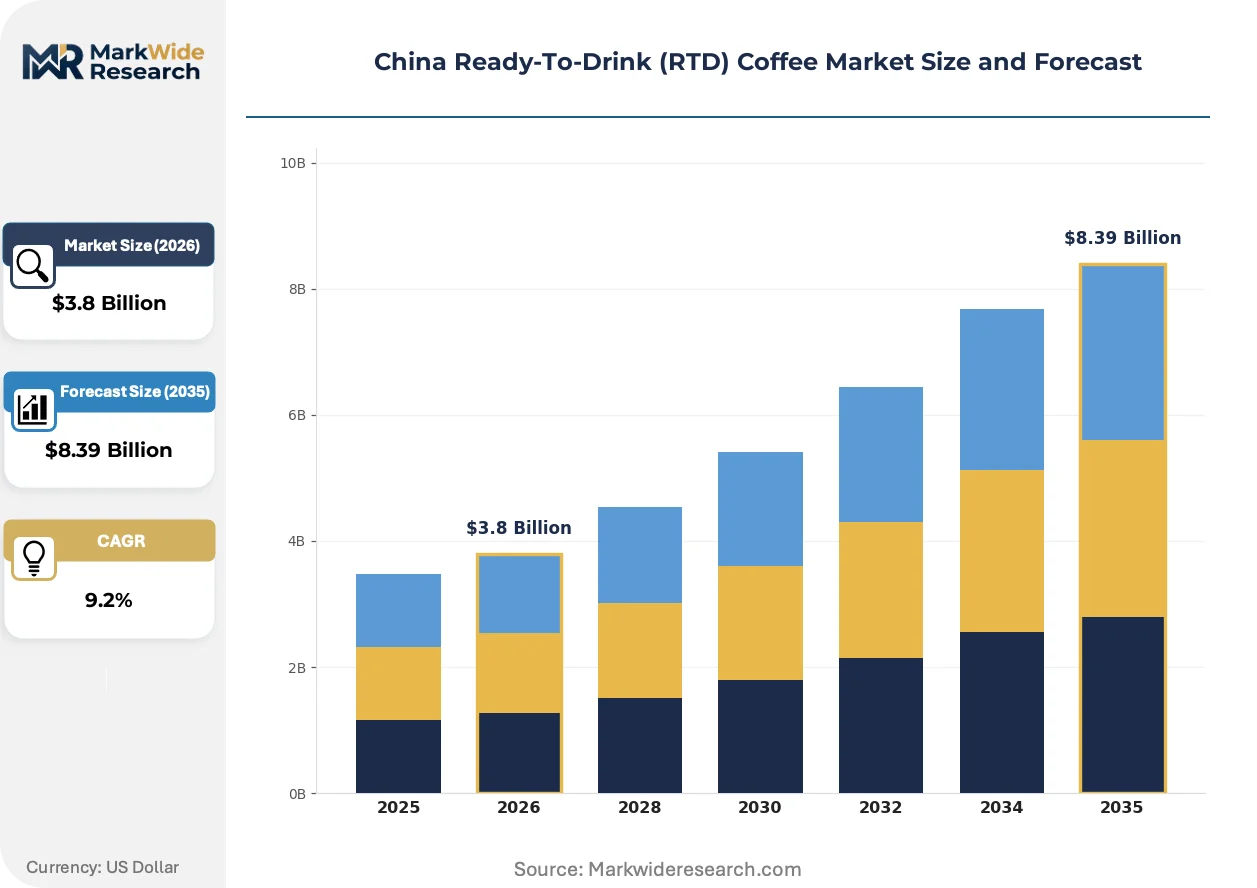
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Bottled, Powdered, Cold Brew Flavor Profile: Sweetened, Unsweetened, Mocha, Vanilla Packaging Type: Aluminum Can, Glass Bottle, Tetra Pak, Plastic Bottle Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Cafes |
| Companies Covered | Nestle S.A, Suntory Holdings Ltd, Uni-President Enterprises Corp, The Coca-Cola Company, Restaurant Brands International Inc., Starbucks Corporation, Tingyi Holding Corp, Nongfu Spring Co., Ltd., Vitasoy International Holdings Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ready-To-Drink (RTD) Coffee Market Strategic Shifts
Formulation science and packaging engineering are converging to extend shelf stability without sacrificing sensory quality, while regulatory pressure and consumer scrutiny accelerate ingredient deck simplification.
High-pressure processing is decentralizing quality control from centralized sterilization facilities toward distributed co-packing networks. Regional dairy and coffee processors in Jiangsu and Zhejiang are adopting HPP units at twice the rate of northern provinces. This shift is compressing lead times for seasonal flavor launches while reducing thermal degradation of volatile aromatic compounds.
GB standards on nutrition labeling are tightening disclosure thresholds for added sugars and synthetic stabilizers. Domestic brands face reformulation costs that imported competitors absorb through existing global R&D pipelines. Premium segments in Beijing and Shenzhen are responding with front-of-pack clean-label certifications that command shelf-space premiums.
Commute-window consumption patterns are fragmenting bulk purchasing toward single-serve impulse formats. Convenience stores in Shanghai are displacing supermarket multipacks with chilled grab-and-go placement near checkout zones. This rotation is most visible among 25-35 year old professionals in subway-adjacent retail clusters.
China Ready-To-Drink (RTD) Coffee Market Segmentation
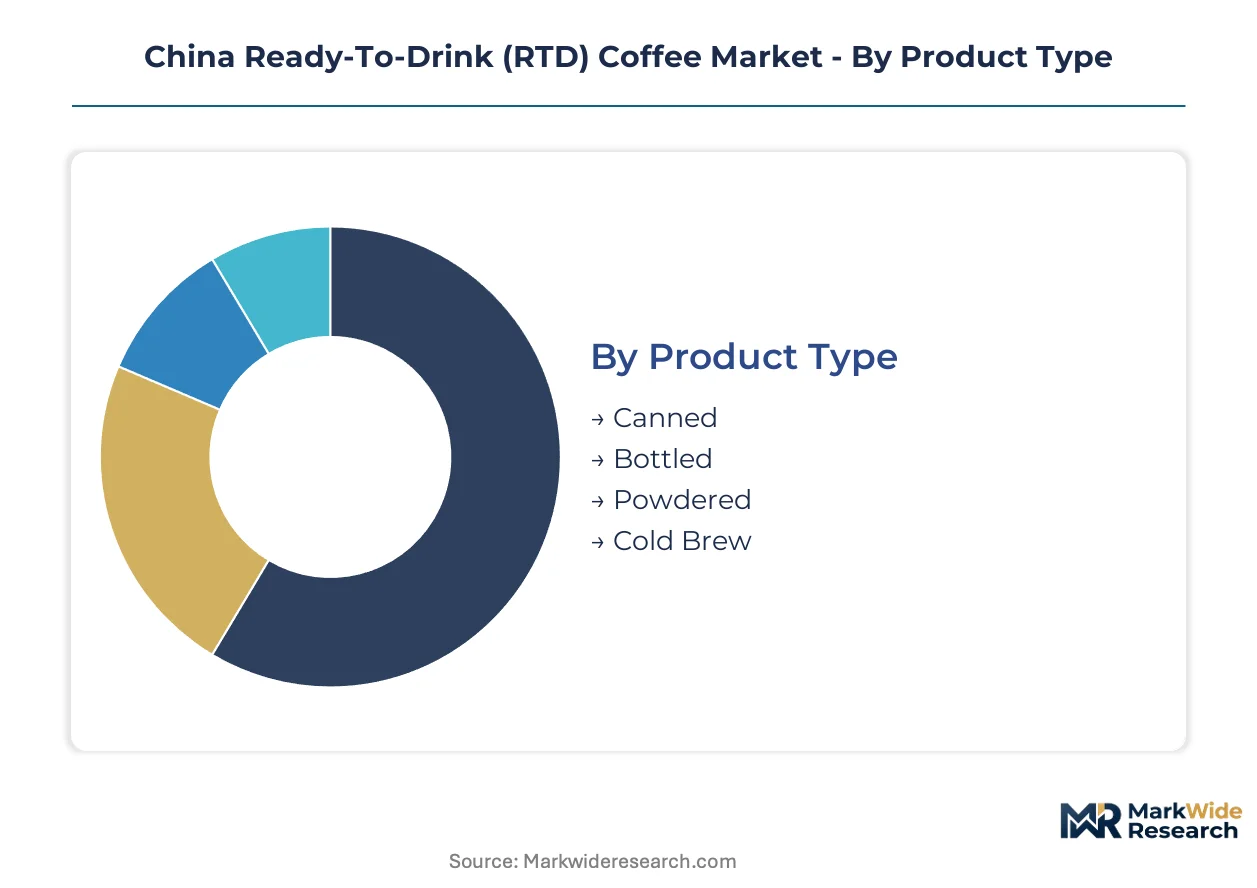
Segmentation in China's RTD coffee market reveals how consumption occasions, price sensitivity, and channel access fragment demand across distinct product configurations. Manufacturers must align formulation stability, packaging logistics, and retail placement to capture specific buyer moments from commute convenience to premium gifting.
Product Type:
Upgrade cycles in China's RTD coffee market trace shifting work patterns and cold-chain maturity, with consumers trading up from ambient-stable formats toward fresher-tasting alternatives as refrigerated infrastructure penetrates tier-one cities.
- Bottled:PET and glass containers dominate mass-market shelf presence through ambient distribution economics. Shanghai and Beijing convenience stores rotate chilled bottled SKUs near checkout zones to intercept morning commute traffic.
- Canned:Aluminum formats concentrate in lower-tier city networks where cold-chain gaps favor shelf-stable logistics. Tingyi Holding Corp. anchors mass-market penetration through deep distribution into tier-three and tier-four municipalities.
- Cold Brew:Extended extraction at ambient temperature preserves volatile aromatic compounds without thermal degradation. Coastal specialty grocers and premium convenience channels in Shenzhen expand shelf space for Japanese-origin glass-bottle positioning.
- Powdered:Soluble coffee concentrates enable on-the-go reconstitution for outdoor and travel occasions. Nestle S.A. leverages existing soluble infrastructure to supply co-packing networks across Greater China.
Bottled formats sit at the top of the volume ranking, with cold brew climbing the fastest as extraction methods improve and premium positioning resonates with younger buyers.
Flavor Profile:
Flavor diversification follows demographic segmentation, with sweetness calibration and dairy integration separating mass-market penetration from premium margin capture.
- Sweetened:Sugar and milk solids formulations dominate lower-tier city acceptance where palate familiarity drives trial conversion. GB 7101 beverage standards mandate added sugar disclosure, elevating reformulation costs for domestic brands.
- Unsweetened:Black coffee positioning targets health-conscious professionals and calorie-tracking consumers. Beijing and Shenzhen front-of-pack clean-label certifications command shelf-space premiums in premium channels.
- Mocha:Chocolate-coffee hybrid appeals to younger demographics seeking dessert-replacement occasions. Convenience stores in the Yangtze River Delta corridor rotate seasonal mocha SKUs during winter months.
- Vanilla:Flavoring integration softens bitterness for entry-level coffee consumers. Coastal city specialty grocers expand vanilla-variant placement alongside Japanese-origin imports.
Sweetened variants hold the volume lead, though unsweetened formats are expanding most quickly as SAMR labeling transparency and health consciousness reshape formulation priorities.
Packaging Type:
Material selection balances logistics economics, recycling infrastructure, and sensory preservation against NMPA food-contact certification timelines.
- Aluminum Can:Lightweight logistics and established recycling streams compress unit economics for high-velocity SKUs. Multi-pack bundling of smaller-format cans expands trial rates across convenience-store channels.
- Glass Bottle:Premium perception and chemical inertness support extended shelf stability without flavor migration. Suntory Holdings Ltd. competes through Japanese-origin positioning in coastal city convenience stores.
- Plastic Bottle:PET versatility enables diverse format sizing from single-serve to family packs. MEE dual carbon goals pressure recycled-content adoption, extending approval timelines for novel polymer formulations.
- Tetra Pak:Aseptic carton technology bridges ambient distribution with extended shelf life. Regional dairy processors in Jiangsu and Zhejiang adopt carton lines for seasonal flavor launches.
Plastic bottles maintain volume dominance, while glass bottles gain share fastest in premium coastal channels where origin positioning commands price premiums.
Distribution Channel:
Channel strategy must reconcile cold-chain intensity against impulse-placement economics, with each route commanding distinct packaging and formulation trade-offs.
- Convenience Stores:Chilled grab-and-go placement near checkout zones captures compressed commute-window consumption. Shanghai subway-adjacent retail clusters displace supermarket multipacks with single-serve impulse formats.
- Supermarkets:Bulk multipack economics favor ambient-stable formulations and family-size SKUs. Lower-tier city networks rely on supermarket penetration where convenience-store density remains underdeveloped.
- Online Retailers:Direct-to-home fulfillment enables subscription models and flavor variety bundling. Cold-chain last-mile infrastructure demands upfront investment that ambient competitors avoid.
- Cafes:On-premise chilled cabinet placement targets premium trial and brand elevation. Luckin Coffee and Manner Coffee storefront proliferation threatens RTD trial rates among urban professionals.
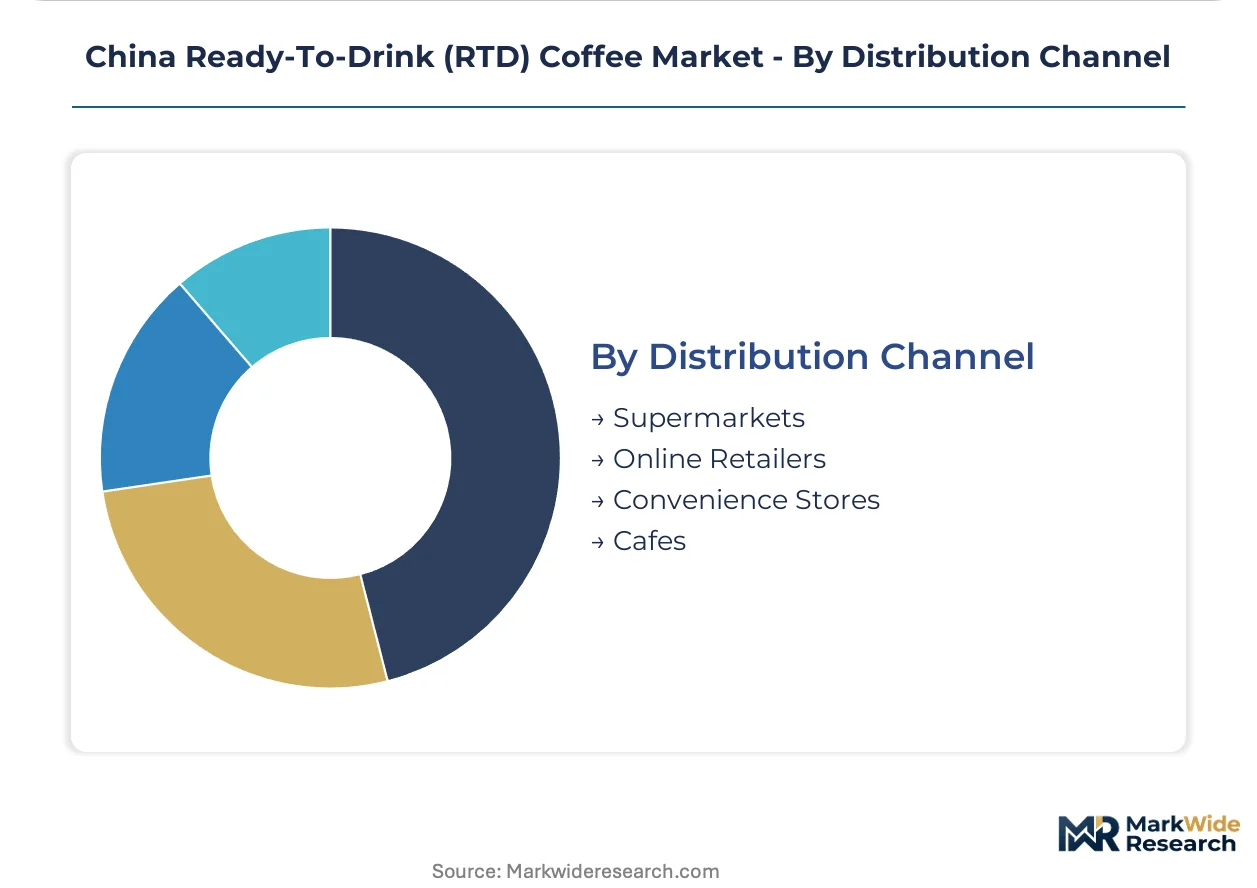
Convenience stores lead by volume velocity, with online retailers showing the steepest expansion trajectory as logistics networks mature and subscription models lock in repeat purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's RTD coffee industry traces its modern scale to Nestle's soluble coffee infrastructure build-out in the 1990s, which established manufacturing templates later adapted for bottled and canned formats. The market now concentrates in coastal corridors where cold-chain density and convenience-store penetration enable premium format distribution.
Yangtze River Delta
Shanghai and Hangzhou white-collar workers compress consumption into subway-adjacent commute windows, driving chilled grab-and-go placement strategies. SAMR's GB 7101 beverage standards mandate nutrition-label transparency that elevates reformulation costs for domestic brands operating here. Jiangsu and Zhejiang regional processors adopt high-pressure processing units at twice northern provincial rates, shortening seasonal flavor lead times.
Pearl River Delta
Shenzhen and Guangzhou consumers demonstrate strongest appetite for Japanese-origin glass-bottle positioning and unsweetened black coffee variants. MEE dual carbon goals pressure energy-intensive sterilization facilities across Guangdong province, favoring capital-heavy producers with cleaner production lines. Dongguan manufacturing clusters supply aseptic filling equipment to regional dairy processors expanding into RTD coffee co-packing.
Beijing-Tianjin-Hebei
Capital region professionals prioritize clean-label certifications and front-of-pack disclosure, responding to SAMR's tightening additive regulations. MIIT smart manufacturing incentives subsidize IoT-enabled quality-control system upgrades for automated filling lines. Tianjin port infrastructure handles imported Arabica bean flows serving northern China's soluble coffee concentrate production.
Sichuan-Chongqing
Western China's emerging middle class in Chengdu and Chongqing creates whitespace for ambient-stable, price-optimized canned formats where cold-chain gaps persist. GB national food safety standards filter market access for novel packaging technologies seeking NMPA food-contact material certification. Chongqing's logistics hub position enables distribution into tier-three and tier-four municipalities across southwestern provinces.
China Ready-To-Drink (RTD) Coffee Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation transparency and cold-chain investment intensity, creating a tiered structure where clean-label R&D separates price bands. The vendor base clusters around three strategic archetypes: multinational beverage conglomerates leveraging global supply infrastructure, domestic FMCG giants with deep lower-tier distribution networks, and specialty coffee retailers extending brand equity into packaged formats. Dominant competitive moves include vertical integration into soluble coffee concentrate production and strategic partnerships with regional dairy processors for co-packing capacity.
Within the multinational tier, Nestle S.A. and Suntory Holdings Ltd. exemplify divergent positioning strategies—Swiss-origin soluble-coffee supply dominance versus Japanese-origin premium glass-bottle coastal positioning. Tingyi Holding Corp. anchors the domestic mass-market archetype through ambient-stable can formats penetrating tier-three and tier-four networks where refrigerated logistics remain underdeveloped. These three entities collectively represent the competitive spectrum from commodity-margin scale to premium-margin origin positioning.
| Leading Market Players |
|---|
| Nestle S.A |
| Suntory Holdings Ltd |
| Uni-President Enterprises Corp |
| The Coca-Cola Company |
| Restaurant Brands International Inc. |
| Starbucks Corporation |
| Tingyi Holding Corp |
| Nongfu Spring Co., Ltd. |
| Vitasoy International Holdings Ltd. |
| Others |
Value Chain & Pricing Dynamics
Arabica futures on the Intercontinental Exchange cascade through China's RTD coffee supply chain, compressing margin buffers for mid-tier producers while premium brands absorb volatility through long-term Brazilian and Colombian offtake contracts. This commodity-driven cost structure stratifies pricing power across three distinct tiers anchored by cold-chain investment intensity and formulation transparency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates glass-bottle cold brew in Shanghai convenience stores from aluminum-can mass-market SKUs in tier-three cities. Price differentiation hinges on SAMR-mandated clean-label certification and refrigerated logistics density. Cost compression in the economy tier intensifies as Tingyi Holding Corp. optimizes ambient-stable formulations for lower-tier networks. White-collar professionals in Beijing and Shenzhen demonstrate lowest price sensitivity, prioritizing front-of-pack disclosure and Japanese-origin positioning over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements for Arabica beans mandate qualification across Brazilian and Colombian origins, with Vietnamese Robusta blending for cost-optimized SKUs. The supply chain draws from soluble coffee concentrate production in Tianjin, aseptic filling equipment manufacturing in Dongguan, and regional dairy processor networks across Jiangsu and Zhejiang. Single-source vulnerability concentrates in cold-chain logistics providers serving the Yangtze River Delta corridor. Distribution runs through convenience-store chains in tier-one cities, supermarket bulk channels in lower-tier municipalities, and direct-to-home fulfillment for subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
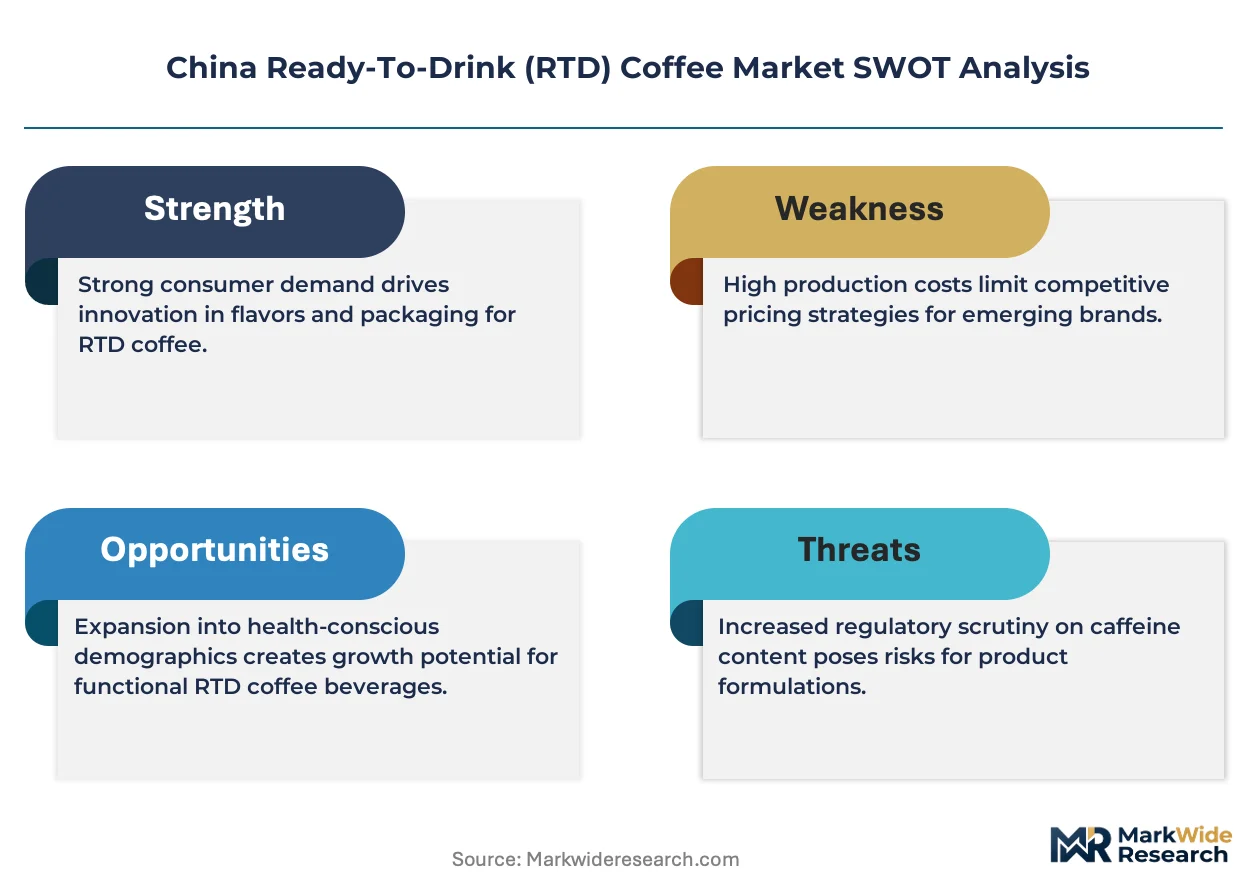
China's RTD coffee market functions as a regulatory compounder where SAMR's GB 7101 beverage standards and MEE dual carbon goals continuously elevate compliance costs, favoring capital-heavy incumbents with captive R&D infrastructure.
For Market Incumbents: Cement dominance through backward integration into soluble coffee concentrate production and IoT-enabled filling line upgrades subsidized by MIIT smart manufacturing incentives. Fresh coffee substitution from Luckin Coffee and Manner Coffee storefronts threatens trial rates; defend through exclusive chilled cabinet placement in subway-adjacent retail clusters. For New Entrants and Emerging Players: High-pressure processing technology offers a technology-first wedge for regional dairy processors seeking RTD coffee co-packing contracts. Target tier-three and tier-four municipalities in Sichuan-Chongqing where cold-chain gaps persist and ambient-stable canned formats face minimal premium competition. Lead with price-optimized SKUs distributed through supermarket bulk channels. For Investors and Strategic Acquirers: Consolidation pressure builds where aseptic technician scarcity inflates unit economics for mid-tier producers lacking automated quality-control systems. Long-term viability favors capital-heavy players with NMPA-aligned packaging certification pipelines. Watch GB standards tightening on added sugar disclosure as the inflection indicator for reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soluble Concentrate | Nestle S.A. leverages existing infrastructure to compress input costs for co-packing networks. |
| Aseptic Filling Line Automation | MIIT subsidies reduce wage premiums for scarce ultra-high-temperature processing technicians. |
| Clean-Label Certification Investment | SAMR-mandated disclosure elevates shelf-space premiums in Beijing and Shenzhen convenience stores. |
| Cold-Chain Logistics Partnership | Refrigerated last-mile infrastructure captures commute-window consumption in Shanghai subway clusters. |
| Lower-Tier Distribution Expansion | Tingyi Holding Corp. penetrates tier-three cities where ambient-stable formats bypass cold-chain capex. |
Study Parameters
Bottom-up convenience-store velocity modeling reconciled against top-down soluble coffee concentrate production tracking forms the analytical core of this study. Primary interviews with brand managers at multinational beverage conglomerates, category buyers at convenience-store chains, supply planners at regional dairy processors, and regulatory affairs leads navigating SAMR certification generated operational data. Secondary validation drew from customs records of Arabica bean imports, Nielsen retail audit data for chilled placement metrics, SEC filings of listed FMCG parents, and MIIT automation subsidy disclosures.
Historical trendline analysis of bottled versus canned format penetration across tier-one through tier-four cities established baseline growth patterns across the projection horizon. The quantitative framework models segmentation dimensions including packaging material, flavor profile, distribution channel, and regional cold-chain maturity. CAGRs derive from curve-fitting observed velocity data against regulatory milestone timelines and infrastructure investment cycles. Forecast inputs incorporate MEE carbon-intensity cap trajectories and NMPA food-contact material approval timelines.
The model holds under stable Brazilian and Colombian harvest conditions with sustained SAMR enforcement intensity; deviation in Arabica price volatility or GB standards acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Extracts Market
Coffee
Green Coffee Bean Extract Market
Coffee
Oceania Coffee Market
Coffee
Butter Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
India Coffee Roaster Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Global Cafe Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
RTD Coffee Market
Coffee
Coffee Bottle Market
Coffee
High Protein Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
Espresso Tamper Market
Coffee
Specialty Coffee Market