
 Cafix Market | 2026-2036
Cafix Market Size, Share, and Industry Trends Forecast 2026-2036
Cafix Market Outlook
The capability gap between vertically integrated roasters and private-label assemblers is collapsing as commodity chicory prices erode brand premiums. Teeccino Coffee leverages its proprietary roasted grain supply chain to sustain margin integrity across North American natural food channels. Dandy Blend anchors its position through direct-to-consumer subscription models that compete effectively against mass-market shelf placements. MUD\WTR differentiates via adaptogenic ingredient positioning that occupies the functional beverage crossover segment.
Cafix denotes roasted grain and chicory-based instant beverages formulated as caffeine-free coffee alternatives, typically produced through drum roasting at temperatures between 180°C and 220°C followed by aqueous extraction and spray-drying to preserve volatile aromatic compounds. The product serves consumers seeking to eliminate caffeine intake while retaining the sensory ritual of hot brewed drinks. Instant Drink formulations lead volume due to convenience alignment with busy professional routines, though Roasted Grain whole-bean formats capture superior margins through specialty health store distribution. Herbal Blend variants represent the fastest-expanding category as adaptogenic ingredients reshape consumer expectations around functional benefits. Coffee Substitute positioning in conventional supermarkets remains mature with limited pricing power relative to premium channel alternatives.
FDA labeling requirements for caffeine content declarations and EU Regulation 1169/2011 on food information to consumers shape product formulation transparency and cross-border market access protocols. EFSA health claim assessments on chicory root fiber further influence permissible marketing language in European jurisdictions. Stakeholders must monitor evolving caffeine-free certification standards and adaptogenic ingredient approval pathways to sustain competitive positioning as regulatory scrutiny intensifies across multiple geographies.
Market Dynamics
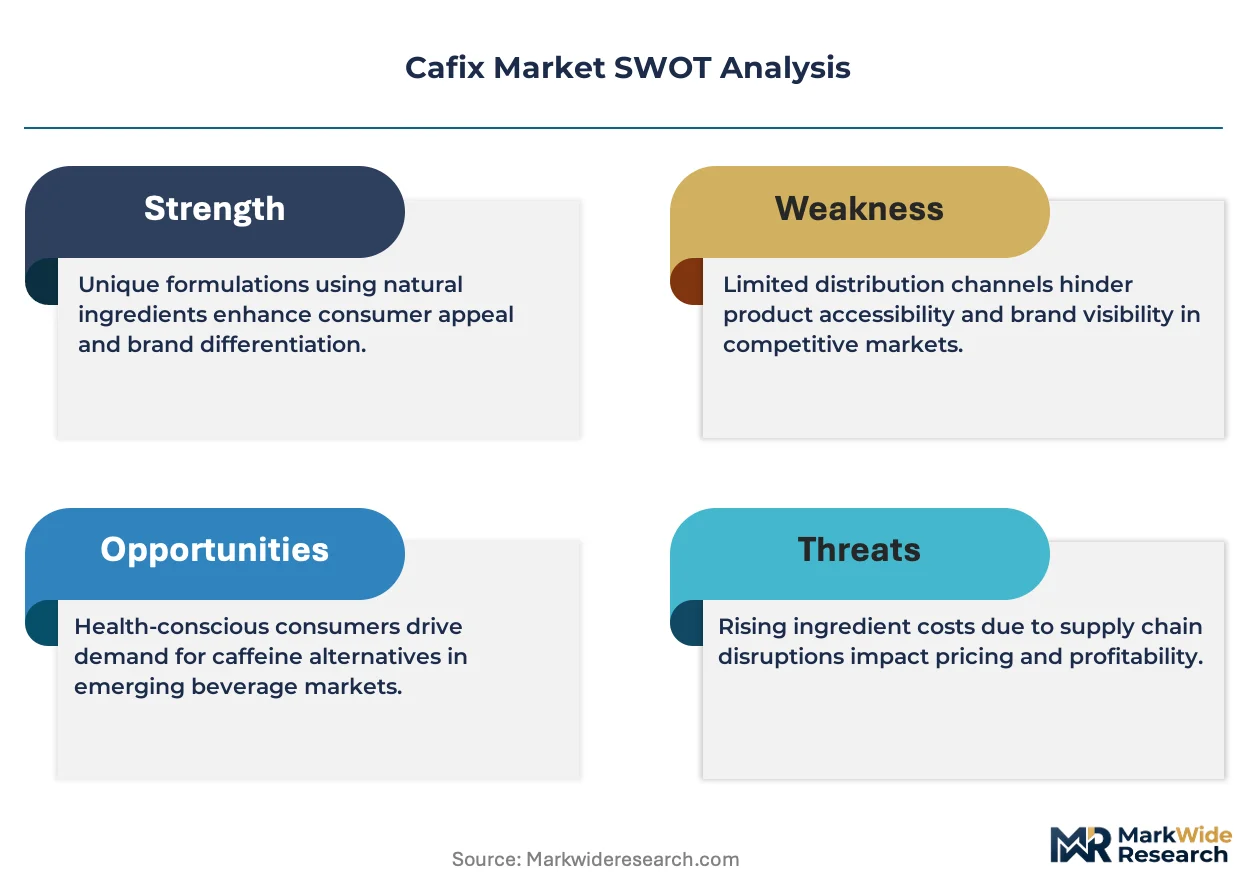
EU Regulation 1169/2011 on food information transparency is compressing formulation flexibility while chicory root supply concentration in Belgium and France reshapes procurement economics for grain-based coffee alternatives.
Growth Catalysts
- Clean-label mandates:EFSA health claim assessments on chicory root fiber validate functional positioning in German and French wellness cafés.
- Specialty channel expansion:Roasted grain whole-bean formats capture premium shelf space in UK health food cooperatives.
- Adaptogenic ingredient convergence:Functional beverage crossovers in North American natural food channels broaden consumption occasions beyond morning rituals.
Market Restraints
- Input cost volatility:Commodity chicory price swings in Belgian processing hubs erode margin predictability for private-label assemblers.
- Technical limitation:Spray-drying at 180°C to 220°C degrades volatile aromatic compounds, constraining sensory parity with conventional coffee.
- Substitution threat:Low-acid arabica and decaffeinated specialty coffee retain ritual authenticity for caffeine-reducing consumers.
Strategic Opportunities
- Underpenetrated geography:Nordic markets show latent demand for caffeine-free morning rituals with established botanical consumption culture.
- Distribution innovation:Direct-to-consumer subscription models bypass conventional supermarket slotting fees and build recurring revenue.
- Regulatory tailwind:EU Green Deal sustainable packaging mandates favor instant drink formats with reduced shipping intensity.
Industry Challenges
- Certification timeline compression:FDA caffeine content declaration requirements demand reformulation cycles that strain R&D bandwidth.
- Skill scarcity:Drum roasting expertise at 180°C to 220°C thresholds concentrates among aging European equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cafix Market |
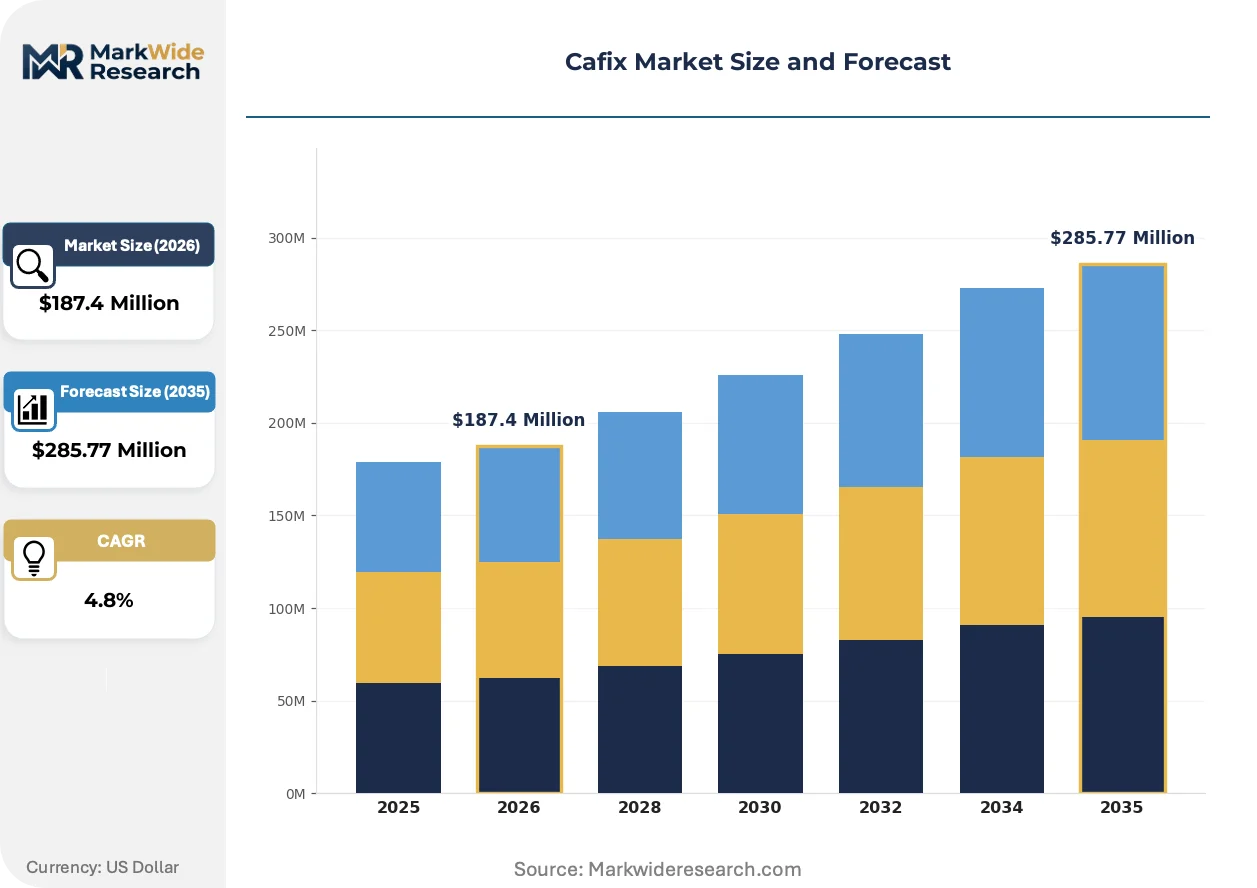
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Drink, Roasted Grain, Coffee Substitute, Herbal Blend Packaging Type: Box, Pouch, Jar, Sachet Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Customer Type: Health-Conscious Consumers, Vegans, Coffee Drinkers, Busy Professionals |
| Companies Covered | Teeccino Coffee, Dandy Blend (Goosefoot Acres), MUD\WTR, Postum (Eliza's Quest Foods), Rasa Inc., Tattva's Herbs LLC, Ayurvedic Roast (Only Tasty Goods), The Hain Celestial Group Inc., World Finer Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cafix Market Strategic Shifts
Formulation science and regulatory transparency requirements are compressing traditional competitive moats while demand patterns fragment across convenience and premium ritual segments.
Low-temperature aqueous extraction protocols are miniaturizing production footprints for specialty roasters. Boutique wellness cafés in Berlin and Copenhagen adopt compact drum roasting cells that preserve volatile aromatic compounds previously lost to industrial spray-drying scale. This technology is miniaturizing the capability gap between artisan producers and commodity processors.
REACH chemical safety assessments and EFSA novel food approvals are extending ingredient validation timelines. Chicory root fiber and emerging adaptogenic compounds face cumulative toxicology requirements that delay market entry by 18 to 36 months. European jurisdictions with established botanical traditions are accelerating pre-submission consultations to compress regulatory uncertainty.
Subscription-based replenishment is displacing conventional retail discovery for habitual consumers. Direct channels capture lifetime value through personalized roast profiles while mass-market shelf placements stagnate. This behavioral pivot concentrates in North American metropolitan markets with established specialty coffee culture and high digital commerce penetration.
Cafix Market Segmentation
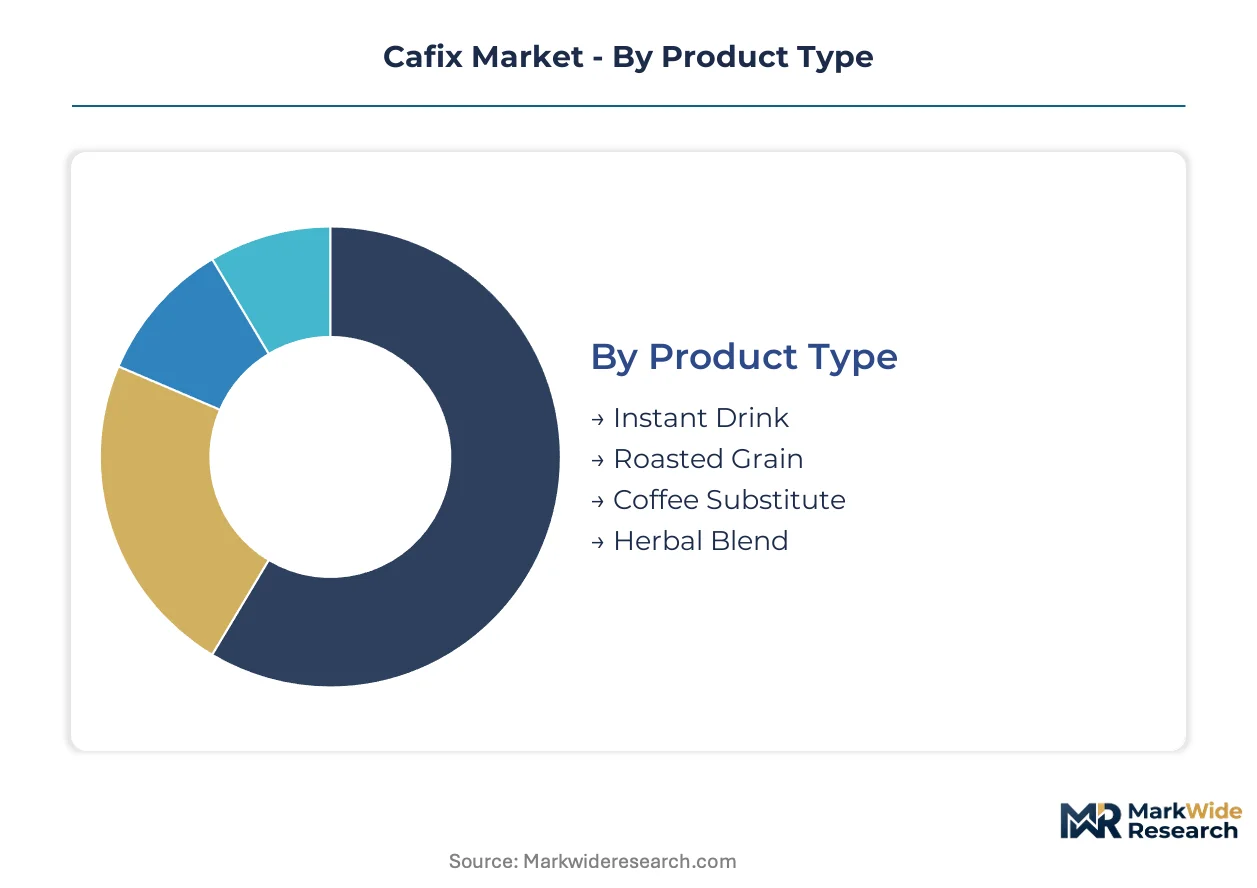
Grain-based coffee alternatives fragment across four distinct product architectures, each commanding differentiated shelf economics and regulatory scrutiny. Packaging configurations and channel strategies must align with the consumption ritual—convenience versus ceremony—that each customer segment prioritizes.
Product Type:
EFSA novel food approvals and FDA caffeine content declarations create divergent compliance burdens across formulation categories, compressing time-to-market for adaptogenic variants while grandfathering traditional roasted grain formats.
- Instant Drink:Spray-dried aqueous extracts of roasted chicory and barley dissolve in hot water without brewing equipment. German wellness cafés and French office canteens concentrate procurement here, driven by EU Green Deal packaging mandates that favor reduced shipping intensity.
- Roasted Grain:Whole roasted barley, rye, and chicory root require grinding and brewing like conventional coffee. UK health food cooperatives and Nordic specialty retailers capture premium margins through drum-roasted small batches, though Belgian commodity processors dominate volume supply.
- Coffee Substitute:Blends positioned explicitly as caffeine-free coffee alternatives in conventional supermarkets. Mature category with limited pricing power relative to premium channel alternatives.
- Herbal Blend:Adaptogenic ingredients including ashwagandha and lion's mane reshape functional expectations. REACH chemical safety assessments extend validation timelines for North American natural food channel entrants.
Established volume favors Instant Drink; emerging adoption favors Herbal Blend.
Packaging Type:
Cost-to-serve economics stratify sharply between single-serve convenience and bulk pantry formats, with subscription models disrupting traditional slotting fee structures.
- Box:Multi-serve cartons dominate pantry replenishment cycles in North American metropolitan markets with established specialty coffee culture.
- Pouch:Flexible film reduces per-unit shipping cost for direct-to-consumer replenishment channels displacing retail discovery.
- Jar:Glass containers command premium positioning in Berlin and Copenhagen boutique wellness cafés adopting compact drum roasting cells.
- Sachet:Single-serve sticks align with busy professional routines in French and UK urban centers seeking caffeine-free morning rituals.
Volume concentrates in Box and Pouch; margin expansion concentrates in Jar and Sachet.
Distribution Channel:
Customer lifetime value diverges between habitual replenishment through direct channels and episodic discovery through mass-market shelf placement.
- Online Retail:Subscription-based replenishment captures recurring revenue through personalized roast profiles. Teeccino Coffee and Dandy Blend anchor positioning here with proprietary supply chain control.
- Supermarkets:Conventional shelf placement stagnates as slotting fees erode margin predictability for private-label assemblers facing commodity chicory price swings.
- Health Stores:UK health food cooperatives and German natural food channels sustain premium pricing for clean-label certified formats.
- Specialty Shops:Berlin and Copenhagen wellness cafés drive adoption of low-temperature aqueous extraction protocols miniaturizing production footprints.
Online Retail climbs the fastest; Supermarkets face structural compression.
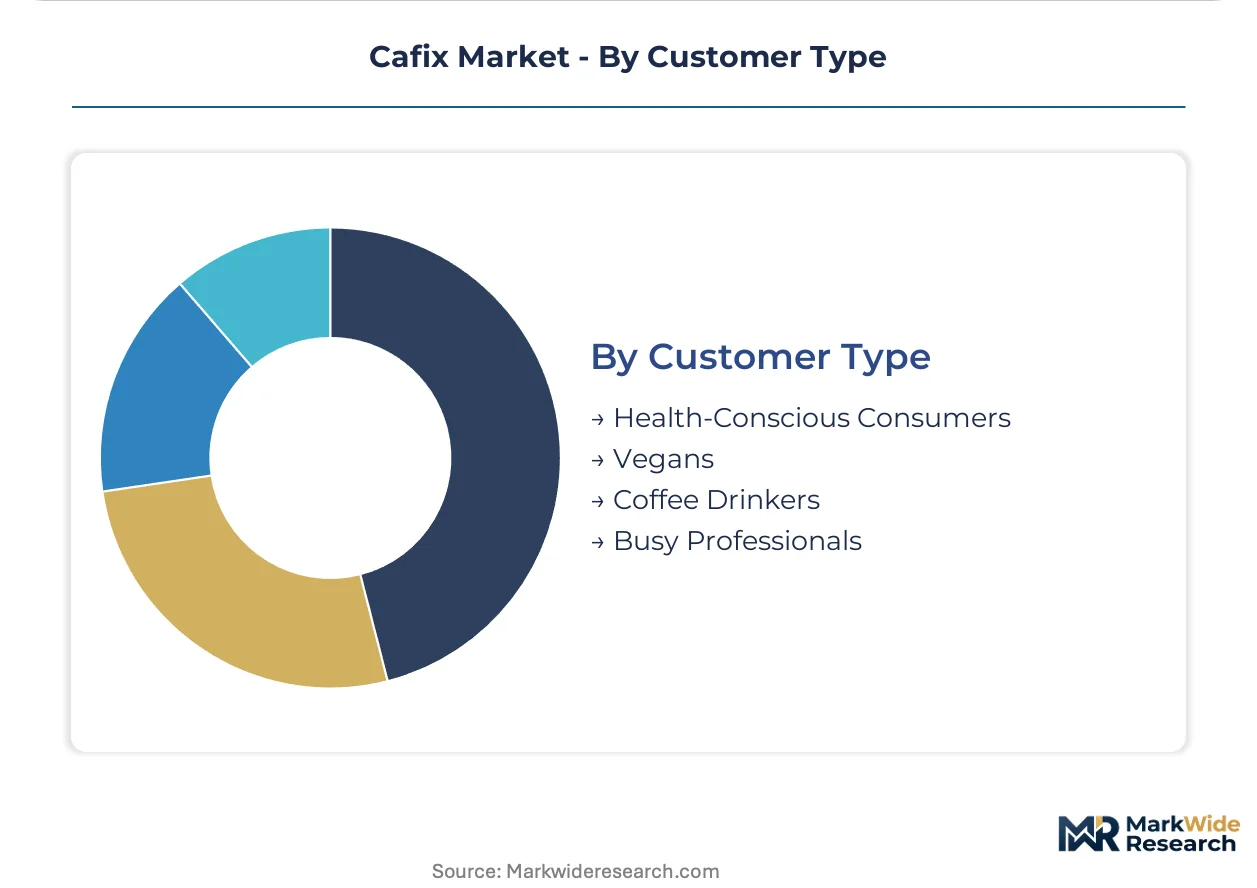
Customer Type:
Consumption occasion fragmentation demands distinct messaging architectures across ritual replacement versus functional supplementation motivations.
- Health-Conscious Consumers:Clean-label certification requirements under EU regulation reshape formulation standards for this core demographic.
- Vegans:Plant-based positioning aligns with grain and chicory sourcing excluding animal derivatives entirely.
- Coffee Drinkers:Caffeine-reducing consumers retain ritual authenticity concerns, creating substitution threat from low-acid arabica and decaffeinated specialty coffee.
- Busy Professionals:Convenience alignment with instant formats dominates morning routine substitution in German and French urban centers.
Health-Conscious Consumers anchor current revenue; Busy Professionals drive expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes Cafix as a functional wellness beverage integrated into morning routines, while North American buyers treat it as a coffee alternative for caffeine elimination, creating divergent product-positioning requirements across Atlantic markets.
Germany
Wellness cafés in Berlin and Munich drive specialty-grade roasted grain adoption among health-conscious professionals seeking clean-label morning rituals. EFSA health claim assessments on chicory root fiber validate functional positioning under EU Regulation 1169/2011. The Bavarian processing corridor concentrates drum roasting expertise for small-batch supply to natural food cooperatives.
United States
Direct-to-consumer subscription models capture habitual replenishment in metropolitan markets with established specialty coffee culture. FDA caffeine content declaration requirements demand precise labeling reformulation for cross-border European imports. Pacific Northwest urban clusters anchor natural food channel distribution for adaptogenic herbal blend variants.
France
Office canteens and urban hospitality channels concentrate procurement of instant drink formats aligned with convenience-driven professional routines. EU Green Deal sustainable packaging mandates favor reduced shipping intensity for spray-dried aqueous extracts. The Paris basin logistics network enables rapid replenishment cycles for caffeine-free morning ritual substitution.
United Kingdom
Health food cooperatives sustain premium pricing for clean-label certified roasted grain whole-bean formats. REACH chemical safety assessments extend validation timelines for novel adaptogenic ingredient introductions. London and Southeast England retail clusters drive specialty channel expansion beyond conventional supermarket placements.
Belgium
Commodity chicory processing hubs supply volume feedstock to private-label assemblers across Northwestern Europe. EFSA novel food approval pathways influence permissible marketing language for functional ingredient positioning. The Flemish agricultural belt concentrates root crop cultivation and industrial-scale aqueous extraction infrastructure.
Cafix Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier competing on formulation transparency and supply chain provenance. The capability gap between vertically integrated roasters and private-label assemblers collapses as commodity input prices erode brand premiums. Three archetypes dominate: proprietary roasted grain supply chain operators, direct-to-consumer subscription specialists, and adaptogenic functional beverage crossovers. Capacity expansion in compact drum roasting cells and strategic partnerships with wellness café networks represent the dominant competitive moves.
Among North American natural food channel anchors, Teeccino Coffee exemplifies integrated supply chain control, while Dandy Blend occupies the subscription-model specialist position. MUD\WTR represents the functional beverage crossover archetype through adaptogenic ingredient positioning. These three entities collectively illustrate how grain-based coffee alternatives fragment across convenience, premium ritual, and functional supplementation vectors without consolidated market leadership.
| Leading Market Players |
|---|
| Teeccino Coffee |
| Dandy Blend (Goosefoot Acres) |
| MUD\WTR |
| Postum (Eliza's Quest Foods) |
| Rasa Inc. |
| Tattva's Herbs LLC |
| Ayurvedic Roast (Only Tasty Goods) |
| The Hain Celestial Group Inc. |
| World Finer Foods |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Belgian chicory processors and German wellness café networks lock in both raw material access and price visibility for roasted grain whole-bean formats. These agreements insulate specialty roasters from commodity spot volatility while compressing margin flexibility for private-label assemblers dependent on spot-market feedstock.
Pricing Analysis
After-sales subscription revenue drives lifetime value for direct-to-consumer specialists competing against mass-market shelf placements. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and drum-roasting batch scale. Price erosion runs through private-label instant drink tiers as Belgian commodity processors flood volume supply. Health-conscious consumers in UK health food cooperatives show least price sensitivity; busy professionals in French office canteens exhibit highest elasticity.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp feedstock lanes elevates inbound logistics costs for North American natural food channel distributors sourcing Belgian chicory extract. Supply concentrates in Belgium for industrial-scale aqueous extraction, France for organic root cultivation, and Germany for small-batch drum roasting. Raw material dependencies include chicory root, barley, and rye feedstock. Single-source vulnerability sits with Belgian processing hubs supplying volume to private-label assemblers. Distribution runs through direct-to-consumer subscription channels displacing conventional supermarket slotting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward habitual replenishment platforms as subscription models consolidate consumer loyalty away from episodic retail discovery. This consolidation compresses margin capture for mass-market shelf-dependent assemblers.
For Market Incumbents: Consolidate proprietary roasted grain supply chain control to defend against adaptogenic functional beverage crossovers eroding ritual-authenticity positioning. Secure drum roasting expertise through apprenticeship programs addressing skill scarcity among aging European equipment operators. Expand clean-label certification investment under EU Regulation 1169/2011 to sustain premium channel pricing power.
For New Entrants and Emerging Players: Anchor in Nordic markets showing latent demand for caffeine-free morning rituals with established botanical consumption culture. Target herbal blend variants with adaptogenic positioning as the fastest-expanding category. Pursue wellness café partnerships in Berlin and Copenhagen adopting compact drum roasting cells as primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated roasters with captive chicory supply and established direct-to-consumer subscription infrastructure. Long-term viability favors entities controlling both formulation transparency and recurring revenue capture. Monitor EFSA novel food approval timelines for adaptogenic ingredients as inflection indicator for functional segment expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chicory Cultivation | Captive root supply from Flemish agricultural belt secures margin integrity against commodity price swings. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture bypasses supermarket slotting fees eroding private-label profitability. |
| Clean-Label Certification Investment | EU Regulation 1169/2011 compliance validates premium positioning in German wellness café channels. |
| Compact Drum Roasting Cell Deployment | Berlin and Copenhagen boutique adoption preserves volatile aromatics lost to industrial spray-drying. |
| Adaptogenic Ingredient Pipeline | REACH chemical safety assessments extend validation timelines but unlock functional beverage crossover demand. |
Study Parameters
A standing panel of specialty roaster operations directors, natural food channel buyers, EFSA regulatory consultants, and wellness café procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU novel food approval databases, Belgian customs trade records for chicory root shipments, FDA caffeine content labeling guidance, and SEC filings for publicly traded parent entities. Bottom-up volume modeling triangulated against top-down category spend estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product architecture, packaging configuration, distribution channel, and customer motivation type. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory approval timeline compression and subscription adoption curves. Forecast inputs incorporated drum roasting capacity expansion plans and EFSA health claim assessment pipelines.
Material uncertainties — commodity chicory price volatility, REACH chemical safety assessment delays, and FDA labeling requirement reformulation cycles — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and consumer ritual substitution persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Single-Serve Coffee Containers Market
Coffee
Australia Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Coffee Syrup Market
Coffee
High Protein Coffee Market
Coffee
Coffee and Tea Capsule Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Mushroom Coffee Market
Coffee
Nitrogenated Coffee Market
Coffee
UK Coffee Roaster Market
Coffee
Coffee Cherry Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Global Cafe Market
Coffee
Caffeine Market
Coffee
Green Coffee Market