
 Retail Analytics Market | 2026-2036
Retail Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Analytics Market Analysis
Omnichannel fulfillment architecture is rewriting how retailers orchestrate data flows between digital storefronts and physical locations. Microsoft leverages its cloud infrastructure to anchor enterprise-grade analytics stacks across large-format retail networks. IBM competes through specialized supply-chain optimization modules that extend its historical strength in enterprise resource planning. Oracle dominates database-centric deployments where real-time transaction processing sustains competitive differentiation for high-velocity merchants.
Retail analytics encompasses the systematic computational analysis of consumer behavior, inventory movement, pricing elasticity, and operational metrics through statistical models, machine-learning algorithms, and data-visualization dashboards, typically processing terabyte-scale structured and unstructured datasets with sub-second query response thresholds to enable merchandising decisions, loss prevention, and demand forecasting. Predictive analytics leads solution adoption as retailers prioritize forward-looking demand signals over historical reporting, while prescriptive analytics represents the fastest-expanding margin pool where algorithmic recommendation engines command premium pricing. Cloud-based deployment is displacing on-premise installations as latency-tolerant workloads migrate to distributed infrastructure, though hybrid architectures persist where edge computing handles real-time inventory tracking in warehouse environments.
The EU AI Act imposes transparency obligations on algorithmic pricing systems deployed across European retail operations, while the GDPR constrains customer-data aggregation practices that underpin loyalty-analytics platforms. In the United States, the FTC scrutinizes surveillance pricing methodologies that leverage consumer-behavioral data for individualized rate setting. Stakeholders must monitor evolving algorithmic-accountability frameworks as regulatory divergence between jurisdictions complicates cross-border analytics standardization and data-governance protocols.
Market Dynamics
Real-time inventory synchronization between digital storefronts and physical fulfillment nodes is forcing retailers to rebuild their data architectures around sub-second latency requirements rather than batch-processing legacy systems.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic pricing disclosure requirements are accelerating investment in explainable AI tooling across European retail operations.
- Grocery chain demand-forecasting modernization:North American supermarket networks are deploying machine-learning modules to reduce perishable waste and optimize replenishment cycles.
- Edge computing in warehouse environments:Distributed processing nodes enable real-time inventory tracking without cloud round-trip delays, supporting high-velocity omnichannel fulfillment.
Market Restraints
- GDPR data-aggregation constraints:Customer loyalty analytics face structural limitations on cross-border behavioral data pooling, fragmenting insight generation across European jurisdictions.
- Cloud migration capex burdens:Mid-market retailers lack balance-sheet capacity for full-stack infrastructure replacement, trapping segments in hybrid deployment limbo.
- Terabyte-scale storage costs:Unstructured behavioral data retention requirements impose ongoing operational expenditure pressures that on-premise installations avoided.
Strategic Opportunities
- Prescriptive analytics premium tier:Algorithmic recommendation engines that automate merchandising decisions command pricing multiples over descriptive dashboards.
- FTC surveillance-pricing scrutiny:Regulatory pressure on individualized rate-setting creates demand for compliant transparency tools that document non-discriminatory algorithmic logic.
- Loss-prevention computer vision:Convergence of video analytics with point-of-sale data streams opens shrinkage-reduction applications in high-theft retail verticals.
Industry Challenges
- Sub-second query engineering talent:Retailers compete for data infrastructure specialists capable of optimizing distributed database performance at terabyte scale.
- Legacy ERP integration complexity:Decades-old transaction processing systems resist API-native connectivity, forcing expensive middleware development for analytics layer attachment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Analytics Market |
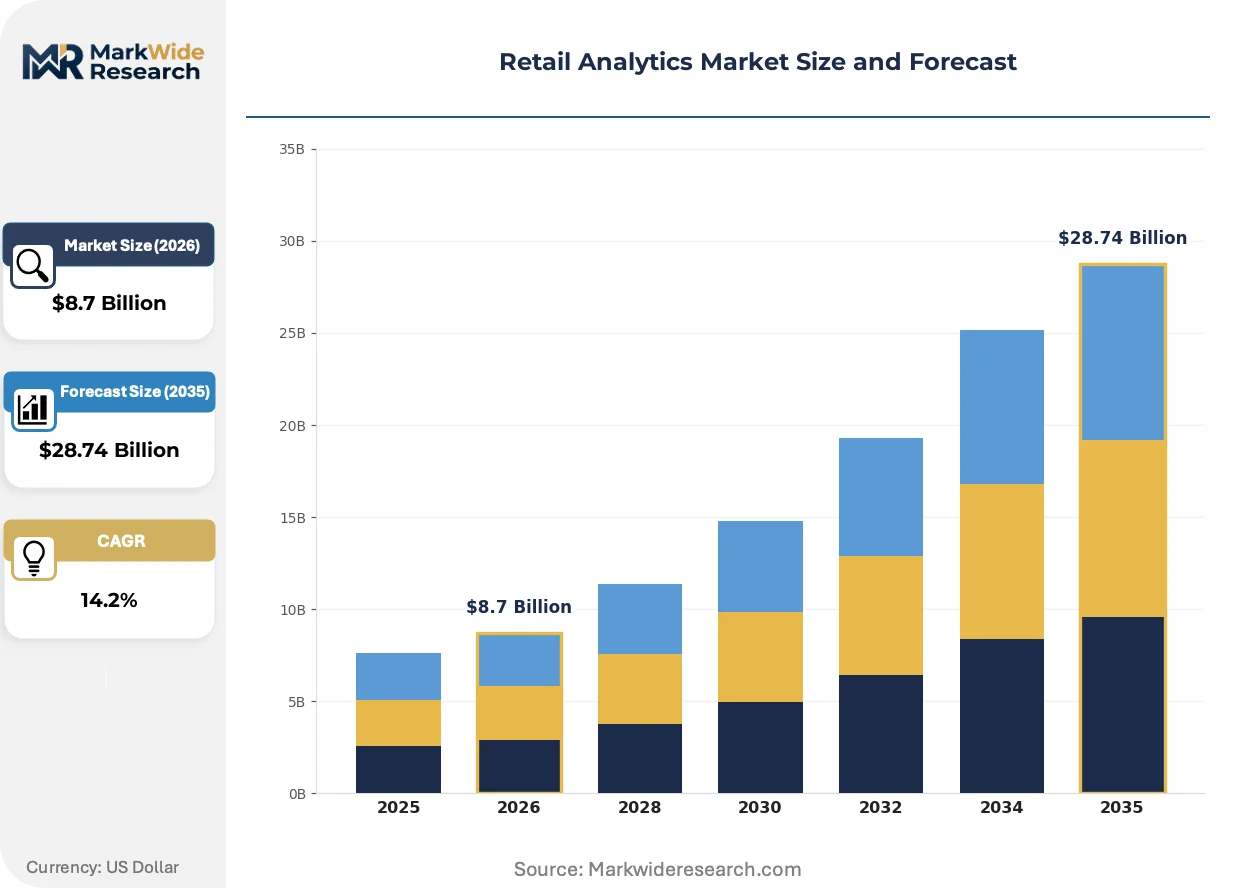
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Diagnostic Analytics Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Retail Chains, E-Commerce Platforms, Supermarkets, Department Stores Solution: Customer Insights, Inventory Management, Price Optimization, Marketing Analytics |
| Companies Covered | Microsoft, IBM, Oracle, SAP, Salesforce, SAS Institute, Adobe, MicroStrategy, Teradata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Analytics Market Emerging Trajectories
Computational retail is pivoting from retrospective reporting to anticipatory systems that embed predictions directly into operational workflows, compressing decision cycles from weeks to minutes.
Digital twin technology is virtualizing physical store layouts and supply chain nodes, enabling scenario simulation without operational disruption. Large-format retailers deploy these replicas to test fulfillment reconfigurations before capital deployment. The technology is virtualizing traditional merchandising experimentation, collapsing the cost and time barriers that protected incumbent planning processes.
The EU AI Act imposes documentation burdens on algorithmic pricing systems that leverage consumer-behavioral segmentation. Retailers must now maintain technical files demonstrating non-discriminatory intent and human oversight protocols. European omnichannel operators are responding by embedding compliance checkpoints into model development pipelines, treating regulatory documentation as a product feature rather than post-hoc audit preparation.
Merchant buying patterns are compressing toward continuous replenishment models that replace seasonal forecasting with demand-signal responsiveness. Apparel and fast-moving consumer goods retailers are abandoning buy-commitment cycles in favor of test-and-scale micro-assortments. This behavioral shift is most pronounced among digitally native vertical brands operating direct-to-consumer channels with integrated manufacturing partnerships.
Retail Analytics Market Segmentation
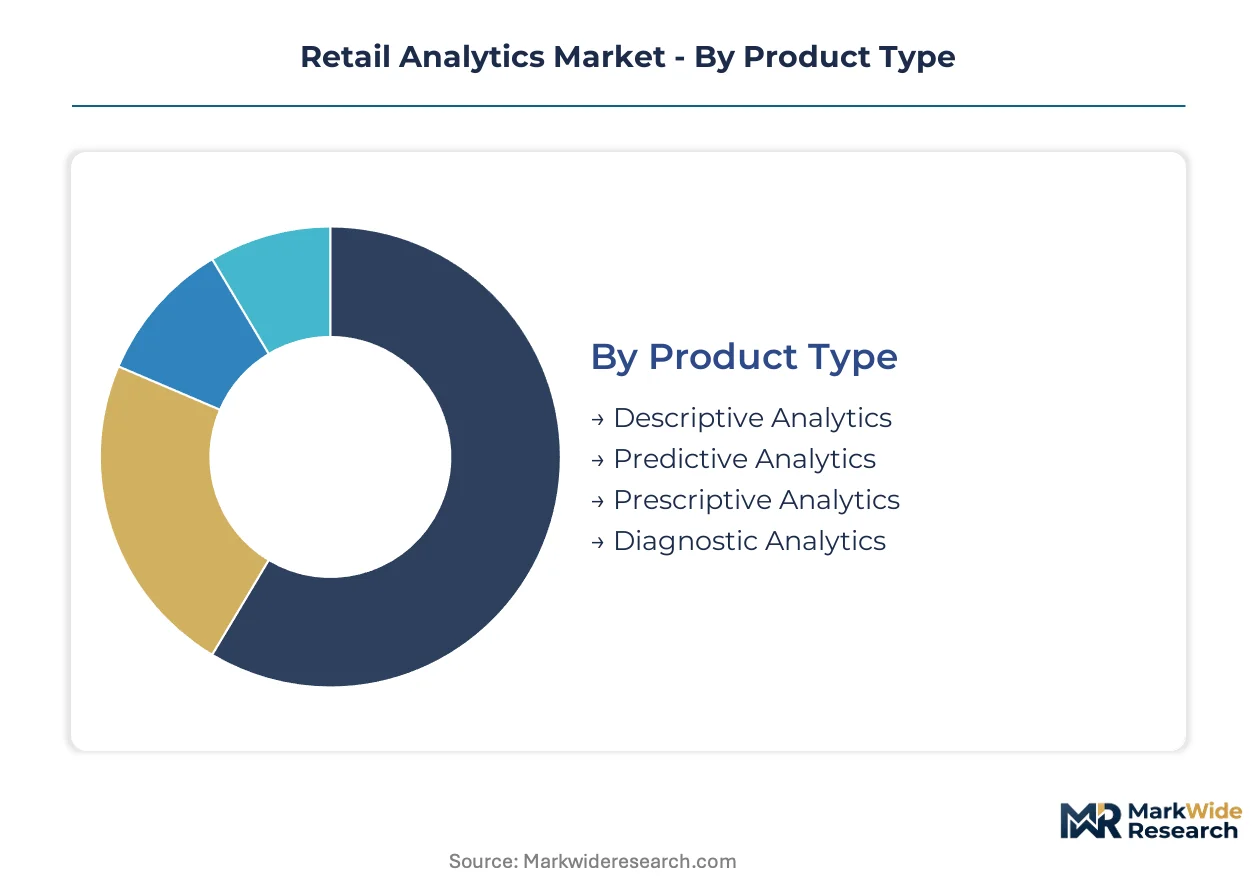
Retail analytics procurement splits across four intersecting dimensions: analytical maturity, infrastructure topology, channel archetype, and functional application. Understanding these segment boundaries clarifies where solution providers concentrate R&D investment versus where standardization dominates.
Product Type:
Use-case spectrum spans retrospective reporting through autonomous decision execution, with capability depth determining pricing architecture and implementation complexity.
- Descriptive Analytics:Historical dashboards aggregate point-of-sale, inventory, and customer transaction records into standardized visualization layers. Supermarket chains in the United States deploy these modules for weekly performance reviews, though batch-processing latency limits operational responsiveness during promotional surges.
- Predictive Analytics:Machine-learning models forecast demand signals, price elasticity, and churn probability from structured behavioral datasets. Grocery networks accelerating perishable waste reduction prioritize this segment, where demand-signal accuracy directly impacts margin preservation.
- Prescriptive Analytics:Algorithmic recommendation engines automate merchandising decisions, inventory positioning, and dynamic pricing adjustments. Premium pricing reflects embedded optimization logic that compresses decision cycles from planning horizons to real-time execution.
- Diagnostic Analytics:Root-cause identification tools isolate performance variance drivers across operational metrics. Retail chains apply these for post-promotional analysis and supply-chain disruption forensics.
Established volume favors Descriptive Analytics; emerging adoption favors Prescriptive Analytics.
Deployment:
Infrastructure topology selection hinges on latency tolerance, data sovereignty requirements, and capital availability for distributed compute investment.
- Cloud-Based:Distributed infrastructure hosts analytics workloads with elastic scaling for terabyte-scale behavioral datasets. E-commerce platforms with volatile traffic patterns prioritize this model for capacity flexibility without fixed asset commitment.
- Edge Computing:Warehouse-local processing nodes execute inventory tracking and fulfillment optimization without cloud round-trip delays. Omnichannel retailers with sub-second synchronization requirements deploy these for real-time stock positioning across digital and physical nodes.
- On-Premise:Captive data centers retain full operational control over sensitive transaction records and algorithmic pricing logic. Department stores with legacy ERP dependencies maintain these installations despite higher total cost of ownership.
- Hybrid:Partitioned architectures route latency-sensitive workloads to edge nodes while reserving cloud capacity for batch analytical processing. Mid-market retailers lacking full migration capital occupy this transitional configuration.
Cloud-Based deployment captures the steepest expansion trajectory; Hybrid architectures persist where capital constraints block full-stack replacement.
End User:
Channel archetype dictates data architecture requirements, with fulfillment velocity and assortment breadth shaping analytics sophistication thresholds.
- E-Commerce Platforms:Digital-native merchants process continuous clickstream, cart, and conversion events through real-time personalization engines. Direct-to-consumer operators with integrated manufacturing partnerships leverage these capabilities for test-and-scale micro-assortment strategies.
- Retail Chains:Multi-location operators synchronize pricing, promotion, and inventory decisions across distributed store networks. Large-format networks anchor enterprise-grade analytics stacks requiring sub-second query performance at terabyte scale.
- Supermarkets:High-velocity, low-margin operators balance perishable spoilage risk against stockout penalties in replenishment algorithms. North American grocery chains modernizing demand-forecasting modules concentrate procurement in this segment.
- Department Stores:Assortment-heavy merchants with seasonal buying cycles apply analytics to markdown optimization and vendor performance scorecarding. Legacy transaction processing systems complicate analytics layer attachment for this channel.
E-Commerce Platforms drive capability innovation; Supermarkets represent the fastest-climbing adoption curve for predictive modules.
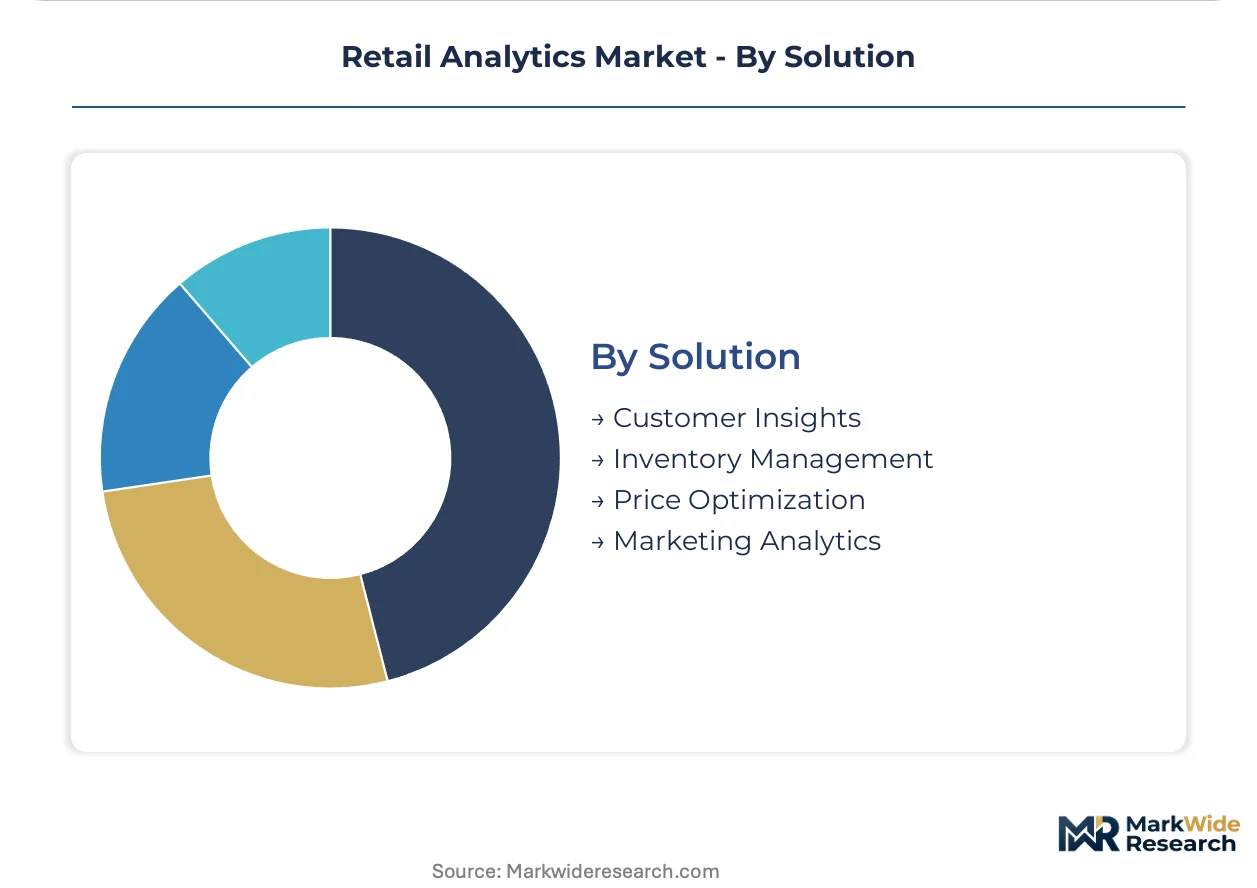
Solution:
Functional application areas map to distinct operational workflows, with integration depth determining vendor stickiness and renewal pricing power.
- Price Optimization:Algorithmic engines adjust rate positioning based on competitive intelligence, elasticity modeling, and inventory aging signals. EU AI Act transparency mandates are accelerating explainable AI tooling investment for European deployments.
- Inventory Management:Real-time stock positioning systems synchronize digital storefront availability with physical fulfillment node capacity. Edge computing integration supports warehouse-local tracking without cloud dependency.
- Customer Insights:Behavioral segmentation and loyalty analytics platforms aggregate purchase history, demographic proxies, and engagement signals. GDPR constraints on cross-border data pooling fragment insight generation across European jurisdictions.
- Marketing Analytics:Campaign performance attribution and media mix modeling tools quantify promotional ROI across channels. Retail chains with omnichannel customer journeys prioritize unified measurement across digital and in-store touchpoints.
Inventory Management anchors established procurement volumes; Price Optimization gains share fastest under regulatory pressure for algorithmic accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retailers command pricing premiums for prescriptive analytics modules, while European procurement concentrates on compliance-embedded tooling under heavier regulatory documentation burdens. This asymmetry fragments vendor pricing power across Atlantic markets.
United States
Omnichannel retailers in California and New York Metro drive demand for real-time inventory synchronization between digital storefronts and physical fulfillment nodes. FTC surveillance-pricing scrutiny forces algorithmic transparency investments. Seattle anchors enterprise-grade cloud analytics stacks serving large-format retail networks.
Germany
Automotive-adjacent retail chains in Bavaria and Baden-Württemberg prioritize supply-chain optimization modules. EU AI Act documentation requirements reshape model development pipelines. Berlin-Brandenburg hosts compliance-embedded tooling specialists serving pan-European operators.
United Kingdom
London-based grocery chains accelerate demand-forecasting modernization to reduce perishable waste. GDPR constraints fragment customer-data aggregation for loyalty analytics. The Southeast corridor concentrates cloud-migration advisory services for mid-market retailers.
China
Yangtze River Delta e-commerce platforms process terabyte-scale behavioral datasets through distributed infrastructure. SAMR algorithmic accountability standards impose domestic transparency obligations. Shenzhen anchors edge-computing hardware integration for warehouse-local inventory tracking.
India
Maharashtra and Karnataka retail chains adopt predictive modules for test-and-scale micro-assortment strategies. RBI data-localization norms constrain cross-border cloud deployments. Bangalore concentrates analytics engineering talent for sub-second query optimization.
Retail Analytics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional depth. The vendor base stratifies across three tiers: hyperscale cloud providers anchoring enterprise deployments, legacy ERP extenders supplying supply-chain modules, and niche specialists occupying diagnostic or prescriptive niches. Dominant competitive moves include strategic partnerships binding analytics layers to legacy transaction systems and portfolio diversification into edge-computing hardware.
Within the hyperscale platform tier, Microsoft exemplifies cloud-native infrastructure play, while Oracle occupies a position anchoring database-centric real-time processing deployments. IBM represents the ERP-extender archetype with supply-chain optimization heritage. These three companies collectively illustrate how vendor origin—software infrastructure, database systems, enterprise resource planning—determines competitive positioning in retail analytics procurement.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Oracle |
| SAP |
| Salesforce |
| SAS Institute |
| Adobe |
| MicroStrategy |
| Teradata |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud infrastructure concentration in the United States anchors margin capture downstream, where prescriptive analytics modules command premium pricing multiples over descriptive dashboards in procurement negotiations with large-format retail networks.
Pricing Analysis
Configured-to-order deployment pricing spreads 40-60% above standard SaaS tiers, reflecting the engineering hours embedded in legacy ERP integration work. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation resting on query latency guarantees and edge-computing node inclusion. Cost compression in the standard tier is intensifying because mid-market retailers lack balance-sheet capacity for full-stack infrastructure replacement. Supermarket chains in North America exhibit highest price sensitivity due to perishable-margin pressures, while omnichannel retailers in California and New York Metro show least sensitivity given real-time synchronization requirements.
Supply Chain Analysis
Export-control regimes limiting GPU and advanced semiconductor flows to Chinese data centers are constraining analytics infrastructure deployment in the Yangtze River Delta. Supply concentrates in the United States, Ireland, and Singapore for cloud compute capacity, with hardware dependencies spanning NVIDIA accelerators, high-bandwidth memory modules, and specialized networking ASICs. Single-source vulnerability in advanced node semiconductor fabrication poses structural risk to edge-computing hardware availability. Distribution runs through hyperscaler marketplaces and systems integrator channels, with direct enterprise sales capturing the largest transaction values.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail analytics procurement follows a cyclical recovery pattern tied to enterprise IT refresh cycles, with grocery chains in North America currently accelerating demand-forecasting module investments after deferred spending during prior periods.
For Market Incumbents: Build switching-cost moats through deep integration with legacy ERP systems that resist API-native connectivity, forcing expensive middleware development for competitors attempting displacement. Incumbents should deepen backward integration into edge-computing hardware to control warehouse-local processing node supply, while embedding EU AI Act compliance documentation as a product feature to capture European procurement preference.
For New Entrants and Emerging Players: Establish a beachhead in prescriptive analytics for mid-market supermarkets lacking in-house data science teams, where algorithmic recommendation engines remain underpenetrated relative to large-format networks. Target hybrid deployment architectures as the most penetrable infrastructure topology, given capital constraints blocking full-stack replacement. A channel partnership with systems integrators possessing existing ERP relationships offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models, reducing barrier-to-entry concerns for software-only entrants over the coming decade. Acquisition targets should display proprietary optimization algorithms with demonstrated perishable waste reduction outcomes in grocery deployments. The signal to watch is FTC enforcement action on surveillance pricing, which would accelerate demand for compliant transparency tooling.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Tooling Investment | EU AI Act transparency mandates reshape European model development pipelines toward compliance-embedded architectures. |
| Edge Computing Hardware Integration | Warehouse-local processing nodes enable sub-second inventory tracking without cloud round-trip latency penalties. |
| Legacy ERP Connectivity Development | Middleware layers binding analytics stacks to decades-old transaction systems create defensive switching costs. |
| Prescriptive Analytics Premium Tier Launch | Algorithmic recommendation engines automate merchandising decisions, compressing planning cycles to real-time execution. |
| Loss Prevention Computer Vision Deployment | Video analytics convergence with point-of-sale data streams opens shrinkage-reduction applications in high-theft verticals. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief technology officers, IT procurement officers at omnichannel retailers, platform engineers at hyperscale cloud providers, and integration specialists serving grocery chain modernization programs. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, EU regulatory documentation, and customs records of edge-computing hardware imports. Bottom-up sizing of module deployments and top-down reconciliation against aggregate IT spending estimates provided triangulation across the analysis window.
Calibration anchored volume and value outputs to observable procurement patterns across deployment models, organization size tiers, vertical specializations, and regional adoption clusters. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated grocery chain demand-forecasting modernization timelines, EU AI Act implementation phases, and FTC surveillance-pricing scrutiny intensity.
Stress conditions across cloud migration capital availability, semiconductor supply constraints, and regulatory enforcement variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise IT refresh cyclicality and compliance cost absorption capacity. Material shifts in hyperscaler pricing architecture or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Big Data Market
Analytics
Connected Device Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
Predictive Analytics Market
Analytics
Data Analysis Tools Market
Analytics
APAC Location Analytics Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
Datacenter Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
Content Analytics and Search Software Market
Analytics
Assortment Analytics Market
Analytics
Business Value Dashboard Market
Analytics
Europe Supply Chain Analytics Market