
 Global Mobile Phone Protective Cases Market | 2026-2036
Global Mobile Phone Protective Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Phone Protective Cases Market Outlook
Polymer engineering talent is bifurcating between commodity plastic molders and advanced composite specialists, constraining supply of drop-certified case manufacturers. Otter Products LLC leverages captive testing labs to sustain military-grade certification pipelines. Spigen Inc. anchors its cost structure through direct-to-consumer channel control across Asian e-commerce platforms. Incipio LLC differentiates via in-house production of plant-based TPU formulations.
Mobile phone protective cases are injection-molded or thermoformed enclosures, typically 1-3mm thick, engineered to absorb impact energy through air-gap geometry, elastomeric liners, or aramid fiber reinforcement; their commercial purpose is to reduce repair costs and extend device resale value. Silicone and hard shell variants dominate volume, while wallet cases capture higher margin pools through leather sourcing and RFID-blocking functionality. Online retail is displacing specialty stores as the primary channel for teenagers and working professionals seeking customization.
REACH in Europe, California's Proposition 65, and India's BIS certification for electronic accessories collectively restrict hazardous substance content and mandate labeling transparency. The US Consumer Product Safety Commission monitors choking hazards from detachable decorative elements, while China's GB standards govern flame retardancy in battery-proximate designs. Stakeholders must monitor evolving e-waste directives that could mandate recyclable case materials and producer take-back obligations.
Market Dynamics
Smartphone replacement cycle elongation is compressing case refresh rates while simultaneously elevating average selling prices for premium protective accessories. Manufacturers must now engineer for durability parity with device longevity rather than seasonal fashion turnover.
Growth Catalysts
- India PLI Incentives:Domestic manufacturing subsidies under India's Production Linked Incentive scheme are accelerating localized molding capacity and reducing import dependency for polymer components.
- ECHA REACH Restrictions:Phthalate and heavy metal prohibitions are accelerating bio-based TPU formulation adoption as European retailers demand compliant supply chains.
- Aramid Fiber Integration:Drop-certified composite engineering is capturing working professional segments upgrading protection levels alongside flagship device purchases.
Market Restraints
- Polymer Engineering Talent Scarcity:Qualified molders capable of military-grade certification testing remain concentrated in Guangdong and Tamil Nadu, constraining qualified supplier expansion.
- Petrochemical Input Volatility:TPU and polycarbonate resin prices fluctuate with crude oil derivatives, compressing margin predictability for mid-tier manufacturers lacking long-term supply contracts.
- California Proposition 65 Labeling:Warning requirements for BPA and certain flame retardants create compliance friction for direct-to-consumer cross-border shipments into the United States.
Strategic Opportunities
- Rural India Penetration:Feature phone-to-smartphone migration in tier-3 and tier-4 cities creates first-time protective case demand among price-sensitive entrants.
- RFID-Blocking Wallet Convergence:Leather sourcing expertise from accessory manufacturers is enabling premium hybrid cases that merge device protection with payment security functionality.
- E-Waste Directive Anticipation:Draft EU regulations mandating recyclable materials and producer take-back obligations favor early movers establishing closed-loop polymer recovery systems.
Industry Challenges
- Military-Grade Certification Timelines:MIL-STD-810G testing protocols require 12-18 month validation cycles, delaying product launches for drop-certified entrants.
- Multi-Standard Compliance Burden:Simultaneous navigation of China's GB flame retardancy rules, India's BIS electronic accessory mandates, and US CPSC choking hazard monitoring strains quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Phone Protective Cases Market |
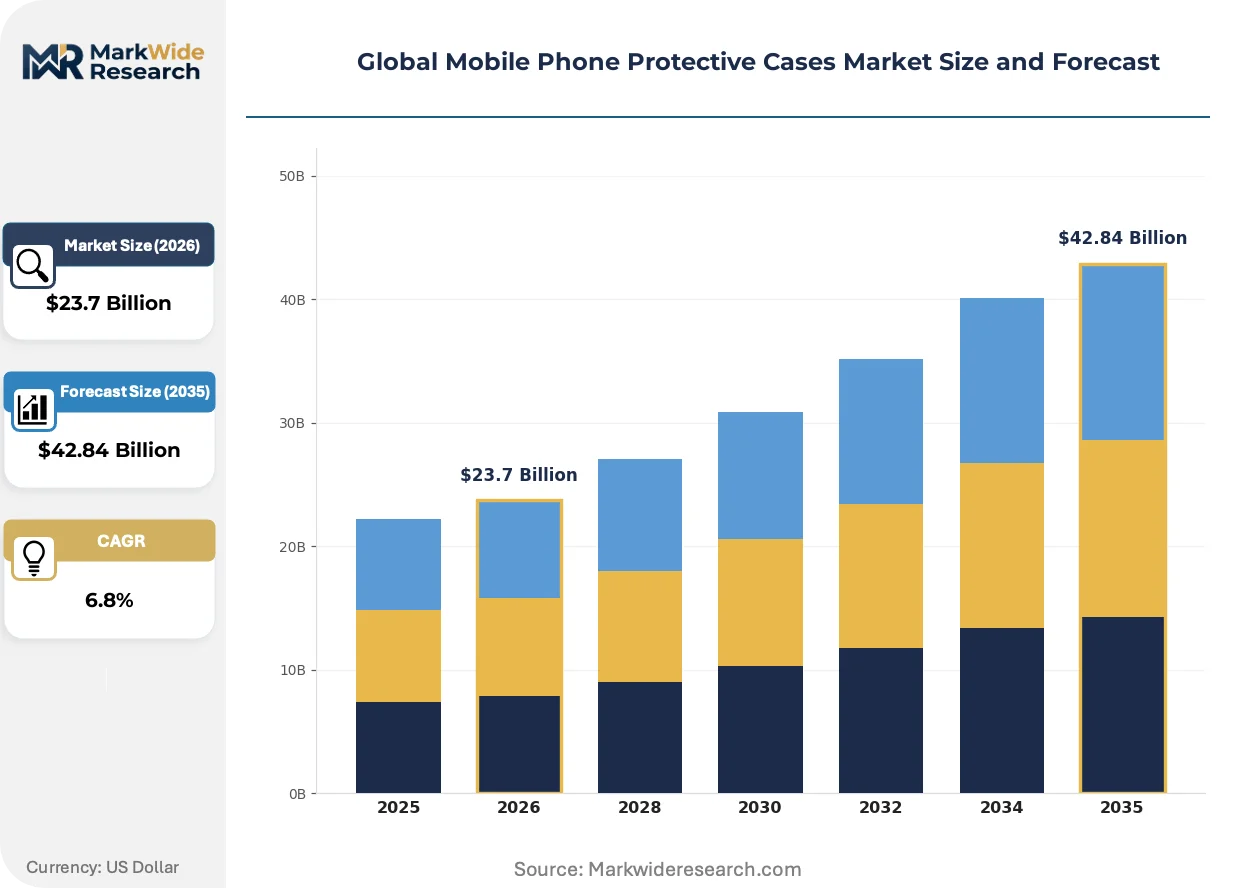
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Leather, Hard Shell, Wallet End User: Teenagers, Working Professionals, Travelers, Students Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Material: Plastic, Fabric, Rubber, Metal |
| Companies Covered | Otter Products LLC, Spigen Inc., Incipio LLC, Belkin International Inc, Case-Mate Inc., ZAGG Inc, Tech21, Urban Armor Gear LLC, CG Mobile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Phone Protective Cases Market Strategic Shifts
Material science convergence with regulatory compliance requirements is redefining competitive differentiation beyond aesthetic customization. Functional performance certification and environmental credentialing now drive premium positioning.
Plant-based thermoplastic polyurethane formulations derived from castor oil and corn starch are displacing petroleum-derived TPU in European retail channels. Sustainability-conscious buyers in Germany and the Netherlands now specify bio-content thresholds in procurement specifications. This displacement is compressing conventional polymer margins while rewarding compounders with verified life-cycle assessment documentation.
REACH authorization procedures for persistent organic pollutants are tightening acceptable substance thresholds for plasticizers and stabilizers used in battery-proximate case designs. Compounders serving the European Economic Area are reformulating halogen-free flame retardant packages. Battery case segments for power-integrated designs face the steepest compliance cost escalation and are consolidating supplier relationships toward ECHA-registered compound specialists.
Direct-to-consumer channel control is capturing teenager and young professional segments previously served by electronics specialty retailers. Spigen and similar operators leverage TikTok Shop and Shopee live commerce for launch velocity. This channel rotation is most visible in Southeast Asian urban centers where mall-based retail foot traffic has not recovered to pre-pandemic levels.
Global Mobile Phone Protective Cases Market Segmentation
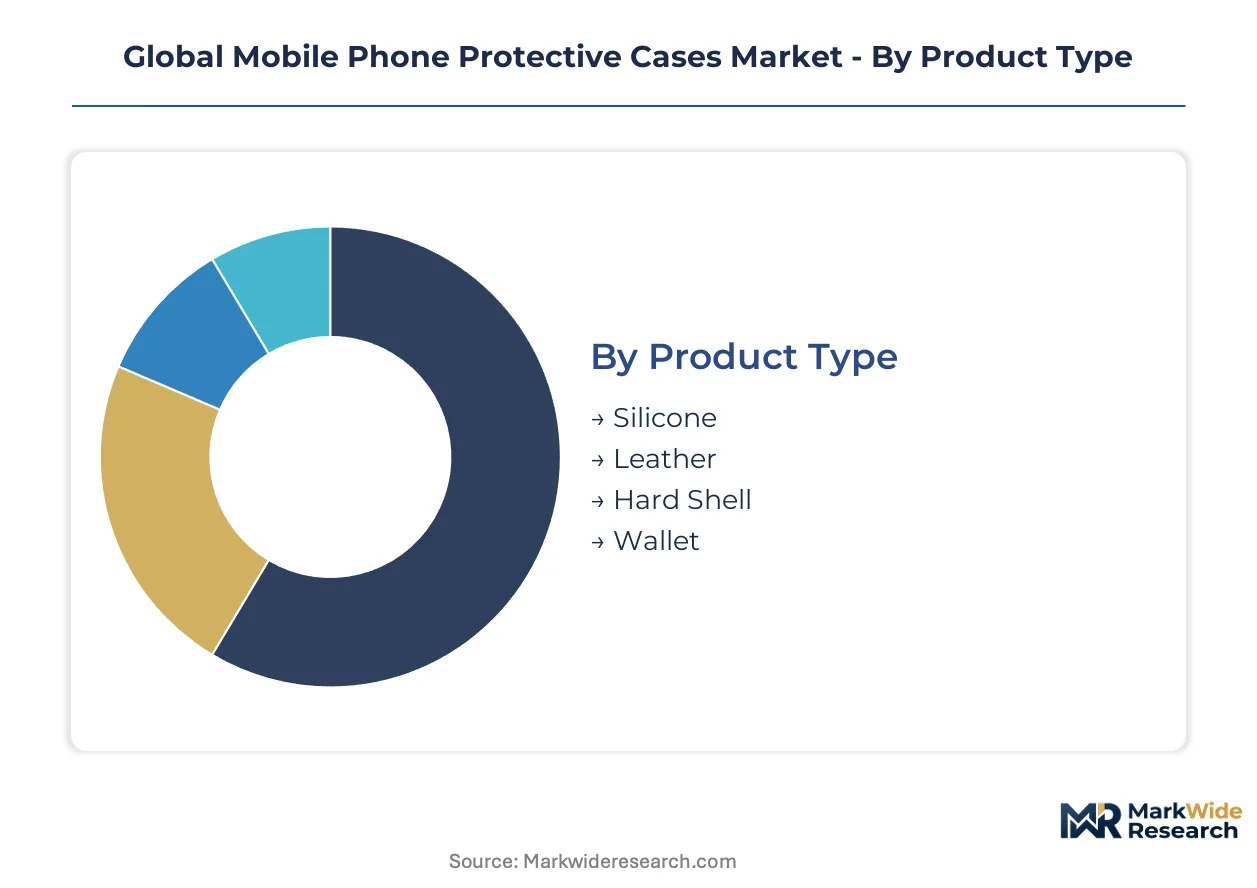
Protective case segmentation reveals how margin pools migrate across material science, distribution control, and demographic targeting. Manufacturers engineer product architectures around specific price-performance thresholds rather than pursuing universal coverage.
Product Type:
Margin pools concentrate in hybrid constructions that merge drop protection with lifestyle functionality, while commodity single-material variants compete on molding efficiency.
- Silicone:Thermoset elastomer formulations provide grip texture and shock absorption through Shore A 40-60 durometer specifications. Teenagers in Southeast Asian urban centers drive volume through Shopee and TikTok Shop flash sales, where colorway refresh cycles compress to six weeks.
- Leather:Full-grain and bonded leather constructions command premium positioning through vegetable-tanning credentials and patina aging characteristics. Working professionals in Frankfurt and Amsterdam specify bio-based tanning agents that comply with ECHA REACH restrictions on chromium VI compounds.
- Hard Shell:Polycarbonate and ABS blends achieve 1.5-2.0mm wall thickness with ribbed internal structures for impact distribution. Price compression in Indian tier-2 cities under PLI-incentivized domestic molding limits margin expansion.
- Wallet:Hybrid designs integrate card slots and RFID-blocking metallic layers with protective enclosures. Leather sourcing from Italian tanneries and Turkish manufacturers enables payment security convergence for premium positioning.
The dominant share belongs to Silicone, while Wallet is closing the gap fastest.
End User:
Application-specific engineering requirements diverge sharply across mobility patterns, device handling intensity, and aesthetic sensitivity.
- Teenagers:Demand concentrates on customization platforms with interchangeable backplates and licensed character IP. Direct-to-consumer channels in Jakarta and Manila capture this segment through live commerce events.
- Working Professionals:Aramid fiber and carbon fiber composites satisfy MIL-STD-810G certification requirements for field-deployed devices. Corporate procurement in London and Singapore specifies drop-test documentation and warranty terms.
- Travelers:Multi-device compatibility and passport-slot integration define functional requirements. Airport retail in Dubai and Changi prioritizes impulse purchase visibility and compact packaging.
- Students:Price elasticity dominates with preference for bulk-packaged clear cases showing institutional branding. Campus bookstores in US Midwest states and Australian state universities maintain seasonal inventory cycles.
Working Professionals extract the highest per-unit margins, though Teenagers generate the steepest volume expansion trajectory.
Distribution Channel:
Channel control determines pricing architecture and customer data capture capabilities, with digital platforms displacing physical retail for demographic segments under 35.
- Online Retail:Platform algorithms and review aggregation drive discovery. Spigen and similar operators leverage Amazon and regional e-commerce dominance in Seoul and Bangkok to bypass distributor markups.
- Supermarkets:Impulse placement near checkout and electronics aisles captures unplanned purchases. Carrefour and Auchan hypermarkets in France and Spain rotate seasonal colorways on 12-week cycles.
- Specialty Stores:Staff consultation and device-specific fitting services justify premium positioning. Mall-based retailers in Mumbai and São Paulo face foot traffic deficits versus pre-pandemic baselines.
- Wholesale:Bulk procurement for carrier bundling and corporate fleet deployment concentrates in Shenzhen trading companies and Tamil Nadu molding clusters.
Online Retail commands the dominant transaction volume, while Specialty Stores retain the highest conversion rates for premium SKUs.
Material:
Raw material selection governs regulatory compliance pathways, molding process compatibility, and end-of-life recovery economics.
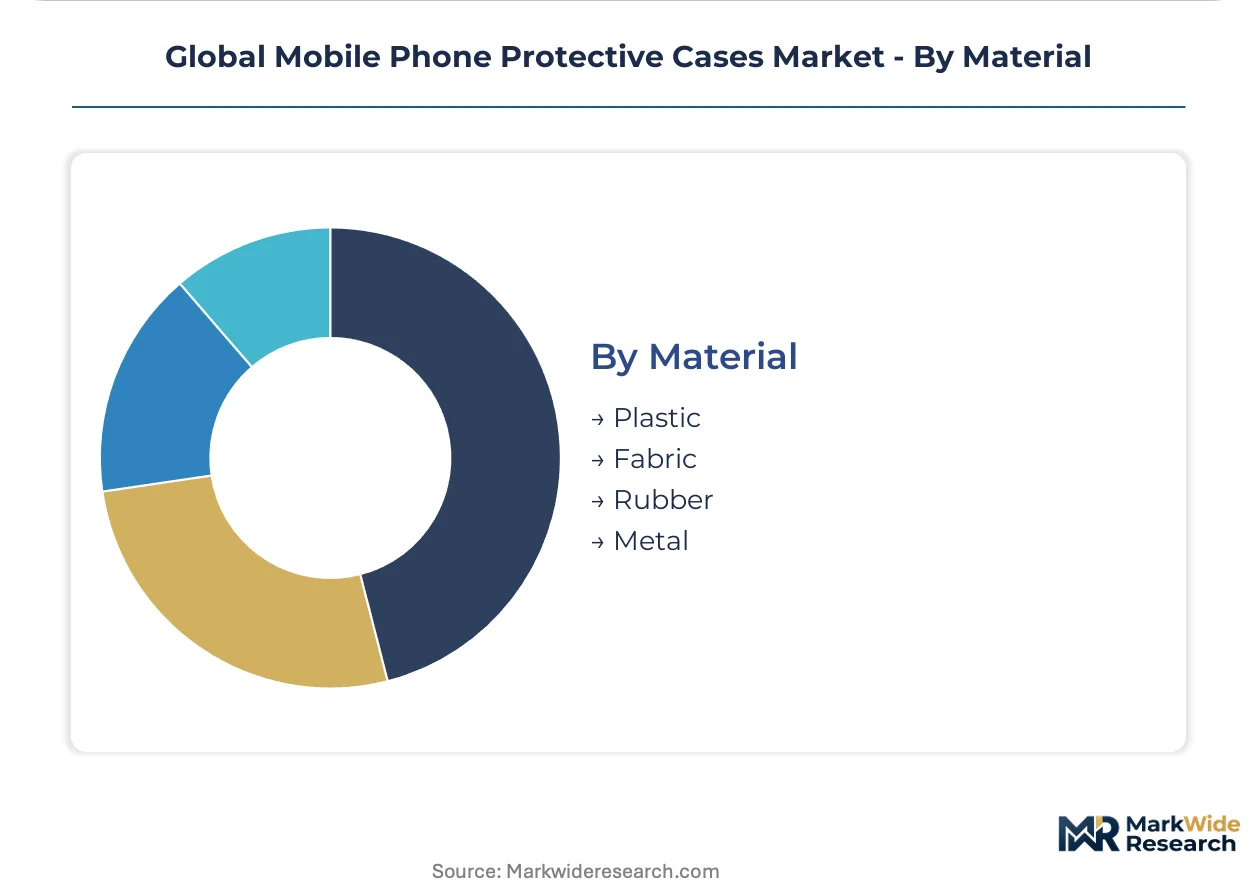
- Plastic:Polycarbonate, TPU, and bio-based PLA formulations dominate injection molding throughput. REACH-registered compounders in Germany and the Netherlands reformulate halogen-free flame retardants for battery-proximate designs.
- Fabric:Woven nylon and canvas constructions enable textile printing and embroidery customization. Limited drop protection restricts application to fashion-forward segments in Milan and Tokyo.
- Rubber:Natural and synthetic latex blends provide grip and shock absorption at material cost premiums. Plantation sourcing traceability requirements complicate European retail compliance.
- Metal:Aluminum and magnesium alloys enable thermal dissipation for gaming-optimized devices. CNC machining costs limit scaling beyond flagship protection tiers.
Plastic maintains overwhelming volume leadership, while Fabric gains share fastest among sustainability-positioned European retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH restrictions on phthalates and heavy metals anchor European demand patterns for bio-based material substitution. Manufacturing clusters in Guangdong and Tamil Nadu supply military-grade certification pipelines to working professionals upgrading protection alongside flagship device purchases.
United States
Working professionals in New York and San Francisco drive premium protective accessory upgrades as smartphone replacement cycles elongate. California's Proposition 65 mandates BPA and flame retardant warning labels for cross-border direct-to-consumer shipments. Injection molding capacity concentrates in Shenzhen trading corridors serving US carrier bundling procurement.
Germany
Sustainability-conscious buyers in Frankfurt and Hamburg specify bio-content thresholds for plant-based TPU formulations in procurement contracts. ECHA REACH authorization procedures tighten plasticizer thresholds for battery-proximate case designs. REACH-registered compounders in the Netherlands reformulate halogen-free flame retardants for German retail compliance.
China
Teenagers in Shenzhen and Guangzhou purchase colorway-refreshed silicone variants through TikTok Shop and Shopee live commerce flash sales. GB standards govern flame retardancy requirements for power-integrated battery case segments. Pearl River Delta molding clusters maintain military-grade certification testing infrastructure for export markets.
India
Feature phone-to-smartphone migration in tier-3 and tier-4 cities creates first-time protective case demand among price-sensitive entrants. BIS certification mandates for electronic accessories restrict hazardous substance content in domestic distribution. Tamil Nadu molding clusters under PLI incentives reshape polymer component supply patterns away from import dependency.
Japan
Corporate procurement in Tokyo and Osaka specifies MIL-STD-810G drop-test documentation for field-deployed flagship devices. METI guidelines influence material disclosure requirements for consumer electronics accessories. Kanto region specialty retailers retain premium SKU conversion rates through staff consultation services.
Global Mobile Phone Protective Cases Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive testing labs and direct-to-consumer channel control separating premium positioning from commodity molding. The vendor base spans vertically integrated compounders with in-house bio-based TPU formulation, direct-to-consumer operators leveraging Asian e-commerce platform algorithms, and specialty fabricators focused on military-grade certification pipelines. Two dominant competitive moves define current dynamics: backward integration into REACH-registered compound supply and geographic expansion through live commerce channel establishment.
Within the integrated testing and certification tier, Otter Products LLC exemplifies captive laboratory infrastructure sustaining military-grade validation cycles. Spigen Inc. anchors direct-to-consumer positioning across Seoul and Bangkok e-commerce dominance. Incipio LLC occupies the bio-based formulation specialist position through plant-derived TPU development.
| Leading Market Players |
|---|
| Otter Products LLC |
| Spigen Inc. |
| Incipio LLC |
| Belkin International Inc |
| Case-Mate Inc. |
| ZAGG Inc |
| Tech21 |
| Urban Armor Gear LLC |
| CG Mobile |
| Others |
Value Chain & Pricing Dynamics
MIL-STD-810G certification requirements gate both supplier qualification and price tier separation in the mobile phone protective cases market. Manufacturers without captive testing infrastructure cannot access premium pricing pools reserved for drop-certified aramid fiber constructions.
Pricing Analysis
Price spreads between Shenzhen-produced economy cases and German-engineered bio-based TPU variants reach 8-15x multiples. Pricing stratifies across premium, standard, and economy tiers based on certification grade and material science complexity. Cost compression in Indian tier-2 cities under PLI-incentivized domestic molding is intensifying because of localized polymer component supply. Teenagers in Southeast Asian urban centers exhibit highest price sensitivity through flash-sale platforms, while working professionals in Frankfurt and Singapore demonstrate lowest sensitivity when MIL-STD documentation accompanies purchase.
Supply Chain Analysis
China and India anchor global molding capacity for injection-molded polycarbonate and TPU enclosures. Raw material supply draws from petrochemical derivatives in the Middle East, bio-based castor oil feedstock from Indian plantations, and aramid fiber from DuPont and Teijin production. Single-source vulnerability concentrates in military-grade certification testing infrastructure located exclusively in Guangdong and Tamil Nadu clusters. Distribution runs through direct-to-consumer platforms in Seoul and Bangkok, bypassing traditional electronics specialty retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile phone protective cases market is recovering from pandemic-era channel disruption as smartphone replacement cycle elongation sustains premium accessory upgrades. Device longevity trends compress case refresh rates while elevating average selling prices for certified protection tiers.
For Market Incumbents: Compound backward integration into REACH-registered bio-based TPU formulation to defend margin pools against European regulatory displacement. Establish captive military-grade certification testing in Tamil Nadu to reduce 12-18 month validation cycle exposure. Channel control through TikTok Shop and Shopee live commerce algorithms secures teenager segment volume against emerging direct-to-consumer specialists.
For New Entrants and Emerging Players: Differentiate on plant-based material credentials with verified life-cycle assessment documentation targeting sustainability-conscious procurement in Germany and the Netherlands. Rural India penetration offers the most penetrable white space as feature phone-to-smartphone migration creates first-time protective case demand. RFID-blocking wallet convergence with Italian leather sourcing enables premium hybrid positioning without competing on drop-test certification timelines.
For Investors and Strategic Acquirers: ECHA REACH authorization procedures for persistent organic pollutants reshape the acquisition landscape toward compounders with halogen-free flame retardant reformulation capabilities. Long-term viability centers on closed-loop polymer recovery systems anticipating EU e-waste directive mandates. The signal to watch is draft producer take-back obligation language in Brussels regulatory filings.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based TPU | REACH-registered compound supply secures European retail compliance and margin expansion. |
| Direct-to-Consumer Platform Expansion | Seoul and Bangkok e-commerce dominance bypasses distributor markups for volume capture. |
| Military-Grade Certification Investment | Captive MIL-STD-810G testing infrastructure locks in working professional premium positioning. |
| Rural India Distribution Buildout | Tier-3 and tier-4 city penetration captures first-time smartphone owner protective case demand. |
| Closed-Loop Polymer Recovery System | Anticipatory EU e-waste directive compliance creates sustainable sourcing differentiation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, BIS certification filings, and SEC 10-K disclosures. Primary interviews engaged polymer engineering directors at molding clusters, procurement leads at European electronics retailers, regulatory affairs specialists at ECHA-registered compounders, and category managers at Amazon and Shopee. Bottom-up volume modeling triangulated against top-down value aggregation across the analysis window.
Segmentation dimensions modeled include product type, end-user demographic, distribution channel, and raw material composition. CAGRs were derived from historical trajectory analysis and forward projection of smartphone replacement cycle dynamics, regulatory compliance cost escalation, and channel migration patterns. Industry-specific forecast inputs incorporated PLI incentive uptake rates in Tamil Nadu and bio-based TPU adoption curves in German retail.
Material uncertainties — petrochemical input volatility, REACH authorization timeline delays, and live commerce platform algorithm changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about device longevity trends and regulatory enforcement intensity. Recalibration cycles align with material shifts in PLI scheme modifications and ECHA substance restriction announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Pet Control Devices Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Helmet Lining Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Work Shoes Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Cooking Gloves Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Europe Lanyards Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Insect Repellent Market
Protective Gear
China Pollution Mask Market
Protective Gear
Flavored Condoms Market