
 Personal Floatation Devices (Pfds) Market | 2026-2036
Personal Floatation Devices (Pfds) Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Floatation Devices (Pfds) Market Analytics
Buyer concentration among recreational boaters is realigning as fleet operators and marina rental chains consolidate procurement volumes. Survitec Group Limited leverages its marine safety heritage to dominate commercial vessel contracts. Johnson Outdoors Inc. sustains brand loyalty through specialty retail channel control across North American boating hubs.
Personal flotation devices are engineered buoyancy apparatus designed to keep wearers afloat in water, typically constructed from closed-cell polyethylene foam or inflatable chambers rated to specific Newton buoyancy thresholds, with primary purpose of preventing drowning in maritime and freshwater environments. Life jackets command the largest volume share within product type segmentation, though inflatable vest configurations are capturing faster growth curves among sailing and paddle-sport participants. Water sports enthusiasts represent the most margin-attractive end user segment, with neoprene material grades enabling premium pricing differentiation in performance-oriented channels.
The US Coast Guard, Transport Canada, and ISO 12402 standards collectively govern design approval, with the Coast Guard's updated Type I-V classification system mandating higher buoyancy retention in rough-water conditions. ISO certification functions as a de facto market access gate for manufacturers exporting into European Union waters. Stakeholders must monitor evolving harmonization between US domestic standards and international ISO protocols to anticipate retooling requirements and certification timeline shifts.
Market Dynamics
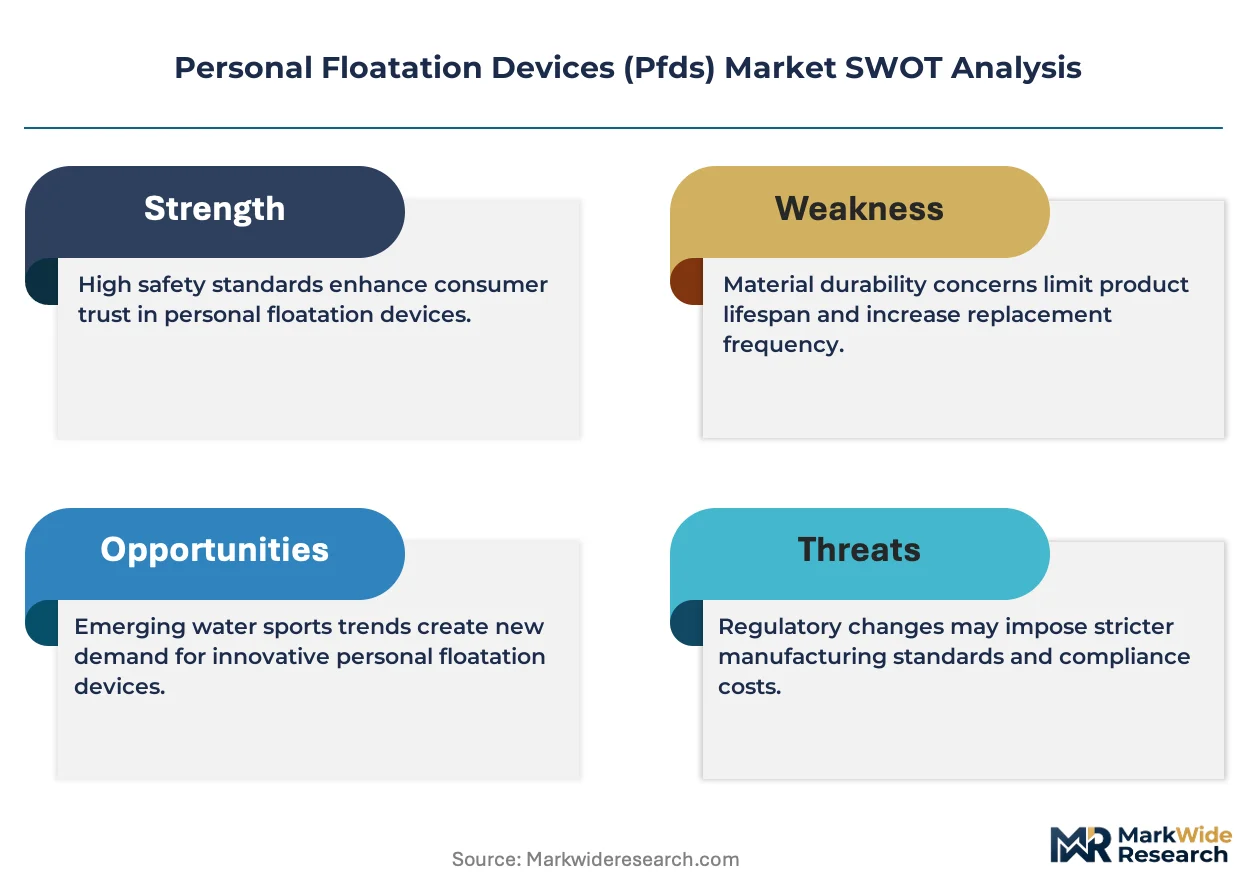
The US Coast Guard's updated Type I-V classification standards are compressing product development cycles while recreational boater procurement consolidates through marina rental chains and fleet operators, reshaping volume allocation across the supply base.
Growth Catalysts
- Florida Marina Corridor Expansion:Recreational boating infrastructure investment across Tampa Bay, Fort Lauderdale, and Miami-Dade is concentrating demand for Type II and Type III devices in high-turnover rental fleets.
- ISO 12402 Harmonization Pressure:European Union market access requirements are pushing manufacturers to dual-certify products, expanding addressable market scope for compliant suppliers.
- Closed-Cell Foam Innovation:Advanced polyethylene foam compounds are improving buoyancy-to-weight ratios, enabling lighter designs that satisfy rough-water performance thresholds without inflatables.
Market Restraints
- Neoprene Raw Material Volatility:Petrochemical feedstock price swings directly compress margin structures for premium water-sports PFD lines.
- Great Lakes Manufacturing Concentration:Production gravity in Michigan and Wisconsin creates weather-related supply disruption exposure during Q1-Q2 shipping windows.
- Inflatable Chamber Reliability Ceiling:Manual and automatic inflation mechanisms face technical limitations in sub-40°F water temperatures, restricting year-round deployment in northern climates.
Strategic Opportunities
- Paddle-Sport Specialty Retail:Kayak and stand-up paddleboard outfitters represent an underpenetrated channel for slim-profile vest configurations with premium neoprene finishes.
- Transport Canada Alignment:Regulatory convergence with US standards is creating streamlined certification pathways for cross-border product launches.
- Smart Sensor Integration:Convergence of GPS beacons with inflatable vest activation mechanisms is opening maritime safety monitoring contracts with commercial fishing cooperatives.
Industry Challenges
- Coast Guard Certification Timeline Compression:Updated buoyancy testing protocols are extending approval cycles by 4-6 months, straining working capital for new product launches.
- Multi-Standard Inventory Complexity:Maintaining separate SKUs for USCG Type I-V, ISO 12402, and Transport Canada requirements fragments production runs and complicates demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Floatation Devices (Pfds) Market |
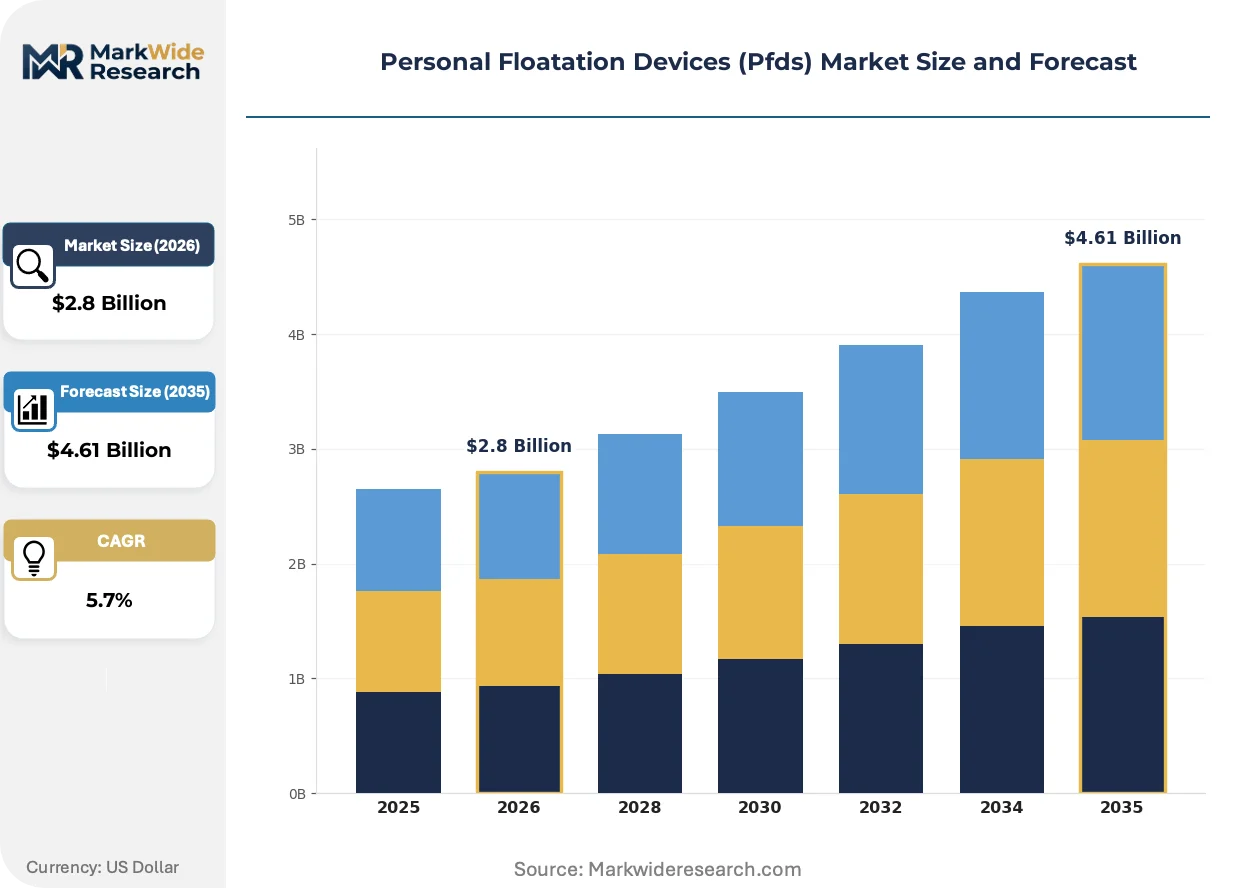
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Jackets, Buoyancy Aids, Inflatable Vest, Personal Flotation Device Accessories End User: Commercial Users, Recreational Boaters, Emergency Services, Water Sports Enthusiasts Distribution Channel: Online Retailers, Specialty Stores, General Merchandisers, Direct Sales Material: Nylon, Polyethylene, Neoprene, Other Fabrics |
| Companies Covered | Survitec Group Limited, Johnson Outdoors Inc., The Coleman Company Inc., Mustang Survival Corp., Aqua Lung International, Kent Sporting Goods Company Inc., Kokatat Inc., NRS (Northwest River Supplies), Marine Rescue Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Floatation Devices (Pfds) Market Evolving Landscape
Product development trajectories in personal flotation devices are converging around lighter materials, smarter activation systems, and certification harmonization that reduces regulatory friction for cross-border sales.
Inflatable vest technology is consolidating market share among sailing and offshore powerboat segments. Coastal cruisers and racing fleets are adopting automatic hydrostatic activation models at accelerating rates. This shift is consolidating procurement volumes toward specialized marine safety suppliers with in-house inflation mechanism engineering capabilities.
REACH chemical restrictions in the European Union are forcing reformulation of foam compounds and textile treatments used in PFD construction. Manufacturers serving EU waters must now validate alternative flame retardants and plasticizers. The neoprene wetsuit-integrated PFD category faces the steepest compliance burden, driving reformulation investment toward bio-based synthetic rubber alternatives.
Marina rental chains are unbundling PFD procurement from vessel maintenance contracts, creating direct vendor relationships with manufacturers rather than through traditional marine distributors. This disintermediation is most visible across Florida's intracoastal waterway operations, where volume commitments now flow to suppliers offering fleet management software integration and seasonal inventory rotation programs.
Personal Floatation Devices (Pfds) Market Segmentation
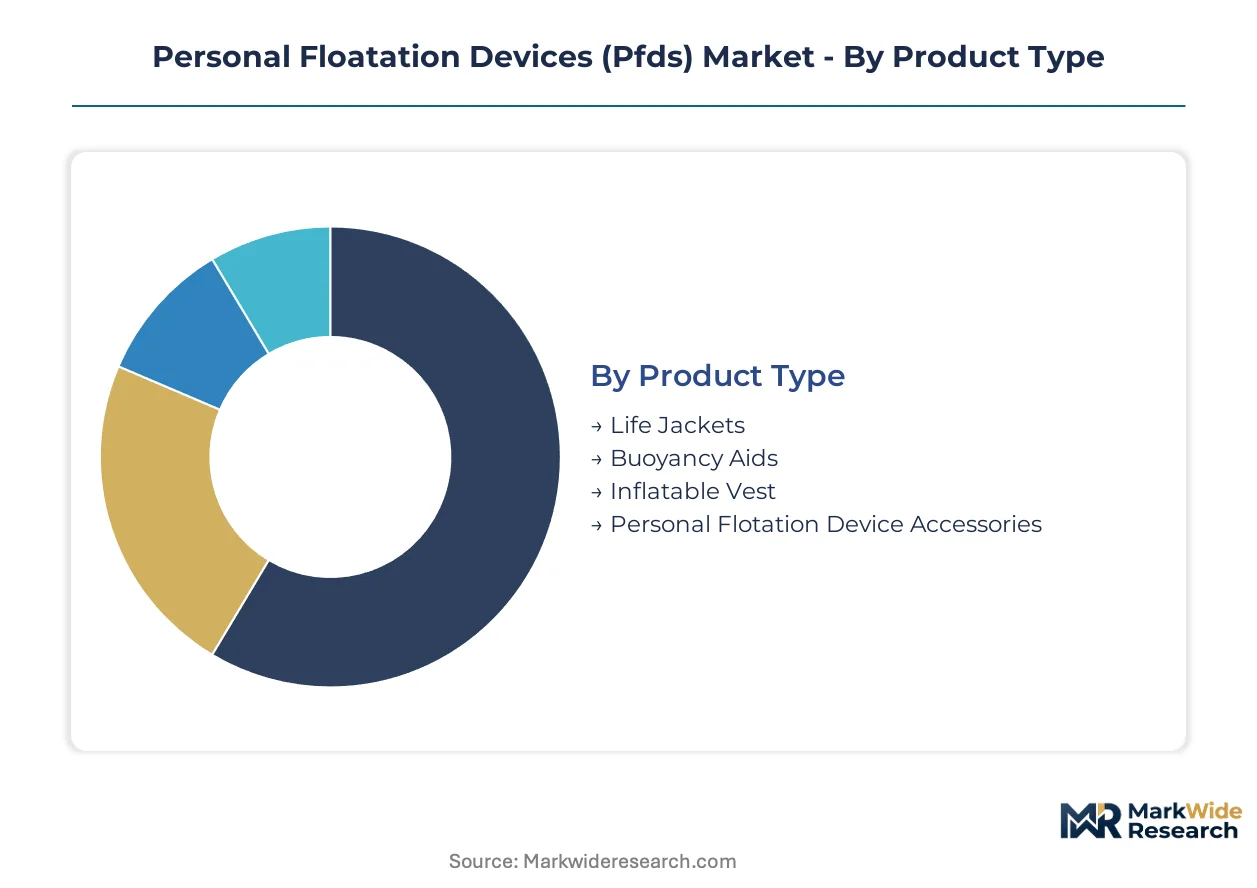
Segmentation in the PFD market determines manufacturing footprint, certification requirements, and channel strategy. Supply-side configuration varies sharply across product types and end-user categories, with commercial contracts demanding bulk production runs while specialty retail favors SKU proliferation.
Product Type:
Supply concentration tilts toward foam-based configurations where production scales efficiently across Midwest manufacturing clusters, while inflatable mechanisms require specialized engineering partnerships.
- Life Jackets:Constructed from closed-cell polyethylene foam with inherent buoyancy requiring no user activation. Demand concentrates among commercial fishing fleets and marina rental operations across Florida's intracoastal corridor, where US Coast Guard Type I-III compliance is non-negotiable.
- Buoyancy Aids:Slim-profile foam panels offering mobility-optimized flotation for active water sports. Procurement is accelerating through kayak outfitters and paddle-sport specialty retailers in the Great Lakes boating cluster, driven by consumer preference for unrestricted arm movement.
- Inflatable Vest:Hydrostatic or manual activation systems delivering high buoyancy-to-weight ratios for offshore sailing.
- Personal Flotation Device Accessories:Replacement CO2 cartridges, harness systems, and signaling attachments.
Life jackets absorb the bulk of installed capacity; inflatable vest configurations are expanding most quickly.
End User:
Cost tier stratification separates specification-heavy commercial procurement from discretionary recreational purchasing, with emergency services occupying a premium-certification middle ground.
- Commercial Users:Fishing cooperatives, offshore energy contractors, and cargo vessel operators procuring Type I offshore life jackets with SOLAS-grade retroreflective tape. Volume concentrates through fleet management contracts with integrated safety monitoring requirements.
- Recreational Boaters:Weekend cruisers and day sailors selecting Type II near-shore or Type III flotation aids based on water conditions. Florida marina chains and Great Lakes yacht clubs are consolidating procurement through direct manufacturer relationships.
- Emergency Services:Swift-water rescue teams and coast guard auxiliaries requiring quick-don harness-integrated systems.
- Water Sports Enthusiasts:Wakeboarders, kite surfers, and tow-sport participants driving neoprene-vest premiumization.
Recreational boaters dominate unit volume; water sports enthusiasts command the steepest margin premiums.
Distribution Channel:
Geographic reach and inventory velocity determine channel viability, with coastal density favoring specialty retail while inland markets rely on online fulfillment.
- Online Retailers:Direct-to-consumer platforms capturing replacement purchases and size-specific reorders. Growth concentrates among paddle-sport participants seeking technical specifications unavailable in general merchandiser assortments.
- Specialty Stores:Marine chandleries and water-sport outfitters providing fit consultation and US Coast Guard compliance verification. Florida's Tampa Bay and Miami-Dade corridors sustain the densest specialty store networks.
- General Merchandisers:Big-box outdoor retailers and mass-market chains moving entry-level Type II devices.
- Direct Sales:Fleet operators and commercial vessel managers procuring through manufacturer account teams.
Specialty stores capture the highest-margin transactions; online retailers are gaining share fastest in repeat-purchase segments.
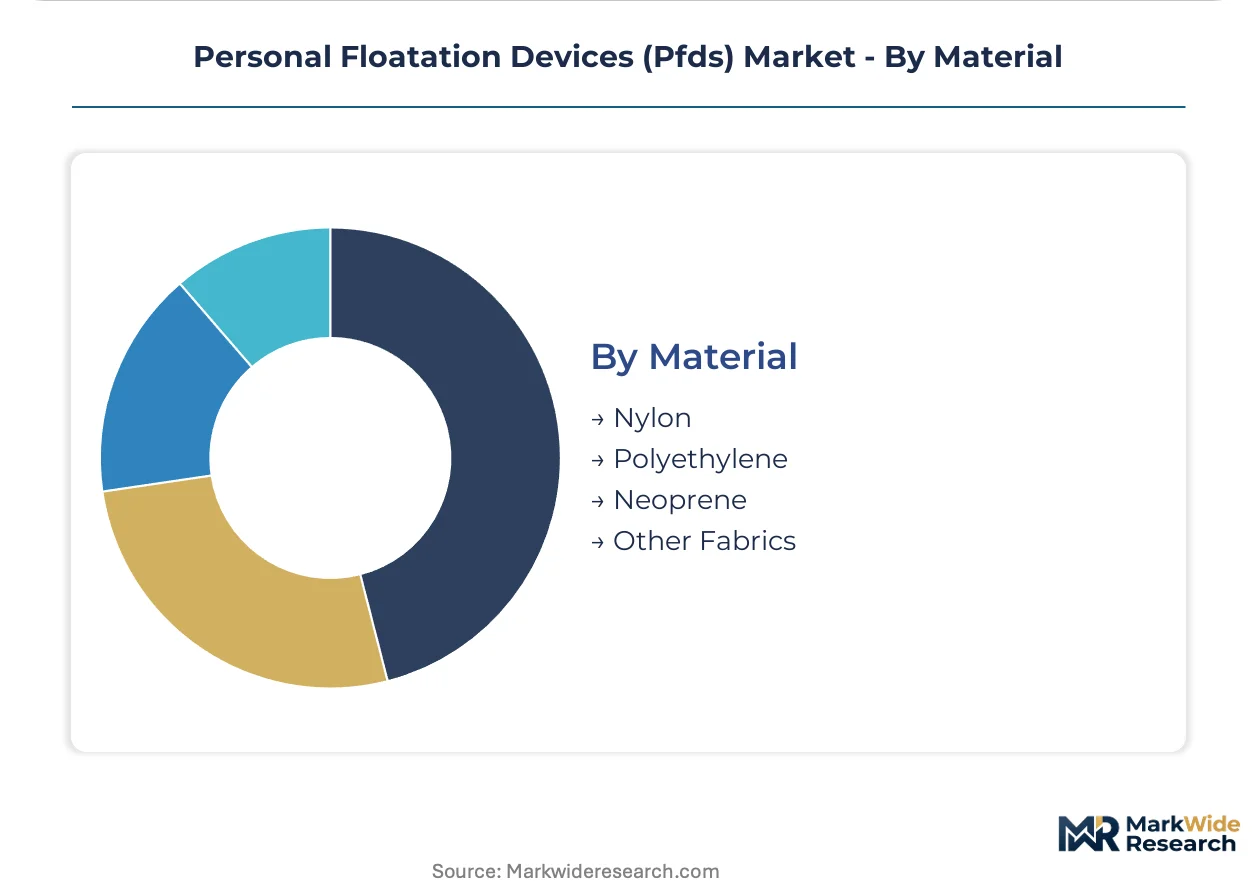
Material:
Margin structure and regulatory compliance burden vary by material chemistry, with petroleum-derived synthetics facing REACH-driven reformulation costs in European Union markets.
- Nylon:Woven shell fabric providing abrasion resistance and UV degradation protection for Type I offshore life jackets. Supply concentrates among Southeast Asian textile mills serving high-volume commercial contracts.
- Polyethylene:Closed-cell foam core delivering inherent flotation without inflation dependency. Michigan and Wisconsin manufacturing clusters specialize in foam molding for domestic USCG-certified production.
- Neoprene:Synthetic rubber foam enabling stretch-fit integration with wetsuit systems for performance water sports.
- Other Fabrics:Aramid reinforcements, mesh ventilation panels, and bio-based synthetic alternatives.
Polyethylene commands the greatest production tonnage; neoprene faces the steepest raw material cost volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational boating infrastructure investment concentrates demand for Type II and Type III devices across Florida's marina corridors and the Great Lakes cluster. Fleet operators in these regions are consolidating procurement volumes through direct manufacturer relationships.
United States
Florida's Tampa Bay and Miami-Dade corridors sustain the densest specialty retail networks for PFD distribution. The US Coast Guard's updated Type I-V classification standards mandate higher buoyancy retention thresholds, compressing product development cycles. Michigan and Wisconsin manufacturing clusters specialize in closed-cell polyethylene foam molding for domestic USCG-certified production.
Canada
Transport Canada alignment with US standards is creating streamlined certification pathways for cross-border product launches. The Great Lakes boating cluster spans the Ontario shoreline, where marina rental chains are unbundling PFD procurement from vessel maintenance contracts. Swift-water rescue teams in British Columbia drive demand for quick-don harness-integrated systems.
Germany
REACH chemical restrictions are forcing reformulation of foam compounds and textile treatments used in PFD construction. Bavaria's lake districts and North Rhine-Westphalia's inland waterway networks concentrate recreational boater demand. German manufacturers must validate alternative flame retardants and plasticizers to maintain EU market access.
United Kingdom
Coastal cruising and racing fleets in the Solent and Scottish lochs are adopting automatic hydrostatic activation models at accelerating rates. The Maritime and Coastguard Agency enforces ISO 12402 standards as de facto market access requirements. Marine chandleries in Southampton and Lymington anchor specialty retail distribution for offshore sailing segments.
Australia
New South Wales and Queensland coastal jurisdictions enforce state-level lifejacket regulations that exceed federal minimums. Sydney Harbour and Gold Coast marina operators are consolidating fleet procurement through seasonal inventory rotation programs. TGA-aligned product safety standards create parallel certification requirements for inflatable mechanism reliability testing.
Personal Floatation Devices (Pfds) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart sensor integration and specialty paddle-sport configurations. The vendor base organizes around three strategic archetypes: marine safety heritage suppliers with commercial vessel contracts, outdoor recreation conglomerates controlling specialty retail channels, and regional foam molding specialists serving rental fleet operators. Competitive moves concentrate on certification harmonization investments and fleet management software integration capabilities.
Within the marine safety heritage tier, Survitec Group Limited and Mustang Survival Corp. exemplify suppliers with deep commercial vessel contracting relationships. Johnson Outdoors Inc. anchors the outdoor recreation conglomerate archetype through North American specialty retail channel presence. Aqua Lung International represents the diving equipment crossover specialist pursuing paddle-sport market expansion.
| Leading Market Players |
|---|
| Survitec Group Limited |
| Johnson Outdoors Inc. |
| The Coleman Company Inc. |
| Mustang Survival Corp. |
| Aqua Lung International |
| Kent Sporting Goods Company Inc. |
| Kokatat Inc. |
| NRS (Northwest River Supplies) |
| Marine Rescue Technologies Ltd. |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility in neoprene synthetic rubber cascades through premium water-sports PFD tiers, compressing margin structures for manufacturers sourcing from Southeast Asian textile mills while reinforcing pricing power for vertically integrated foam molders in Michigan and Wisconsin.
Pricing Analysis
Volume concentrates in standard-grade polyethylene foam life jackets for commercial fishing fleets and marina rental chains, while margin accumulates in neoprene-integrated buoyancy aids for wakeboarders and kite surfers. Three-tier pricing structure across premium, standard, and economy levels separates SOLAS-grade Type I offshore devices with retroreflective tape from Type II near-shore rentals and entry-level general merchandiser SKUs. Cost compression in neoprene-dependent premium lines is intensifying because petrochemical feedstock swings directly transmit to synthetic rubber compound costs. Commercial fleet operators exhibit lowest price sensitivity due to regulatory compliance mandates, while recreational day sailors demonstrate highest elasticity, trading between Type II and Type III devices based on seasonal promotion cycles.
Supply Chain Analysis
Regional distribution centers in Tampa Bay and Miami-Dade anchor hub-and-spoke fulfillment patterns serving Florida's intracoastal marina corridors, with seasonal inventory rotation programs managing Q1-Q2 weather disruption exposure. Manufacturing concentrates in Michigan, Wisconsin, and Vietnam, with domestic foam molding clusters feeding USCG-certified production and Southeast Asian textile mills supplying nylon shell fabrics. Raw material dependencies rest on closed-cell polyethylene resin, neoprene synthetic rubber compounds, and CO2 inflation cartridges. Single-source vulnerability in automated inflation mechanism engineering creates bottleneck risk for offshore sailing vest suppliers. Distribution runs through specialty marine chandleries for high-margin transactions and direct fleet contracts for volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as Coast Guard certification timeline compression extends approval cycles by 4-6 months, straining working capital for smaller players unable to absorb dual-certification investments for ISO 12402 harmonization.
For Market Incumbents: Lock in fleet management software integration capabilities to defend marina rental chain contracts against disintermediation pressure from direct manufacturer relationships. Deepen backward integration into closed-cell polyethylene foam molding to insulate margin structures from petrochemical volatility while capturing Type I-III commercial vessel procurement consolidating through Survitec Group Limited and Mustang Survival Corp. heritage networks. For New Entrants and Emerging Players: Capture paddle-sport specialty retail white space across kayak outfitters and stand-up paddleboard channels in the Great Lakes boating cluster, where slim-profile vest configurations with premium neoprene finishes remain underpenetrated. Target swift-water rescue teams in British Columbia and emergency services coast guard auxiliaries requiring quick-don harness-integrated systems with limited incumbent specialization. Pursue Transport Canada alignment as streamlined cross-border certification pathway. For Investors and Strategic Acquirers: ISO 12402 harmonization completion is the leading indicator that dual-certified suppliers will capture disproportionate European Union market access, making certification-ready manufacturing assets attractive acquisition targets. Five-to-ten year viability favors suppliers with in-house inflation mechanism engineering and smart sensor GPS beacon integration capabilities serving commercial fishing cooperatives. Watch for REACH chemical restriction enforcement accelerating bio-based synthetic rubber alternative adoption as inflection signal for neoprene-dependent portfolio risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | ISO 12402 alignment with USCG Type I-V standards unlocks European Union marina and commercial vessel contracts. |
| Smart Sensor Integration | GPS beacon convergence with inflatable vest activation opens maritime safety monitoring contracts with fishing cooperatives. |
| Fleet Management Software | Seasonal inventory rotation programs secure direct procurement relationships with Florida intracoastal rental chains. |
| Bio-Based Neoprene Reformulation | REACH-compliant synthetic rubber alternatives protect EU market access for water-sports premium lines. |
| Paddle-Sport Channel Expansion | Kayak and stand-up paddleboard outfitters represent underpenetrated distribution for slim-profile vest configurations. |
Research Methodology
Independent corroboration across marine safety procurement directors, Coast Guard certification engineers, and specialty retail channel managers underwrites the qualitative findings in this analysis. Primary interviews with fleet operators, marina rental chain buyers, and foam molding plant managers combined with secondary validation from USCG approval databases, Transport Canada regulatory filings, and REACH chemical restriction notices. Bottom-up triangulation across product type segmentation and top-down cross-check against recreational boating infrastructure investment data anchored volume and value estimates.
Comparable-period anchoring to historical USCG certification cycle data and ISO 12402 adoption trajectories structured the forecast window across the projection horizon. The analytical framework modeled product type, end-user category, distribution channel, and material chemistry dimensions alongside regional regulatory cluster alignment. CAGRs derived from segmented growth rate reconciliation and cross-validation against boating participation surveys and marina fleet expansion disclosures. Inflation mechanism reliability testing standards and hydrostatic activation adoption curves informed offshore sailing segment projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction enforcement, petrochemical feedstock volatility, and Coast Guard-ISO harmonization timeline shifts. Outputs reflect documented assumptions around certification cycle durations and fleet procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Diving Suits Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
China Pollution Mask Market
Protective Gear
Tactical Boots Market
Protective Gear
Europe Lanyards Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Heated Goggles Market
Protective Gear
Earplug Distributor Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Flavored Condoms Market
Protective Gear
Pet Control Devices Market
Protective Gear
Helmets Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Waterproof Boots Market