
 Insect Repellent Market | 2026-2036
Insect Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Repellent Market Intelligence
EPA-registered formulation tiers is bifurcating the competitive landscape into professional-grade and mass-market channels. S.C. Johnson & Son leverages its Raid and Off! brand portfolios to sustain shelf dominance across North American retail networks. Reckitt Benckiser Group anchors its position through concentrated R&D spending on next-generation active ingredient delivery systems. Godrej Consumer Products dominates emerging-market price points with region-specific scent and format adaptations.
Insect repellents are topical or ambient formulations containing active compounds such as DEET, picaridin, or oil of lemon eucalyptus that interfere with arthropod olfactory receptors to prevent bites. These products serve commercial and consumer markets by reducing vector-borne disease transmission and enabling sustained outdoor activity. Spray formats lead volume sales due to convenience and dose control, while wearable devices represent the fastest-expanding application method as consumers seek hands-free protection. DEET-based formulations occupy the deepest margin pools in professional and military procurement channels, whereas oil of lemon eucalyptus derivatives capture premium positioning in natural-product retail segments.
EPA registration requirements govern active ingredient efficacy claims and label specifications in the United States, while ECHA REACH compliance shapes chemical authorization across European manufacturing. Brazil's ANVISA mandates clinical efficacy documentation for repellents marketed against Aedes aegypti, tightening market access for unverified formulations. Stakeholders must monitor evolving regulatory thresholds for synthetic active concentrations and emerging natural-compound equivalency standards to align R&D pipelines with compliance timelines.
Market Dynamics
EPA registration timelines are compressing product development cycles while Brazilian ANVISA mandates on Aedes-targeting efficacy claims force reformulation investments. These dual regulatory pressures are fragmenting competitive positioning between established synthetic actives and emerging bio-based alternatives.
Growth Catalysts
- Adventure tourism expansion:Outdoor recreation participation is pulling portable repellent formats into hiking, camping, and ecotourism gear kits across Southeast Asia and Latin America.
- ECHA REACH substance authorization:Accelerated review timelines for synthetic actives are opening registration windows for plant-derived compounds in European consumer channels.
- Wearable device convergence:Ultrasonic and thermal emission technologies are integrating with fitness trackers and outdoor apparel to create hands-free protection systems.
Market Restraints
- DEET supply concentration:Active ingredient production clusters in Chinese chemical manufacturing zones, exposing formulators to input volatility and logistics disruption.
- EPA efficacy claim substantiation:Extended clinical testing requirements delay market entry for novel active compounds by 24-36 months in United States distribution channels.
- Natural oil substitution pressure:Oil of lemon eucalyptus and citronella derivatives are capturing shelf space in premium retail segments, compressing synthetic active margins.
Strategic Opportunities
- Sub-Saharan Africa household penetration:Malaria endemic zones present underdeveloped ambient repellent markets where coil and vaporizer formats remain nascent.
- IR3535 regulatory tailwind:ECHA favorable hazard classification is expanding approved use concentrations in European personal care formulations.
- Direct-to-consumer subscription models:Seasonal replenishment programs are bypassing traditional retail markup structures for outdoor enthusiast segments.
Industry Challenges
- Entomological testing capacity scarcity:Validated mosquito colony maintenance and cage testing facilities are bottlenecking product claim verification timelines.
- Label claim harmonization complexity:Divergent protection duration standards across EPA, ECHA, and ANVISA frameworks force territory-specific packaging configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Repellent Market |
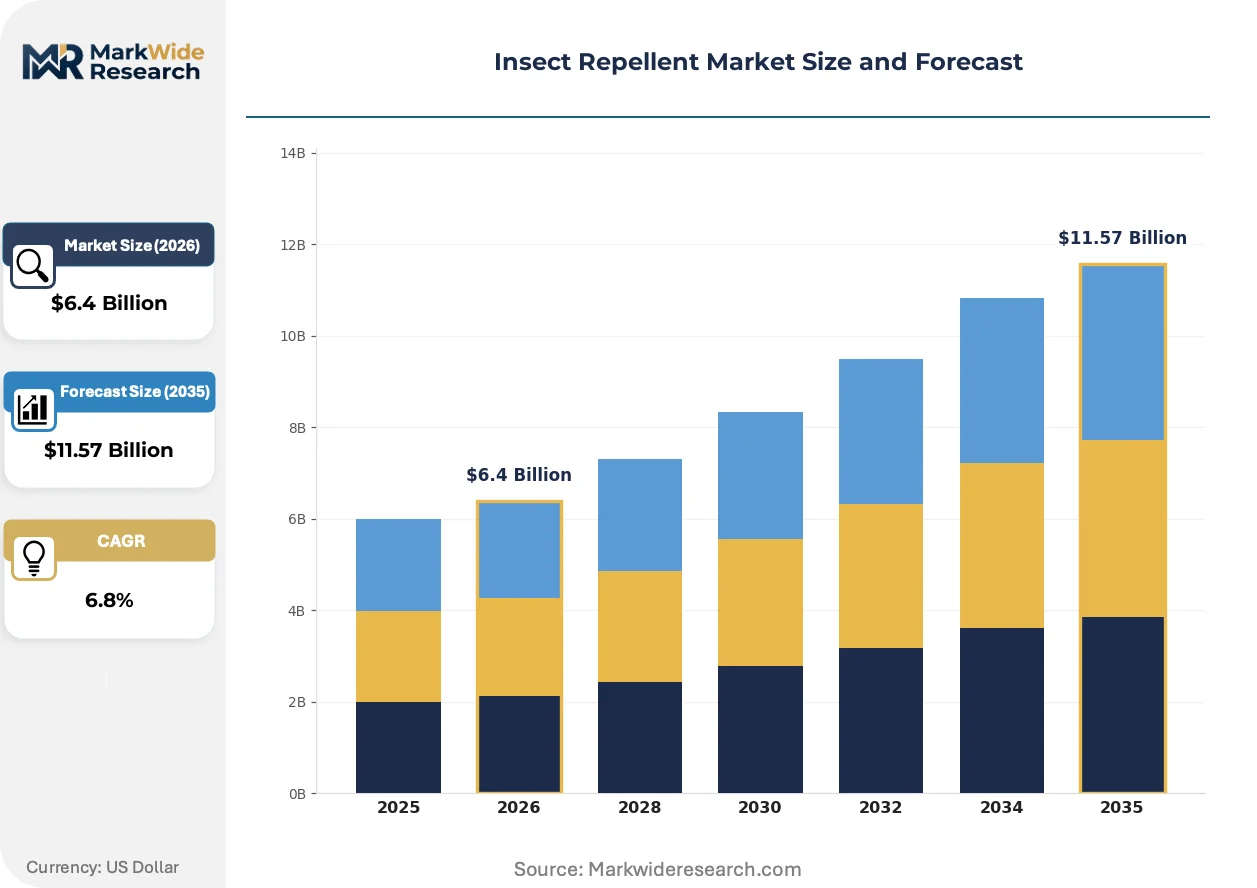
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Lotion, Gel, Wipes Active Ingredient: DEET, Picaridin, Oil of Lemon Eucalyptus, IR3535 Application Method: Topical, Ambient, Wearable, Space Spray End User: Households, Outdoor Enthusiasts, Travelers, Pet Owners |
| Companies Covered | S.C. Johnson & Son, Reckitt Benckiser Group, Spectrum Brands, Godrej Consumer Products, Dabur India, BASF SE, Henkel AG & Co. KGaA, The 3M Company, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Repellent Market Strategic Shifts & Innovations
Formulation science is pivoting toward encapsulation technologies that extend active release duration while reducing skin permeation. This shift is redrawing competitive boundaries between pharmaceutical-grade delivery expertise and traditional consumer goods manufacturing.
Microencapsulation of DEET and picaridin is decomposing the tradeoff between efficacy duration and cosmetic elegance that has constrained premium positioning. Outdoor apparel manufacturers are licensing these technologies for fabric-integrated protection systems. The result is collapsing the distinction between topical and wearable application categories.
EU Green Deal chemical sustainability criteria are tightening biodegradability thresholds for rinse-off personal care products. Formulators are reformulating emulsion bases to meet OECD 301B testing standards ahead of mandatory compliance deadlines. Natural-product retail channels in Germany and France are capturing accelerated shelf placement for certified-biodegradable alternatives.
Subscription-based replenishment is displacing seasonal retail purchasing patterns among urban outdoor enthusiasts. Direct channels are offering calibrated dosing schedules tied to local vector activity forecasts. This behavioral shift is most pronounced in United States coastal markets where Lyme disease awareness drives year-round tick repellent consumption.
Insect Repellent Market Segmentation
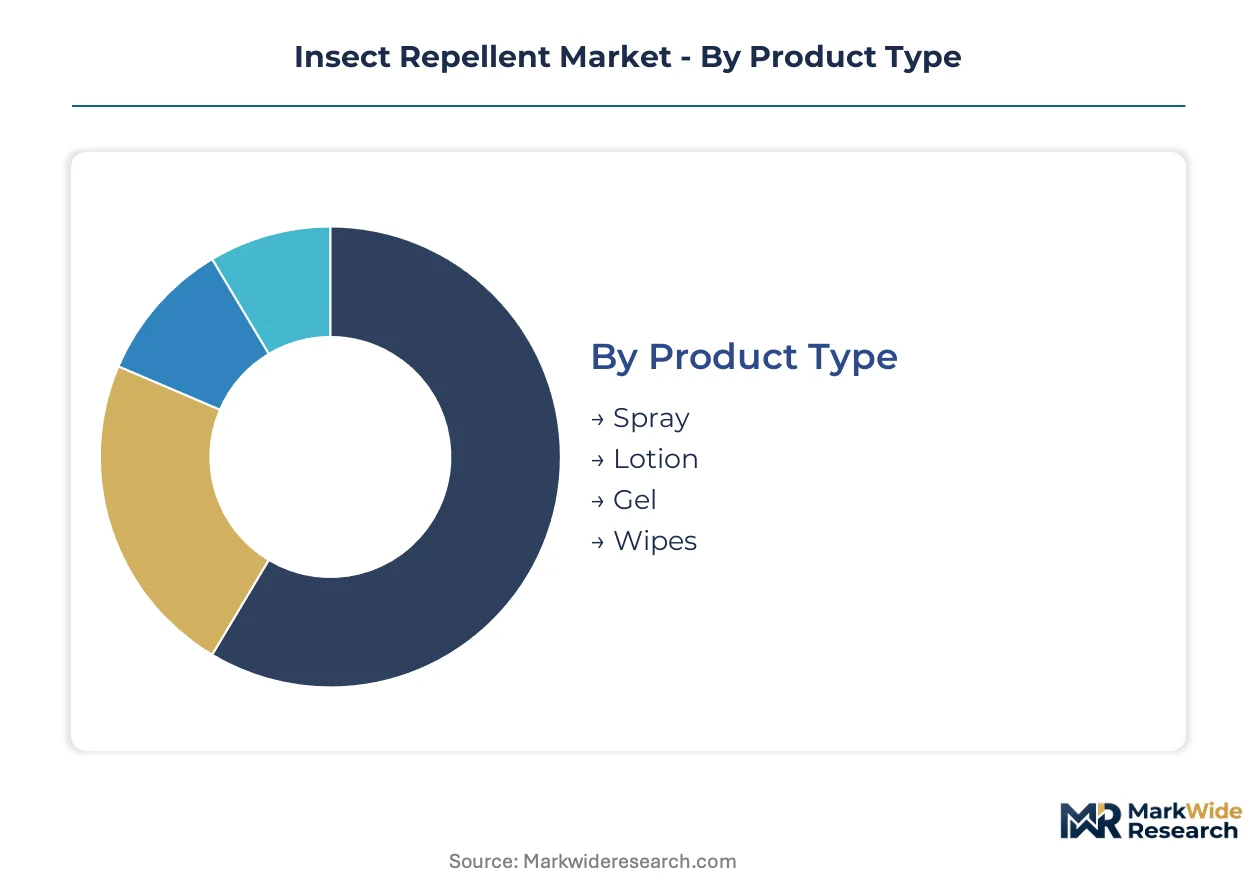
Segmentation in insect repellents tracks how formulation chemistry, application convenience, and vector exposure risk intersect to determine purchasing patterns. Manufacturers align R&D pipelines and distribution investments against these divides to capture margin pools across professional procurement and mass retail channels.
Product Type:
Spray formats face the strongest substitution pressure from wearable devices and fabric-integrated systems as consumers seek hands-free protection during sustained outdoor activity.
- Spray:Aerosol and pump-dispensed formulations containing emulsified active compounds in alcohol or water bases. Demand concentrates in North American mass retail where convenience drives household replenishment cycles, though EPA volatility restrictions on propellants are forcing reformulation investments.
- Lotion:Cream and milk emulsions with extended skin adherence through polymer thickeners. Brazilian and Southeast Asian households favor these for children and evening outdoor dining, where longer protection duration justifies application effort.
- Gel:Hydroalcoholic matrices with rapid drying and non-greasy cosmetic finish. Travelers in European airport retail channels select these for carry-on compliance and discrete reapplication.
- Wipes:Nonwoven substrates impregnated with calibrated active doses. Outdoor enthusiasts in United States national park gateway towns purchase these for pack weight reduction and precise dosing control.
Spray retains volume leadership; wearable-integrated formats hold the steepest expansion curve.
Active Ingredient:
Cost tier stratification separates military-procurement synthetics from premium natural-positioned compounds, with mid-tier molecules capturing share through regulatory tailwinds.
- DEET:N,N-diethyl-meta-toluamide, the reference standard for arthropod olfactory receptor interference at concentrations from 10% to 100%. United States military and professional forestry contracts specify high-concentration formulations, though supply concentration in Chinese chemical zones exposes formulators to input volatility.
- Picaridin:Synthetic piperidine derivative with comparable efficacy to DEET and improved cosmetic elegance. European consumer channels favor these for skin-feel preferences, with ECHA REACH authorization supporting expanded use concentrations.
- Oil of Lemon Eucalyptus:Botanically derived p-menthane-3,8-diol from Corymbia citriodora. German and French natural-product retail segments capture premium shelf placement for certified-biodegradable alternatives meeting EU Green Deal criteria.
- IR3535:Ethyl butylacetylaminopropionate with favorable ECHA hazard classification enabling higher concentrations in European personal care formulations. Direct-to-consumer subscription channels in coastal United States markets are building seasonal replenishment programs around this chemistry.
DEET commands the deepest margin pools in institutional procurement; IR3535 is climbing the fastest through regulatory-enabled personal care integration.
Application Method:
Customer type divergence separates skin-contact formulations from environmental systems, with hybrid technologies collapsing traditional category boundaries.
- Topical:Direct skin application through sprays, lotions, or sticks. Households in malaria-endemic zones maintain year-round consumption, though Brazilian ANVISA efficacy documentation requirements for Aedes-targeting claims tighten market access.
- Ambient:Coil, mat, and vaporizer formats releasing spatial protection through thermal or electrical dispersion. Sub-Saharan African markets remain underpenetrated for these systems despite high vector disease burden.
- Wearable:Ultrasonic emitters, thermal diffusion patches, and apparel-integrated microencapsulated fabrics. Fitness tracker manufacturers in United States and Japanese markets are licensing pharmaceutical-grade delivery expertise for converged protection systems.
- Space Spray:Aerosolized area treatment for immediate knockdown and residual barrier effects. Commercial hospitality and food service operations in Southeast Asian ecotourism zones deploy these for guest area management.
Topical maintains household penetration dominance; wearable formats are gaining share fastest through technology convergence.
End User:
Volume concentration tracks geography and seasonality, with adventure tourism expansion reshaping demand timing across formerly seasonal markets.
- Households:Year-round ambient and topical consumption in tropical disease-endemic regions. Brazilian year-round Aedes vigilance sustains coil and vaporizer replenishment cycles unmatched in temperate climates.
- Outdoor Enthusiasts:Hikers, campers, and ecotourism participants requiring portable, multi-hour protection. Southeast Asian and Latin American adventure tourism growth is pulling calibrated-dose formats into gear kit standard configurations.
- Travelers:Air passengers and international visitors seeking TSA-compliant sizes and destination-appropriate efficacy. United States coastal Lyme disease awareness has extended tick repellent consumption into traditional off-season months.
- Pet Owners:Species-specific formulations addressing flea, tick, and mosquito vectors on companion animals. Veterinary channel distribution in North America and Europe separates this segment from human-product retail.
Households anchor absolute volume; outdoor enthusiasts command the steepest trajectory through adventure tourism expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient manufacturing clusters in Chinese chemical zones expose formulators to input volatility, while regulatory divergence across EPA, ECHA, and ANVISA frameworks fragments territory-specific packaging requirements.
United States
EPA registration timelines compress product development cycles by 24-36 months for novel compounds. Military and professional forestry contracts specify high-concentration DEET formulations, anchoring institutional procurement volumes. S.C. Johnson & Son maintains shelf dominance across retail networks through concentrated brand portfolios.
Brazil
Year-round Aedes aegypti vigilance sustains household consumption of coils and vaporizers unmatched in temperate climates. ANVISA mandates clinical efficacy documentation for vector-targeting claims, tightening market access for unverified formulations. São Paulo anchors national distribution infrastructure for ambient repellent formats.
Germany
ECHA REACH authorization for IR3535 and picaridin enables expanded use concentrations in personal care channels. German natural-product retail segments capture premium shelf placement for oil of lemon eucalyptus derivatives meeting EU Green Deal biodegradability criteria. Cologne and Frankfurt concentrate formulation R&D for European consumer markets.
China
DEET and synthetic active production clusters in eastern manufacturing zones supply global formulators. NMPA registration requirements govern domestic efficacy claims while export-oriented capacity serves international procurement channels. Zhejiang and Jiangsu provinces dominate active ingredient chemical synthesis.
India
CDSCO oversight aligns with WHO prequalification standards for vector-borne disease prevention products. Household penetration of ambient formats remains underdeveloped relative to topical consumption in malaria-endemic eastern states. Mumbai and Ahmedabad anchor Godrej Consumer Products' emerging-market price-point distribution.
Insect Repellent Market Key Industry Players
Concentration sits with diversified consumer goods conglomerates holding EPA-registered formulation portfolios and established retail shelf presence. The competitive landscape bifurcates between professional-grade channels serving institutional procurement and mass-market retail networks. Three archetypes dominate: legacy household brands with regulatory scale, chemical suppliers with backward integration into active ingredient production, and regional specialists with localized scent and format adaptations. Dominant competitive moves include technology licensing for microencapsulation delivery systems and geographic expansion into underpenetrated ambient repellent markets.
Within the diversified conglomerate tier, S.C. Johnson & Son and Reckitt Benckiser Group exemplify regulatory-scale incumbents with established North American and European retail anchoring. Godrej Consumer Products occupies a position representing emerging-market price-point specialization with region-specific adaptation capabilities. Among chemical suppliers with active ingredient integration, BASF SE and Sumitomo Chemical sit within the supply-side concentration that shapes formulator input costs and availability.
| Leading Market Players |
|---|
| S.C. Johnson & Son |
| Reckitt Benckiser Group |
| Spectrum Brands |
| Godrej Consumer Products |
| Dabur India |
| BASF SE |
| Henkel AG & Co. KGaA |
| The 3M Company |
| Sumitomo Chemical |
| Others |
Cost & Logistics Intelligence
Active ingredient manufacturing scale economies in Chinese chemical zones anchor global price floors for DEET and picaridin, concentrating supply-side leverage among formulators with backward integration into eastern production clusters. This concentration compresses margins for non-integrated competitors while amplifying volatility exposure during logistics disruptions or regulatory interventions.
Pricing Analysis
EPA registration dictates the pricing tier structure across the United States market, separating professional-grade military procurement from mass retail channels through efficacy claim substantiation requirements. Three-tier pricing structure across premium, standard, and economy levels tracks active ingredient concentration and cosmetic elegance, with oil of lemon eucalyptus derivatives commanding brand premiums in natural-product segments. Cost compression in synthetic active tiers is intensifying because Brazilian ANVISA reformulation mandates force incremental R&D pass-through. Outdoor enthusiasts in direct-to-consumer subscription channels show least price sensitivity, while emerging-market households in price-point segments exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for DEET and synthetic actives extend 16-20 weeks from Zhejiang and Jiangsu province manufacturing clusters, exposing formulators to working capital strain and demand forecasting errors. Supply concentrates in China for active ingredient synthesis, with India anchoring secondary capacity for natural oil derivatives and Germany hosting formulation R&D for European consumer channels. Raw material dependencies include meta-toluic acid for DEET production, Corymbia citriodora biomass for oil of lemon eucalyptus extraction, and polymer encapsulation substrates for extended-release technologies. Single-source vulnerability in Chinese chemical zones poses structural risk. Distribution runs through North American retail networks, Brazilian ambient product wholesalers, and European pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through EPA-registered formulation portfolios creates durable defensive moats, as 24-36 month approval timelines for novel actives deter competitive replication and anchor incumbent shelf presence.
For Market Incumbents: Shield market position by deepening microencapsulation technology licensing to outdoor apparel manufacturers, collapsing topical-wearable category boundaries before substitute formats gain scale. Prioritize capacity addition in Brazilian formulation facilities to capture ANVISA-compliant production capacity ahead of regional competitors. Channel control through direct-to-consumer subscription platforms offers secondary defensive leverage against retail margin compression.
For New Entrants and Emerging Players: ECHA REACH fast-track authorization for IR3535 and plant-derived compounds opens registration windows without DEET's supply concentration exposure. Target underpenetrated ambient repellent markets in Sub-Saharan Africa, where coil and vaporizer formats remain nascent despite malaria endemicity. Go-to-market angle should emphasize biodegradable certification alignment with EU Green Deal criteria to capture premium shelf placement in German and French natural-product retail.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade delivery expertise over traditional consumer goods manufacturing, as encapsulation science redraws competitive boundaries. Long-term viability rests on converged protection systems integrating with fitness trackers and outdoor apparel. Acquisition target archetype: regional specialists with localized ANVISA or ECHA regulatory capabilities and established mosquito colony testing partnerships. Signal to watch: wearable device manufacturer licensing announcements indicating technology convergence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Extends protection duration while reducing skin permeation, enabling fabric-integrated systems for outdoor apparel manufacturers. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional retail markup structures through calibrated dosing schedules tied to local vector activity forecasts. |
| Biodegradable Formulation Repositioning | Captures premium shelf placement in German and French natural-product channels meeting EU Green Deal OECD 301B standards. |
| Regional Regulatory Certification Investment | ANVISA and ECHA registration capabilities tighten market access for unverified competitors in Brazil and European personal care. |
| Backward Integration into Active Ingredient Production | Reduces exposure to Chinese chemical zone supply concentration and input volatility for DEET-dependent formulators. |
Research Approach
A spread of perspectives from brand managers at consumer goods conglomerates, category buyers at North American and European retailers, regulatory affairs leads navigating EPA and ECHA frameworks, and supply planners managing active ingredient procurement converged on the working assumptions. Primary interviews triangulated with secondary validation from EPA registration databases, ANVISA efficacy documentation filings, ECHA REACH substance authorization records, and customs trade data tracking DEET and picaridin import flows. Bottom-up demand modeling across product formats and active ingredient tiers cross-checked against top-down market sizing from manufacturer capacity disclosures.
Segmentation dimensions modeled include formulation chemistry, application convenience, vector exposure risk, and geographic regulatory cluster across the analysis window. CAGRs derived from trend extrapolation of outdoor recreation participation rates, adventure tourism expansion trajectories, and vector-borne disease incidence patterns. Industry-specific forecast inputs incorporate entomological testing capacity constraints and evolving biodegradability thresholds under EU Green Deal implementation timelines.
Underlying assumptions cover sustained EPA registration timeline compression, ANVISA enforcement consistency, and Chinese chemical zone supply stability, with deviation risk concentrated in regulatory harmonization failures across territories and substitution acceleration toward wearable formats. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Food Processing Uniforms Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Tactical Boots Market
Protective Gear
Waterproof Cases Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Work Shoes Market
Protective Gear
Helmet Lining Market
Protective Gear
Heated Goggles Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Combat Boots Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Flavored Condoms Market
Protective Gear
Hand Gloves Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Military Boots Market