
 Equestrian Helmets Market | 2026-2036
Equestrian Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Equestrian Helmets Market Analysis
The capital-intensity divergence between premium custom-fit producers and mass-market assemblers is unwinding competitive stability across the equestrian helmets landscape. Charles Owen leverages its English manufacturing heritage and bespoke fitting services to sustain pricing power in the show-jumping segment. Troxel competes through domestic US production scale and broad retail distribution, while KEP Italia differentiates via Italian design integration and ventilation technology leadership.
Equestrian helmets are protective headgear engineered with multi-layer construction—typically an outer shell of polycarbonate, fiberglass, or carbon fiber bonded to an inner expanded polystyrene liner—to absorb and dissipate impact energy during falls from horseback. Their primary commercial purpose centers on reducing traumatic brain injury risk across competitive, training, and recreational riding contexts. The product type dimension shows jumping and cross-country helmets commanding premium positioning due to higher certification thresholds and shorter replacement cycles, while dressage and western styles occupy more mature, price-sensitive demand pools. Carbon fiber and polycarbonate materials are capturing fastest-growing share as riders trade up for lighter weight and superior impact ratings, whereas fiberglass faces gradual displacement in professional tiers.
ASTM F1163, SEI certification, and EN 1384 standards govern helmet approval across the United States and European Union, with compliance audits intensifying as insurers tie coverage to certified equipment use. The US Consumer Product Safety Commission and EU's Personal Protective Equipment Regulation coordinate recall protocols but diverge on testing velocity requirements, creating compliance complexity for multinational suppliers. Stakeholders must monitor whether emerging national equestrian federations adopt harmonized standards or fragment certification demands further.
Market Dynamics
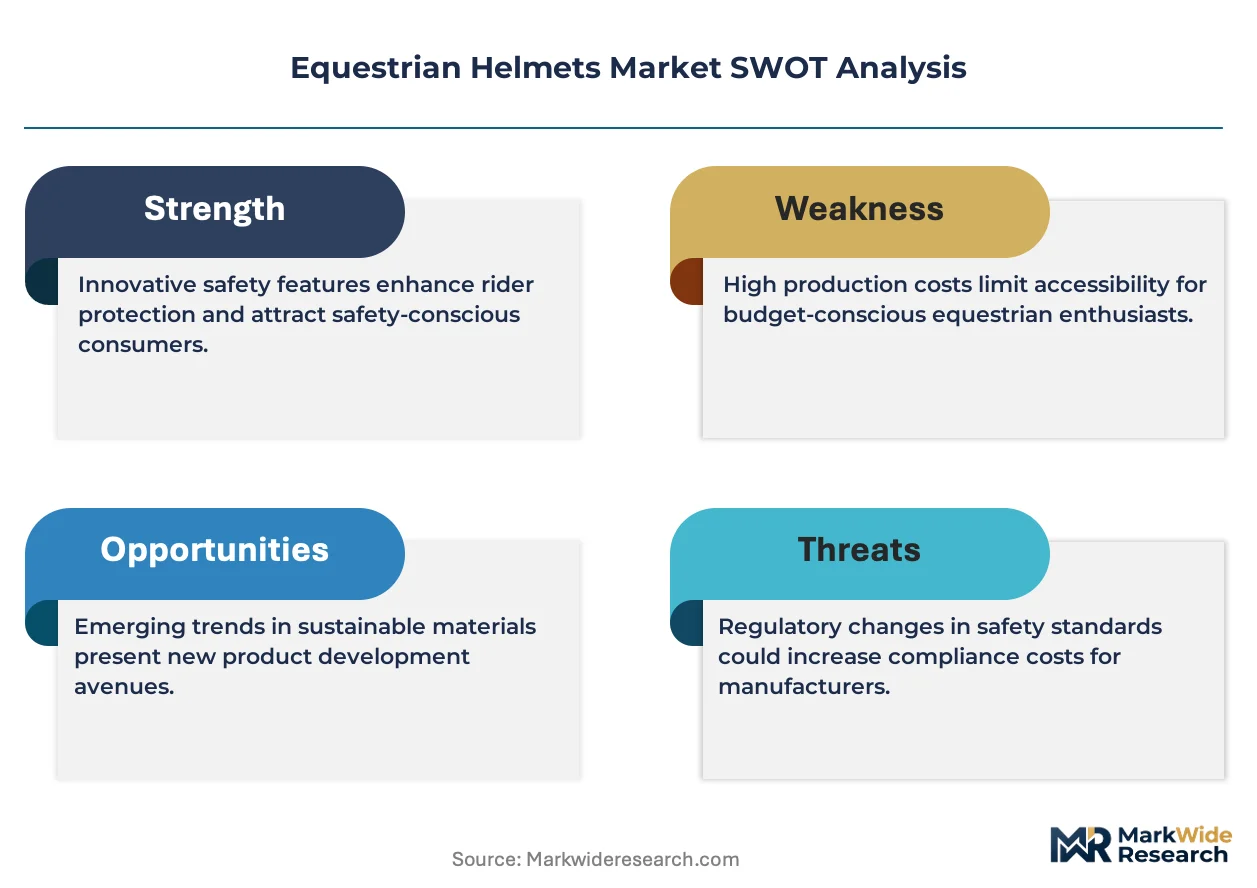
Safety certification tightening across ASTM F1163 and EN 1384 standards is compressing replacement cycles and forcing material upgrades throughout the equestrian helmets supply base. Manufacturers must requalify existing product lines while absorbing higher testing costs.
Growth Catalysts
- ASTM F1163 Certification Mandates:US competitive riding programs now require SEI-certified helmets for sanctioned events, accelerating turnover in show-jumping and cross-country disciplines.
- Carbon Fiber Material Adoption:Professional riders in Germany and the United Kingdom are trading up to lighter shell constructions that improve comfort during extended training sessions.
- Youth Equestrian Program Expansion:Pony Club and 4-H chapter growth across Texas, Virginia, and Kentucky is creating first-time helmet demand from institutional bulk purchasers.
Market Restraints
- Polycarbonate Resin Price Volatility:Petrochemical feedstock fluctuations directly compress margin on entry-level helmet production.
- Italian Component Concentration:KEP Italia and specialized ventilation hardware suppliers cluster in Lombardy, creating single-source risk for premium ventilation systems.
- EN 1384 Testing Bottlenecks:European Notified Body capacity constraints extend certification timelines by four to six months for new product launches.
Strategic Opportunities
- India Equestrian Infrastructure Buildout:Delhi and Mumbai polo club expansions lack established helmet distribution networks, opening white-space for ASTM-compliant imports.
- Smart Helmet Sensor Integration:Convergence of micro-accelerometers with Bluetooth telemetry enables fall-detection alerts for remote training monitoring.
- Direct-to-Consumer Custom Fitting:3D head-scanning apps bypass traditional tack shop intermediaries, capturing margin from bespoke show-helmet buyers.
Industry Challenges
- Master Craftsman Shortage:Bespoke helmet fitting requires trained technicians; English manufacturing heritage programs graduate fewer specialists than replacement demand requires.
- Multi-Jurisdiction Compliance Costs:Simultaneous ASTM, SEI, and EN 1384 testing duplicates expenditure for products sold across US and EU markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equestrian Helmets Market |
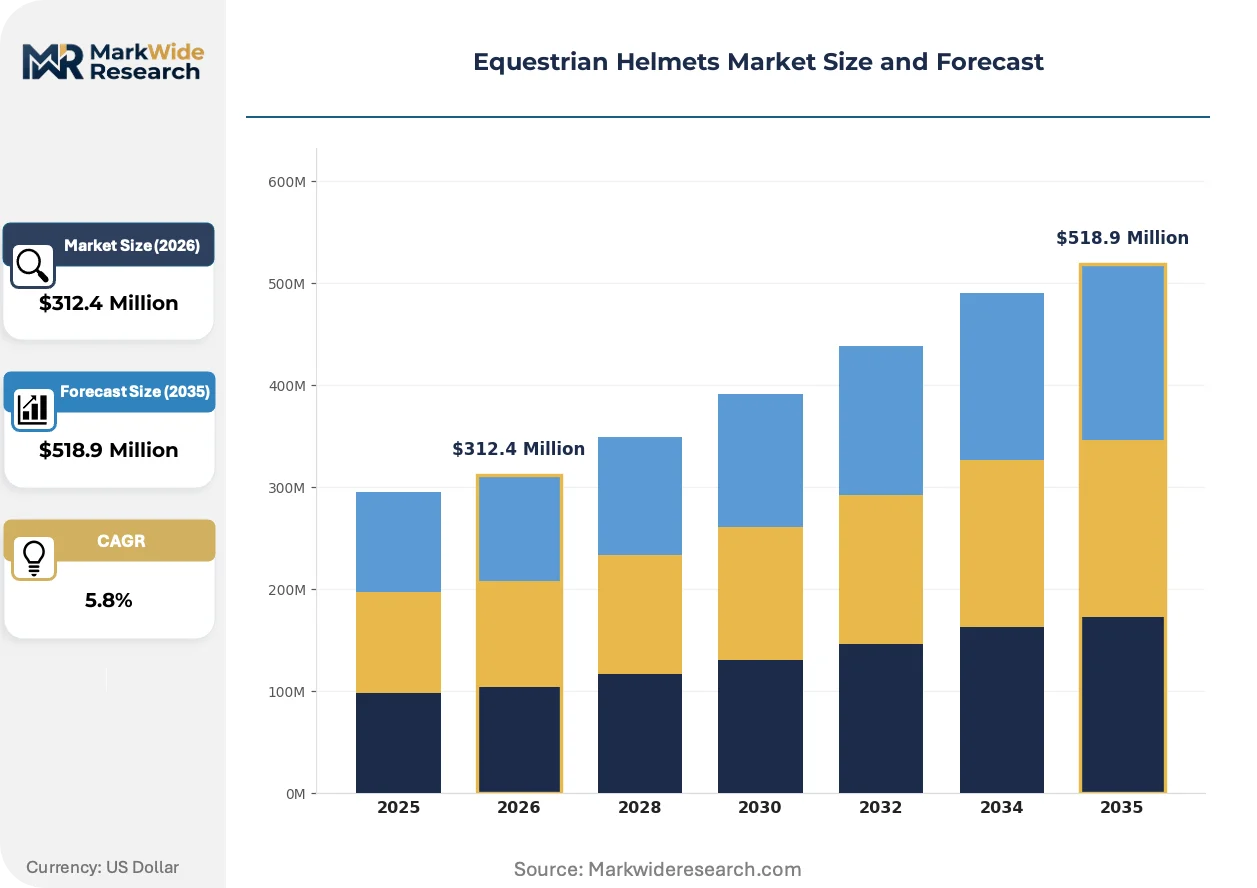
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-Country, Jumping, Dressage, Western Material: Polycarbonate, Fiberglass, Carbon Fiber, Synthetic Leather End User: Athletes, Hobbyists, Professionals, Leisure Riders Safety Standard: ASTM, SEI, SNELL, EN |
| Companies Covered | Samshield, KEP Italia, Troxel, Ovation, GPA, Charles Owen, UVEX, IRH Helmet, One K, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equestrian Helmets Market Emerging Trajectories
Material science advances and certification digitization are restructuring how helmet performance is validated and communicated to risk-conscious buyers. These shifts favor suppliers with in-house testing capabilities and transparent supply chain documentation.
Multi-density expanded polystyrene liners are fragmenting traditional single-layer impact absorption designs. Professional three-day event riders in the United Kingdom and Germany are specifying variable-density constructions for cross-country falls. This technology is fragmenting the premium segment into certified-performance tiers that separate elite competition gear from recreational products.
REACH chemical compliance deadlines in the European Union are restricting legacy flame-retardant additives in interior padding materials. Manufacturers must reformulate foam compositions or face market withdrawal across France, Germany, and the Netherlands. Show-helmet producers with advanced materials R&D facilities are capturing displaced volume from suppliers caught in regulatory transition.
Subscription-based helmet replacement programs are displacing traditional ownership models among US collegiate equestrian teams. Institutional buyers in Texas and Virginia now lease certified headgear with automatic swap-out at impact or expiration. This procurement evolution concentrates volume with suppliers offering logistics integration and bulk refurbishment capabilities.
Equestrian Helmets Market Segmentation
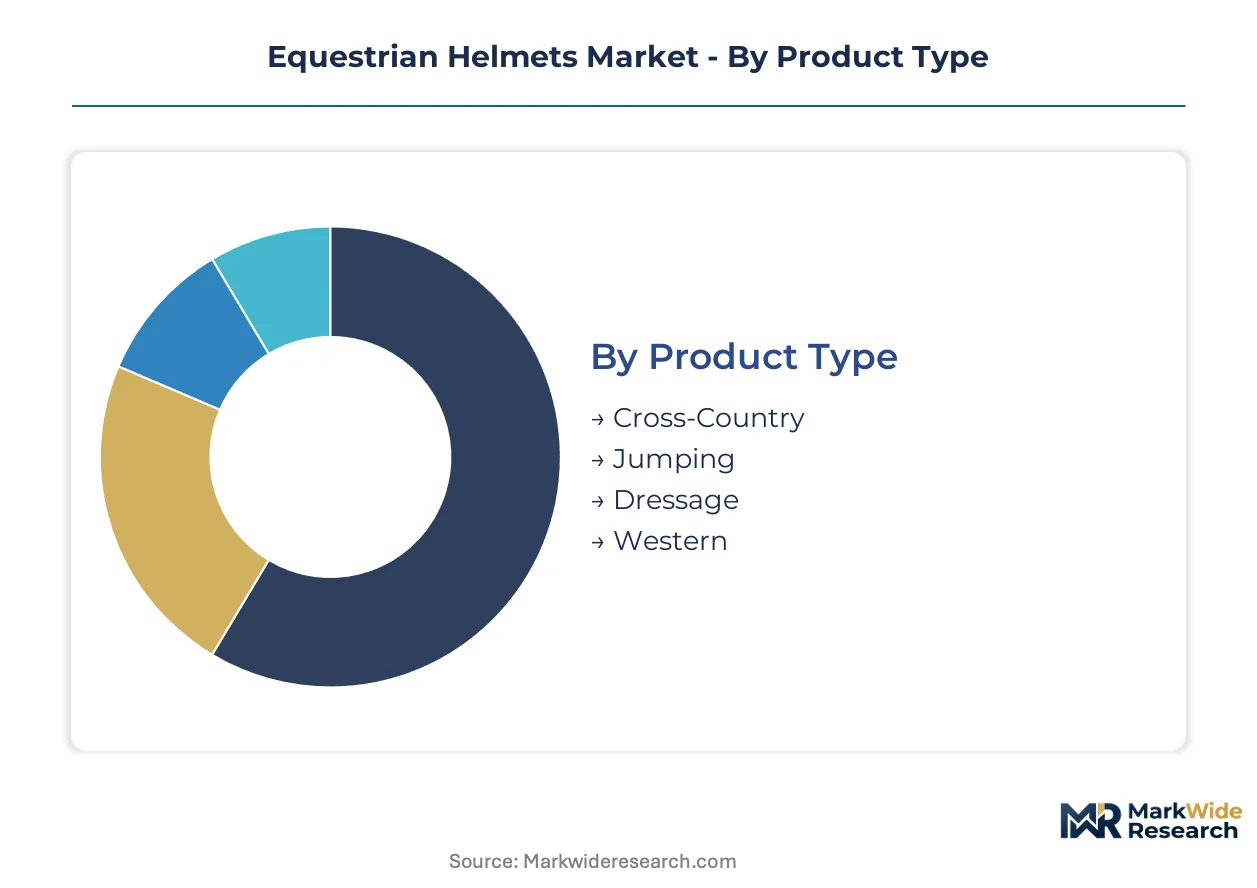
Segmentation in equestrian helmets determines certification pathways, replacement cycles, and margin capture. Product type and material choices dictate distribution channel selection, while end-user classification shapes pricing architecture and safety standard requirements.
Product Type:
Jumping and cross-country helmets flow through specialty tack shops and direct-to-consumer premium channels, while dressage and western styles concentrate in mass retail and feed-store distribution networks.
- Jumping:Multi-layer construction with reinforced crown protection meets ASTM F1163 and EN 1384 certification thresholds. Demand concentrates in the United States and United Kingdom competitive circuits where SEI-certified helmets are mandatory for sanctioned events.
- Cross-Country:Extended rear coverage and enhanced ventilation systems address the higher fall-risk profile of three-day eventing. German and British professional riders specify these for extended training sessions, driving carbon fiber adoption.
- Dressage:Streamlined profiles with minimal protrusions suit arena-based precision riding. Hobbyist segments in France and the Netherlands favor these for recreational training.
- Western:Broader brim configurations and heritage styling target leisure riders. Distribution runs through ranch supply chains and regional rodeo equipment vendors.
Western helmets dominate installed base in North American recreational markets. Jumping configurations are where expansion concentrates among competitive program participants.
Material:
Cost tier stratification separates professional-grade carbon fiber from entry-level polycarbonate, with fiberglass occupying the contested mid-market and synthetic leather addressing aesthetic customization demand.
- Carbon Fiber:Ultra-lightweight shell construction delivers superior impact absorption-to-weight ratios. Professional athletes in Germany and the United Kingdom trade up for reduced neck strain during multi-hour training sessions.
- Polycarbonate:Injection-molded shells offer cost-efficient production at scale. Hobbyist and leisure rider segments in the United States absorb volume through big-box sporting goods retailers.
- Fiberglass:Hand-laid composite construction balances durability with moderate weight. Mid-tier professionals seeking ASTM compliance without carbon fiber pricing gravitate here.
- Synthetic Leather:Surface finishing materials enable color matching and show-ring aesthetics. Custom fitting services integrate these for bespoke orders.
Polycarbonate holds the broadest installed base across institutional and first-time purchasers. Carbon fiber is climbing the fastest among competitive riders prioritizing performance specifications.
End User:
Customer type determines procurement modality, with athletes demanding certified performance tiers, hobbyists responding to price-positioned retail, and professionals requiring bespoke fitting protocols.
- Athletes:Competitive riders in sanctioned programs require SEI, ASTM, or EN-certified helmets with documented impact testing. Replacement cycles compress to 3-5 years under federation mandates.
- Professionals:Trainers and coaches specify premium custom-fit helmets with ventilation optimization. Direct-to-consumer channels and specialized fitting studios serve this segment.
- Hobbyists:Recreational riders prioritize cost accessibility over advanced specifications. Mass retail and online marketplaces capture this volume.
- Leisure Riders:Occasional participants in trail and pleasure riding seek basic protection with comfort features. Western-style preferences dominate in United States ranching regions.
Hobbyists represent the largest addressable population by headcount. Athletes are where margin expansion and replacement velocity concentrate.
Safety Standard:
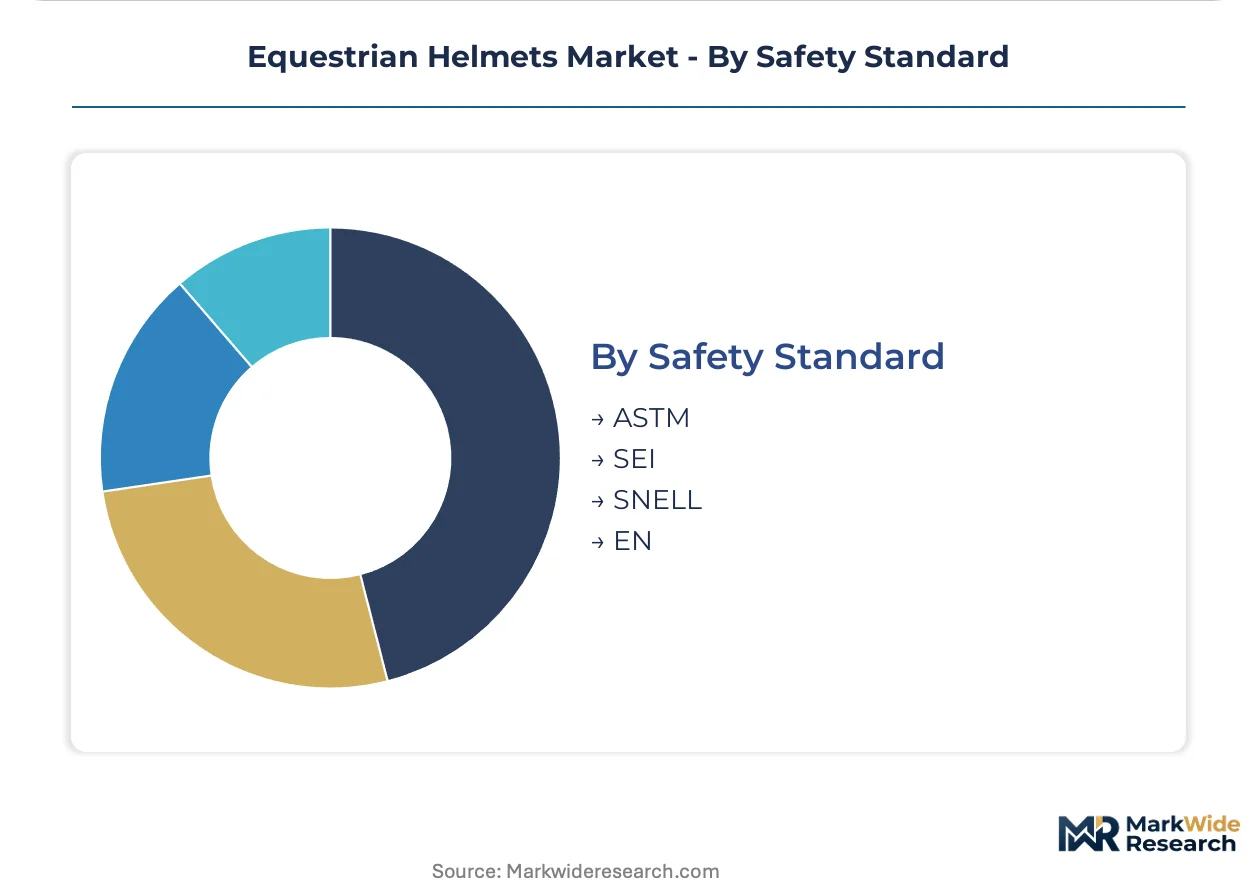
Geographic regulatory scope fragments certification requirements, with ASTM governing United States competitive access, EN controlling European market entry, and SNELL addressing voluntary premium positioning.
- ASTM:F1163 specifications govern impact attenuation and retention system performance. United States Pony Club and collegiate equestrian programs mandate this certification for participation.
- EN:EN 1384 and VG1 standards apply across European Union member states. Notified Body testing bottlenecks in Germany and France extend certification timelines.
- SEI:Safety Equipment Institute certification provides independent ASTM F1163 verification. United States insurers increasingly tie coverage to SEI-labeled equipment.
- SNELL:Voluntary higher-threshold certification appeals to risk-averse professional segments. Limited adoption outside elite North American competitors.
ASTM-certified helmets dominate United States competitive infrastructure. EN certification is where European market access and cross-border harmonization efforts concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United Kingdom and Germany where bespoke fitting services command substantial premiums, while mass-market volume gravitates toward US domestic producers operating at scale. ASTM F1163 mandates in the United States compress replacement cycles, whereas EN 1384 bottlenecks in Europe extend certification timelines. Regional divergence in safety infrastructure and competitive program density shapes procurement patterns across national markets.
United States
SEI-certified helmets are mandatory for Pony Club and collegiate equestrian programs across Texas, Virginia, and Kentucky. The US Consumer Product Safety Commission coordinates recall protocols with insurers tying coverage to certified equipment. Domestic production clusters in Pennsylvania and Tennessee serve mass retail through broad distribution networks.
Germany
Professional three-day event riders in Baden-Württemberg and Lower Saxony specify carbon fiber constructions for extended training sessions. The country's national standards body enforces EN 1384 and VG1 certification through Notified Body testing facilities in Berlin and Munich. Stuttgart-area suppliers concentrate on ventilation-optimized designs for competitive segments.
United Kingdom
Show-jumping circuits in Surrey and Gloucestershire drive demand for custom-fit helmets with heritage styling. The British Standards Institution administers EN 1384 compliance alongside voluntary BSI Kitemark programs. Northamptonshire manufacturing retains English craftsmanship traditions for bespoke show-helmet production.
France
Dressage hobbyists in Île-de-France and Provence-Alpes-Côte d'Azur favor streamlined recreational helmets for arena-based training. ANSM and the national standards body oversee REACH chemical compliance deadlines restricting legacy flame-retardant additives. Lyon-area distributors channel volume through specialized tack shop networks.
Italy
Lombardy-based producers supply premium ventilation hardware to KEP Italia and specialized component manufacturers. The national Ministry of Health coordinates with EU Personal Protective Equipment Regulation enforcement for helmet market entry. Milan design studios integrate aesthetic customization with performance engineering for show-ring applications.
Equestrian Helmets Market Vendor Landscape
Concentration sits with heritage English manufacturers and Italian design houses that anchor premium positioning through bespoke services. The vendor base splits between scale-driven domestic assemblers and specialized European fabricators. Three archetypes dominate: English bespoke fitters leveraging manufacturing heritage, US mass-market producers exploiting retail scale, and Italian specialists integrating ventilation innovation. Capacity expansion and direct-to-consumer channel development constitute the primary competitive vectors reshaping procurement relationships.
Among English manufacturing heritage representatives, Charles Owen occupies a position exemplifying bespoke fitting protocols for show-jumping segments. Troxel and IRH Helmet sit within the scale-driven tier, anchoring domestic US production and broad retail distribution networks. KEP Italia represents Italian design integration, with Lombardy-based ventilation technology leadership distinguishing premium positioning. These three archetypes illustrate how geographic manufacturing heritage translates into differentiated procurement relationships across competitive, professional, and hobbyist end-user segments.
| Leading Market Players |
|---|
| Samshield |
| KEP Italia |
| Troxel |
| Ovation |
| GPA |
| Charles Owen |
| UVEX |
| IRH Helmet |
| One K |
| Others |
Supply Flow & Price Mechanics
Carbon fiber substitution for fiberglass in professional-tier shells simultaneously shifts procurement geography toward German and British composite specialists and compresses margin structures for mid-tier assemblers dependent on hand-laid construction. This material transition rewards suppliers with captive R&D facilities while exposing mass-market producers to petrochemical feedstock volatility.
Pricing Analysis
The customization-premium spread separates bespoke show-helmet fittings from standard retail configurations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and shell material, with ASTM F1163 and EN 1384 compliance tiers commanding substantial markups over uncertified recreational alternatives. Cost compression in entry-level polycarbonate segments is intensifying because resin price volatility transfers directly to margin. Hobbyist leisure riders exhibit highest price sensitivity, while competitive athletes demonstrate inelastic demand for certified performance specifications.
Supply Chain Analysis
Lombardy-based ventilation hardware suppliers constitute a chokepoint for premium helmet producers seeking Italian design integration. Manufacturing concentration clusters in the United Kingdom, Germany, and Italy for carbon fiber and bespoke fitting services, while mass-market polycarbonate assembly feeds from domestic US and Asian molding operations. Raw material dependencies center on expanded polystyrene liners, polycarbonate resins, and specialized ventilation components. Single-source vulnerability runs through Lombardy component manufacturers for KEP Italia-compatible hardware. Distribution runs through specialty tack shops for premium tiers and big-box sporting goods retailers for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained technician shortages in English bespoke fitting protocols constrain capacity expansion for heritage manufacturers, creating acquisition premiums for firms with established apprenticeship pipelines.
For Market Incumbents: Shield proprietary fitting protocols through apprenticeship program expansion in Northamptonshire and Surrey manufacturing clusters. Acquire carbon fiber pre-preg suppliers to secure shell material access against German and Italian competitor vertical integration. Certification investment in simultaneous ASTM and EN testing capabilities defends against multi-jurisdiction compliance cost duplication. For New Entrants and Emerging Players: Lead with direct-to-consumer 3D head-scanning apps targeting underserved collegiate equestrian programs in Texas and Virginia. White-space concentration sits in India polo club infrastructure buildout where ASTM-compliant import distribution remains undeveloped. Subscription-based helmet replacement logistics integration offers the most penetrable go-to-market angle against traditional ownership models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Italian design houses holding Lombardy ventilation technology leadership. Long-term viability hinges on smart helmet sensor integration convergence with micro-accelerometer and Bluetooth telemetry capabilities. Watch EN 1384 Notified Body capacity expansion in Berlin and Munich as inflection indicator for European certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Helmet Sensor Integration | Micro-accelerometer fall-detection alerts enable remote training monitoring for German professional riders. |
| Direct-to-Consumer Custom Fitting | 3D head-scanning apps bypass tack shop intermediaries and capture margin from bespoke show-helmet buyers. |
| Carbon Fiber Backward Integration | In-house pre-preg production secures shell material supply against polycarbonate resin price volatility. |
| Subscription Replacement Programs | Institutional leasing with automatic swap-out concentrates volume with logistics-integrated suppliers. |
| India Distribution Network Buildout | Delhi and Mumbai polo club expansions lack established ASTM-compliant helmet import channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with helmet manufacturers, equestrian federation safety officers, specialty tack shop proprietors, and collegiate equestrian program equipment managers. Secondary validation drew from ASTM F1163 certification registries, SEI laboratory testing records, EN 1384 Notified Body audit documentation, and customs trade data for polycarbonate resin and carbon fiber composite imports. Bottom-up unit economics triangulated against top-down market sizing across product type, material, end user, and safety standard segmentation dimensions.
Across the analysis window, volume and value outputs reflect analytical framework approaches modeling replacement cycle compression, certification mandate adoption curves, and material substitution elasticities. Segmentation dimensions span product type, shell material, end-user archetype, and geographic regulatory cluster. CAGRs were derived from fitted growth curves incorporating youth program expansion rates, competitive riding participation trends, and safety standard harmonization probabilities. Industry-specific forecast inputs include EN 1384 testing bottleneck duration estimates and carbon fiber adoption velocity among German three-day event professionals.
The analysis sits within stated boundaries; outcomes outside sustained ASTM and EN certification tightening trajectories would require recalibration. Forecasts reflect assumptions regarding federation mandate enforcement consistency and petrochemical feedstock price regime stability. Practitioners should keep alternative scenarios live as Notified Body capacity constraints and REACH chemical compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Work Shoes Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
China Pollution Mask Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Waterproof Boots Market
Protective Gear
Hand Gloves Market
Protective Gear
Europe Lanyards Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Diving Suits Market