
 Western Boots Market | 2026-2036
Western Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Western Boots Market Analytics
A capital-intensity divergence between heritage hand-last operations and automated cut-and-sew facilities is rotating competitive advantage toward brands that control both craftsmanship narrative and scale economics. Ariat leverages advanced footbed engineering to sustain technical credibility in performance segments. Lucchese anchors ultra-premium positioning through hand-stitched construction traditions in its El Paso workshop. Tecovas competes via direct-to-consumer channel control, bypassing wholesale margin dilution.
Western boots are pull-on footwear distinguished by tall shafts, underslung heels, and leather construction using Goodyear welt or Blake stitch methods, historically designed for horseback riding and ranch labor but now spanning fashion and occupational applications. Leather dominates material value capture due to durability premiums and patina-driven replacement cycles, while synthetic compounds gain share in wet-climate work applications where waterproofing trumps breathability. Rodeo boots command the highest per-unit margins within product-type segmentation, though fashion boots drive absolute volume through broader demographic reach.
The U.S. Consumer Product Safety Commission monitors heel-height safety standards for occupational use, while EPA tanning-effluent rules elevate compliance costs for domestic leather processors. USDA grade specifications for hide quality directly influence raw-material access for premium manufacturers. Stakeholders must monitor how California's Proposition 65 enforcement against chromium VI exposure reshapes tanning chemistry investments and supplier qualification timelines.
Market Dynamics
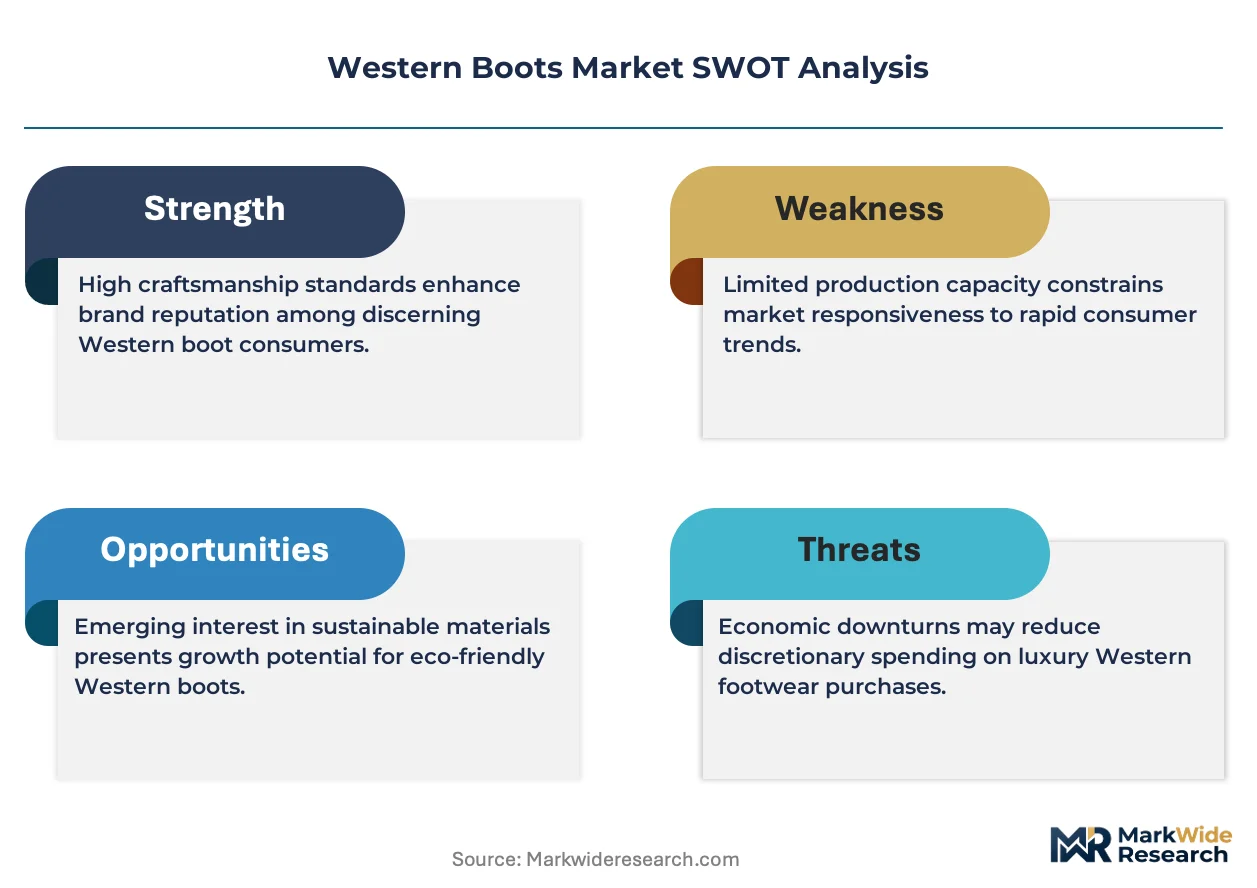
USDA leather traceability mandates and EPA tanning-effluent rules are forcing tanneries to retool chemistry investments, compressing supplier qualification timelines and reshaping raw-material access tiers for premium manufacturers.
Growth Catalysts
- Equestrian Sports Expansion:Professional rodeo circuits and ranch labor standards are elevating performance-grade boot specifications. Competitive riders now prioritize ASTM-certified safety features in competition footwear.
- REACH Chemical Compliance:European Union restrictions on chromium VI and aromatic amines are accelerating bio-based tanning chemistry adoption. Domestic tanneries investing in vegetable-tanning lines gain preferential supplier status with heritage brands.
- Heritage Manufacturing Clusters:Concentrated bootmaking expertise in El Paso and Mercedes sustains artisan output capacity. Geographic density of hand-last craftsmen preserves construction quality differentiation against offshore alternatives.
Market Restraints
- Hide Cost Volatility:USDA grade specifications for premium steer hides create supply rationing during drought cycles. Tanneries face margin compression when hide quality downgrades force yield losses.
- Domestic Tannery Concentration:Over half of specialty western boot leather originates from three US tanning operations. Single-source dependencies expose brands to capacity constraints during regulatory compliance transitions.
- Synthetic Substitution in Work Applications:Waterproof polyurethane compounds displace leather in wet-climate ranch operations. Breathability trade-offs are accepted where durability premiums fail to justify cost differentials.
Strategic Opportunities
- Direct-to-Consumer Channel Control:Bypassing wholesale margin dilution enables full-price capture and customer data ownership. Digital-native entrants demonstrate viable path to scale without retail partner dependency.
- Bio-Based Tanning Chemistry:Vegetable and synthetic alternatives to chromium tanning align with California Proposition 65 enforcement trends. Early compliance investments position suppliers for premium brand qualification.
- Fashion Segment Demographic Expansion:Urban consumers outside traditional ranch and rodeo cultures are adopting western boots as statement footwear. Stylized shaft embroidery and exotic leather options attract discretionary spending from coastal metropolitan markets.
Industry Challenges
- Hand-Last Craftsmanship Shortage:Master bootmakers capable of traditional hand-stitched construction are aging out of the workforce. Training pipelines fail to replenish skilled labor at replacement rates.
- Prop 65 Compliance Timelines:California enforcement actions against chromium VI exposure create retroactive liability exposure. Brands must audit entire supplier tiers to certify chemical safety documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Western Boots Market |
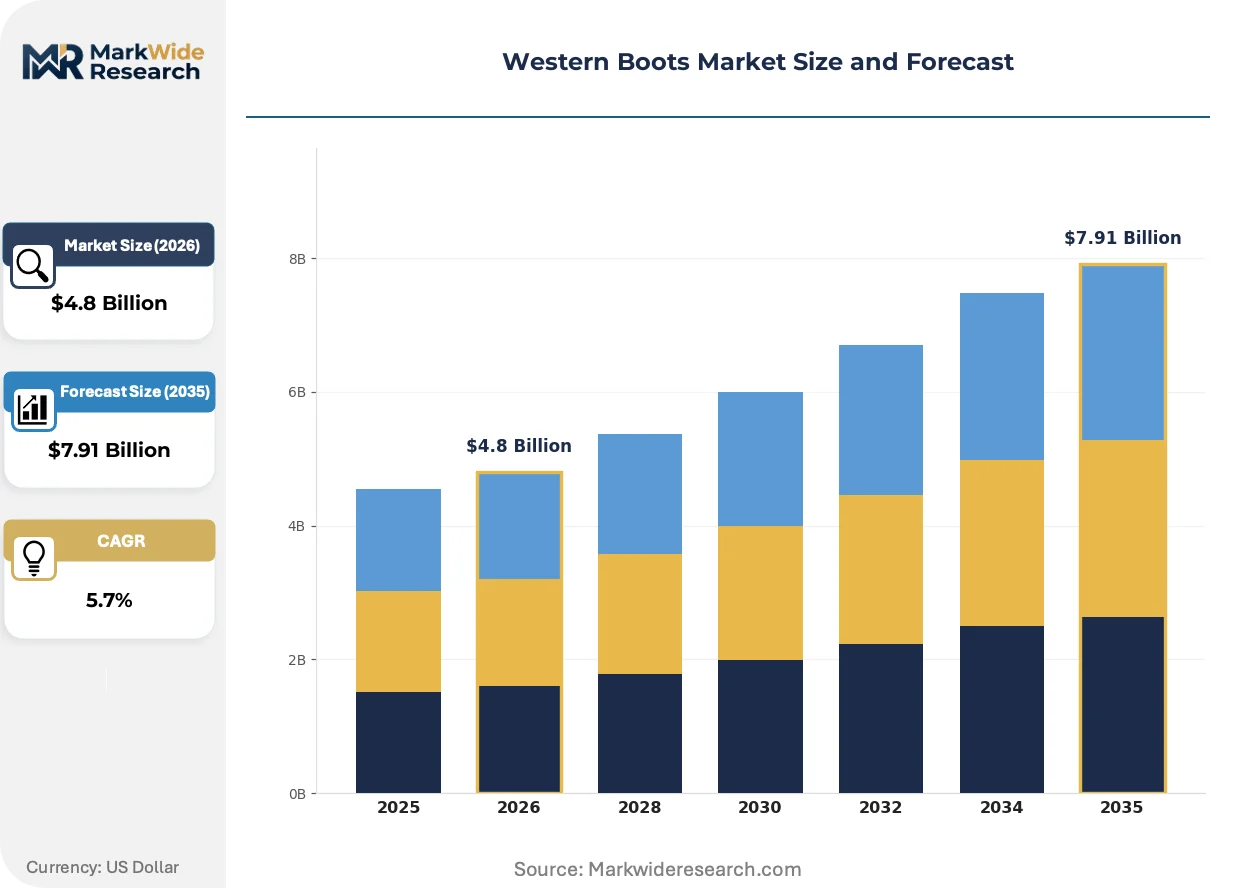
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Work Boots, Fashion Boots, Rodeo Boots, Cowboy Boots Material: Leather, Synthetic, Suede, Canvas End User: Men, Women, Children, Riders Distribution Channel: Online Retail, Specialty Stores, Department Stores, Farmers Markets |
| Companies Covered | Tecovas, Anderson Bean, Ariat, Double H, Twisted X, Lucchese, Tony Lama, Fenoglio Boot Co., Justin Boots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Western Boots Market Evolving Landscape
Advanced footbed engineering and automated cutting systems are fragmenting competitive advantage between technical performance credibility and manufacturing scale economics. Material science investments now determine tier positioning as much as heritage construction methods.
Biomechanical footbed systems incorporating dual-density polyurethane and gel cushioning layers are decomposing the traditional trade-off between all-day comfort and authentic western silhouette requirements. Professional ranchers and competitive riders are specifying ASTM F2413-compliant safety toes with moisture-wicking linings at accelerating rates. Technical credibility is compressing price premiums for heritage-only brands lacking engineering credentials.
EPA effluent guidelines for leather tanning operations are mandating closed-loop water recycling and heavy-metal capture systems. Domestic tanneries face seven-figure capital requirements to maintain operating permits under revised discharge standards. Small-batch artisan producers in Texas and New Mexico are consolidating or exiting as compliance costs outstrip revenue scale.
Wholesale bypass models are capturing margin previously allocated to multi-tier distribution. Digital-native brands operating company-owned retail and direct fulfillment are achieving full-price realization rates fifteen to twenty points above traditional wholesale-dependent competitors. Texas and Oklahoma metropolitan corridors show highest direct-to-consumer penetration, where rodeo culture overlap with e-commerce fluency creates favorable customer acquisition economics.
Western Boots Market Segmentation
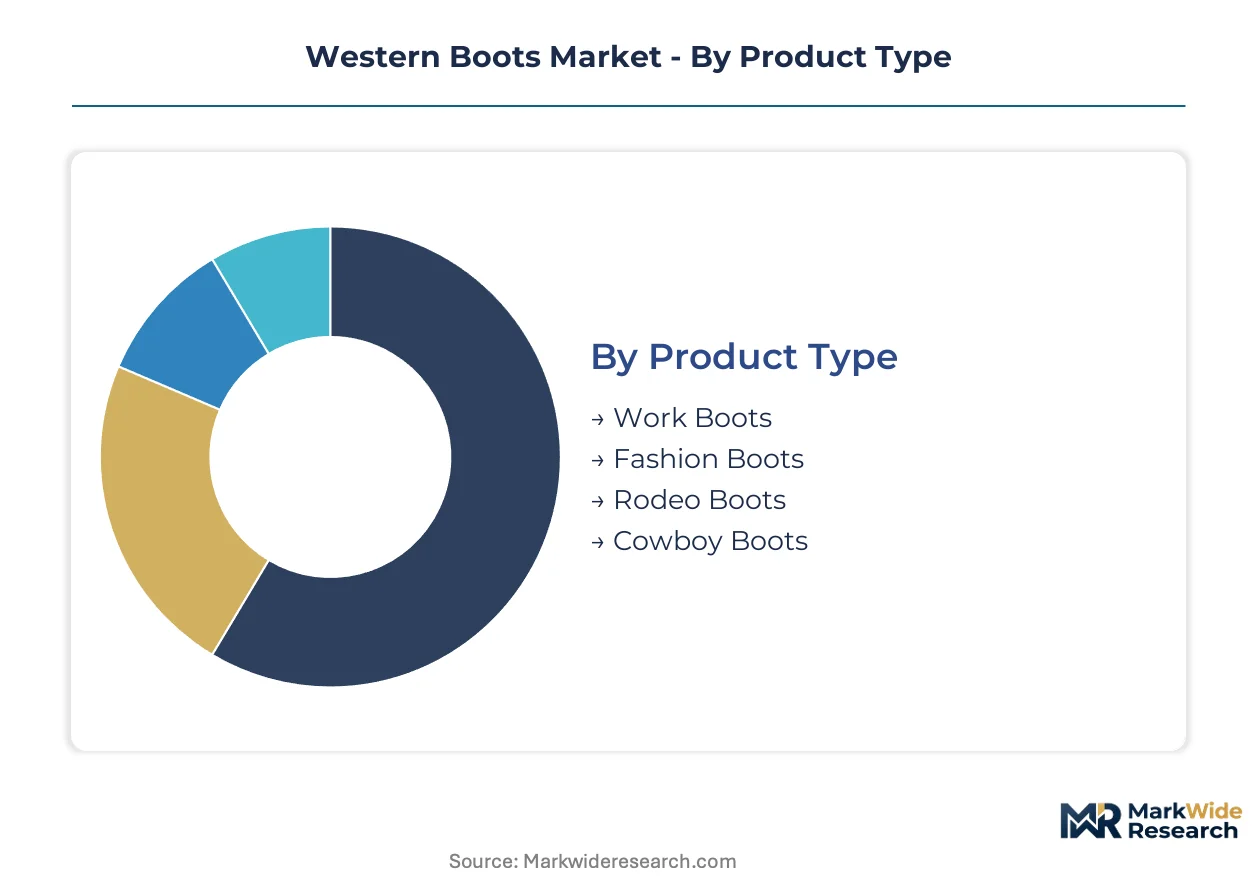
Western boots traverse distinct demand curves across product categories, with ranch labor specifications diverging sharply from fashion-forward styling priorities. Material selection and channel strategy further fragment addressable markets, forcing brands to anchor positioning against specific use cases rather than broad demographic appeals.
Product Type:
Domestic consumption concentrates in heritage ranching states, while export demand gravitates toward fashion-forward silhouettes for European and Asian urban markets.
- Work Boots:ASTM F2413 safety certifications and moisture-wicking linings define technical specifications for professional ranchers and oilfield workers. Demand clusters in Texas, Oklahoma, and Wyoming, where occupational safety mandates and all-day wear durability override styling considerations.
- Rodeo Boots:Hand-stitched construction with underslung heels and tall shafts engineered for competitive performance. Professional circuits in Texas and Oklahoma sustain premium pricing, with custom fitting services capturing margins unavailable in mass-market alternatives.
- Fashion Boots:Stylized shaft embroidery and exotic leather options target coastal metropolitan consumers outside traditional ranch culture.
- Cowboy Boots:Heritage silhouettes balance authenticity with accessibility for casual western wear occasions.
Work boots hold the largest share; momentum sits with fashion boots.
Material:
Cost tiers separate premium heritage positioning from volume-accessible alternatives, with tanning chemistry investments determining supplier qualification tiers.
- Leather:Full-grain steer hides graded under USDA specifications deliver durability premiums and patina-driven replacement cycles. Vegetable-tanning lines at domestic tanneries are gaining preferential supplier status as California Proposition 65 enforcement accelerates chromium VI phaseouts.
- Synthetic:Polyurethane compounds displace leather in wet-climate ranch operations where waterproofing trumps breathability. Oilfield workers in Gulf Coast states accept durability trade-offs for chemical resistance and lower replacement costs.
- Canvas:Lightweight construction targets festival and casual wear segments with price-sensitive entry points.
- Suede:Napped finishes serve fashion applications requiring softer drape and distinctive texture differentiation.
Leather dominates absolute volume; synthetics are climbing the fastest as work applications accept performance trade-offs.
End User:
Customer type stratification reveals divergent fit engineering requirements and styling priorities across demographic segments.
- Men:Traditional sizing dominance in ranch labor and rodeo competition segments, with width variations accommodating occupational boot requirements. Professional riders specify technical performance features at rates exceeding casual consumers.
- Women:Fashion segment expansion drives shaft height and toe shape experimentation beyond heritage masculine silhouettes. Urban adopters in coastal markets prioritize stylized embroidery and colorway variety.
- Riders:Competitive equestrian athletes demand ASTM-certified safety toes and biomechanical footbed systems for performance protection.
- Children:Growth-accommodating construction and cost-conscious pricing serve family ranching households with rapid replacement cycles.
Men's boots retain the largest share; women's fashion adoption shows steepest expansion trajectory.
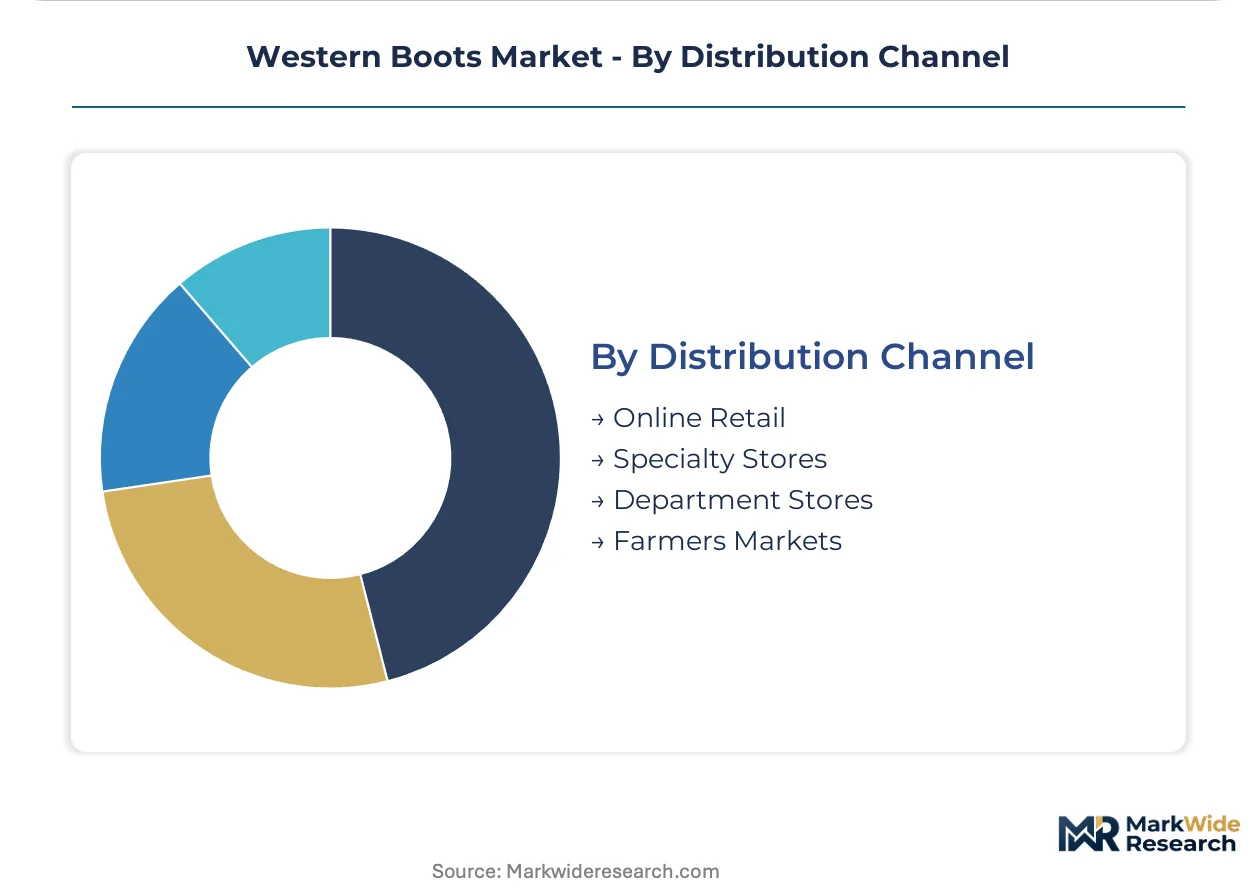
Distribution Channel:
Channel economics fragment margin capture, with direct control enabling full-price realization against wholesale-dependent alternatives.
- Online Retail:Company-owned digital storefronts bypass multi-tier distribution margin dilution. Texas and Oklahoma metropolitan corridors demonstrate highest penetration where rodeo culture overlap with e-commerce fluency reduces customer acquisition costs.
- Specialty Stores:Bootfitting expertise and custom order capabilities sustain premium positioning for heritage brands. El Paso and Mercedes workshop proximity enables made-to-measure services unavailable through mass retail.
- Department Stores:Broader geographic reach sacrifices margin to wholesale partner terms and inventory risk transfer.
- Farmers Markets:Artisan producers leverage direct producer-consumer relationships for small-batch heritage construction.
Specialty stores hold the largest share; online retail is gaining share fastest through margin recapture and data ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: heritage ranching cultures sustain premium leather demand in North American heartlands, while European and Asian markets gravitate toward stylized fashion silhouettes with limited functional riding applications.
United States
Texas and Oklahoma metropolitan corridors concentrate both production capacity and consumption intensity, with El Paso and Mercedes workshop clusters sustaining hand-last craftsmanship traditions. USDA leather traceability programs and EPA tanning-effluent rules are forcing domestic tanneries to retool chemistry investments, compressing supplier qualification timelines for heritage brands. The Southwestern states anchor premium bootmaking, where geographic density of artisan producers preserves construction quality differentiation against offshore alternatives.
Canada
Alberta ranching operations and Calgary Stampede culture sustain demand for performance-grade work and rodeo specifications, though absolute volumes trail US consumption by an order of magnitude. Health Canada product safety standards align with ASTM certification requirements, enabling cross-border supply chain integration for technical footwear. Prairie Provinces distribution networks channel heritage American brands rather than cultivating domestic manufacturing clusters.
Mexico
Northern border states and the Bajío Region host leather tanning operations supplying raw material to US bootmakers, with Guanajuato tanneries navigating EPA-compliant chemistry transitions to maintain export access. Domestic consumption clusters in rural ranching states, where price-sensitive demand favors standard-grade construction over ultra-premium hand-stitched alternatives. Mexico's national standards body certifies occupational safety features for oilfield and agricultural work applications.
Germany
Equestrian sports culture in Lower Saxony and Baden-Württemberg sustains niche demand for technical riding boots, though European consumers favor dressage and jumping silhouettes over western-specific underslung heel designs. ECHA REACH restrictions on chromium VI and aromatic amines are accelerating bio-based tanning chemistry adoption, with domestic tanneries investing in vegetable-tanning lines to serve heritage brand qualification requirements. German distributors function as fashion importers rather than manufacturing anchors.
Australia
New South Wales and Queensland cattle stations sustain work boot demand, though local preferences favor elastic-sided riding boots over traditional western shaft constructions. The country's national agricultural regulator monitors chemical exposure standards for occupational footwear, with drought-driven hide quality volatility creating supply rationing during El Niño cycles. Australian tanneries serve domestic workwear brands rather than exporting to premium western boot manufacturers.
Western Boots Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence between heritage hand-last operations and automated cut-and-sew facilities rotating competitive advantage toward dual-capability players. The market structure fragments across three strategic archetypes: engineering-driven performance brands, artisan heritage houses, and digital-native direct-to-consumer entrants. Dominant competitive moves include wholesale bypass strategies that recapture margin from multi-tier distribution, and backward integration into tannery operations to secure compliant leather supply.
Within the heritage artisan tier, Lucchese and Tony Lama exemplify concentrated geographic production models, with El Paso workshop proximity enabling made-to-measure services unavailable through scaled manufacturing. Among engineering-driven specialists, Ariat occupies a position representing technical credibility in performance segments through biomechanical footbed systems. Tecovas anchors the digital-native archetype, demonstrating viable path to scale through direct channel control without retail partner dependency.
| Leading Market Players |
|---|
| Tecovas |
| Anderson Bean |
| Ariat |
| Double H |
| Twisted X |
| Lucchese |
| Tony Lama |
| Fenoglio Boot Co. |
| Justin Boots |
| Others |
Value Network & Pricing Analysis
EPA tanning-effluent rules and California Proposition 65 enforcement against chromium VI exposure simultaneously gate supplier qualification tiers and compress price differentiation between heritage and mass-market construction. Brands investing early in vegetable-tanning chemistry compliance capture preferential raw-material access while commanding sustained premiums against late-adopting competitors facing retroactive liability exposure.
Pricing Analysis
Long-term offtake contracts between heritage bootmakers and domestic tanneries dominate premium leather procurement, insulating qualified suppliers from spot-market hide volatility while locking in volume commitments. Three-tier pricing structure across premium hand-stitched, standard Goodyear-welt, and economy cemented construction separates Lucchese-grade artisans from automated cut-and-sew facilities. Cost compression in entry-level tiers is intensifying because polyurethane work-boot substitution erodes leather's durability premium justification in wet-climate applications. Oilfield workers and price-sensitive ranch laborers exhibit highest price sensitivity; competitive rodeo athletes and coastal fashion adopters show lowest.
Supply Chain Analysis
Texas and Oklahoma anchor domestic bootmaking capacity, with El Paso and Mercedes workshop clusters sustaining hand-last craftsmanship traditions against offshore automation. Raw material flows draw from Guanajuato tanneries in Mexico's Bajío Region and three concentrated US tanning operations supplying specialty western boot leather. Single-source dependencies in domestic tannery concentration expose brands to capacity constraints during EPA compliance transitions. Distribution runs through company-owned digital storefronts, specialty bootfitting retailers, and wholesale department store partnerships with divergent margin economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Western Boots Market is recovering from drought-driven hide quality volatility and regulatory compliance cost spikes, with normalized rainfall patterns and completed tannery retooling investments restoring supply stability.
For Market Incumbents: Compound defensive positioning through backward integration into compliant tannery operations and captive vegetable-tanning capacity, countering synthetic substitution threats in Gulf Coast work applications. Secure master bootmaker apprenticeship pipelines in El Paso and Mercedes heritage clusters to replenish aging hand-last craftsmanship capacity before workforce attrition accelerates. For New Entrants and Emerging Players: California Proposition 65 certification fast-track for chromium-free construction enables qualification with heritage brands seeking compliant supplier alternatives. Target urban coastal fashion adopters outside traditional ranch demographics through direct-to-consumer digital channels, leveraging stylized shaft embroidery and exotic leather options with lower technical performance requirements than rodeo or work specifications. For Investors and Strategic Acquirers: EPA effluent guideline implementation reshapes the acquisition landscape toward tanneries with completed closed-loop water recycling investments and heavy-metal capture systems. Mid-cap heritage brands with dual manufacturing capability—hand-last workshops plus automated lines—offer strongest long-term viability within a five-to-ten-year window. Monitor USDA leather traceability program enrollment rates as inflection indicator for raw-material access tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compliant Tanneries | Captive vegetable-tanning capacity secures preferential supplier status with heritage brands facing Prop 65 deadlines. |
| Direct-to-Consumer Channel Expansion | Company-owned digital storefronts bypass wholesale margin dilution and enable full-price realization in Texas and Oklahoma corridors. |
| Master Bootmaker Apprenticeship Programs | Structured training pipelines in El Paso and Mercedes replenish hand-stitched construction capacity before workforce aging accelerates. |
| Bio-Based Tanning Chemistry Investment | Early compliance with EPA effluent guidelines positions tanneries for premium brand qualification and avoids retroactive liability. |
| Fashion Segment Product Line Extension | Stylized embroidery and exotic leather options attract discretionary spending from urban coastal consumers outside ranch culture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA hide grading specifications, EPA tanning-effluent enforcement records, and tannery discharge compliance databases. Interviews with heritage brand production directors, El Paso workshop master bootmakers, domestic tannery operations managers, and specialty retail buyers informed supply-side dynamics. Bottom-up unit economics from product-type segmentation triangulate against top-down market sizing from customs trade data and channel shipment reports.
Segmentation dimensions modeled include product type, material grade, end-user demographic, and distribution channel across the analysis window. CAGRs derive from trend extrapolation of ASTM certification adoption rates, direct-to-consumer penetration curves in Texas and Oklahoma metropolitan corridors, and synthetic substitution trajectories in wet-climate work applications. Hide quality volatility indices and regulatory compliance cost curves inform scenario-weighted projections.
Decision-makers should treat outputs as directional under assumptions of stable EPA enforcement timelines and normalized drought cycles; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding tannery consolidation pace and hand-last craftsmanship replenishment rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Dance Shoes Market
Footwear
Waterproof Sneakers Market
Footwear
Barefoot Shoes Market
Footwear
Tennis Shoes Market
Footwear
Europe Footwear Market
Footwear
Running Shoes Market
Footwear
Womens Footwear Market
Footwear
Europe Athletic Footwear Market
Footwear
North America Footwear Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Global Footwear Market
Footwear
Orthopedic Footwear Market
Footwear
Sports Shoes Market
Footwear
PVC Footwear Market
Footwear
E-Commerce Footwear Market
Footwear
Football Shoes Market