
 Waterproof Shoe Covers Market | 2026-2036
Waterproof Shoe Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Shoe Covers Market Outlook
The gap between premium Tyvek covers and commodity polyethylene units is expanding across procurement channels. DuPont leverages its material science heritage to dominate the high-performance segment where chemical resistance commands price premiums. Medline Industries anchors hospital supply contracts through scale manufacturing of lightweight disposable covers. Cardinal Health competes on distribution density, sustaining shelf presence across integrated delivery networks.
Waterproof shoe covers are protective footwear accessories manufactured from synthetic polymers or rubber compounds, typically 1-5 mil in thickness, designed to prevent liquid penetration and cross-contamination in occupational environments. The primary commercial purpose spans infection control in clinical settings, jobsite moisture protection in construction, and chemical splash guarding in manufacturing plants. Polyethylene dominates volume due to single-use economics, while Tyvek captures margin pools where particulate and liquid barrier performance justifies unit cost premiums. Healthcare end users drive consistent baseline demand through standardized PPE protocols, whereas construction and manufacturing segments fluctuate with capital expenditure cycles and seasonal weather severity.
OSHA workplace PPE standards, FDA device classification for medical-grade barriers, and EPA chemical content restrictions collectively shape product specifications and market access thresholds in the United States. REACH substance restrictions in Europe are accelerating PVC displacement across export-oriented manufacturers. Stakeholders must monitor evolving biocompatibility testing requirements and regional chemical disclosure mandates to align portfolio positioning with procurement compliance timelines.
Market Dynamics
OSHA workplace safety enforcement is compressing procurement cycles for disposable polyethylene covers in US healthcare facilities, while REACH chemical restrictions in Europe are forcing PVC displacement across manufacturing supply chains. These dual regulatory pressures are restructuring competitive positioning between commodity and premium barrier technologies.
Growth Catalysts
- OSHA PPE Mandates:United States healthcare facilities face stepped-up workplace safety inspections, accelerating standardized procurement of liquid-impermeable footwear barriers for clinical staff.
- Heavy-Duty Industrial Mandates:Germany's manufacturing corridor now requires chemical-resistant protective accessories in chemical processing and electronics assembly environments.
- Tyvek Material Substitution:High-performance spunbonded olefin barriers are capturing specification share where particulate and liquid dual protection justifies unit cost premiums over polyethylene.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings directly compress margins on polyethylene and polypropylene cover production.
- REACH Compliance Costs:European chemical disclosure and substance restriction protocols add formulation testing burdens that disadvantage smaller compounders.
- Reusable Rubber Boot Substitution:Industrial laundries in manufacturing sectors promote washable neoprene alternatives that threaten single-use volume in non-critical applications.
Strategic Opportunities
- India Healthcare Infrastructure:Hospital accreditation standards under the country's national pharmaceutical regulator are creating first-time demand for standardized infection control PPE.
- CSRD-Driven Sustainability:European corporate sustainability reporting requirements favor suppliers offering certified recyclable or bio-based polymer alternatives to virgin polyethylene.
- E-Commerce Direct Procurement:Amazon Business and specialized medical supply platforms are disintermediating traditional distributor relationships for mid-size clinic chains.
Industry Challenges
- Biocompatibility Testing Timelines:FDA device classification requirements for medical-grade barriers extend product validation cycles by 12-18 months.
- Polymer Compounding Expertise Gap:Formulation chemists capable of balancing barrier performance with PVC-free compliance command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Shoe Covers Market |
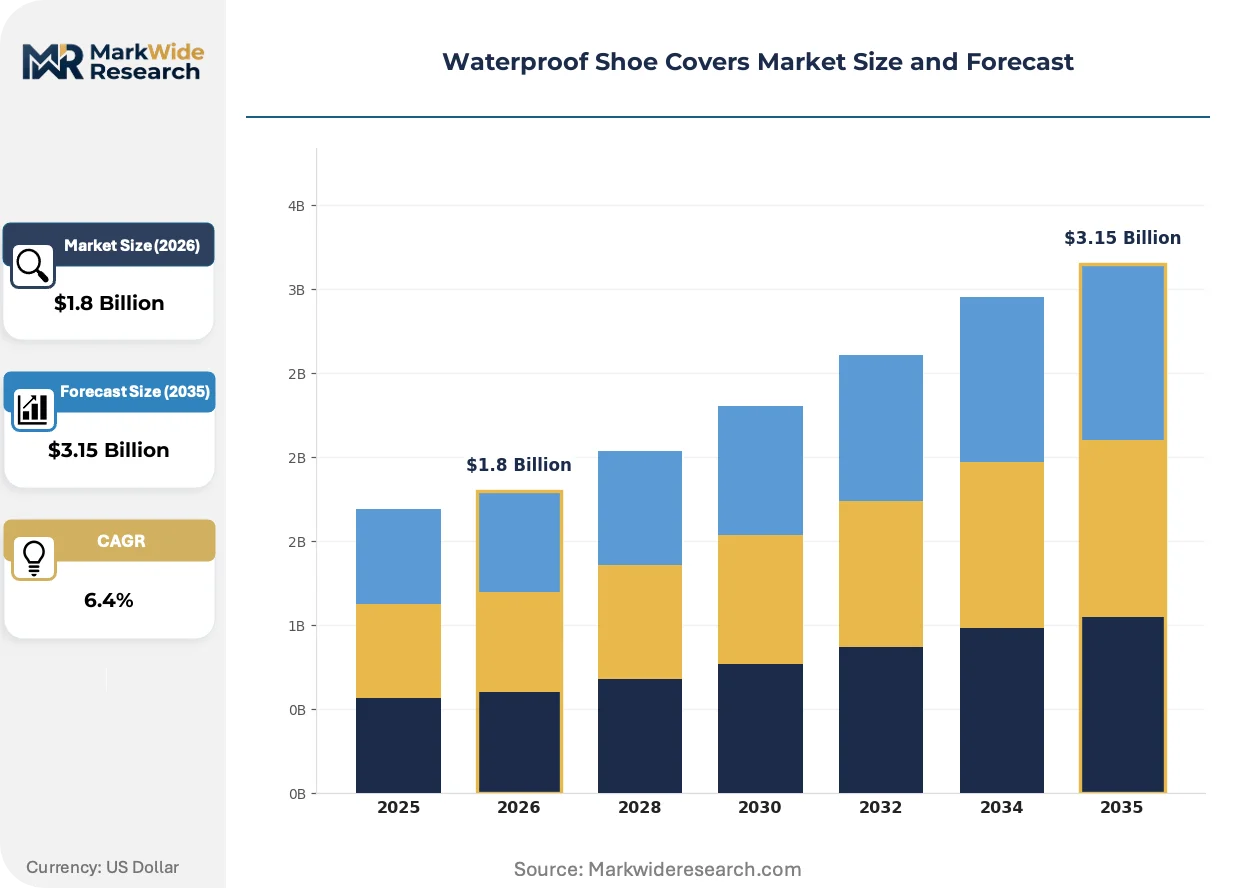
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, PVC, Tyvek, Rubber End User: Healthcare, Construction, Manufacturing, Household Thickness: Lightweight, Medium, Heavy Duty, Ultra-Thick Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Keystone Safety, Medline Industries, ProWorks, DuPont, Cardinal Health, Kimberly Clark, 3M, ShuBee, Pro Shoe Covers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Shoe Covers Market Strategic Shifts
Material science advances are compressing the performance gap between single-use disposables and limited-use durability, while regulatory chemical restrictions are accelerating formulation diversification beyond legacy polymer platforms.
Multilayer coextrusion technology is unifying liquid barrier and particulate filtration in single-film constructions. Hospital systems in the United States are specifying these hybrid constructions for isolation unit protocols. The technology is unifying previously separate premium and standard product tiers into consolidated procurement SKUs.
REACH substance restrictions on phthalate plasticizers and heavy metal stabilizers are forcing PVC displacement across European export-oriented manufacturers. Compounders are reformulating around thermoplastic elastomers and bio-based polyurethanes. Medical device distributors in Germany and France are prioritizing certified PVC-free inventory to preempt downstream compliance liability.
Integrated delivery networks are consolidating vendor relationships from multi-source to dual-source or sole-source contracts for standard PPE categories. Group purchasing organizations are centralizing specification authority that previously sat with individual facility materials managers. This concentration is most visible in United States hospital systems exceeding 50 facilities, where procurement standardization reduces SKU complexity and audit burden.
Waterproof Shoe Covers Market Segmentation
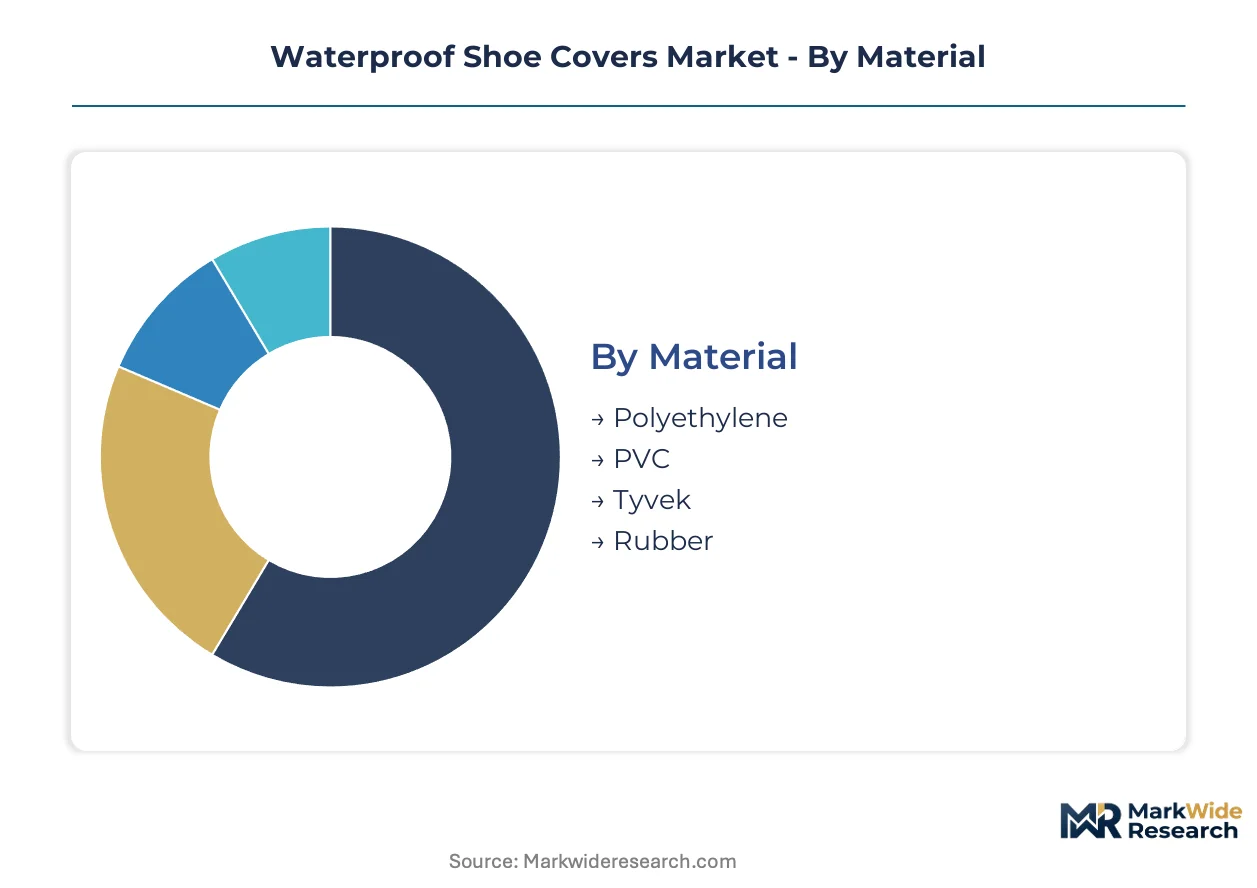
Material selection dictates barrier performance and cost economics across waterproof shoe cover procurement. End-use specifications diverge sharply between infection control protocols and industrial chemical exposure requirements.
Material:
Standardization dominates commodity polymer grades while premium spunbonded olefins command specification customization for dual-barrier applications.
- Polyethylene:Extruded low-density films 1-3 mil thick deliver single-use liquid protection at unit economics below five cents. Hospital systems in the United States specify polyethylene for general ward protocols where OSHA mandates liquid-impermeable footwear barriers without particulate filtration requirements.
- Tyvek:Spunbonded high-density polyethylene olefin fabric fuses particulate and liquid barrier in 4-7 mil constructions. Germany's chemical processing corridor specifies Tyvek for cleanroom environments where ECHA REACH substance restrictions have accelerated PVC displacement toward certified halogen-free alternatives.
- PVC:Plasticized polyvinyl chloride compounds 2-4 mil thick offer tactile grip and chemical resistance in heavy-duty applications. Formulation costs are climbing under European phthalate restriction protocols.
- Rubber:Natural and synthetic latex or neoprene constructions 5-8 mil thick deliver reusable durability for industrial laundries. Manufacturing plants in India's pharmaceutical zones are adopting rubber alternatives amid CDSCO biocompatibility testing requirements for device-grade barriers.
Leading the category by volume: Polyethylene. Expanding most quickly: Tyvek.
End User:
Procurement concentration varies from institutional contract scale to fragmented consumer purchasing patterns.
- Healthcare:Infection control protocols mandate liquid-impermeable footwear barriers across clinical zones. FDA device classification requirements for medical-grade barriers extend validation timelines for new material introductions.
- Manufacturing:Chemical splash and electrostatic discharge protection specifications dominate electronics assembly and pharmaceutical production environments. Germany's industrial corridor anchors European demand density.
- Construction:Seasonal moisture protection fluctuates with capital expenditure cycles and weather severity. Jobsite procurement favors disposable economics over reusable alternatives.
- Household:Consumer purchasing through e-commerce platforms concentrates in weather-event preparation and home renovation projects. Amazon Business channels are disintermediating traditional retail for mid-volume buyers.
Driving procurement scale: Healthcare. Gaining share fastest: Manufacturing.
Thickness:
Performance tiering aligns barrier durability with end-use criticality and cost tolerance.
- Lightweight:1-2 mil constructions serve single-shift clinical protocols where OSHA mandates liquid protection without structural stress. United States hospital GPOs centralize lightweight specifications across multi-facility contracts.
- Heavy Duty:4-5 mil films withstand extended chemical exposure and abrasive surfaces. REACH-compliant heavy-duty formulations are displacing legacy PVC in European export manufacturing.
- Medium:2.5-3.5 mil balances cost and durability for general industrial applications. Procurement standardization is compressing medium-thickness SKU variety.
- Ultra-Thick:6-8 mil constructions address extreme chemical immersion and reusable cleaning cycles. Niche demand concentrates in semiconductor fabrication and hazardous waste handling.
Capturing procurement volume: Lightweight. Climbing the fastest: Heavy Duty.
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and delivery velocity requirements.
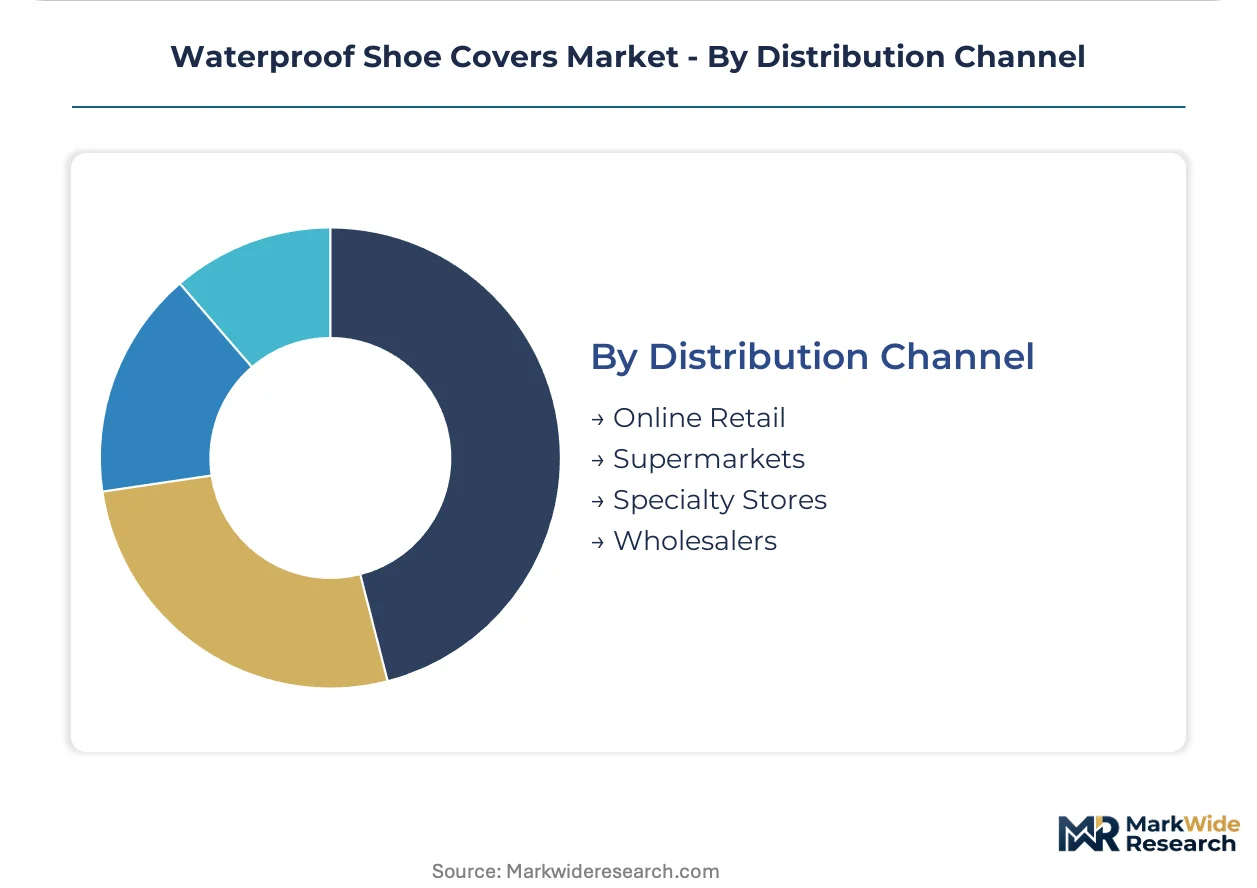
- Wholesalers:Medical supply distributors anchor hospital system contracts through integrated delivery network relationships. Cardinal Health and Medline Industries sustain shelf presence across GPO-negotiated agreements.
- Online Retail:Amazon Business and specialized medical platforms enable direct procurement for mid-size clinic chains. E-commerce is compressing distributor margins on standardized SKUs.
- Specialty Stores:Industrial safety suppliers serve manufacturing accounts requiring technical specification support. Germany's Rhine-Ruhr corridor concentrates specialty store density for chemical-resistant accessories.
- Supermarkets:Mass retail captures household and small contractor demand for commodity polyethylene covers. Seasonal merchandising drives volume spikes in weather-sensitive regions.
Holding procurement share: Wholesalers. Disrupting fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor concentrates heavy-duty waterproof shoe cover procurement for chemical processing and electronics assembly environments. Healthcare systems across multiple continents are standardizing infection control protocols. Regulatory divergence between OSHA enforcement in the United States and REACH chemical restrictions in Europe is fragmenting formulation strategies.
United States
OSHA workplace safety inspections are compressing procurement cycles for disposable polyethylene covers across hospital systems. FDA device classification requirements extend validation timelines for medical-grade barrier introductions. The Texas Medical Center in Houston anchors concentrated demand from multi-facility integrated delivery networks standardizing PPE protocols.
Germany
ECHA REACH substance restrictions on phthalate plasticizers are accelerating PVC displacement toward thermoplastic elastomer alternatives. The country's national pharmaceutical regulator enforces biocompatibility testing requirements for device-grade barriers. Bavaria's semiconductor fabrication clusters specify ultra-thick Tyvek constructions for cleanroom electrostatic discharge protection.
China
GB standards for medical device barriers are tightening polymer purity requirements for export-oriented manufacturers. The Ministry of Ecology and Environment enforces dual carbon goals that favor lightweight single-use designs over energy-intensive reusable alternatives. Yangtze River Delta contract manufacturers are consolidating compounding capacity to serve European REACH-compliant export orders.
India
CDSCO hospital accreditation standards under the national pharmaceutical regulator are creating first-time demand for standardized infection control PPE. The country's central bank liquidity provisions support healthcare infrastructure expansion in tier-2 cities. Maharashtra's pharmaceutical manufacturing zones in Mumbai-Pune corridor are adopting heavy-duty rubber alternatives for chemical splash protection.
Japan
METI industrial safety guidelines mandate liquid-impermeable footwear barriers in electronics assembly environments. PMDA medical device quality management systems extend certification timelines for new material introductions. Kansai's Osaka-Kyoto manufacturing belt concentrates demand for particulate-liquid dual barrier specifications in precision component fabrication.
Waterproof Shoe Covers Market Competitive Environment
Premium-margin players sit above commodity-margin players across material science capability and barrier performance certification. The vendor base stratifies between spunbonded olefin specialists, scale polyethylene fabricators, and diversified health supply distributors. Three archetypes dominate: material science heritage firms commanding specification authority, scale manufacturers anchoring hospital GPO contracts, and distribution-heavy players sustaining shelf presence through integrated delivery network density. Competitive moves concentrate on portfolio diversification beyond legacy polymer platforms and backward integration into compounding operations.
Within the material science tier, DuPont represents heritage capability in spunbonded olefin barriers. Among scale-driven manufacturers, Medline Industries and Cardinal Health exemplify divergent strategies—one anchoring production volume, the other distribution density. Keystone Safety occupies a position bridging industrial safety specialization with healthcare crossover applications.
| Leading Market Players |
|---|
| Keystone Safety |
| Medline Industries |
| ProWorks |
| DuPont |
| Cardinal Health |
| Kimberly Clark |
| 3M |
| ShuBee |
| Pro Shoe Covers |
| Others |
Value Chain & Pricing Dynamics
Captive compounding operations in Germany's industrial corridor anchor both supply security and pricing power for REACH-compliant heavy-duty formulations. This backward integration into polymer formulation insulates premium-tier producers from ethylene price volatility while compressing margins for non-integrated commodity polyethylene fabricators.
Pricing Analysis
Outcome-based pricing tied to infection control compliance anchors hospital procurement contracts, with Tyvek constructions commanding unit cost premiums over polyethylene where dual barrier performance prevents cross-contamination events. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in lightweight polyethylene runs through distributor disintermediation by Amazon Business channels. Small clinic chains exhibit highest price sensitivity, while integrated delivery networks prioritize specification standardization over unit economics.
Supply Chain Analysis
Ethylene feedstock supply rests on Gulf Coast petrochemical complexes in the United States, integrated European crackers in Germany and the Netherlands, and naphtha-based production in Japan. Specialty spunbonded olefin production draws from DuPont's Richmond, Virginia and Luxembourg manufacturing assets. Single-source vulnerability concentrates in phthalate-free plasticizer formulations for PVC alternatives. Distribution runs through medical supply wholesalers anchoring hospital GPO contracts, with e-commerce platforms eroding traditional channel margins on standardized SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH substance restrictions erect barrier-to-entry moats favoring compounders with certified PVC-free portfolios and validated biocompatibility testing capabilities.
For Market Incumbents: Deploy formulation R&D investment to preempt regulatory displacement of legacy polymer platforms. Consolidate vendor relationships with hospital GPOs from multi-source to sole-source contracts before e-commerce platforms capture mid-size clinic procurement. Rubber boot substitution by industrial laundries threatens single-use volume in manufacturing segments.
For New Entrants and Emerging Players: Launch via direct-to-clinic e-commerce platforms targeting India's tier-2 hospital accreditation surge under CDSCO standards. White-space concentrates in bio-based polyurethane formulations for European CSRD-driven sustainability procurement. Avoid competing head-to-head with integrated distributors on polyethylene commodity SKUs.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified health supply distributors seeking compounding capability in-house. Long-term viability favors compounders with validated REACH-compliant portfolios and hospital system contract density. Watch FDA device classification timeline extensions as inflection indicator for new material introduction velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding | Captive formulation capability insulates margins from ethylene volatility and REACH compliance costs. |
| Hospital GPO Contract Consolidation | Sole-source agreements with integrated delivery networks reduce SKU complexity and audit burden across multi-facility systems. |
| Bio-Based Polyurethane Development | CSRD-driven sustainability requirements in Europe favor certified recyclable alternatives to virgin polyethylene. |
| E-Commerce Direct Procurement Launch | Amazon Business channels disintermediate traditional distributors for mid-size clinic chains on standardized SKUs. |
| India Healthcare Infrastructure Expansion | CDSCO hospital accreditation standards create first-time demand for standardized infection control PPE in tier-2 cities. |
Study Parameters
Multi-period observation of OSHA enforcement intensity, REACH substance restriction timelines, and hospital procurement standardization anchored the trend analysis, supplemented by interviews with GPO contracts managers, biomedical engineers, polymer formulation chemists, and industrial safety procurement leads. Secondary validation drew from FDA device classification databases, ECHA substance restriction notifications, hospital procurement contract disclosures, and customs trade data for polymer imports. Bottom-up facility-level demand estimation triangulated against top-down market sizing from producer capacity assessments.
Input-output matrices modeled polyethylene and Tyvek volume flows across material grade, end-use sector, thickness tier, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure and industrial capital formation indicators. Forecast inputs incorporated OSHA inspection frequency projections and ECHA substance restriction phase-out schedules.
Regulatory enforcement intensity shifts, petrochemical feedstock price dislocations, and hospital system merger activity are the dominant revision risks to demand assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Cooking Gloves Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Diving Suits Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Dust Covers Market
Protective Gear
Military Boots Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Tactical Boots Market
Protective Gear
Combat Boots Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Work Boots Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Earplug Distributor Market
Protective Gear
Work Shoes Market