
 Safety Shoes Market | 2026-2036
Safety Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Shoes Market Analysis
Asian manufacturing clusters for safety footwear is shifting toward composite material platforms and automated lasting lines. VF Corporation leverages its workwear heritage to sustain premium positioning across North American distribution channels. Bata Corporation anchors emerging market volume through localized production networks in Africa and Latin America. Honeywell International competes on integrated PPE system sales rather than standalone footwear, bundling respiratory and foot protection for industrial accounts.
Safety shoes are protective footwear engineered with reinforced toe caps, puncture-resistant midsoles, and slip-resistant outsoles to shield workers from impact, compression, and electrical hazards in occupational environments; ASTM F2413 and ISO 20345 specify minimum impact resistance and compression performance thresholds that manufacturers must validate through third-party certification. Leather construction dominates premium tiers due to durability and heat resistance, while breathable fabrics represent the fastest-growing material segment as warehouse and logistics employers prioritize all-shift comfort to reduce fatigue-related incidents. Composite toe configurations are displacing steel in aviation and electrical utility applications where metal-free zones are mandatory, concentrating margin pools in specialized certification tiers rather than commodity steel-toe volumes.
OSHA's general industry standards in the United States and the EU's PPE Regulation enforce minimum protective specifications that employers must satisfy, creating non-negotiable replacement demand rather than discretionary purchasing. India's BIS certification requirements for industrial safety footwear are tightening import compliance burdens for offshore suppliers seeking access to infrastructure and manufacturing plant procurement channels. Stakeholders must monitor evolving composite material certifications and regional testing mutual recognition agreements to anticipate which production bases will retain cost-competitive access into regulated end markets.
Market Dynamics
Composite toe technology is restructuring procurement priorities across aviation, electrical utilities, and manufacturing, forcing manufacturers to retool certification pipelines while buyers abandon steel-toe legacy specifications.
Growth Catalysts
- EU PPE Regulation:Mandatory employer compliance drives non-discretionary replacement cycles across German, French, and Italian industrial clusters.
- Construction sector safety mandates:Site-specific protocols in the United States and Germany intensify certified footwear procurement for infrastructure projects.
- Composite material platforms:Automated lasting lines in Asian manufacturing bases reduce unit costs while meeting ASTM F2413 and ISO 20345 thresholds.
Market Restraints
- Leather input volatility:Premium tier margins compress when hide prices spike, squeezing manufacturers dependent on full-grain construction.
- Supply concentration in Southeast Asia:Vietnam and Indonesia dominate mid-sole injection molding, creating single-source vulnerability for Western brands.
- BIS certification friction:India's tightened import testing protocols delay market access for offshore suppliers targeting infrastructure procurement channels.
Strategic Opportunities
- Underpenetrated African markets:Localized production networks in Nigeria and Kenya bypass import duties while serving mining and oil sector demand.
- Warehouse logistics comfort specifications:Breathable fabric uppers address all-shift fatigue reduction mandates from e-commerce fulfillment operators.
- Integrated PPE bundling:Respiratory-foot protection system sales capture industrial accounts seeking consolidated vendor relationships.
Industry Challenges
- Composite certification timelines:Third-party validation for non-metallic toe caps extends product development cycles by 4-8 months.
- Legacy steel-toe inventory obsolescence:Aviation and electrical utility metal-free zone mandates strand existing stock in affected segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Shoes Market |
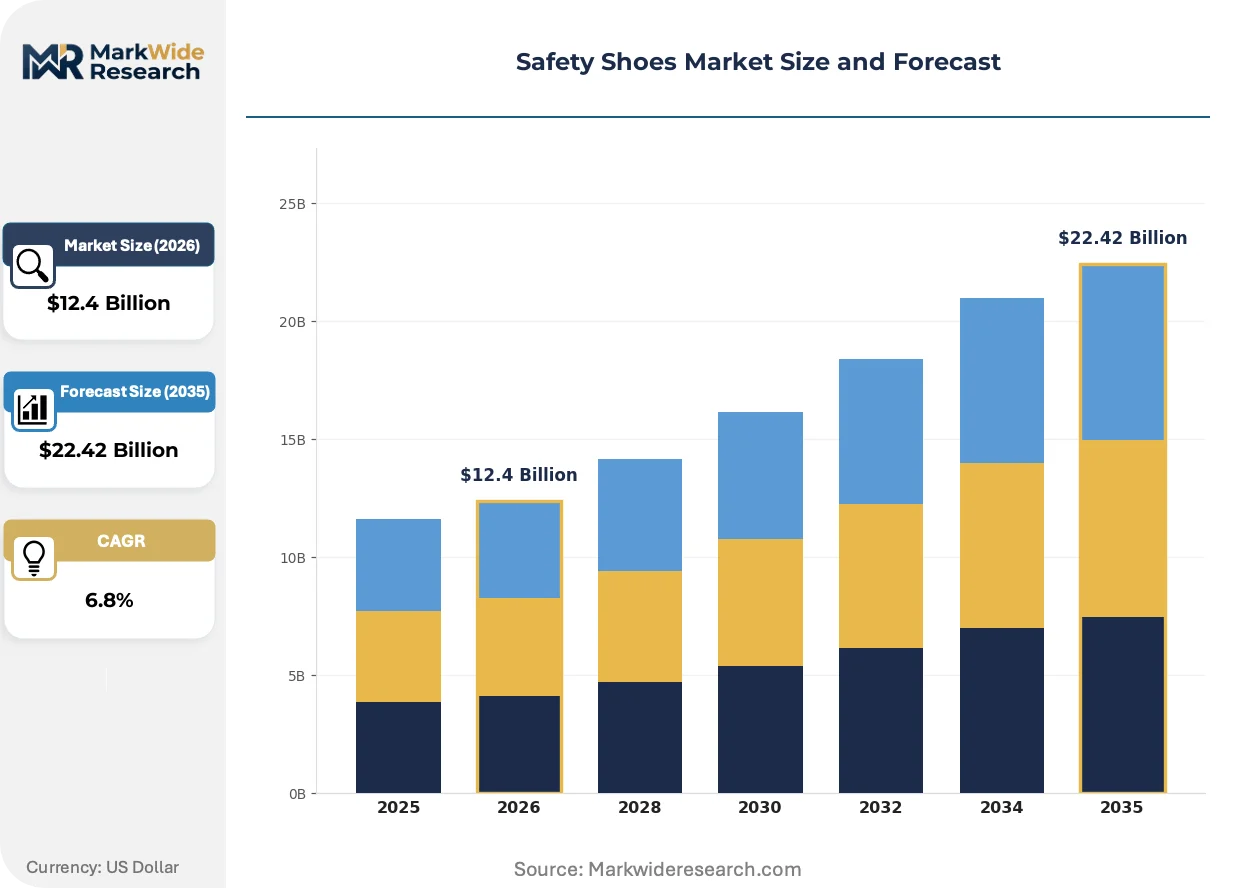
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Toe, Composite Toe, Soft Toe, Electrostatic Discharge End User: Construction, Manufacturing, Healthcare, Oil & Gas Material: Leather, Rubber, Synthetic, Breathable Fabrics Feature: Waterproof, Slip Resistant, Lightweight, Insulated |
| Companies Covered | UVEX Safety Group, VF Corporation, Bata Corporation, Red Wing Shoe Company, ELTEN GmbH, Wolverine World Wide, ATLAS, Giasco, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Shoes Market Emerging Trajectories
Material substitution and regulatory harmonization are compressing traditional product lifecycles while reshaping how safety footwear is specified, certified, and procured across occupational verticals.
Carbon-fiber and fiberglass toe caps are overtaking steel configurations in weight-critical and metal-detector environments. Aviation ground crews and electrical linemen now specify composite protection exclusively. ASTM F2413-18 updates accommodate these materials, enabling certification parity that steel-toe incumbents struggle to match on comfort metrics.
REACH substance restrictions in Europe are phasing out chromium-tanned leather processing chemicals. German tanneries face reformulation costs while Portuguese and Spanish suppliers gain share with vegetable-tan alternatives. Footwear brands serving EU public procurement must trace chemical inputs through tier-three suppliers.
Direct specification by safety officers is replacing distributor-mediated purchasing in North American manufacturing plants. Large automotive and chemical employers now mandate brand-specific models rather than accepting distributor substitutions. This shift concentrates volume with manufacturers maintaining dedicated industrial sales engineering teams.
Safety Shoes Market Segmentation
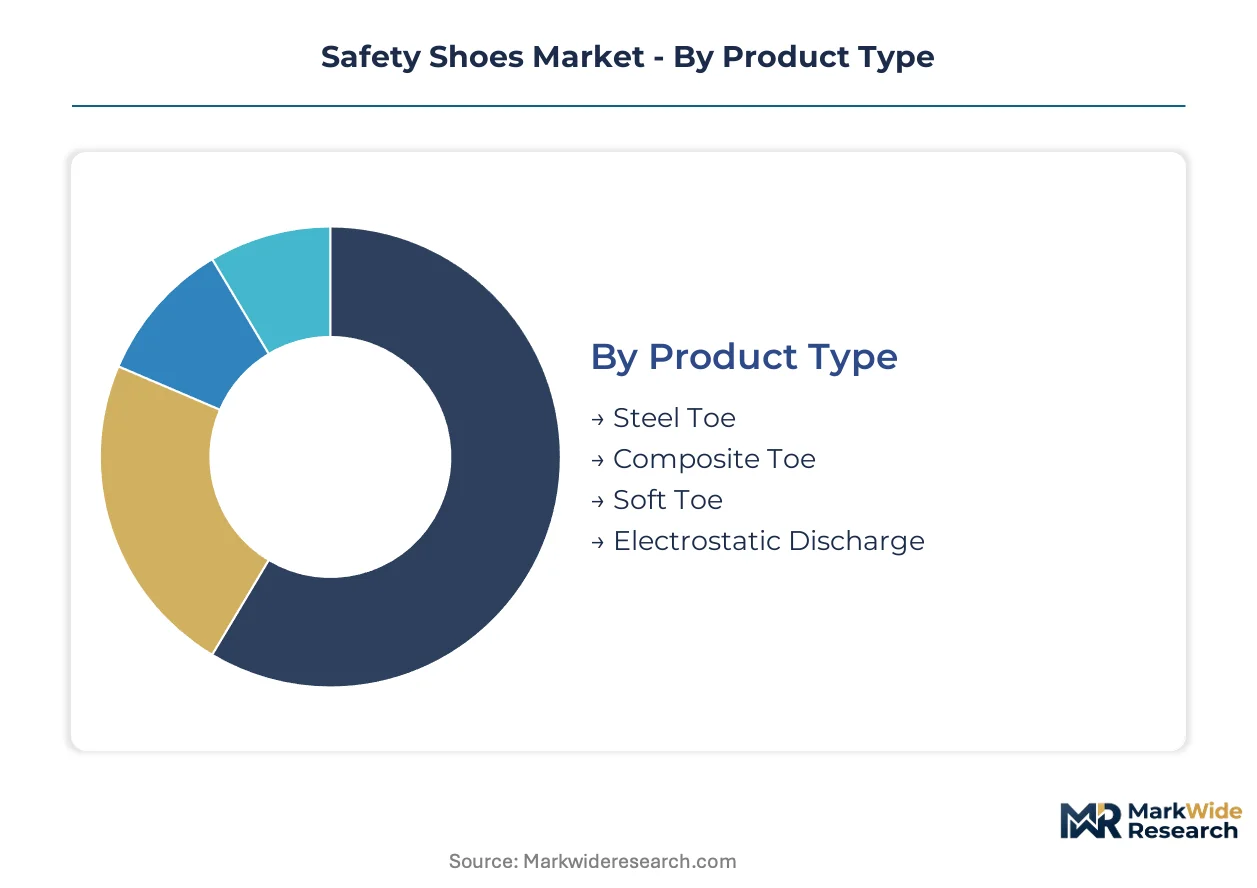
Segmentation in safety footwear reveals how procurement specifications diverge across hazard types, workplace environments, and regulatory jurisdictions. Buyers prioritize toe protection technology and material compliance over brand preference, creating tiered demand pools that manufacturers must address through distinct certification pipelines.
Product Type:
Employers specify toe protection based on metal-detector requirements, electrical hazard exposure, and weight tolerance thresholds rather than cost alone.
- Composite Toe:Carbon-fiber and fiberglass-reinforced caps deliver impact resistance without conductive properties. Aviation ground crews at Hartsfield-Jackson Atlanta and electrical linemen across Texas utilities now mandate this specification exclusively to satisfy metal-free zone protocols.
- Steel Toe:Traditional reinforced steel caps remain dominant in heavy manufacturing and warehousing where metal detectors are absent. German automotive plants and U.S. distribution centers specify this configuration for maximum compression resistance at lowest unit cost.
- Soft Toe:Unreinforced protective footwear serves warehouse logistics and light assembly where impact hazards are minimal but slip resistance remains mandatory.
- Electrostatic Discharge:Conductive sole assemblies dissipate static buildup for electronics manufacturing cleanrooms and semiconductor fabrication facilities in South Korea and Taiwan.
Volume sits with steel toe configurations; growth tilts toward composite toe as aviation and utility sectors complete specification transitions.
End User:
Sector-specific hazard profiles dictate certification grade, replacement frequency, and bundling potential with adjacent PPE categories.
- Construction:OSHA-compliant sites in the United States and Germany's BauBG-mandated projects drive bulk procurement of puncture-resistant midsoles and ankle support features.
- Manufacturing:Automotive and chemical plants specify brand-direct models through safety engineering channels rather than distributor substitutions, concentrating volume with manufacturers maintaining dedicated industrial sales teams.
- Healthcare:Slip-resistant outsoles and fluid-resistant uppers address hospital and long-term care facility protocols where fall prevention intersects with infection control.
- Oil & Gas:Extraction platforms and refineries demand metatarsal guards and flame-resistant materials certified to ASTM F2413-18 electrical hazard specifications.
Construction commands the largest procurement volumes; manufacturing exhibits the steepest expansion trajectory as reshoring intensifies plant safety investments.
Material:
Raw material selection determines heat resistance, break-in period, and compliance with REACH substance restrictions in European procurement channels.
- Leather:Full-grain hides dominate premium tiers for welding and foundry applications where heat resistance is non-negotiable. Portuguese and Spanish tanneries gain share as German suppliers face chromium-tanning reformulation costs under REACH.
- Breathable Fabrics:Mesh and knit uppers address all-shift comfort mandates from e-commerce fulfillment operators in Poland and the Netherlands.
- Rubber:Injection-molded compounds serve chemical processing and food service environments requiring complete fluid impermeability.
- Synthetic:Polyurethane and thermoplastic constructions reduce unit weight for logistics workers covering extended warehouse footprints.
Leather retains margin concentration; breathable fabrics are climbing the fastest as warehouse automation expands shift durations.
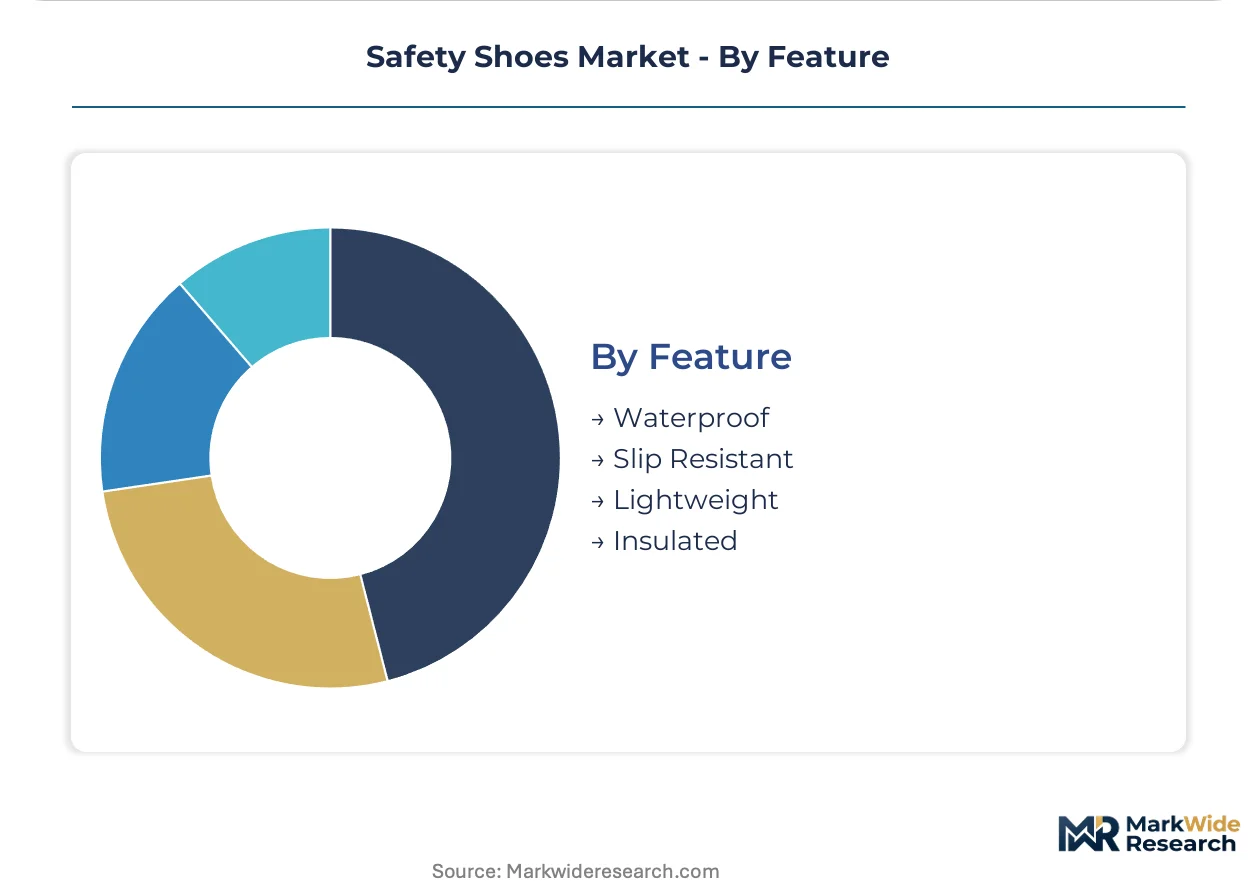
Feature:
Performance attributes increasingly determine specification compliance rather than serving as discretionary upgrades.
- Slip Resistant:SRA/SRB/SRC-rated outsoles satisfy regulatory minimums across EU member states and reduce workers' compensation exposure for U.S. employers.
- Waterproof:Membrane-lined constructions serve outdoor utilities and municipal workers in climates with extended precipitation seasons.
- Lightweight:Midsole density reductions address fatigue-related incident prevention in high-step-count environments.
- Insulated:Thinsulate and comparable thermal barriers protect cold-storage workers and northern climate construction crews.
Slip resistance anchors baseline procurement; lightweight specifications gain share fastest as fatigue science influences safety officer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hide sourcing from Italian and Spanish tanneries anchors European premium production, while Vietnamese injection-molding clusters supply mid-sole components across multiple continents. Regional demand patterns diverge sharply between mature regulatory environments with mandated replacement cycles and emerging markets where infrastructure build-out drives first-time procurement.
United States
Construction sector wage growth and OSHA enforcement intensification drive certified footwear procurement at scale. The Department of Labor's site inspection protocols compel employers to maintain ASTM F2413-compliant inventory. Texas utility corridors and Georgia distribution hubs concentrate demand for composite-toe specifications serving electrical and logistics verticals.
Germany
Union-negotiated safety protocols in automotive and chemical plants sustain shorter replacement cycles than European peers. REACH substance restrictions phase out chromium-tanned leather, forcing reformulation investments by domestic tanneries. Bavarian industrial clusters and North Rhine-Westphalia manufacturing belts specify brand-direct procurement through safety engineering channels.
India
Infrastructure project acceleration and manufacturing plant expansion create first-time protective footwear demand across industrial zones. BIS certification requirements for safety footwear tighten import compliance, privileging domestic producers in government procurement channels. Maharashtra and Gujarat manufacturing corridors concentrate bulk orders from automotive and pharmaceutical employers.
China
Domestic production capacity expansion serves both internal demand and export markets, with automated lasting lines reducing unit costs for composite material platforms. GB standards alignment with ISO 20345 facilitates mutual recognition in target export jurisdictions. Yangtze River Delta manufacturing bases supply Western brands seeking cost-competitive certification-grade output.
Brazil
Mining sector investment and oil platform maintenance activity drive puncture-resistant and metatarsal-guard specifications. ANVISA industrial safety protocols influence employer procurement standards, though enforcement varies by state. São Paulo state manufacturing plants and Minas Gerais mining belts represent the primary demand concentrations.
Safety Shoes Market Vendor Landscape
Global majors compete with regional champions across certification pipelines and distribution reach, producing a tiered structure where scale-driven players bundle adjacent PPE categories while specialists defend margin in single-vertical applications. Three archetypes dominate: integrated safety conglomerates selling respiratory-foot protection systems, heritage workwear brands leveraging distribution depth, and regional fabricators capturing localized public procurement through tariff-advantaged production. Competitive moves concentrate on certification pipeline expansion for composite materials and strategic partnerships with industrial safety officers bypassing traditional distributor channels.
Within the integrated conglomerate tier, Honeywell International and VF Corporation exemplify divergent bundling strategies, with the former anchoring system sales to industrial accounts and the latter sustaining premium positioning through workwear heritage. Among European specialists, UVEX Safety Group and ELTEN GmbH occupy positions defined by regional certification expertise and proximity to German industrial clusters. Bata Corporation represents the emerging-market archetype, with localized production networks enabling duty-free access across African and Latin American procurement channels.
| Leading Market Players |
|---|
| UVEX Safety Group |
| VF Corporation |
| Bata Corporation |
| Red Wing Shoe Company |
| ELTEN GmbH |
| Wolverine World Wide |
| ATLAS |
| Giasco |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of composite toe cap components anchors both supply security and margin retention for manufacturers retooling from steel legacy lines. This integration choice insulates premium tier producers from Vietnamese mid-sole injection molding bottlenecks while concentrating pricing power with brands controlling ASTM F2413 certification pipelines.
Pricing Analysis
Extended replacement warranty bundling separates premium safety footwear from unbundled economy tiers in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Cost compression in economy steel-toe segments is intensifying because Asian automated lasting lines erode legacy manufacturing cost advantages. Price-sensitive construction contractors in emerging markets drive volume at lowest certification tiers while German automotive plants absorb premium pricing for REACH-compliant leather specifications.
Supply Chain Analysis
Workforce availability constraints in Vietnamese and Indonesian injection-molding clusters are elevating wage pressure across mid-sole component sourcing. Geographic supply concentration centers on Vietnam, Indonesia, and China for molded components, with Portuguese and Spanish tanneries feeding European premium leather demand. Raw material dependencies draw from petroleum-derived polyurethane compounds, chrome-tanned hides, and carbon-fiber composite feedstocks. Single-source vulnerability in Vietnamese mid-sole production creates exposure for Western brands lacking alternative tooling partnerships. Distribution runs through industrial safety distributors in North America and direct specification channels in German manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite material certification bottlenecks constrain qualified supplier expansion, propping pricing power for incumbents with validated ASTM F2413-18 pipelines. This supply scarcity rewards early certification investments while penalizing steel-toe legacy inventory.
For Market Incumbents: Extend composite toe certification coverage into aviation and electrical utility verticals before specification transitions complete. Defensive consolidation of Portuguese tannery partnerships secures REACH-compliant leather supply as German suppliers face reformulation costs. Capacity addition in Vietnamese injection-molding clusters mitigates single-source vulnerability threatening margin stability. For New Entrants and Emerging Players: Begin with warehouse logistics breathable fabric specifications where e-commerce fulfillment operators prioritize all-shift comfort over legacy brand recognition. Underpenetrated African mining corridors offer white-space access through localized Nigerian or Kenyan production networks bypassing import duty structures. Direct safety officer engagement in North American automotive plants bypasses distributor substitution risks. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated PPE bundling plays where respiratory-foot protection system sales command industrial account consolidation premiums. Long-term viability favors manufacturers with captive composite material certification pipelines and dedicated industrial sales engineering teams. Watch for BIS certification mutual recognition agreements as inflection signals for Indian market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Certification Pipeline Expansion | ASTM F2413-18 validation enables aviation and utility specification capture before steel obsolescence. |
| Localized African Production Network | Nigerian and Kenyan facilities bypass import duties serving mining and oil sector procurement. |
| REACH-Compliant Leather Supply Partnership | Portuguese and Spanish tannery alliances secure EU public procurement channel access. |
| Direct Safety Officer Specification Channel | Bypassing distributor substitution concentrates volume with dedicated industrial sales teams. |
| Integrated PPE System Bundling | Respiratory-foot protection combinations capture consolidated vendor relationships in chemical plants. |
Methodological Framework
Multi-period observation of OSHA enforcement intensity, EU PPE Regulation amendment trajectories, and composite material certification timelines anchored the trend analysis, supplemented by interviews with plant safety officers, industrial procurement managers, certification laboratory directors, and distributor channel heads. Secondary validation drew from OSHA inspection data, EU Official Journal regulatory filings, ASTM standards documentation, and customs trade records. Bottom-up procurement volume estimates triangulated against top-down market sizing across the analysis window.
Segment-weighting approaches modeled product type, end-use vertical, material composition, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from replacement cycle frequency analysis, infrastructure project pipeline tracking, and specification transition velocity in aviation and electrical utility sectors. Forecast inputs incorporated BIS certification timeline assumptions and REACH substance restriction phase-in schedules.
Underlying measurement precision varies by segment; composite toe and breathable fabric categories carry tighter precision than legacy steel-toe volumes due to specification transition uncertainty. Forecasts reflect assumptions regarding regulatory enforcement consistency and certification mutual recognition progress. Material deviation in OSHA budget allocation, EU PPE Regulation amendment scope, or BIS testing protocol reciprocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Hand Gloves Market
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Waterproof Boots Market
Protective Gear
Combat Boots Market
Protective Gear
Work Shoes Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Cooking Gloves Market
Protective Gear
Diving Suits Market
Protective Gear
Waterproof Cases Market
Protective Gear
Equestrian Helmets Market