
 France Hospitality Market | 2026-2036
France Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
France Hospitality Market Insights
France's Atout France classification system is bifurcating competitive access, as only properties meeting rigorous star-rating and service benchmarks qualify for national tourism promotion and corporate contract eligibility. Accor leverages its multi-brand architecture to span luxury through economy tiers across Paris, Lyon, and Marseille. Louvre Hotels Group anchors mid-scale density in secondary cities, while B&B Hotels competes on standardized, cost-controlled formats in roadside and suburban locations.
France hospitality encompasses lodging, food service, event coordination, and travel facilitation delivered through fixed and itinerant establishments, with operational parameters governed by star-rating criteria covering room size, amenity minimums, and service frequency. Accommodation and food and beverage segments generate the dominant revenue pools, though event management captures disproportionate margins in Paris and Cannes. Budget and economy tiers face saturation in major urban corridors, while luxury properties in coastal and alpine destinations sustain pricing power through constrained supply.
ANSM enforces hygiene and safety protocols across food service operations, while CNIL mandates data handling standards for guest information systems, and Atout France's classification framework directly conditions distribution platform visibility and public procurement eligibility. The EU Green Deal's building performance standards will require energy retrofit investments across aging urban hotel stock. Stakeholders must weigh renovation timelines against evolving corporate travel policies and leisure booking platform commission structures.
Market Dynamics
The EU Green Deal's building performance standards are forcing wholesale renovation of France's aging urban hotel stock, while Atout France's classification tightening bifurcates promotional access and corporate contract eligibility.
Growth Catalysts
- EU Green Deal retrofit mandates:Building renovation requirements create mandatory upgrade cycles that refresh supply quality and enable premium repositioning across Paris, Lyon, and Marseille.
- Corporate travel policy recalibration:Post-pandemic procurement teams prioritize properties with verified sustainability credentials and flexible cancellation terms.
- Secondary city infrastructure investment:Regional rail connectivity improvements unlock compressed-stay demand in Bordeaux, Toulouse, and Nantes.
Market Restraints
- Energy retrofit capex burden:Aging Haussmann-era building stock in Paris requires structural reinforcement alongside thermal upgrades, stretching payback timelines.
- Labor cost rigidity:France's SMIC minimum wage indexation and 35-hour week conventions compress operating leverage in service-intensive luxury formats.
- Platform commission compression:Booking.com and Expedia take rates of 15-25 percent erode net operating income across independent properties.
Strategic Opportunities
- Alpine and coastal supply constraints:Strict zoning in Courchevel, Saint-Tropez, and Biarritz protects pricing power for properties securing development permits.
- Hybrid hospitality formats:Co-living and extended-stay concepts capture bleisure demand from remote workers seeking 7-14 day stays.
- ANSM-certified wellness integration:Spa and thalassotherapy properties leveraging thermal mineral water certifications access medical tourism reimbursement flows.
Industry Challenges
- Digital talent scarcity:Revenue management and guest data analytics roles compete with tech sector compensation, leaving mid-scale properties under-resourced.
- Classification compliance timelines:Atout France's 2024 service-frequency audits demand front-desk staffing adjustments that conflict with automated check-in investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Hospitality Market |
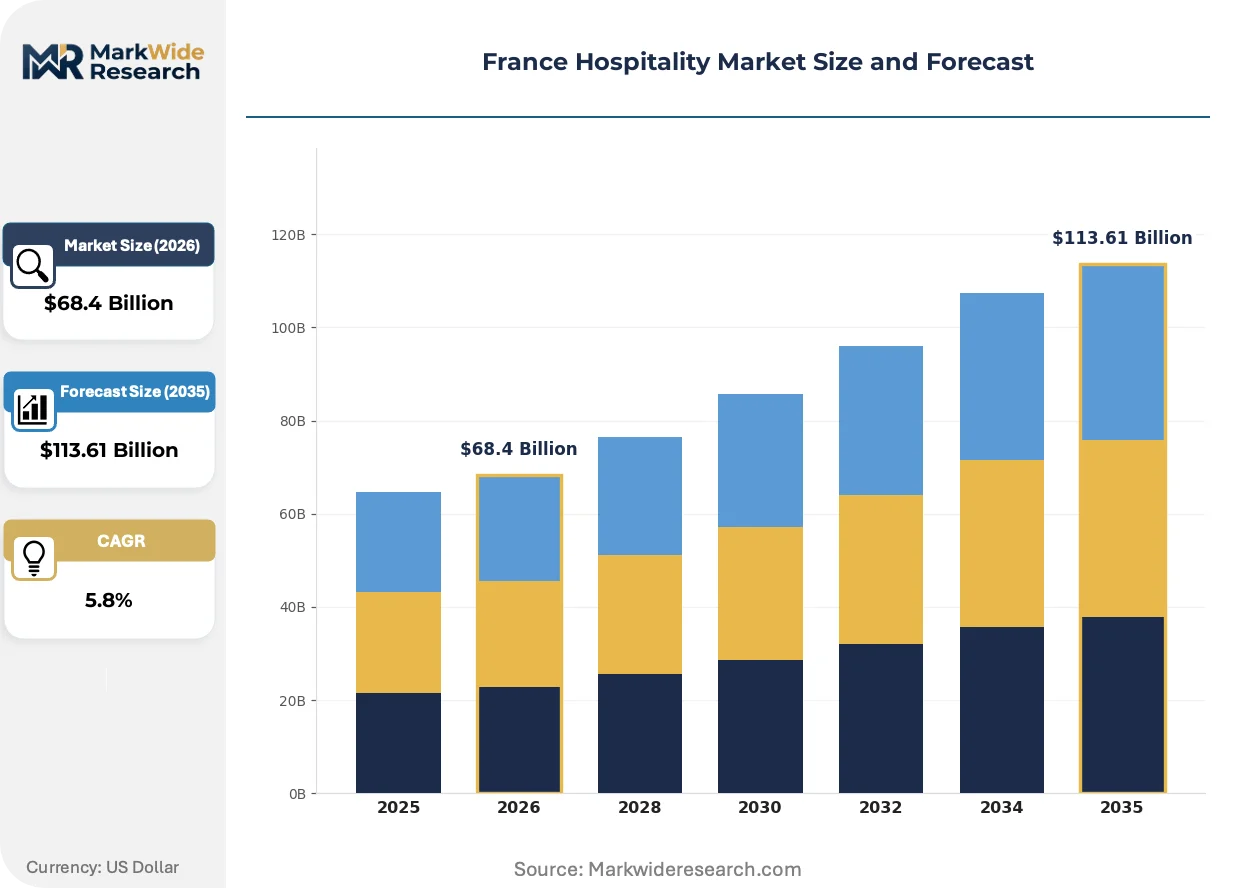
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food & Beverage, Accommodation, Event Management, Travel Services Customer Type: Business Travelers, Leisure Guests, Groups, Families Price Tier: Luxury, Mid-Scale, Budget, Economy End User: Corporates, Tourists, Residents, Event Organizers |
| Companies Covered | Accor, Louvre Hotels Group, B&B Hotels, Marriott International, IHG Hotels & Resorts, Best Western Hotels & Resorts, Brit Hotel, Hilton Worldwide, Logis Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Hospitality Market Trends and Innovations
Property management systems and guest-facing digital interfaces are displacing legacy operational workflows, while regulatory pressure on building performance intersects with shifting corporate procurement criteria.
Contactless mobile check-in and digital key distribution is displacing front-desk staffing models in mid-scale and economy properties. Accor and Louvre Hotels Group are deploying these systems across 60 percent of new openings. Labor cost savings are compressing breakeven occupancy thresholds by 8-12 points in standardized formats.
EU Green Deal building performance standards mandate energy consumption reductions of 55 percent by 2030 for commercial properties. France's Direction Générale des Entreprises enforces compliance timelines through tax penalty mechanisms. Urban properties in Paris and Lyon face the steepest retrofit curves, with many triggering full closure-reconstruction cycles.
Bleisure booking patterns now blend corporate rate negotiation with leisure extension flexibility. Procurement teams at pharmaceutical and consulting firms prioritize properties offering weekend rate holds and family room availability. This hybrid demand concentrates in Marseille, Nice, and Strasbourg where conference infrastructure overlaps with cultural tourism assets.
France Hospitality Market Segmentation
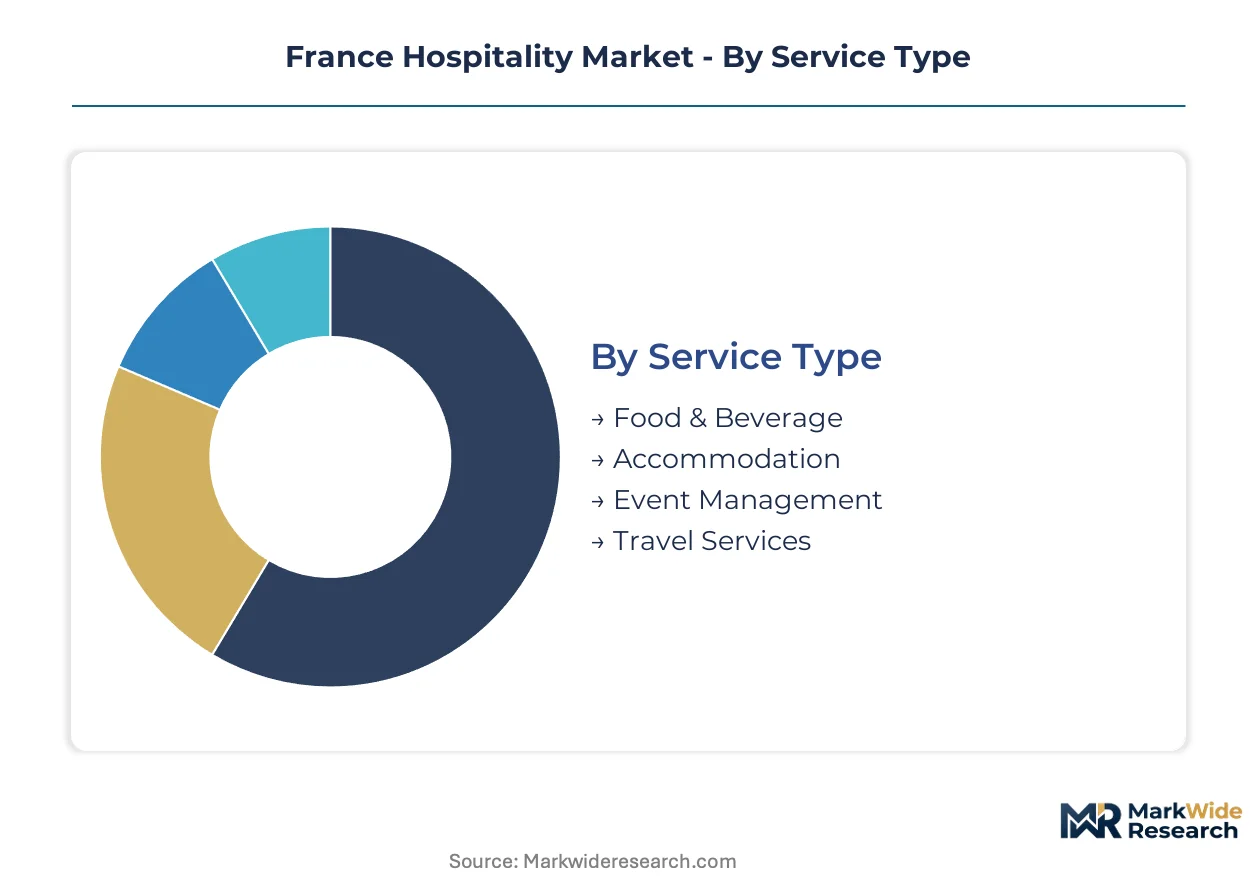
Segmentation in the France hospitality market reveals how margin pools concentrate across service formats and customer profiles. Atout France's classification framework directly ties star ratings to promotional access, making segment positioning a regulatory as well as commercial decision.
Service Type:
Margin concentration follows the fixed-asset intensity of each service format, with owned real estate and long-term leases creating divergent return profiles.
- Accommodation:Room revenue generates the dominant share of hospitality value pools, with Paris and French Riviera properties commanding premium rates through constrained supply. ANSM hygiene protocols and CNIL data handling mandates add compliance layers that favor scaled operators over independents.
- Food & Beverage:On-premise dining and banquet operations capture ancillary spend from accommodation guests while serving walk-in demand in urban centers. Labor cost rigidity under France's SMIC indexation compresses margins in full-service formats, driving automation investment in mid-scale properties.
- Event Management:Conference and wedding coordination in Paris, Cannes, and Lyon delivers disproportionate margins through bundled catering and room-block negotiations.
- Travel Services:Itinerary planning and concierge functions increasingly integrate with digital platforms, eroding standalone agency economics.
Accommodation holds installed capacity. Event Management is rotating up the share rankings.
Customer Type:
Volume distribution across customer categories reflects post-pandemic shifts in corporate travel policy and leisure booking behavior.
- Leisure Guests:Individual and couple travelers drive weekend demand in Paris, Bordeaux, and coastal destinations, with booking windows shortening to 7-14 days. Platform commission structures at 15-25 percent erode property economics for this price-sensitive segment.
- Business Travelers:Corporate procurement teams now prioritize sustainability credentials and flexible cancellation terms, filtering hotel selection through ESG scorecards. This segment concentrates in Lyon, Marseille, and Strasbourg where conference infrastructure overlaps with transport connectivity.
- Groups:Tour operators and incentive planners negotiate volume discounts that test revenue management systems.
- Families:Multi-room bookings and extended-stay patterns favor apartment-hotel formats in Disneyland Paris periphery and alpine resorts.
Leisure Guests hold installed capacity. Business Travelers is climbing the fastest as procurement policies recalibrate.
Price Tier:
Cost tier positioning determines access to Atout France promotional channels and corporate contract eligibility, with classification audits tightening differentiation.
- Luxury:Palace-rated properties in Paris, Courchevel, and Saint-Tropez sustain pricing power through strict zoning limits on new supply. EU Green Deal retrofit mandates trigger full reconstruction cycles for aging Haussmann-era stock, stretching capital deployment timelines.
- Mid-Scale:Three- and four-star properties in Lyon, Toulouse, and Nantes capture regional business travel and domestic leisure demand. Louvre Hotels Group anchors density in these secondary cities through standardized operating formats.
- Budget:Two-star and comparable properties face saturation in major urban corridors, with roadside locations competing on parking and motorway access.
- Economy:Formats emphasizing cost control over service frequency expand in suburban and exurban zones, with B&B Hotels deploying automated check-in to compress breakeven thresholds.
Luxury holds installed capacity. Mid-Scale is gaining share fastest through secondary city infrastructure investment.
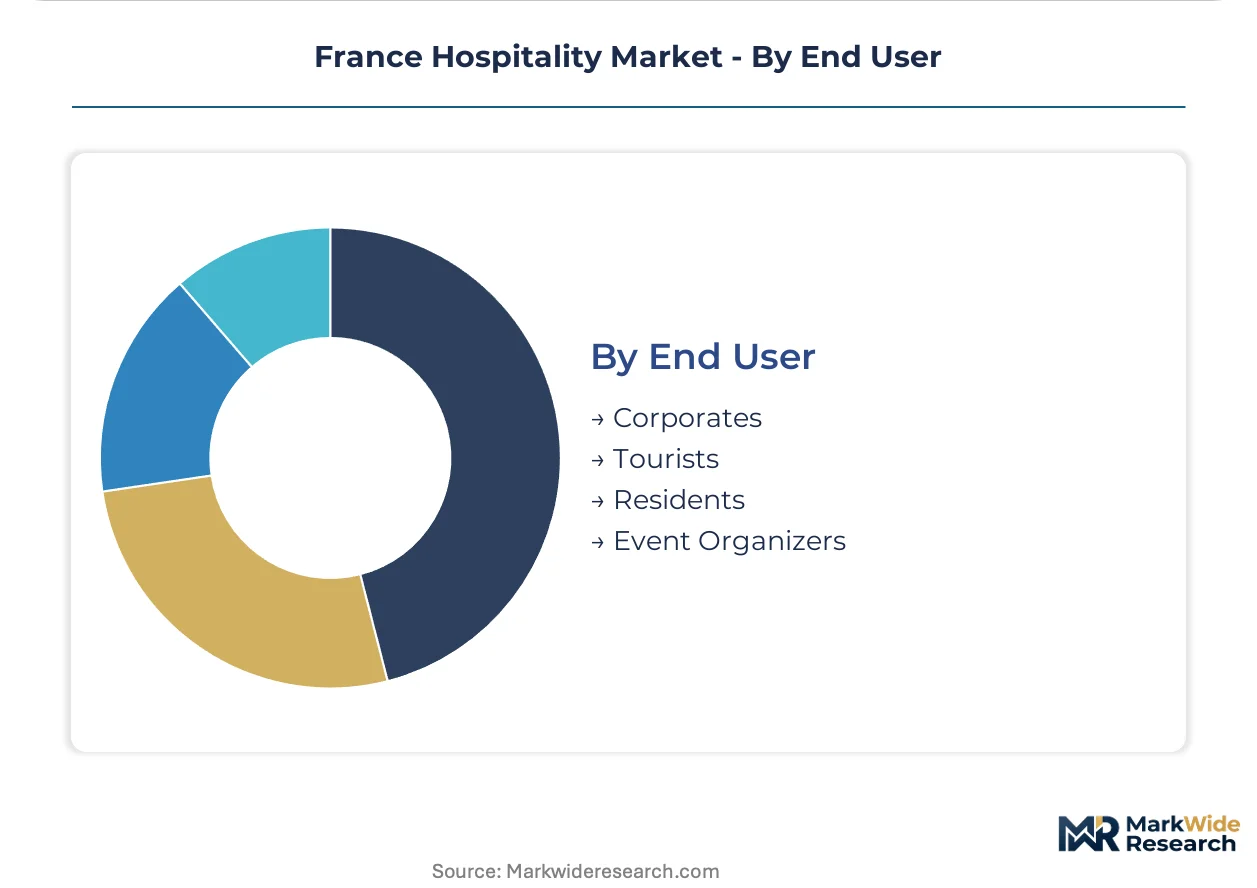
End User:
Application concentration varies by booking channel, with direct corporate contracts yielding superior net operating income compared to platform-mediated tourist demand.
- Tourists:International and domestic leisure travelers concentrate demand in Paris, Nice, and Biarritz, with seasonal patterns creating occupancy volatility. Atout France's classification visibility on booking platforms directly conditions capture rates for this segment.
- Corporates:Pharmaceutical and consulting firms negotiate annual rate agreements that prioritize properties with verified sustainability credentials under EU Green Deal alignment.
- Event Organizers:Trade associations and wedding planners source bundled packages combining accommodation, F&B, and AV services.
- Residents:Local demand for dining, spa, and day-use facilities provides base-load revenue independent of travel seasonality.
Tourists hold installed capacity. Corporates is rotating up the share rankings through procurement policy recalibration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal retrofit mandates and Atout France classification tightening are redistributing hospitality investment across French sub-regions, with secondary cities capturing supply expansion while Paris and coastal zones absorb compliance-driven renovation cycles.
Île-de-France
Corporate bleisure demand and international tourism concentrate in Paris, where Haussmann-era building stock triggers full reconstruction cycles under EU Green Deal energy standards. ANSM hygiene protocols and CNIL data mandates add compliance layers that favor scaled operators. Palace-rated properties in central arrondissements sustain pricing power through strict zoning limits on new supply.
Auvergne-Rhône-Alpes
Lyon anchors regional business travel alongside alpine resort demand in Courchevel and Chamonix. Atout France's classification audits condition promotional access for properties serving pharmaceutical and consulting firm procurement teams. Strict environmental zoning in mountain municipalities protects premium positioning for properties securing development permits.
Provence-Alpes-Côte d'Azur
Cannes conference infrastructure and Saint-Tropez leisure demand generate disproportionate event management margins. Coastal supply constraints under strict zoning regulations sustain rate premiums. EU Green Deal building performance standards force thermal upgrades across aging waterfront properties in Nice and Antibes.
Nouvelle-Aquitaine
Bordeaux wine tourism and Biarritz coastal demand attract compressed-stay visitors via improved TGV connectivity. Secondary city infrastructure investment unlocks mid-scale supply expansion. Atout France classification visibility on booking platforms directly conditions capture rates for international tourist segments.
Occitanie
Toulouse aerospace corporate travel and Carcassonne heritage tourism blend business and leisure demand patterns. Roadside and suburban locations compete on motorway access and parking for domestic leisure segments. Automated check-in deployments compress breakeven thresholds in standardized economy formats.
France Hospitality Market Competitive Landscape
Player mix skews toward integrated multi-brand hospitality groups with portfolio diversification across luxury through economy tiers. Market structure concentrates around operators controlling distribution platform relationships and corporate contract eligibility. Two strategic archetypes dominate: vertically integrated real estate owners with captive management contracts, and asset-light brand licensors expanding through franchise agreements. Competitive moves center on M&A-driven portfolio consolidation and technology licensing for property management systems.
Within the integrated multi-brand tier, Accor and Louvre Hotels Group exemplify archetype positioning through spanning luxury through economy tiers across Paris, Lyon, and Marseille. B&B Hotels anchors the standardized cost-controlled format archetype in roadside and suburban locations. These three operators collectively represent the competitive tension between full-service portfolio breadth and focused-format operational efficiency that defines French hospitality rivalry.
| Leading Market Players |
|---|
| Accor |
| Louvre Hotels Group |
| B&B Hotels |
| Marriott International |
| IHG Hotels & Resorts |
| Best Western Hotels & Resorts |
| Brit Hotel |
| Hilton Worldwide |
| Logis Hotels |
| Others |
Pricing and Supply Chain Analysis
Automated check-in systems displacing front-desk labor simultaneously compress operating costs in secondary French cities and enable rate undercutting against Paris properties still bound to SMIC-indexed staffing conventions. This substitution dynamic redistributes pricing power toward standardized formats while fragmenting supply geography across roadside, suburban, and urban-core locations with divergent labor cost structures.
Pricing Analysis
Cost-plus contracts with SMIC indexation dominate labor-intensive luxury formats, while economy tiers deploy fixed-cost automation to flatten breakeven curves. Price differentiation rests on Atout France star certification and EU Green Deal compliance visibility. Pricing pressure intensifies in budget corridors where platform commissions extract 15-25 percent of gross revenue. Corporate procurement teams show lowest price sensitivity, prioritizing sustainability credentials over rate negotiation.
Supply Chain Analysis
Inbound logistics costs from Mediterranean port congestion and container availability constraints affect linen, fixture, and foodservice equipment flows into Marseille and Nice. Supply concentration centers on Italy for luxury furnishings, Spain for fresh produce, and Turkey for textiles. Single-source vulnerability sits with specialized kitchen equipment from German manufacturers. Distribution runs through regional procurement consortia serving multi-property operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France hospitality functions as a service-attach opportunity where property management system licensing and wellness certification fees expand faster than room-night revenue. Recurring technology and compliance service layers now capture disproportionate margin expansion relative to fixed-asset yields.
For Market Incumbents: Compound defensive positioning through captive PMS technology licensing to independent properties and accelerated EU Green Deal retrofit completion in Palace-rated assets. Labor cost rigidity under SMIC indexation threatens operating leverage; vertical integration into automated check-in hardware manufacturing preserves margin control against platform commission erosion.
For New Entrants and Emerging Players: Anchor in secondary city extended-stay formats serving aerospace and pharmaceutical corporate travel in Toulouse and Lyon. The mid-scale bleisure segment shows lowest competitive density. Go-to-market through direct corporate contract negotiation bypasses platform commission structures entirely.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light brand licensors with captive franchise networks. Five-to-ten year viability hinges on technology transfer capability rather than real estate ownership. Watch Atout France classification audit failure rates as inflection signal for distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Retrofit Completion | Unlocks Palace-rated pricing power and corporate contract eligibility under sustainability procurement criteria. |
| Property Management System Licensing | Captures recurring SaaS revenue from independent properties seeking platform commission mitigation. |
| ANSM-Certified Wellness Integration | Accesses medical tourism reimbursement flows through thermal mineral water certification protocols. |
| Secondary City Franchise Expansion | Exploits TGV connectivity improvements in Bordeaux and Nantes with standardized cost-controlled formats. |
| Corporate Direct Contract Negotiation | Bypasses Booking.com and Expedia commission structures for pharmaceutical and consulting firm demand. |
Research Methodology
The analysis maps accommodation, food and beverage, event management, and travel service segments, each validated through revenue managers, procurement officers at pharmaceutical firms, Atout France classification auditors, and PMS technology vendors. Primary interviews combined with secondary validation from Atout France registry data, EU Green Deal compliance filings, ANSM hygiene inspection records, and corporate travel policy disclosures. Bottom-up property-level capacity assessment triangulates against top-down sector value estimates.
Consistency checks validated outputs against external benchmarks across the projection horizon. The analytical framework models service type, customer profile, price tier, and end-user channel dimensions alongside regional infrastructure development trajectories. CAGRs derive from occupancy-rate elasticity to transport connectivity investments and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate SMIC indexation trajectories and platform commission rate stability.
Material uncertainties — abrupt corporate travel policy reversals, Atout France classification timeline accelerations, or EU Green Deal penalty enforcement variations — sit outside the modeled envelope. Forecasts reflect documented assumptions about labor cost rigidity and secondary city demand conversion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
China Online Accommodation Market
Accommodation
Youth Summer Camp Market
Accommodation
China Tourism and Hotel Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
India Online Accommodation Market
Accommodation
Europe Online Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Luxury Hotel Market
Accommodation
Hotel Market
Accommodation
Russia Online Accommodation Market
Accommodation
Germany Student Accommodation Market
Accommodation
Movie Theaters Market
Accommodation
Italy Online Accommodation Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
US Recreational and Vacation Camp Market