
 UK Student Accommodation Market | 2026-2036
UK Student Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Student Accommodation Market Outlook
Premium ensuite specification is reorganizing the UK student accommodation market as operators shift from basic halls to self-contained units with private bathrooms and study zones. Unite Students leverages its scale across 25 university towns to control development pipelines and secure long-term university partnerships. iQ Student Accommodation anchors its portfolio in London and major regional hubs, sustaining occupancy premiums through in-house property management. Vita Student differentiates with concierge services and wellness programming, occupying the lifestyle-branded tier above commodity providers.
UK student accommodation comprises purpose-built residential assets designed to house enrolled students during academic terms, typically featuring fire-rated construction, integrated Wi-Fi infrastructure, and shared or private kitchen facilities. The primary commercial purpose is to generate rental yield from a captive demographic with predictable annual turnover tied to university calendars. Studio apartments command the highest rent per square foot among property types, with margin pools concentrating in assets within 15 minutes' walk of campus gates. Short-term and flexible lease structures are expanding fastest, responding to postgraduate and international student cohorts seeking non-standard arrival patterns.
The Homes England regulatory framework shapes development finance availability for student housing, while local authority planning committees enforce Section 106 affordable housing contributions under the National Planning Policy Framework. Building Regulations Part L and forthcoming Future Homes Standards mandate energy efficiency upgrades that raise refurbishment costs for older stock. Stakeholders must monitor how university enrollment caps, international visa policy shifts, and interest rate trajectories intersect to reshape development feasibility and institutional capital allocation.
Market Dynamics
Institutional capital allocation into purpose-built student housing is restructuring competitive economics across England, Scotland, and Wales. Pension funds and sovereign wealth vehicles now underwrite development pipelines that universities alone cannot finance, shifting control toward yield-focused asset managers.
Growth Catalysts
- International enrollment recovery:Postgraduate visa routes under the UK's Graduate visa scheme are attracting non-EU students who pay premium rents for ensuite and studio stock. London and Russell Group cities absorb the bulk of this demand.
- Section 106 planning contributions:The National Planning Policy Framework mandates affordable housing quotas from large residential schemes. Student housing developers negotiate viability assessments that secure planning consent while managing cost burdens.
- Energy efficiency retrofit mandates:Building Regulations Part L and Future Homes Standards force older stock upgrades. Refurbishment cycles accelerate replacement of 1990s-era halls with modern, low-carbon alternatives.
Market Restraints
- Construction cost volatility:Steel and concrete input prices fluctuate with energy markets. Development appraisals face margin compression when fixed-price contracts expire mid-build.
- Interest rate exposure:Floating-rate debt dominates development finance. Refinancing risk concentrates in assets delivered during 2021-2022 low-rate windows.
- Planning committee delays:Local authority capacity constraints extend determination timelines. Pre-application consultation phases now routinely exceed twelve months in high-growth university towns.
Strategic Opportunities
- Flexible lease structures:Short-term and rolling contracts accommodate international students with non-standard arrival patterns. Operators capture postgraduate cohorts previously served by private rental sector.
- Wellness amenity integration:Concierge services, mental health programming, and fitness facilities differentiate lifestyle-branded assets. Premium positioning commands rent gaps above commodity providers.
- Regional hub expansion:Supply deficits persist in Russell Group cities outside London. Development pipelines in Manchester, Bristol, and Edinburgh offer yield premiums over capital-saturated zones.
Industry Challenges
- Net-zero retrofit execution:Older stock requires fabric-first efficiency upgrades. Capital allocation conflicts between refurbishment spend and new development returns strain portfolio strategy.
- University partnership negotiation:Long-term nomination agreements demand revenue-sharing structures. Operators balance guaranteed occupancy against rent escalation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Student Accommodation Market |
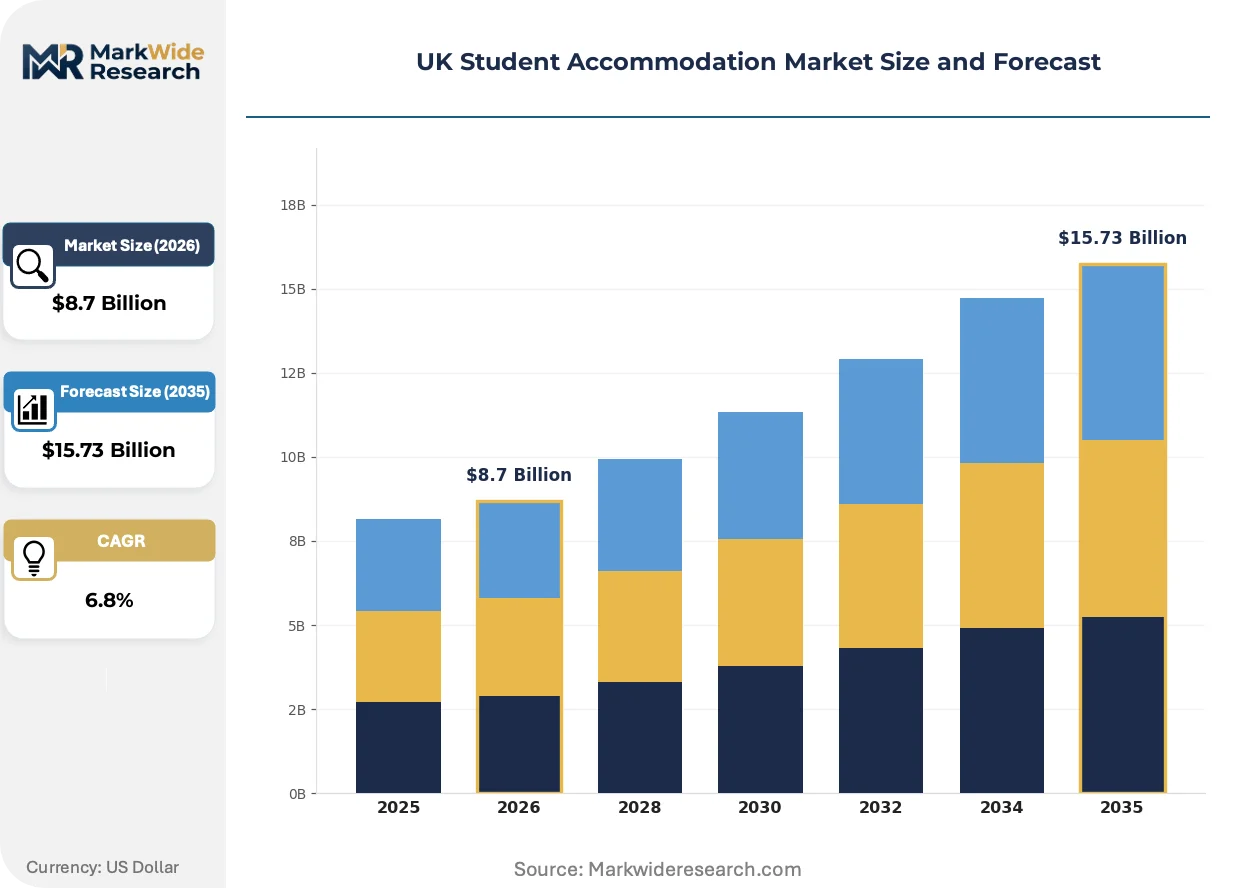
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
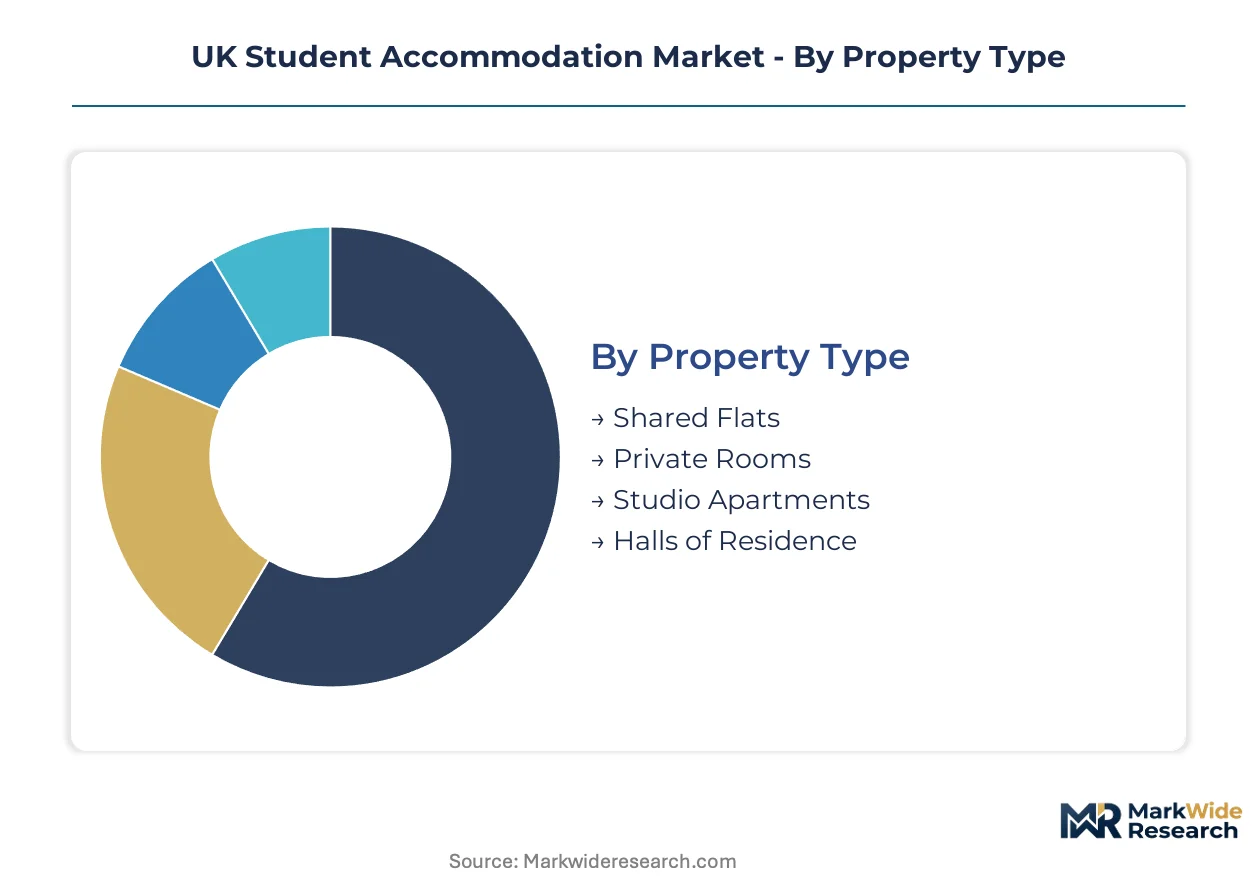
| Segmentation | Property Type: Shared Flats, Private Rooms, Studio Apartments, Halls of Residence Lease Duration: Short-Term, Full Academic Year, Semester-Based, Flexible Lease Campus Proximity: On-Campus, Off-Campus, City Center, Suburban Facility Type: Basic Amenities, Fully Furnished, Ensuite Bathrooms, Communal Spaces |
| Companies Covered | Unite Students, iQ Student Accommodation, Student Roost, Vita Student, Global Student Accommodation, Homes for Students, UPP, The Student Hotel, Campus Living Villages, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Student Accommodation Market Strategic Shifts
Digital infrastructure and service unbundling are redefining how student housing operators capture and retain rental income. Technology deployment now separates margin leaders from commodity landlords.
Smart building management systems are decomposing traditional facilities cost structures. Sensors and predictive maintenance algorithms reduce reactive repair spend across large portfolios. Operators with in-house technical teams deploy these platforms fastest. The technology is compressing operating expenditure per bed while enabling remote oversight of geographically dispersed assets.
The Future Homes Standards framework mandates operational energy limits for new residential construction. Developers must specify heat pumps and high-efficiency glazing to secure building control sign-off. Studio and ensuite stock in urban regeneration zones faces the steepest compliance cost escalation. Forward-funded schemes are locking in specification standards two years ahead of 2025 enforcement dates.
Postgraduate and international cohorts now expect hotel-style service packaging with accommodation. Operators unbundle amenities into tiered subscription models rather than inclusive rents. This consumption-pattern shift is most visible in London Zone 1-2 assets serving one-year master's students. Revenue management systems track uptake to optimize bundle pricing against churn rates.
UK Student Accommodation Market Segmentation
Student accommodation demand fragments across multiple axes that determine rent capture and capital intensity. Operators must align portfolio composition with university calendars, visa policy shifts, and postgraduate enrollment patterns.
Property Type:
Substitution pressure runs highest where private rental sector inventory overlaps with purpose-built stock, compressing rent premiums in shared formats while studio units defend pricing power.
- Shared Flats:Multi-bedroom configurations with communal kitchens serve price-sensitive domestic undergraduates. Demand concentrates in northern England university towns where land costs permit lower rent bands. Operators face margin pressure from competing private rental housing nearby.
- Studio Apartments:Self-contained units with private kitchenettes and bathrooms command peak rent per square foot. International postgraduates in London and Russell Group cities absorb supply fastest. Visa-linked enrollment surges drive pre-leasing velocity here.
- Private Rooms:Individual bedrooms within cluster flats balance privacy with cost control.
- Halls of Residence:Traditional corridor-style layouts with shared facilities dominate university-owned stock.
Shared flats retain volume leadership; studio apartments hold the steepest expansion curve.
Lease Duration:
Cost tier stratification separates operators serving predictable academic calendars from those capturing premium yields through flexibility.
- Full Academic Year:Standard 40-44 week contracts align with undergraduate term structures. Domestic students in traditional university towns generate baseline occupancy. Revenue certainty supports fixed-rate debt service coverage.
- Flexible Lease:Rolling or customizable terms accommodate non-standard arrival patterns. Postgraduate researchers and short-course participants in London pay premium rates for this adaptability. Operators deploy dynamic pricing algorithms to optimize yield.
- Short-Term:Contracts under 12 weeks serve summer school and exchange cohorts.
- Semester-Based:Half-year alignments match specific course structures.
Full academic year contracts anchor portfolio cash flow; flexible lease structures are expanding most quickly.
Campus Proximity:
Geographic positioning directly determines development feasibility and planning committee risk exposure.
- On-Campus:University-controlled land with direct institutional oversight. Oxford and Cambridge colleges maintain historic embedded provision. New supply requires land release negotiations with vice-chancellor offices.
- Off-Campus:Purpose-built developments within 15-minute walk of campus gates. Edinburgh and Manchester pipelines concentrate here. Section 106 affordable housing contributions apply to larger schemes.
- City Center:Central business district locations with transport connectivity.
- Suburban:Peripheral zones with lower land costs but transit dependency.
Off-campus stock dominates institutional investment flows; on-campus provision maintains the tightest supply constraints.
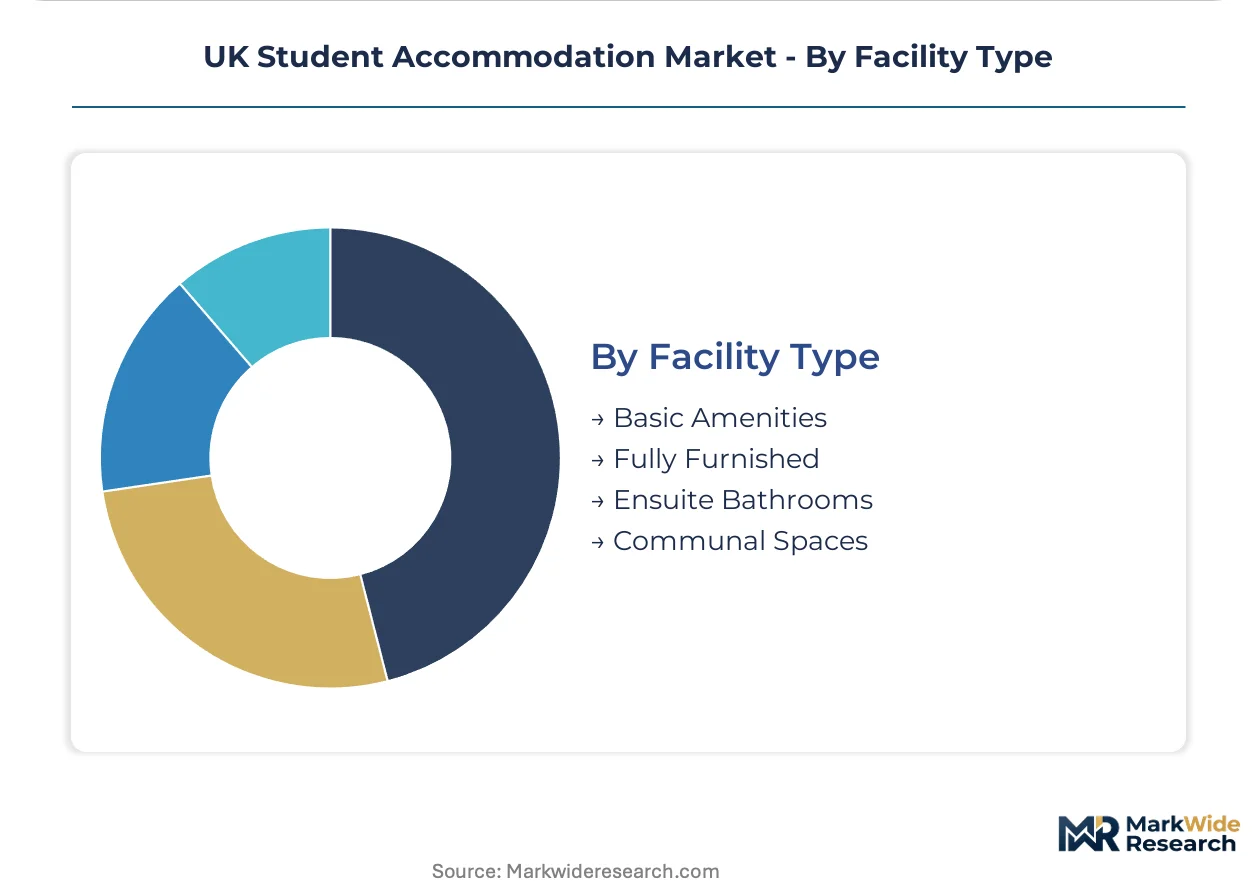
Facility Type:
Application-driven specification tiers separate commodity operators from lifestyle-branded competitors.
- Ensuite Bathrooms:Private wash facilities within individual bedrooms now constitute baseline expectation. New developments in Bristol and Leeds mandate this specification. Building Regulations Part L compliance raises construction costs for wet room pods.
- Fully Furnished:Complete fixture packages including desks, storage, and white goods. International students without UK furniture sourcing capability require this standard. Operators bundle replacement reserves into service charge structures.
- Basic Amenities:Minimal fit-out with tenant-supplied furnishings.
- Communal Spaces:Shared kitchens, lounges, and study areas as primary differentiators.
Fully furnished specification retains volume leadership; ensuite bathrooms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK student accommodation market operates as a net capital importer, with institutional investment flows from North American pension funds and Middle Eastern sovereign wealth vehicles exceeding outbound domestic developer equity. Regional performance fragments sharply between London's yield-compressed prime zones and regional university cities where supply deficits sustain rent growth premiums.
London and Southeast
International postgraduate enrollment from India and Nigeria drives studio and ensuite demand in Zone 1-2 locations. The Greater London Authority's Affordable Housing and Viability Supplementary Planning Guidance shapes Section 106 negotiations for large schemes. King's Cross and Stratford regeneration clusters concentrate new purpose-built supply serving University College London and Queen Mary University of London cohorts.
Midlands
Birmingham and Nottingham absorb domestic undergraduate volume through shared flat configurations at lower rent bands than southern competitors. West Midlands Combined Authority planning frameworks prioritize brownfield student housing near transport interchanges. Coventry's manufacturing heritage zones host refurbishment pipelines converting 1990s office stock into ensuite clusters.
North England
Manchester and Leeds exhibit the steepest supply-demand imbalances among Russell Group cities, with occupancy rates sustaining above national averages. Combined Authority mayoral development corporations expedite planning determinations for strategic sites. Liverpool's Baltic Triangle and Sheffield's Knowledge Quarter anchor urban regeneration-linked student housing pipelines.
Scotland
Edinburgh's historic core constraints limit new supply despite University of Edinburgh international enrollment growth. Scottish Government planning policy distinguishes student housing from mainstream residential use classes. Glasgow's West End and Dundee's waterfront regeneration zones concentrate development activity serving Strathclyde and Abertay University populations.
Wales
Cardiff and Swansea operate smaller institutional investment markets dominated by university partnership models rather than speculative development. Welsh Government planning policy permits student housing as enabling development in town center regeneration schemes. Cardiff Bay and Swansea University's Bay Campus anchor the limited pipeline of new purpose-built stock.
UK Student Accommodation Market Competitive Environment
Listed leaders compete with private specialists across capital access and development risk tolerance, producing a tiered market structure where scale operators control pipeline visibility and niche players capture lifestyle premiums. The competitive field separates into three archetypes: yield-focused institutional platforms, university-linked partnership vehicles, and lifestyle-branded premium operators. Dominant competitive moves include forward-funded development partnerships with universities and portfolio acquisitions of mature assets to secure immediate income streams.
Within the scale-driven tier, Unite Students and iQ Student Accommodation exemplify institutional platforms with national footprint coverage, while Vita Student occupies the lifestyle-branded position above commodity providers. Student Roost represents the mid-market consolidation archetype, and UPP anchors the university partnership model through long-term concession agreements.
| Leading Market Players |
|---|
| Unite Students |
| iQ Student Accommodation |
| Student Roost |
| Vita Student |
| Global Student Accommodation |
| Homes for Students |
| UPP |
| The Student Hotel |
| Campus Living Villages |
| Others |
Value Chain & Pricing Dynamics
Portfolio scale economies across 25-plus university towns compress per-unit operating expenditure while establishing rent floors that smaller operators cannot match. Unite Students and iQ Student Accommodation leverage this density to negotiate bulk procurement contracts for wet room pods and fire-rated construction materials, translating supply-side concentration into pricing power that defends margin pools against fragmented private rental sector competition.
Pricing Analysis
International postgraduate cohorts anchor studio and ensuite pricing premiums in London Zone 1-2 and Russell Group cities. Pricing stratifies across lifestyle-branded, institutional-scale, and commodity tiers, with visa-linked enrollment surges and campus walkability as primary differentiation drivers. Cost compression in shared flat configurations is intensifying because private rental sector inventory overlaps with purpose-built stock in northern England university towns. Domestic undergraduates in Birmingham and Nottingham exhibit highest price sensitivity; international postgraduates in Edinburgh and Manchester show lowest.
Supply Chain Analysis
Steel and concrete input chokepoints through UK and European manufacturing hubs expose development pipelines to energy-market volatility. Construction materials draw from Germany, China, and domestic UK suppliers, with heat pump and high-efficiency glazing specifications mandated under Future Homes Standards. Single-source vulnerability concentrates in wet room pod fabrication. Distribution runs through forward-funded development partnerships where institutional capital locks specification standards two years ahead of enforcement dates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent operators must defend against substitution from flexible private rental sector inventory and university-owned halls expansion that capture price-sensitive domestic undergraduates.
For Market Incumbents: Fortify long-term university partnership pipelines through revenue-sharing nomination agreements that guarantee occupancy against rent escalation flexibility. Secure backward integration into development land banks in Manchester, Bristol, and Edinburgh where supply deficits sustain yield premiums. Counter private rental sector substitution by embedding wellness amenity programming that commodity landlords cannot replicate. For New Entrants and Emerging Players: Differentiate on flexible lease architecture targeting postgraduate researchers with non-standard arrival patterns underserved by rigid academic calendars. White-space concentrates in short-term and rolling contract segments within London and Russell Group cities. Pursue urban regeneration-linked development sites where Combined Authority mayoral corporations expedite planning determinations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among institutional-scale platforms with forward-funded pipelines and in-house property management capabilities. Five-to-ten year viability favors assets within 15-minute walk of campus gates in supply-constrained Russell Group cities. Monitor international visa policy shifts and Graduate route enrollment data as inflection indicators for studio and ensuite demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Forward-Funded Development Partnership | Institutional capital from pension funds locks pipeline visibility against interest rate volatility. |
| University Nomination Agreement | Long-term revenue-sharing structures guarantee occupancy for Unite Students and UPP portfolios. |
| Wellness Amenity Integration | Concierge and mental health programming commands rent gaps above commodity providers like Student Roost. |
| Energy Efficiency Retrofit | Building Regulations Part L compliance future-proofs older stock against obsolescence risk. |
| Flexible Lease Platform Launch | Dynamic pricing algorithms capture postgraduate cohorts previously served by private rental sector. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Homes England regulatory filings, local authority planning committee determinations, and university enrollment statistics. Interviews with development directors at institutional investors, planning officers at Combined Authorities, and procurement leads at major operators triangulate against construction cost databases and visa policy documentation. Bottom-up bed-stock counts across 25 university towns validate top-down capital flow estimates from pension fund and sovereign wealth disclosures.
Segmentation dimensions modeled include property type, lease duration, campus proximity, and facility specification tier across the analysis window. CAGRs derive from enrollment trajectory projections, development pipeline visibility, and rent growth assumptions in supply-constrained versus capital-saturated zones. International visa policy shifts and interest rate trajectories feed sensitivity testing.
The analysis sits within stated boundaries; outcomes outside sustained Graduate visa route access and institutional capital availability would require recalibration. Forecasts reflect assumptions on construction cost stabilization and planning determination timelines. Practitioners should keep alternative scenarios live as Homes England regulatory frameworks and Future Homes Standards enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Youth Summer Camp Market
Accommodation
France Online Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Airport Lounges Market
Accommodation
France Casino Tourism Market
Accommodation
Europe Student Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
United States Online Accommodation Market
Accommodation
China Online Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Croatia Hospitality Market
Accommodation
Glamping Market
Accommodation
Romania Hospitality Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
China Tourism and Hotel Market