
 UAE Hospitality Market | 2026-2036
UAE Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Hospitality Market Insights
Dubai's hotel room inventory expansion is reshaping competitive dynamics across the emirate. Marriott International leverages its portfolio breadth to anchor premium positioning in the Downtown and Marina districts. Hilton Worldwide sustains operational density through its Waldorf Astoria and Conrad flags on the Palm Jumeirah. Emaar Hospitality Group controls supply pipelines via its Address and Vida brands tied to master developments.
Hospitality denotes the commercial provision of lodging, food service, and guest experiences through physical properties ranging from 50-key boutique assets to 1,500-room integrated resorts. Properties operate on revenue-per-available-room metrics, food-and-beverage yield management, and ancillary spend capture from spas, retail, and entertainment venues. Luxury Hotels and Resorts command the dominant margin pool across the UAE, while Boutique Hotels represents the fastest-growing structural category as developers target experiential differentiation. Business Travelers still generate the highest per-stay ancillary spend, though Leisure Travelers now drives absolute volume growth through extended-stay patterns and repeat visitation.
MOHAP enforces health and safety licensing standards for all hospitality facilities, while the UAE's central tourism authorities mandate green building compliance under federal sustainability frameworks. ADQIA and Dubai Tourism's classification systems shape product standards through star-rating criteria that govern market access and pricing authority. Stakeholders must monitor how evolving emirate-level licensing requirements and sustainability mandates will reshape capital allocation decisions for new supply.
Market Dynamics
Sustainability mandates from the UAE's Department of Culture and Tourism are restructuring capital allocation across new hotel developments, forcing developers to integrate green building compliance from project inception rather than retrofitting later.
Growth Catalysts
- Leisure Traveler Volume:Extended-stay patterns and repeat visitation from leisure segments are filling shoulder-season inventory gaps that business travel once dominated.
- Federal Sustainability Frameworks:Mandatory green building compliance is accelerating premium positioning for properties that certify early under UAE central tourism authority protocols.
- Master Development Pipelines:Emaar Hospitality Group's Address and Vida brands tied to integrated developments are capturing supply-constrained beachfront corridors in Dubai.
Market Restraints
- Construction Input Volatility:Specialized sustainable materials and MEP systems required for green certification are inflating pre-opening capex by unpredictable margins.
- Labor Pool Concentration:Skilled hospitality operations talent concentrates in Dubai, creating wage pressure for Abu Dhabi and Northern Emirates properties.
- Regulatory Fragmentation:Divergent licensing timelines between MOHAP health standards and emirate-level tourism classifications delay revenue commencement.
Strategic Opportunities
- Abu Dhabi Cultural District:Underpenetrated luxury inventory around Saadiyat Island's museum cluster offers first-mover positioning ahead of 2030 cultural infrastructure completion.
- Wellness-Integrated F&B:Convergence of clinical wellness protocols and food service operations is opening ancillary revenue streams beyond traditional spa models.
- Direct Booking Channels:Proprietary loyalty platforms are reducing OTA dependency for properties with established repeat guest databases.
Industry Challenges
- Sustainability Certification Timelines:Green building verification processes are extending pre-opening phases by 8-14 months, compressing developer IRR schedules.
- Legacy PMS Integration:Property management system migrations to cloud-native platforms are disrupting real-time inventory distribution during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Hospitality Market |
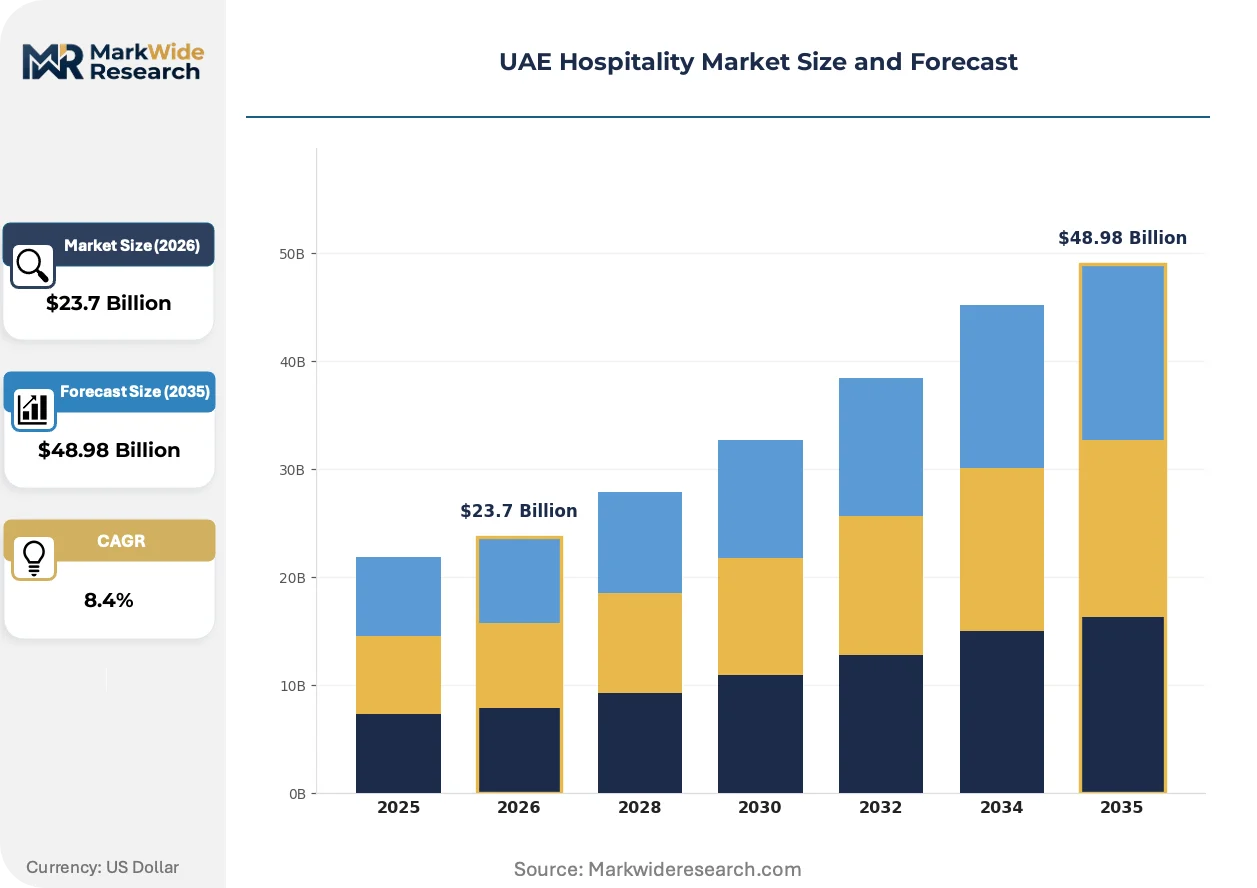
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Hotels, Budget Accommodations, Resorts, Boutique Hotels Customer Type: Leisure Travelers, Business Travelers, Group Tours, Families Facility Type: Hotels, Motels, Serviced Apartments, Hostels Booking Channel: Online Travel Agents, Direct Bookings, Corporate Accounts, Travel Agencies |
| Companies Covered | Marriott International, Hilton Worldwide, Accor, IHG Hotels & Resorts, Jumeirah Group, Rotana Hotels, Hyatt Hotels Corporation, Emaar Hospitality Group, Kerzner International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Hospitality Market Trends and Innovations
Digital guest journey orchestration is displacing traditional front-desk workflows across UAE properties, with biometric check-in and mobile key distribution becoming baseline expectations rather than premium differentiators.
AI-powered revenue management systems are virtualizing legacy yield optimization practices. Marriott International and Hilton Worldwide properties in Downtown Dubai are deploying dynamic pricing algorithms that adjust rates every 15 minutes based on competitor inventory, flight arrival data, and event calendars. This compression of pricing cycles is eliminating static BAR structures and forcing smaller operators into OTA-dependent distribution.
MOHAP's updated health and safety licensing standards are mandating IoT-enabled environmental monitoring in all new hospitality facilities. Properties must now deploy real-time air quality and water safety sensors with centralized reporting dashboards. Luxury resorts on Palm Jumeirah are responding by integrating building management systems with guest-facing wellness apps that display live environmental metrics in guest rooms.
Extended-stay leisure patterns are fragmenting traditional demand segmentation. Families from GCC source markets are booking 10-14 night stays in Dubai beachfront properties, behaving more like residential tenants than transient guests. This shift is forcing F&B operations to redesign service models around grocery delivery partnerships and in-suite dining kitchens rather than restaurant-centric revenue capture.
UAE Hospitality Market Segmentation
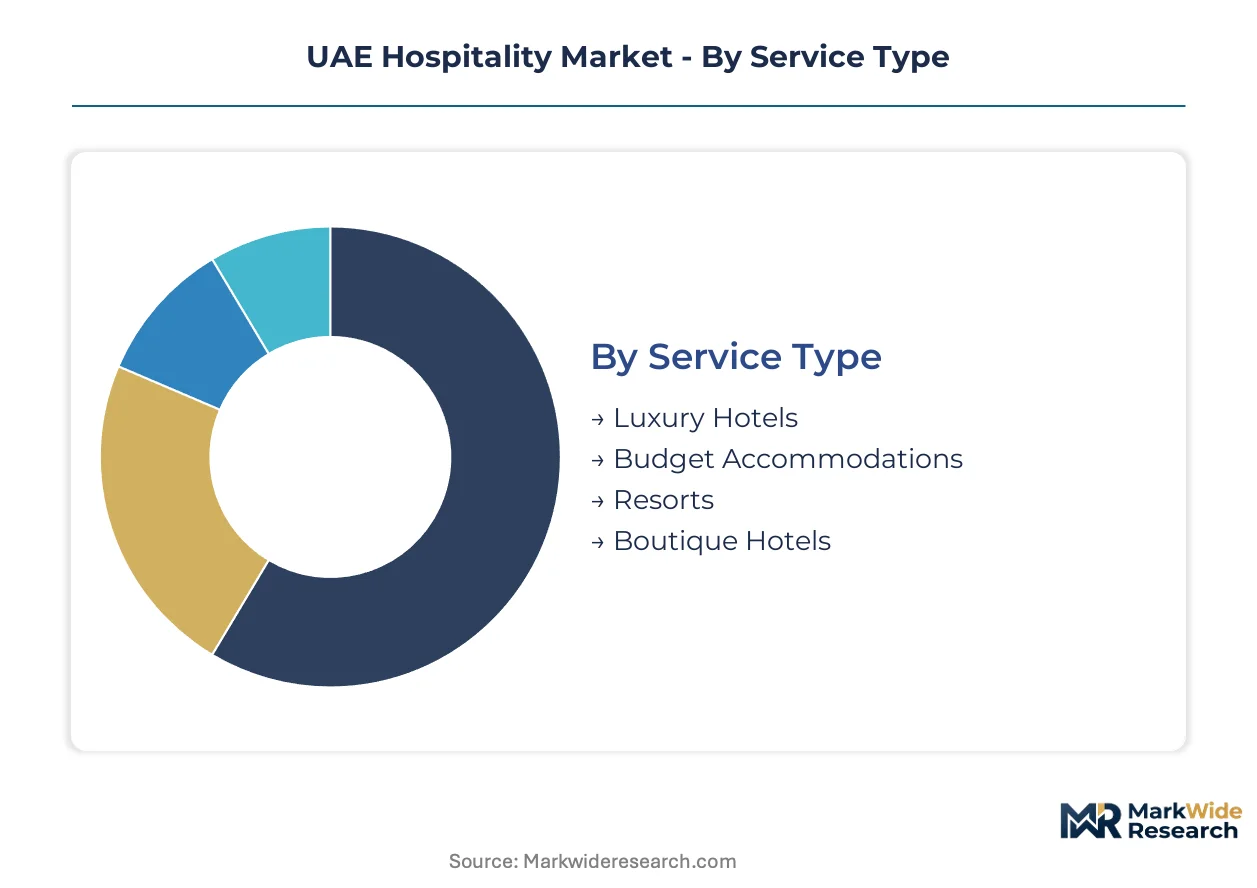
Segmentation in UAE hospitality reveals how capital cycles, guest behavior patterns, and distribution economics create distinct operational profiles across property types. Understanding these divisions helps developers align supply pipelines with demand concentration in Dubai's beachfront corridors and Abu Dhabi's emerging cultural districts.
Service Type:
Inventory turns fastest at budget properties where average lengths of stay compress to 2-3 nights, while luxury assets operate on extended-stay economics with 7-14 night guest cycles that amortize higher fixed costs.
- Luxury Hotels:Full-service properties with 300+ keys, dedicated concierge infrastructure, and integrated F&B operations command premium positioning in Dubai's Downtown and Marina districts. Demand concentrates among GCC leisure segments seeking extended-stay experiences, with MOHAP's updated health licensing standards mandating IoT-enabled environmental monitoring as a baseline operational requirement.
- Resorts:Beachfront and desert properties with standalone recreational facilities operate on all-inclusive or semi-inclusive revenue models. Palm Jumeirah assets anchor this segment, where Hilton Worldwide and Marriott International properties capture repeat visitation through loyalty program density.
- Boutique Hotels:50-150 key assets with design-forward positioning and localized F&B concepts. Emaar Hospitality Group's Vida brand exemplifies this category tied to master developments.
- Budget Accommodations:Limited-service properties with stripped amenity sets and automated guest journey touchpoints. Demand concentrates in Dubai's Deira and Al Barsha corridors serving price-sensitive transit passengers.
Luxury Hotels dominate installed base across the emirates. Boutique Hotels is where expansion concentrates as developers pursue experiential differentiation in supply-constrained corridors.
Customer Type:
Volume distribution skews toward leisure segments, though revenue per available room economics still favor commercial guests with higher ancillary capture rates.
- Leisure Travelers:Individual and couple bookings driven by destination marketing, event calendars, and visa accessibility. Dubai Tourism's promotional infrastructure targets this segment through repeat visitation campaigns.
- Business Travelers:Corporate-rate transient bookings with compressed 1-2 night stays and predictable weekday demand patterns. Abu Dhabi's business district corridor retains concentration despite Dubai's leisure dominance.
- Group Tours:Packaged itineraries with 15-30 room night blocks and negotiated F&B minimums. Demand concentrates among Asian source markets with established UAE operator relationships.
- Families:Multi-generational bookings with extended-stay patterns, kitchenette requirements, and adjacent-room inventory needs. Dubai beachfront properties report 10-14 night average lengths from GCC source markets.
Leisure Travelers anchor absolute volume. Families is where guest-night expansion climbs the fastest as residential-style service models displace traditional hotel operations.
Facility Type:
Capital intensity varies threefold across facility categories, with full-service hotels requiring 40-60 month development cycles versus 18-24 months for limited-service formats.
- Hotels:Purpose-built hospitality assets with centralized services and uniform room inventory. Dubai's pipeline concentrates in beachfront and business district corridors where land scarcity extends development timelines.
- Serviced Apartments:Extended-stay inventory with kitchen facilities and reduced daily housekeeping touchpoints. Demand concentrates among corporate relocations and family leisure segments seeking residential-style accommodations.
- Motels:Drive-up properties with surface parking and limited public area programming. Northern Emirates distribution serves highway transit corridors.
- Hostels:Shared-accommodation formats with bunk configurations and communal facilities. Limited UAE penetration reflects cultural preferences for privacy and family-unit travel.
Hotels dominate capital deployment. Serviced Apartments is where development activity gains share fastest as extended-stay leisure patterns reshape inventory requirements.
Booking Channel:
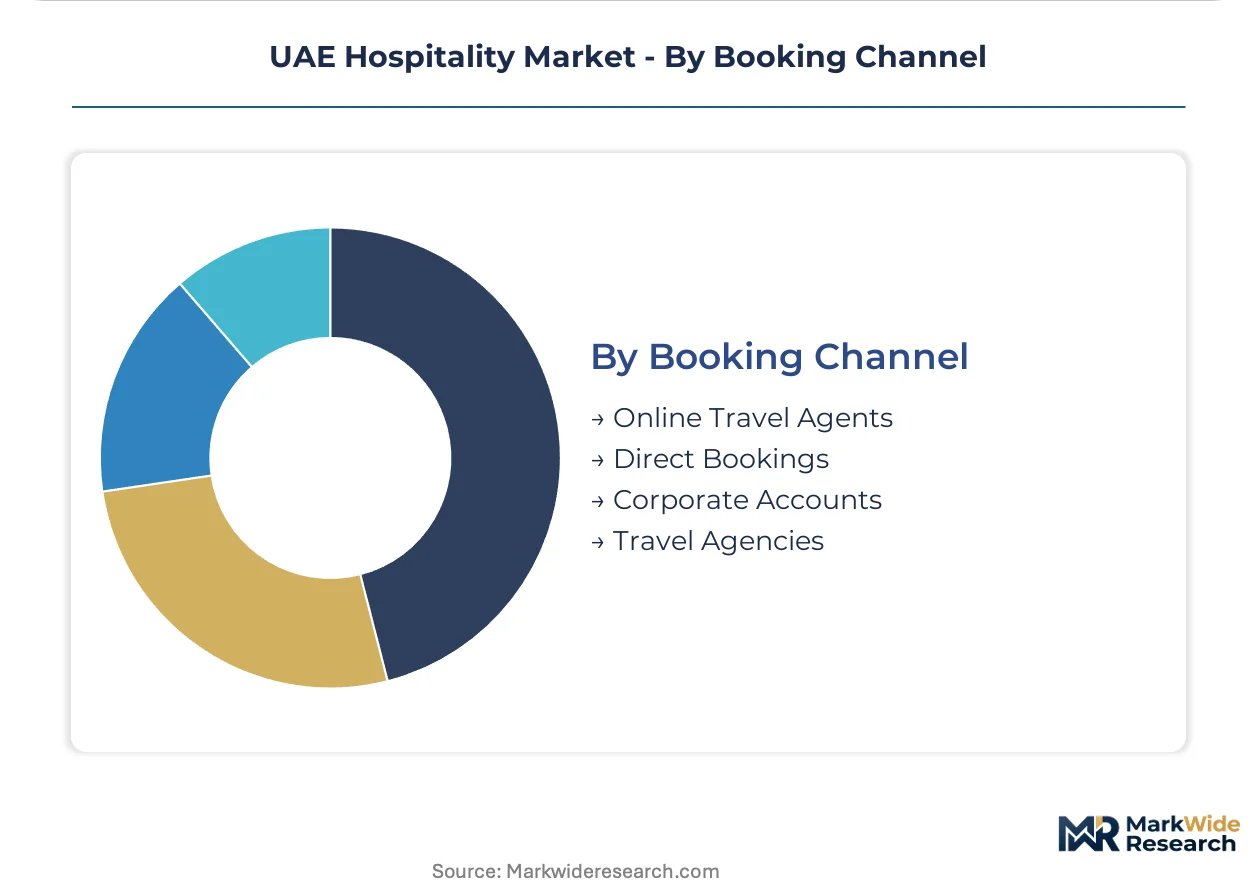
Commission structures range from 15-25% for online intermediaries to sub-5% for direct proprietary channels, creating divergent margin profiles across distribution strategies.
- Direct Bookings:Proprietary website and loyalty platform transactions with full margin retention and guest data ownership. Marriott Bonvoy and Hilton Honors density in Dubai enables this channel for established flags.
- Online Travel Agents:Third-party platform bookings with rate parity requirements and commission obligations. Smaller operators without loyalty infrastructure depend on this channel for visibility.
- Corporate Accounts:Negotiated rate contracts with volume commitments and centralized billing. Abu Dhabi government and Dubai corporate headquarters anchor this segment.
- Travel Agencies:Traditional intermediary bookings with manual confirmation workflows and group block management. Concentrates in source markets with established UAE tour operator relationships.
Online Travel Agents dominate transaction volume. Direct Bookings is where margin protection efforts concentrate as properties invest in loyalty platform infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development capital pools across Dubai's beachfront corridors and Abu Dhabi's emerging cultural districts, with MOHAP licensing standards and emirate-level tourism classifications shaping supply timelines throughout the federation.
Dubai
Leisure traveler volume and extended-stay family bookings from GCC source markets dominate demand. Dubai Tourism mandates sustainability certifications for new hotel developments under federal frameworks. The Downtown and Marina districts concentrate luxury inventory where Marriott International and Hilton Worldwide anchor competitive positioning through loyalty program density.
Abu Dhabi
Business traveler segments and government corporate accounts generate predictable weekday demand patterns. The Department of Culture and Tourism Abu Dhabi enforces green building compliance protocols for new developments. Saadiyat Island's museum cluster hosts underpenetrated luxury supply pipelines ahead of 2030 cultural infrastructure completion.
Sharjah
Price-sensitive leisure segments and transit passengers from neighboring emirates fill limited-service inventory. The Sharjah Commerce and Tourism Development Authority maintains classification systems parallel to Dubai's star-rating criteria. Beachfront corridors near Al Khan Lagoon concentrate midscale development activity from regional operators.
Northern Emirates
Domestic weekend travelers and highway transit corridors sustain motel and limited-service formats. Federal MOHAP health and safety licensing applies uniformly across Ras Al Khaimah, Fujairah, Ajman, and Umm Al Quwain. Mountain and coastal tourism zones in Ras Al Khaimah attract boutique development targeting experiential differentiation.
UAE Hospitality Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The UAE hospitality market structures around consolidated global flags with portfolio breadth, regional master developers controlling supply pipelines, and specialized luxury operators capturing niche positioning. Three archetypes dominate: multinational loyalty platforms, emirate-anchored development groups, and experience-focused boutique specialists. Competitive dynamics center on master development partnerships and sustainability certification speed-to-market.
Among multinational loyalty platforms, Marriott International and Hilton Worldwide occupy positions anchored by Bonvoy and Honors density in Dubai's premium corridors. Emaar Hospitality Group exemplifies the master-developer archetype through Address and Vida brands tied to integrated developments. These three represent the competitive core around which smaller operators and specialized flags coordinate distribution and capital access.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Accor |
| IHG Hotels & Resorts |
| Jumeirah Group |
| Rotana Hotels |
| Hyatt Hotels Corporation |
| Emaar Hospitality Group |
| Kerzner International |
| Others |
Pricing and Supply Chain Analysis
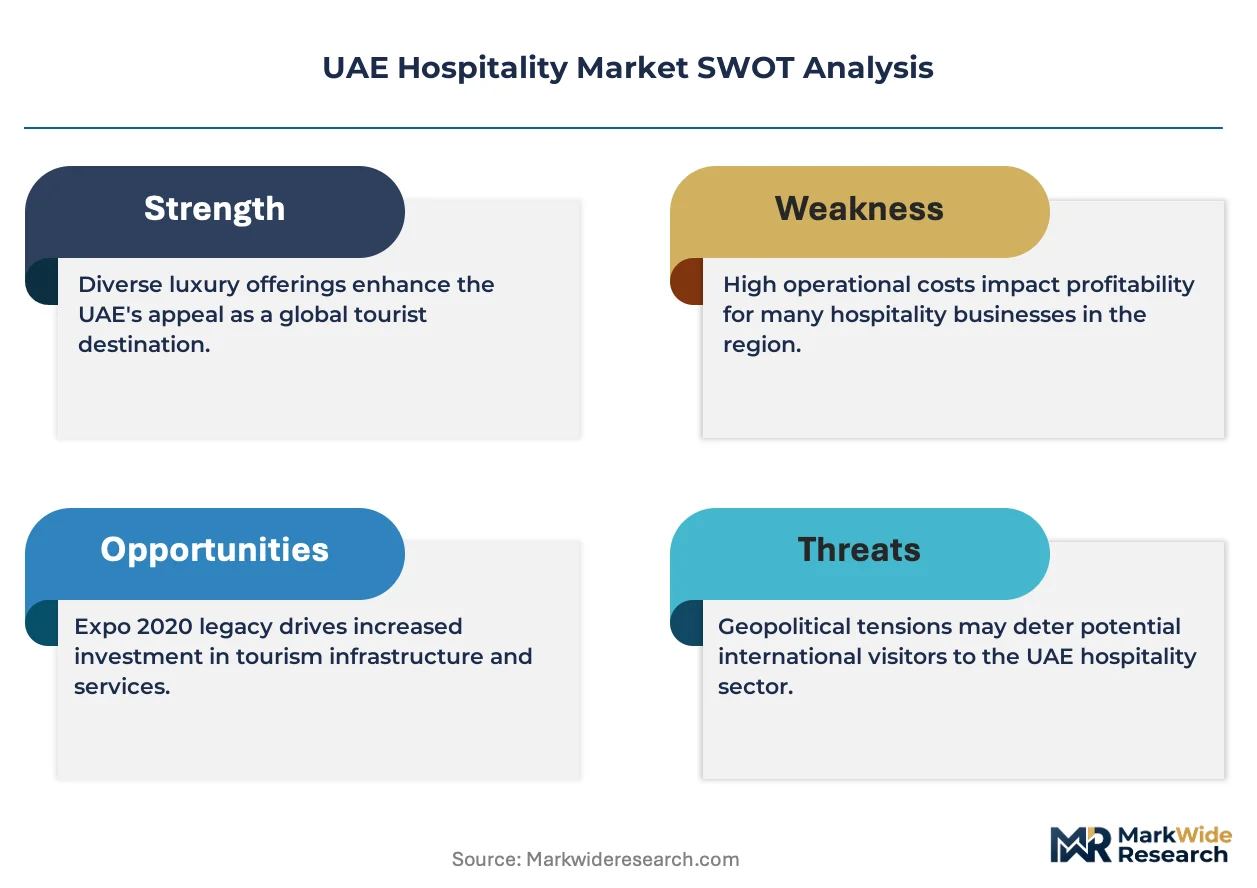
Regulatory fragmentation between MOHAP health standards and emirate-level tourism classifications determines both pricing tier spreads and supply chain shape across UAE hospitality development. Construction input volatility for sustainable materials and MEP systems compresses developer IRR schedules while inflating pre-opening capex by unpredictable margins, forcing tier stratification between certified premium inventory and conventional supply.
Pricing Analysis
MOHAP's updated health and safety licensing standards dictate the pricing tier structure across UAE hospitality. Three-tier pricing separates green-certified luxury assets from standard-grade properties and limited-service economy formats. Price differentiation rests on sustainability certification speed-to-market and loyalty platform density. Pricing pressure stems from OTA commission burdens on smaller operators lacking direct booking infrastructure. Budget accommodations in Dubai's Deira corridor exhibit highest price sensitivity; Palm Jumeirah luxury resorts anchored by Bonvoy and Honors density show lowest elasticity.
Supply Chain Analysis
Export-control restrictions on IoT-enabled environmental monitoring technologies limit flows of certified building management systems into UAE hospitality projects. Supply concentrates in Germany, South Korea, and Japan for advanced MEP components and sensor hardware. Raw material dependencies include specialized sustainable concrete formulations, low-VOC finishes, and smart glass technologies. Single-source vulnerability runs through European HVAC certification bodies extending green building verification timelines. Distribution runs through Emaar Hospitality Group's master development pipelines and multinational flag direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Short-term rental platforms and serviced apartment operators pose acute substitution threats to traditional hotel inventory, pressuring incumbents to defend through experiential differentiation and loyalty density.
For Market Incumbents: Build certification moats through early green building compliance under federal sustainability frameworks. Accelerate proprietary loyalty platform investment to reduce OTA dependency. Expand wellness-integrated F&B operations beyond traditional spa revenue models. Counter short-term rental encroachment through extended-stay product redesigns with residential-style service touchpoints. For New Entrants and Emerging Players: Pursue white-space positioning in Abu Dhabi's Saadiyat Island cultural district ahead of museum cluster completion. Target boutique hotel formats in Ras Al Khaimah's mountain and coastal tourism zones where experiential differentiation commands premium positioning. Leverage direct booking channel architecture from inception rather than retrofitting legacy distribution dependence. For Investors and Strategic Acquirers: Federal sustainability framework mandates reshape the acquisition landscape toward certified supply pipelines. Five-to-ten year viability concentrates on properties with completed green verification and established repeat guest databases. Target acquisition archetype: boutique assets with design-forward positioning tied to master developments. Watch for signals in construction input cost stabilization as inflection indicator for development IRR recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Acceleration | Early green building compliance under UAE federal frameworks secures premium positioning and pricing authority. |
| Direct Booking Channel Investment | Proprietary loyalty platform density reduces OTA commission exposure and captures guest data ownership. |
| Wellness-Integrated F&B Expansion | Clinical wellness protocol convergence opens ancillary revenue streams beyond traditional spa operations. |
| Master Development Partnership | Emaar Hospitality Group pipeline access captures supply-constrained beachfront corridors in Dubai. |
| Extended-Stay Product Redesign | Residential-style service models counter short-term rental substitution with grocery delivery and in-suite kitchen partnerships. |
Research Methodology
Operator-level perspectives from hotel development executives, sustainability certification consultants, F&B operations directors, and revenue management specialists anchored the qualitative base. Secondary validation drew from Dubai Tourism classification databases, MOHAP licensing filings, Emaar Hospitality Group supply disclosures, and federal sustainability framework documentation. Bottom-up property-level economics triangulated against top-down emirate-level supply pipeline assessments.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type tier, customer segment behavior pattern, facility format capital intensity, and booking channel margin structure. CAGRs derived from supply pipeline absorption rates, demand concentration shifts, and certification timeline compression. Forecast inputs incorporated leisure traveler extended-stay pattern persistence and green building compliance cost trajectories.
Sensitivities concentrate around construction input volatility, regulatory timeline divergence between MOHAP and emirate authorities, and loyalty platform adoption rates. Forecasts reflect documented assumptions on demand segmentation stability and certification process duration. Material shifts in federal sustainability mandate enforcement or short-term rental regulatory treatment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Romania Hospitality Market
Accommodation
Croatia Hospitality Market
Accommodation
Hostel Market
Accommodation
Youth Summer Camp Market
Accommodation
Extended Stay Hotel Market
Accommodation
United States Online Accommodation Market
Accommodation
Airport Lounges Market
Accommodation
Austria Hospitality Market
Accommodation
Movie Theaters Market
Accommodation
Glamping Market
Accommodation
Underwater Hotels Market
Accommodation
Airport Sleeping Pods Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Alternative Accommodation Market
Accommodation
Russia Online Accommodation Market