
 Swimming Gear Market | 2026-2036
Swimming Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Gear Market Outlook
Recycled polyester is hardening its position against virgin nylon in competitive swimsuit construction, compressing material costs while preserving compressive fit properties. Speedo leverages vertical integration in textile R&D to sustain its technical leadership across FINA-compliant racing suits. Arena anchors its European manufacturing base with specialized neoprene production for triathlon wetsuits. TYR Sport competes aggressively on price in the collegiate team procurement channel, where bulk uniform contracts determine seasonal volume allocation.
Swimming gear encompasses purpose-built apparel and equipment engineered for hydrodynamic efficiency, thermal insulation, and ocular protection in aquatic environments; competitive swimsuits integrate bonded seams and water-repellent surface treatments to reduce drag coefficients below 0.01 at race velocities. Goggles employ polycarbonate lenses with silicone gaskets to maintain optical clarity and facial seal integrity across chlorine and saltwater chemistries. The product type dimension shows swimsuits commanding the dominant margin pool due to textile complexity and brand premiumization, while fins represent the fastest-expanding category as underwater training methodologies proliferate in masters and rehabilitation programs. The material segment reveals neoprene gaining share in open-water and triathlon applications where thermal retention dictates purchase decisions, even as polyester dominates pool-based categories for its chlorine resistance and dye-substitution compatibility.
FDA oversight of latex-containing products shapes cap and goggle strap formulations for skin-sensitization compliance, while EU REACH restrictions on N-nitrosamines in rubber accelerators are forcing reformulation of traditional latex swim caps. ISO 8124 toy safety standards govern children’s flotation and learning products, creating certification barriers for discount-channel imports. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York, which threaten to impose material-recovery obligations on swimwear brands without established reverse-logistics infrastructure.
Market Dynamics
Neoprene and recycled polyester formulations are displacing conventional petroleum-based fabrics as EU REACH chemical restrictions and California environmental mandates force material transitions across the value chain. This regulatory-material tension compresses margins for incumbents while opening procurement advantages for vertically integrated textile producers.
Growth Catalysts
- Collegiate swimming programs:Competitive team expansion in the United States drives bulk procurement of performance suits and technical training equipment through institutional purchasing channels.
- EU REACH chemical restrictions:Regulatory pressure on N-nitrosamines in rubber accelerators accelerates reformulation of latex swim caps toward silicone alternatives with superior skin-sensitization profiles.
- Masters swimming participation:Demographic expansion of age-group competitive swimming in Germany and Australia sustains replacement demand for durability-focused training gear.
Market Restraints
- Petroleum-based fabric dependency:Virgin nylon and conventional polyester feedstock costs fluctuate with crude oil volatility, compressing margin stability for mid-tier manufacturers without captive polymer supply.
- Chinese neoprene concentration:Triathlon wetsuit supply chains concentrate in East Asian manufacturing clusters, exposing brands to single-source risk and shipping cost surges.
- Limited thermal retention alternatives:No commercially scalable substitute for chloroprene rubber exists for open-water thermal protection, locking price structures to petrochemical input cycles.
Strategic Opportunities
- Reverse logistics infrastructure:California and New York extended producer responsibility frameworks create first-mover advantages for swimwear brands establishing material-recovery programs before mandate enforcement.
- Underwater rehabilitation protocols:Physical therapy clinics adopt fin-based resistance training for joint-safe aquatic exercise, expanding addressable demand beyond competitive swimming.
- Digital fitting technologies:3D body scanning and AI-driven size recommendation engines reduce return rates in direct-to-consumer channels, capturing margin lost to brick-and-mortar intermediation.
Industry Challenges
- Textile R&D talent scarcity:Polymer chemistry and hydrodynamic engineering expertise concentrates in legacy apparel hubs, forcing brands to relocate technical centers or absorb relocation premiums.
- ISO 8124 certification timelines:Children's flotation product safety testing creates 6-12 month market entry delays for innovative learning aids, ceding seasonal sales windows to established competitors.
- Multi-jurisdiction compliance layering:Simultaneous FDA latex oversight, EU REACH substance restrictions, and state-level chemical disclosure mandates fragment quality assurance protocols and inflate audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Gear Market |
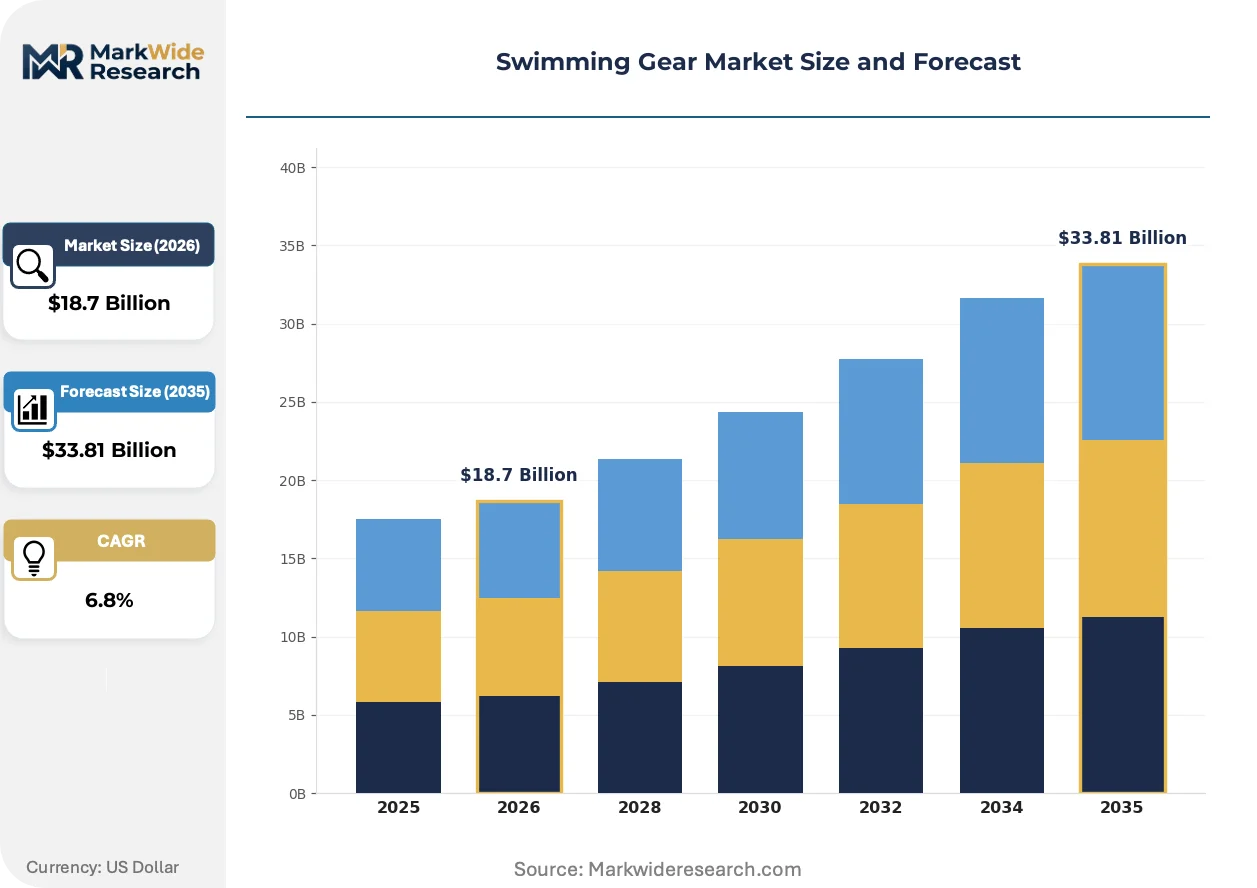
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swimsuits, Goggles, Caps, Fins End User: Adults, Children, Competitive Swimmers, Casual Swimmers Material: Polyester, Nylon, Latex, Neoprene Distribution Channel: Online Retail, Brick-and-Mortar Stores, Specialty Shops, Discount Stores |
| Companies Covered | FINIS, Aqua Sphere, Speedo, Adidas, Zoggs, Arena, Nike, Head, TYR Sport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Gear Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are rewriting competitive advantage in aquatic apparel. Hydrodynamic surface engineering, sustainable polymer substitution, and procurement channel restructuring define the current transformation cycle.
Bonded seam construction with ultrasonic welding is rewriting drag coefficient benchmarks in competitive swimsuit performance. Elite collegiate and masters swimmers adopt these suits for race-day use within 18-month replacement cycles. The technology compresses demand for traditional stitched constructions while elevating technical barriers to market entry.
EU REACH Annex XVII restrictions on N-nitrosamines in rubber accelerators are forcing latex-to-silicone transitions across cap and goggle strap formulations. Manufacturers serving European distribution channels reformulate product lines ahead of enforcement deadlines to maintain shelf access. Children's swim categories face the steepest compliance costs due to stricter skin-contact exposure limits.
Masters swimming clubs and rehabilitation centers now specify fin-based training equipment through group purchasing organizations rather than individual retail acquisition. This channel consolidation shifts volume toward specialized aquatic fitness distributors and away from general sporting goods retailers. Australia and Germany exhibit the fastest adoption of institutional procurement frameworks for age-group aquatic programming.
Swimming Gear Market Segmentation
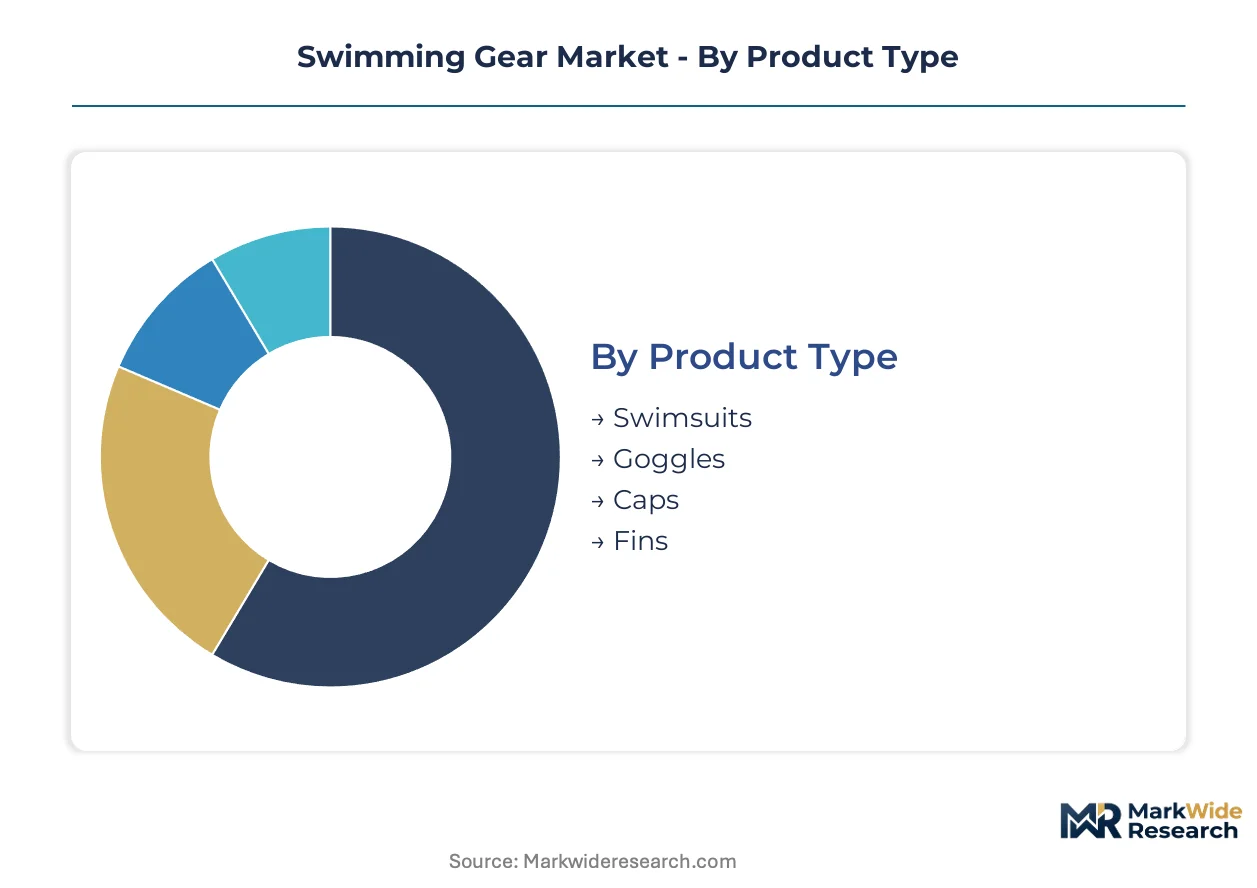
Segmentation in swimming gear tracks divergent performance requirements across competitive, recreational, and therapeutic use cases. Material chemistry and procurement channel selection determine margin capture and regulatory exposure for manufacturers.
Product Type:
Buyers prioritize hydrodynamic efficiency and durability based on training intensity and water chemistry exposure.
- Swimsuits:Bonded seam construction with ultrasonic welding reduces drag coefficients below 0.01 at race velocities. Competitive swimmers in the United States and Germany replace technical suits within 18-month cycles, compressing demand for stitched constructions.
- Goggles:Polycarbonate lenses with silicone gaskets maintain optical clarity across chlorine and saltwater chemistries. Masters swimmers and rehabilitation clinics in Australia drive specification for anti-fog coatings and prescription lens compatibility.
- Caps:Silicone formulations displace latex under EU REACH N-nitrosamine restrictions, with children's categories facing stricter skin-contact exposure limits.
- Fins:Underwater training methodologies proliferate in age-group and therapeutic programs.
Volume sits with swimsuits; growth tilts toward fins.
End User:
Customer lifetime value varies dramatically by replacement frequency and price elasticity.
- Competitive Swimmers:Institutional procurement through collegiate programs and club teams in the United States drives bulk contracts for performance suits and technical training equipment. FINA compliance requirements elevate technical barriers and sustain brand premiumization.
- Casual Swimmers:Price-sensitive demand concentrates in discount channels and seasonal retail, with polyester durability preferences overriding technical performance specifications.
- Adults:Masters swimming participation in Germany and Australia sustains replacement demand for durability-focused training gear.
- Children:ISO 8124 toy safety standards govern flotation and learning products, creating certification barriers for discount-channel imports.
Revenue concentrates with competitive swimmers; expansion accelerates among adults in age-group programming.
Material:
Thermal retention requirements and chemical resistance dictate formulation selection across open-water versus pool environments.
- Neoprene:Chloroprene rubber formulations dominate triathlon wetsuits and open-water thermal protection where no commercially scalable substitute exists. Australian and German triathlon participation locks price structures to petrochemical input cycles.
- Polyester:Recycled formulations displace virgin nylon in competitive swimsuit construction, preserving compressive fit properties while compressing material costs. Chlorine resistance and dye-substitution compatibility sustain dominance in pool-based categories.
- Nylon:Virgin feedstock costs fluctuate with crude oil volatility, compressing margin stability for mid-tier manufacturers.
- Latex:FDA oversight and EU REACH restrictions on rubber accelerators force reformulation toward silicone alternatives.
Procurement volume clusters around polyester; neoprene claims the steepest expansion trajectory in open-water applications.
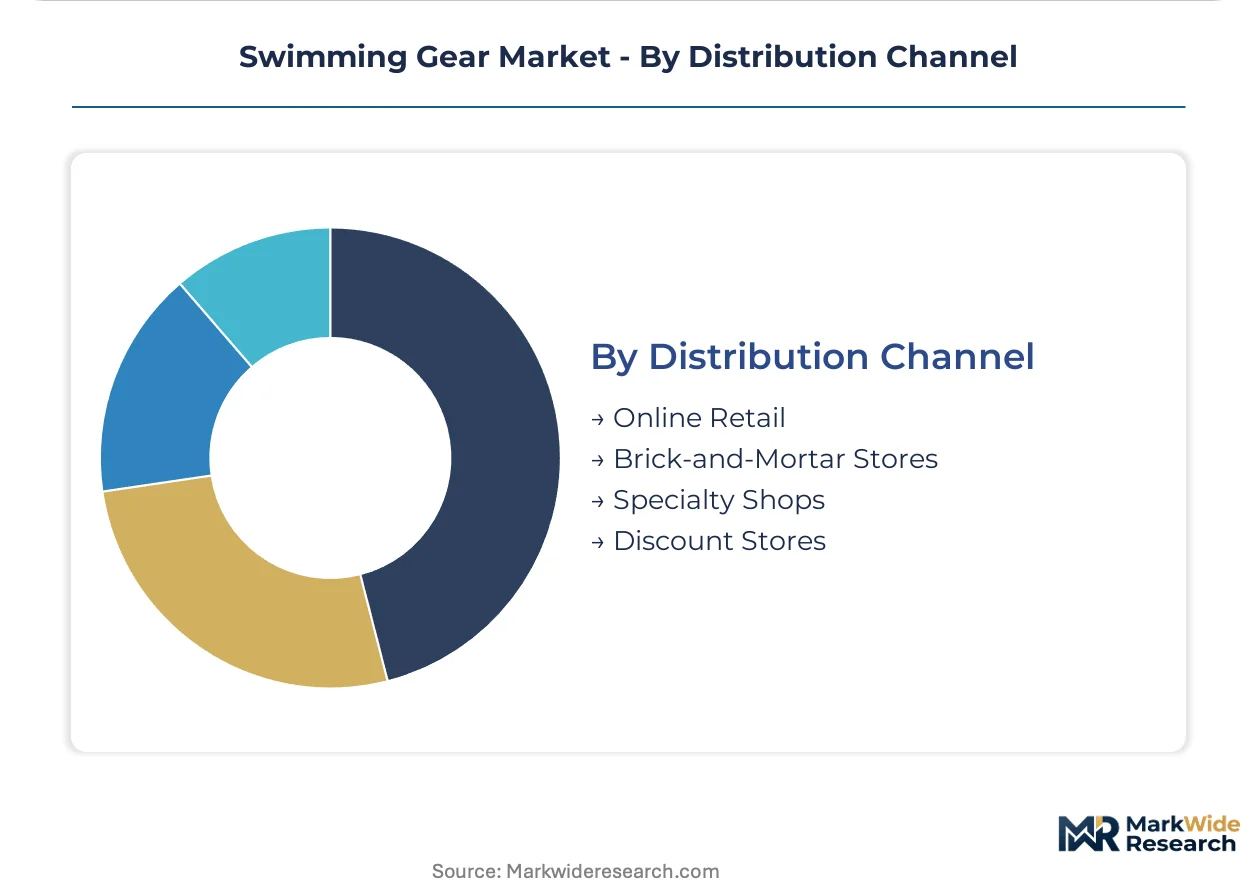
Distribution Channel:
Channel selection determines margin capture, return rates, and regulatory compliance exposure.
- Specialty Shops:Technical fitting services and FINA-compliant product knowledge sustain premium pricing for competitive swimmers. Masters clubs in Australia and Germany specify equipment through group purchasing organizations rather than individual retail acquisition.
- Online Retail:3D body scanning and AI-driven size recommendation engines reduce return rates, capturing margin lost to brick-and-mortar intermediation.
- Brick-and-Mortar Stores:General sporting goods retailers face volume erosion as institutional procurement consolidates.
- Discount Stores:Price-competitive casual swimmer demand concentrates here, with thinner margins and higher regulatory compliance risk on imported children's products.
Transaction volume flows through online retail; specialty shops defend the highest margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Australia, and Germany, where aquatic facility investment and masters swimming participation sustain replacement cycles for performance suits and technical training equipment.
United States
Collegiate swimming programs drive bulk procurement of FINA-compliant racing suits through institutional purchasing channels. The country's national consumer product safety regulator enforces flammability standards on children's flotation devices. California's extended producer responsibility framework threatens material-recovery obligations on swimwear brands without reverse-logistics infrastructure.
Germany
Masters swimming participation sustains replacement demand for durability-focused training gear among age-group competitors. ECHA REACH restrictions on N-nitrosamines in rubber accelerators force latex-to-silicone transitions in cap and goggle strap formulations. Bavaria's industrial textile clusters host specialized neoprene production for triathlon wetsuit manufacturers serving European distribution.
Australia
Masters clubs and rehabilitation centers specify fin-based training equipment through group purchasing organizations rather than individual retail acquisition. The country's therapeutic goods regulator oversees claims on aquatic fitness devices marketed for injury recovery. Melbourne and Sydney anchor the fastest adoption of institutional procurement frameworks for age-group aquatic programming.
China
Manufacturing concentration for neoprene and polyester textiles supplies global brand procurement with cost-competitive feedstock. The country's ministry of ecology and environment enforces dual carbon goals pressuring petrochemical-dependent fabric production. Guangdong and Zhejiang provinces cluster wetsuit and competitive swimsuit contract manufacturing for export markets.
United Kingdom
Competitive club swimming sustains demand for technical training equipment through regional aquatic center networks. The country's product safety regulator enforces toy safety standards on children's flotation and learning aids. London and the Southeast concentrate specialty retail distribution for premium competitive swim brands.
Swimming Gear Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with technical racing suits consolidating around heritage labels while training accessories fragment across price tiers. The vendor base organizes into three strategic archetypes: vertically integrated textile producers controlling polymer-to-garment supply, performance brands commanding FINA compliance premiums, and contract fabricators serving private-label discount channels. Competitive moves concentrate on backward integration into neoprene and recycled polyester production, plus geographic expansion into masters swimming growth markets.
Among heritage performance labels, Speedo and Arena exemplify the technical-premium archetype through captive textile R&D and European manufacturing bases. TYR Sport occupies a position within the collegiate procurement-focused tier, competing on price in bulk uniform contracts. These three entities represent distinct competitive vectors: textile innovation leadership, regional manufacturing anchoring, and institutional channel penetration.
| Leading Market Players |
|---|
| FINIS |
| Aqua Sphere |
| Speedo |
| Adidas |
| Zoggs |
| Arena |
| Nike |
| Head |
| TYR Sport |
| Others |
Value Chain & Pricing Dynamics
Captive textile production from polymer to finished garment anchors supply position and pricing power for heritage performance brands, insulating them from crude oil volatility while mid-tier competitors absorb feedstock cost swings without recourse.
Pricing Analysis
Volume concentrates in casual polyester swimsuits sold through discount channels, while margin pools in FINA-compliant racing suits where bonded seam construction and ultrasonic welding sustain three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and brand heritage, with competitive swimmers showing lowest sensitivity and casual swimmers highest. Cost compression in mid-tier nylon swimsuits is intensifying because virgin feedstock tracks crude oil cycles.
Supply Chain Analysis
Freight cost surges from East Asian manufacturing clusters have compressed margins for triathlon wetsuit brands dependent on Chinese neoprene concentration. Raw material flows draw from chloroprene rubber formulations in China, recycled polyester feedstock in Southeast Asia, and specialized textile R&D in Germany and Australia. Single-source vulnerability in neoprene supply chains threatens price stability. Distribution runs through institutional procurement channels for competitive gear and direct-to-consumer platforms for casual segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH Annex XVII restrictions on N-nitrosamines erect barrier-to-entry moats for silicone-capable incumbents while excluding latex-dependent discount entrants.
For Market Incumbents: Cement technical leadership by deepening backward integration into recycled polyester polymer production and securing captive neoprene supply agreements ahead of petrochemical input cycles. Defend against emerging private-label entrants by accelerating FINA pre-certification pipelines that lock collegiate procurement channels.
For New Entrants and Emerging Players: Rehabilitation clinics and physical therapy centers represent an underserved buyer archetype with institutional procurement frameworks still forming. Capture this white space through fin-based resistance training equipment bundled with clinician education programs, bypassing established competitive swimming distribution.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty retail consolidation and vertical textile platform roll-ups. Five-to-ten year viability favors brands with established reverse-logistics infrastructure ahead of California extended producer responsibility enforcement. Watch masters swimming participation rates in Germany and Australia as inflection indicators for durable training gear replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polyester | Captive polymer supply insulates margin from crude oil volatility and EU REACH compliance costs. |
| FINA Pre-Certification Pipeline Investment | Early technical validation locks collegiate and club procurement channels before seasonal allocation. |
| Reverse Logistics Infrastructure Buildout | Material-recovery programs defend California and New York market access ahead of mandate enforcement. |
| Rehabilitation Channel Partnership Program | Clinic-based specification of fin-based equipment expands addressable demand beyond competitive swimming. |
| Digital Fitting Technology Deployment | AI-driven size recommendation reduces direct-to-consumer return rates and captures brick-and-mortar margin. |
Study Parameters
Trade databases, ECHA regulatory filings, and collegiate athletic procurement records formed the secondary backbone, cross-referenced with primary interviews of textile R&D directors, aquatic facility procurement managers, masters swimming club organizers, and neoprene contract manufacturers. Bottom-up and top-down triangulation validated segment sizing across product categories.
Bottom-up unit economics and top-down macro demand drivers converged across the analysis window, with segmentation modeled by product type, material chemistry, end-user intensity, and distribution channel format. CAGRs derived from replacement cycle analysis, masters participation demographics, and regulatory transition timelines incorporating EU REACH enforcement schedules and state-level extended producer responsibility frameworks.
Revisions become necessary when petrochemical input cycles diverge from baseline assumptions or when extended producer responsibility mandates accelerate enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Starting Blocks Market
Sports Equipment
Football Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Riding Gear Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Surfboard Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Boxing Equipment Market