
 Smart Swim Goggles Market | 2026-2036
Smart Swim Goggles Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Swim Goggles Market Insights
Direct-to-consumer online channels is tilting away from traditional sporting-goods retail for smart swim goggles distribution. FORM Swim leverages its dedicated e-commerce platform to control pricing and customer data across North American markets. Arena anchors its position through specialty swim-shop partnerships that sustain brand authority among competitive athletes. Holoswim competes aggressively on Chinese domestic platforms, using live-stream commerce to convert fitness enthusiasts at lower acquisition cost.
Smart swim goggles integrate optical waveguide displays, waterproofed ARM-based chipsets, and biometric sensors into standard hydrodynamic lens housings to deliver real-time performance metrics without interrupting stroke mechanics. The primary commercial purpose is to replace post-session video analysis with instantaneous, heads-up feedback that tightens training loops for both amateur and elite swimmers. Wearable goggles and augmented reality goggles currently occupy the dominant revenue positions, while swim tracking goggles with GPS functionality represent the fastest-expanding margin pool as open-water triathlon participation broadens. Bluetooth connectivity and heads-up display technology lead R&D allocation, though heart rate monitoring modules are gaining engineering attention for integration into mid-range price tiers.
FCC certification governs radio-frequency emissions for all Bluetooth-enabled models sold in the United States, while CE marking and REACH compliance dictate material safety and electromagnetic standards across European markets. China's MIIT enforces network-access licensing for GPS-equipped variants, creating a fragmented regulatory entry path that favors manufacturers with regional compliance teams. Stakeholders must monitor evolving waterproofing IPX rating requirements from ISO and national consumer-safety bodies, as these standards increasingly incorporate battery-thermal management protocols that could disqualify existing designs from major markets.
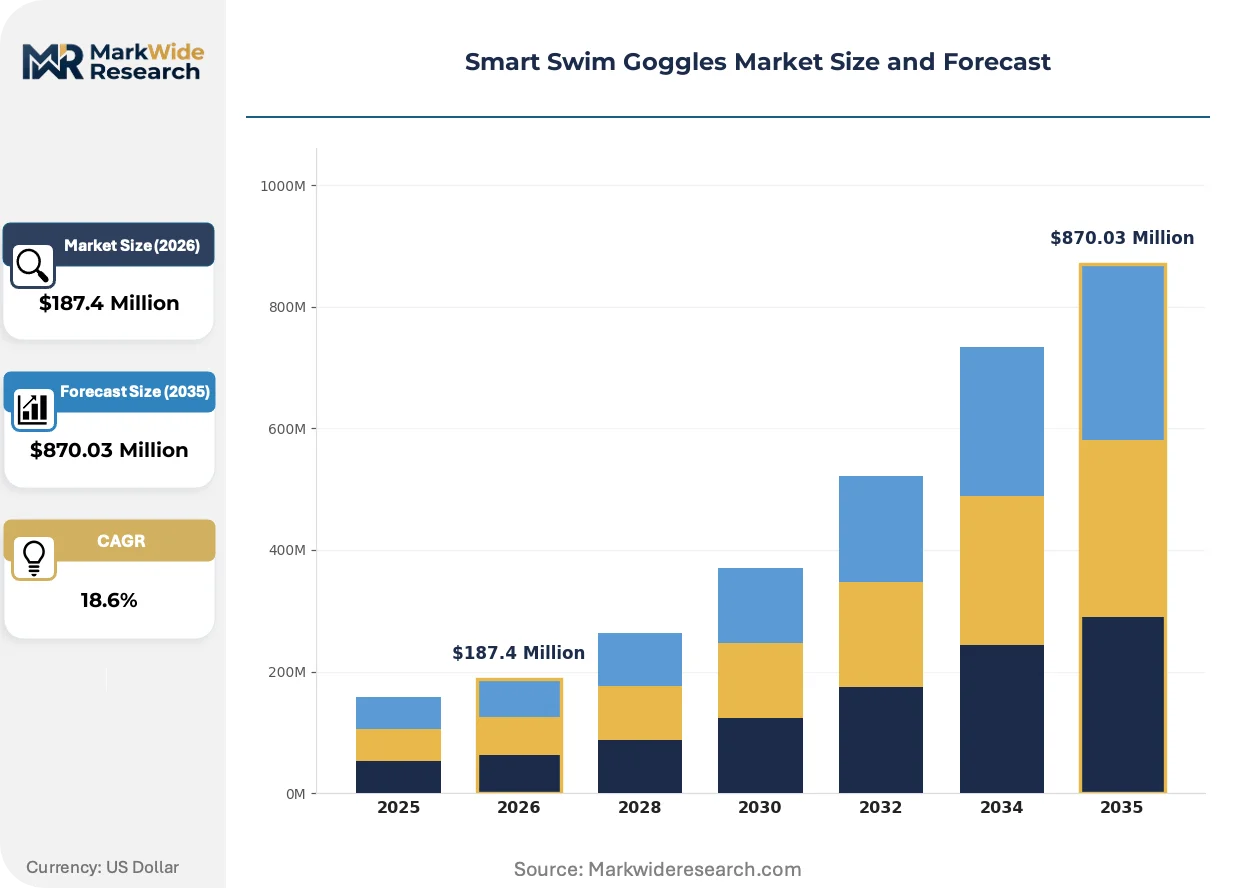
Market Dynamics
Waterproof micro-OLED display manufacturing advances from Taiwanese and South Korean component suppliers are compressing unit costs and enabling mass-market price points for augmented reality swim goggles. This supply-side concentration is reshaping competitive positioning between premium wearable brands and emerging mid-tier entrants.
Growth Catalysts
- Collegiate Competitive Swimming:University athletic programs in the United States are standardizing augmented reality goggles for stroke analysis, creating institutional procurement pipelines that validate consumer adoption.
- REACH Compliance Maturation:European material safety standards have stabilized, reducing regulatory uncertainty for manufacturers launching GPS-equipped variants across EU member states.
- Triathlon Participation Surge:Open-water endurance events in Germany and coastal China are generating demand for heads-up display metrics that replace wrist-worn devices.
Market Restraints
- Display Panel Supply Concentration:Micro-OLED fabrication depends on a narrow base of Taiwanese and South Korean foundries, exposing pricing volatility to regional semiconductor capacity constraints.
- Battery Thermal Management:IPX waterproofing ratings impose strict enclosure designs that limit heat dissipation, capping processing power for real-time biometric algorithms.
- MIIT Licensing Friction:China's network-access requirements for GPS-enabled models create six-to-nine month approval timelines that delay product launches versus Bluetooth-only variants.
Strategic Opportunities
- Municipal Aquatic Investment:German city governments are retrofitting public pools with lane-integrated timing systems that pair with consumer goggles, expanding the addressable base beyond private club members.
- Live-Stream Commerce Penetration:Chinese domestic platforms enable direct manufacturer-to-consumer conversion at lower acquisition cost than traditional sporting-goods retail.
- Heart Rate Module Convergence:Integration of photoplethysmography sensors with optical waveguide displays creates mid-range tier differentiation between basic lap-counters and full AR systems.
Industry Challenges
- Optical Engineering Talent Scarcity:Waveguide display calibration requires specialized photonics expertise that concentrates in South Korean and Taiwanese supplier ecosystems, limiting in-house R&D capabilities for Western brands.
- Multi-Regulatory Certification Overlap:Simultaneous FCC, CE marking, and MIIT compliance demands parallel testing tracks that extend product development cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Swim Goggles Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Goggles, Augmented Reality Goggles, Smart Sensors, Swim Tracking Goggles Technology: Bluetooth Connectivity, Heads-Up Display, GPS Tracking, Heart Rate Monitoring End User: Professional Athletes, Fitness Enthusiasts, Casual Swimmers, Coaches Price Tier: Premium, Mid-Range, Budget, High-End |
| Companies Covered | Speedo, Arena, FORM Swim, Aquasphere, Zoggs, FINIS, TYR, Magic5, Holoswim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Swim Goggles Market Trends and Innovations
Real-time biometric feedback is migrating from post-session analysis tools to instantaneous heads-up displays that tighten training loops for competitive and recreational swimmers. This shift is compressing the technology adoption cycle and redefining value propositions across price tiers.
Optical waveguide technology is migrating from military aviation applications to consumer swim goggles through scaled manufacturing partnerships with Taiwanese display foundries. Elite triathlon coaching programs in Germany and the United States are piloting these systems for open-water pacing guidance. The structural consequence is a price-performance curve that brings augmented reality displays within reach of mid-market fitness enthusiasts.
REACH and RoHS material safety frameworks in Europe are tightening disclosure requirements for battery thermal management compounds used in sealed waterproof housings. Manufacturers must now document full chemical supply chains for lithium-polymer cell assemblies. GPS-equipped variants face the steepest compliance burden, prompting some brands to delay European launches until certification pathways clarify.
Direct-to-consumer channels are displacing traditional sporting-goods retail for smart swim goggles distribution. FORM Swim's dedicated e-commerce platform and Holoswim's Chinese live-stream commerce demonstrate model viability. The United States and China exhibit the most pronounced channel bifurcation, with specialty swim shops retaining authority only among competitive athlete segments that demand fitting services.
Smart Swim Goggles Market Segmentation
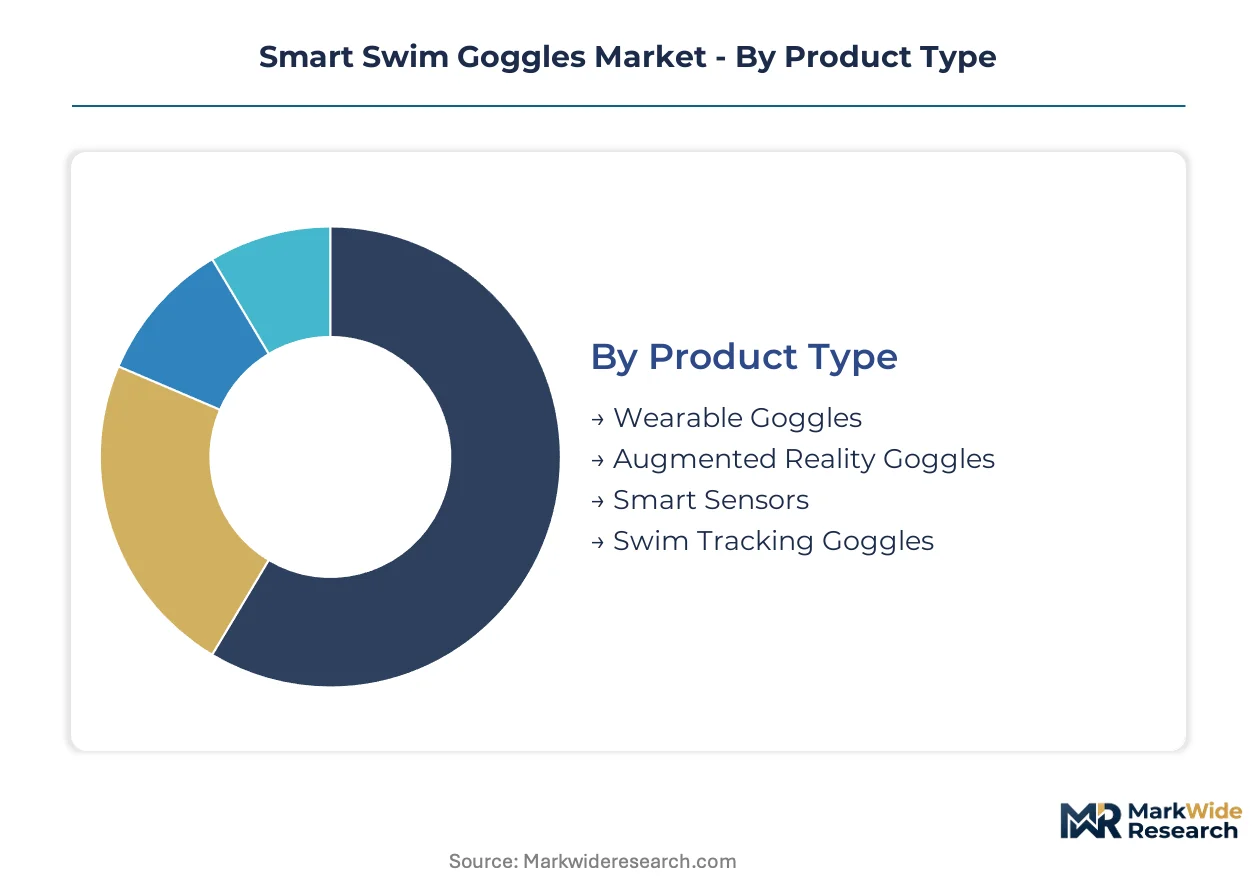
Smart swim goggles manufacturers calibrate warranty terms and replacement lens programs differently across hardware configurations. Optical waveguide displays demand specialized calibration services that reshape post-purchase support economics for premium tiers versus basic lap-counting models.
Product Type:
After-sales service intensity varies sharply by optical complexity, with augmented reality variants requiring firmware update subscriptions and waveguide recalibration that basic wearable goggles never trigger.
- Augmented Reality Goggles:Optical waveguide displays project real-time metrics directly into the swimmer's field of vision through transparent lens overlays. Demand concentrates among collegiate athletic programs in the United States seeking stroke-analysis feedback without interrupting training rhythm. The hardware-software integration demands ongoing calibration support that extends customer lifetime value beyond initial purchase.
- Wearable Goggles:Standard hydrodynamic housings incorporate biometric sensors and Bluetooth chipsets for post-session data sync. Fitness enthusiasts in Germany and coastal China drive procurement for open-water triathlon preparation where wrist-worn devices prove impractical. Simpler optical stacks reduce service touchpoints to battery replacement and strap hardware.
- Swim Tracking Goggles:GPS-enabled variants capture open-water route mapping and pace calculations through sealed antenna arrays. MIIT licensing requirements in China delay launches but create defensible positioning for compliant manufacturers.
- Smart Sensors:Modular clip-on units retrofit standard goggles with basic lap-counting and interval timing. Budget-conscious casual swimmers in municipal pool systems favor this entry point before upgrading to integrated displays.
By volume, wearable goggles lead. By growth pace, augmented reality goggles are expanding most quickly.
Technology:
Component cost tiers separate subscription-ready platforms from disposable electronics, with heads-up display modules commanding three to four times the BOM cost of basic Bluetooth chipsets.
- Heads-Up Display:Micro-OLED projection systems from Taiwanese foundries render split-time and stroke-rate data within the swimmer's natural sightline. German triathlon coaching programs pilot these systems for open-water pacing guidance where peripheral vision must remain unobstructed. Waterproofing IPX ratings constrain thermal design, limiting peak brightness to preserve battery longevity.
- Bluetooth Connectivity:Low-energy protocols synchronize session data to smartphone applications for post-workout analysis. FCC certification governs radio-frequency emissions for all United States market entrants, creating baseline compliance costs that favor scaled manufacturers.
- GPS Tracking:Multi-constellation receivers capture satellite positioning through sealed antenna housings for open-water route verification. China's network-access licensing imposes six-to-nine month approval timelines that disadvantage first-movers.
- Heart Rate Monitoring:Photoplethysmography sensors integrated into temple pads capture pulse data without chest straps. Engineering attention is concentrating on mid-range price tiers as manufacturers seek differentiation between basic lap-counters and full AR systems.
Bluetooth connectivity dominates unit economics through scale. Heads-up display technology is gaining share fastest as manufacturing yields improve.
End User:
Training intensity and data sophistication requirements create distinct purchasing workflows, with institutional procurement cycles stretching twelve to eighteen months longer than direct-to-consumer fitness channels.
- Professional Athletes:Olympic and national team programs specify custom firmware for stroke-specific metric calibration. United States collegiate swimming programs are standardizing augmented reality goggles, creating institutional validation that cascades to consumer segments.
- Coaches:Team management platforms demand multi-athlete dashboard integration and session comparison tools. Specialty swim shops retain authority in this segment through fitting services that direct-to-consumer channels cannot replicate.
- Fitness Enthusiasts:Triathlon participants in Germany and coastal China drive demand for GPS-equipped variants that replace wrist-worn devices in open-water conditions.
- Casual Swimmers:Municipal pool investment in lane-integrated timing systems expands addressable reach beyond private club membership in German city markets.
Fitness enthusiasts represent the largest addressable base. Professional athletes are climbing the fastest as collegiate procurement pipelines mature.
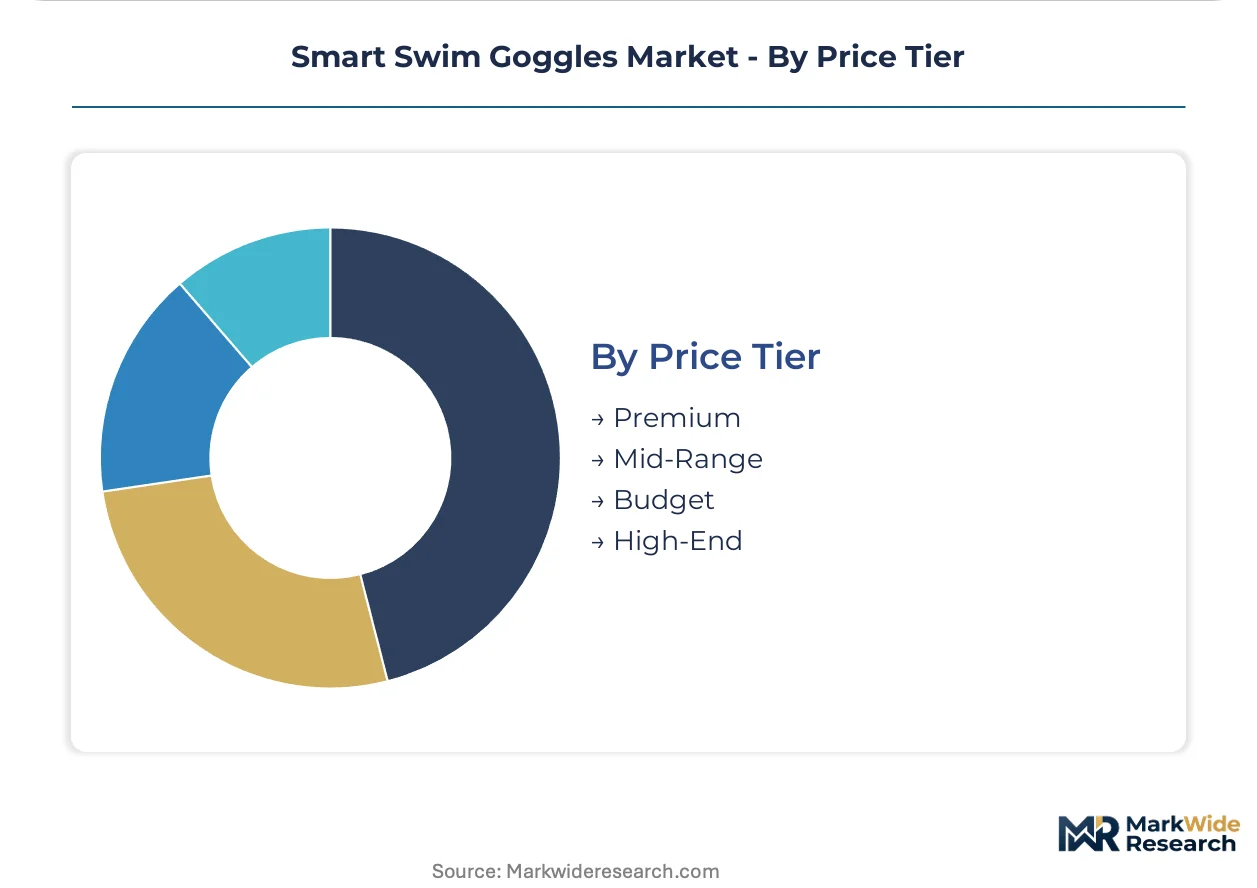
Price Tier:
Manufacturing yield curves and component sourcing strategies enable three distinct margin architectures that align with customer lifetime value projections.
- Premium:Full optical waveguide systems with integrated heart rate monitoring and GPS positioning target triathlon competitors and collegiate programs. South Korean and Taiwanese display supply concentration limits competitor entry.
- Mid-Range:Bluetooth-enabled biometric sensors with basic heads-up notification displays capture fitness enthusiasts seeking upgrade paths. Heart rate module convergence is creating differentiation opportunities against both flanks.
- High-End:Custom-fitted prescription lens integration and team-branded firmware configurations serve national federation contracts with extended service agreements.
- Budget:Basic lap-counting and interval timing through simple LED indicators address casual swimmers in emerging markets and municipal pool systems.
Mid-range tiers dominate unit shipment volume. Premium positioning is gaining share fastest as display costs compress and AR manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where triathlon participation and municipal aquatic investment sustain premium positioning, while Chinese manufacturers compete aggressively on domestic platforms at compressed margins.
United States
Collegiate swimming programs and open-water triathlon training drive institutional procurement pipelines. FCC certification governs radio-frequency emissions for all Bluetooth-enabled models, creating baseline compliance costs that favor scaled manufacturers. Greater Boston and Southern California host the densest concentration of competitive swimming programs piloting augmented reality goggles for stroke analysis.
Germany
Municipal aquatic facility investment and elite triathlon coaching programs generate sustained demand for GPS-equipped variants. REACH and RoHS material safety frameworks tighten disclosure requirements for battery thermal management compounds in sealed waterproof housings. Bavarian and North Rhine-Westphalian city governments are retrofitting public pools with lane-integrated timing systems that pair with consumer goggles.
China
Fitness enthusiasts in coastal provinces and live-stream commerce penetration create high-volume, lower-margin procurement channels. MIIT enforces network-access licensing for GPS-equipped variants, creating six-to-nine month approval timelines that disadvantage first-movers. Guangdong and Zhejiang provinces concentrate domestic platform distribution through manufacturer-direct live-stream commerce models.
South Korea
Component supply concentration in micro-OLED fabrication creates upstream pricing leverage for display foundries. Korean industrial standards and export certification protocols shape regional supply chain configurations. Seoul Capital Area foundries supply waterproof micro-OLED panels that compress unit costs for augmented reality goggle manufacturers worldwide.
Australia
Open-water swimming culture and triathlon participation sustain demand for GPS tracking functionality in coastal metropolitan markets. TGA medical device frameworks and consumer safety standards influence product registration pathways for biometric sensor integration. New South Wales and Queensland coastal cities represent the strongest addressable base for swim tracking goggles with open-water route verification.
Smart Swim Goggles Market Competitive Landscape
Established aquatic equipment specialists and dedicated wearable technology ventures split the market between brand authority and technical innovation. The vendor base concentrates around three strategic archetypes: heritage swim brands with retail distribution depth, pure-play smart wearable developers with direct-to-consumer platforms, and Asian electronics manufacturers leveraging component supply proximity. Competitive moves center on specialty retail partnerships for fitting services and live-stream commerce penetration for customer acquisition cost compression.
Within the heritage equipment tier, Speedo and Arena exemplify brand authority sustained through specialty swim-shop relationships that serve competitive athlete segments. FORM Swim occupies a position as the archetypal direct-to-consumer platform operator controlling pricing and customer data across North American markets. Holoswim represents the domestic Chinese platform specialist competing through live-stream commerce conversion at lower acquisition cost than traditional sporting-goods retail.
| Leading Market Players |
|---|
| Speedo |
| Arena |
| FORM Swim |
| Aquasphere |
| Zoggs |
| FINIS |
| TYR |
| Magic5 |
| Holoswim |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific air freight corridors from Seoul and Taipei to Los Angeles and Frankfurt carry waterproof micro-OLED display modules that constitute the dominant cost stack in augmented reality goggles, compressing margins for assemblers while enabling aggressive price positioning by brands with direct foundry relationships.
Pricing Analysis
The customization-premium spread separates prescription-lens configured orders from standard SKUs by roughly the cost of the optical waveguide module itself. Pricing stratifies across premium AR systems, mid-range biometric wearables, and economy lap-counting tiers, with FCC and MIIT certification grades acting as the primary price differentiation drivers. Pricing pressure stems from live-stream commerce penetration in China, where manufacturer-direct channels undercut traditional retail markups. Casual swimmers in municipal pool systems exhibit highest price sensitivity, while collegiate athletic programs demonstrate lowest sensitivity due to institutional procurement budgets.
Supply Chain Analysis
Export-control restrictions on advanced display fabrication equipment limit capacity expansion outside South Korea and Taiwan, concentrating supply leverage among incumbent foundries. Micro-OLED panels, ARM-based waterproof chipsets, and lithium-polymer thermal management compounds draw from South Korean, Taiwanese, and Chinese supplier bases respectively. Single-source vulnerability in waveguide calibration equipment creates chokepoint exposure for Western brands lacking in-house photonics capabilities. Distribution runs through direct-to-consumer platforms and specialty swim-shop partnerships, with channel bifurcation most pronounced in North American and Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock institutional buyers into validated supplier relationships.
For Market Incumbents: Entrench position by deepening backward integration into optical waveguide calibration capabilities, reducing dependency on Taiwanese and South Korean photonics specialists. Accelerate FCC pre-certification investments for next-generation Bluetooth protocols before emerging entrants can parallel-track approvals. Prioritize channel control through exclusive partnerships with collegiate athletic programs that generate multi-year procurement lock-in.
For New Entrants and Emerging Players: Pursue white-space opportunity in heart rate monitoring module convergence for mid-range price tiers, where engineering attention is concentrating but product-market fit remains unclaimed. Target German municipal aquatic facility retrofit programs, where lane-integrated timing system pairings create installed-base expansion potential. Deploy live-stream commerce go-to-market models to compress customer acquisition costs below traditional sporting-goods retail economics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated assemblers with captive display sourcing relationships and established multi-regulatory certification track records. Long-term viability over the next decade hinges on sustained IPX waterproofing standard evolution and battery thermal management protocol adaptation. Monitor MIIT licensing timeline compression as the critical inflection signal—accelerated approvals would erode first-mover advantage for compliant incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Waveguide Calibration Partnership | Secures photonics expertise from Taiwanese foundries that Western brands cannot replicate in-house. |
| Collegiate Athletic Program Standardization | Creates institutional validation pipelines that cascade consumer adoption through competitive swimming networks. |
| Live-Stream Commerce Platform Buildout | Enables manufacturer-direct conversion at acquisition costs below traditional sporting-goods retail in Chinese markets. |
| Multi-Regulatory Certification Parallel-Tracking | Compresses FCC, CE marking, and MIIT approval timelines that currently extend product development cycles. |
| Heart Rate Module Mid-Range Integration | Differentiates against basic lap-counters and full AR systems in the fastest-expanding price tier. |
Research Methodology
A standing panel of product managers at smart wearable developers, procurement leads at collegiate athletic programs, optical engineers at Taiwanese display foundries, and channel directors at specialty swim retailers provided ongoing calibration against secondary validation from MIIT licensing databases, FCC equipment authorization records, and EU REACH compliance filings. Bottom-up unit shipment estimates triangulated with top-down market sizing across hardware configuration tiers.
Scenario-bracketing around display yield improvement curves and regulatory approval timeline distributions anchored projections across the analysis window. Segmentation dimensions modeled include product type complexity, technology module integration, end-user training intensity, and price tier positioning. CAGRs derived from fitted adoption curves incorporating collegiate procurement pipeline maturation and open-water triathlon participation expansion as swim-specific demand drivers.
Sensitivities concentrate around micro-OLED foundry capacity allocation shifts and evolving IPX waterproofing standards that incorporate battery-thermal management protocols. Forecasts reflect assumptions on certification pathway stability and component cost compression trajectories. Material shifts in export-control regimes governing display fabrication equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Riding Gear Market
Sports Equipment
Diving Board Market
Sports Equipment
Crampon Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Trail Shoes Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Cycling Helmet Market