
 Buckwheat Seed Market | 2026-2036
Buckwheat Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Buckwheat Seed Market Outlook
Aftermarket seed treatment and custom seed coating services is reshaping margin pools in the buckwheat seed value chain, pulling profitability downstream from basic multiplication into增值 processing. Johnny's Selected Seeds leverages direct-to-grower digital channels to sustain premium pricing on heirloom and open-pollinated buckwheat lines. KWS anchors European breeding programs with proprietary hybridization protocols for Fagopyrum esculentum, while Minn-Dak Growers dominates North American contract production through tight control over identity-preserved supply chains.
Buckwheat seed comprises the dried, germinable caryopsis of Fagopyrum esculentum or Fagopyrum tataricum, typically exhibiting 12-14% moisture content at harvest and requiring after-ripening dormancy release before commercial sale; its primary commercial purpose centers on cover crop establishment, gluten-free grain production, and pollinator forage systems. Organic buckwheat commands structural premium pools due to three-year field history requirements and limited certified acreage, while raw buckwheat sustains volume leadership through bulk commodity channels into Eastern European milling and Asian soba noodle manufacturing. Roasted buckwheat competes as a fastest-growing value-added format within health food retail, though buckwheat flour concentrates margin capture among specialty millers serving celiac and low-glycemic diet formulations.
The USDA National Organic Program and EU Organic Regulation jointly enforce genetic integrity thresholds and prohibited substance lists that determine market access for certified buckwheat seed lots. China's GB seed standards and Russia's Federal Service for Veterinary and Phytosanitary Surveillance impose additional phytosanitary certification burdens on cross-border germplasm movement. Stakeholders must monitor evolving carbon accounting methodologies for cover crop crediting, as these frameworks will determine whether buckwheat's soil health benefits translate into premium-bearing climate-smart seed designations.
Market Dynamics
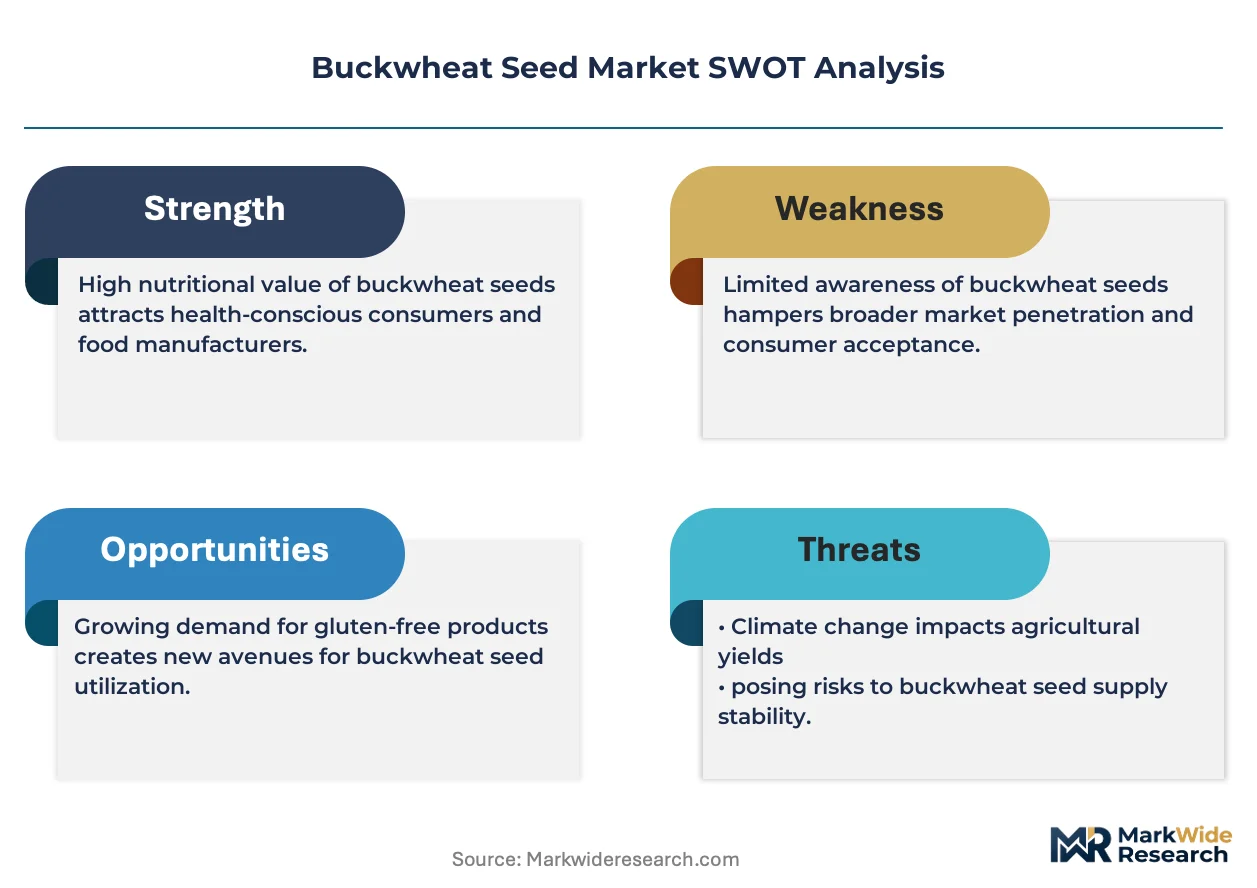
Seed certification requirements under the EU Organic Regulation and USDA National Organic Program are tightening genetic purity standards, forcing breeders to reconfigure multiplication protocols and pushing contract farming networks toward identity-preserved supply chains.
Growth Catalysts
- Gluten-free bakery expansion:Specialty flour millers in Poland and Ukraine are scaling contract acreage for food-grade buckwheat varieties, pulling seed demand through certified multiplication channels.
- EU Organic Regulation enforcement:Tighter genetic integrity thresholds for certified seed lots are creating structural premium pools for compliant breeders with established three-year field history documentation.
- Cover crop crediting frameworks:Emerging carbon accounting methodologies for soil health benefits are positioning buckwheat for climate-smart seed designations in North American sustainable agriculture programs.
Market Restraints
- After-ripening dormancy requirements:Buckwheat's 12-14% harvest moisture and mandatory dormancy release before commercial sale compresses working capital cycles for seed multiplication operations.
- Eastern European supply concentration:Deepening contract farming networks in Russia and Ukraine expose procurement channels to phytosanitary certification burdens from Federal Service for Veterinary and Phytosanitary Surveillance.
- Quinoa and amaranth substitution:Alternative pseudocereals with shorter multiplication cycles compete for gluten-free grain shelf space and cover crop rotations in premium organic segments.
Strategic Opportunities
- Roasted buckwheat value-addition:Health food retail channels in Germany and France are expanding shelf space for kasha-format products, creating pull-through demand for identity-preserved groat varieties.
- Direct-to-grower digital channels:Heirloom and open-pollinated line specialists are bypassing distributor markups through e-commerce platforms serving small-scale organic producers.
- Pollinator forage system integration:Apiary service providers in the US Midwest are specifying buckwheat in multi-species cover crop blends, opening non-commodity seed contract structures.
Industry Challenges
- Genetic purity verification timelines:Laboratory testing protocols for Fagopyrum esculentum cross-contamination extend seed lot release schedules, straining just-in-time planting logistics for cover crop contractors.
- Seed coating equipment capex:Custom treatment services for enhanced germination and early vigor require specialized pelleting infrastructure that smaller multiplication farms cannot amortize across limited buckwheat acreage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buckwheat Seed Market |
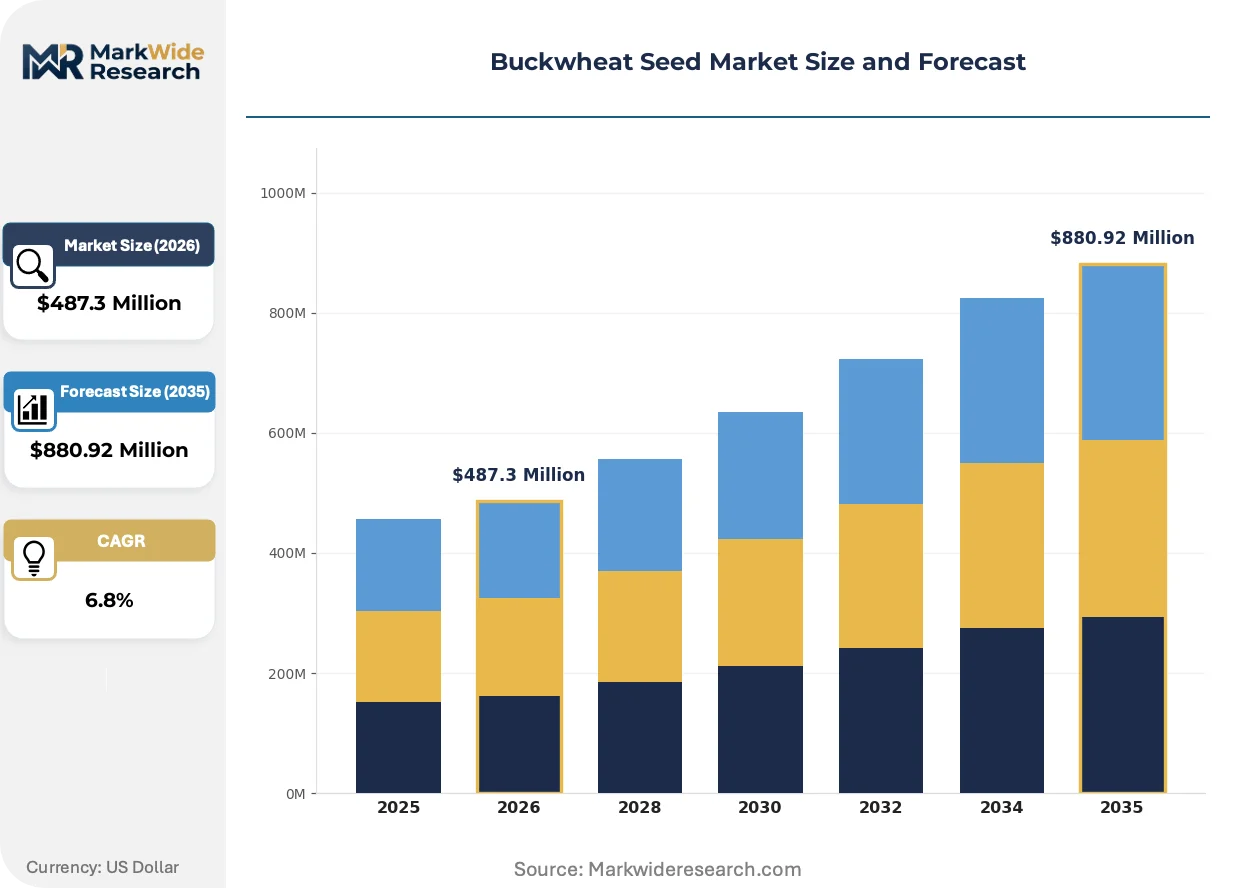
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Buckwheat, Organic Buckwheat, Roasted Buckwheat, Buckwheat Flour End Use Industry: Food & Beverage, Pharmaceuticals, Animal Feed, Cosmetics Packaging Type: Bags, Bulk Containers, Retail Packs, Sachets Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Wholesale Distributors |
| Companies Covered | Johnny's Selected Seeds, UFENAL ltd., West Coast Seeds, Johnston Seed Company, Ziegler Organic, Minn-Dak Growers, KWS, Great Basin Seed, High Mowing Seed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buckwheat Seed Market Strategic Shifts
Breeding protocols and downstream processing formats are converging to reshape margin capture across the buckwheat seed value chain, with digital distribution and regulatory compliance emerging as decisive competitive differentiators.
Proprietary hybridization protocols for Fagopyrum esculentum are hybridizing open-pollinated line dominance in European breeding programs. KWS and continental research stations are deploying controlled crossbreeding systems to capture heterosis effects previously unavailable in self-incompatible buckwheat germplasm. This technology is hybridizing competitive positioning between heritage seed preservationists and yield-focused commodity suppliers.
REACH and EU Green Deal sustainability reporting obligations are extending chemical scrutiny to seed treatment formulations used in organic multiplication. The European Chemicals Agency is tightening substance authorization timelines for conventional fungicide coatings, compelling treatment service providers to reformulate with approved biological alternatives. Certified organic seed lots face the steepest compliance burden, as prohibited substance lists now encompass legacy treatment residues in soil and equipment.
Buyer concentration among specialty millers is compressing traditional wholesale distribution layers in gluten-free supply chains. Large-scale bakery cooperatives in Poland and Ukraine are negotiating direct varietal specification with multiplication farms, displacing commodity traders who previously aggregated undifferentiated seed lots. This channel restructuring is most visible in Eastern European contract farming networks where identity-preserved documentation commands measurable premium capture over bulk commodity channels.
Buckwheat Seed Market Segmentation
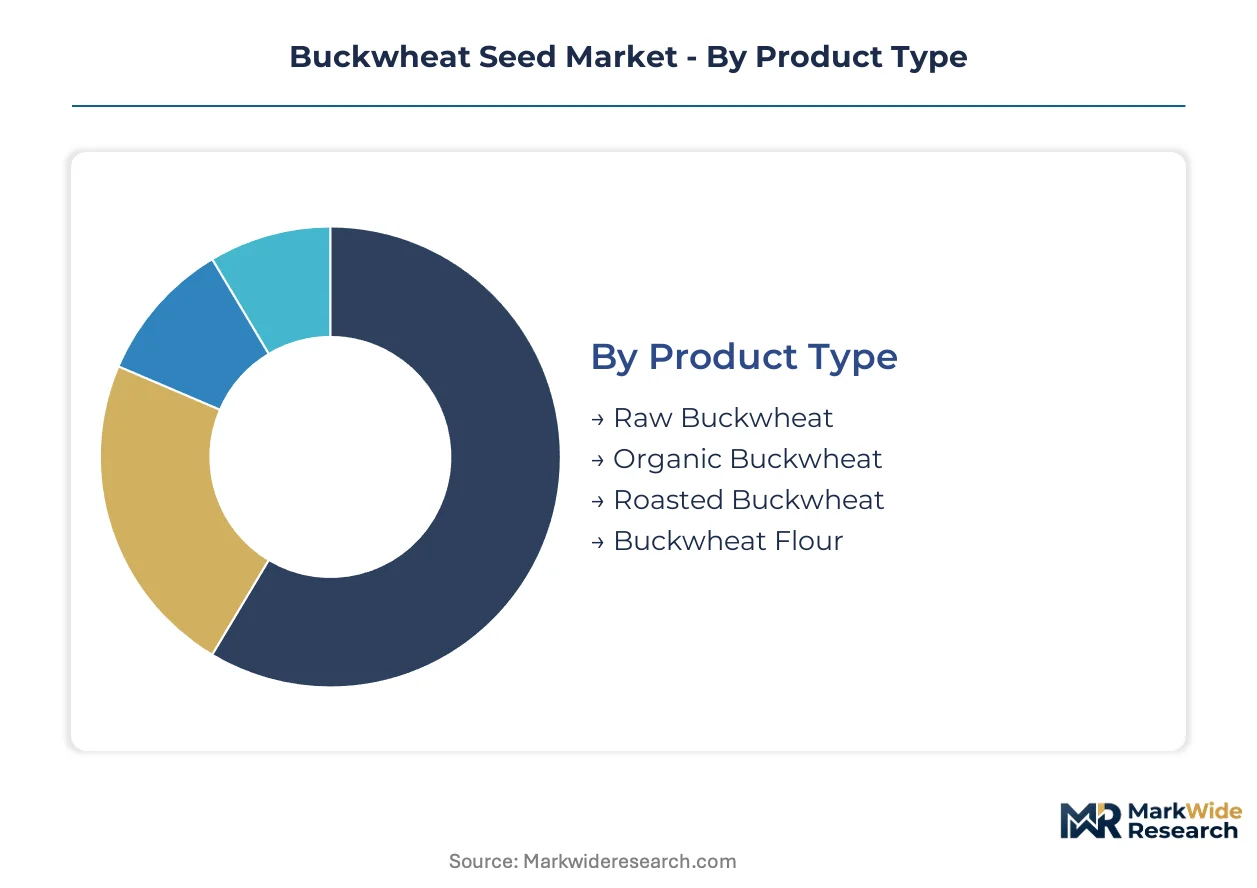
Buckwheat seed markets stratify sharply across product form and channel structure, with certification tiers and processing depth determining margin capture. Channel configuration varies dramatically by end-use, from commodity bulk flows into Eastern European milling to precision retail packs for gluten-free consumers.
Product Type:
Cycle times stretch from immediate-sale raw grain to multi-year organic certification pipelines, with processed formats commanding working capital premiums proportionate to their value-add intensity.
- Raw Buckwheat:Harvested caryopsis at 12-14% moisture content moves directly into bulk commodity channels. Eastern European millers in Poland and Ukraine dominate procurement through contract farming networks, though phytosanitary certification burdens from Russia's Federal Service for Veterinary and Phytosanitary Surveillance constrain cross-border germplasm velocity.
- Organic Buckwheat:Three-year field history requirements and limited certified acreage create structural premium pools. USDA National Organic Program and EU Organic Regulation enforcement tightens genetic integrity thresholds, forcing breeders to reconfigure multiplication protocols and document prohibited substance compliance across equipment and soil.
- Roasted Buckwheat:Thermal processing for kasha-format products targets health food retail in Germany and France.
- Buckwheat Flour:Milled product concentrates margin capture among specialty millers serving celiac and low-glycemic diet formulations.
Raw buckwheat anchors the volume base while organic buckwheat gains share at the steepest rate.
End Use Industry:
Application intensity ranges from mass-volume food processing to precision pharmaceutical extraction, with regulatory burden scaling inversely to throughput.
- Food & Beverage:Soba noodle manufacturing in Asia and gluten-free bakery expansion in Europe pull seed demand through certified multiplication channels. Specialty flour millers scale contract acreage for food-grade varieties, with identity-preserved documentation commanding measurable premium capture over bulk commodity flows.
- Pharmaceuticals:Rutin and quercetin extraction requires high-purity germplasm with verified active compound profiles. Laboratory testing protocols for Fagopyrum esculentum cross-contamination extend seed lot release schedules, straining just-in-time logistics for cover crop contractors.
- Animal Feed:Protein-rich groat byproducts serve poultry and aquaculture formulations.
- Cosmetics:Buckwheat-derived antioxidants appear in dermal care applications with niche volume contribution.
Food and beverage absorbs the dominant procurement volume while pharmaceutical applications expand most quickly on margin per ton.
Packaging Type:
Unit economics invert between infrastructure-heavy bulk handling and high-touch retail fulfillment, with mid-scale bag formats capturing farmer-direct and small-miller demand.
- Bags:Standard woven polypropylene units serve farm-supply and small-miller procurement with moderate handling efficiency.
- Bulk Containers:Intermodal tank and hopper systems minimize per-unit logistics cost for identity-preserved supply chains into large-scale bakery cooperatives.
- Retail Packs:Consumer-facing formats with brand differentiation and usage instructions command shelf-space premiums in health food channels.
- Sachets:Single-serve and sample configurations support trial conversion and direct-to-grower digital channel fulfillment.
Bulk containers dominate tonnage throughput while retail packs climb the fastest on value per kilogram.
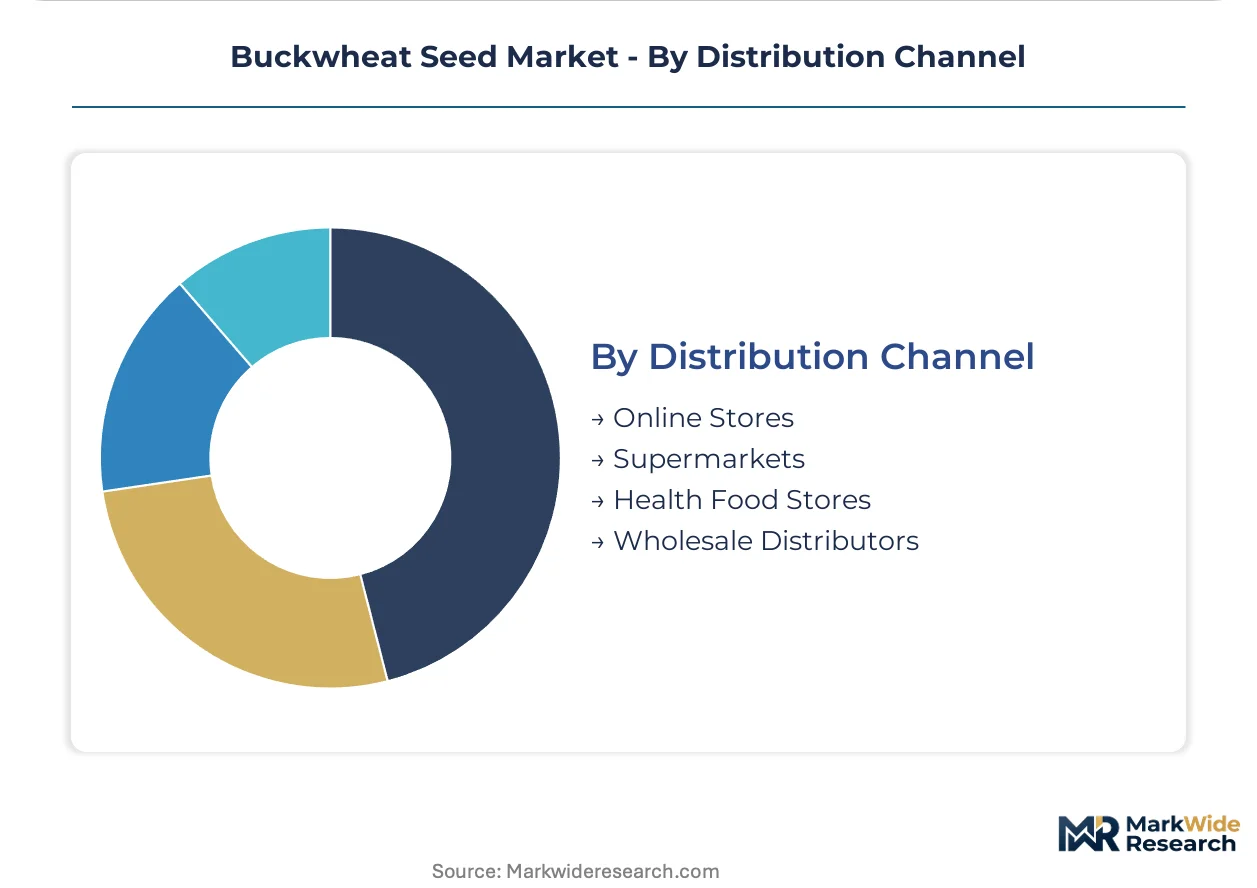
Distribution Channel:
Channel control determines margin retention, with disintermediation pressures strongest where buyer concentration enables direct varietal specification.
- Online Stores:Direct-to-grower digital channels enable heirloom and open-pollinated line specialists to bypass distributor markups. E-commerce platforms serving small-scale organic producers sustain premium pricing through varietal transparency and planting guidance content.
- Supermarkets:Mass retail shelf space for roasted buckwheat and flour formats concentrates negotiation leverage among consolidated grocery chains.
- Health Food Stores:Curated product assortments in Germany and France expand kasha-format visibility with educated consumer demographics.
- Wholesale Distributors:Traditional aggregation layers face compression as large-scale bakery cooperatives negotiate direct multiplication farm contracts.
Wholesale distributors retain the broadest geographic coverage while online stores achieve the steepest expansion trajectory on margin capture efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland consumes buckwheat seed primarily for gluten-free milling, while Russia deploys it for cover crop rotations and pollinator forage, creating divergent procurement specifications across Eastern European supply basins.
Poland
Specialty flour millers in Łódź and Kraków are scaling contract acreage for food-grade buckwheat varieties. EU Organic Regulation enforcement tightens genetic integrity thresholds for certified seed lots entering Polish multiplication channels. The Greater Poland Voivodeship hosts deepening contract farming networks where identity-preserved documentation commands measurable premium capture over bulk commodity flows.
Russia
Federal Service for Veterinary and Phytosanitary Surveillance imposes phytosanitary certification burdens on cross-border germplasm movement into cover crop establishment programs. The Central Federal District around Moscow concentrates procurement gravity for pollinator forage systems serving apiary service providers. Rostov Oblast multiplication farms face extended seed lot release schedules due to laboratory testing protocols for Fagopyrum esculentum cross-contamination verification.
Ukraine
Large-scale bakery cooperatives in Lviv and Kyiv oblasts negotiate direct varietal specification with multiplication farms, displacing commodity traders who previously aggregated undifferentiated seed lots. The country's national agricultural regulator maintains seed certification requirements that align with EU Organic Regulation genetic purity standards. Dnipropetrovsk Oblast contract farming networks are deepening for both cover crop and food-grade buckwheat production.
Germany
Health food retail channels in Berlin and Munich expand shelf space for kasha-format roasted buckwheat products, creating pull-through demand for identity-preserved groat varieties. REACH and EU Green Deal sustainability reporting obligations extend chemical scrutiny to seed treatment formulations used in organic multiplication. Bavaria hosts breeding programs deploying proprietary hybridization protocols for Fagopyrum esculentum to capture heterosis effects.
United States
USDA National Organic Program enforcement tightens genetic integrity thresholds for certified buckwheat seed lots entering gluten-free bakery supply chains. The Midwest region concentrates apiary service providers specifying buckwheat in multi-species cover crop blends. North Dakota contract production networks dominate through tight control over identity-preserved supply chains for food-grade and cover crop varieties.
Buckwheat Seed Market Competitive Environment
Capability concentration sits with heritage preservation specialists; scale advantage sits with commodity multiplication networks. The vendor base stratifies across three tiers: direct-to-grower digital channel operators, continental breeding program anchors, and contract production aggregators. Two strategic archetypes dominate competitive positioning—heirloom line preservationists leveraging e-commerce transparency, and yield-focused suppliers deploying controlled crossbreeding systems. M&A activity concentrates among seed coating service providers, while portfolio diversification drives expansion into roasted buckwheat value-added formats.
Among North American direct-to-grower specialists, Johnny's Selected Seeds and Minn-Dak Growers occupy positions at opposite ends of the supply chain control spectrum. Johnny's Selected Seeds exemplifies the heritage preservation archetype through digital channel reach. Minn-Dak Growers represents contract production aggregation with tight identity-preserved supply chain management. KWS anchors the European breeding program tier with proprietary hybridization protocol development.
| Leading Market Players |
|---|
| Johnny's Selected Seeds |
| UFENAL ltd. |
| West Coast Seeds |
| Johnston Seed Company |
| Ziegler Organic |
| Minn-Dak Growers |
| KWS |
| Great Basin Seed |
| High Mowing Seed Company |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in certified organic multiplication networks across Poland and Ukraine is forcing buyers into longer contract windows and premium prepayment structures. This utilization squeeze simultaneously elevates supplier bargaining power and compresses margin recovery for downstream millers caught between fixed-price bakery offtake agreements and escalating seed input costs.
Pricing Analysis
Long-term offtake contracts dominate procurement between Eastern European multiplication farms and large-scale bakery cooperatives, though spot market liquidity persists for undifferentiated raw buckwheat into Asian soba manufacturing. Price differentiation rests on EU Organic Regulation certification tier and identity-preserved documentation depth, with three-year field history verification commanding substantial premia over conventional commodity grades. Pricing pressure stems from quinoa and amaranth substitution in gluten-free formulations, forcing buckwheat suppliers to absorb certification compliance costs rather than pass through to price-sensitive conventional millers. Contract bakery channels exhibit lowest price sensitivity due to formulation lock-in requirements, while spot-traded commodity flows face acute margin compression from alternative pseudocereal competition.
Supply Chain Analysis
Extended payment terms from German health food retailers are cascading upstream through supply-chain finance facilities, straining working capital for Polish multiplication farms already burdened by after-ripening dormancy inventory holds. Geographic supply concentration centers on Poland, Russia, and Ukraine for food-grade germplasm, with North Dakota contract production networks serving North American cover crop demand. Raw material dependencies include certified foundation seed stocks, organic-approved biological treatment formulations, and specialized pelleting equipment for enhanced germination. Single-source vulnerability runs through Russia's Federal Service for Veterinary and Phytosanitary Surveillance phytosanitary certification bottlenecks. Distribution runs through direct-to-grower digital channels for heirloom lines and bulk intermodal systems for identity-preserved commodity flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting methodologies for cover crop crediting represent a technological-regulatory inflection that will restructure premium capture across the buckwheat seed value chain. Early positioning in climate-smart seed designation protocols will determine competitive viability as sustainable agriculture programs mature.
For Market Incumbents: Harden genetic purity verification infrastructure against tightening USDA National Organic Program and EU Organic Regulation thresholds. Invest in in-house seed coating capacity to capture margin pools shifting downstream from basic multiplication into增值 processing services. Quinoa substitution in gluten-free bakery formulations demands defensive certification investment to maintain varietal specification lock-in with large-scale cooperatives.
For New Entrants and Emerging Players: Build out direct-to-grower digital channels targeting small-scale organic producers in the US Midwest apiary service segment. Pollinator forage system integration offers the most penetrable white-space entry point, with non-commodity contract structures bypassing established commodity trader aggregation layers. Lead with varietal transparency content and planting guidance to differentiate against opaque bulk seed offerings.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among seed coating service providers with captive treatment infrastructure and multi-year organic multiplication contracts. Long-term viability over a five-to-ten-year window favors targets with established three-year field history documentation and EU Organic Regulation compliance track records. Monitor carbon credit verification protocol adoption rates as the decisive inflection signal for climate-smart seed premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Hybridization Protocol Development | KWS and Bavarian research stations capture heterosis effects previously unavailable in self-incompatible buckwheat germplasm. |
| Direct-to-Grower Digital Channel Expansion | Johnny's Selected Seeds sustains premium pricing through varietal transparency and planting guidance content. |
| Identity-Preserved Supply Chain Control | Minn-Dak Growers dominates North American contract production through tight documentation and lot segregation infrastructure. |
| Biological Seed Treatment Reformulation | REACH and EU Green Deal obligations compel coating providers to replace legacy fungicides with approved organic alternatives. |
| Roasted Buckwheat Value-Addition | German and French health food retail expansion creates pull-through demand for kasha-format groat varieties. |
Study Parameters
A standing panel of seed multiplication farm operators, specialty flour miller procurement directors, EU Organic Regulation compliance officers, and apiary service providers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation against USDA National Organic Program filings, EU Organic Regulation enforcement bulletins, customs trade data for buckwheat germplasm flows, and REACH substance authorization timelines. Bottom-up acreage and yield modeling triangulated against top-down bakery cooperative procurement disclosures and health food retail channel expansion announcements.
Scenario-bracketing around carbon credit verification adoption rates, phytosanitary certification disruption severity, and quinoa substitution elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form (raw, organic, roasted, flour), end-use application (food and beverage, pharmaceuticals, animal feed, cosmetics), packaging configuration, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints, with specific weighting for cover crop crediting framework maturation and EU Green Deal sustainability reporting obligation implementation timelines.
Stress conditions across Federal Service for Veterinary and Phytosanitary Surveillance enforcement intensity, alternative pseudocereal price competitiveness, and organic certification acreage expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume documented regulatory trajectories and technology adoption curves. Macroeconomic contraction, abrupt regulatory reversal, or breakthrough synthetic biology substitution for rutin extraction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Cotton Seed Treatment Market
Seeds
Custom Selected Seed Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Mexico Seed Market
Seeds
Europe Flaxseeds Market
Seeds
Africa Sorghum Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Asia-Pacific Seed Market
Seeds
Rapeseed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Wax Gourd Seed Market
Seeds
Ghana Seeds Market
Seeds
Mustard Seeds Market
Seeds
India Seed Market
Seeds
Europe Amaranth Market