
 Europe Cannabis Seeds Market | 2026-2036
Europe Cannabis Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cannabis Seeds Market Foresight
Specialty seed banks across Amsterdam, Barcelona, and Berlin is rewriting how European growers access certified genetics. Sensi Seeds leverages decades of stabilized breeding lines to anchor Netherlands-based distribution. Royal Queen Seeds competes through direct-to-consumer platforms that bypass traditional wholesale tiers. Dutch Passion differentiates by maintaining feminized seed lines with documented cannabinoid profiles for medical registrants.
Cannabis seeds are botanically classified as dormant embryonic plants encased in protective testa, requiring controlled humidity below 9% and darkness for viable long-term storage; their commercial purpose centers on enabling reproducible cultivation of chemotype-specific cannabis plants for regulated medical and adult-use supply chains. Feminized seeds command the dominant position in value terms due to elimination of male plant culling and labor cost savings in commercial greenhouses. Autoflowering varieties represent the fastest-expanding grade pool as northern European outdoor growers seek harvest independence from photoperiod constraints.
EMA guidelines on cannabis-based medicinal products and the EU Green Deal's sustainable agriculture mandates together shape seed certification requirements across member states. Germany's BfArM cannabis agency enforces strict batch traceability that filters which seed suppliers gain pharmacy-channel access. France's ANSM maintains tighter THC thresholds for hemp-derived seeds than most neighbors, fragmenting product eligibility. Stakeholders must track how the European Commission's ongoing Novel Food and cosmetics deliberations recalibrate the boundary between hemp and narcotic cannabis classifications.
Market Dynamics
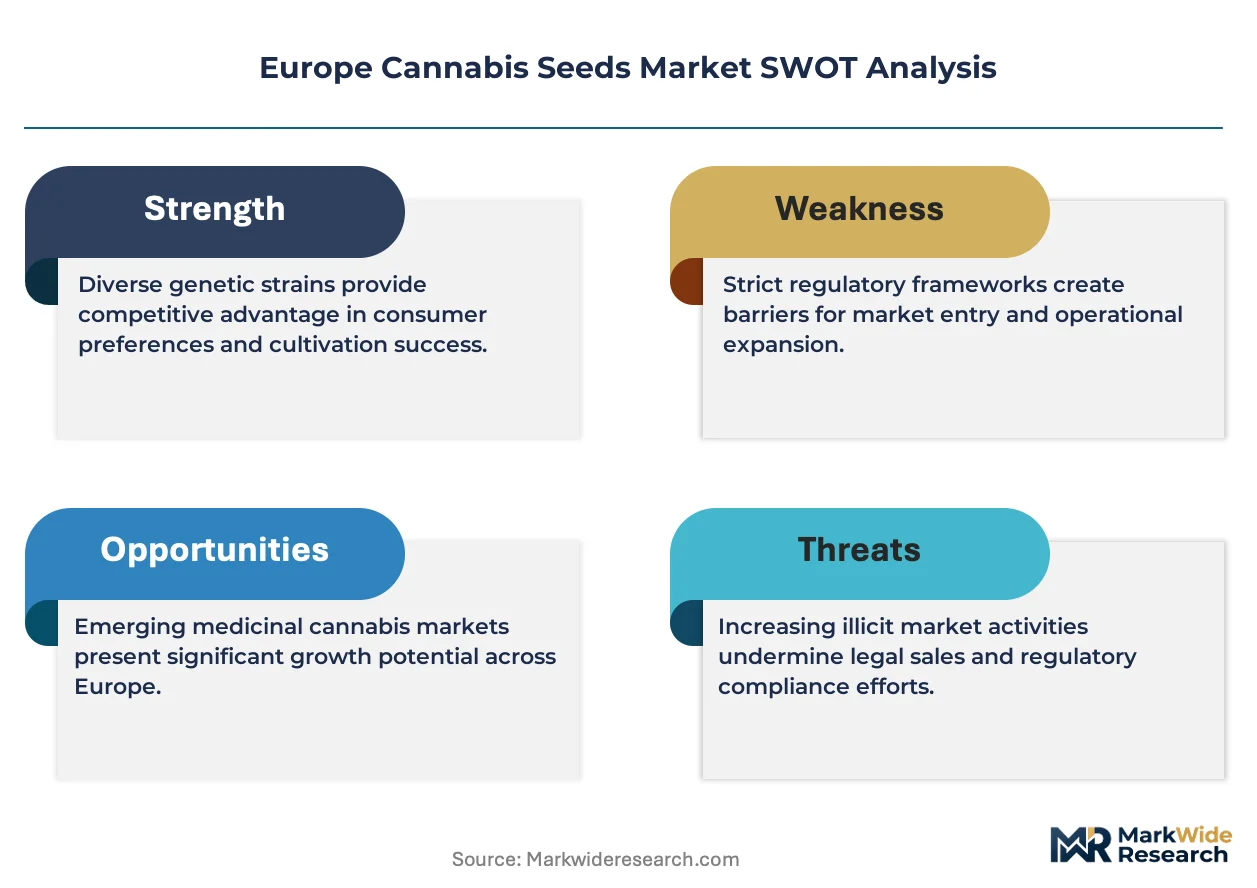
Cross-border seed commerce is accelerating as the EU Court of Justice ruling on CBD trade dismantles national barriers that previously fragmented distribution networks across member states.
Growth Catalysts
- EMA Guidelines:The European Medicines Agency's cannabis-based medicinal products framework is standardizing quality benchmarks that certified seed suppliers leverage for pharmacy-channel entry.
- Photoperiod Independence:Autoflowering genetics eliminate seasonal cultivation constraints, enabling outdoor harvests in Nordic latitudes previously unsuitable for cannabis agriculture.
- Germany:Europe's largest federally regulated medical cannabis market is scaling licensed cultivation capacity, driving bulk procurement of documented chemotype seed lines.
Market Restraints
- Batch Traceability Costs:Germany's BfArM mandates force seed suppliers to absorb expensive genetic documentation systems that smaller breeders cannot finance.
- THC Threshold Fragmentation:France's ANSM maintains stricter hemp-derived seed limits than neighboring jurisdictions, forcing product line bifurcation.
- Controlled Humidity Infrastructure:Long-term viability requires sub-9% humidity storage facilities that concentrate distribution among capitalized operators.
Strategic Opportunities
- Spain:Barcelona's established cultivation culture and tolerant policy environment position the region for adult-use seed market expansion pending federal reform.
- EU Green Deal:Sustainable agriculture mandates create certification premiums for organic seed production methods that differentiate suppliers.
- Direct-to-Consumer Platforms:E-commerce channels are bypassing traditional wholesale tiers, compressing margin extraction by intermediary distributors.
Industry Challenges
- Genetic Stabilization Expertise:Qualified cannabis breeders capable of maintaining chemotype consistency across generations remain scarce relative to demand.
- Novel Food Classification Uncertainty:Ongoing European Commission deliberations on hemp-derived product boundaries create inventory risk for seed banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cannabis Seeds Market |
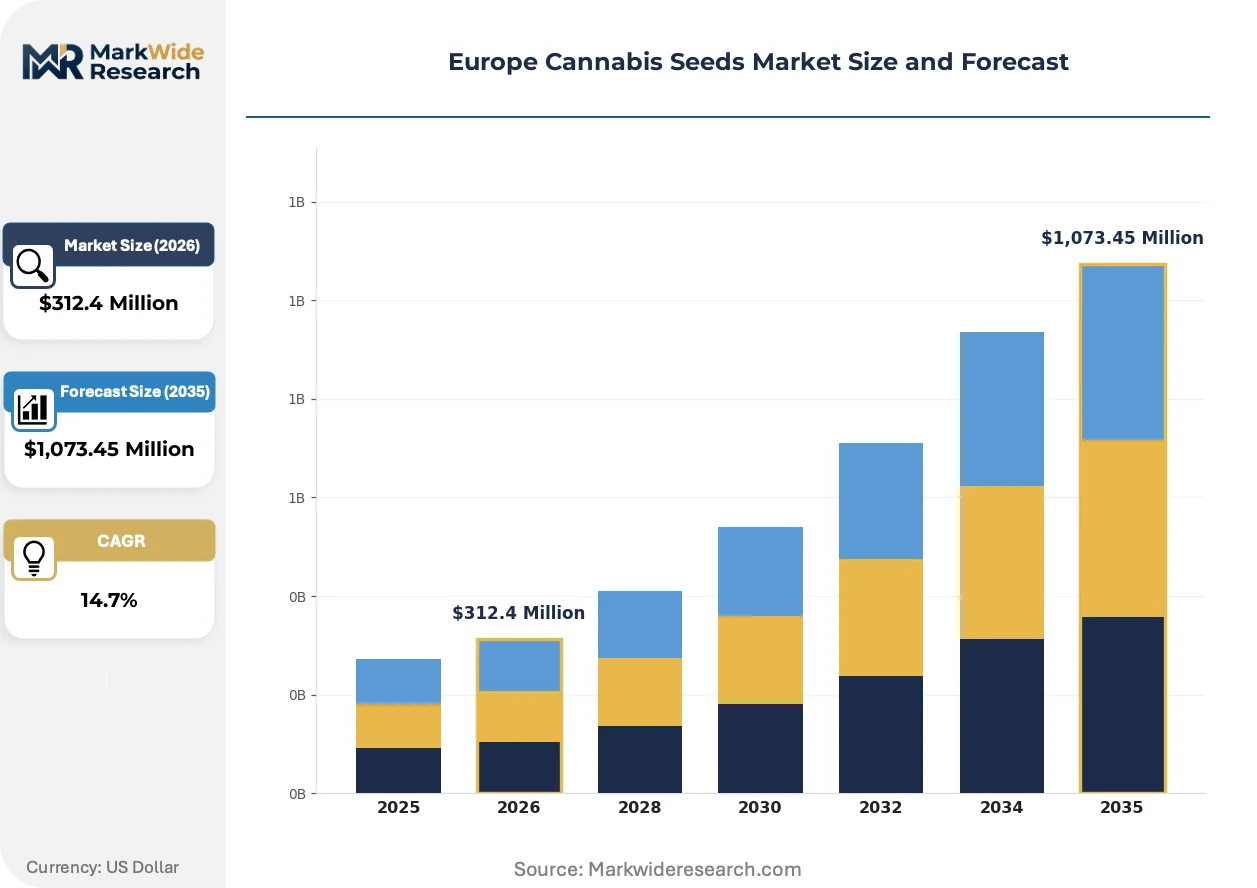
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feminized Seeds, Autoflowering Seeds, Regular Seeds, Medical Seeds Grade: Standard Grade, Premium Grade, Organic Grade, High THC Grade End Use: Medical Use, Recreational Use, Research, Industrial Use Distribution Channel: Online Retail, Specialty Stores, Dispensaries, Wholesale |
| Companies Covered | Sensi Seeds, Royal Queen Seeds, Dutch Passion, Barney's Farm, Green House Seeds, Paradise Seeds, Fast Buds, Blimburn Seeds, Zamnesia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cannabis Seeds Market Shifts & Advancements
Genetic documentation and digital traceability systems are transforming how European cultivators verify seed provenance, compressing information asymmetries between breeders and commercial buyers.
Blockchain-based seed certification is digitizing the chain of custody for genetic material. Dutch and German licensed cultivators are adopting these platforms to satisfy BfArM audit requirements. The technology is digitizing what previously required paper-based batch records and third-party laboratory verification.
The EU Green Deal's sustainable agriculture mandates are recalibrating input standards for certified seed production. Organic cultivation methods and reduced chemical inputs now qualify for preferential procurement in German medical channels. Spanish outdoor growers are responding fastest due to established organic horticulture infrastructure.
Buyer concentration among licensed cultivators is consolidating procurement power. Germany's top ten medical cannabis producers now account for the majority of feminized seed volume. This shift is compressing supplier margins and forcing seed banks to offer genetic exclusivity arrangements rather than commodity catalog sales.
Europe Cannabis Seeds Market Segmentation
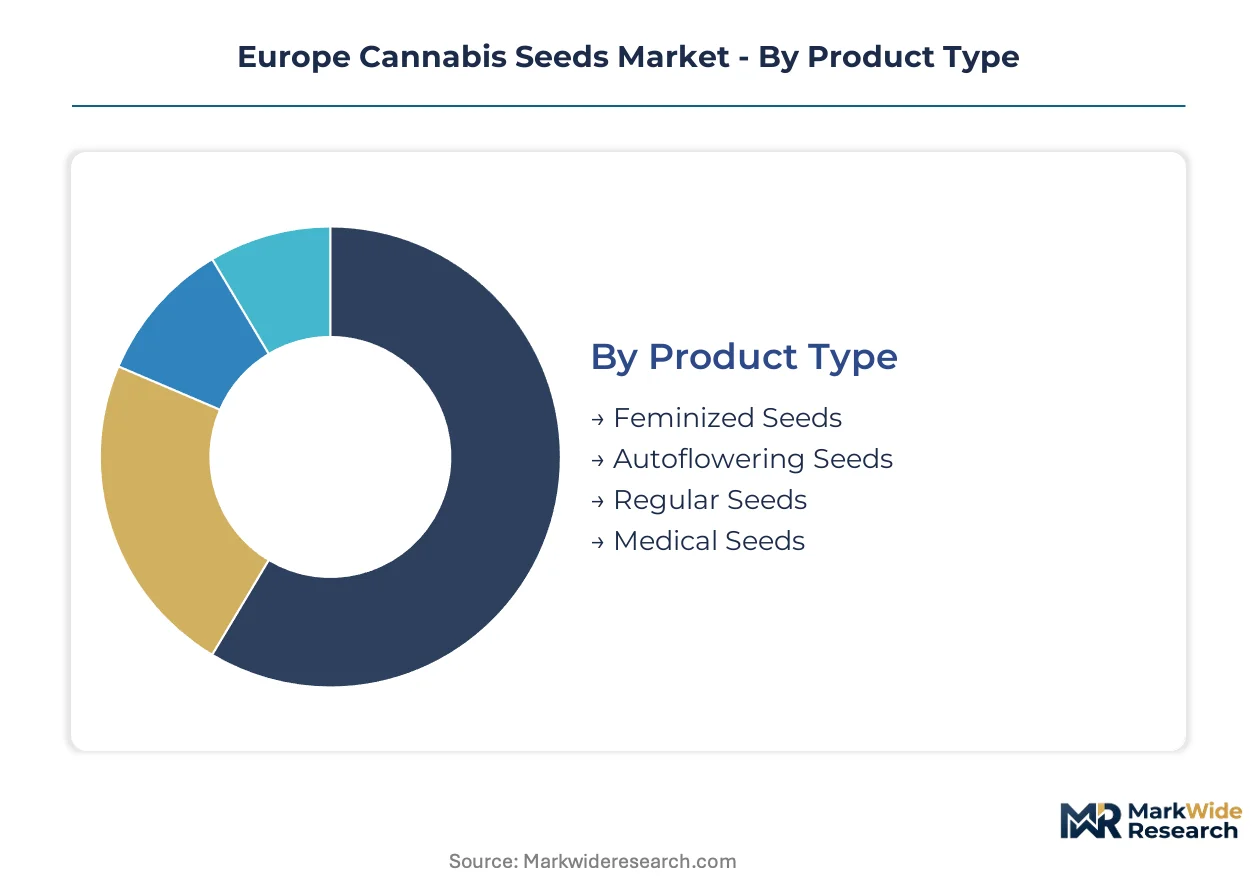
European cannabis seed buyers navigate a fragmented procurement landscape where product type, certification grade, and channel access determine commercial viability. Segmentation reveals how licensed cultivators prioritize feminized genetics for greenhouse efficiency while research institutions source distinct chemotype lines under separate regulatory frameworks.
Product Type:
Use cases span from commercial greenhouse operations seeking labor efficiency to outdoor growers requiring photoperiod independence across Nordic latitudes.
- Feminized Seeds:Genetically stabilized to eliminate male chromosomes, removing pollination risk and culling labor in commercial facilities. German licensed producers under BfArM oversight account for the dominant procurement volume as batch traceability mandates favor documented genetic lines.
- Autoflowering Seeds:Ruderalis-crossed varieties flower independently of light cycles, enabling outdoor harvests in climates with short growing seasons. Spanish outdoor cultivators in Catalonia and Andalusia are adopting these genetics fastest to bypass seasonal constraints.
- Regular Seeds:Unmodified sexual reproduction produces both male and female plants, retaining value for breeding programs and genetic preservation. Dutch seed banks maintain these lines for stabilization research.
- Medical Seeds:Chemotype-documented varieties with verified cannabinoid ratios for pharmaceutical-channel compliance. EMA framework adherence requires batch-specific analytical certificates.
The dominant share belongs to Feminized Seeds, while Autoflowering Seeds is closing the gap fastest.
Grade:
Certification tiers separate commodity supply from premium procurement channels where organic and high-potency designations command price premiums.
- Premium Grade:Laboratory-verified genetic stability with documented terpene profiles and feminization rates exceeding 99%. German pharmacy-channel suppliers require this tier for BfArM-registered cultivation batches.
- Organic Grade:EU Green Deal-compliant production without synthetic pesticides or chemical fertilizers. Spanish cooperatives in Valencia and Murcia leverage established organic horticulture infrastructure to supply this segment.
- Standard Grade:Conventionally produced seeds meeting baseline viability and purity thresholds. Volume sales through wholesale channels serve budget-constrained operations.
- High THC Grade:Genetics selected for elevated psychoactive cannabinoid expression, restricted to licensed adult-use frameworks where national law permits. Netherlands coffee shop supply chains represent the primary demand concentration.
Premium Grade holds the revenue concentration, though Organic Grade is gaining share fastest under EU sustainable agriculture procurement preferences.
End Use:
Regulatory boundaries between medical, recreational, and industrial applications create distinct sourcing requirements and compliance obligations.
- Medical Use:EMA-guided pharmaceutical production requiring GACP-certified cultivation from documented genetic starting material. Germany's statutory health insurance reimbursement system anchors regional demand.
- Recreational Use:Adult-use cultivation where national frameworks permit personal or commercial production. Spain's cannabis social clubs in Barcelona and Madrid operate in a policy-tolerant environment pending federal reform.
- Research:Academic and commercial R&D programs investigating chemotype expression and breeding methodologies. University partnerships in the Netherlands and Switzerland drive specialized procurement.
- Industrial Use:Fiber and seed-oil production from low-THC hemp varieties. French hemp cooperatives in Auvergne-Rhône-Alpes supply textile and construction material processors.
Medical Use commands the procurement volume, with Recreational Use expanding most quickly as reform discussions advance in multiple jurisdictions.
Distribution Channel:
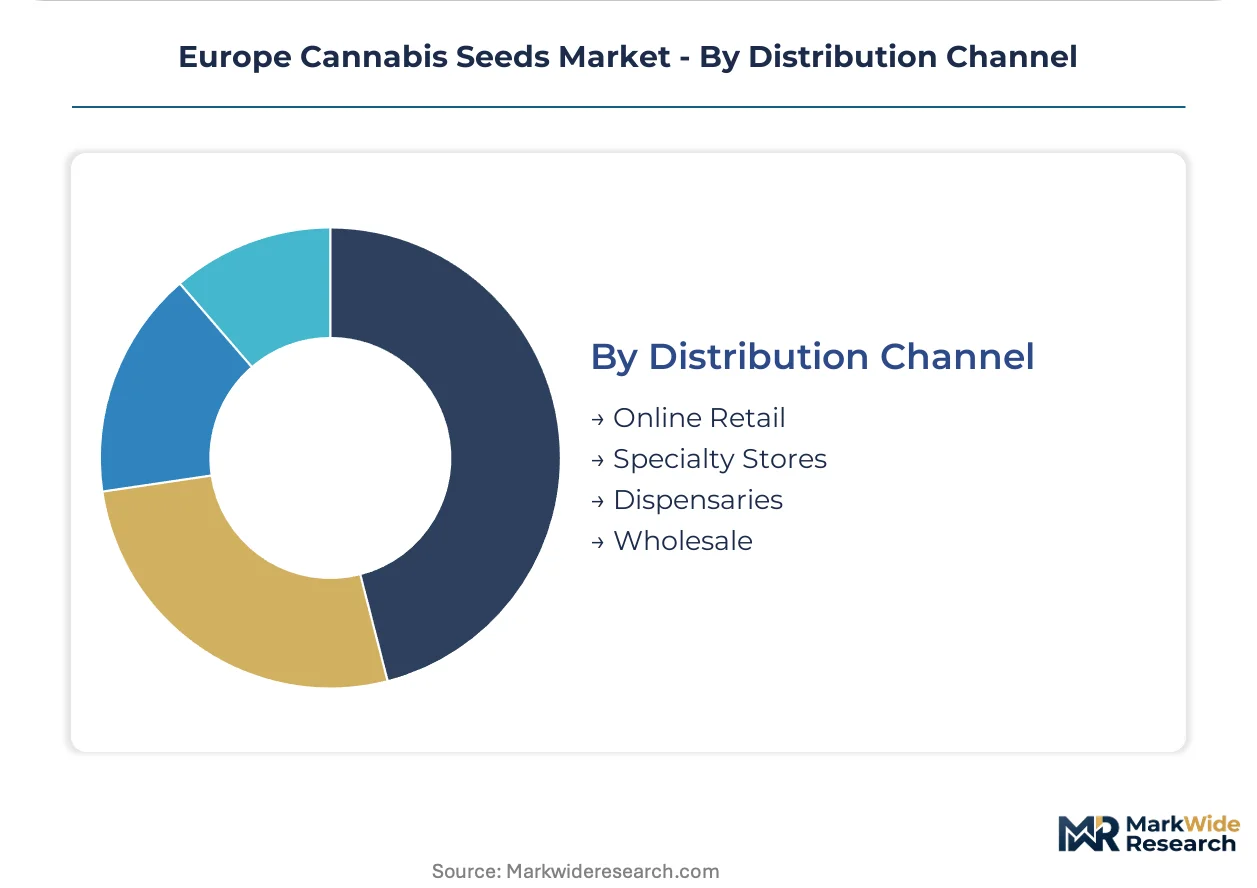
Channel selection determines margin extraction, regulatory exposure, and customer access for seed suppliers across European markets.
- Online Retail:Direct-to-consumer platforms enabling geographic reach beyond physical storefront limitations. Royal Queen Seeds and comparable operators compress wholesale margin layers through proprietary e-commerce infrastructure.
- Specialty Stores:Amsterdam, Barcelona, and Berlin seed banks offering in-person genetic consultation and verified provenance. These outlets serve experienced cultivators seeking stabilized breeding lines.
- Dispensaries:Regulated retail points in jurisdictions with licensed distribution frameworks. German pharmacy channels represent the most restrictive access tier.
- Wholesale:Bulk supply relationships with licensed cultivation facilities and retail chains. Buyer concentration among Germany's top ten medical producers is compressing supplier negotiating position.
Online Retail captures the volume lead, while Specialty Stores are climbing fastest as cultivators prioritize genetic verification and technical consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BfArM's batch traceability mandates anchor Germany as the dominant procurement geography. Licensed cultivators across Bavaria and North Rhine-Westphalia scale greenhouse capacity under statutory health insurance reimbursement. Dutch seed banks leverage Amsterdam's distribution infrastructure to serve cross-border demand.
Germany
Medical cultivators in Bavaria and North Rhine-Westphalia drive feminized seed procurement for BfArM-registered batches. Germany's statutory health insurance system reimburses cannabis-based medicines, concentrating pharmacy-channel demand. Berlin-based distributors coordinate logistics for documented genetic lines entering licensed facilities.
Netherlands
Amsterdam seed banks exploit decades of breeding infrastructure to supply stabilized genetics across European borders. The EU Court of Justice CBD ruling dismantled distribution barriers that previously constrained Dutch exporters. Rotterdam logistics hubs enable humidity-controlled seed shipments reaching German and Spanish cultivators within 48 hours.
Spain
Catalonia's cannabis social clubs in Barcelona create tolerated demand for autoflowering varieties suited to Mediterranean outdoor cycles. Pending federal reform discussions position Andalusia for adult-use market expansion. Valencia organic cooperatives supply EU Green Deal-compliant seed production for German medical channels.
France
Auvergne-Rhône-Alpes hemp cooperatives dominate low-THC fiber and seed-oil production under ANSM's stricter THC thresholds than neighboring jurisdictions. The country's textile and construction material processors anchor industrial demand. Paris-based regulatory fragmentation forces product line bifurcation for suppliers seeking multi-country market access.
Switzerland
Geneva and Zurich research institutions source chemotype-documented varieties for pharmaceutical R&D programs under Swissmedic oversight. The country's precision agriculture sector adopts blockchain-based seed certification ahead of EU adoption curves. Basel biotech clusters partner with Dutch breeders for genetic stabilization research.
Europe Cannabis Seeds Market Competitive Landscape
Heritage seed banks and direct-to-consumer platforms split the market between provenance credibility and margin compression. The vendor base concentrates among Dutch and Spanish operators with decades of breeding infrastructure. Three archetypes dominate: legacy Amsterdam institutions with stabilized genetic libraries, Barcelona-based social club suppliers, and e-commerce-native operators bypassing wholesale tiers. Competitive moves center on genetic exclusivity arrangements with licensed cultivators and blockchain-based batch documentation systems.
Within the heritage institution tier, Sensi Seeds and Dutch Passion occupy positions anchored by decades of stabilized breeding lines and Amsterdam distribution infrastructure. Royal Queen Seeds exemplifies the direct-to-consumer archetype through proprietary e-commerce platforms that compress traditional wholesale margin extraction. These three operators collectively represent the strategic spectrum from provenance-verified specialty supply to digitally native market access.
| Leading Market Players |
|---|
| Sensi Seeds |
| Royal Queen Seeds |
| Dutch Passion |
| Barney's Farm |
| Green House Seeds |
| Paradise Seeds |
| Fast Buds |
| Blimburn Seeds |
| Zamnesia |
| Others |
Supply & Pricing Matrix
Amsterdam's seed banking cluster concentrates stabilized genetic libraries that command premium positioning in downstream European markets. The Netherlands' decades-long breeding infrastructure creates asymmetric pricing power against newer market entrants lacking documented chemotype lineages.
Pricing Analysis
Price spreads between Dutch-certified genetics and Spanish outdoor varieties stretch across premium-mid-economy pricing differentiation. Certification grade under BfArM traceability mandates and volume scale through wholesale procurement anchor the two primary price differentiation drivers. Pricing pressure stems from buyer concentration among Germany's top ten licensed medical producers compressing supplier margins. Research institutions exhibit lowest price sensitivity due to grant-funded procurement, while Spanish social clubs face highest sensitivity from membership-funded budgets.
Supply Chain Analysis
EU Green Deal sustainable agriculture mandates and BfArM genetic documentation requirements operate as de facto export controls limiting seed flow to uncertified channels. Supply concentrates in the Netherlands, Spain, and Germany as the three dominant production geographies. Raw material dependencies center on stabilized breeding stock, laboratory verification services, and humidity-controlled storage infrastructure. Single-source vulnerability from concentrated Dutch genetic libraries creates structural supply risk. Distribution runs through direct-to-consumer platforms and specialty seed banks, with wholesale tiers losing share to vertically integrated licensed cultivators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based genetic certification services and recurring analytical verification contracts expand faster than commodity seed sales, transforming supplier economics toward service-attach models.
For Market Incumbents: Entrench position through exclusive genetic licensing arrangements with Germany's BfArM-registered cultivators and backward integration into laboratory verification capacity. Direct-to-consumer platforms threaten traditional wholesale margin extraction; certification investment in EU Green Deal organic standards creates defendable differentiation against price-competitive Spanish entrants. For New Entrants and Emerging Players: France's industrial hemp cooperatives in Auvergne-Rhône-Alpes represent underpenetrated demand for low-THC breeding stock with ANSM-compliant documentation. Switzerland's precision agriculture sector offers secondary entry through blockchain certification partnerships ahead of EU adoption curves. Target research institution procurement with chemotype-documented specialty lines as the most penetrable segment bypassing licensed cultivator concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators combining genetic libraries with digital traceability platforms. Five-to-ten year viability hinges on regulatory clarity around hemp-cannabis boundaries rather than cultivation scale alone. Acquisition targets should demonstrate BfArM audit compliance and established Amsterdam or Barcelona distribution infrastructure. Watch European Commission Novel Food deliberations as the signal indicating inventory risk or channel expansion opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Genetic Exclusivity Arrangements | BfArM-registered cultivators lock in documented chemotype lines, securing pharmacy-channel access against competitors. |
| Blockchain Certification Platform Deployment | Dutch and German licensed operators digitize batch traceability, satisfying audit requirements while compressing verification costs. |
| Organic Grade Production Scale-Up | Spanish cooperatives leverage Valencia infrastructure to capture EU Green Deal procurement preferences in German medical channels. |
| Direct-to-Consumer Platform Expansion | E-commerce-native operators bypass wholesale margin layers, capturing cultivators seeking genetic consultation beyond commodity catalogs. |
| Autoflowering Genetics R&D Investment | Ruderalis-crossed varieties enable Nordic outdoor harvests, opening geographic expansion previously constrained by photoperiod limitations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with licensed cultivators, seed bank procurement directors, regulatory affairs specialists at BfArM-registered facilities, and Dutch breeding program managers. Secondary validation drew from EMA guideline documents, BfArM batch registration databases, EU Court of Justice CBD trade rulings, and ANSM hemp threshold regulations. Bottom-up volume estimates from cultivation facility expansion plans were triangulated against top-down market sizing from trade flow analysis.
Calibration against historical adoption curves for feminized and autoflowering varieties anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, certification grade, end-use regulatory framework, and distribution channel structure. CAGRs were derived from weighted capacity expansion announcements and statutory reimbursement policy trajectories. Industry-specific inputs incorporated BfArM licensing velocity and EU Green Deal procurement preference implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation by e-commerce-native operators or rapid ANSM threshold harmonization would shift outcomes. Material shifts in European Commission Novel Food classification boundaries or BfArM traceability mandate enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Alfalfa Seed Market
Seeds
Tomato Seed Market
Seeds
Carrot Seed Oil Market
Seeds
Eucommia Seed Oil Market
Seeds
Ghana Seed Extract Market
Seeds
China Vegetable Seed Market
Seeds
Buckwheat Market
Seeds
Europe Vegetable Seed Market
Seeds
Chamomile Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Mustard Seeds Market
Seeds
Global Forage Seeds Market
Seeds
Hemp Seed Oil Market
Seeds
Pigeon Pea Market
Seeds
Africa Seed Market