
 United States Seed Market | 2026-2036
United States Seed Market Size, Share, and Industry Trends Forecast 2026-2036
United States Seed Market Outlook
Buyer concentration among large-scale row-crop operations is shifting procurement power toward fewer, more sophisticated customers who negotiate directly for trait packages. Bayer Crop Science leverages its biotechnology pipeline to anchor positions in herbicide-tolerant soybeans. Corteva Agriscience sustains broad germplasm libraries across multiple crop categories. Syngenta competes through integrated seed-and-crop-protection bundles that reduce per-acre input complexity for commercial growers.
Seeds are reproductive plant units containing embryonic tissue, nutrient reserves, and protective outer layers, engineered through conventional breeding, hybridization, or genetic modification to express specific agronomic traits such as drought tolerance or pest resistance. Their primary commercial purpose is to establish uniform, high-yielding stands that convert agronomic inputs into harvestable biomass. Grain seeds occupy the dominant value pool due to acreage scale across the Midwest, while vegetable seeds command premium pricing from specialty producers serving direct-to-retail and foodservice channels. Herbicide-tolerant trait packages lead the pest-resistance dimension, though insect-resistant stacked traits gain share as EPA refuge requirements evolve.
USDA's Animal and Plant Health Inspection Service oversees genetically engineered organism release permits, while EPA regulates plant-incorporated protectants under FIFRA pesticide frameworks; together these agencies determine which biotech traits reach commercial fields and at what stewardship cost. Seed treatment regulations under the Federal Seed Act mandate truth-in-labeling standards that govern coated and enhanced seed claims across interstate commerce. Stakeholders must monitor how state-level dicamba and 2,4-D drift restrictions in Arkansas, Illinois, and Indiana reshape trait adoption geography and channel inventory decisions.
Market Dynamics
Consolidation among row-crop operators is concentrating procurement power into fewer hands, forcing seed suppliers to negotiate directly for customized trait packages rather than selling through traditional distribution tiers. This structural shift is compressing margins while accelerating the pace of varietal turnover.
Growth Catalysts
- USDA biotechnology regulations:Streamlined permit pathways for gene-edited crops are reducing time-to-market for drought-tolerant varieties, accelerating farmer access to climate-adaptive germplasm.
- Herbicide-tolerant trait packages:Corn Belt farmers are prioritizing stacked resistance profiles as weed pressure intensifies, driving replacement cycles for legacy seed inventories.
- California specialty vegetable producers:Proprietary seed purchases are expanding as direct-to-retail channels demand differentiated produce varieties with specific size and color specifications.
Market Restraints
- EPA pesticide tolerance frameworks:Plant-incorporated protectants face extended review timelines under FIFRA, delaying commercialization of insect-resistant stacked traits and increasing regulatory compliance costs.
- Input cost volatility:Fertilizer price swings directly constrain farmer working capital available for premium seed upgrades, particularly affecting mid-scale operations in Illinois and Indiana.
- Trait licensing concentration:Patent thickets around CRISPR-edited germplasm limit independent breeding programs, forcing smaller seed companies into costly royalty arrangements with technology holders.
Strategic Opportunities
- Cover crop seed expansion:USDA conservation programs are subsidizing multi-species blends for soil health, creating new demand channels beyond traditional commodity grain markets.
- Organic certification tailwinds:NOP standards are mandating non-GMO seed sourcing for certified operations, opening premium pricing tiers for untreated and organic-certified varieties.
- Drone-enabled variable-rate planting:Precision agriculture integration allows seed suppliers to bundle prescription services with varietal recommendations, capturing recurring revenue streams.
Industry Challenges
- Gene editing talent scarcity:Molecular breeding expertise concentrates at major research universities and incumbent firms, limiting pipeline capacity for emerging seed developers.
- Refuge compliance complexity:EPA insect resistance management requirements mandate structured refuge planting, creating operational friction for growers adopting Bt-traited corn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Seed Market |
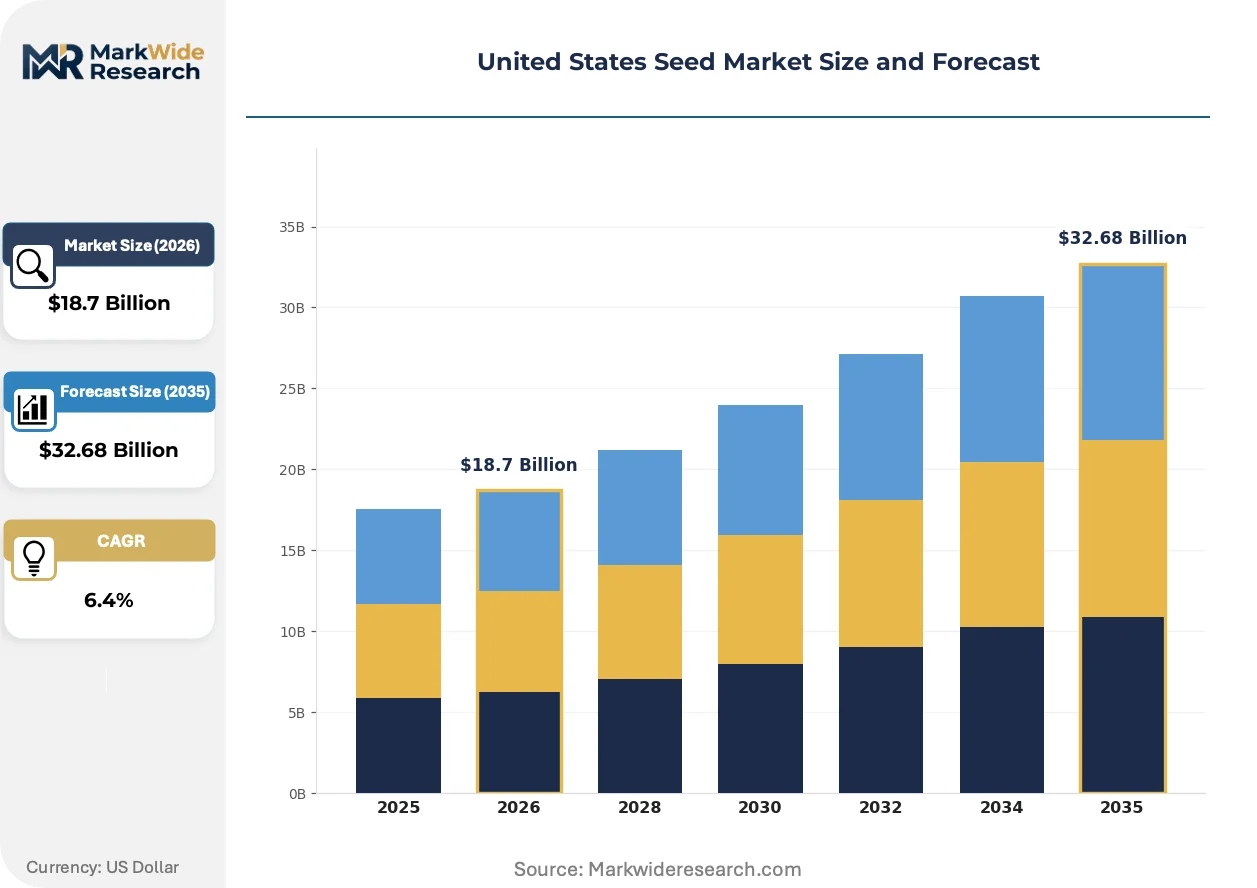
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Flower Seeds, Herb Seeds, Grain Seeds End Use Industry: Agricultural, Horticultural, Commercial, Home Gardening Pest Resistance: Herbicide Tolerant, Insect Resistant, Disease Resistant, Conventional Seed Treatment: Coated, Untreated, Inoculated, Enhanced |
| Companies Covered | AgReliant Genetics, Limagrain, Corteva Agriscience, CHS Inc., KWS SAAT, Bayer Crop Science, BASF, GROWMARK, Syngenta, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Seed Market Strategic Shifts
Gene editing platforms are compressing varietal development timelines from a decade to under five years, fundamentally altering how seed companies allocate R&D capital and how quickly farmers gain access to climate-adaptive genetics.
CRISPR-Cas9 precision breeding is overtaking conventional transgenic insertion for trait development, enabling single-gene edits without foreign DNA. Mid-scale soybean operations in Iowa and Nebraska are adopting these varieties at twice the pace of smaller farms. The technology is compressing regulatory review burdens while opening trait stacks previously blocked by patent thickets.
EPA's evolving refuge requirements for Bt corn are mandating larger non-traited planting buffers in cotton-growing regions, forcing seed companies to reformulate product mixes. Iowa and Illinois processors are adjusting grain handling protocols to segregate refuge harvests. The policy is accelerating demand for refuge-in-a-bag convenience formulations that simplify compliance.
Direct contracting between seed suppliers and large-scale cooperatives is replacing distributor-mediated sales for operations exceeding ten thousand acres. Channel disintermediation is most visible across Kansas and Nebraska, where grain handling cooperatives now negotiate proprietary germplasm access. The shift is compressing working capital cycles for distributors while transferring pricing power to consolidated buying entities.
United States Seed Market Segmentation
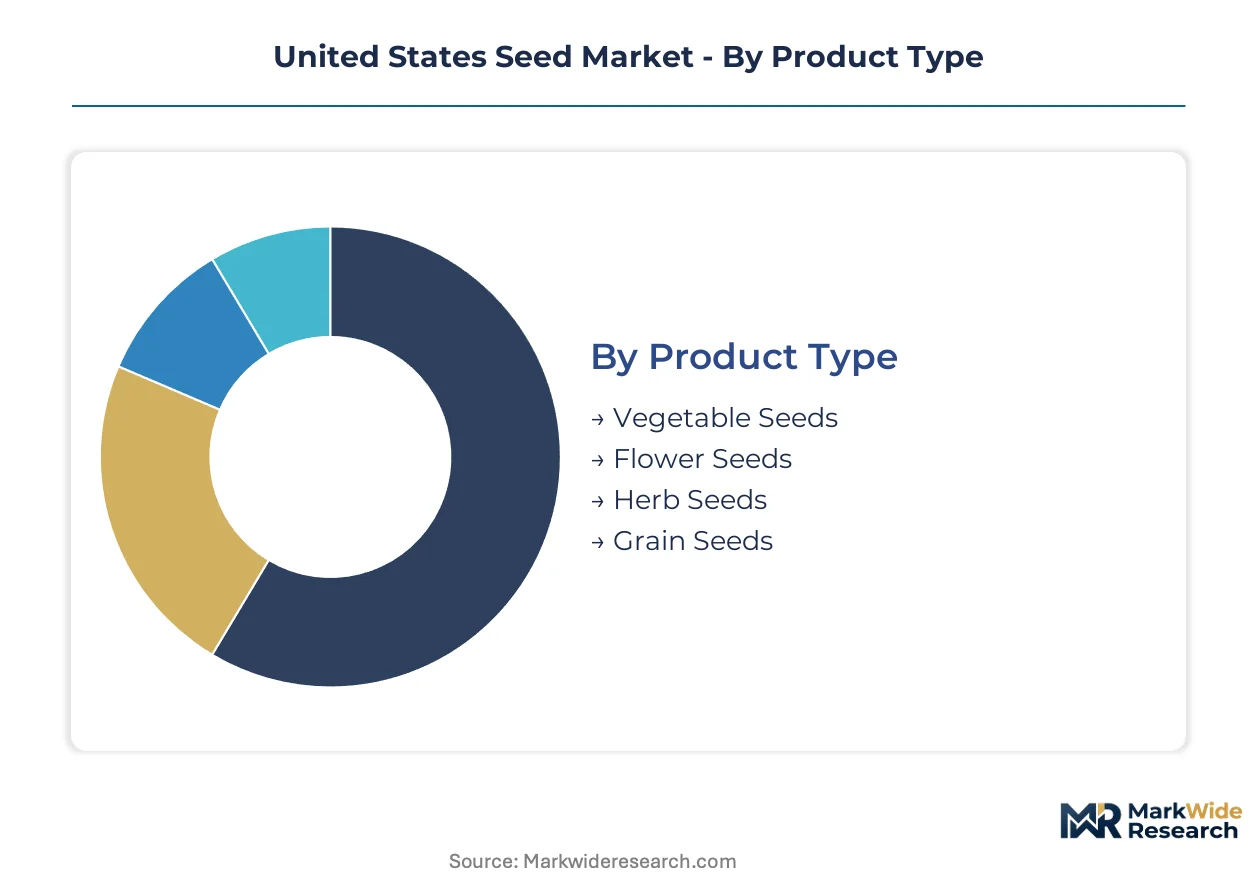
Seed suppliers configure product portfolios around agronomic application and input integration. Trait packages and treatment technologies determine pricing tiers and channel placement across distinct customer workflows.
Product Type:
Grain seeds dominate acreage economics while vegetable seeds extract premium returns per unit area.
- Grain Seeds:Corn and soybean germplasm engineered for herbicide tolerance and yield stability. Demand concentrates in Iowa and Illinois where consolidated row-crop operations negotiate direct trait licensing. Input bundling with crop protection chemicals reinforces supplier lock-in across the Corn Belt.
- Vegetable Seeds:Hybrid tomato, pepper, and leafy green varieties selected for size uniformity and shelf-life extension. California's Salinas Valley and Florida's Immokalee region drive proprietary purchases as direct-to-retail channels impose strict produce specifications. Premium pricing reflects per-acre value density far exceeding commodity grains.
- Flower Seeds:Ornamental varieties for commercial landscaping and retail garden centers.
- Herb Seeds:Culinary and medicinal species for specialty agriculture and home cultivation.
Mature deployment sits with grain seeds. Newer deployment is concentrated in vegetable seeds.
End Use Industry:
Commercial scale determines procurement sophistication and trait package complexity.
- Agricultural:Large-scale field crop production requiring certified germplasm with documented genetic purity. Midwest grain elevators and ethanol processors enforce identity-preserved handling protocols that cascade back to seed sourcing requirements. Volume contracting secures preferential pricing for operations exceeding five thousand acres.
- Commercial:Professional greenhouse and nursery operations sourcing high-germination, pathogen-indexed stock. Controlled-environment agriculture in Arizona and Texas demands varieties bred for hydroponic and vertical farming systems. Speed-to-harvest metrics override raw seed cost in procurement decisions.
- Horticultural:Specialty fruit and vegetable production with emphasis on post-harvest quality.
- Home Gardening:Retail-packaged varieties for consumer direct purchase through garden centers and e-commerce.
Input integration runs deepest in agricultural applications. Operational flexibility matters most in commercial settings.
Pest Resistance:
Trait stacking intensity separates premium tiers from baseline commodity offerings.
- Herbicide Tolerant:Glyphosate and dicamba resistance genes enabling post-emergent weed control without crop injury. EPA tolerance frameworks and state-level drift restrictions in Arkansas and Indiana reshape adoption geography. Refuge-in-a-bag formulations simplify compliance for Bt-stacked hybrids.
- Insect Resistant:Bacillus thuringiensis protein expression targeting corn rootworm and European corn borer. Iowa processors maintain separate handling streams for refuge harvest segregation. Stacked trait premiums reflect reduced insecticide application costs and yield protection value.
- Disease Resistant:Genetic markers for fungal and bacterial pathogen tolerance.
- Conventional:Non-transgenic germplasm for organic certification compliance and export markets with biotechnology restrictions.
Herbicide tolerance anchors the largest planted base. Insect resistance commands the steepest expansion trajectory as refuge requirements evolve.
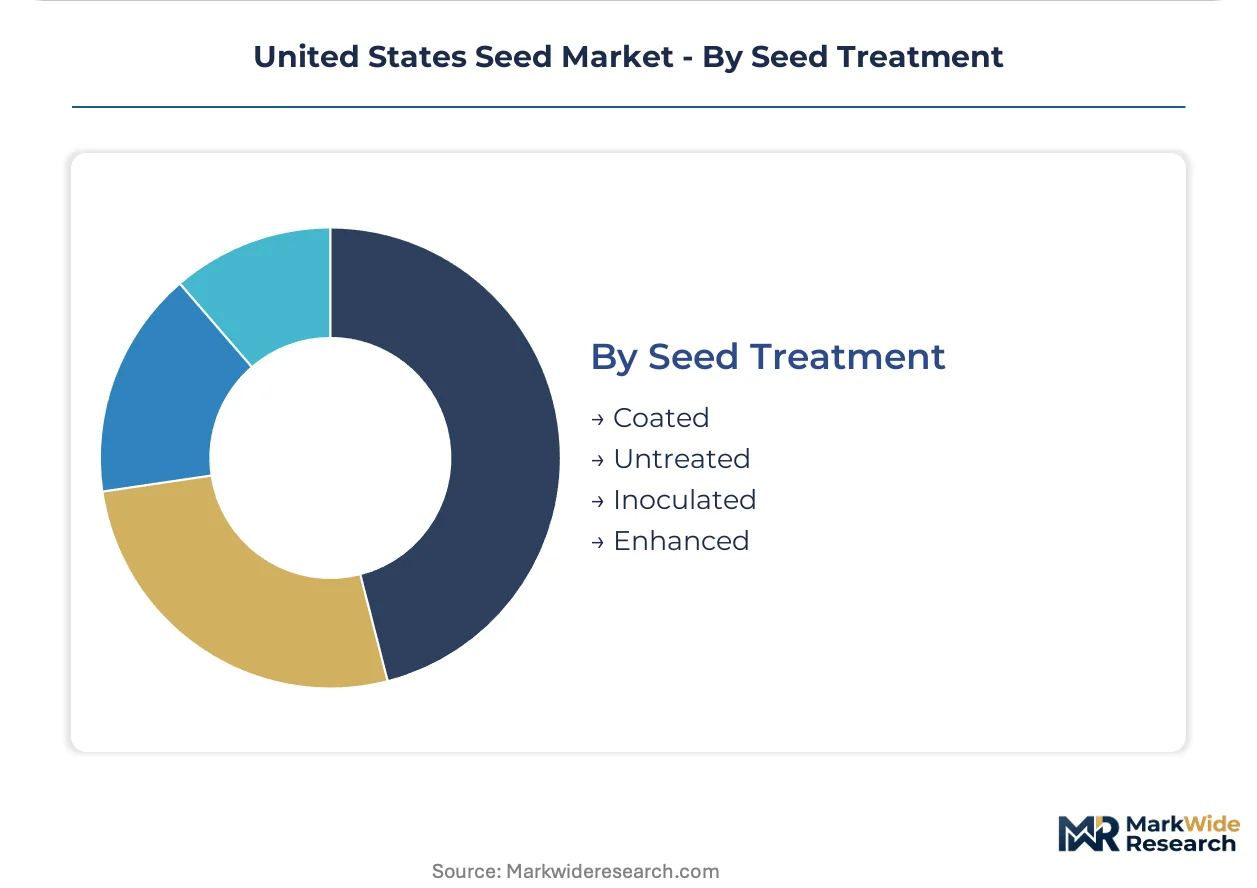
Seed Treatment:
Biological and chemical coatings differentiate performance tiers and regulatory compliance burdens.
- Coated:Polymer-encapsulated fungicides and insecticides applied at point-of-sale. Federal Seed Act labeling mandates govern active ingredient disclosure across interstate shipment. Nebraska and Kansas distributors maintain specialized application equipment for custom treatment orders.
- Inoculated:Rhizobium and mycorrhizal formulations for nitrogen fixation and phosphorus uptake enhancement. Soybean operations in Minnesota and Wisconsin specify strain compatibility with local soil microbiomes. Biological additive costs trade off against synthetic fertilizer reduction.
- Untreated:Raw germplasm for organic operations and farmer-applied custom treatments.
- Enhanced:Micronutrient and biostimulant fortification for stress tolerance and early vigor.
Coated treatments dominate conventional acreage. Inoculated products are gaining share fastest in legume rotations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest corn and soybean germplasm anchors United States seed demand, with trait licensing negotiations concentrated among Iowa and Illinois grain cooperatives.
Midwest Corn Belt
Iowa and Illinois row-crop operations drive herbicide-tolerant corn and soybean volumes through direct cooperative contracting. USDA biotechnology permit pathways under APHIS accelerate drought-tolerant variety approvals for climate adaptation. Des Moines and Champaign-Urbana clusters host major germplasm research stations where stacked-trait development cycles compress below five years.
California Central Valley
Specialty vegetable producers in Salinas Valley and Fresno County source proprietary tomato and leafy green seeds for direct-to-retail specifications. State pesticide drift regulations under California Department of Pesticide Regulation reshape trait adoption boundaries for neighboring organic operations. Monterey County processing contracts enforce identity-preserved handling that cascades back to seed sourcing requirements.
Florida Peninsula
Winter vegetable growers in Immokalee and Palm Beach County expand pepper and tomato seed purchases for foodservice channel differentiation. EPA FIFRA frameworks govern plant-incorporated protectant approvals affecting insect-resistant variety timelines. Miami-Dade greenhouse operations demand pathogen-indexed stock for controlled-environment speed-to-harvest metrics.
Texas Southern Plains
Cotton and sorghum seed demand concentrates in Lubbock and High Plains regions where drought tolerance traits command premium positioning. Texas Department of Agriculture seed certification programs enforce genetic purity standards across interstate shipment. Corpus Christi grain terminals enforce identity-preserved protocols that influence upstream varietal selection.
Pacific Northwest
Seed potato and specialty crop germplasm in Columbia Basin and Willamette Valley serves export markets with phytosanitary restrictions. Oregon Department of Agriculture organic certification programs mandate non-GMO sourcing for NOP compliance. Portland metro distributors maintain specialized treatment equipment for custom biological inoculation orders.
United States Seed Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue gene-edited specialty varieties and regional cooperative partnerships. Three multinational agribusinesses anchor biotechnology licensing, while mid-scale independents compete through regional germplasm adaptation and organic-certified portfolios. Competitive positioning hardens around trait stacking speed, regulatory navigation capacity, and direct procurement relationships with consolidated buying cooperatives. M&A activity targets regional breeding programs with climate-adaptive germplasm libraries; technology licensing agreements concentrate CRISPR access among capitalized research pipelines.
Within the multinational tier, Bayer Crop Science and Corteva Agriscience exemplify integrated biotechnology and germplasm platform operators. Syngenta occupies a position bridging seed-crop protection bundling with global trait distribution networks. Among cooperative-aligned independents, AgReliant Genetics represents the regional adaptation archetype through Midwest-focused varietal development. CHS Inc. anchors the agricultural supply cooperative segment with procurement leverage across grain handling infrastructure.
| Leading Market Players |
|---|
| AgReliant Genetics |
| Limagrain |
| Corteva Agriscience |
| CHS Inc. |
| KWS SAAT |
| Bayer Crop Science |
| BASF |
| GROWMARK |
| Syngenta |
| Others |
Value Chain & Pricing Dynamics
Trait licensing fees embedded in germplasm contracts cascade through distributor markups to final per-acre seed costs, compressing margins at each tier while concentrating pricing power with biotechnology patent holders. Iowa and Illinois grain cooperatives negotiate directly with suppliers to strip out intermediary layers, converting saved distribution costs into volume discounts on stacked-trait varieties.
Pricing Analysis
Warranty-backed germplasm performance guarantees separate premium-tier offerings from unbundled commodity seed, with Bayer Crop Science and Corteva Agriscience bundling replant policies and agronomic advisory services into per-acre contracts. Three-tier pricing structure across premium, standard, and economy levels reflects trait stacking intensity, genetic purity certification, and treatment technology sophistication. Pricing pressure stems from consolidated buyer leverage in the Corn Belt, where operations exceeding ten thousand acres demand customized trait packages at reduced per-unit rates. Mid-scale Illinois and Indiana farms exhibit highest price sensitivity due to fertilizer cost volatility constraining working capital, while California specialty vegetable producers accept premium positioning for proprietary varieties meeting direct-to-retail specifications.
Supply Chain Analysis
Refuge-in-a-bag seed returns and replant claims flow through distributor service centers to supplier germplasm replacement programs, creating reverse-logistics infrastructure that smaller independents struggle to replicate. Domestic biotechnology R&D concentrates in Iowa, Illinois, and Indiana research stations, while proprietary vegetable genetics sources from California and Florida breeding operations. Raw material dependencies include CRISPR reagent supplies, polymer seed coating chemicals, and biological inoculant strains. Single-source vulnerability around gene-editing patent licensing creates supply chain risk as Bayer, Corteva, and BASF control access to stacked-trait platforms. Distribution runs through agricultural cooperatives and independent retail networks, with direct contracting displacing traditional tiers across Kansas and Nebraska grain handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA APHIS biotechnology permit requirements and EPA FIFRA plant-incorporated protectant frameworks impose compliance cost burdens that erect substantial barriers to entry, protecting capitalized incumbents while forcing emerging players into costly technology licensing arrangements.
For Market Incumbents: Acquire regional breeding programs with climate-adaptive germplasm libraries to secure differentiated varietal pipelines outside patent-thicketed trait platforms. Consolidated buyer leverage in Iowa and Illinois cooperative contracting threatens margin compression; defend position through backward integration into precision agriculture prescription services that lock in recurring revenue streams beyond transactional seed sales. For New Entrants and Emerging Players: Organic-certified operations represent the most penetrable buyer archetype, as NOP standards mandate non-GMO sourcing and established suppliers underinvest in untreated variety portfolios. Target Pacific Northwest seed potato and specialty crop producers facing phytosanitary export restrictions, where Oregon Department of Agriculture certification requirements create defensible niche positioning. Pursue cooperative partnership models with mid-scale distributors lacking CRISPR access to bypass direct biotechnology licensing. For Investors and Strategic Acquirers: EPA refuge requirement modifications for Bt corn is the leading indicator that regulatory burden shifts will favor suppliers with integrated compliance service capabilities. Long-term viability centers on gene-editing platform operators with demonstrated regulatory navigation capacity across USDA and EPA frameworks. Monitor state-level dicamba and 2,4-D drift restriction adoptions in Arkansas, Illinois, and Indiana as signals of geographic trait demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Platform Licensing | CRISPR-Cas9 access agreements compress varietal development timelines below five years for drought-tolerant germplasm. |
| Refuge-in-a-Bag Formulation Expansion | Integrated compliance products simplify EPA insect resistance management requirements for Iowa and Illinois corn growers. |
| Direct Cooperative Contracting | Channel disintermediation transfers pricing power to Kansas and Nebraska grain handling cooperatives exceeding ten thousand acres. |
| Organic-Certified Portfolio Buildout | NOP-compliant untreated varieties capture premium positioning as California and Florida specialty producers expand proprietary sourcing. |
| Precision Agriculture Integration | Drone-enabled variable-rate planting services bundle prescription recommendations with varietal sales for recurring revenue capture. |
Study Parameters
Multi-period observation of trait adoption rates, biotechnology permit approval timelines, and cooperative procurement contract structures anchored the trend analysis, supplemented by interviews with seed company R&D directors, agricultural cooperative procurement managers, USDA APHIS regulatory affairs specialists, and EPA pesticide tolerance reviewers. Secondary validation drew from USDA NASS crop acreage reports, EPA FIFRA registration databases, Federal Seed Act compliance filings, and state-level seed certification records. Bottom-up acreage and pricing estimates triangulated against top-down market value reconstructions across grain, vegetable, and specialty crop segments.
Segment-weighting approaches applied differential growth assumptions to herbicide-tolerant versus insect-resistant trait packages, organic-certified versus conventional germplasm, and direct-contracted versus distributor-mediated channel volumes across the projection horizon. CAGRs derived from historical adoption curve analysis and regulatory pathway duration modeling, with inputs including climate adaptation urgency indices and consolidated farm operator expansion rates.
Revisions become necessary when EPA FIFRA review timeline extensions, state-level pesticide drift restriction adoptions, or gene-editing patent landscape shifts materialize beyond baseline assumptions. Forecasts reflect documented parameters around biotechnology regulatory capacity and cooperative buyer consolidation trajectories. Practitioners should monitor USDA APHIS permit backlog indicators and dicamba tolerance framework modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Flax Crop Market
Seeds
Sesame Seeds Market
Seeds
Grass Seed Market
Seeds
Agricultural Seeder Market
Seeds
India Vegetable Seed Market
Seeds
Global Sorghum Seed Market
Seeds
China Vegetable Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Africa Vegetable Seed Market
Seeds
Watermelon Seeds Market
Seeds
Africa Chia Seeds Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Commercial Seed Market
Seeds
Global Wheat Seed Market
Seeds
Asia-Pacific Onion Seed Market