
 Sweden Cosmetics Products Market | 2026-2036
Sweden Cosmetics Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Cosmetics Products Market Analytics
Subscription-based replenishment services for skincare routines is restructuring how Swedish consumers discover and repurchase cosmetics. Oriflame Holding leverages its direct-selling heritage to sustain recurring revenue streams in Nordic households. L'Oréal anchors its position through R&D intensity focused on microbiome science and personalized diagnostics. KICKS Group competes by controlling the specialty retail channel with exclusive brand partnerships and in-store consultation services.
Cosmetics products encompass topical formulations designed for skin, hair, and personal adornment, typically comprising emulsions, surfactants, active ingredients, and preservatives manufactured through cold-process or hot-process methods to achieve stability and sensorial performance. Skincare dominates value contribution as Swedish consumers prioritize preventive aging and barrier-repair formulations with clinical efficacy claims. Fragrance experiences accelerated momentum through niche indie positioning and limited-edition drops that capture experiential purchasing behavior among Gen Z buyers. Eco-friendly brand positioning commands margin premiums as clean certification requirements reshape procurement and packaging specifications across the supply base.
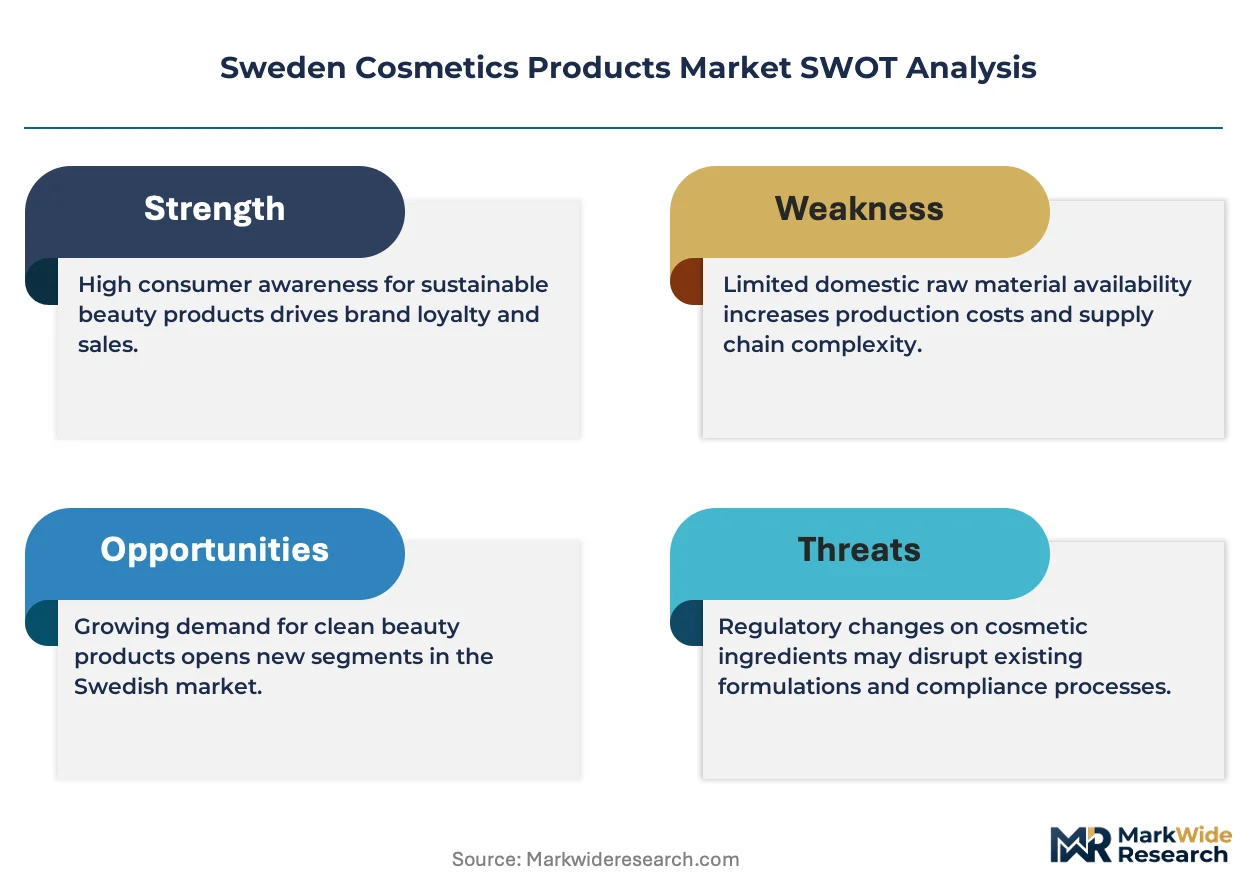
EU REACH chemical registration rules and the EU Green Deal's sustainable product framework govern ingredient disclosure and environmental footprint standards for all cosmetics sold in Sweden. The Swedish Chemicals Agency enforces national compliance with these frameworks while monitoring per- and polyfluoroalkyl substance restrictions in cosmetic formulations. Stakeholders must monitor evolving biodegradability mandates and digital product passport requirements that will reshape labeling, sourcing decisions, and competitive differentiation in Nordic beauty retail.
Market Dynamics
EU REACH chemical registration requirements and the EU Green Deal's sustainable product framework are forcing Swedish cosmetics manufacturers to reconfigure formulation pipelines and packaging supply chains ahead of accelerating biodegradability mandates.
Growth Catalysts
- Urban millennial skincare prioritization:Stockholm's metropolitan retail corridor concentrates specialty store density that accelerates brand discovery and trial for premium preventive aging formulations.
- REACH chemical transparency mandates:The European Chemicals Agency's expanded ingredient disclosure requirements are compressing time-to-market for clean-certified products while raising barriers for non-compliant imports.
- Microbiome science R&D intensity:Biotechnology platforms enabling personalized skin diagnostics are integrating into Swedish consumer expectations for clinical efficacy claims.
Market Restraints
- Per- and polyfluoroalkyl substance restrictions:The Swedish Chemicals Agency's tightening PFAS limits in cosmetic formulations are eliminating certain long-chain emulsifiers from approved ingredient lists.
- Packaging material cost volatility:Post-consumer recycled glass and aluminum supply bottlenecks are compressing margin structures for eco-positioned brands dependent on premium sustainable materials.
- Digital product passport preparation:EU-wide traceability infrastructure requirements are imposing systems integration costs on mid-tier manufacturers before mandatory 2027 implementation.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer recurring revenue platforms are capturing household-level loyalty in Gothenburg and Malmö metropolitan zones beyond Stockholm's saturated retail core.
- Niche fragrance experiential positioning:Limited-edition drops and indie brand curation are unlocking Gen Z purchasing velocity through social commerce channels.
- Barrier-repair clinical formulations:Ceramide and peptide-based skincare is penetrating the male grooming segment, which remains underdeveloped relative to Nordic female category penetration rates.
Industry Challenges
- Formulation chemist talent scarcity:The intersection of clean chemistry certification and cosmetic stability science is creating recruitment bottlenecks for compound development roles.
- Dual certification timeline compression:Brands pursuing simultaneous EU Ecolabel and Nordic Swan Ecolabel approvals face overlapping documentation requirements and divergent testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Cosmetics Products Market |
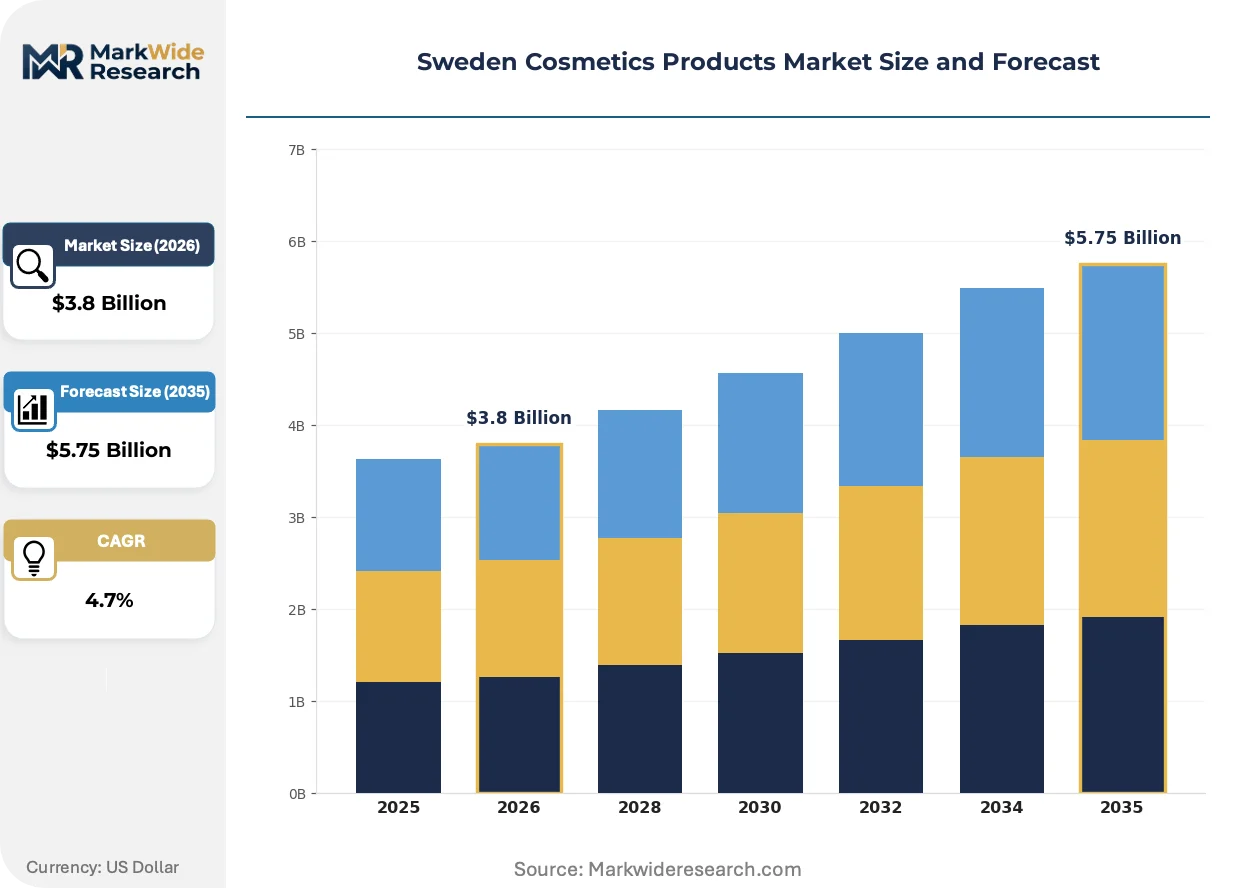
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Distribution Channel: Online, Specialty Stores, Drugstores, Department Stores Customer Demographic: Millennials, Gen Z, Baby Boomers, Professionals Brand Positioning: Luxury, Mass Market, Indie, Eco-Friendly |
| Companies Covered | Oriflame Holding, Henkel, L'Oréal, KICKS Group, Shiseido, Estée Lauder Companies, Beiersdorf, Lumene, Unilever, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Cosmetics Products Market Evolving Landscape
Biotechnology platforms and regulatory traceability infrastructure are converging to reshape how Swedish cosmetics are formulated, certified, and distributed through increasingly direct consumer relationships.
Artificial intelligence-driven skin analysis tools are integrating into at-home diagnostic devices that capture sebum levels, barrier function, and microbiome diversity. Swedish millennials are adopting these platforms faster than European averages, compressing the traditional consultation-to-purchase funnel that specialty retailers previously controlled. This integration is enabling personalized regimen subscriptions that bypass conventional trial-size sampling economics.
The EU Green Deal's sustainable product framework is mandating environmental footprint disclosures across cosmetics value chains. Swedish manufacturers must now document upstream ingredient sourcing impacts and downstream packaging recyclability under protocols enforced by the Swedish Chemicals Agency. Fragrance and color cosmetic categories face the steepest compliance curves due to complex petrochemical-derived ingredient dependencies.
Social commerce discovery patterns are displacing traditional department store beauty halls as the primary trial environment for Swedish Gen Z consumers. TikTok-native indie brands are capturing Stockholm and Malmö urban demand through algorithmic targeting and peer validation loops. This behavioral rotation is forcing established retailers to unbundle in-store consultation services into standalone digital appointments.
Sweden Cosmetics Products Market Segmentation
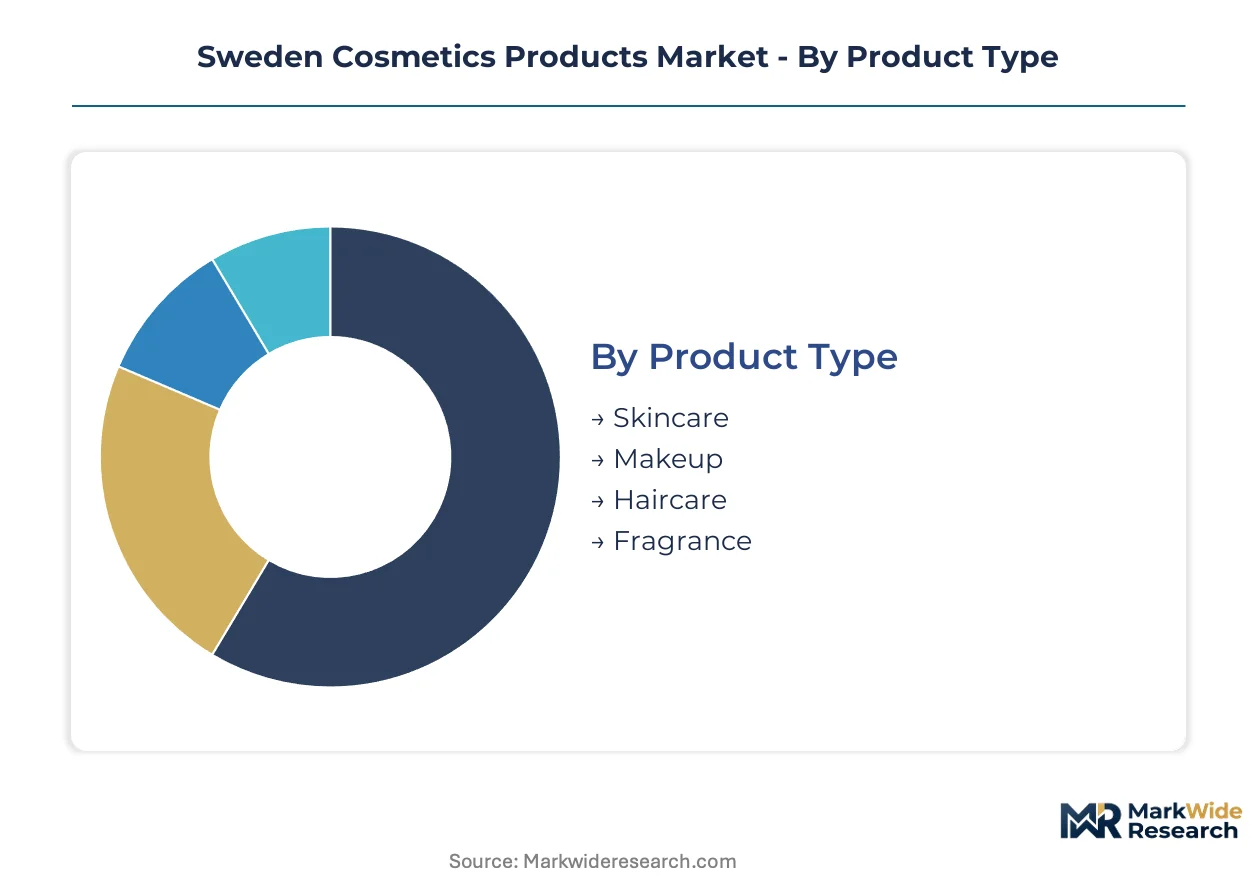
Swedish cosmetics purchasing patterns fragment across four distinct dimensions, each revealing divergent margin structures and channel economics. Product type stratification concentrates value in clinical skincare, while distribution channel evolution is compressing traditional retail intermediaries.
Product Type:
Upgrade cycles vary dramatically across topical categories, with preventive formulations commanding shorter replenishment intervals than color cosmetics.
- Skincare:Emulsions and active concentrates featuring ceramides, peptides, and microbiome-supporting biotics dominate household spending. Stockholm metropolitan consumers prioritize barrier-repair claims, with clinical efficacy certifications from the Swedish Medical Products Agency accelerating premium adoption among urban millennials.
- Fragrance:Niche indie positioning and limited-edition drops capture experiential purchasing velocity. Gen Z buyers in Gothenburg and Malmö metropolitan zones drive demand for algorithmically-targeted social commerce discovery, displacing traditional department store sampling.
- Makeup:Clean-certified color cosmetics face compressed margins as EU REACH disclosure requirements raise formulation costs.
- Haircare:Scalp health positioning and sulfate-free claims penetrate professional salon channels and direct-to-consumer subscriptions.
Skincare sits at the top of the volume ranking, with fragrance climbing the fastest.
Distribution Channel:
Channel economics stratify by customer acquisition cost and lifetime value capture, with digital-native platforms restructuring traditional margin allocation.
- Online:Direct-to-consumer subscriptions and AI-driven skin diagnostic platforms compress the consultation-to-purchase funnel. Swedish millennials adopt at-home sebum analysis devices faster than European averages, enabling personalized regimen algorithms that bypass specialty retailer sampling economics.
- Specialty Stores:KICKS Group and independent retailers control brand discovery through exclusive partnerships and in-store consultation services. Stockholm's retail corridor concentrates trial density for premium preventive aging formulations.
- Drugstores:Mass-market accessibility and pharmacist endorsement drive clinical dermocosmetic penetration in secondary cities.
- Department Stores:Flagship beauty halls face displacement as social commerce captures Gen Z discovery patterns.
Online channels command the steepest expansion trajectory, while specialty stores retain the highest customer lifetime value.
Customer Demographic:
Generational cohorts exhibit divergent sensitivity to sustainability certification and digital purchasing interfaces.
- Millennials:Urban professionals prioritize clean beauty formulations and subscription-based replenishment for preventive aging regimens. Stockholm's metropolitan density supports specialty store discovery and trial for premium clinical efficacy claims.
- Gen Z:TikTok-native discovery patterns and peer validation loops drive niche fragrance and indie brand velocity. Algorithmic targeting captures demand in Malmö and Gothenburg metropolitan zones beyond Stockholm's saturated retail core.
- Baby Boomers:Loyalty to established retailers and dermatologist-endorsed formulations sustains mass-market and professional channel relevance.
- Professionals:Time-constrained purchasing favors streamlined digital interfaces and auto-replenishment platforms.
Millennials generate the highest absolute spending, with Gen Z gaining share fastest.
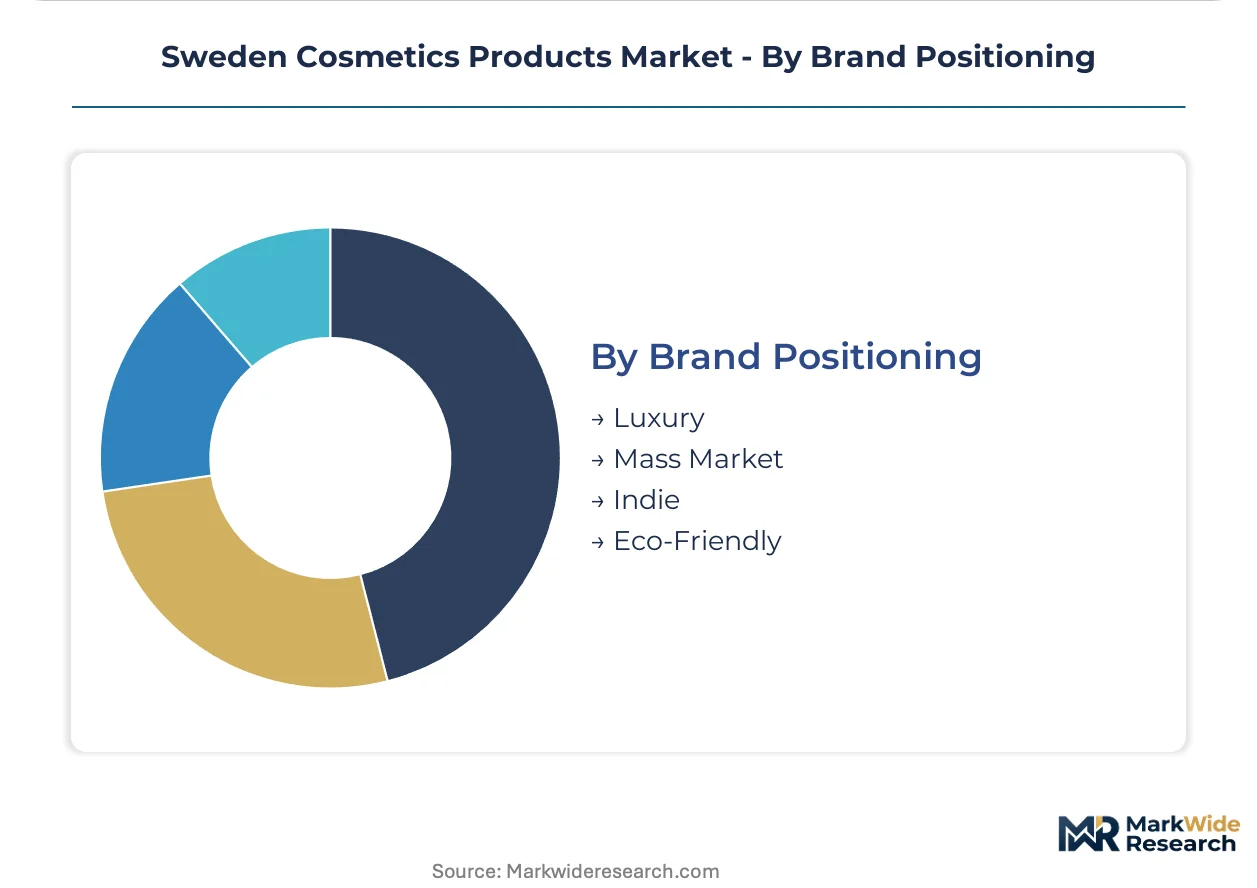
Brand Positioning:
Positioning tiers separate by certification intensity, ingredient transparency depth, and packaging sustainability credentials.
- Luxury:Biotechnology platforms and personalized diagnostics justify margin premiums through clinical efficacy claims. L'Oréal's R&D intensity in microbiome science anchors this tier.
- Eco-Friendly:Nordic Swan Ecolabel and EU Ecolabel dual certification requirements reshape procurement and packaging specifications. Post-consumer recycled glass supply bottlenecks compress margins for compliant brands.
- Mass Market:Price-sensitive accessibility through drugstore and grocery channels serves secondary city demand.
- Indie:Social commerce-native brands leverage limited-edition drops and algorithmic targeting to capture Gen Z velocity without traditional retail overhead.
Luxury positioning retains the highest margin structure, with eco-friendly certification climbing fastest as EU Green Deal mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden trails Germany in absolute cosmetics market value but exceeds Nordic neighbors Finland and Denmark in per-capita premium skincare spend. The Swedish Chemicals Agency enforces stricter PFAS limits than ECHA baseline requirements, creating regulatory asymmetry across Scandinavian markets.
Stockholm Metropolitan Area
Urban millennials drive preventive aging formulation demand through KICKS Group's specialty store network. The Swedish Chemicals Agency monitors REACH compliance for all imported active ingredients entering the capital's distribution hubs. Stockholm's retail corridor concentrates brand discovery density, with Södermalm and Östermalm districts hosting flagship consultation services.
Gothenburg
Subscription-based replenishment platforms capture household loyalty through direct-to-consumer channels. ECHA's expanded ingredient disclosure requirements compress time-to-market for clean-certified products targeting West Sweden's professional demographic. The Lindholmen Science Park cluster supports biotech R&D partnerships for microbiome diagnostic tools.
Malmö
Gen Z consumers accelerate niche fragrance velocity through TikTok-native discovery patterns. EU Green Deal sustainable product frameworks mandate environmental footprint disclosures for all formulations sold in Skåne County. The Hyllie district's logistics infrastructure enables same-day delivery for personalized regimen subscriptions.
Uppsala
Academic research institutions anchor clinical efficacy testing for barrier-repair formulations. Swedish Medical Products Agency certifications accelerate premium adoption among university-affiliated healthcare professionals. The Uppsala Science Park hosts formulation chemistry talent pipelines serving national manufacturers.
Norrland
Rural consumers sustain mass-market drugstore channels through pharmacist-endorsed dermocosmetic penetration. Post-consumer recycled glass supply bottlenecks compress margin structures for eco-positioned brands dependent on premium sustainable materials. Umeå's regional distribution centers serve dispersed populations across Västerbotten and Norrbotten counties.
Sweden Cosmetics Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-selling heritage sustaining recurring revenue in Nordic households while multinational R&D intensity anchors premium tier positioning. The vendor base stratifies across three tiers: biotechnology platform operators, specialty retail channel controllers, and mass-market accessibility providers. Two dominant competitive moves define current dynamics: exclusive brand partnerships consolidating shelf access, and microbiome science licensing agreements accelerating clinical efficacy claim differentiation.
Within the direct-selling heritage tier, Oriflame Holding occupies a position exemplifying subscription-based household loyalty models. Among multinational R&D-intensive operators, L'Oréal represents biotechnology platform investment patterns. On the specialty retail control vector, KICKS Group exemplifies channel consolidation through exclusive partnerships and in-store consultation services. These three anchors illustrate divergent strategic archetypes competing for urban millennial and Gen Z purchasing velocity across Swedish metropolitan zones.
| Leading Market Players |
|---|
| Oriflame Holding |
| Henkel |
| L'Oréal |
| KICKS Group |
| Shiseido |
| Estée Lauder Companies |
| Beiersdorf |
| Lumene |
| Unilever |
| Others |
Value Network & Pricing Analysis
Post-consumer recycled glass procurement costs cascade through Swedish cosmetics pricing tiers, compressing margins for Nordic Swan Ecolabel-certified brands while mass-market drugstore alternatives absorb less packaging premium. The EU Green Deal's biodegradable mandate timeline accelerates this cost transmission from upstream converters to downstream shelf pricing.
Pricing Analysis
Capacity additions in German and French sustainable packaging facilities are reshaping price floors for eco-positioned Swedish brands. Three-tier pricing structure across premium, standard, and economy levels separates clinical efficacy claims from clean certification tiers from basic accessibility. Pricing pressure stems from REACH compliance documentation costs intensifying across mid-tier manufacturers. Mass-market drugstore buyers exhibit highest price sensitivity, while urban millennials subscribing to personalized regimen platforms demonstrate lowest elasticity.
Supply Chain Analysis
Formulation chemist scarcity in Sweden and Denmark constrains batch production scalability for barrier-repair emulsions. Manufacturing concentrates in Germany, France, and Italy for active ingredient synthesis, with Nordic assembly for final packaging. Raw material dependencies include ceramide precursors, peptide libraries, and microbiome-derived postbiotics. Single-source vulnerability characterizes post-consumer recycled glass supply. Distribution runs through KICKS Group's specialty retail network and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's cosmetics sector operates as a regulatory compounder where EU Green Deal enforcement timelines and ECHA disclosure mandates continuously elevate compliance investment floors. The Swedish Chemicals Agency's PFAS restrictions ahead of EU baselines create asymmetric competitive barriers.
For Market Incumbents: Lock in microbiome science licensing agreements before diagnostic platform commoditization accelerates. Secure exclusive shelf partnerships with KICKS Group's consultation services to defend against direct-to-consumer subscription erosion. Prioritize backward integration into peptide synthesis capabilities to offset raw material cost volatility.
For New Entrants and Emerging Players: Capture male grooming barrier-repair demand in Gothenburg and Malmö metropolitan zones where clinical efficacy positioning remains underdeveloped. Deploy TikTok-native discovery patterns for niche fragrance limited-edition drops targeting Gen Z velocity. Leverage algorithmic targeting to bypass Stockholm's saturated retail corridor.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification timelines compress mid-tier manufacturer cash conversion cycles. Five-to-ten year viability favors biotechnology platform operators with personalized diagnostic integration. Target acquisition archetypes include AI-driven skin analysis device manufacturers and Nordic Swan Ecolabel-compliant packaging converters. Monitor ECHA's expanded ingredient disclosure implementation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Diagnostic Platform Integration | L'Oréal's R&D intensity anchors clinical efficacy claim differentiation in premium tiers. |
| Nordic Swan Ecolabel Dual Certification | Swedish Chemicals Agency enforcement creates compliance moats for certified formulations. |
| Direct-to-Consumer Subscription Launch | Oriflame's heritage model demonstrates recurring revenue capture in Nordic households. |
| Exclusive Specialty Retail Partnership | KICKS Group's channel control concentrates brand discovery in Stockholm's retail corridor. |
| Sustainable Packaging Backward Integration | Post-consumer recycled glass supply bottlenecks compel captive sourcing for eco-positioned brands. |
Research Methodology
Multiple input streams — primary interviews, regulatory filing analysis, and trade data reconciliation — were reconciled to construct segment-level demand estimates. Conversations with formulation chemists, specialty retail category managers, Swedish Chemicals Agency compliance officers, and biotechnology R&D directors informed qualitative assessments. Secondary validation drew from ECHA REACH registrations, EU Green Deal implementation timelines, Nordic Swan Ecolabel certification databases, and Swedish customs import records. Bottom-up brand-level revenue estimates triangulated against top-down household spending surveys.
Data-stream reconciliation across product type, distribution channel, customer demographic, and brand positioning dimensions structured the analytical framework. CAGRs were derived from trend extrapolation moderated by regulatory milestone impacts. Microbiome science patent filings and AI diagnostic device adoption curves served as technology diffusion inputs. Subscription platform penetration rates and social commerce velocity metrics informed channel shift assumptions across the projection horizon.
Regulatory enforcement delays, raw material supply disruptions, and consumer preference shifts toward unregulated indie alternatives are the dominant revision risks. Forecasts embed assumptions about ECHA disclosure timeline adherence and biodegradable packaging cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Night Cream Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
North America Face Compact Market