
 Botanical Skin Care Ingredients Market | 2026-2036
Botanical Skin Care Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Skin Care Ingredients Market Outlook
Phytochemistry expertise is reorganizing competitive boundaries as suppliers race to standardize active compound profiles in botanical extracts. Givaudan leverages integrated botanical sourcing networks across multiple climate zones to secure raw material consistency. Indena sustains leadership through advanced extraction technologies that isolate marker compounds for skin care actives. Sabinsa anchors its position with patented bioavailability enhancement processes for herbal derivatives.
Botanical skin care ingredients comprise plant-derived actives, including polyphenol-rich extracts, terpene-dense essential oils, lipid-based carrier oils, and micronized herbal powders, standardized for cosmetic efficacy through processes such as supercritical CO2 extraction and cold-press isolation. These inputs serve primarily as functional actives, emollients, and stabilizers in topical formulations targeting barrier repair, oxidative stress mitigation, and microbiome balance. Botanical extracts occupy the largest value share given their versatility across anti-aging and soothing applications, while essential oils command premium positioning in aromatherapeutic and high-performance serum segments. Carrier oils represent the fastest-expanding category as clean-label moisturizers displace synthetic emollients in mass-market creams and gels.
EU REACH and the EU Green Deal constrain permissible solvent residues and mandate biodegradability documentation for imported botanicals, elevating compliance costs for non-European suppliers. FDA cosmetic labeling requirements and emerging state-level fragrance disclosure laws in California and New York reshape formulation transparency expectations across North American supply chains. ISO 16128 guidelines on natural and organic cosmetic ingredients provide a harmonized definitional framework that reduces market fragmentation but intensifies certification competition. Stakeholders must monitor evolving biodegradability testing protocols and bioprospecting access regulations as supply chain due diligence requirements deepen.
Market Dynamics
Clean beauty mandates from personal care brands are compressing formulation cycles and forcing raw material suppliers to requalify under stricter botanical provenance standards. This demand-side pressure is restructuring supplier-buyer power dynamics across the value chain.
Growth Catalysts
- EU REACH biodegradability mandates:Compliance requirements for imported botanicals are accelerating investment in green solvent extraction infrastructure among European suppliers.
- Supercritical CO2 extraction:This cold-process technology preserves heat-sensitive polyphenols and terpenes that steam distillation degrades, expanding the functional claims portfolio for anti-aging serums.
- France and Germany:These formulation hubs are consolidating botanical sourcing relationships as brand headquarters demand shorter qualification timelines for new active ingredients.
Market Restraints
- Climate-dependent raw material volatility:Drought cycles in Mediterranean growing regions disrupt terpene yield consistency in essential oil crops.
- Supplier concentration in specific bioclimatic zones:Limited geographic diversity in certified organic lavender and chamomile cultivation creates single-source vulnerability.
- Patent thickets around bioavailability enhancement:Proprietary micellar delivery systems for herbal actives restrict formulation freedom for mid-tier cosmetic manufacturers.
Strategic Opportunities
- US state-level fragrance disclosure laws:California and New York mandates for ingredient transparency are creating first-mover advantage for suppliers with pre-standardized botanical traceability documentation.
- Microbiome-targeted topical applications:Prebiotic botanical extracts from polyphenol-rich sources are opening white space in barrier repair formulations.
- ISO 16128 certification harmonization:This definitional framework reduces market fragmentation and enables cross-border ingredient qualification efficiency.
Industry Challenges
- Phytochemistry analytical talent scarcity:Standardization of marker compound profiles requires specialized chromatography expertise that outpaces current training pipeline output.
- Dual certification timeline compression:Simultaneous EU organic and COSMOS approvals demand parallel documentation streams that strain smaller supplier compliance departments.
- Legacy emollient displacement friction:Reformulation of established cream bases with botanical carrier oils requires stability testing cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Skin Care Ingredients Market |
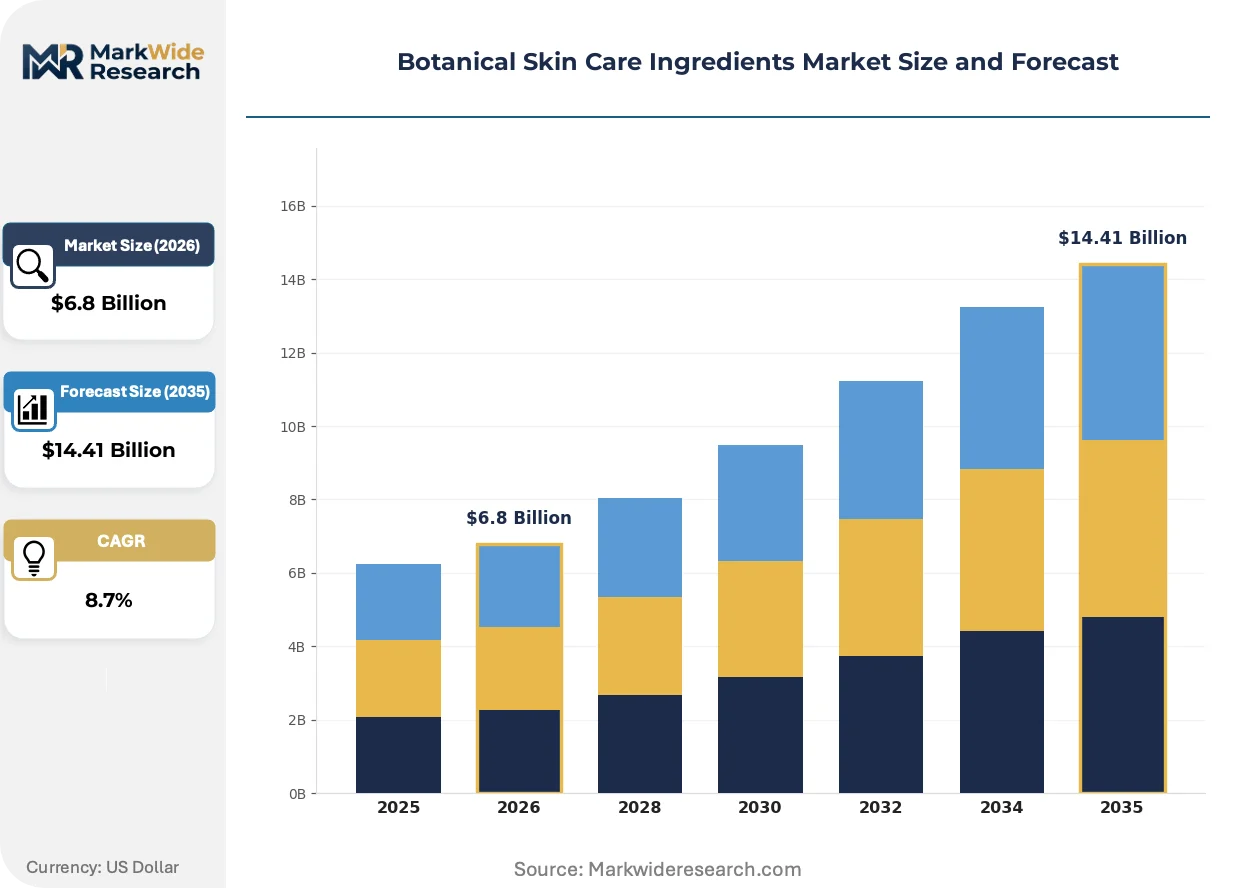
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Botanical Extracts, Essential Oils, Carrier Oils, Herbal Powders Application: Moisturizers, Serums, Cleansers, Masks Formulation: Creams, Gels, Oils, Emulsions End User: Beauty Salons, Personal Care Brands, Retailers, Private Label |
| Companies Covered | International Flavors & Fragrances, Givaudan, Indena, Martin Bauer Group, Indesso, Lipoid Kosmetic AG, Sabinsa, Nexira, BotanicalsPlus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Skin Care Ingredients Market Strategic Shifts
Biotechnology convergence with traditional extraction methods is redefining what constitutes a botanical active, blurring boundaries between plant-derived and bio-identical molecules. This fusion is compressing the innovation cycle from raw material to finished cosmetic claim.
Supercritical CO2 extraction paired with in-line chromatographic fractionation is displacing conventional solvent-based methods in high-value serum production. Premium cosmetic houses in France and Germany are adopting these systems to secure batch-to-batch consistency in polyphenol standardization. The displacement of hexane and ethanol residues eliminates reformulation costs for EU REACH compliance.
EU Green Deal solvent residue thresholds and biodegradability documentation requirements are forcing non-European suppliers to retrofit extraction facilities or exit the market. This regulatory tightening is concentrating qualified supplier relationships around integrated botanical networks with captive climate-zone diversification. French and German formulation hubs are responding by locking in multi-year supply agreements with compliant extractors.
Direct sourcing contracts between cosmetic brands and agricultural cooperatives are compressing traditional distributor margins in botanical supply chains. Mass-market personal care manufacturers in the United States are bypassing ingredient traders to secure cold-pressed carrier oils with verified organic chain of custody. This channel disintermediation is most visible in jojoba and argan oil procurement, where price transparency pressures are restructuring middle-tier supplier economics.
Botanical Skin Care Ingredients Market Segmentation
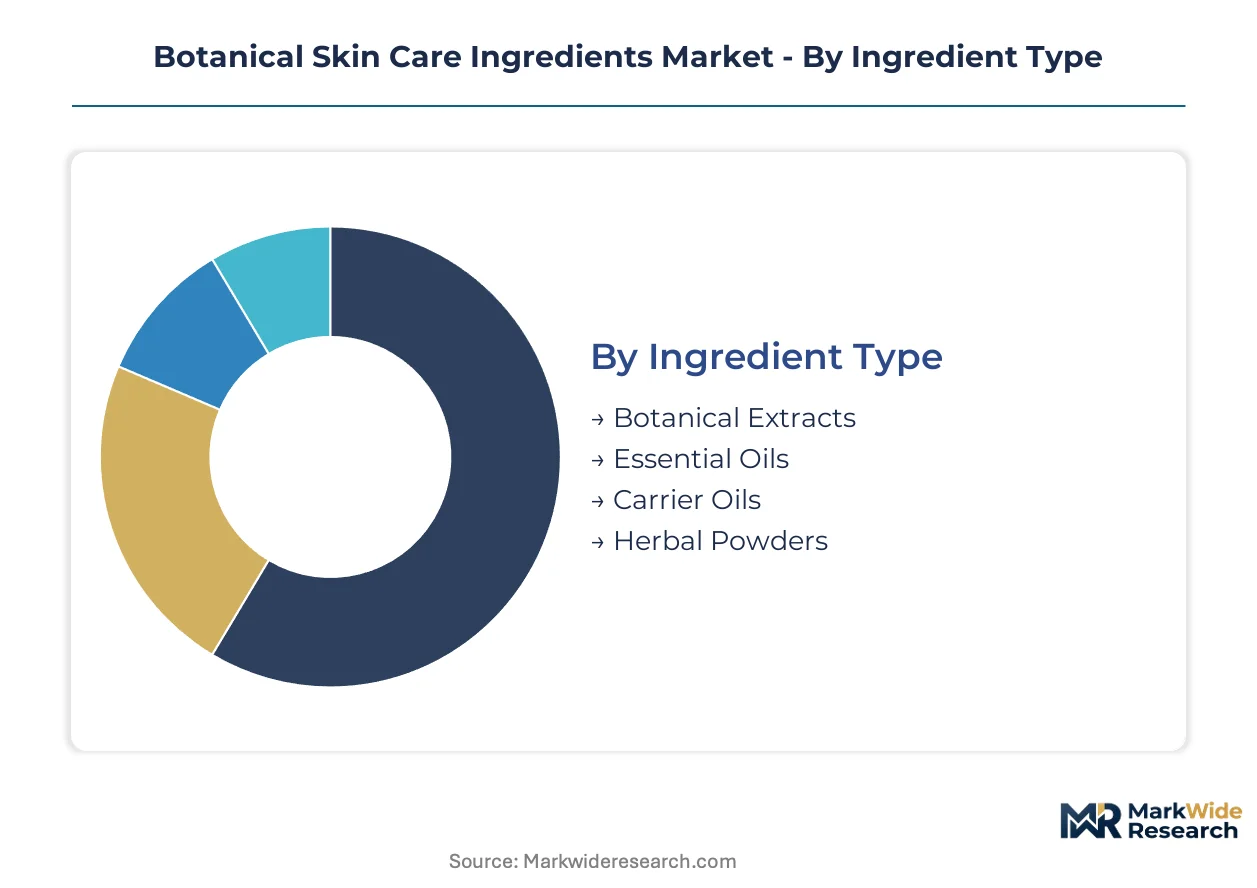
Ingredient categorization in botanical skin care determines extraction technology requirements, stability testing protocols, and regulatory qualification pathways. Each segment carries distinct supply chain risk profiles and margin structures that reshape supplier-buyer negotiations.
Ingredient Type:
Domestic cultivation dominates carrier oils and herbal powders, while essential oils and standardized extracts depend heavily on Mediterranean and tropical export zones.
- Botanical Extracts:Polyphenol-rich concentrates standardized through supercritical CO2 or ethanol extraction for anti-aging and soothing claims. French and German formulation hubs concentrate demand as brand headquarters compress qualification timelines for new actives. EU REACH solvent residue mandates favor suppliers with green extraction infrastructure.
- Carrier Oils:Cold-pressed lipid bases including jojoba, argan, and rosehip oils displace synthetic emollients in clean-label moisturizers. US mass-market manufacturers bypass distributors to secure direct contracts with agricultural cooperatives in Morocco and Argentina.
- Essential Oils:Terpene-dense aromatic fractions for aromatherapeutic and high-performance serum positioning.
- Herbal Powders:Micronized plant materials for physical exfoliation and visual texture in mask formulations.
Botanical extracts hold the largest share; momentum sits with carrier oils.
Application:
Cost tier stratification separates premium serum actives from mass-market moisturizer bases, with cleansers and masks occupying intermediate positioning.
- Moisturizers:High-volume cream and lotion bases incorporating carrier oils and basic extracts for barrier repair claims. US retailers and private label manufacturers drive volume procurement of cost-optimized botanical emollients.
- Serums:Concentrated treatment formats demanding standardized polyphenol profiles and bioavailability enhancement. French cosmetic houses specify supercritical CO2 extracts with chromatographic fractionation for batch consistency.
- Cleansers:Mild surfactant systems with botanical extracts for sensory differentiation and skin-conditioning benefits.
- Masks:Clay and hydrogel vehicles combining herbal powders with extract soaks for immediate visible effects.
Moisturizers dominate volume; serums command the steepest expansion trajectory.
Formulation:
Volume concentration favors emulsions for mass-market distribution, while oils and gels serve premium positioning with simpler supply chains.
- Emulsions:Water-in-oil or oil-in-water systems stabilizing botanical actives in shelf-stable formats. German manufacturers lead technical specification for emulsion compatibility with sensitive polyphenol structures.
- Oils:Anhydrous formats preserving terpene integrity without preservative systems. Direct brand-cooperative sourcing concentrates in argan and jojoba procurement channels.
- Creams:Semisolid emulsions requiring stability testing cycles that delay reformulation with botanical carrier oils.
- Gels:Hydrocolloid matrices with limited botanical oil loading but clean-label appeal for younger demographics.
Emulsions capture the largest share; oils are gaining share fastest.
End User:
Customer type determines procurement scale and documentation requirements, from bulk traders serving retailers to captive supply for integrated personal care brands.
- Personal Care Brands:Integrated manufacturers with in-house formulation and direct agricultural contracting. California and New York fragrance disclosure laws force these buyers to demand pre-standardized botanical traceability documentation.
- Beauty Salons:Professional channel purchasing smaller volumes of high-concentration extracts for treatment protocols.
- Retailers:Mass-market distributors specifying cost-optimized carrier oils with basic organic certification.
- Private Label:Contract manufacturers serving multiple retail banners with flexible formulation and rapid turnaround requirements.
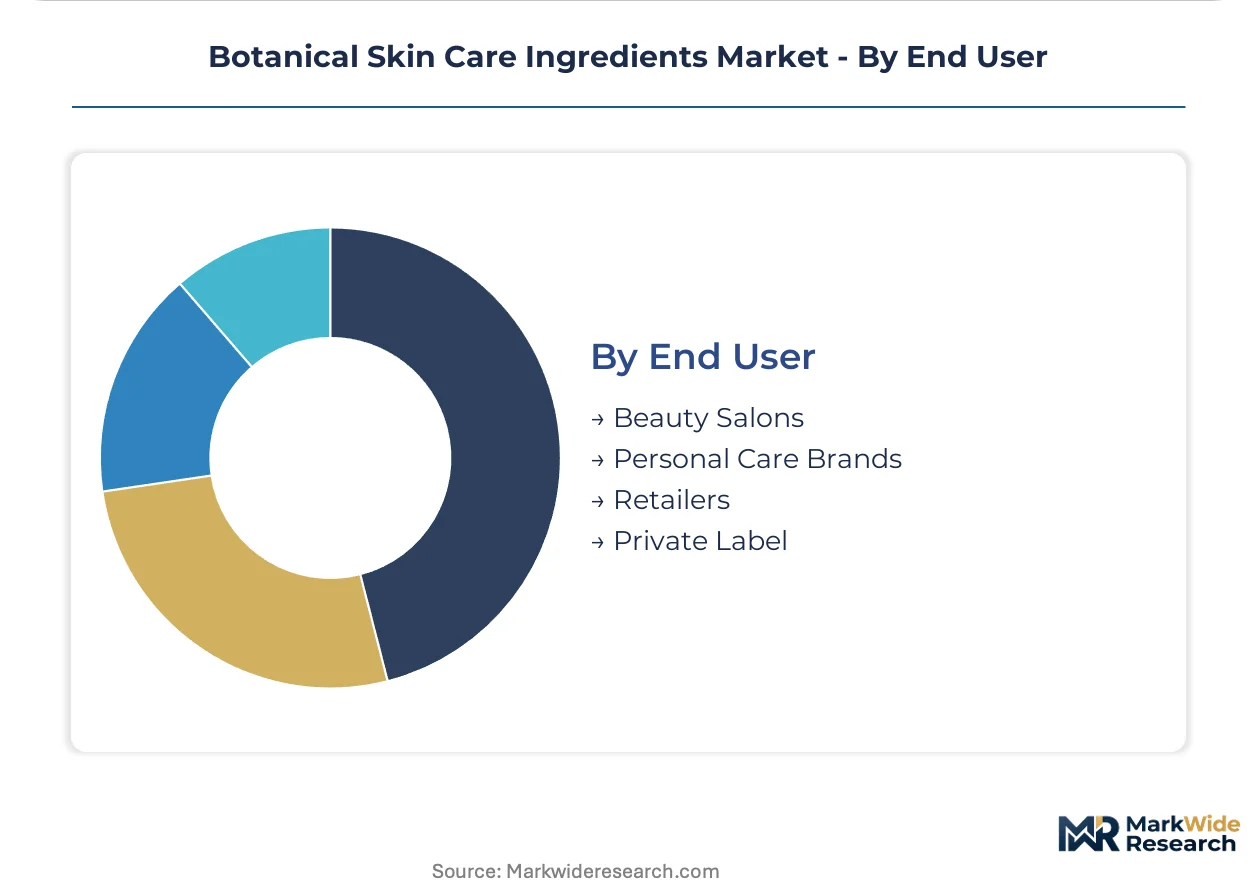
Personal care brands hold the largest share; private label shows the fastest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between formulation-intensive European markets and volume-driven North American procurement, with Asia-Pacific emerging as a dual-use zone blending premium extraction demand with cost-optimized bulk sourcing.
United States
Mass-market personal care manufacturers drive carrier oil procurement through direct agricultural contracting, bypassing traditional distributors. California and New York state-level fragrance disclosure laws compel brands to demand pre-standardized botanical traceability documentation. The Pacific Northwest and California clusters concentrate clean beauty brand headquarters that compress supplier qualification timelines.
Germany
Formulation hubs in North Rhine-Westphalia and Bavaria anchor technical specification leadership for emulsion-compatible polyphenol structures. ECHA REACH biodegradability mandates accelerate green solvent extraction infrastructure investment among domestic extractors. The Frankfurt-Rhine-Main corridor hosts integrated botanical networks with captive climate-zone diversification.
France
Premium cosmetic houses in the Île-de-France region specify supercritical CO2 extracts with chromatographic fractionation for batch consistency in anti-aging serums. ANSM cosmetic safety requirements intersect with EU Green Deal solvent residue thresholds. The Provence-Alpes-Côte d'Azur zone concentrates lavender and chamomile cultivation vulnerable to drought-driven terpene yield volatility.
India
Herbal derivatives suppliers leverage BIS quality certification and traditional medicine knowledge systems for export positioning to European formulators. CDSCO cosmetic ingredient regulations align with international harmonization pressures. The Maharashtra and Gujarat industrial corridors develop extraction capacity serving both domestic Ayurvedic brands and international clean beauty supply chains.
Brazil
Biodiversity-rich Atlantic Forest and Cerrado biomes supply unique botanical actives for microbiome-targeted topical applications. ANVISA cosmetic registration requirements shape documentation standards for exported extracts. São Paulo state anchors formulation partnerships linking agricultural cooperatives to international personal care brands seeking novel prebiotic botanical sources.
Botanical Skin Care Ingredients Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with mid-scale regional extractors filling supply gaps in specific bioclimatic zones. The upper tier commands multi-year supply agreements through captive sourcing networks across climate-diverse growing regions. Specialist players compete on extraction technology differentiation—supercritical CO2, cold-press isolation, advanced chromatographic fractionation. Dominant competitive moves include backward integration into agricultural contracting and technology licensing for bioavailability enhancement processes.
Within the integrated extraction technology tier, Givaudan and Indena exemplify archetypes of climate-zone diversified sourcing and advanced marker compound standardization respectively. Sabinsa occupies a position representing patented delivery system specialists. These three anchors illustrate how competitive boundaries are reorganizing around phytochemistry expertise rather than raw material access alone.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Givaudan |
| Indena |
| Martin Bauer Group |
| Indesso |
| Lipoid Kosmetic AG |
| Sabinsa |
| Nexira |
| BotanicalsPlus |
| Others |
Value Chain & Pricing Dynamics
Ninety-day crop-to-extraction lead times in Mediterranean lavender and chamomile zones concentrate pricing power with integrated suppliers possessing captive climate diversification, while direct brand-cooperative contracting in Moroccan argan channels compresses distributor margins and resets benchmark pricing for cold-pressed carrier oils.
Pricing Analysis
Long-term offtake agreements dominate procurement for supercritical CO2 extracts with standardized polyphenol profiles, locking in volume commitments from French and German formulation hubs. Three-tier pricing structure across premium chromatographic fractions, standard ethanol extracts, and economy-grade cold-pressed oils reflects certification grade and extraction technology intensity. Cost compression in economy carrier oils intensifies because US mass-market manufacturers bypass distributors for direct agricultural contracts. Private label contract manufacturers exhibit highest price sensitivity, while premium cosmetic houses in France absorb premiums for batch-consistent serum actives.
Supply Chain Analysis
Strait of Gibraltar transit underwrites essential oil flows from Moroccan and Tunisian cultivation zones to European extraction facilities, creating logistics vulnerability for terpene-dense aromatic fractions. Supply concentrates in France, Germany, and Morocco for lavender, chamomile, and argan respectively, with India and Brazil emerging for herbal derivatives and biodiversity-rich prebiotic sources. Raw material dependencies rest on drought-vulnerable Mediterranean growing regions, polyphenol-standardized extract inventories, and cold-pressed lipid bases. Single-source vulnerability in certified organic lavender cultivation elevates supply chain risk. Distribution runs through integrated botanical networks with captive climate-zone diversification, displacing traditional trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as clean beauty mandates from personal care brands reaccelerate ingredient demand after regulatory qualification disruptions.
For Market Incumbents: Secure multi-year supply agreements with agricultural cooperatives in Morocco and Argentina to defend against direct brand contracting that erodes distributor economics. Invest in green solvent extraction infrastructure to maintain EU REACH qualification as non-compliant suppliers exit. Backward integration into Provence-Alpes-Côte d'Azur lavender cultivation mitigates drought-driven terpene yield volatility threatening batch consistency. For New Entrants and Emerging Players: Differentiate on microbiome-targeted prebiotic botanical extracts from Brazilian Atlantic Forest biodiversity, a white space with limited incumbent patent coverage. Target private label contract manufacturers seeking rapid formulation turnaround with flexible carrier oil sourcing and ISO 16128 pre-standardized documentation. Pursue technology licensing partnerships for bioavailability enhancement processes rather than proprietary R&D buildout. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because phytochemistry analytical talent scarcity and dual certification timeline compression favor scaled integrated extractors over fragmented regional suppliers. Acquisition focus: mid-tier European extractors with supercritical CO2 infrastructure and existing COSMOS approval pipelines. Watch ECHA REACH solvent residue threshold enforcement as inflection indicator for supplier exit velocity and pricing power reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Contracting | Captive supply of Moroccan argan and Provence lavender secures batch consistency against climate volatility. |
| Green Solvent Extraction Infrastructure Investment | EU REACH biodegradability mandates favor suppliers with supercritical CO2 and cold-press capabilities. |
| Prebiotic Botanical Extract Development | Brazilian biodiversity sources open microbiome-targeted white space in barrier repair formulations. |
| ISO 16128 Certification Harmonization | Cross-border qualification efficiency reduces dual certification timeline strain for smaller suppliers. |
| Direct Brand-Cooperative Sourcing Contracts | Channel disintermediation in US mass-market carrier oil procurement compresses traditional distributor margins. |
Study Parameters
Cross-validation between primary interviews with extraction technology directors, cosmetic formulation chemists, agricultural cooperative managers, and EU regulatory compliance officers anchors the qualitative findings, while secondary validation draws from ECHA REACH guidance documents, ANSM cosmetic safety filings, customs trade data for essential oil and carrier oil flows, and SEC disclosures from integrated personal care brands. Bottom-up triangulation across ingredient type volumes and top-down reconciliation against end-use application demand ensures consistency.
Sensitivity analysis around drought frequency in Mediterranean growing regions, EU Green Deal solvent residue threshold enforcement timing, and US state-level fragrance disclosure law adoption pace informs the analytical framework. Segmentation dimensions modeled include ingredient type, application format, end-user category, and regional regulatory cluster. CAGRs were derived from volume trajectory analysis against price elasticity assumptions, incorporating supercritical CO2 extraction capacity expansion schedules and clean beauty brand formulation pipeline visibility.
Forecasts assume regulatory continuity in EU REACH, FDA cosmetic labeling, and California fragrance disclosure regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as climate-driven raw material volatility and bioprospecting access regulation evolution reshape supply economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Face Wash Market