
 Period Balm Market | 2026-2036
Period Balm Market Size, Share, and Industry Trends Forecast 2026-2036
Period Balm Market Analytics
Certified organic formulation expertise is redrawing competitive boundaries in period balm manufacturing. Cora leverages its vertically integrated supply chain to secure consistent botanical sourcing. Earth Mama Organics anchors its market presence through clinician-trusted positioning in maternity and postpartum channels. Rael competes via K-beauty-inspired product architecture and Asian market distribution density.
Period balm denotes a topical anhydrous or emollient preparation containing active ingredients such as menthol, arnica, clary sage essential oil, or cannabidiol, formulated for transdermal application to relieve dysmenorrhea-associated cramping and muscular tension. The balm matrix typically employs a shea butter or beeswax base with melting points calibrated between 32°C and 37°C for controlled dermal release. Balm and stick formats dominate current revenue owing to portability and precise dosing, while essential oil and herbal ingredient types command margin premiums through perceived efficacy differentiation and clean-label positioning. The adolescent customer segment represents the fastest-expanding addressable pool as school-based wellness education normalizes proactive menstrual symptom management.
FDA cosmetic labeling requirements and EMA guidelines on essential oil concentration limits shape permissible claims and safety testing burdens for period balm entrants. BIS standards in India and KFDA regulations in South Korea add compliance layers for brands pursuing multi-territory distribution. ISO 16128 on natural and organic cosmetic ingredients increasingly serves as a baseline reference for ingredient transparency documentation. Stakeholders must monitor evolving state-level cannabis derivative regulations, as CBD-infused variants face fragmented legal status that could either unlock premium positioning or trigger reformulation costs.
Market Dynamics
Clean-label ingredient mandates from FDA and EMA are forcing period balm manufacturers to reformulate around restricted essential oil concentrations and botanical sourcing documentation, compressing margins while creating tiered competitive positions based on certification depth.
Growth Catalysts
- ISO 16128 adoption:Natural and organic cosmetic ingredient standards are accelerating transparency investments across European and North American supply chains, rewarding brands with documented botanical provenance.
- Adolescent wellness education:School-based menstrual health programs in the United States, Germany, and South Korea are normalizing proactive symptom management and expanding first-time user acquisition.
- Postpartum channel expansion:Maternity retail and clinician endorsement networks are creating dedicated distribution pathways for recovery-focused balm formulations.
Market Restraints
- Shea butter price volatility:West African supply disruptions and climate variability are destabilizing base matrix costs for anhydrous formulations.
- CBD regulatory fragmentation:Inconsistent state-level cannabis derivative laws in the United States create reformulation risks and limit cross-border inventory mobility.
- Beeswax supply concentration:Dependence on commercial apiary regions in China and Argentina introduces single-source vulnerability for stick-format production.
Strategic Opportunities
- Indian regulatory alignment:BIS standards for natural cosmetics present a compliance pathway for brands seeking entry into underpenetrated South Asian markets.
- Direct-to-consumer subscription models:Menstrual cycle tracking apps and wellness platforms are creating embedded commerce channels with recurring revenue potential.
- Clary sage-cannabidiol convergence:Formulation science combining terpene-rich botanicals with hemp-derived actives is opening premium positioning in jurisdictions with clarified CBD status.
Industry Challenges
- Cosmetic chemist scarcity:Specialized expertise in transdermal delivery systems for temperature-sensitive balm matrices commands premium compensation and extends R&D timelines.
- Multi-territory testing burdens:Divergent dermal irritation protocols across FDA, EMA, KFDA, and BIS jurisdictions multiply pre-market validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Period Balm Market |
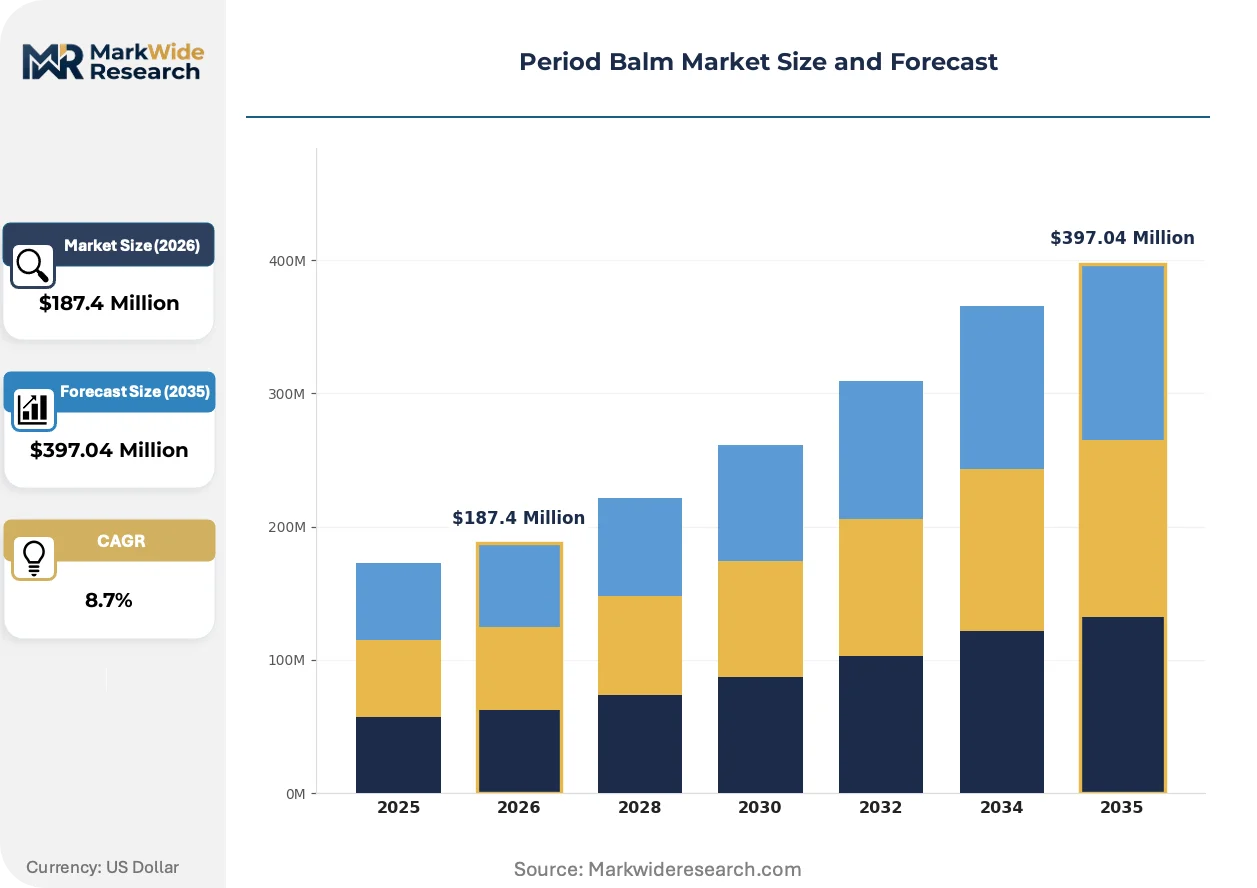
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balm, Oil, Cream, Stick Ingredient Type: Natural, Synthetic, Herbal, Essential Oil Application Area: Abdomen, Lower Back, Thighs, Neck Customer Type: Women, Adolescents, Postpartum, Others |
| Companies Covered | Cora, Rael, Earth Mama Organics, Brùme, Zen Maitri, Lola, Pink Stork, The Honest Company, Still Not A Hippie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Period Balm Market Evolving Landscape
Formulation science and distribution architecture are converging to reshape how period balms reach consumers, with technology miniaturization, regulatory transparency mandates, and channel disintermediation operating as interconnected forces.
Microencapsulation technology for essential oil stabilization is miniaturizing active ingredient delivery systems, enabling precise dosing in portable stick formats. Adolescent consumers and travel-oriented segments are adopting these formats at accelerated rates. The structural consequence is compression of traditional jar-format market share and elevation of unit economics for precision-engineered products.
EMA guidelines on essential oil concentration limits and FDA cosmetic labeling requirements are mandating expanded safety documentation and restricted therapeutic claims. Manufacturers must now invest in dermal toxicity testing and reformulate around permissible active thresholds. Premium-positioned brands in Germany and the United States are responding by pursuing ISO 16128 certification to differentiate on transparency.
Subscription-based menstrual wellness bundles are displacing single-purchase retail models, with direct-to-consumer platforms capturing recurring revenue through cycle-synced replenishment. Traditional pharmacy and mass retail channels in South Korea and the United States face margin compression as wellness apps integrate embedded commerce. The behavioral shift is most visible among digitally native consumers seeking convenience and personalization over shelf accessibility.
Period Balm Market Segmentation
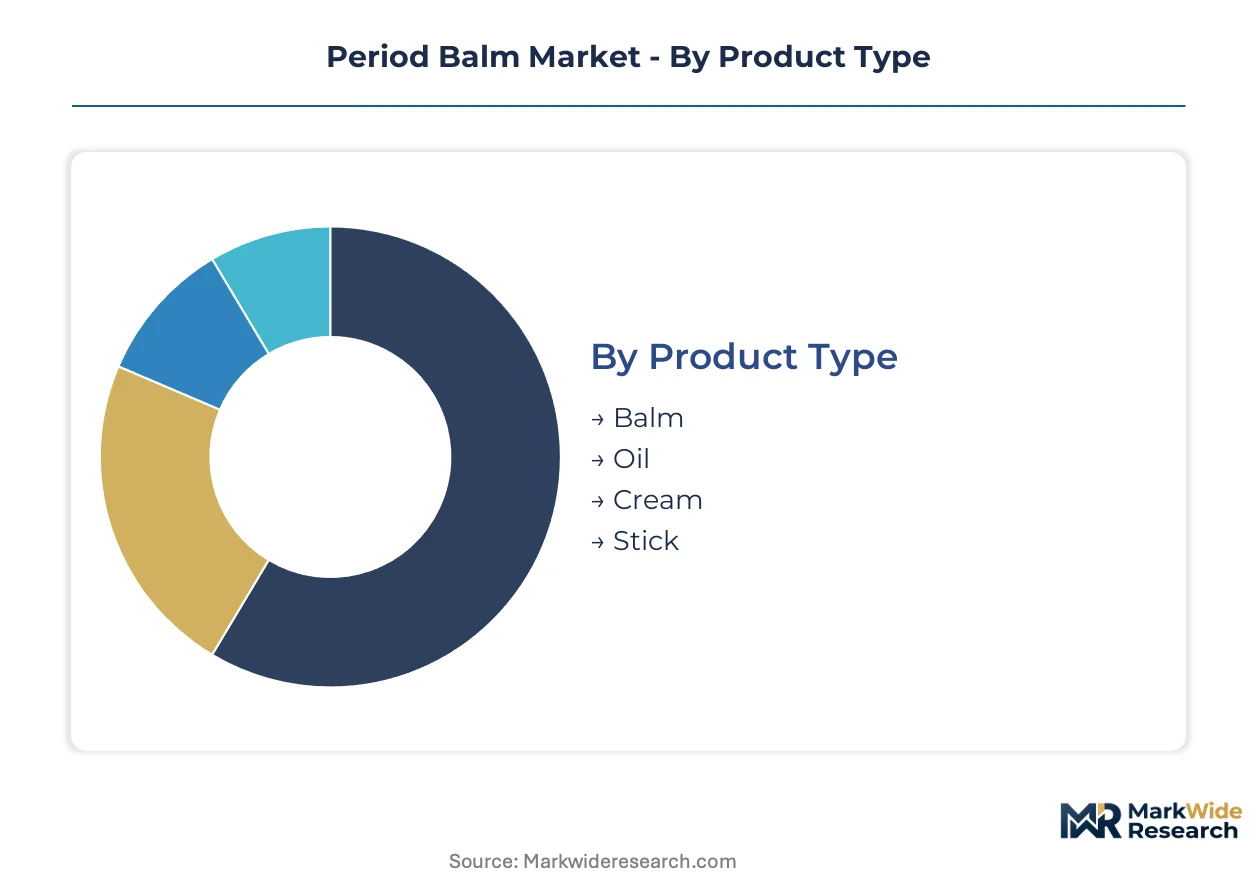
Period balm manufacturers configure product architecture around four intersecting dimensions: physical format, active chemistry, anatomical targeting, and life-stage user profiles. Each segmentation axis carries distinct margin structures, regulatory burdens, and substitution vulnerabilities that reshape competitive positioning.
Product Type:
Stick formats face the most acute substitution pressure from portable roll-on analgesics and disposable heat patches, forcing balm and stick producers to defend portability advantages through precise dosing engineering.
- Balm:Anhydrous shea butter or beeswax matrices with calibrated melting points between 32°C and 37°C enable controlled dermal release of menthol, arnica, or clary sage actives. German and United States direct-to-consumer wellness channels concentrate demand for jar-format balms as adolescent consumers normalize school-based symptom management routines.
- Stick:Solid emollient cylinders deliver portable, mess-free application with precise dosing control. South Korean K-beauty distribution networks and travel retail segments in the United States prioritize stick formats for on-the-go menstrual symptom relief.
- Oil:Liquid carrier systems with faster skin penetration rates suit massage-oriented application rituals and professional spa channels.
- Cream:Water-in-oil emulsions with lighter sensory profiles target consumers preferring non-greasy finishes and rapid absorption.
Balm retains volume leadership; stick holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification runs deepest across this axis, with certification depth separating premium botanical positioning from commodity synthetic alternatives.
- Natural:Plant-derived bases and actives documented under ISO 16128 standards command transparency premiums in EMA-regulated European markets and FDA-scrutinized United States channels.
- Essential Oil:Terpene-rich formulations face EMA concentration limits and FDA cosmetic labeling requirements that elevate safety testing burdens. Clary sage and menthol variants concentrate demand among German consumers seeking clinician-trusted efficacy signals.
- Herbal:Traditional botanical preparations including arnica and calendula extracts compete on perceived gentleness for postpartum recovery applications.
- Synthetic:Laboratory-engineered actives and petroleum-derived bases occupy economy positioning with compressed margins and limited differentiation.
Essential oil captures margin leadership; natural ingredients are gaining share fastest.
Application Area:
Volume concentration maps directly onto cramp severity patterns and clothing coverage norms, with discrete application sites enabling differentiated positioning.
- Abdomen:Primary dysmenorrhea targeting commands the largest addressable base across all customer segments, with balm and stick formats optimized for under-clothing portability.
- Lower Back:Secondary muscular tension relief expands usage occasions beyond menstrual cramping into general wellness positioning.
- Thighs:Radiating pain pathways and lymphatic massage rituals create niche demand among postpartum recovery and athletic recovery crossover segments.
- Neck:Tension headache adjacencies represent the smallest application niche with highest substitution risk from dedicated migraine therapies.
Abdomen dominates volume; lower back shows the steepest expansion trajectory.
Customer Type:
Life-stage segmentation determines channel strategy, with educational institution access and clinical endorsement networks creating divergent acquisition economics.
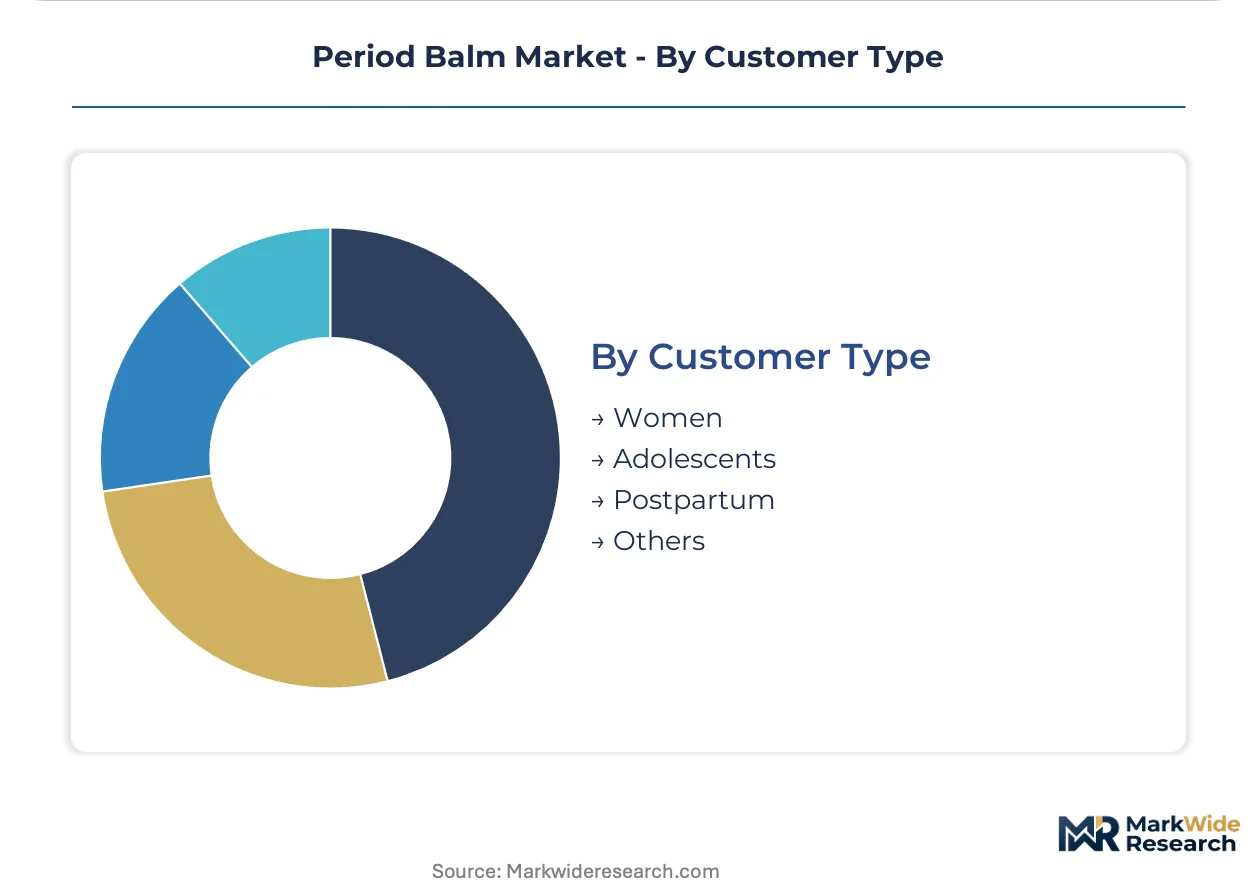
- Adolescents:School-based menstrual health programs in the United States, Germany, and South Korea normalize proactive symptom management. This segment climbs fastest as first-time user acquisition accelerates through wellness education curricula and peer socialization.
- Women:Established menstrual care consumers in the 18-45 demographic sustain baseline volume through pharmacy, mass retail, and direct-to-consumer subscription replenishment.
- Postpartum:Maternity retail networks and clinician endorsement pathways in the United States and Germany create dedicated distribution for recovery-focused formulations with arnica and calendula positioning.
- Others:Transgender and non-binary consumers seeking gender-inclusive menstrual care represent an emerging addressable pool with specialized messaging requirements.
Women sustain volume leadership; adolescents command the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Period balm consumption patterns diverge sharply across geographies, with direct-to-consumer wellness channels dominating in North America and Europe while pharmacy-retail hybrids prevail in Asian markets. German consumers prioritize clinician-endorsed formulations, whereas South Korean demand clusters around K-beauty portability aesthetics. United States volume concentrates in subscription-driven adolescent acquisition.
United States
School-based menstrual health curricula and cycle-tracking app integrations are normalizing proactive symptom management among adolescents. FDA cosmetic labeling requirements and state-level CBD fragmentation create compliance complexity for multi-state distribution. Direct-to-consumer wellness brands in New York and California are building embedded commerce channels through menstrual cycle subscription platforms.
Germany
Clinician-trusted positioning in maternity and postpartum channels sustains premium pricing for arnica-based recovery formulations. EMA guidelines on essential oil concentration limits mandate reformulation investments and expanded dermal toxicity documentation. Natural cosmetics clusters in Bavaria and Baden-Württemberg are advancing ISO 16128 certification depth to differentiate botanical provenance claims.
South Korea
K-beauty-inspired stick formats command portability premiums among travel-oriented and digitally native consumer segments. MFDS regulations on cosmetic safety and ingredient disclosure shape permissible claims and pre-market testing burdens. Seoul-based wellness platforms are disintermediating traditional pharmacy channels through cycle-synced subscription bundles and embedded app commerce.
United Kingdom
Postpartum recovery positioning through midwife endorsement networks is expanding maternity retail penetration for herbal formulations. MHRA alignment with EMA cosmetic guidelines ensures regulatory continuity for cross-European formulation strategies. London-headquartered direct-to-consumer brands are leveraging NHS menstrual health education partnerships to accelerate adolescent first-time user acquisition.
India
Underpenetrated South Asian markets present expansion opportunities for natural cosmetics meeting BIS standards documentation. CDSCO and FSSAI regulatory convergence on cosmetic safety is elevating import compliance costs for international entrants. Maharashtra and Karnataka wellness retail clusters in Mumbai and Bangalore are incubating domestic Ayurveda-inspired balm formulations for menstrual symptom relief.
Period Balm Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in period balm manufacturing, with supply chain control over shea butter and beeswax sourcing separating premium positioning from commodity competition. The market structures around three archetypes: vertically integrated botanical specialists, clinician-endorsed maternity channel anchors, and K-beauty-inspired portability innovators. Competitive moves concentrate on ISO 16128 certification depth, direct-to-consumer subscription infrastructure, and multi-territory regulatory compliance capabilities.
Within the integrated specialist tier, Cora and Earth Mama Organics represent contrasting geographic and channel strategies, with the former anchoring North American direct-to-consumer subscription density and the latter exemplifying clinician-trusted maternity network penetration. Rael occupies a position bridging Asian distribution density with K-beauty product architecture, illustrating how portability engineering and cycle-tracking app integration can displace traditional retail shelf presence. These three companies collectively demonstrate how supply chain control, certification depth, and channel-specific positioning create defensible tier separation in a market where formulation transparency increasingly determines consumer selection.
| Leading Market Players |
|---|
| Cora |
| Rael |
| Earth Mama Organics |
| Brùme |
| Zen Maitri |
| Lola |
| Pink Stork |
| The Honest Company |
| Still Not A Hippie |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for shea butter and beeswax base matrices concentrate cost volatility exposure among stick-format producers, amplifying pricing power for vertically integrated operators with captive West African and Argentine apiary sourcing. This lead-time structure rewards manufacturers holding strategic stockpiles against climate-driven supply disruptions while compressing margins for just-in-time dependent competitors.
Pricing Analysis
Long-term offtake contracts for certified organic shea butter and clary sage extracts dominate procurement among premium-positioned German and United States manufacturers, insulating against spot-market volatility while locking in ISO 16128 transparency premiums. Price differentiation separates ISO-certified botanical formulations from commodity synthetic alternatives, with adolescent-targeted subscription bundles commanding the highest price inelasticity. Cost compression in standard-tier jar formats intensifies as mass retail pharmacy channels consolidate purchasing power. Postpartum recovery segments show least price sensitivity due to clinician endorsement premiums.
Supply Chain Analysis
Strategic stockpile preferences concentrate among manufacturers serving EMA-regulated European markets, where essential oil concentration compliance mandates extended safety documentation lead times. Shea butter sourcing draws from Ghana, Burkina Faso, and Ivory Coast; beeswax dependence centers on Chinese and Argentine commercial apiary regions. Single-source vulnerability in South American wax supply introduces reformulation risk for stick-format producers. Distribution runs through direct-to-consumer wellness platforms, menstrual cycle tracking apps, and maternity retail networks with embedded subscription commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Period balm markets are approaching a platform-economics inflection as cycle-tracking apps and wellness subscription platforms disintermediate traditional pharmacy retail, with interoperability between menstrual health data and automated replenishment creating embedded commerce lock-in.
For Market Incumbents: Secure backward integration into West African shea butter cooperatives and Argentine apiary networks to defend margin position against climate-driven input volatility. Invest in ISO 16128 certification depth to differentiate from synthetic-formulation entrants exploiting clean-label mandates. Control channel access through exclusive cycle-tracking app partnerships that block emerging competitors from subscription replenishment workflows.
For New Entrants and Emerging Players: Postpartum recovery channel gaps in underpenetrated South Asian markets present white-space acquisition economics with lower competitive density than saturated adolescent segments in North America. Target Indian metropolitan wellness retail clusters in Mumbai and Bangalore with BIS-compliant Ayurveda-inspired formulations. Pursue clinician endorsement networks in maternity hospitals as the primary go-to-market angle rather than competing for shelf space in consolidated pharmacy retail.
For Investors and Strategic Acquirers: Carve-out targets emerge from personal care conglomerates with dormant botanical sourcing assets and underutilized ISO 16128 certification infrastructure. Long-term viability hinges on subscription retention economics and regulatory compliance capabilities rather than single-purchase brand equity. Watch for state-level CBD regulatory clarification in the United States as the signal indicating premium formulation expansion or forced reformulation writedowns.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16128 Certification Investment | EMA and FDA transparency mandates reward documented botanical provenance with premium positioning in German and United States channels. |
| Direct-to-Consumer Subscription Launch | Cycle-tracking app integration captures recurring revenue and displaces traditional pharmacy retail shelf dependence. |
| Backward Integration into Shea Butter Sourcing | Captive West African supply insulates margin compression from climate-driven commodity volatility in base matrix costs. |
| Postpartum Channel Expansion | Clinician endorsement networks in maternity retail create defensible positioning with higher price inelasticity than adolescent segments. |
| CBD Regulatory Compliance Pathway | State-level cannabis derivative law monitoring enables rapid pivot between premium positioning and reformulation cost avoidance. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulation chemists, menstrual wellness brand managers, maternity retail buyers, and regulatory affairs specialists, then refined through secondary validation against FDA cosmetic labeling guidance, EMA essential oil concentration guidelines, ISO 16128 natural cosmetics standards, and South Korean MFDS safety disclosure requirements. Bottom-up demand modeling across product format, ingredient certification tier, and customer life-stage segments was triangulated with top-down market sizing from trade customs data and wellness platform subscription disclosures.
Variance decomposition across the projection horizon isolates volume sensitivity to adolescent education program expansion rates, postpartum channel penetration curves, and CBD regulatory status evolution in key jurisdictions. Segmentation dimensions modeled include physical format architecture, active chemistry certification depth, anatomical targeting specificity, and life-stage user profiles with channel preference mapping. CAGRs were derived from elasticity-adjusted adoption curves incorporating school-based wellness curriculum rollout schedules and direct-to-consumer platform subscriber acquisition costs.
Underlying assumptions cover shea butter supply stability, EMA essential oil concentration limit continuity, and cycle-tracking app commerce penetration rates, with deviation risk concentrated in West African climate disruption, United States state-level CBD law fragmentation, and beeswax apiary disease outbreaks. Revision becomes warranted when clean-label certification adoption thresholds cross inflection points that reconfigure competitive tier boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Silicone Makeup Sponge Market