
 North America Face Compact Market | 2026-2036
North America Face Compact Market Size, Share, and Industry Trends Forecast 2026-2036
North America Face Compact Market Insights
Aftermarket service revenue from refillable compact programs is fragmenting across brand-owned channels and third-party beauty retailers. L'Oréal S.A. leverages its extensive R&D infrastructure to develop sustainable packaging formats that reduce material waste. The Estée Lauder Companies Inc. anchors its North American position through prestige department store partnerships and loyalty ecosystems. Coty Inc. competes aggressively in the mass-market tier through pharmacy and drugstore distribution networks.
A face compact is a pressed or baked powder formulation housed in a portable case, typically containing talc, mica, silica, and binding agents, designed for skin-tone correction, oil absorption, and finish setting during cosmetic application. The manufacturing process involves hydraulic pressing at controlled temperatures to achieve uniform density and pan adhesion. Pressed powder dominates unit volume due to its convenience and shelf stability, while cream compact formats capture expanding margin pools among dry-skin and mature demographics seeking emollient-rich coverage. Online retail channels represent the fastest-growing distribution vector, though specialty stores sustain higher conversion rates through tactile trial and shade-matching services.
The U.S. FDA governs cosmetic ingredient safety and labeling accuracy under the Federal Food, Drug, and Cosmetic Act, while Health Canada's PMRA enforces parallel standards for product claims and allergen disclosure across Canadian provinces. California's Proposition 65 adds state-level chemical warning requirements that compel reformulation of certain pigment and preservative systems. Stakeholders must monitor evolving state-level fragrance disclosure legislation and cross-border e-commerce duty structures that could alter competitive positioning between domestic and imported compact offerings.
Market Dynamics
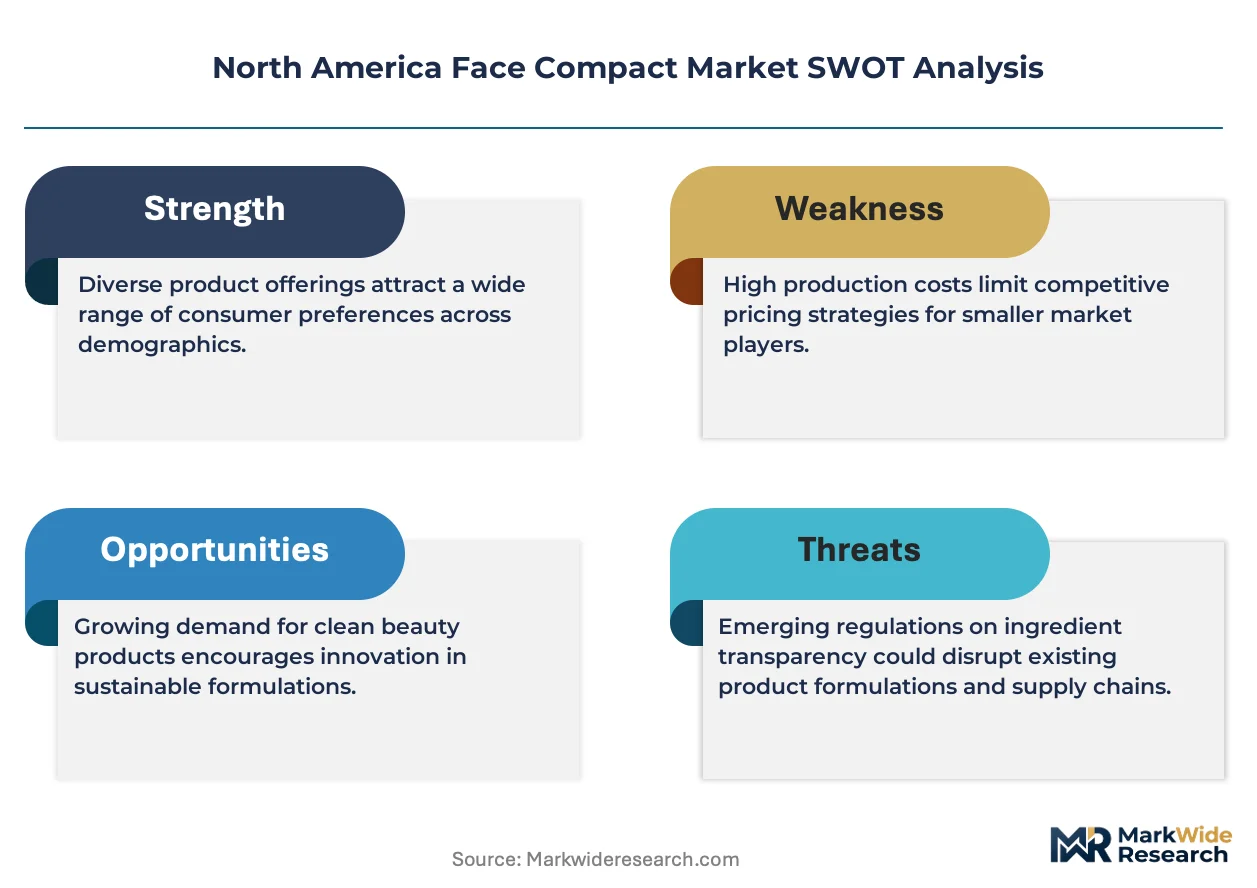
Refillable compact architectures are restructuring North American manufacturing priorities as brands confront California's Proposition 65 chemical disclosure mandates and Health Canada's tightening allergen labeling standards. The convergence of regulatory stringency and consumer sustainability expectations is compressing formulation-to-shelf timelines while elevating capital requirements for compliant packaging infrastructure.
Growth Catalysts
- Professional Makeup Artist Adoption:Salon and studio professionals across the U.S. and Canada are standardizing multi-use compact formats that streamline kit portability and shade versatility.
- FDA Ingredient Safety Framework:The U.S. FDA's modernized cosmetic safety protocols under the Federal Food, Drug, and Cosmetic Act are legitimizing premium positioning for compliant domestic manufacturers.
- Silica-Based Formulation Advances:Engineered silica particles are improving oil absorption performance in pressed powder compacts, extending wear duration for humid climate applications in Florida and Gulf Coast markets.
Market Restraints
- Talc Supply Concentration:Dependence on limited U.S. talc mining operations and select international suppliers creates input cost volatility for pressed powder formulations.
- Proposition 65 Compliance Burden:California's chemical warning requirements impose reformulation costs and label redesign cycles that disproportionately affect small-to-mid tier manufacturers.
- Cream Compact Substitution Pressure:Liquid foundation and cushion compact formats are capturing coverage-seeking consumers who prioritize dewy finish over powder matte aesthetics.
Strategic Opportunities
- Underpenetrated Canadian Prairies:Manitoba and Saskatchewan retail corridors show compact consumption gaps relative to Toronto and Vancouver, presenting whitespace for targeted distribution expansion.
- Health Canada PMRA Alignment:Harmonized cross-border labeling standards between U.S. FDA and Canadian regulators enable unified North American product lines that reduce SKU complexity.
- Specialty Store Tactile Services:Shade-matching technologies and in-person trial infrastructure at Sephora and Ulta Beauty locations are converting online browsers into higher-margin purchasers.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Cosmetic chemists with pressed powder density optimization expertise command premium compensation in California's competitive beauty labor market.
- Refillable Mechanism Capex Requirements:Magnetic pan and modular case engineering demands injection molding retooling that strains mid-tier brand capital allocation.
- Cross-Border E-Commerce Duty Complexity:U.S.-to-Canada direct-to-consumer shipments face evolving tariff classifications that complicate pricing consistency across Amazon and brand-owned channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Face Compact Market |
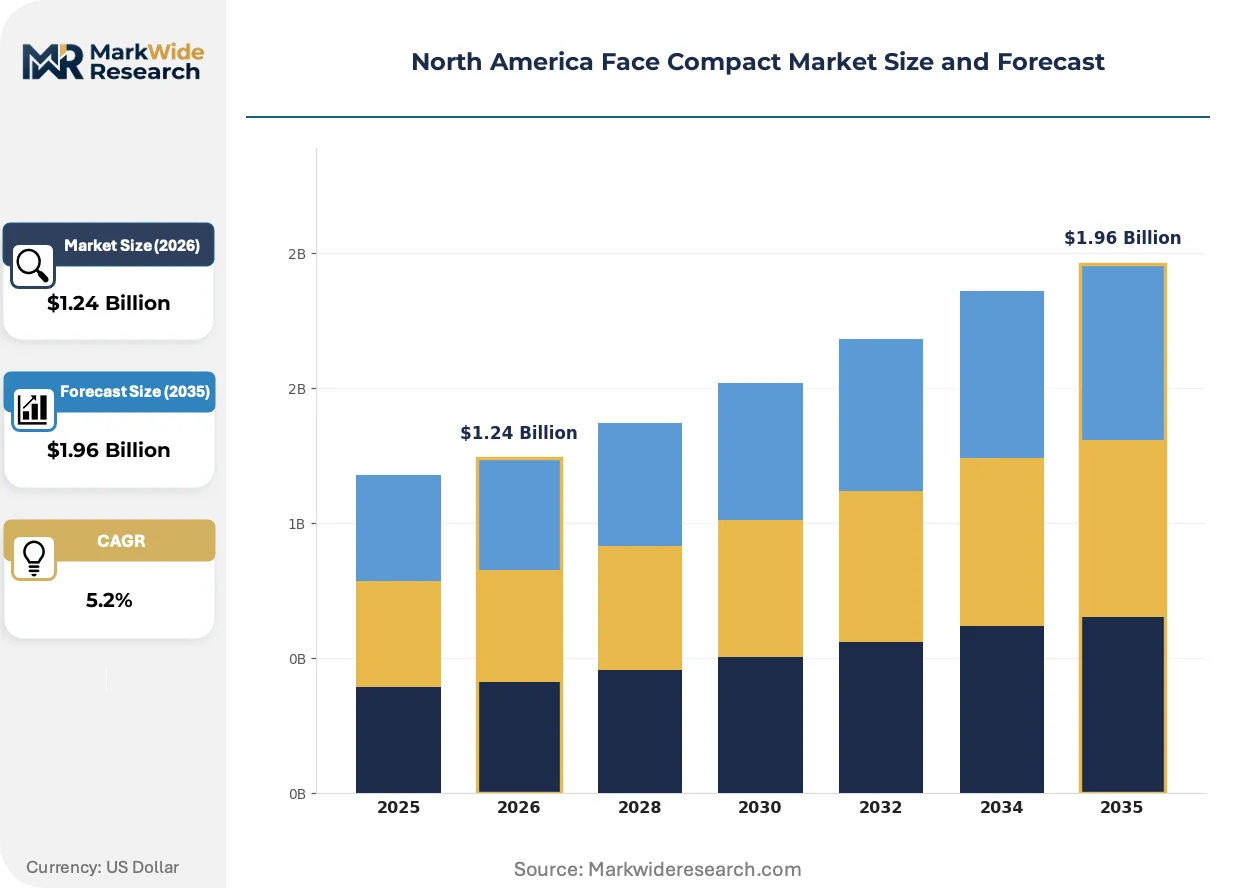
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressed Powder, Cream Compact, Loose Powder, Baked Powder Application: Everyday Use, Professional Makeup, Special Events, Photography Distribution Channel: Online Retail, Specialty Stores, Department Stores, Pharmacies Customer Type: Teenagers, Millennials, Professionals, Seniors |
| Companies Covered | The Estée Lauder Companies Inc., L'Oréal S.A., Revlon, Inc., Coty Inc., Procter & Gamble Company, Mary Kay Inc., Johnson & Johnson Consumer Inc., Bare Escentuals, Inc., Urban Decay, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Face Compact Market Trends and Innovations
Biodegradable binding agents and AI-driven shade-matching tools are reconfiguring how North American consumers discover and repurchase face compacts. These shifts are compressing traditional retail cycles while elevating expectations for personalization and environmental accountability.
Plant-derived binding systems from corn starch and rice protein are replacing synthetic polymers in pressed powder matrices. Clean beauty retailers in Los Angeles and New York are prioritizing these formulations for shelf placement. The technology is collapsing the performance gap between natural and conventional binders, forcing legacy ingredient suppliers to accelerate R&D timelines or cede formulation partnerships.
Health Canada's PMRA is expanding mandatory fragrance allergen disclosure requirements beyond the current 26-substance list. Manufacturers serving the Canadian market must reformulate preservative systems and retest stability profiles. Premium brands with established "free-from" positioning are capturing regulatory-compliant shelf space faster than mass-market competitors scrambling to adapt existing SKUs.
TikTok-driven discovery patterns are shortening the compact purchase cycle from seasonal to impulse-driven replenishment. Gen Z consumers in Texas and Illinois are abandoning department store counters for algorithm-curated product recommendations. This behavioral rotation is elevating micro-influencer seeding budgets while eroding legacy loyalty program effectiveness among younger demographics.
North America Face Compact Market Segmentation
Face compact manufacturers deploy distinct service architectures for each segment tier. Refill programs, shade-matching support, and warranty policies vary sharply between mass-market and prestige positioning, creating aftermarket revenue streams that now rival initial unit margins.
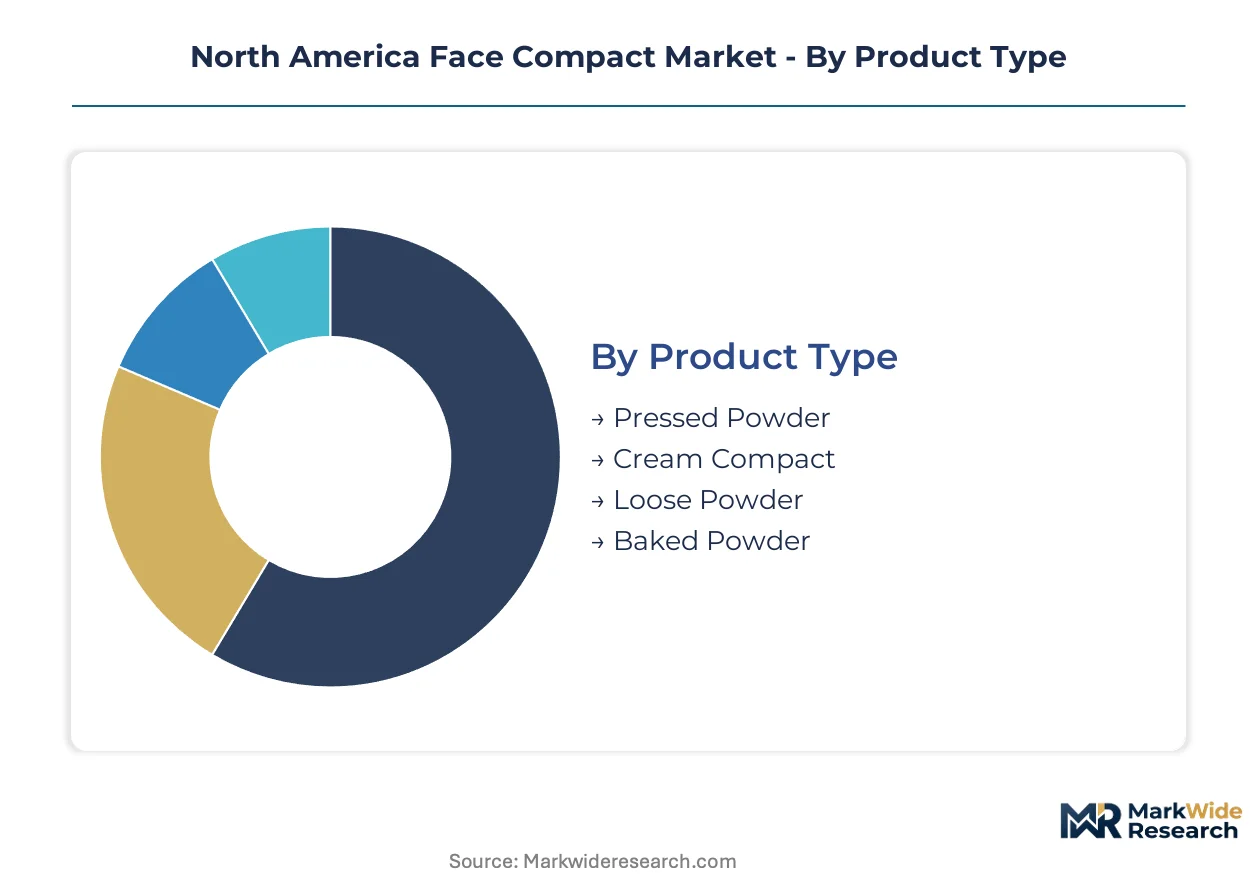
Product Type:
After-sales service intensity peaks with refillable architectures, where magnetic pan systems and modular case engineering demand ongoing consumer touchpoints.
- Pressed Powder:Talc-mica-silica matrices compressed through hydraulic pressing at controlled temperatures deliver uniform density and pan adhesion. California's beauty cluster and Texas metropolitan markets concentrate demand for portable, shelf-stable formats that withstand humid climate wear.
- Cream Compact:Emollient-rich formulations with wax and oil bases target dry-skin and mature demographics seeking dewy coverage. Manitoba and Saskatchewan retail corridors show expanding adoption among consumers prioritizing skin-nourishing properties over matte finishes.
- Loose Powder:Finely milled talc or silica particles without press binding serve professional makeup artists requiring customizable coverage intensity.
- Baked Powder:Cream-to-powder formulations cured in terracotta pans deliver marbled color effects for contouring applications.
Pressed Powder holds the largest share; momentum sits with Cream Compact.
Application:
Cost tier stratification separates commodity replenishment from premium occasion-based purchasing.
- Everyday Use:Standard coverage formulations with SPF integration dominate pharmacy and drugstore channels across Illinois and Ohio. Value-conscious consumers prioritize multi-functional compacts that combine setting powder with sun protection.
- Professional Makeup:High-pigment, multi-use formats with extensive shade ranges anchor salon and studio kit standardization. Toronto's retail corridor and Los Angeles production hubs concentrate demand from film and television makeup departments.
- Special Events:Long-wear, transfer-resistant formulations target bridal and formal occasion segments.
- Photography:Finely milled silica-based powders eliminate flashback under high-definition camera conditions.
Everyday Use commands volume leadership; Professional Makeup climbs the fastest on kit-portability requirements.
Distribution Channel:
Customer acquisition economics vary dramatically by touchpoint infrastructure investment.
- Online Retail:Algorithm-driven discovery and subscription replenishment models compress purchase cycles. Gen Z consumers in Texas and Arizona abandon traditional counters for TikTok-curated recommendations and auto-shade-matching tools.
- Specialty Stores:Tactile trial infrastructure and in-person shade-matching services at Sephora and Ulta Beauty locations sustain superior conversion rates.
- Department Stores:Prestige brand counters with loyalty ecosystems anchor higher-margin transactions.
- Pharmacies:Mass-market accessibility and impulse placement drive volume in CVS and Walgreens networks.
Specialty Stores retain margin leadership; Online Retail gains share fastest on demographic rotation.
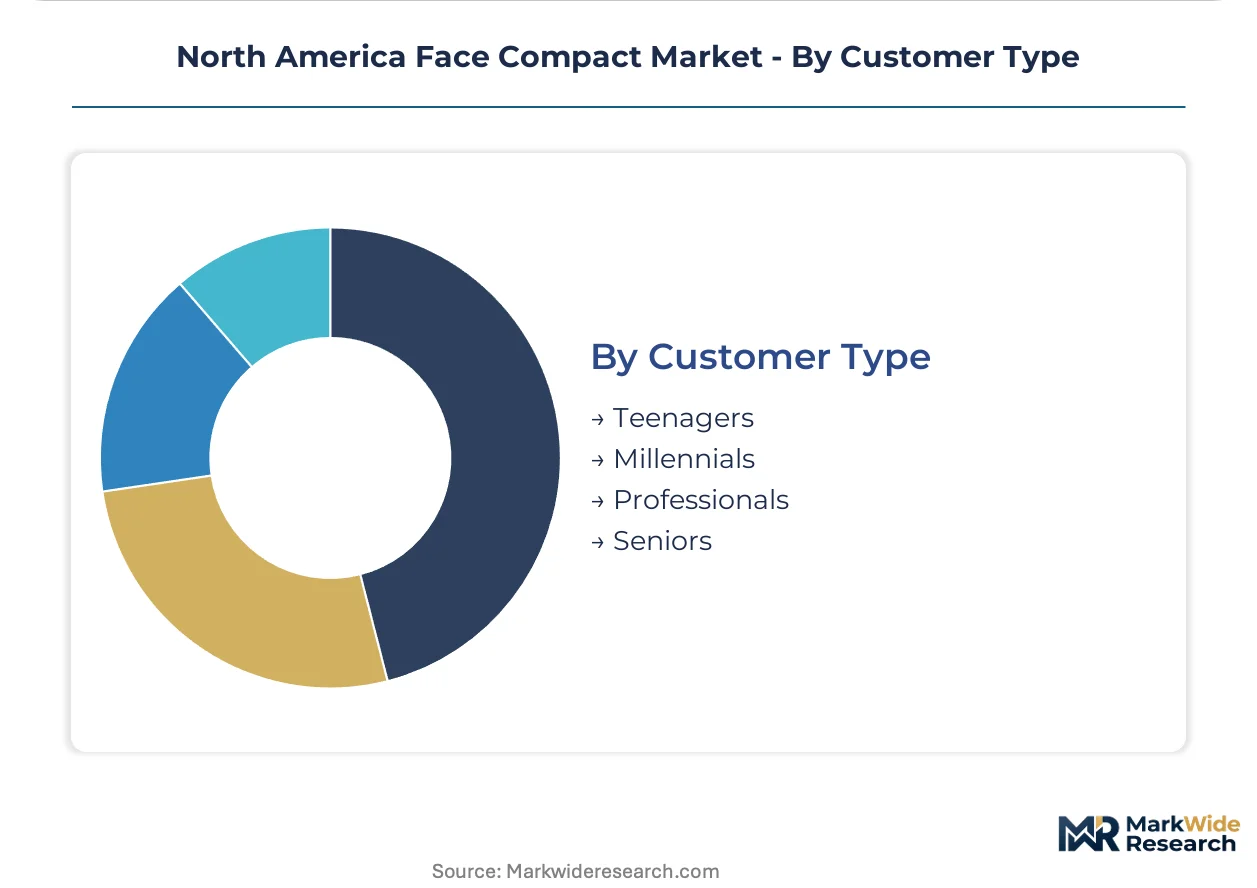
Customer Type:
Life-stage purchasing patterns dictate formulation complexity and price-point tolerance.
- Millennials:Clean beauty preferences and sustainability credentials drive refillable compact adoption. New York and Los Angeles metropolitan markets concentrate demand for plant-derived binding systems and transparent supply chains.
- Professionals:Time-constrained purchasing prioritizes multi-functional formats with portable case designs.
- Teenagers:Entry-level price sensitivity and social media discovery patterns shape mass-market brand selection.
- Seniors:Hydration-focused cream formats and ergonomic case engineering address dexterity and skin-moisture needs.
Millennials anchor current revenue; Professionals represent the steepest expansion trajectory on kit-standardization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American sub-regions. California and New York consumers absorb premium pricing for sustainable formulations, while Midwest and Prairie markets prioritize value-tier accessibility. This bifurcation shapes distinct distribution and marketing architectures.
United States
California's beauty cluster drives clean formulation adoption and refillable compact innovation. The FDA's cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act govern ingredient disclosure and safety substantiation. Los Angeles and New York metropolitan areas concentrate prestige brand headquarters and professional makeup artist demand.
Canada
Toronto's retail corridor anchors national distribution for mass-market and prestige tiers alike. Health Canada's PMRA enforces allergen disclosure standards that often exceed U.S. requirements, compelling cross-border SKU harmonization. Vancouver and Montreal emerging as secondary demand nodes for Asian-imported beauty influences.
Mexico
Mexico City metropolitan area concentrates mass-market consumption and pharmacy channel dominance. The country's national consumer protection regulator enforces labeling accuracy for imported cosmetics. Guadalajara and Monterrey manufacturing zones supply packaging components to North American compact assemblers.
California
Proposition 65 chemical warning mandates impose reformulation costs that filter small competitors from shelf placement. State-level fragrance disclosure legislation is expanding beyond federal minimums. Silicon Valley adjacent beauty-tech startups pilot AI-driven shade-matching for compact customization.
Texas
Houston and Dallas-Fort Worth metropolitan areas sustain humid-climate demand for oil-absorbing silica formulations. State sales tax structures favor e-commerce penetration versus brick-and-mortar prestige counters. Austin emerging as influencer marketing hub for Gen Z compact discovery patterns.
North America Face Compact Market Competitive Landscape
Prestige conglomerates and mass-market diversifiers split the market into distinct margin territories. The structure consolidates around parent-company portfolios rather than standalone brands. Three archetypes dominate: multinational beauty conglomerates with R&D depth, pharmaceutical-consumer hybrids with pharmacy channel access, and independent prestige houses with cult-brand positioning. Competitive moves center on sustainable packaging licensing and refill program infrastructure deployment.
Within the multinational tier, L'Oréal S.A. and The Estée Lauder Companies Inc. exemplify divergent strategic postures. Coty Inc. occupies a position bridging mass-market scale with selective prestige licensing. These Paris-based and New York-based entities anchor the competitive set through distinct channel emphases and formulation heritage positioning.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc. |
| L'Oréal S.A. |
| Revlon, Inc. |
| Coty Inc. |
| Procter & Gamble Company |
| Mary Kay Inc. |
| Johnson & Johnson Consumer Inc. |
| Bare Escentuals, Inc. |
| Urban Decay, LLC |
| Others |
Pricing and Supply Chain Analysis
California's beauty manufacturing cluster dictates downstream pricing power through its concentration of formulation chemistry talent and compliant packaging infrastructure. Brands lacking presence in this corridor absorb premium logistics costs and extended lead times that compress margins on refillable compact architectures.
Pricing Analysis
Aftermarket refill program revenue anchors lifetime value calculations across the competitive set. Three-tier pricing structure across prestige, masstige, and mass-market levels separates brands by distribution channel control and shade-matching service bundling. Pricing pressure stems from talc input cost volatility and Proposition 65 compliance investments that filter smaller competitors. Mass-market pharmacy consumers exhibit highest price sensitivity, while professional makeup artists absorb premium positioning for kit-standardized formats.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Cosmobeauty Laboratories, KDC/One, and Fareva Holdings serving North American brand portfolios. Raw material sourcing draws from U.S. talc mining operations in Montana and Vermont, Chinese mica processors, and Brazilian silica suppliers. Single-source vulnerability in talc procurement creates formulation cost instability during mining regulatory reviews. Distribution runs through brand-owned direct-to-consumer channels, specialty beauty retailers, and pharmacy networks with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise with pressed powder density optimization commands compensation premiums that constrain mid-tier brand R&D staffing. This capability scarcity rewards early investments in talent pipelines and university partnerships.
For Market Incumbents: Pre-empt refillable compact standardization by locking in magnetic pan engineering patents and modular case supplier exclusivity. Cushion compact and liquid foundation substitution threats demand accelerated cream-to-powder hybrid development. Backward integration into talc sourcing or binding agent R&D secures input cost control against supply concentration risks. For New Entrants and Emerging Players: Pursue underpenetrated Canadian Prairie retail corridors in Manitoba and Saskatchewan where mass-market compact consumption lags Toronto and Vancouver benchmarks. Professional makeup artist kit standardization presents the most penetrable entry vector through high-pigment, multi-use format development. Direct-to-consumer launch with AI-driven shade-matching bypasses specialty store gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-infrastructure play because refillable mechanism engineering and biodegradable binding agent R&D determine competitive survival beyond regulatory compliance windows. Acquisition targets with established Health Canada PMRA registration and magnetic pan IP portfolios offer defensive positioning. Monitor California state-level fragrance disclosure legislation expansion as inflection signal for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Compact Infrastructure Deployment | Magnetic pan and modular case engineering at KDC/One reduces per-unit material waste and extends consumer lifetime value. |
| Biodegradable Binding Agent R&D Partnership | Corn starch and rice protein formulations from California clean beauty labs collapse the natural-conventional performance gap. |
| Professional Makeup Artist Certification Program | Kit standardization agreements with Los Angeles and Toronto studio professionals lock in recurring bulk purchasing commitments. |
| Cross-Border E-Commerce Duty Optimization | Harmonized U.S.-Canada SKU architecture reduces Amazon and brand-owned channel pricing complexity under evolving tariff classifications. |
| AI-Driven Shade-Matching Platform Integration | TikTok-curated discovery tools at Sephora and Ulta Beauty locations convert Gen Z browsers into higher-margin purchasers. |
Research Methodology
Desk research of FDA cosmetic ingredient filings, Health Canada PMRA registration databases, and California Proposition 65 chemical warning precedents preceded structured interviews with formulation chemists, packaging engineers, and specialty store category buyers. Primary fieldwork with brand managers at prestige conglomerates and mass-market diversifiers combined with secondary validation from customs trade records and retail audit data. Bottom-up demand modeling and top-down supply capacity assessments triangulated volume and value outputs.
Assumptions held fixed include regulatory stringency trajectories at FDA and PMRA, while talc supply concentration and TikTok-driven discovery penetration were stress-tested across scenarios. Segmentation dimensions spanned product type, application context, distribution channel, and customer life-stage with regional production hub differentiation. CAGRs derived from fitted growth curves applied to segment-level baseline estimates, incorporating silica-based formulation advance rates and refillable compact adoption curves as industry-specific inputs.
Sensitivities concentrate around California fragrance disclosure legislation expansion, Health Canada allergen list extensions, and talc mining regulatory review outcomes. Forecasts reflect documented assumptions without forward guarantee. Quarterly review of Proposition 65 chemical warning updates, PMRA registration processing times, and professional makeup artist kit standardization trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Liquid Makeup Market
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market