
 GCC Bath Soap Market | 2026-2036
GCC Bath Soap Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Bath Soap Market Intelligence
Premium-grade soap formulations is collapsing the gap between mass-market and luxury personal care across Gulf retail channels. Unilever PLC leverages its manufacturing footprint in Saudi Arabia to sustain cost-competitive distribution throughout the peninsula. Procter & Gamble Company anchors its position through specialized antibacterial lines targeting institutional buyers in hospitality and healthcare.
GCC bath soap comprises surfactant-based cleansing bars and liquid preparations formulated with fatty acid salts, glycerin, and functional additives for skin hygiene and moisture retention, manufactured through continuous saponification or neutralization processes for daily consumer and commercial use. Bar soap occupies the largest volume share across supermarket and convenience store channels, though liquid soap and shower gel segments capture expanding margin pools in urban centers where refillable bottle systems gain traction. Natural and moisturizing formulations now lead formulation-based growth as consumers reject synthetic preservatives.
Gulf Standards Organization halal certification and Saudi Food and Drug Authority cosmetic safety standards govern ingredient transparency and labeling across all six member states, while UAE Ministry of Industry and Advanced Technology enforces packaging material compliance that elevates production costs for non-compliant imports. Stakeholders must monitor regulatory convergence between national cosmetic frameworks and emerging sustainability mandates from GCC Standardization Organization before committing to long-term formulation investments.
Market Dynamics
Halal certification mandates from Gulf Standards Organization are compressing formulation timelines and redirecting procurement toward domestic manufacturing bases across Saudi Arabia and the UAE. This regulatory pressure is forcing multinational suppliers to reconfigure supply chains and ingredient sourcing to maintain market access.
Growth Catalysts
- Hospitality Sector Procurement:Premium hotel chains across Saudi Arabia and the UAE are mandating sulfate-free formulations for guest amenities, creating dedicated supply contracts for certified manufacturers.
- Gulf Standards Organization Halal Framework:Unified cosmetic safety standards across all six member states are streamlining cross-border product registration and reducing compliance duplication costs.
- Refillable Dispenser Systems:Liquid soap concentrate formats are penetrating urban retail corridors in Riyadh and Dubai, displacing single-use packaging through cost-per-use economics.
Market Restraints
- Palm Oil Derivative Volatility:Fatty acid feedstock costs fluctuate with Malaysian and Indonesian export quotas, compressing margin predictability for bar soap producers.
- Import Dependency for Specialty Additives:Glycerin and botanical extracts concentrate in European and Asian supplier networks, exposing GCC formulators to currency and shipping risk.
- Synthetic Preservative Substitution Limits:Natural antimicrobial alternatives lack the shelf-stability of parabens, constraining distribution reach to temperature-controlled retail channels.
Strategic Opportunities
- Oman and Bahrain Penetration:Modern trade infrastructure gaps in secondary cities present first-mover advantages for brands establishing direct distribution partnerships.
- Healthcare Institutional Contracts:Antibacterial and surgical scrub formulations face limited domestic competition, opening procurement windows for compliant local manufacturers.
- E-commerce Subscription Models:Direct-to-consumer replenishment platforms are capturing urban professional households in Jeddah and Dubai through personalized scent profiling.
Industry Challenges
- Halal Certification Timeline Compression:Gulf Standards Organization documentation requirements extend product launch cycles by four to six months, straining working capital for seasonal formulations.
- Technical Formulation Talent Scarcity:Cosmetic chemists with saponification process expertise and Arabic regulatory fluency command premium compensation in Riyadh and Dubai labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Bath Soap Market |
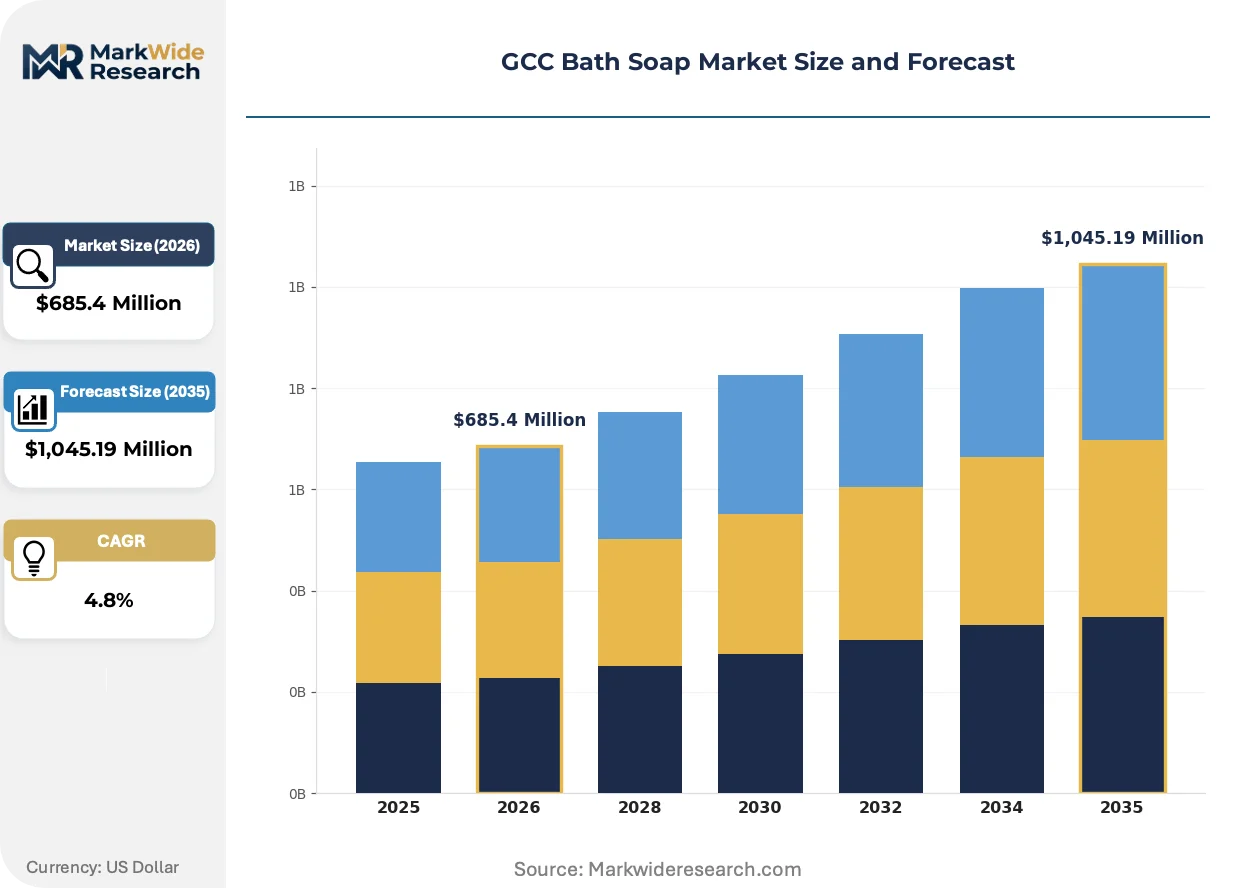
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bar Soap, Liquid Soap, Foam Soap, Shower Gel Formulation: Natural, Organic, Antibacterial, Moisturizing Packaging Type: Single Use, Bulk Packaging, Refillable Bottles, Sachets Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Procter & Gamble Company, Estee Lauder Companies Inc., Unilever PLC, Avon Products, Inc., Reckitt Benckiser Group PLC, Colgate-Palmolive Company, Beiersdorf AG, Bath & Body Works, Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Bath Soap Market Strategic Shifts & Innovations
Consumer rejection of synthetic additives is fragmenting traditional surfactant chemistry and elevating botanical extraction methods to industrial scale. Formulators now compete on ingredient provenance transparency rather than fragrance differentiation alone.
Cold-process saponification is fragmenting production economics across mid-sized GCC manufacturers. This method preserves glycerin integrity and enables superfatting customization for sensitive-skin positioning. Regional contract manufacturers in Jeddah industrial zones are adopting batch-scale equipment to serve boutique hospitality brands seeking small-run differentiation. The technology is fragmenting volume concentration away from continuous-process multinationals toward flexible domestic producers.
Saudi Food and Drug Authority cosmetic labeling amendments now mandate Arabic ingredient disclosure and manufacturing origin statements on primary packaging. This policy compresses design-to-shelf timelines for imported brands and elevates domestic printing and packaging capabilities. Smaller UAE-based formulators are capturing market share by leveraging local compliance expertise to accelerate registration.
Switching behavior among urban GCC consumers now favors trial-sized discovery formats over standard bar purchases. Supermarket chains in Dubai and Riyadh are displacing bulk displays with curated sampler stations and QR-linked educational content. This pattern concentrates margin capture in brands with diversified SKU architectures and direct digital engagement infrastructure.
GCC Bath Soap Market Segmentation
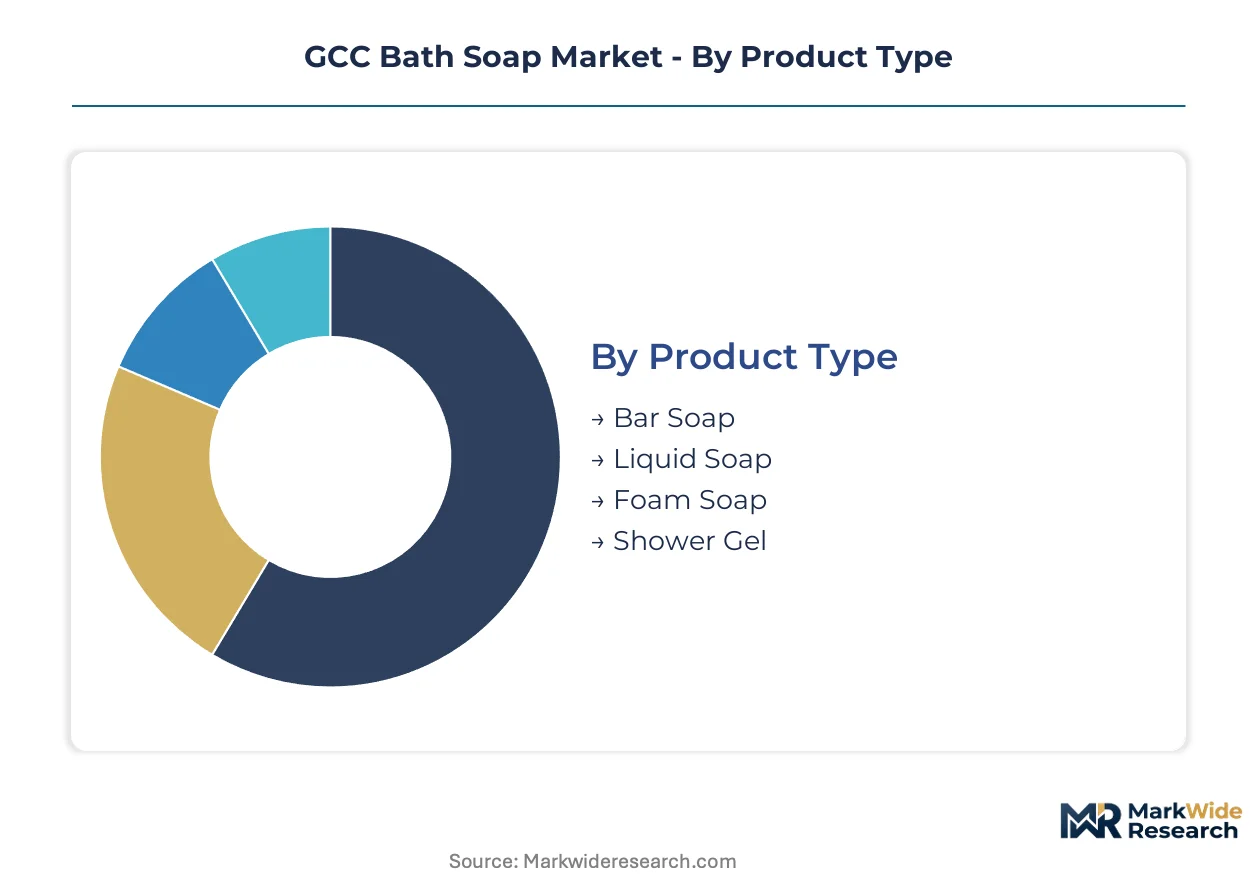
Segmentation in the GCC bath soap market reveals how Gulf Standards Organization halal mandates and hospitality procurement standards are fragmenting traditional mass-market categories. Formulation choices and packaging formats now determine regulatory compliance speed and shelf placement priority across Saudi Arabia and the UAE.
Product Type:
Gulf Standards Organization certification timelines vary by physical form, with bar soap facing streamlined documentation and liquid preparations requiring extended stability testing.
- Bar Soap:Continuous saponification produces fatty acid salt matrices with glycerin retention for mass-market positioning. Demand concentrates in supermarket bulk displays across Riyadh and Jeddah where price-per-unit economics dominate household procurement. Halal certification documentation moves fastest for solid formats with minimal preservative loads.
- Liquid Soap:Surfactant concentrates diluted with deionized water require pump-dispenser compatibility and viscosity stabilization. Hospitality chains in Dubai mandate sulfate-free liquid formats for guest amenities, creating dedicated supply contracts with extended payment terms. Shelf-stability testing extends Gulf Standards Organization approval cycles.
- Foam Soap:Aerated dispensers reduce per-use surfactant volume through air-injection mechanisms. Airport and mall washroom contracts in the UAE specify foam systems for traffic volume efficiency.
- Shower Gel:Thickened liquid preparations with fragrance encapsulation target premium bathroom positioning. Urban professional households in Jeddah trial shower gel through e-commerce subscription discovery formats.
Established volume favors Bar Soap; emerging adoption favors Liquid Soap.
Formulation:
Cost tier differentiation separates commodity surfactant bases from certified botanical extracts commanding hospitality procurement premiums.
- Natural:Plant-derived surfactants and cold-process glycerin retention bypass synthetic preservative dependencies. Saudi Food and Drug Authority labeling amendments favor natural claims with Arabic ingredient disclosure requirements. Temperature-controlled distribution constraints limit rural penetration.
- Organic:Certified botanical inputs with supply chain traceability documentation meet European export standards alongside Gulf compliance. Premium hotel chains in the UAE specify organic formulations for sustainability positioning in guest communications. Input scarcity elevates procurement costs versus conventional alternatives.
- Antibacterial:Triclosan-restricted markets now deploy benzalkonium chloride or botanical antimicrobial alternatives. Healthcare institutional contracts across Saudi Arabia specify antibacterial compliance for surgical scrub applications.
- Moisturizing:Superfatting chemistry and humectant additives target dry climate skin conditions prevalent across Gulf urban centers. Modern trade channels in Dubai allocate expanded shelf space to moisturizing positioning during winter months.
Margin concentration sits with Organic; volume accessibility sits with Natural.
Packaging Type:
Customer type and usage occasion determine format selection, with institutional buyers favoring bulk economics and urban households prioritizing convenience and sustainability signaling.
- Single Use:Individually wrapped bars or sealed sachets eliminate contamination risk in high-turnover environments. Budget hospitality properties across secondary Saudi cities procure single-use formats for cost control and hygiene assurance.
- Bulk Packaging:Multi-unit cartons or large-format containers reduce per-unit logistics costs for high-volume institutional buyers. Hospital supply chains in the UAE specify bulk antibacterial soap for staff washroom replenishment.
- Refillable Bottles:Concentrate-to-dilute systems or pump dispenser reuse platforms capture cost-per-use economics. Urban retail corridors in Riyadh and Dubai displace single-use alternatives through supermarket refill stations with deposit mechanisms.
- Sachets:Flexible film single-dose packets enable trial sampling and low-income market access. Convenience stores in Jeddah industrial zones stock sachet formats for migrant worker dormitory demand.
Procurement scale favors Bulk Packaging; sustainability positioning favors Refillable Bottles.
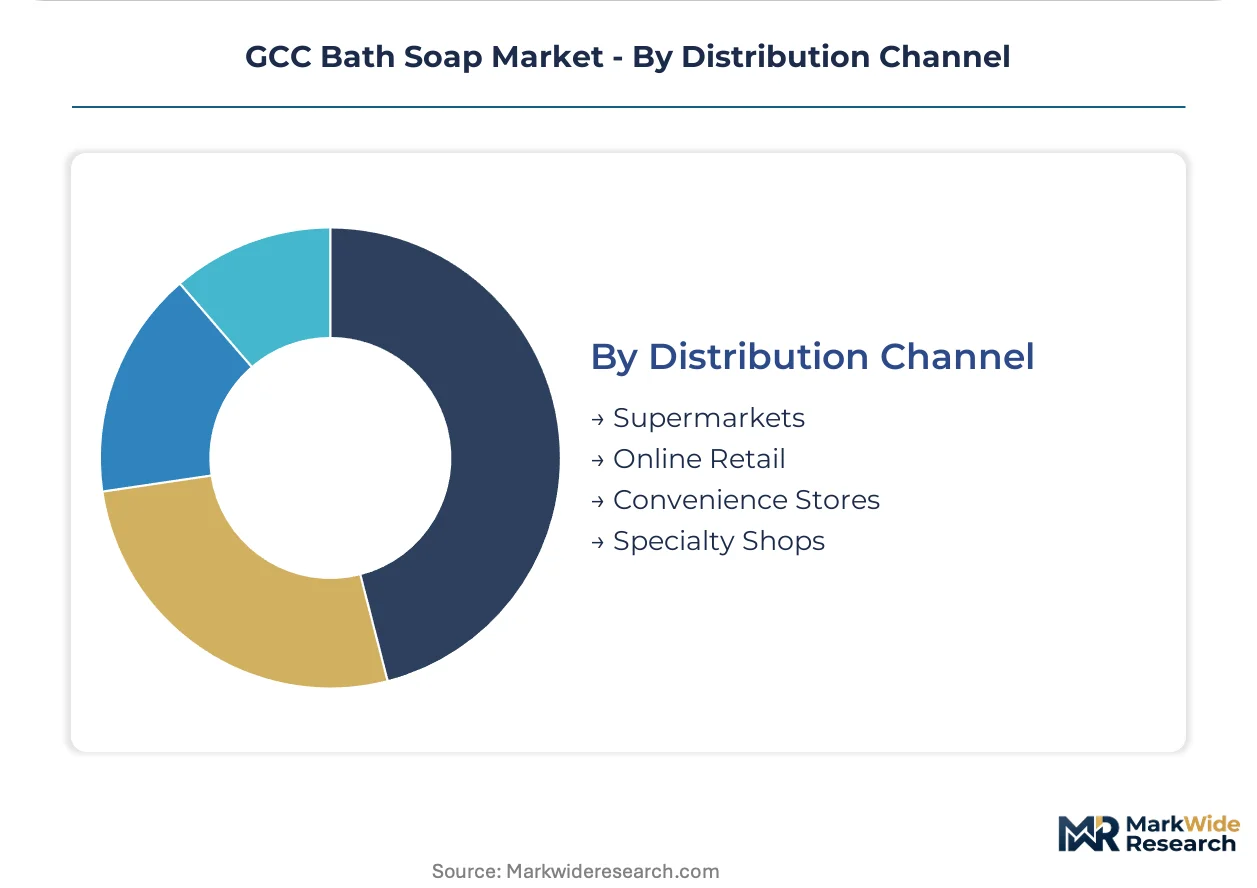
Distribution Channel:
Geography and retail maturity determine channel priority, with modern trade infrastructure concentrated in primary urban corridors and digital platforms capturing professional household convenience demand.
- Supermarkets:Curated shelf sets with Arabic labeling compliance and halal certification visibility dominate mass-market volume. Hypermarket chains in Dubai and Riyadh negotiate exclusive regional launches for premium formulation introductions.
- Online Retail:Direct-to-consumer platforms with subscription replenishment and scent profiling algorithms capture urban professional households. Last-mile cold chain limitations constrain temperature-sensitive natural formulation distribution.
- Convenience Stores:High-frequency replenishment locations in residential neighborhoods and fuel station networks stock impulse-format sachets and standard bar soap. Limited shelf space restricts SKU breadth to velocity leaders.
- Specialty Shops:Pharmacy and personal care boutiques with trained staff consultation support premium and therapeutic positioning. Organic and sensitive-skin formulations gain trial through recommendation-driven purchase in UAE mall locations.
Volume throughput concentrates in Supermarkets; margin expansion concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports finished bath soap formulations to hospitality buyers across Bahrain, Kuwait, and Oman, while the UAE re-exports specialty liquid preparations to East African markets through Dubai's Jebel Ali corridor.
Saudi Arabia
Domestic manufacturing clusters in Riyadh and Jeddah supply sulfate-free formulations to premium hotel chains under SFDA cosmetic safety standards. The Saudi Food and Drug Authority mandates Arabic ingredient disclosure on primary packaging, compressing design-to-shelf timelines for imported brands. Industrial zones in Jeddah now host flexible batch-scale equipment serving boutique hospitality brands seeking small-run differentiation.
United Arab Emirates
Dubai's modern trade corridors dominate liquid soap and shower gel distribution, with refillable dispenser systems penetrating urban retail through cost-per-use economics. The UAE Ministry of Industry and Advanced Technology enforces packaging material compliance that elevates production costs for non-compliant imports. Mall-based specialty shops in Dubai allocate expanded shelf space to organic formulations during winter procurement cycles.
Oman
Secondary cities present first-mover advantages for brands establishing direct distribution partnerships outside Muscat's concentrated retail infrastructure. The country's national standards body aligns cosmetic safety requirements with Gulf Standards Organization halal frameworks, streamlining cross-border registration from Saudi suppliers. Industrial development zones near Sohar are attracting contract manufacturers seeking lower operational costs than UAE or Saudi bases.
Kuwait
High per-capita income households drive demand for premium and organic bath soap segments through supermarket hypermarket channels. The national regulatory authority maintains strict adherence to GSO halal certification timelines that extend product launch cycles for seasonal formulations. Urban retail corridors in Kuwait City concentrate procurement decisions for hospitality chains operating across the northern Gulf.
Qatar
World Cup legacy infrastructure has expanded modern trade capacity in Doha, creating dedicated supply contracts for institutional buyers in healthcare and education sectors. The national food and drug regulator enforces cosmetic labeling amendments parallel to Saudi and UAE standards. Industrial zones in Ras Laffan are developing downstream personal care manufacturing capabilities to reduce import dependency.
GCC Bath Soap Market Key Industry Players
Listed leaders compete with private specialists across formulation certification and hospitality procurement channels. Multinational consumer goods conglomerates anchor volume through continuous saponification facilities in Saudi Arabia, while mid-sized regional formulators capture margin in natural and cold-process segments. Three archetypes dominate: scale-driven multinationals with domestic manufacturing footprints, flexible domestic contract manufacturers serving boutique hospitality brands, and import-dependent premium specialists leveraging compliance expertise. Capacity expansion and portfolio diversification toward sulfate-free and organic lines constitute the dominant competitive moves.
Within the scale-driven tier, Unilever PLC and Procter & Gamble Company exemplify multinational archetypes with established manufacturing footprints across the peninsula. Among compliance-specialist positions, Beiersdorf AG and Johnson & Johnson Services, Inc. occupy positions that leverage regulatory fluency to accelerate product registration. Colgate-Palmolive Company represents the institutional procurement anchor, with antibacterial formulations targeting healthcare and hospitality buyers.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Estee Lauder Companies Inc. |
| Unilever PLC |
| Avon Products, Inc. |
| Reckitt Benckiser Group PLC |
| Colgate-Palmolive Company |
| Beiersdorf AG |
| Bath & Body Works, Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Cost & Logistics Intelligence
Gulf Standards Organization halal certification gates both supplier qualification and price tiering across Saudi Arabia and the UAE, compressing margin pools for non-compliant imports while elevating domestic manufacturing premiums. Procurement officers at hospitality chains and hospital systems now weight certification speed equally with unit economics, reshaping how formulators compete on landed cost.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the GCC bath soap market. Price differentiation rests on halal certification grade and sulfate-free formulation compliance, with hospitality procurement contracts commanding premiums for accelerated Gulf Standards Organization documentation. Cost compression in economy bar soap segments is intensifying because Malaysian palm oil derivative quotas feed fatty acid feedstock volatility. Budget hospitality properties in secondary Saudi cities exhibit highest price sensitivity, while premium hotel chains in Dubai demonstrate lowest sensitivity due to guest experience positioning requirements.
Supply Chain Analysis
Strategic stockpiling of glycerin and botanical extracts dominates inventory strategy among GCC formulators seeking to buffer European and Asian supplier lead times. Raw material concentration draws from Malaysia and Indonesia for palm oil derivatives, Germany and France for specialty surfactants, and India for botanical extracts. Single-source vulnerability concentrates in glycerin supply chains tethered to biodiesel production economics in Southeast Asia. Distribution runs through Jeddah and Riyadh manufacturing clusters for Saudi domestic coverage, with Dubai's Jebel Ali corridor handling UAE re-export logistics to East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around Gulf Standards Organization halal frameworks constructs defensive moats for incumbent formulators with established Saudi Food and Drug Authority relationships, elevating switching costs for institutional buyers.
For Market Incumbents: Shield market position by deepening backward integration into palm oil derivative processing within Saudi industrial zones to buffer feedstock volatility. Accelerate Gulf Standards Organization pre-certification investments for seasonal formulation pipelines to compress launch cycles against emerging regional contract manufacturers. Prioritize capacity addition in Jeddah batch-scale facilities serving boutique hospitality brands seeking small-run differentiation. For New Entrants and Emerging Players: E-commerce subscription replenishment gaps in Jeddah and Dubai professional households present first-mover white-space for direct-to-consumer platforms with personalized scent profiling. Target Omani secondary cities outside Muscat's concentrated retail infrastructure through direct distribution partnerships with modern trade developers. Pursue healthcare institutional contracts for antibacterial surgical scrub formulations facing limited domestic competition. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods conglomerates seeking to divest non-core personal care assets with established Gulf Standards Organization certification dossiers. Long-term viability centers on formulators with captive sulfate-free chemistry capabilities and hospitality procurement relationships spanning Saudi Vision 2030 hospitality expansion. Monitor Gulf Standardization Organization sustainability mandate convergence as inflection signal for formulation investment reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-Investment | Accelerates Gulf Standards Organization timelines for seasonal hospitality procurement windows. |
| Backward Integration into Feedstock Processing | Captures margin from Malaysian palm oil derivative volatility in Saudi manufacturing zones. |
| Batch-Scale Equipment Deployment | Serves boutique hospitality brands seeking cold-process saponification differentiation in Jeddah. |
| E-commerce Subscription Platform Launch | Captures urban professional household replenishment demand through personalized scent algorithms. |
| Healthcare Institutional Contract Pursuit | Accesses antibacterial surgical scrub procurement with limited domestic Saudi competition. |
Research Approach
Desk research of customs trade records, Gulf Standards Organization regulatory filings, and hospitality procurement databases preceded structured interviews with cosmetic formulation chemists, Saudi Food and Drug Authority registration consultants, and hypermarket category buyers across Riyadh and Dubai. Primary fieldwork with contract manufacturers in Jeddah industrial zones and UAE Ministry of Industry compliance officers validated secondary data on certification timeline compression. Bottom-up volume modeling across bar soap, liquid soap, and shower gel segments triangulated against top-down macroeconomic consumption indicators.
Variance decomposition across product type, formulation grade, packaging format, and distribution channel segmentation informed CAGR derivation through regression against household expenditure and hospitality sector capex trajectories. The analytical framework incorporated palm oil derivative price indices, Gulf Standards Organization documentation backlog estimates, and urban retail corridor modern trade penetration rates as industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover sustained Gulf Standards Organization halal framework enforcement and hospitality sector sulfate-free procurement mandates, with deviation risk concentrated in Malaysian export quota disruptions and synthetic preservative substitution technical failures. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory convergence timelines and feedstock commodity volatility. Revision becomes warranted when Gulf Standardization Organization sustainability mandates cross implementation thresholds or when cold-process saponification equipment adoption accelerates beyond current Jeddah industrial zone deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Mushroom Cosmetics Market