
 Digital Mailroom Services Market | 2026-2036
Digital Mailroom Services Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Mailroom Services Market Analysis
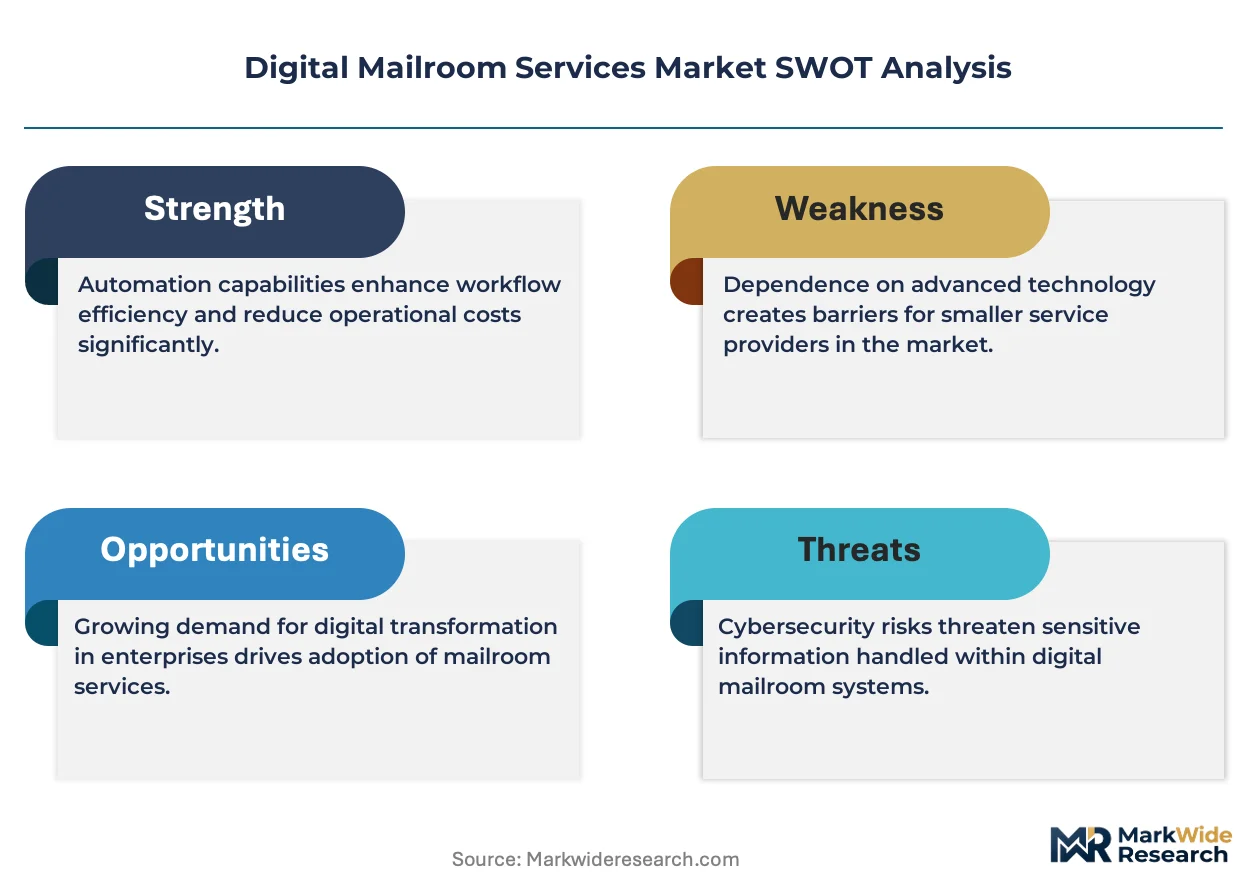
Outsourced mailroom management is expanding as enterprises shed legacy in-house operations. Iron Mountain leverages its physical document heritage to anchor hybrid digital-physical service bundles. Xerox competes through workflow automation platforms that extend beyond traditional print infrastructure. DATAMARK specializes in high-volume inbound processing for regulated industries requiring audit trails.
Digital mailroom services encompass the receipt, sorting, digitization, routing, and archival of physical and electronic correspondence using automated capture technologies such as optical character recognition achieving extraction accuracy above 95 percent on structured forms. These services eliminate manual handling delays and enable enterprise content management integration. Cloud-based deployment leads adoption due to lower capital requirements and faster implementation cycles, while AI-based solutions capture the fastest growth as machine learning reduces exception-handling costs. Document scanning retains the largest revenue pool among service types because legacy backfile conversion projects continue across corporate offices and government agencies.
US enterprises navigate HIPAA requirements for healthcare correspondence and SEC record retention rules that mandate defensible chain-of-custody documentation. European operations face GDPR constraints on personal data extraction and the EU AI Act's risk classification for automated decision systems in public-sector mail routing. Stakeholders must evaluate how emerging AI transparency obligations will reshape vendor qualification criteria and service-level agreements.
Market Dynamics
Cloud infrastructure migration is compressing implementation timelines from months to weeks while AI-based document classification is eliminating manual exception-handling bottlenecks that previously constrained service scalability.
Growth Catalysts
- HIPAA compliance mandates:US healthcare providers face escalating audit scrutiny over patient correspondence chain-of-custody documentation, accelerating outsourcing to vendors with defensible audit trails.
- AI-based extraction engines:Machine learning models achieving above 95 percent accuracy on structured forms are collapsing labor costs and enabling real-time routing decisions.
- German industrial concentration:Manufacturing hubs in Bavaria and Baden-Württemberg are consolidating supplier bases, driving demand for centralized document processing.
Market Restraints
- GDPR data residency requirements:European cross-border data flows face restrictions that fragment service delivery architectures and inflate infrastructure duplication costs.
- Legacy hardware dependency:High-volume scanning operations remain tethered to specialized capture equipment with limited vendor alternatives.
- Optical character recognition limitations:Handwritten and degraded documents still require human intervention, capping automation ceilings.
Strategic Opportunities
- Japan's aging administrative workforce:Public-sector agencies face retirement-driven knowledge gaps, creating openings for fully outsourced correspondence management.
- EU AI Act risk classification:Automated decision systems in public-sector routing will require certified transparency, positioning early-compliant vendors for preferred procurement status.
- Blockchain-anchored audit trails:Immutable ledger integration with document management systems is emerging as a differentiation vector for regulated industries.
Industry Challenges
- Enterprise content management integration:Proprietary legacy archives resist API standardization, forcing costly custom middleware development.
- ISO 27001 certification timelines:Information security management system audits extend 9-14 months, delaying vendor qualification for security-sensitive contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Mailroom Services Market |
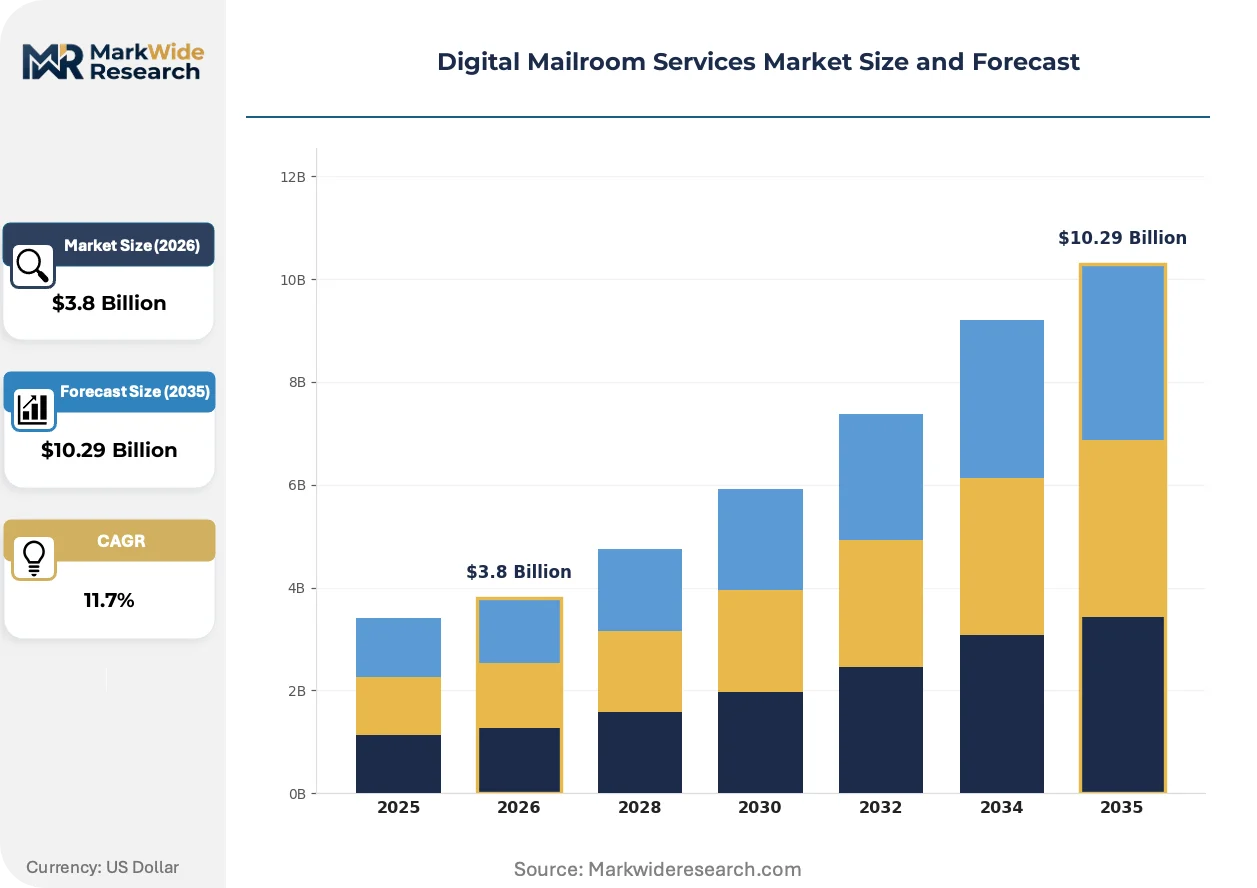
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inbound Processing, Outbound Mail, Document Scanning, Mail Tracking Technology: OCR, AI-Based Solutions, Cloud Infrastructure, Workflow Automation End User: Corporate Offices, Educational Institutions, Government Agencies, Healthcare Providers Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services |
| Companies Covered | Iron Mountain, Xerox, Conduent, DATAMARK, Kofax, MetaSource, Swiss Post Solutions, Access, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Mailroom Services Market Emerging Trajectories
Intelligent document processing is migrating from rules-based extraction to self-learning neural architectures that adapt to format variations without template reconfiguration.
Transformer-based language models are rewriting extraction economics by eliminating training data requirements for new document types. Financial services procurement teams are piloting zero-shot classification for unstructured correspondence. This compression of model deployment cycles is collapsing vendor switching costs and eroding incumbent data moats.
The EU AI Act's risk-tiered obligations for automated decision systems are mandating algorithmic transparency documentation. Public-sector mail routing contracts now require explainability audits for classification confidence thresholds. German municipal authorities are embedding these requirements into technical specifications ahead of enforcement deadlines.
Healthcare payers are unbundling mailroom services from broader business process outsourcing contracts. Large US insurers are issuing standalone RFPs for correspondence digitization with discrete SLAs for extraction accuracy and turnaround time. This fragmentation is exposing specialized vendors to direct competition with generalist providers.
Digital Mailroom Services Market Segmentation
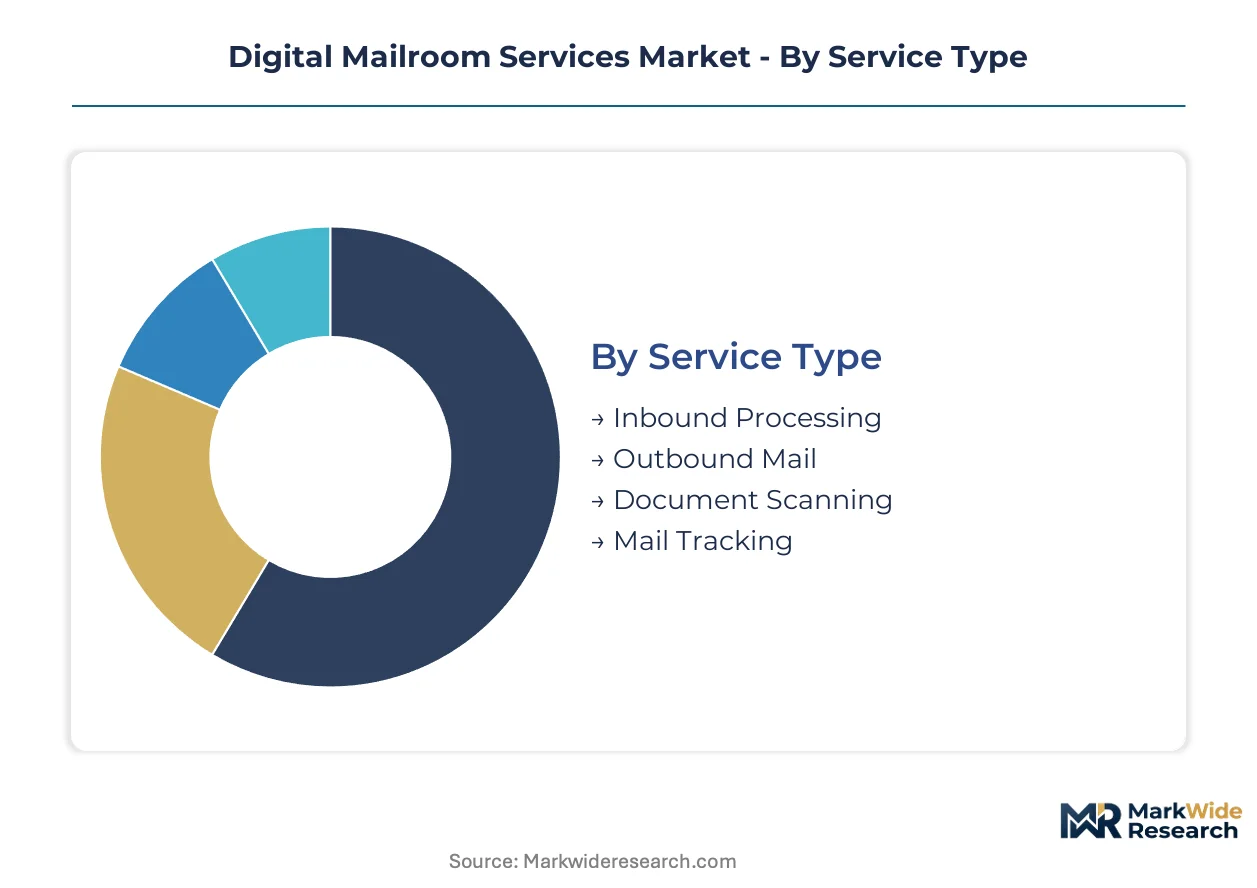
Segmentation in digital mailroom services reveals how compliance burdens and technology maturity reshape vendor selection. Healthcare providers demand HIPAA-certified inbound processing while manufacturers prioritize AI-based extraction with audit-ready chain-of-custody documentation.
Service Type:
ISO 27001 certification applies universally across all service types, though HIPAA attestation separates healthcare-qualified vendors from generalist providers. German public-sector contracts additionally require EU AI Act transparency documentation for automated routing decisions.
- Document Scanning:High-volume capture operations using production-grade scanners with throughput exceeding 200 pages per minute dominate legacy backfile conversion projects. Corporate offices in the United States and government agencies in Germany drive sustained demand for archival digitization with defensible metadata tagging.
- Inbound Processing:Receipt, sorting, and routing of physical correspondence through automated capture pipelines with sub-24-hour turnaround SLAs. Healthcare providers concentrate procurement here due to HIPAA audit trail requirements for patient correspondence chain-of-custody.
- Outbound Mail:Print-to-mail services integrating variable data composition with postal optimization. Financial services firms in Japan leverage these services for regulatory disclosure distribution with delivery confirmation.
- Mail Tracking:Real-time visibility systems using barcode or RFID tagging for custody verification. Government agencies require these capabilities for sensitive document handling with location-based status updates.
Document Scanning sits at the top of the volume ranking, with AI-Based Solutions climbing the fastest across service type adjacencies.
Technology:
Technology selection determines both capital intensity and exception-handling economics. Cloud infrastructure minimizes upfront deployment costs while AI-based solutions compress labor-dependent processing timelines.
- Cloud Infrastructure:Multi-tenant SaaS delivery models with API-first architecture enabling ECM integration without on-premises hardware. Corporate offices in Germany and the United States favor this deployment for rapid implementation and elastic capacity scaling.
- AI-Based Solutions:Self-learning neural architectures for document classification and extraction achieving above 95 percent accuracy on structured forms without template reconfiguration. Healthcare payers in the United States pilot these systems for real-time eligibility verification from scanned correspondence.
- OCR:Rules-based optical character recognition for standardized form fields with defined templates. Legacy installations persist in government agencies with high structured-form volumes and limited IT modernization budgets.
- Workflow Automation:Business process management platforms routing digitized content through approval hierarchies with escalation rules. Educational institutions deploy these for student services correspondence handling across distributed campuses.
Cloud Infrastructure commands the largest installed base, though AI-Based Solutions are expanding most quickly as machine learning collapses training data requirements.
End User:
End-user verticals impose distinct compliance frameworks that fragment vendor qualification criteria. Healthcare and government segments require specialized certifications unavailable to generalist providers.
- Healthcare Providers:Hospitals, insurers, and pharmacy benefit managers processing patient correspondence with HIPAA-mandated access controls and audit logging. United States procurement teams prioritize vendors with HITRUST certification alongside ISO 27001.
- Government Agencies:Federal, state, and municipal entities handling citizen correspondence with public records retention obligations. German municipal authorities embed EU AI Act explainability requirements into technical specifications for automated routing systems.
- Corporate Offices:Enterprise headquarters and regional facilities managing supplier invoices, customer correspondence, and internal communications. Manufacturing clusters in Bavaria concentrate demand for centralized document processing with multi-language extraction.
- Educational Institutions:Universities and school districts handling admissions, financial aid, and alumni correspondence with FERPA privacy constraints in the United States.
Healthcare Providers represent the highest-margin segment, with Government Agencies gaining share fastest on public-sector modernization mandates.
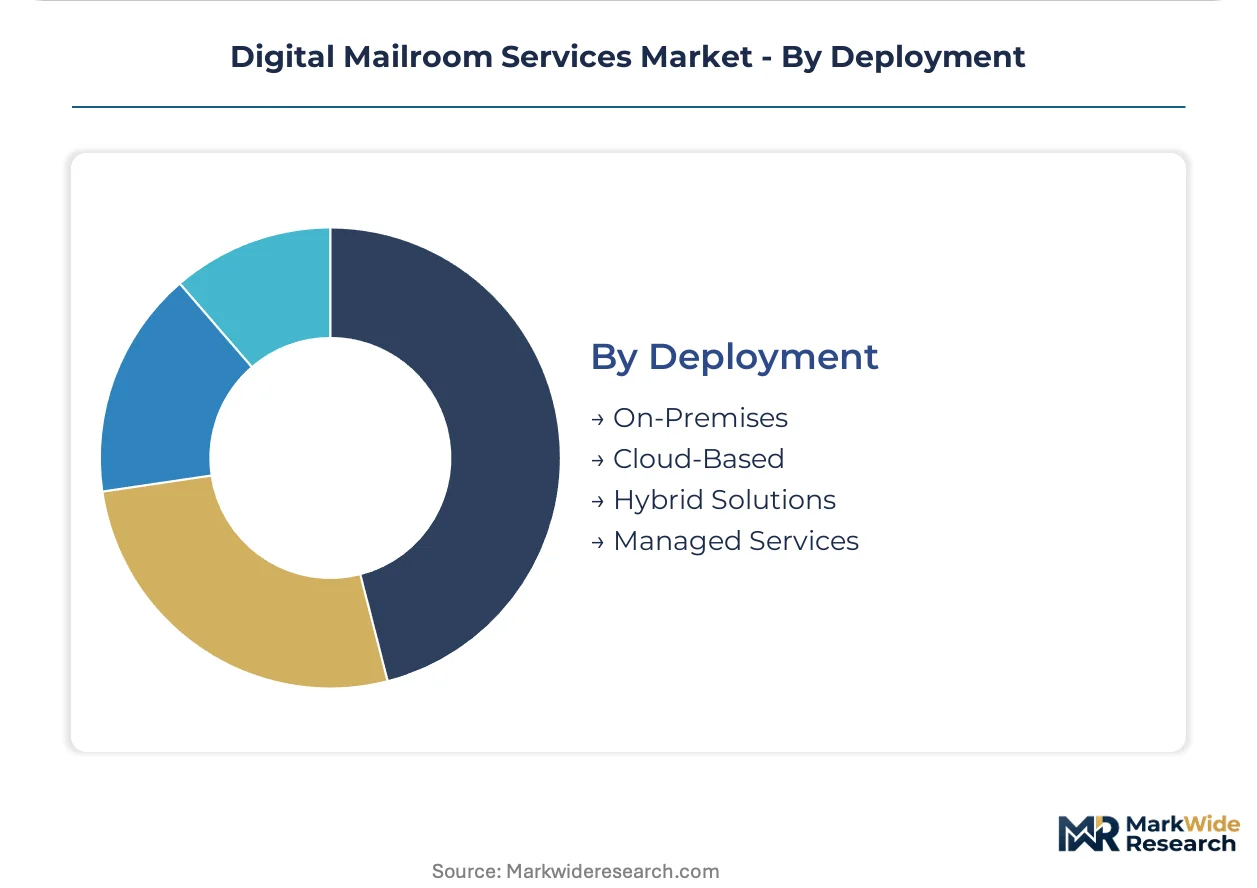
Deployment:
Deployment architecture tradeoffs center on data residency requirements versus operational agility. Regulated industries face constraints that hybrid architectures attempt to reconcile.
- Cloud-Based:Fully off-premises delivery with vendor-managed infrastructure and automatic software updates. Corporate offices prioritize this model for fastest implementation and lowest IT overhead.
- Hybrid Solutions:Split architectures retaining sensitive capture on-premises while leveraging cloud analytics and storage. Healthcare providers in the United States adopt this pattern to maintain HIPAA-compliant local custody while accessing AI-based classification.
- Managed Services:Outsourced operations with dedicated staff at client or vendor facilities assuming full process ownership. Government agencies in Japan utilize these arrangements to address retirement-driven administrative workforce gaps.
- On-Premises:Client-owned infrastructure with perpetual licensing and internal IT maintenance. Declining preference except where GDPR data residency or classified information handling mandates local control.
Cloud-Based deployment leads current adoption, with Hybrid Solutions climbing fastest as regulated industries seek compliance-agility balance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavarian manufacturing clusters anchor procurement demand for centralized document processing, with German industrial concentration driving supplier consolidation across automated capture services.
United States
Healthcare payers unbundle mailroom services from broader outsourcing contracts, issuing standalone RFPs with discrete SLAs for extraction accuracy. HIPAA audit scrutiny over patient correspondence chain-of-custody accelerates vendor qualification to HITRUST-certified providers. Large insurers in the Northeast and California pilot real-time eligibility verification from scanned correspondence.
Germany
Manufacturing hubs in Bavaria and Baden-Württemberg consolidate supplier bases, creating demand for centralized document processing with multi-language extraction capabilities. Municipal authorities embed EU AI Act explainability requirements into technical specifications for automated routing systems ahead of enforcement deadlines. Stuttgart-based automotive suppliers drive archival digitization with defensible metadata tagging.
Japan
Public-sector agencies face retirement-driven administrative workforce gaps, creating openings for fully outsourced correspondence management. METI modernization mandates accelerate procurement of managed services arrangements with dedicated vendor staff. Tokyo and Osaka municipal governments pilot blockchain-anchored audit trails for sensitive citizen document handling.
United Kingdom
Corporate headquarters in London and the Southeast prioritize cloud-based deployment for rapid implementation and elastic capacity scaling. GDPR constraints on cross-border data flows fragment service delivery architectures, inflating infrastructure duplication costs for vendors serving continental European operations. Financial services firms in the City pilot zero-shot classification for unstructured regulatory correspondence.
India
Business process outsourcing hubs in Bengaluru and Hyderabad expand capture operations for North American and European clients, leveraging cost arbitrage in high-volume scanning. The country's national IT regulator emphasizes data localization requirements for government contract eligibility. Mumbai-based financial services firms adopt hybrid architectures retaining sensitive capture on-premises while accessing cloud analytics.
Digital Mailroom Services Market Vendor Landscape
Global majors compete with regional champions across compliance certification depth, with tiered vendor qualification separating HIPAA-attested healthcare specialists from generalist document processors. Market structure consolidates around three strategic archetypes: physical document heritage players extending into hybrid digital-physical bundles, workflow automation platforms transcending legacy print infrastructure, and high-volume inbound specialists serving regulated industries with audit trail mandates. Dominant competitive moves include strategic partnerships for AI-based extraction engine licensing and geographic expansion through ISO 27001 certification acquisition.
Among physical document heritage players, Iron Mountain exemplifies the hybrid bundle archetype, leveraging legacy infrastructure to anchor integrated service offerings. Xerox occupies a position within workflow automation platforms that extend beyond traditional infrastructure boundaries. DATAMARK represents the high-volume inbound specialist tier, serving regulated verticals requiring defensible audit trails. These three companies illustrate how vendor selection fragments across compliance depth, technology architecture, and vertical specialization vectors.
| Leading Market Players |
|---|
| Iron Mountain |
| Xerox |
| Conduent |
| DATAMARK |
| Kofax |
| MetaSource |
| Swiss Post Solutions |
| Access |
| Konica Minolta |
| Others |
Supply Flow & Price Mechanics
HIPAA-certified processing premiums diverge sharply from commodity digitization rates, compressing margins for vendors lacking healthcare attestation while concentrating supply relationships around HITRUST-validated infrastructure providers. This certification ladder reshapes both contract structures and vendor qualification pipelines, as buyers with audit-trail mandates accept limited supplier pools in exchange for defensible chain-of-custody documentation.
Pricing Analysis
Input-cost pass-through from specialized capture hardware and ISO 27001 certification maintenance feeds directly into SaaS-tiered subscription structures with volume-scaled per-page rates. Price differentiation hinges on extraction accuracy guarantees above 95 percent and HITRUST certification tier, with healthcare payers showing lowest sensitivity due to compliance liability exposure while corporate offices in Germany drive hardest bargain on standardized scanning. Pricing pressure intensifies in document scanning commoditization as cloud-native entrants collapse implementation timelines.
Supply Chain Analysis
Certification gating through HITRUST and ISO 27001 audits concentrates qualified vendor relationships around established players with 9-14 month compliance investment cycles. Production-grade scanner manufacturing concentrates in Japan and Germany, while AI-based extraction engine development clusters in the United States and Israel. Supply chain risk centers on single-source vulnerability for high-throughput capture equipment exceeding 200 pages per minute. Distribution runs through direct enterprise sales with embedded professional services for ECM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital mailroom services function as a stable compounder anchored by persistent compliance burdens that resist automation commoditization. HIPAA audit scrutiny and EU AI Act transparency mandates create durable vendor switching costs across healthcare and public-sector verticals.
For Market Incumbents: Anchor market position through backward integration into AI-based extraction engine development, reducing licensing exposure to emerging neural architecture providers. Defend against cloud-native entrants by embedding blockchain-anchored audit trails as standard offerings, creating differentiation that compliance-sensitive buyers cannot replicate without 12-18 month certification cycles. Prioritize capacity expansion in Stuttgart and Munich to capture Bavarian manufacturing cluster consolidation.
For New Entrants and Emerging Players: The mid-market price-point gap between Iron Mountain's premium hybrid bundles and regional scanning bureaus offers white-space entry through AI-native workflow automation without legacy hardware overhead. Target Japanese municipal agencies facing retirement-driven workforce gaps with managed services arrangements assuming full correspondence ownership. Penetrate through outcome-based pricing tied to extraction accuracy SLAs rather than per-page commoditization.
For Investors and Strategic Acquirers: Consolidation pressure builds where HIPAA attestation scarcity meets cloud infrastructure scale requirements, favoring acquisition of HITRUST-certified specialists with established healthcare payer relationships. Long-term viability frames around 5-10 year compliance automation cycles as EU AI Act enforcement ripples through public-sector procurement. Watch for inflection in German municipal RFP language embedding explainability requirements as signal of vendor qualification bar elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Extraction Engine Licensing | Machine learning partnerships with healthcare payers collapse training data requirements for eligibility verification workflows. |
| Blockchain Audit Trail Integration | Immutable ledger anchoring satisfies SEC record retention and GDPR chain-of-custody demands for financial services clients. |
| ISO 27001 Certification Acquisition | Accelerated compliance timelines unlock security-sensitive contracts in government and healthcare verticals. |
| Hybrid Deployment Architecture Launch | Split on-premises capture with cloud analytics reconciles HIPAA local custody mandates with AI classification economics. |
| Geographic Expansion to Japan | METI modernization mandates and workforce retirement create procurement openings for fully outsourced correspondence management. |
Methodological Framework
Bottom-up healthcare payer and corporate office demand modeling reconciled against top-down cloud infrastructure and AI solution provider tracking forms the analytical core. Primary interviews with HIPAA compliance officers, ECM integration specialists, procurement directors at German automotive suppliers, and municipal IT administrators in Japan informed service-type segmentation. Secondary validation drew from SEC 10-K filings of document management providers, CMS Medicare correspondence audit reports, EU AI Act implementation guidance, and hyperscaler AI service capex disclosures.
Input-output matrices map document volume flows across scanning, inbound processing, and AI-based extraction service types, with deployment mode and end-user vertical cross-tabulations informing penetration assumptions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market sizing. Forecast inputs include HIPAA audit frequency trends, EU AI Act enforcement timeline assumptions, and cloud infrastructure migration pace at German manufacturing clusters.
The model assumes a particular technology adoption path; alternative pathways for transformer-based zero-shot classification would alter the outlook if training data requirements collapse faster than projected. Forecasts reflect assumptions about regulatory enforcement intensity and healthcare payer unbundling velocity. A model refresh is warranted upon material change in EU AI Act public-sector procurement specifications or HITRUST certification timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Managed Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Proactive Services Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Europe Warehouse Management Systems Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
IT Staffing Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
US Enterprise Asset Management Market