
 Biodegradable Chelating Agents Market | 2026-2036
Biodegradable Chelating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Chelating Agents Market Analysis
A shift from single-source petrochemical supply toward multi-source bio-based feedstock procurement is repositioning procurement strategies across the value chain. BASF SE leverages its integrated biotechnology platforms to secure fermentation-derived raw materials for GLDA production. Nouryon anchors its position through specialized alkali metal salt formulations that serve high-purity water treatment segments. Jungbunzlauer Suisse AG differentiates via microbial fermentation expertise concentrated in Central European manufacturing clusters.
Biodegradable chelating agents are coordination compounds designed to form stable, water-soluble complexes with metal ions, typically manufactured through microbial fermentation or enzymatic catalysis using renewable carbohydrate feedstocks, with primary industrial purpose centered on metal ion sequestration in cleaning formulations, agricultural micronutrient delivery, and industrial water softening. GLDA dominates product type segments due to its superior biodegradability profile and broad pH stability across application temperatures. Water treatment applications sustain premium pricing pools as utilities confront escalating discharge compliance costs. Green chemistry technology pathways are expanding fastest as enzymatic processes reduce energy intensity and eliminate petrochemical intermediates from synthesis routes.
REACH registration requirements and the EU Green Deal framework constrain conventional EDTA and DTPA placement in European formulations, redirecting formulation chemistry toward GLDA and bio-based alternatives. EPA standards under the Clean Water Act impose parallel discharge limits on metal-chelate complexes in US industrial effluent, shaping product qualification protocols for multinational suppliers. Stakeholders must monitor regulatory divergence between EU hazard-based classification and US risk assessment methodologies as this split determines which biodegradability test protocols achieve market access acceptance.
Market Dynamics
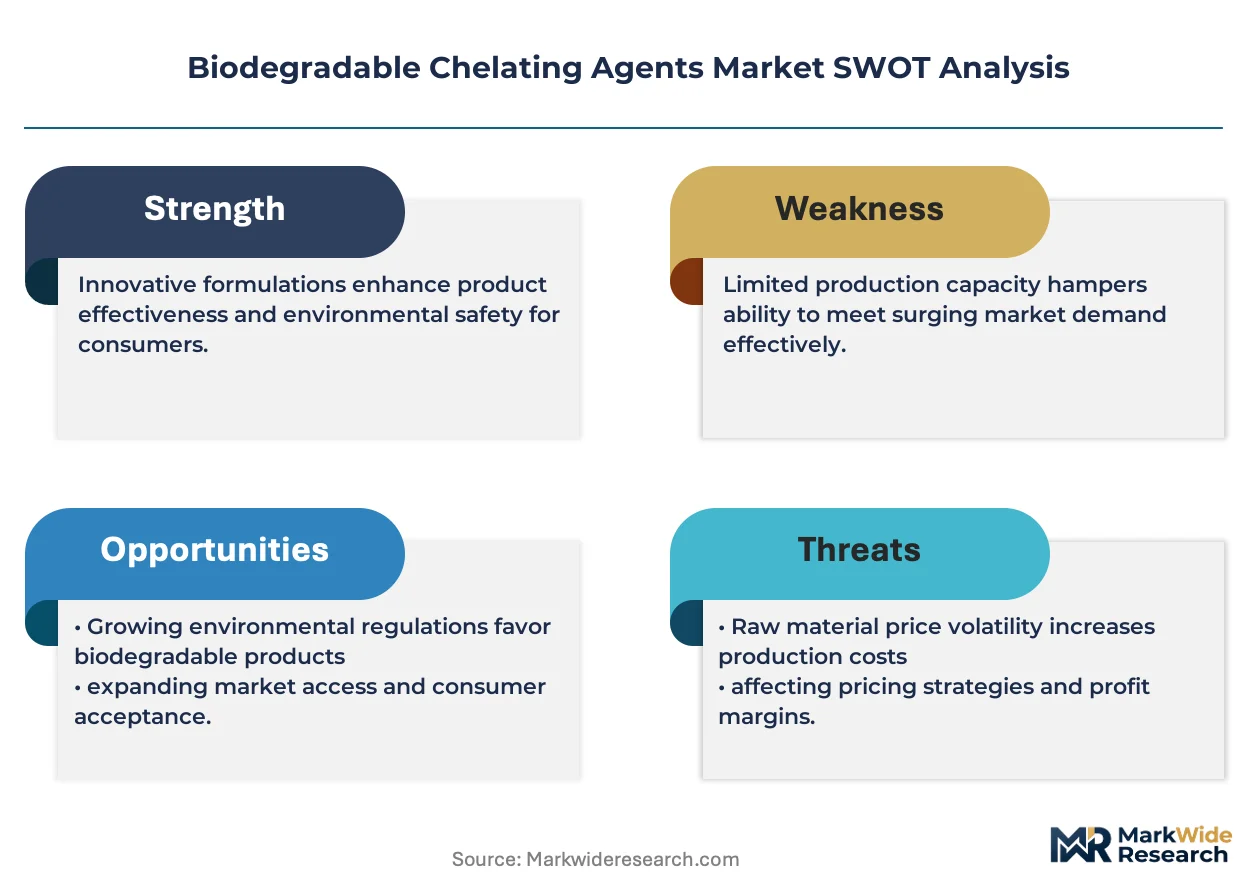
REACH restrictions on persistent chelators are compressing formulation windows for conventional EDTA and DTPA, forcing industrial compounders across Germany, France, and the Netherlands to requalify supply chains around fermentation-derived alternatives before 2027 registration deadlines.
Growth Catalysts
- EU Green Deal framework:The EU Green Deal's chemical sustainability targets mandate biodegradable alternatives in industrial cleaning, creating procurement pull from facility management contractors in Belgium and Denmark.
- Water treatment utilities:German municipal water boards facing tightened phosphonate discharge limits under the Wastewater Ordinance are accelerating GLDA trials for hardness control in boiler feed systems.
- Enzymatic catalysis:Advances in immobilized enzyme reactors are reducing synthesis energy intensity by eliminating high-temperature petrochemical steps, improving unit economics for Central European producers.
Market Restraints
- Feedstock cost volatility:Corn-derived glucose prices fluctuate with agricultural commodity cycles, compressing margins for fermentation-based manufacturers dependent on North American grain supply.
- Technical performance gaps:Bio-based chelators exhibit reduced stability above 80°C in alkaline conditions, limiting substitution rates in high-temperature metal cleaning applications.
- Regulatory test protocol divergence:OECD 301B biodegradability standards accepted in EU REACH registrations differ from EPA 835.3110 protocols required for US Clean Water Act compliance, forcing dual certification costs.
Strategic Opportunities
- Agricultural micronutrient delivery:Controlled-release fertilizer formulations in Poland and Hungary represent underpenetrated demand for biodegradable metal complexation in foliar spray applications.
- Personal care regulatory tailwind:The EU Cosmetics Regulation's microplastic-free positioning is creating preference for GLDA in rinse-off formulations, displacing synthetic polymers in surfactant systems.
- Pulp and paper processing:Scandinavian mills under Nordic Swan Ecolabel requirements are testing bio-chelators for hydrogen peroxide stabilization in mechanical pulp bleaching sequences.
Industry Challenges
- Fermentation scale-up expertise:Qualified bioprocess engineers capable of optimizing GLDA titers above 100g/L remain concentrated at legacy citric acid producers, constraining new entrant capacity expansion.
- REACH data gap closure:Toxicological endpoint studies for chronic aquatic toxicity require 18-24 month timelines, delaying market access for novel bio-based molecular architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Chelating Agents Market |
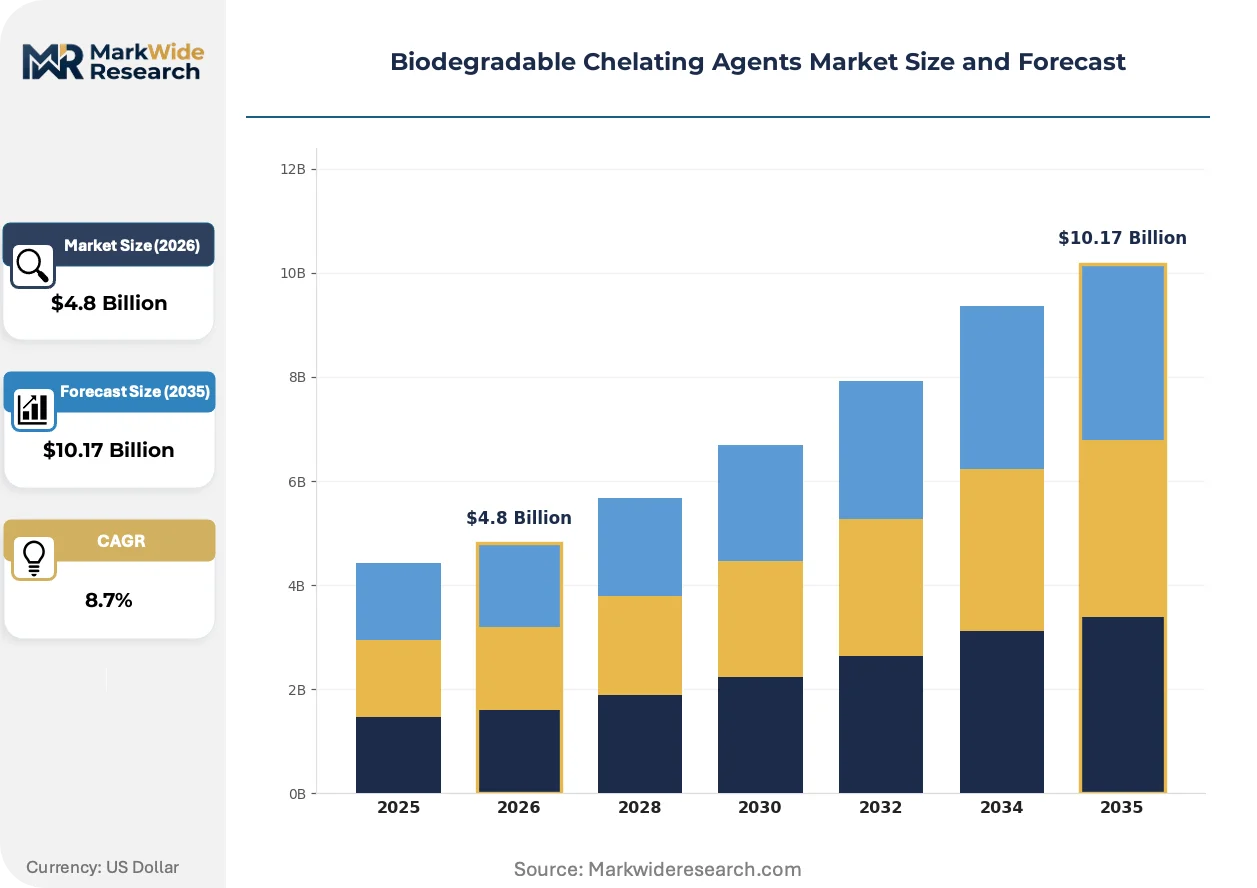
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDTA, NTA, DTPA, GLDA Application: Agriculture, Household Cleaning, Industrial Cleaning, Water Treatment End User: Agriculture Sector, Manufacturing Industry, Residential Users, Water Utilities Technology: Biotechnology, Green Chemistry, High-Performance Liquid Chromatography, Enzymatic Processes |
| Companies Covered | BASF SE, Nouryon, Dow Inc., Solvay S.A., Clariant AG, Lanxess AG, Tosoh Corporation, Jungbunzlauer Suisse AG, Kemira Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Chelating Agents Market Emerging Trajectories
Formulation chemistry is pivoting toward enzymatic synthesis routes that eliminate petrochemical intermediates while regulatory agencies on both sides of the Atlantic tighten discharge compliance windows. These shifts are compressing product development cycles and reconfiguring competitive advantage around biotechnology capabilities rather than conventional chemical engineering.
Enzymatic metal sequestration platforms using engineered oxidoreductases are converging with continuous flow reactor designs to enable ambient-temperature chelator production. Specialty chemical compounders in the Rhine-Ruhr cluster are piloting these systems for GLDA manufacturing. The technology is converging with downstream purification membranes to reduce solvent use and energy consumption versus batch fermentation.
REACH authorization requirements for EDTA under Annex XIV are forcing compounders to submit substitution plans or cease supply to EU industrial cleaning markets by 2026. The regulation is redirecting R&D budgets toward bio-alternative validation and toxicological dossier preparation. Water treatment chemical distributors in Bavaria and Baden-Württemberg are most affected, accelerating supplier qualification programs for GLDA and MGDA alternatives.
Industrial buyers are consolidating supplier panels from twelve-plus vendors to three-to-four preferred partners capable of delivering combined chelator-biocide packages with unified regulatory documentation. This consolidation is displacing spot-market purchasing in favor of multi-year framework agreements with volume commitments. The shift is most visible among German automotive OEM cleaning operations seeking to streamline audit and compliance overhead.
Biodegradable Chelating Agents Market Segmentation
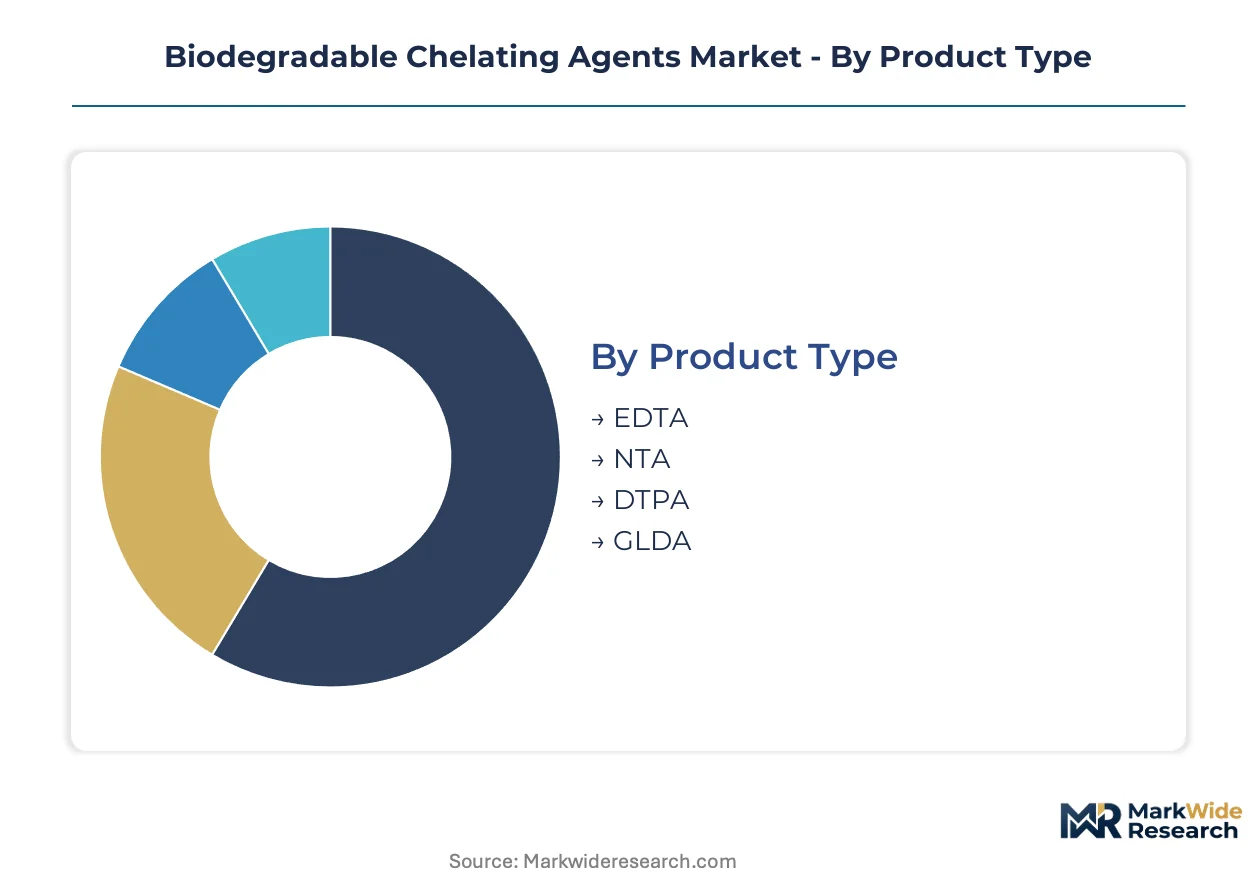
Segmentation in the biodegradable chelating agents market reveals distinct capital requirements and margin profiles across molecular architectures. Each dimension—product chemistry, application intensity, end-user scale, and synthesis technology—shapes supplier positioning and procurement negotiation leverage differently.
Product Type:
GLDA and fermentation-derived alternatives demand the heaviest upfront investment in bioreactor infrastructure and strain development, while petrochemical routes rely more on continuous process engineering.
- GLDA:Manufactured through microbial fermentation of carbohydrate feedstocks using genetically optimized bacterial strains. German water utilities and French industrial cleaning compounders are redirecting procurement volumes here as REACH Annex XIV authorization deadlines approach for conventional alternatives.
- DTPA:A synthetic aminopolycarboxylic acid produced via conventional chemical synthesis with established capacity at legacy petrochemical sites. Demand persists in high-temperature metal cleaning where bio-based alternatives exhibit thermal stability limitations above 80°C.
- EDTA:The incumbent synthetic chelator facing regulatory compression across EU formulations under persistent substance restrictions.
- NTA:A smaller-volume synthetic alternative with niche applications in specific industrial water treatment protocols.
GLDA absorbs the bulk of installed fermentation capacity; DTPA is expanding most quickly in non-EU jurisdictions with less stringent biodegradability mandates.
Application:
Volume concentration varies sharply by application, with water treatment and industrial cleaning commanding multi-ton contracts while household formulations operate on fragmented SKU economics.
- Water Treatment:Municipal and industrial boiler feed systems require high-purity alkali metal salt formulations with documented biodegradability under OECD 301B protocols. German municipal water boards under the Wastewater Ordinance are accelerating supplier qualification for GLDA-based hardness control.
- Industrial Cleaning:Metal surface preparation and equipment degreasing in automotive OEM operations demand chelators with broad pH stability across temperature cycles. Belgian and Danish facility management contractors are consolidating supplier panels to three-to-four preferred partners with unified regulatory documentation.
- Agriculture:Micronutrient delivery systems for foliar fertilizers and controlled-release formulations in Poland and Hungary represent emerging demand pockets with specialized complexation requirements.
- Household Cleaning:Rinse-off formulations under EU Cosmetics Regulation microplastic-free positioning are displacing synthetic polymers, though unit volumes fragment across retail SKU proliferation.
Water Treatment commands the highest contract values per ton; Agriculture is climbing the fastest as Central European fertilizer compounders validate bio-chelator performance in field trials.
End User:
Procurement scale and technical specification intensity diverge dramatically between centralized utility buyers and dispersed residential consumers.
- Water Utilities:German municipal water boards and Scandinavian district heating operators specify chelators with complete REACH registration dossiers and chronic aquatic toxicity data. Multi-year framework agreements with volume commitments are displacing spot-market purchasing.
- Manufacturing Industry:Automotive OEM cleaning operations in Bavaria and Baden-Württemberg seek combined chelator-biocide packages to streamline audit overhead and compliance documentation.
- Agriculture Sector:Fertilizer compounders in Poland and Hungary require price-competitive complexation agents compatible with existing blending equipment and application machinery.
- Residential Users:Fragmented demand channeled through retail and e-commerce platforms with limited technical specification leverage and high price elasticity.
Water Utilities concentrate the largest procurement volumes; the Agriculture Sector is gaining share fastest as foliar micronutrient formulations penetrate Eastern European markets.
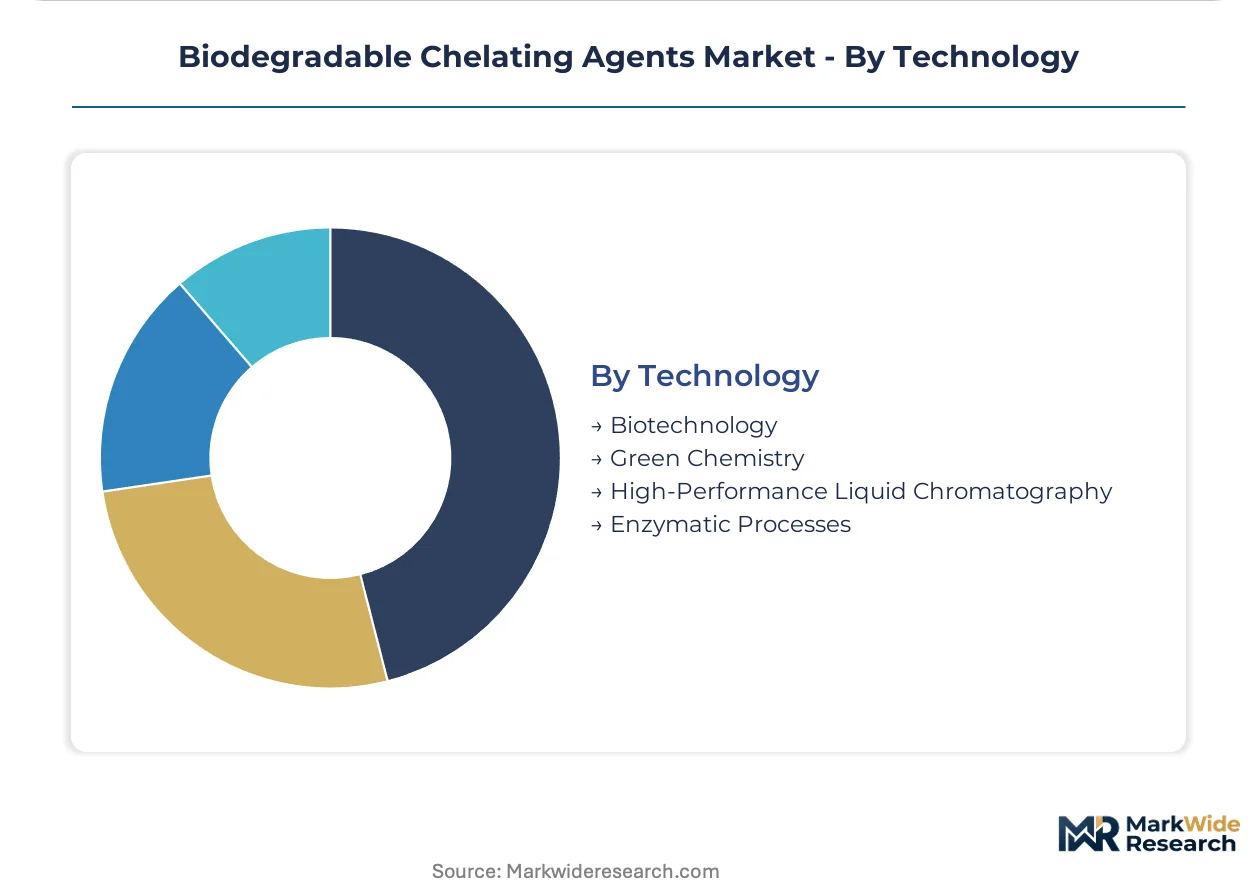
Technology:
Process selection determines energy intensity, feedstock flexibility, and regulatory qualification pathways across the manufacturing base.
- Enzymatic Processes:Immobilized oxidoreductase reactors operating at ambient temperature eliminate high-temperature petrochemical synthesis steps. Rhine-Ruhr cluster specialty compounders are piloting continuous flow designs with downstream membrane purification to reduce solvent use.
- Green Chemistry:Principles-based design eliminating hazardous reagents and minimizing waste streams aligns with EU Green Deal chemical sustainability targets and Ecolabel certification requirements.
- Biotechnology:Microbial fermentation platforms using renewable carbohydrate feedstocks, with strain optimization and titer improvement concentrated at legacy citric acid producers with deep bioprocess engineering expertise.
- High-Performance Liquid Chromatography:Analytical and quality control methodology for purity verification and impurity profiling in high-specification applications, not a primary production technology.
Enzymatic Processes capture the majority of new capital deployment; Green Chemistry adoption is accelerating fastest as regulatory pressure intensifies on conventional synthesis routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn-growing regions in the American Midwest supply carbohydrate feedstocks that anchor fermentation-based production economics. European water utilities and Asian agricultural compounders draw from this supply base while localizing manufacturing to meet regional regulatory requirements.
Germany
Municipal water boards in Bavaria and Baden-Württemberg are accelerating GLDA procurement for boiler feed hardness control. REACH Annex XIV authorization deadlines for EDTA are compressing formulation windows through 2026. The Rhine-Ruhr chemical cluster hosts pilot enzymatic reactor installations for ambient-temperature chelator synthesis.
France
Industrial cleaning compounders around Lyon and Paris are redirecting volumes toward bio-based alternatives as EU Green Deal targets tighten. ANSM oversight of cosmetic-grade formulations is elevating documentation requirements for rinse-off applications. The Greater Paris water utility authority is conducting multi-year GLDA trials for distribution system conditioning.
United States
EPA 835.3110 biodegradability protocols are shaping product qualification for Clean Water Act compliance in Great Lakes industrial discharge zones. Corn-derived glucose from Iowa and Illinois feedstocks supplies fermentation platforms. Specialty chemical distributors in Texas and Louisiana are qualifying bio-chelators for offshore platform water treatment.
China
MIIT guidelines on green chemical manufacturing are redirecting investment toward enzymatic synthesis routes in the Yangtze River Delta. Dual carbon goals are elevating bio-based feedstock preference for agricultural micronutrient formulations. Shandong Province fertilizer compounders are testing fermentation-derived chelators in controlled-release field trials.
Poland
Agricultural cooperatives in the Masovian and Greater Poland voivodeships are expanding foliar fertilizer applications requiring metal complexation agents. EU Common Agricultural Policy sustainability criteria are elevating biodegradable input preference. Poznań-area blending facilities are validating GLDA compatibility with existing application machinery.
Biodegradable Chelating Agents Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation infrastructure scales to meet substitution demand from restricted synthetic alternatives. The market structure concentrates around integrated biotechnology platforms and specialized alkali metal salt formulators, with mid-tier compounders filling regional supply gaps. Three archetypes prevail: legacy citric acid producers with deep bioprocess expertise, diversified chemical majors with REACH registration capabilities, and regional water treatment specialists with utility relationships. M&A activity targets fermentation scale-up expertise, while strategic partnerships secure multi-year feedstock offtake agreements.
Among European-integrated chemical majors, BASF SE exemplifies the biotechnology platform archetype through fermentation-derived raw material integration. Nouryon occupies a position among specialized formulation providers serving high-purity water treatment segments. Jungbunzlauer Suisse AG represents the legacy bioprocess engineering tier with concentrated Central European manufacturing expertise.
| Leading Market Players |
|---|
| BASF SE |
| Nouryon |
| Dow Inc. |
| Solvay S.A. |
| Clariant AG |
| Lanxess AG |
| Tosoh Corporation |
| Jungbunzlauer Suisse AG |
| Kemira Oyj |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-registered fermentation platforms and unregistered commodity imports splits procurement economics across German water utilities and price-sensitive Polish fertilizer compounders. Premium-tier suppliers bundle chronic aquatic toxicity dossiers with multi-year framework agreements, while commodity traders spot-sell unregistered bio-chelators through Baltic port distributors.
Pricing Analysis
Service-bundling separates contract structures: premium tier wraps regulatory documentation, REACH data gap closure support, and technical field service into per-kilogram pricing, while economy tier strips these to commodity spot quotes. Price differentiation rests on OECD 301B biodegradability certification and alkali metal salt purity grades. Cost compression in the economy tier intensifies as Ukrainian glucose feedstock disruptors undercut Central European fermentation bases. Polish agricultural cooperatives exhibit highest price sensitivity; German municipal water boards absorb premium spreads for compliance certainty.
Supply Chain Analysis
Domestic-content mandates under EU Green Deal procurement guidelines redirect sourcing toward fermentation capacity sited within member states. Manufacturing concentrates in Germany, France, and Belgium, with corn-derived glucose feedstock drawn from Iowa and Illinois agricultural belts. Supply chain risk centers on single-source vulnerability for engineered bacterial strains optimized above 100g/L titers. Distribution runs through Rhine-Ruhr chemical distributors serving industrial cleaning compounders and specialized water treatment formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH Annex XIV authorization deadlines for EDTA erect barrier-to-entry moats for dossier-complete fermentation players. Regulatory data generation timelines of 18-24 months for novel molecular architectures protect incumbent positions.
For Market Incumbents: Anchor fermentation capacity expansion in Central European manufacturing clusters to capture substitution demand from compressed synthetic chelator windows. Defend against enzymatic catalysis disruptors by securing captive glucose offtake agreements with North American grain cooperatives. Prioritize backward integration into strain development capabilities held by legacy citric acid producers.
For New Entrants and Emerging Players: Water treatment distributors in Bavaria and Baden-Württemberg offer channel access to consolidated automotive OEM cleaning panels seeking unified regulatory documentation. Target agricultural micronutrient delivery in Poland and Hungary where foliar fertilizer compounders validate bio-chelator performance with limited incumbent penetration. Pursue co-development partnerships with Scandinavian pulp mills under Nordic Swan Ecolabel requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated biotechnology platforms possessing REACH registration capabilities given accelerating substitution mandates across EU industrial cleaning markets. Five-to-ten year viability favors fermentation infrastructure owners with demonstrated titer optimization above 100g/L. Monitor GLDA spot price spreads against synthetic alternatives as inflection signal for capacity utilization tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Captures substitution volume as REACH Annex XIV deadlines compress EDTA formulation windows through 2026. |
| Backward Integration | Secures captive glucose supply from Iowa and Illinois grain belts against agricultural commodity volatility. |
| Green Manufacturing Transition | Aligns with EU Green Deal chemical sustainability targets and Ecolabel certification requirements. |
| Long-term Supply Agreement | Locks multi-year framework contracts with German municipal water boards displacing spot-market purchasing. |
| Joint Venture | Combines legacy citric acid bioprocess expertise with REACH registration capabilities for accelerated market access. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with fermentation plant managers, procurement leads at German water utilities, distribution channel partners in the Rhine-Ruhr cluster, and technical R&D directors at industrial cleaning compounders. Cefic chemical industry reports, ECHA registration dossiers, SEC 10-K disclosures, and OECD biodegradability study databases supplied validation benchmarks. Bottom-up capacity installation tracking and top-down demand segmentation by end-use industry were triangulated for convergence.
Segment-level modeling applied product chemistry, application intensity, end-user scale, and synthesis technology as dimensional axes across the projection horizon. CAGRs were derived from installed fermentation capacity expansion schedules, substitution elasticity estimates for restricted synthetic alternatives, and regional regulatory enforcement intensity differentials. Price formation incorporated glucose feedstock futures curves, REACH data gap closure cost trajectories, and utility procurement contract term structures.
Several conditions sit outside the modeled scope, including abrupt REACH authorization timeline extensions, breakthrough high-temperature stability in bio-based molecular architectures, and trade policy disruptions affecting North American grain export flows. Forecasts reflect documented assumptions around regulatory enforcement consistency and strain optimization learning curve rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Betulinic Acid Market