
 Lactic Acid Blend Market | 2026-2036
Lactic Acid Blend Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Acid Blend Market Intelligence
Market Context
Subscription-based technical service and formulation support is expanding how lactic acid blend suppliers monetize customer relationships beyond commodity volume. Corbion leverages its fermentation expertise to sustain long-term supply agreements with European food manufacturers. Galactic anchors its position through deep specialization in cosmetic-grade blends for personal care formulators. Cargill competes by controlling upstream corn dextrose supply across North American production facilities.
Technical Definition and Segment Structure
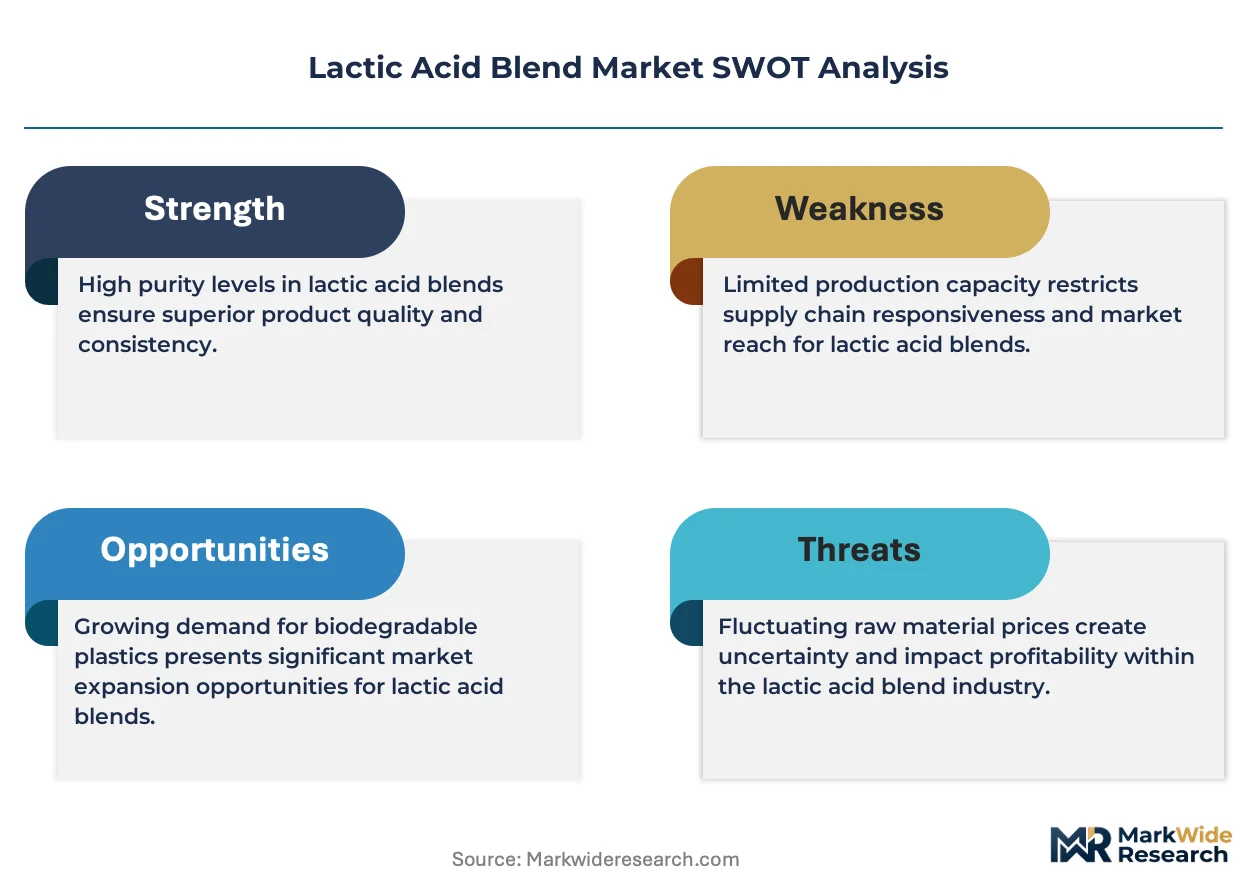
Lactic acid blends comprise mixtures of L-lactic acid, D-lactic acid, or polylactic acid derivatives formulated to specific purity and concentration thresholds for industrial, food, pharmaceutical, or cosmetic applications, typically manufactured through carbohydrate fermentation followed by purification and standardization to pH and optical activity specifications. Food-grade blends dominate current volume flows, while pharmaceutical-grade variants command concentrated margin pools due to USP and EP certification requirements. Bioplastics applications represent the fastest-expanding demand channel as polylactic acid resin producers scale capacity.
Regulatory Environment and Outlook
FDA food additive regulations, EPA bio-based product standards, and REACH chemical registration requirements in Europe collectively shape formulation standards, purity thresholds, and market access conditions for cross-border trade. EFSA safety assessments and JECFA specifications further constrain allowable impurity profiles in food and pharmaceutical applications. Stakeholders must monitor evolving bioplastics certification schemes and compostability standards to anticipate which blend specifications will qualify for preferred procurement programs.
Market Dynamics
Fermentation-based carbohydrate feedstock sourcing is concentrating supply power among corn belt processors, while bioplastics manufacturers in Germany and Thailand lock in multi-year polylactic acid precursor contracts ahead of capacity expansions.
Growth Catalysts
- REACH purity mandates:ECHA registration requirements for chemical substances are forcing blend standardization upgrades across European cosmetic and pharmaceutical channels, filtering out sub-scale producers.
- Bioplastics feedstock demand:Polylactic acid resin manufacturers are securing dedicated lactic acid blend supply streams to meet compostable packaging procurement programs from food service distributors.
- Thailand:Government bio-economy incentives and existing cassava processing infrastructure are attracting fermentation capacity investments for export-grade blend production.
Market Restraints
- Corn dextrose price volatility:North American wet milling output fluctuations transmit directly to lactic acid blend production economics, compressing margin buffers for non-integrated processors.
- Optical purity technical ceiling:Current crystallization and membrane separation methods face yield constraints when pushing L-lactic acid enantiomeric excess above 99.5 percent for pharmaceutical USP grades.
- Citric acid substitution:Food preservation applications in beverage and sauce segments are partially migrating to citric acid blends where pH adjustment tolerance permits lower cost inputs.
Strategic Opportunities
- India personal care penetration:Cosmetic-grade lactic acid blend consumption in skin care formulator channels remains underdeveloped relative to Southeast Asian benchmarks, presenting first-mover positioning potential.
- EU Green Deal bioplastics procurement:Public sector packaging mandates and extended producer responsibility schemes are creating preferred supplier status for certified compostable material feedstock sources.
- Continuous fermentation process integration:Cell retention and in-situ product removal technologies are converging to enable higher titer, lower capital intensity production architectures.
Industry Challenges
- USP and EP certification timelines:Pharmaceutical-grade blend qualification requires 18-24 month stability documentation cycles that delay revenue recognition from new production assets.
- Purification capex intensity:Ion exchange and electrodialysis equipment for food-grade to pharmaceutical-grade upgrading demands front-loaded capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Acid Blend Market |
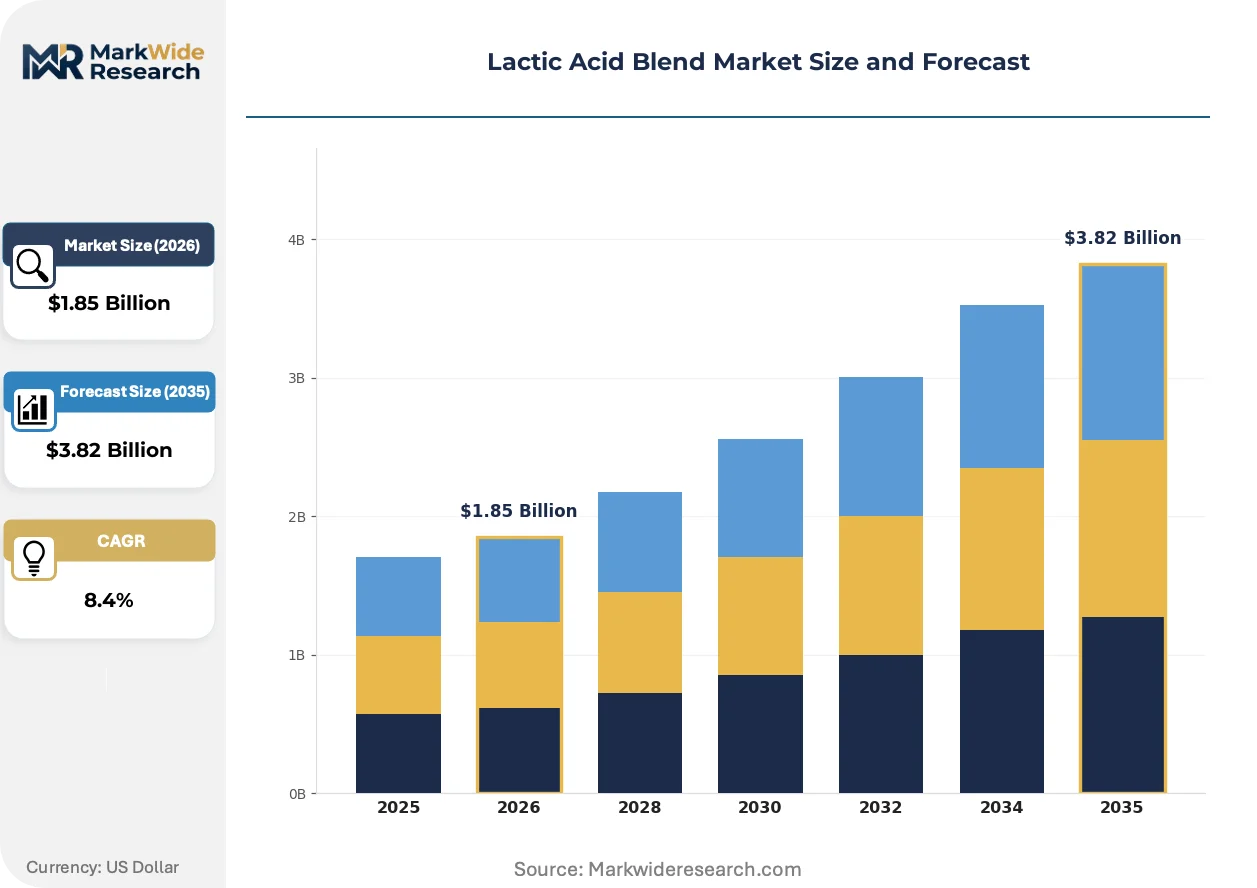
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade Application: Food Preservation, Personal Care, Pharmaceuticals, Bioplastics End User: Food Industry, Cosmetic Manufacturers, Pharmaceutical Companies, Plastic Producers Form: Liquid, Powder, Granule, Tablet |
| Companies Covered | Galactic, Cargill, Corbion, Musashino Chemical, Jungbunzlauer, NatureWorks, BASF, Futerro, Henan Jindan Lactic Acid Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Acid Blend Market Strategic Shifts & Innovations
Process intensification and regulatory certification convergence are compressing the traditional separation between commodity food-grade and specialty pharmaceutical-grade production architectures.
Membrane electrodialysis hybrid systems are unifying purification steps previously executed through discrete ion exchange and solvent extraction stages. Bioplastics manufacturers in Germany and Thailand are adopting these integrated platforms to secure optical purity specifications without dedicated pharmaceutical-grade asset footprints. The technology is unifying what were historically separate production cost structures, enabling mid-scale fermenters to serve multiple end-use tiers from common upstream assets.
EFSA safety reassessments for food additive usage levels are tightening impurity thresholds for ethyl lactate and heavy metal residuals. European compounders serving infant formula and organic labeled channels are reformulating to preempt stricter maximum residue limits. Food-grade blend specifications in France and Italy are already migrating toward pharmaceutical-grade analytical detection limits as a defensive compliance posture.
Long-term offtake contracting is displacing spot market purchasing among personal care formulators seeking supply security for cosmetic acid blend inputs. Multinational beauty brands are directly negotiating three to five year supply agreements with fermentation specialists, bypassing traditional distributor intermediaries. This pattern is most visible in German and Dutch cosmetic manufacturing clusters where just-in-time inventory models previously dominated.
Lactic Acid Blend Market Segmentation
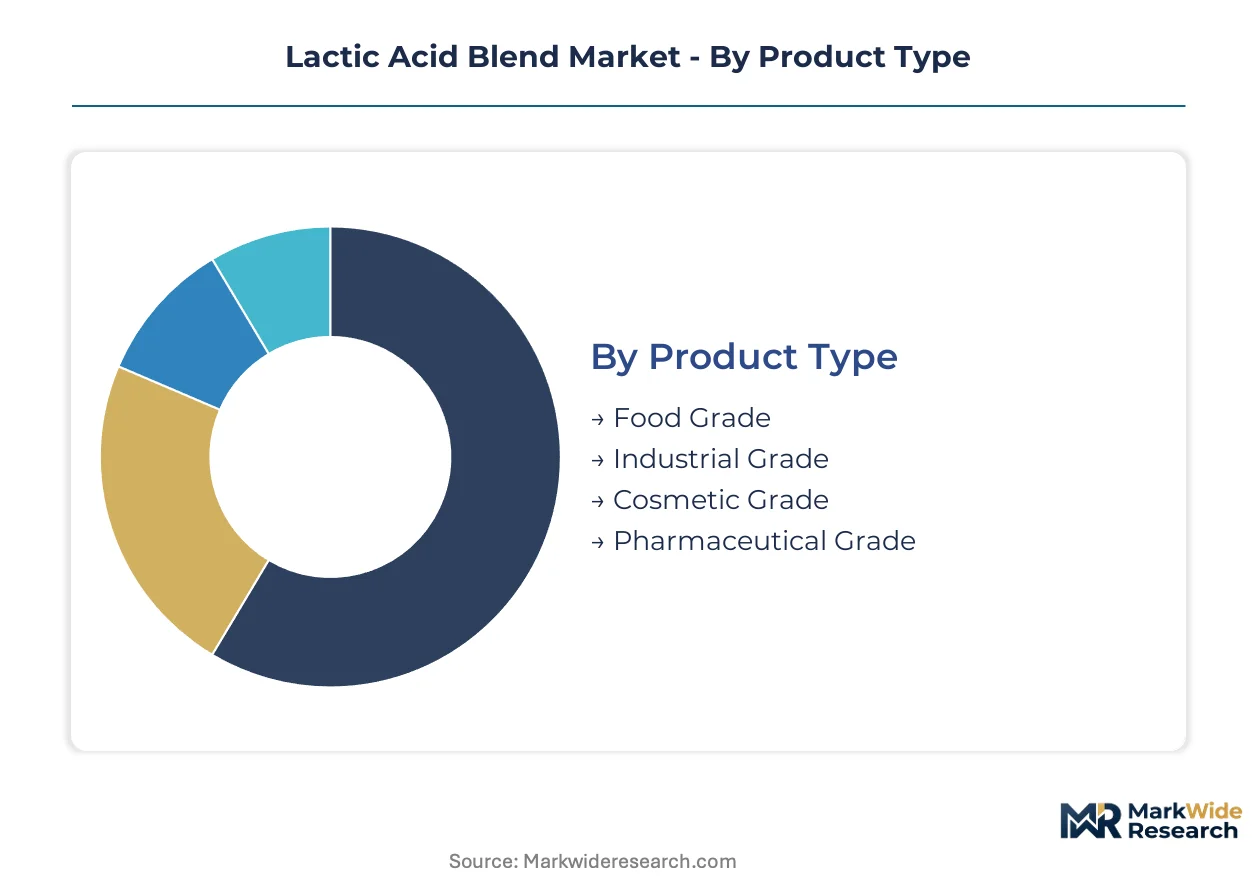
Segmentation in the lactic acid blend market reflects divergent purity mandates, feedstock specifications, and certification burdens that fragment procurement behavior across food, pharmaceutical, and industrial channels. Suppliers configure production assets around specific grade thresholds rather than fungible commodity output.
Product Type:
Certification burden varies sharply across grades, with pharmaceutical and food applications demanding USP, EP, and FDA food additive compliance while industrial grades operate under lighter REACH registration thresholds.
- Food Grade:Blends meeting FDA food additive regulations and EFSA safety assessments for pH control, preservation, and flavor enhancement in packaged goods. Demand concentrates in Germany and France where organic and infant formula channels are tightening impurity thresholds toward pharmaceutical-grade detection limits.
- Pharmaceutical Grade:USP and EP-certified blends requiring 18-24 month stability documentation, enantiomeric excess above 99.5 percent for L-lactic acid, and heavy metal residual controls. German and Swiss drug manufacturers lock in long-term offtake agreements to secure supply security for parenteral and topical formulations.
- Industrial Grade:Standardized fermentation output for chemical synthesis and leather processing without pharmaceutical or food certification overhead.
- Cosmetic Grade:ECHA-registered blends for personal care formulators meeting EU Cosmetics Regulation safety dossier requirements.
Leading the category by volume: Food Grade. Expanding most quickly: Pharmaceutical Grade.
Application:
Application segmentation tracks how end-use specifications cascade backward into blend formulation requirements and supplier qualification protocols.
- Bioplastics:Polylactic acid resin feedstock demanding optical purity and low residual lactide for compostable packaging certification. Thai and German manufacturers are scaling dedicated precursor supply streams ahead of capacity expansions.
- Food Preservation:pH adjustment and antimicrobial preservation in sauces, beverages, and ready-to-eat meals facing citric acid substitution pressure where cost tolerance permits lower-performance inputs.
- Personal Care:Skin care and hair care formulator demand for exfoliant and pH buffering functions in Southeast Asian and Indian markets.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications requiring batch-to-batch consistency documentation for regulatory filings.
Dominant by current volume flows: Food Preservation. Steepest expansion trajectory: Bioplastics.
End User:
End user categories reflect procurement scale, technical service requirements, and contract duration patterns that differentiate supplier monetization models.
- Food Industry:Packaged goods manufacturers and beverage processors purchasing through distributor networks or direct fermentation specialist contracts depending on volume scale.
- Plastic Producers:Polylactic acid resin manufacturers negotiating multi-year feedstock agreements with optical purity specifications and volume commitments.
- Cosmetic Manufacturers:Personal care formulators in German and Dutch clusters shifting from spot purchasing to three-to-five-year supply agreements with fermentation specialists.
- Pharmaceutical Companies:Drug manufacturers requiring qualified supplier status, audit trails, and regulatory support for API and excipient applications.
Highest procurement volume: Food Industry. Fastest contract duration extension: Plastic Producers.
Form:
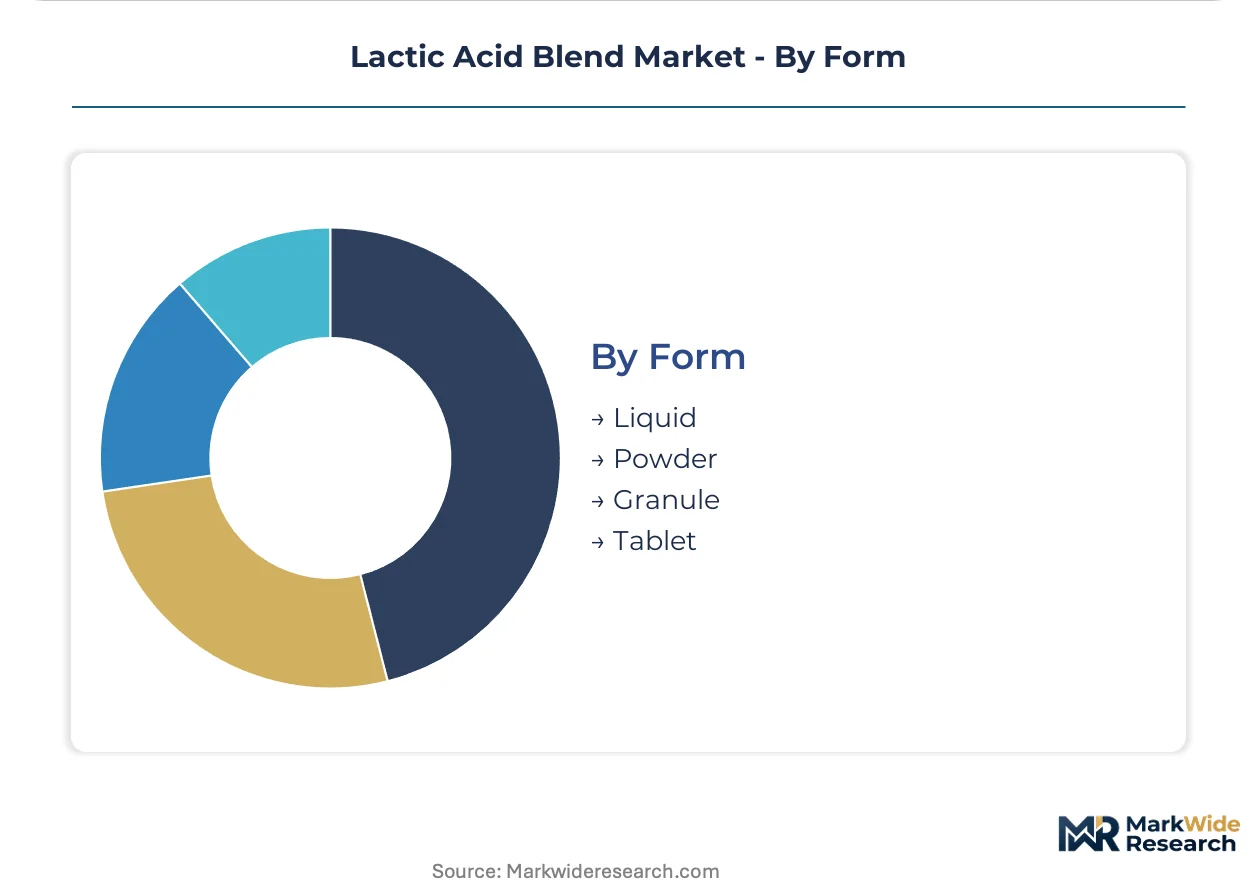
Physical form selection determines logistics economics, handling equipment requirements, and dissolution kinetics for specific manufacturing processes.
- Liquid:Aqueous solutions at standardized concentrations for direct metering into fermentation, food processing, and chemical synthesis operations. Dominates bioplastics feedstock and large-scale food preservation applications for pump-and-meter handling efficiency.
- Powder:Spray-dried or crystallized product for dry blending in cosmetic compounding, pharmaceutical tablet manufacturing, and powder beverage formulations.
- Granule:Agglomerated particles for controlled dissolution in industrial chemical processes and specific pharmaceutical granulation operations.
- Tablet:Compressed solid dosage forms for precise unit-dose dispensing in laboratory, pharmaceutical, and specialty chemical applications.
Leading by shipment volume: Liquid. Gaining share fastest: Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in the United States and Thailand while consumption concentrates in German bioplastics corridors and European food preservation channels. This geographic split creates dedicated export flows from corn-belt processing zones to industrial demand centers.
Germany
Polylactic acid resin manufacturers in the Rhineland industrial belt are locking in multi-year lactic acid blend supply contracts ahead of capacity expansions. REACH registration requirements under ECHA jurisdiction are forcing standardization upgrades across cosmetic and pharmaceutical channels. The Leverkusen-Düsseldorf corridor hosts concentrated bioplastics feedstock demand from compostable packaging producers.
United States
Corn dextrose wet milling output from Iowa and Illinois processing facilities supplies fermentation feedstock for domestic lactic acid blend production. FDA food additive regulations and EPA bio-based product standards shape formulation requirements for cross-state distribution. The Midwest corn belt anchors upstream supply power with integrated processors controlling carbohydrate sourcing.
Thailand
Government bio-economy incentives and existing cassava processing infrastructure are attracting fermentation capacity investments for export-grade blend production. National bio-economy policy frameworks prioritize renewable chemical manufacturing clusters. The Eastern Economic Corridor near Rayong is scaling dedicated precursor supply streams for regional bioplastics manufacturers.
France
Organic and infant formula channels are tightening food-grade impurity thresholds toward pharmaceutical-grade detection limits ahead of anticipated EFSA safety reassessments. EU Cosmetics Regulation compliance requirements under ECHA registration constrain personal care formulation inputs. The Lyon-Grenoble pharmaceutical manufacturing cluster demands USP and EP-certified blends with extended stability documentation.
India
Cosmetic-grade lactic acid blend consumption in skin care formulator channels remains underdeveloped relative to Southeast Asian benchmarks. FSSAI food additive standards and BIS quality certification requirements shape import specifications for food preservation applications. The Mumbai-Pune industrial corridor presents first-mover positioning potential for personal care ingredient suppliers.
Lactic Acid Blend Market Key Industry Players
Top-tier vendors anchor long-term supply agreements with optical purity specifications, while mid-scale fermenters compete on regional feedstock access and certification agility. The vendor base stratifies around fermentation expertise, upstream carbohydrate control, and pharmaceutical-grade qualification timelines. Three archetypes dominate: integrated agribusiness conglomerates with captive corn supply, specialized fermentation houses with cosmetic-grade dossiers, and polylactic acid resin producers with backward integration into precursor manufacturing. Competitive moves concentrate on multi-year offtake contracting and membrane electrodialysis technology licensing.
Within the specialized fermentation tier, Galactic and Jungbunzlauer exemplify cosmetic-grade blend specialists with deep ECHA registration expertise. Corbion represents the integrated fermentation house archetype with long-term European food manufacturer relationships. Among Asia-Pacific capacity builders, Henan Jindan Lactic Acid Technology occupies a position as a scale-driven Chinese supplier leveraging regional carbohydrate processing infrastructure.
| Leading Market Players |
|---|
| Galactic |
| Cargill |
| Corbion |
| Musashino Chemical |
| Jungbunzlauer |
| NatureWorks |
| BASF |
| Futerro |
| Henan Jindan Lactic Acid Technology |
| Others |
Cost & Logistics Intelligence
Corn dextrose futures on the Chicago Board of Trade transmit volatility directly through fermentation economics, compressing margin buffers for non-integrated processors while concentrating pricing power among wet millers with captive carbohydrate supply. This feedstock cost cascade stratifies blend procurement into contract-based long-term offtake agreements for bioplastics manufacturers versus spot-market purchasing for smaller food preservation formulators.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects 18-24 month USP and EP certification timelines that delay revenue recognition from new production assets. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified blends with enantiomeric excess above 99.5 percent from food-grade variants facing citric acid substitution pressure. Cost-down pressure on cosmetic-grade tiers accelerates because personal care formulators in Southeast Asia are consolidating supplier relationships. Food preservation buyers exhibit highest price sensitivity due to readily available acid alternatives, while polylactic acid resin manufacturers lock in volume commitments with lowest sensitivity to per-unit fluctuations.
Supply Chain Analysis
REACH registration requirements under ECHA jurisdiction are gating market access for sub-scale European compounders unable to fund standardization upgrades. Supply concentrates in the United States, Thailand, and Germany, with corn belt wet milling, cassava fermentation infrastructure, and Rhineland bioplastics corridors forming distinct nodes. Raw material dependencies center on corn dextrose, cassava starch, and ion exchange resins for purification upgrading. Single-source vulnerability concentrates in pharmaceutical-grade membrane electrodialysis equipment suppliers. Distribution runs through fermentation specialists serving direct long-term contracts with plastic producers and cosmetic manufacturers, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-mandated purity upgrades that filter out sub-scale producers unable to fund certification investments. ECHA registration timelines and pharmaceutical-grade qualification cycles are forcing weaker players toward exit or acquisition.
For Market Incumbents: Lock in multi-year polylactic acid precursor contracts with optical purity specifications ahead of Thai and German capacity expansions. Secure backward integration into corn dextrose supply or cassava processing infrastructure to defend margin position against feedstock volatility. Prioritize membrane electrodialysis technology licensing to mid-scale fermenters seeking pharmaceutical-grade qualification without dedicated asset footprints. For New Entrants and Emerging Players: Cosmetic-grade lactic acid blend demand in Indian skin care formulator channels remains underserved relative to Southeast Asian penetration benchmarks. Target Mumbai-Pune industrial corridor personal care manufacturers with ECHA-registered dossiers and technical formulation support services. Deploy direct sales teams to bypass distributor intermediaries that currently dominate spot purchasing patterns. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European fermentation houses with existing cosmetic-grade ECHA registrations but insufficient capital for USP and EP pharmaceutical-grade upgrading. Long-term viability over a multi-year window rests on securing preferred supplier status under EU Green Deal bioplastics procurement mandates. Watch for inflection signals in compostable packaging certification scheme adoption rates by food service distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Polylactic acid resin manufacturers in Germany secure optical purity specifications ahead of capacity ramps. |
| Backward Integration | Corn belt processors control upstream dextrose supply to defend margin buffers against wet milling volatility. |
| Green Manufacturing Transition | Cassava-based fermentation in Thailand aligns with national bio-economy policy frameworks and export-grade certification. |
| Capacity Expansion | Eastern Economic Corridor investments scale dedicated precursor supply streams for regional bioplastics demand. |
| Joint Venture | Membrane electrodialysis technology licensing partnerships unify purification steps for mid-scale European compounders. |
Research Approach
Document review covered FDA food additive regulations, ECHA REACH registration databases, and SEC filings from integrated agribusiness conglomerates, complemented by interviews with fermentation plant managers, cosmetic formulation R&D directors, bioplastics procurement leads, and pharmaceutical regulatory affairs specialists. Secondary validation drew from customs trade data, EFSA safety assessment archives, and national bio-economy policy frameworks. Bottom-up volume modeling triangulated against top-down industry association benchmarks.
Historical capacity expansion patterns cross-referenced against panel input from procurement officers at polylactic acid resin manufacturers anchored CAGR derivation across the analysis window. Segmentation dimensions modeled included grade tier certification burden, end-use application specifications, physical form logistics economics, and regional production hub regulatory frameworks. Forecast inputs incorporated corn dextrose price volatility assumptions and EFSA safety reassessment timelines for food additive usage levels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bioplastics compostability certification scheme adoption and citric acid substitution rates in food preservation channels. A model refresh is warranted upon material change in REACH purity mandate enforcement intensity or Thai government bio-economy incentive program revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
United States Aerosol Cans Market