
 Global Liquid Process Analyzer Market | 2026-2036
Global Liquid Process Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Process Analyzer Market Foresight
Asian sensor manufacturing is consolidating as domestic producers scale electrochemical and spectroscopic module output. Emerson Electric leverages vertical integration across transmitter and sensor assembly to sustain pricing power in petrochemical contracts. ABB anchors European utility deployments with integrated digital platforms that compete on protocol compatibility rather than hardware cost alone.
Liquid process analyzers are instruments that measure chemical, physical, or biological parameters in flowing liquid streams, typically achieving response times under thirty seconds for critical parameters like pH, dissolved oxygen, or hydrocarbon concentration, and serve to enable automated process control, regulatory compliance, and quality assurance in continuous manufacturing environments. Inline analyzers dominate installed base across water treatment and petrochemical processing due to their elimination of sampling lag, while laser spectrometry is displacing older chromatography methods in pharmaceutical manufacturing where non-contact measurement reduces contamination risk. Electrochemical sensors occupy the largest technology share by volume because of their lower capital cost and established calibration protocols, though spectroscopy commands margin premiums in food and beverage applications requiring multi-parameter detection.
EPA effluent guidelines and EU Water Framework Directive enforcement are forcing North American and European facilities toward continuous emission monitoring systems that demand analyzer redundancy and data logging capabilities. China's MEE has tightened surface water quality standards, compelling domestic chemical producers to source analyzers meeting GB calibration protocols for discharge permitting. Stakeholders must weigh upgrade cycles against emerging digital twin integration requirements that will redefine how analyzer data flows into enterprise asset management platforms.
Market Dynamics
Laser spectrometry is compressing chromatography's installed base as pharmaceutical manufacturers prioritize non-contact measurement to eliminate contamination pathways in sterile processing environments.
Growth Catalysts
- EPA effluent guidelines:North American chemical processors must deploy redundant continuous monitoring systems, expanding analyzer replacement cycles.
- Water treatment utilities:Inline pH and dissolved oxygen sensors eliminate sampling lag, driving real-time process control adoption.
- China's MEE surface water standards:Domestic chemical producers source GB-calibrated analyzers for discharge permitting compliance.
Market Restraints
- Electrochemical sensor supply concentration:Asian module producers control electrochemical cell manufacturing, creating single-source vulnerability.
- Spectroscopy capital intensity:UV-Vis and infrared systems require 3-4x the upfront investment of electrochemical alternatives.
- Calibration protocol fragmentation:Divergent GB, EPA, and EU standards force manufacturers to maintain multiple certification streams.
Strategic Opportunities
- Digital twin integration:Analyzer data streams into enterprise asset management platforms, creating predictive maintenance revenue.
- Food and beverage multi-parameter detection:Spectroscopy commands margin premiums where simultaneous contaminant screening replaces sequential testing.
- India's Central Pollution Control Board enforcement:Textile and tannery clusters face first-time continuous monitoring mandates.
Industry Challenges
- Spectroscopic technician scarcity:Laser and mass spectrometry systems require specialized calibration expertise unavailable in regional service networks.
- Legacy 4-20mA integration:Digital platform analyzers must bridge analog infrastructure in brownfield petrochemical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Process Analyzer Market |
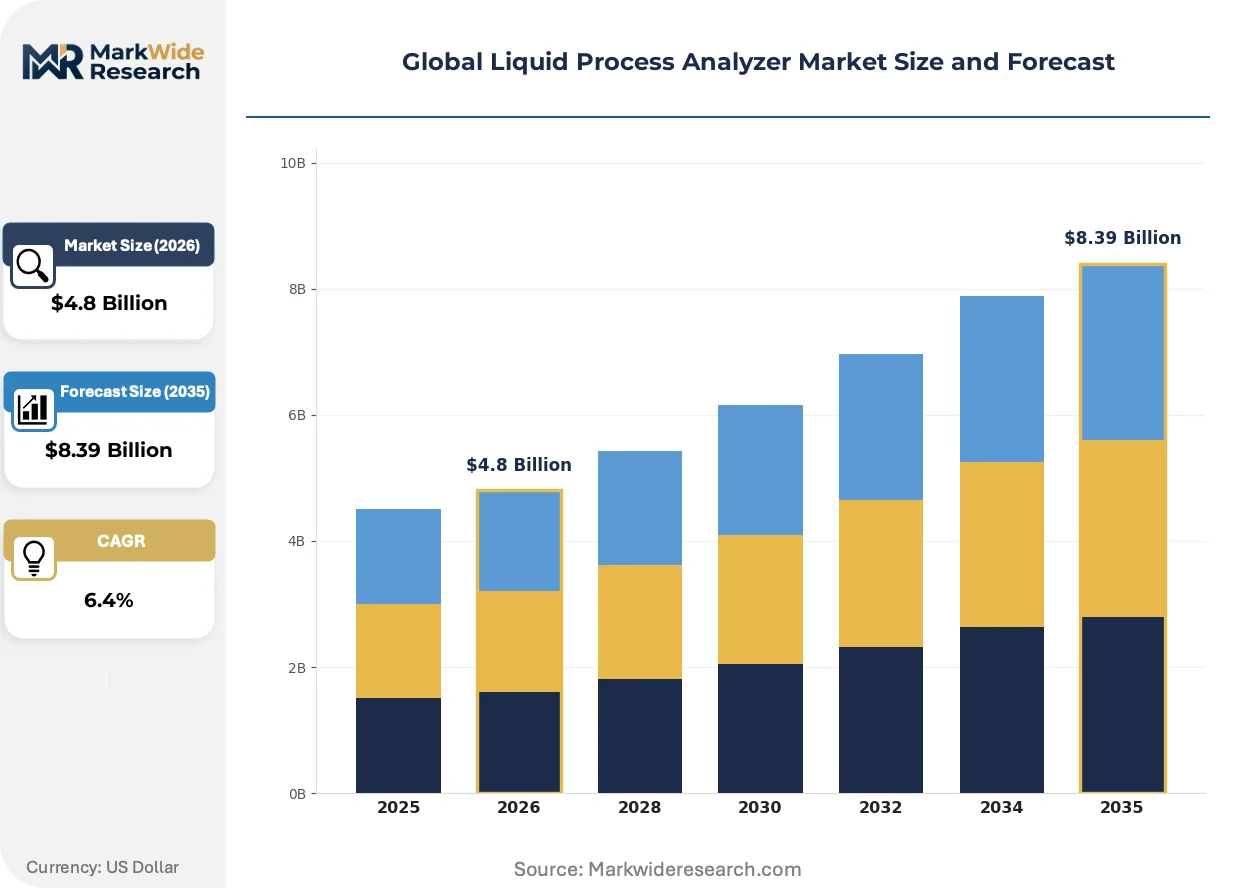
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Inline Analyzers, Online Analyzers, Benchtop Analyzers Technology: Chromatography, Spectroscopy, Electrochemical Sensors, Laser Spectrometry, Nuclear Magnetic Resonance Application: Water Treatment, Food & Beverage Production, Pharmaceuticals Manufacturing, Petrochemical Processing, Paper & Pulp Analysis End User: Chemical Production Facilities, Oil Refineries, Biotechnology Firms, Environmental Monitoring Agencies, Academic Research Institutes |
| Companies Covered | Emerson Electric, ABB, Endress+Hauser, Yokogawa Electric, Siemens, Thermo Fisher Scientific, Mettler-Toledo, Teledyne Technologies, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Process Analyzer Market Shifts & Advancements
Analyzer architecture is bifurcating between low-cost electrochemical volume and premium spectroscopic intelligence, with connectivity standards determining competitive positioning more than measurement accuracy alone.
Raman spectroscopy is absorbing pharmaceutical quality control workflows as manufacturers eliminate sample extraction for bioreactor monitoring. Vaccine producers in Switzerland and Singapore deploy inline Raman probes for real-time glucose and lactate tracking. The technology is absorbing service revenue from offline chromatography labs, compressing third-party testing margins.
REACH chemical registration requirements are forcing European specialty chemical producers to document contaminant profiles at ppb thresholds. Continuous emission monitoring systems now require data logging capabilities spanning ten-year retention periods. German and Dutch facilities are upgrading to laser-induced breakdown spectroscopy to meet ECHA documentation demands without batch sampling delays.
Petrochemical buyers are unbundling analyzer hardware from service contracts, compressing vendor margins on installation and calibration. Integrated digital platforms from ABB and Emerson face pressure from standalone sensor suppliers offering API-first data architectures. This pattern is most visible in US Gulf Coast refineries where procurement teams prioritize interoperability over single-source accountability.
Global Liquid Process Analyzer Market Segmentation
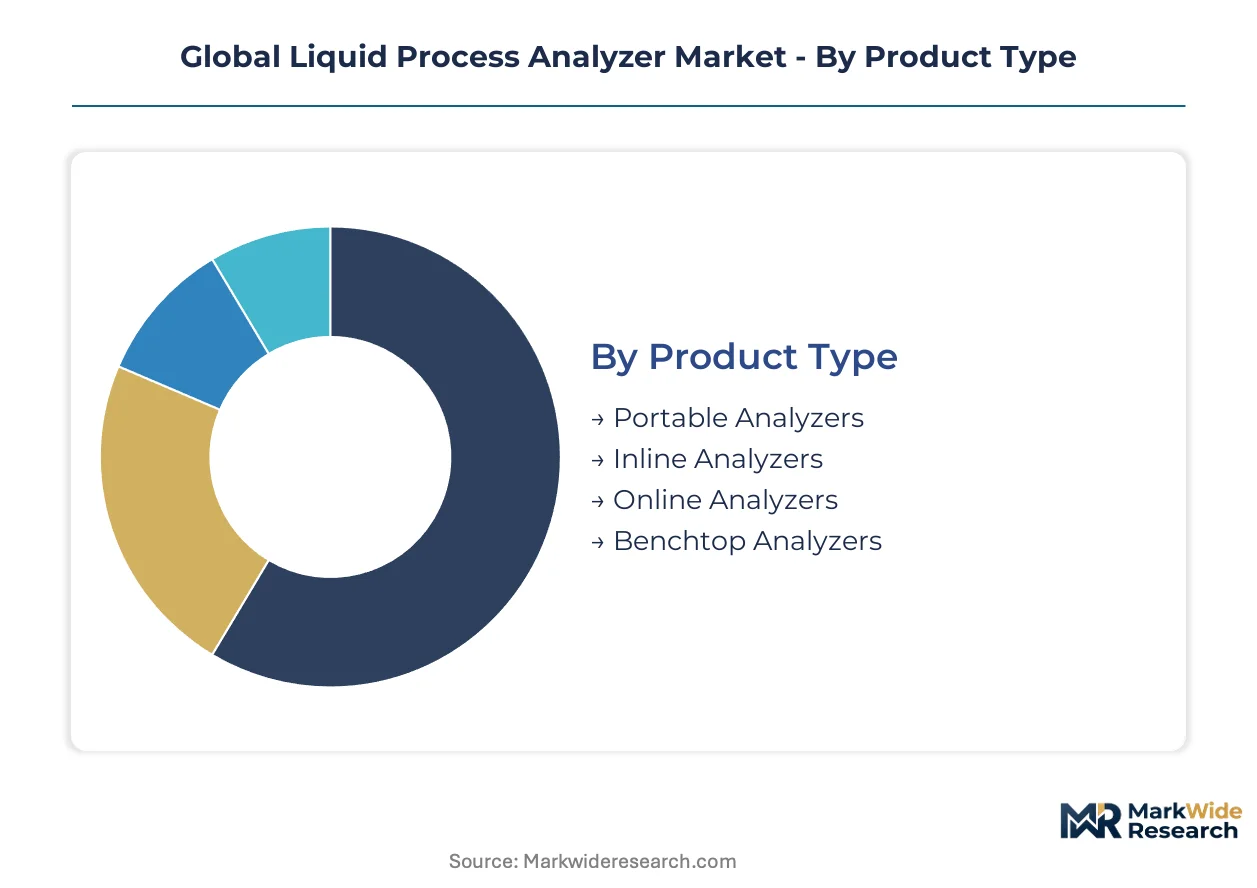
Liquid process analyzer segmentation reveals distinct capital-intensity tiers across product architectures, with inline systems demanding infrastructure investment while portable units serve spot-check applications. Technology choices separate volume-driven electrochemical deployments from spectroscopic premiums in multi-parameter environments.
Product Type:
Capital requirements vary dramatically across analyzer form factors, with permanent installations demanding utility integration versus mobile units requiring minimal infrastructure.
- Inline Analyzers:These systems integrate directly into process piping for continuous measurement without sampling delays. Water treatment utilities in Germany and China favor inline pH and dissolved oxygen sensors for real-time contaminant detection under tightening EPA and MEE discharge rules.
- Portable Analyzers:Battery-operated handheld units enable spot-checking across multiple process points. Environmental monitoring agencies in India deploy portable units for field verification of industrial discharge compliance where fixed infrastructure remains uneconomical.
- Online Analyzers:Automated sampling systems with rapid analysis cycles bridge continuous and laboratory workflows. Petrochemical processors on the US Gulf Coast utilize online configurations for intermediate product quality gates.
- Benchtop Analyzers:Laboratory-grade precision instruments for offline reference testing. Academic research institutes in Switzerland and Singapore specify benchtop Raman systems for bioreactor calibration protocols.
Inline analyzers absorb the bulk of installed capacity; portable analyzers are expanding most quickly in emerging enforcement regimes.
Technology:
Technology selection tracks measurement complexity requirements, with simpler electrochemical methods dominating volume and advanced spectroscopic techniques capturing premium applications.
- Electrochemical Sensors:pH, conductivity, and dissolved oxygen probes utilizing ion-selective electrodes. These sensors occupy the largest technology share by volume due to lower capital cost and established calibration protocols across chemical production facilities.
- Spectroscopy:UV-Vis and infrared systems enabling simultaneous multi-parameter detection. Food and beverage producers in the Netherlands and Germany command margin premiums where contaminant screening replaces sequential testing methods.
- Laser Spectrometry:Non-contact measurement using tunable diode laser absorption spectroscopy. Pharmaceutical manufacturers in Switzerland prioritize laser systems to eliminate contamination pathways in sterile vaccine processing environments.
- Chromatography:Separation-based analysis for complex mixture identification. Petrochemical laboratories retain gas chromatography for hydrocarbon speciation despite displacement pressure from laser methods.
- Nuclear Magnetic Resonance:Molecular structure determination for research-grade applications. Biotechnology firms in Singapore deploy benchtop NMR for metabolite quantification in cell culture media.
Electrochemical sensors retain the largest installed base; laser spectrometry is climbing the fastest as pharmaceutical manufacturers eliminate sample extraction.
Application:
Application segmentation aligns with regulatory enforcement intensity and process criticality, with water and pharmaceutical sectors driving precision requirements.
- Water Treatment:Municipal and industrial effluent monitoring for regulatory compliance. Utilities across the United States upgrade continuous monitoring systems under EPA effluent guidelines mandating redundant analyzer architectures.
- Pharmaceuticals Manufacturing:In-process monitoring for sterile drug production. Vaccine producers deploy inline Raman probes for real-time glucose and lactate tracking in bioreactor environments.
- Petrochemical Processing:Hydrocarbon concentration and quality control in refining operations. US Gulf Coast refineries prioritize analyzer interoperability over single-source accountability in procurement decisions.
- Food & Beverage Production:Contaminant detection and quality assurance in processing lines. European facilities upgrade to laser-induced breakdown spectroscopy to meet ECHA documentation demands without batch sampling delays.
- Paper & Pulp Analysis:Chemical recovery and effluent monitoring in fiber processing. Pulp mills in Finland and Sweden utilize inline conductivity sensors for white liquor composition control.
Water treatment absorbs the bulk of installed capacity; pharmaceuticals manufacturing is gaining share fastest under sterility assurance mandates.
End User:
End-user segmentation reflects divergent procurement authority, with industrial facilities prioritizing integration and agencies emphasizing portability.
- Chemical Production Facilities:Continuous process control and discharge compliance in specialty and commodity chemical manufacturing. German and Dutch producers document contaminant profiles at ppb thresholds under REACH registration requirements.
- Oil Refineries:Hydrocarbon processing quality control and environmental monitoring. Refineries unbundle analyzer hardware from service contracts, compressing vendor margins on installation and calibration.
- Biotechnology Firms:Cell culture monitoring and bioprocess optimization. Singapore-based vaccine producers drive adoption of non-contact measurement technologies for sterile processing.
- Environmental Monitoring Agencies:Regulatory enforcement and ambient water quality surveillance. India's Central Pollution Control Board mandates first-time continuous monitoring for textile and tannery clusters.
- Academic Research Institutes:Method development and reference standard calibration. Swiss research centers pioneer Raman spectroscopy integration for bioreactor monitoring workflows.
Chemical production facilities retain the largest analyzer inventory; environmental monitoring agencies are expanding most quickly under new enforcement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon and specialty glass manufacturing clusters in Germany anchor European supply chains for optical sensor components used in spectroscopic analyzer modules.
United States
Petrochemical processors along the US Gulf Coast drive demand for redundant continuous monitoring systems under EPA effluent guidelines mandating real-time discharge tracking. The EPA's National Pollutant Discharge Elimination System compels Texas and Louisiana refineries to upgrade legacy 4-20mA infrastructure with digital platform analyzers. Houston-area procurement teams prioritize interoperability over single-source vendor relationships.
Germany
Specialty chemical producers in the Rhine-Ruhr industrial corridor document contaminant profiles at ppb thresholds to satisfy ECHA REACH registration requirements. The EU Water Framework Directive enforcement forces North Rhine-Westphalia facilities toward ten-year data retention capabilities. BASF and Bayer cluster sites in Ludwigshafen deploy laser-induced breakdown spectroscopy to eliminate batch sampling delays.
China
Domestic chemical producers in the Yangtze River Delta source GB-calibrated analyzers for discharge permitting compliance under tightened MEE surface water quality standards. The Ministry of Ecology and Environment mandates real-time monitoring for pharmaceutical manufacturers in Jiangsu and Zhejiang provinces. Shanghai Pudong biotech parks deploy inline Raman probes for bioreactor glucose tracking.
Switzerland
Vaccine producers in the Basel pharmaceutical cluster prioritize non-contact laser spectrometry to eliminate contamination pathways in sterile processing environments. Swissmedic sterility assurance mandates drive adoption of inline measurement technologies for bioreactor monitoring. Novartis and Roche manufacturing sites deploy tunable diode laser absorption systems for real-time metabolite quantification.
India
Textile and tannery clusters in Tamil Nadu face first-time continuous monitoring mandates from the Central Pollution Control Board under expanded enforcement protocols. The CPCB's zero liquid discharge requirements compel Tiruppur dyeing units to install inline pH and dissolved oxygen sensors. Environmental monitoring agencies deploy portable analyzers for field verification where fixed infrastructure remains uneconomical.
Global Liquid Process Analyzer Market Competitive Landscape
Global majors compete with regional champions across digital platform integration and electrochemical sensor module supply. The vendor base separates into three tiers: diversified industrial conglomerates with captive transmitter assembly, mid-scale specialists concentrated in spectroscopic instrumentation, and Asian module producers scaling electrochemical cell output. Consolidation pressure intensifies as petrochemical buyers unbundle hardware from service contracts and standalone sensor suppliers offer API-first data architectures.
Within the diversified industrial tier, Emerson Electric Co. and ABB Ltd. exemplify vertical integration strategies spanning transmitter and sensor assembly, while Endress+Hauser AG represents the European precision instrumentation archetype with integrated digital platform positioning. These three anchors demonstrate how protocol compatibility and backward integration into electrochemical module production sustain pricing power against standalone competitors.
| Leading Market Players |
|---|
| Emerson Electric |
| ABB |
| Endress+Hauser |
| Yokogawa Electric |
| Siemens |
| Thermo Fisher Scientific |
| Mettler-Toledo |
| Teledyne Technologies |
| Honeywell International |
| Others |
Supply & Pricing Matrix
Specialty glass and high-purity silicon substrate costs cascade from German optical component foundries through three distinct pricing tiers, with electrochemical sensor modules anchoring economy positioning while laser spectrometry systems capture premium multiples at pharmaceutical buyers.
Pricing Analysis
Warranty and calibration service bundling separates incumbent vendor pricing from emerging API-first competitors, with Emerson and ABB commanding 40-60% attach rates on multi-year service contracts versus standalone hardware discounts. Three-tier pricing structure across premium spectroscopic, standard online, and economy electrochemical levels tracks certification complexity and protocol compatibility rather than raw measurement precision. Cost compression in the electrochemical tier intensifies as Asian module producers scale output, squeezing margins for transmitter assemblers lacking backward integration. Environmental monitoring agencies exhibit highest price sensitivity, while vaccine manufacturers under Swissmedic mandates absorb premium positioning for non-contact measurement systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale petrochemical and water utility demand, while distributor networks serve spot-check portable analyzer procurement across fragmented environmental agency budgets. Electrochemical cell manufacturing concentrates in China, South Korea, and Japan, with specialty optical components sourcing from German and Swiss precision glassworks. Raw material dependencies span rare-earth dopants for laser diodes, ion-selective electrode membranes, and corrosion-resistant housing alloys. Single-source vulnerability in electrochemical sensor modules creates procurement risk for transmitter integrators lacking captive cell production. Distribution runs through authorized service partners for calibration-dependent installations, though API-first architectures are disintermediating traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical sensor module capacity constraints in East Asian foundries prop pricing power for vertically integrated transmitter assemblers, creating a supply-constrained market structure favoring incumbents with captive component sourcing.
For Market Incumbents: Cement protocol compatibility advantages by embedding digital twin data architectures into enterprise asset management platforms before standalone sensor suppliers achieve API standardization. Deepen backward integration into electrochemical cell production to defend against Asian module producer forward integration. Prioritize certification investment for GB, EPA, and EU calibration protocols to maintain multi-regional pricing premiums. For New Entrants and Emerging Players: Capture India's Central Pollution Control Board enforcement wave by targeting Tiruppur textile and tannery clusters with portable analyzer plus calibration service bundles where fixed infrastructure remains uneconomical. Penetrate Switzerland and Singapore vaccine manufacturing with inline Raman probe offerings that displace offline chromatography workflows. Pursue white-label API-first data architectures for US Gulf Coast refineries prioritizing interoperability over single-source accountability. For Investors and Strategic Acquirers: Petrochemical procurement teams unbundling hardware from service contracts is the leading indicator that standalone sensor suppliers with software-centric business models will command valuation premiums over traditional integrated vendors. Target mid-scale spectroscopic specialists with digital platform capabilities and regional calibration service networks. Watch for laser spectrometry technician scarcity forcing acquisition premiums for firms with specialized training infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochemical Module Production | Captive sensor cell manufacturing insulates Emerson and ABB from Asian supply concentration. |
| Digital Twin Platform Integration | Analyzer data streaming into enterprise asset management creates predictive maintenance revenue at ABB. |
| GB Calibration Protocol Certification | Domestic Chinese chemical producers under MEE mandates require GB-compliant analyzers for discharge permitting. |
| Laser Spectrometry Technician Training Infrastructure | Swiss and Singapore vaccine manufacturers face scarcity of specialized calibration expertise for Raman systems. |
| API-First Data Architecture Development | US Gulf Coast refineries prioritize interoperability over single-source vendor relationships in procurement decisions. |
Research Methodology
Multi-period observation of EPA enforcement actions, EU Water Framework Directive implementation timelines, and MEE surface water standard revisions anchored the trend analysis, supplemented by interviews with plant engineers at chemical production facilities, procurement leads at water treatment utilities, aftermarket service heads at instrumentation distributors, and regulatory affairs specialists at pharmaceutical manufacturers. Secondary validation drew from EPA effluent guideline databases, ECHA REACH registration filings, SEC 10-K disclosures from diversified industrial conglomerates, and customs trade data for electrochemical sensor module flows. Bottom-up installed base estimates triangulated against top-down market sizing from capital expenditure tracking at major end-user facilities.
Segment-weighting across product architecture, measurement technology, application vertical, and end-user procurement authority informed the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, regulatory compliance deadline clustering, and digital platform adoption curves. Industry-specific forecast inputs included laser spectrometry displacement rates in pharmaceutical quality control and electrochemical sensor volume scaling in Asian manufacturing hubs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA effluent guideline enforcement intensity, EU Water Framework Directive revision scope, and MEE surface water standard implementation pace across Chinese provincial jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Chromatography Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Paint Tester Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Global Residue Testing Market