
 2D Chromatography Market | 2026-2036
2D Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
2D Chromatography Market Analysis
A shift from single-source to multi-source instrument supply is rebalancing procurement strategies across pharmaceutical and biotechnology laboratories. Agilent Technologies leverages its installed base of LC-MS platforms to sustain service revenue streams in regulated environments. Waters Corporation anchors its competitive position through specialized UPLC technology leadership in peptide mapping applications. Thermo Fisher Scientific dominates the high-end segment with integrated Orbitrap mass spectrometry workflows that reduce method development time.
Two-dimensional chromatography couples two independent separation mechanisms—typically combining reversed-phase liquid chromatography with ion exchange or size exclusion—to resolve complex mixtures exceeding the peak capacity of single-dimension systems, achieving resolving powers above 10,000 peaks per analysis. Pharmaceutical analysis applications command the largest share of current demand as biosimilar developers require orthogonal separation for regulatory filing packages. Mass spectrometry detection technology represents the fastest-growing segment within instrument configurations, driven by its essential role in metabolite identification and host cell protein analysis.
FDA guidance on analytical procedures validation and EMA quality requirements for biological medicines directly shape instrument qualification protocols and software compliance features demanded by end users. ISO 17025 accreditation standards for testing laboratories further tighten performance documentation requirements, creating barriers for unvalidated detection technologies. Stakeholders must monitor evolving pharmacopoeial standards for multidimensional methods as regulatory agencies harmonize acceptance criteria across major jurisdictions.
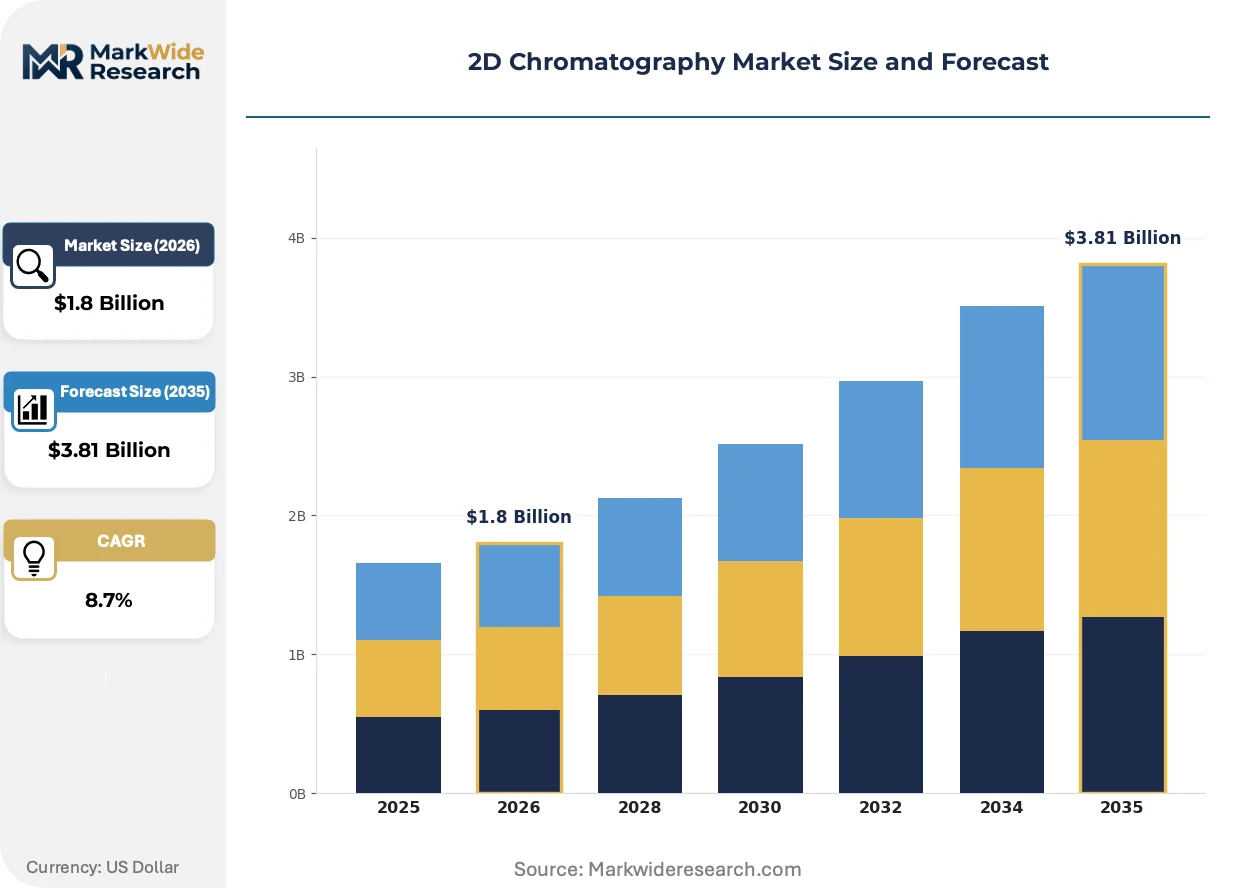
Market Dynamics
Orthogonal separation workflows are compressing method development cycles as biopharma labs face simultaneous pressure from FDA biosimilar guidance and internal pipeline acceleration targets. This structural tension between regulatory stringency and R&D velocity is forcing procurement teams to prioritize detection sensitivity over capital cost in instrument selection.
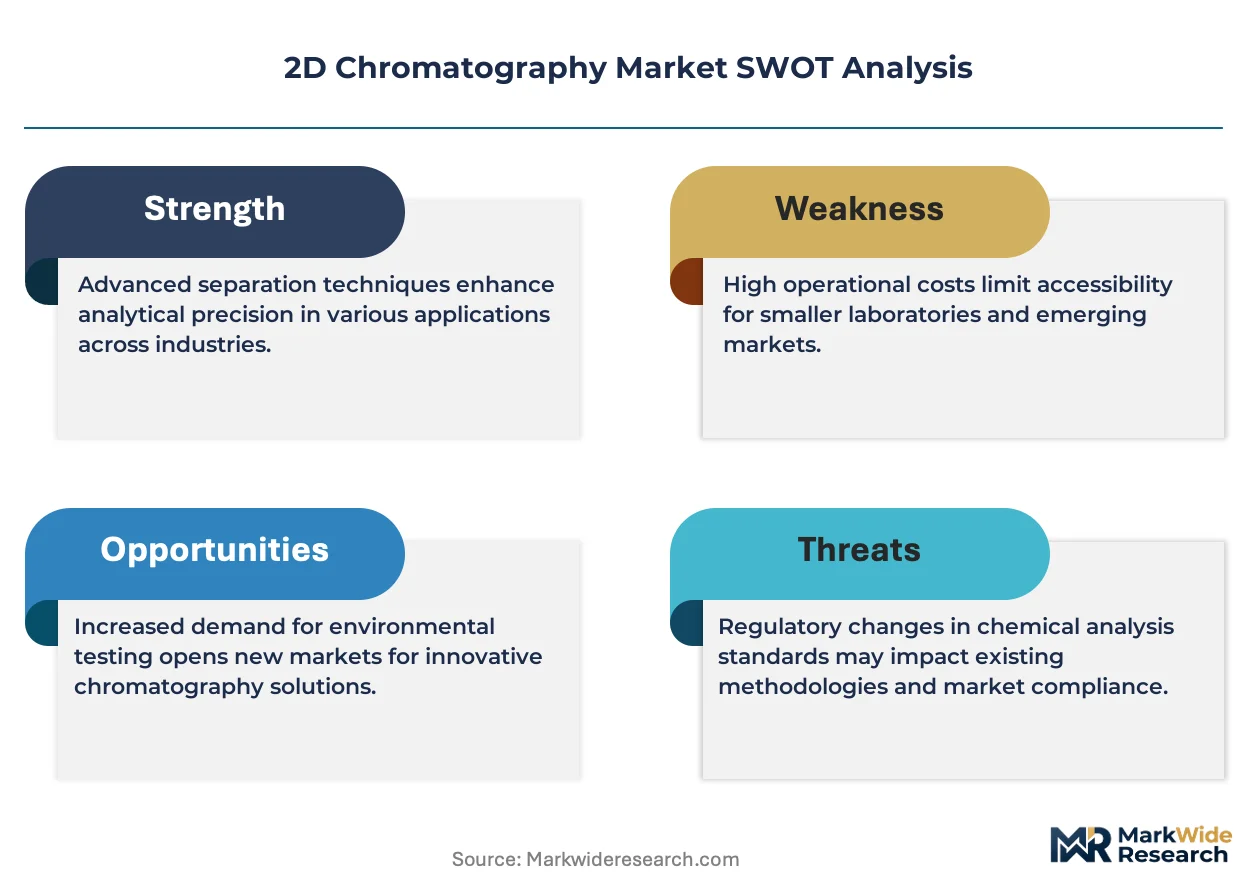
Growth Catalysts
- EMA Quality Requirements:Biological medicines guidelines mandate orthogonal separation for impurity profiling, compelling contract manufacturing organizations to upgrade legacy single-dimension systems.
- Peptide Mapping Workflows:Biosimilar developers require UPLC-ion exchange coupling to demonstrate structural equivalence in regulatory filings, driving replacement demand in quality control laboratories.
- Host Cell Protein Analysis:Mass spectrometry detection configurations are becoming standard for bioprocess validation, with biopharma clusters in Massachusetts and Basel generating concentrated procurement activity.
Market Restraints
- Helium Supply Volatility:Gas chromatography second-dimension configurations face input cost instability from concentrated Qatari and Algerian helium production.
- Method Validation Burden:FDA analytical procedures validation requirements impose 12-18 month qualification timelines that freeze capital budgets during regulatory review periods.
- Single-Vendor Service Lock-in:Proprietary software architectures from dominant instrument suppliers create switching costs that suppress price competition in regulated environments.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building ISO 17025-accredited facilities requiring multidimensional platforms for export compliance.
- Cell and Gene Therapy:Viral vector characterization workflows represent an emerging application segment with unresolved separation challenges for aggregate and empty-full particle analysis.
- AI-Assisted Method Development:Machine learning algorithms trained on historical chromatographic data are converging with instrument control software to reduce optimization cycles from weeks to days.
Industry Challenges
- Multidimensional Method Expertise Gap:Universities produce analytical chemists trained primarily on single-dimension systems, forcing employers to fund 6-12 month internal certification programs.
- LIMS Integration Complexity:Enterprise laboratory information management systems require custom middleware development to capture the expanded data matrices generated by two-dimensional workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2D Chromatography Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HPLC, GC, TLC, SFC Application: Pharmaceutical Analysis, Environmental Testing, Food Safety, Clinical Research End User: Pharmaceutical Companies, Academic Institutions, Research Laboratories, Biotechnology Firms Technology: UV-Vis Spectroscopy, Mass Spectrometry, NMR Spectroscopy, Infrared Spectroscopy |
| Companies Covered | Agilent Technologies, Inc., Waters Corporation, Shimadzu Corporation, Merck KGaA, Thermo Fisher Scientific Inc., LECO Corporation, Restek Corporation, Danaher Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2D Chromatography Market Emerging Trajectories
Compact benchtop configurations are collapsing the traditional boundary between core facility and distributed analytical capacity. This hardware miniaturization is enabling new deployment models that bypass centralized service contracts.
Microfluidic valve interfaces are decentralizing second-dimension column selection, allowing individual researchers to switch between ion exchange, size exclusion, and hydrophilic interaction chemistries without core facility intervention. Academic proteomics labs at Johns Hopkins and ETH Zurich are piloting these configurations to reduce queue times for complex biological samples. The technology is compressing the traditional core facility bottleneck by distributing method control to end users.
REACH chemical registration requirements are expanding analytical disclosure obligations for pharmaceutical impurities, forcing manufacturers to document separation resolution down to 0.1% relative abundance. ECHA guidance on analytical method robustness is driving adoption of validated multidimensional workflows in European quality control operations. Generic drug manufacturers in Germany and Switzerland are responding by consolidating instrument qualification protocols across manufacturing sites.
Service contract unbundling is fragmenting the traditional five-year comprehensive coverage model into modular component subscriptions. Biopharma procurement teams in the Research Triangle Park cluster are negotiating separate agreements for hardware, software, and application support to align spending with project-phase needs. This purchasing behavior shift is most visible among mid-cap biotech firms managing milestone-dependent cash flows.
2D Chromatography Market Segmentation
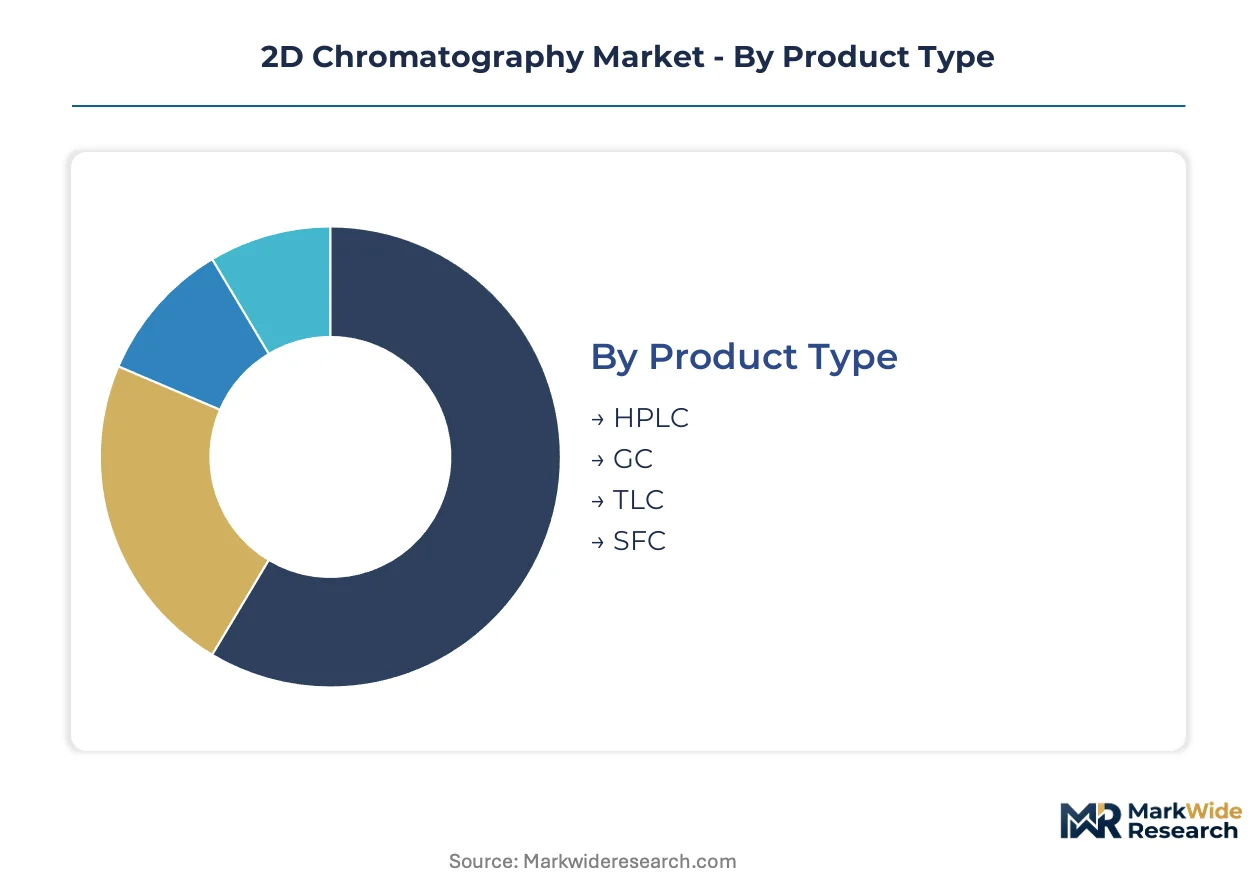
Two-dimensional chromatography systems fragment across four distinct classification axes, each governing procurement patterns and qualification requirements. Product type and detection technology determine capital intensity, while application and end-user categories shape software compliance features and service contract structures.
Product Type:
HPLC configurations dominate unit volume, while SFC systems command premium pricing tiers due to solvent cost advantages and green chemistry alignment.
- HPLC:Reversed-phase liquid chromatography paired with ion exchange or size exclusion delivers resolving powers exceeding 10,000 peaks per analysis. Pharmaceutical quality control laboratories in Massachusetts and Basel generate concentrated procurement for peptide mapping workflows under FDA and EMA biosimilar guidance.
- GC:Gas chromatography second-dimension configurations face input cost instability from concentrated Qatari and Algerian helium production, compressing margin structures for environmental testing applications despite strong detection sensitivity for volatile compounds.
- TLC:Thin-layer chromatography serves cost-sensitive screening applications in academic settings with minimal method validation overhead.
- SFC:Supercritical fluid chromatography leverages compressed carbon dioxide to eliminate toxic solvent disposal costs, attracting European manufacturers under REACH disclosure obligations.
Mature deployment sits with HPLC. Newer deployment is concentrated in SFC.
Application:
Pharmaceutical analysis commands the largest revenue share, while food safety applications are climbing the fastest as multiresidue pesticide screening requirements tighten.
- Pharmaceutical Analysis:Biosimilar developers require orthogonal separation to demonstrate structural equivalence in regulatory filings. Contract manufacturing organizations in Hyderabad and Bangalore are building ISO 17025-accredited facilities specifically for impurity profiling under FDA and EMA quality requirements.
- Environmental Testing:EPA methods mandate detection thresholds that single-dimension systems cannot reliably achieve for complex soil and water matrices, driving replacement cycles in certified laboratories.
- Food Safety:Multiresidue screening for pesticide and veterinary drug residues is gaining share fastest as import testing protocols harmonize across major jurisdictions.
- Clinical Research:Metabolomics applications require mass spectrometry coupling for biomarker discovery, though reimbursement uncertainty constrains hospital laboratory adoption.
Regulatory filing pressure concentrates demand in pharmaceutical analysis. Method standardization is advancing fastest in food safety.
End User:
Pharmaceutical companies anchor capital expenditure, while biotechnology firms are expanding procurement most aggressively as pipeline assets advance toward BLA submission.
- Pharmaceutical Companies:Quality control operations at originator and generic manufacturers drive replacement demand for legacy single-dimension systems. German and Swiss sites are consolidating instrument qualification protocols across manufacturing networks to satisfy ECHA guidance on analytical method robustness.
- Academic Institutions:Johns Hopkins and ETH Zurich proteomics labs pilot microfluidic valve interfaces to reduce core facility queue times, prioritizing publication velocity over regulatory compliance features.
- Research Laboratories:Cell and gene therapy developers require viral vector characterization workflows with unresolved separation challenges for aggregate and empty-full particle analysis.
- Biotechnology Firms:Mid-cap biotech firms in the Research Triangle Park cluster negotiate unbundled service contracts to align spending with milestone-dependent cash flows.
Consolidated procurement sits with pharmaceutical companies. Fragmented purchasing is expanding fastest among biotechnology firms.
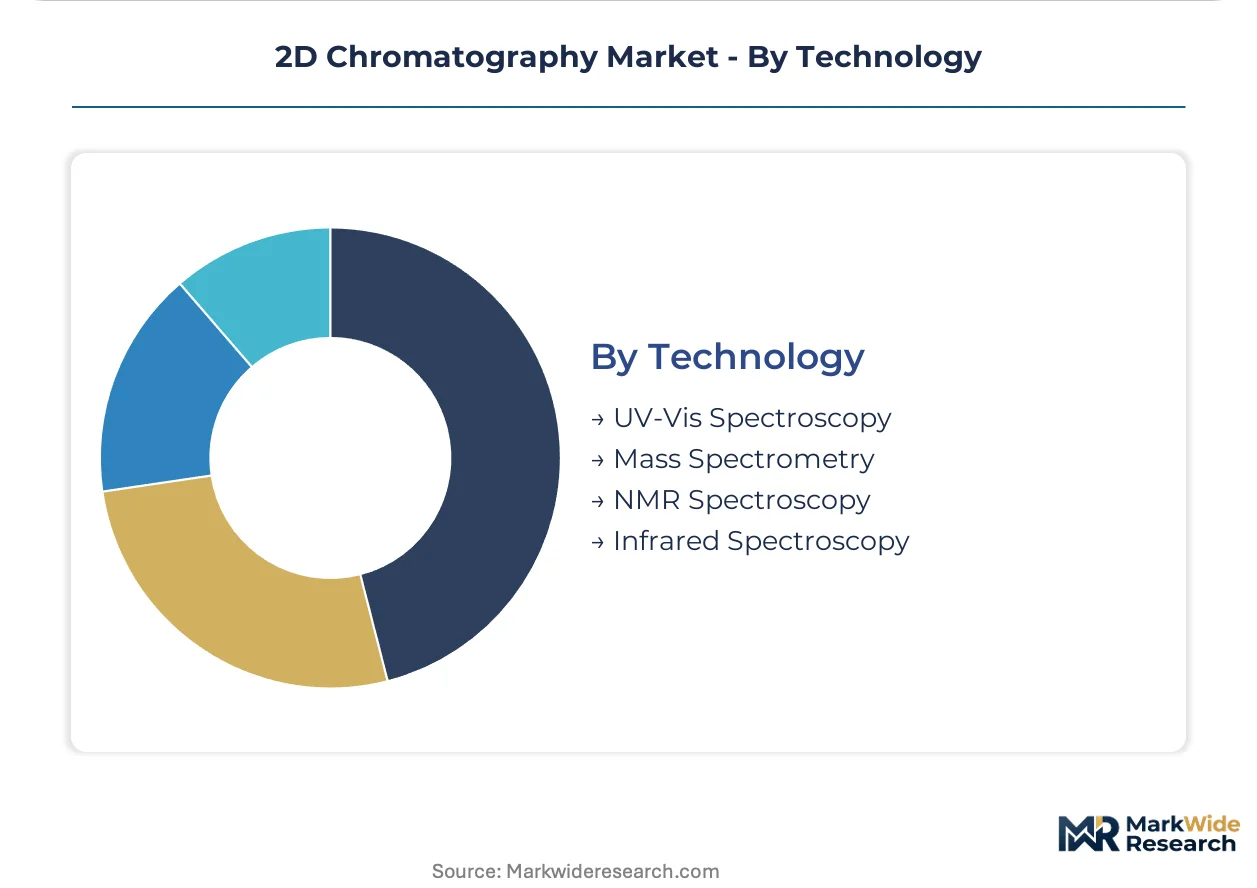
Technology:
Mass spectrometry detection claims the steepest expansion trajectory, while UV-Vis spectroscopy retains the largest installed base due to lower qualification burden.
- Mass Spectrometry:Orbitrap configurations reduce method development time through integrated workflows essential for host cell protein analysis and metabolite identification. Biopharma clusters in Massachusetts and Basel generate concentrated procurement activity for bioprocess validation.
- UV-Vis Spectroscopy:Diode array detection satisfies routine quality control requirements with 12-18 month shorter validation timelines than mass spectrometry alternatives, preserving capital budget flexibility during regulatory review periods.
- NMR Spectroscopy:Structural confirmation applications in academic settings leverage high-field magnets for absolute configuration determination despite substantial facility infrastructure requirements.
- Infrared Spectroscopy:Functional group identification supports forensic and materials science applications with minimal consumable costs.
Established qualification protocols favor UV-Vis spectroscopy. Detection sensitivity requirements are driving fastest adoption in mass spectrometry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharma R&D concentration in specific metropolitan clusters drives procurement intensity for two-dimensional chromatography systems. Regulatory filing requirements from FDA and EMA shape qualification protocols across manufacturing networks.
United States
FDA biosimilar guidance and host cell protein analysis requirements compel Massachusetts-based biopharma clusters to upgrade detection capabilities. EPA methods for environmental testing mandate thresholds that accelerate replacement cycles in certified laboratories. The Research Triangle Park cluster in North Carolina generates concentrated procurement from mid-cap biotechnology firms managing milestone-dependent capital deployment.
Germany
REACH chemical registration obligations expand analytical disclosure requirements for pharmaceutical manufacturers. ECHA guidance on method robustness drives consolidation of instrument qualification protocols across manufacturing sites. Basel-adjacent facilities in southern Germany anchor European demand for peptide mapping workflows under EMA biological medicines guidelines.
Japan
PMDA quality standards for biologics impel orthogonal separation adoption in Osaka and Tokyo pharmaceutical corridors. METI industrial policy supports analytical infrastructure upgrades for biosimilar export compliance. The Kansai region hosts concentrated proteomics research activity piloting microfluidic valve configurations.
Switzerland
Swissmedic requirements for impurity profiling mandate high-resolution platforms in Basel and Zurich quality control operations. Generic drug manufacturers consolidate validation protocols across manufacturing networks to satisfy European pharmacopoeial standards. The Basel biopharma cluster generates specialized demand for UPLC-ion exchange coupling in regulatory filing packages.
India
CDSCO export compliance requirements drive ISO 17025 accreditation investments among Hyderabad and Bangalore contract manufacturing organizations. PLI scheme incentives support analytical infrastructure buildout for biosimilar development. CDMOs in Telangana and Karnataka procure multidimensional platforms specifically for FDA and EMA filing support.
2D Chromatography Market Vendor Landscape
Portfolio diversification dominates the current landscape as established analytical instrument suppliers extend detection technology integration. The market structure concentrates around three strategic tiers: integrated platform providers with mass spectrometry workflows, specialized liquid chromatography vendors with UPLC technology leadership, and diversified life science conglomerates with broad installed bases. Competitive positioning hinges on proprietary software architectures that create service revenue lock-in, alongside method development time reduction through integrated hardware-software configurations.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. exemplify archetypes competing through detection sensitivity and regulatory compliance feature sets. Waters Corporation occupies a specialized position anchored in UPLC technology for peptide mapping applications. These three entities collectively represent the premium-tier procurement channel where pharmaceutical quality control laboratories prioritize validation documentation and service contract reliability over capital cost minimization.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Waters Corporation |
| Shimadzu Corporation |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| LECO Corporation |
| Restek Corporation |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply Flow & Price Mechanics
Helium spot price volatility from concentrated Qatari and Algerian production cascades through gas chromatography configurations into three-tier pricing stratification across premium, standard, and economy instrument tiers. Pharmaceutical quality control laboratories absorb premium pricing for validated Orbitrap-integrated workflows, while academic proteomics facilities face compressed margins on legacy UV-Vis configurations.
Pricing Analysis
High-volume HPLC unit shipments anchor the standard tier, while low-volume SFC systems capture premium margins through solvent cost advantages and REACH-aligned green chemistry positioning. Price differentiation separates FDA-validated mass spectrometry configurations from ISO 17025-accredited diode array alternatives, with certification tier and detection sensitivity as primary drivers. Pricing pressure stems from helium supply instability compressing GC margin structures, though biopharma procurement teams show lowest price sensitivity for host cell protein analysis applications where regulatory filing risk dominates capital cost considerations.
Supply Chain Analysis
Ocean freight cost fluctuations from Asia-Pacific manufacturing hubs to European and North American installation sites compress margin structures for instrument distributors managing project-based delivery timelines. Component sourcing draws from German precision valve manufacturers, Japanese detector suppliers, and Chinese machined housing fabricators, creating tariff exposure risk from concentrated Asian production. Distribution runs through authorized dealer networks with factory-trained service engineers, bypassing direct-to-laboratory channels to preserve qualification protocol integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 accreditation requirements erect a cost-of-compliance barrier that consolidates procurement among validated platform providers, filtering out unqualified detection technologies from regulated pharmaceutical environments.
For Market Incumbents: To counter microfluidic valve interface disruption from academic pilot programs at Johns Hopkins and ETH Zurich, Thermo Fisher and Agilent should deepen application support bundling in Basel and Massachusetts biopharma clusters while accelerating AI-assisted method development integration to compress optimization cycles below competitor reach. For New Entrants and Emerging Players: CDSCO export compliance requirements in India open a window for ISO 17025-accredited platform provision to Hyderabad and Bangalore CDMOs, with unbundled service contract modularity as the primary go-to-market angle against entrenched comprehensive coverage models. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized UPLC technology holders with peptide mapping workflow depth in European regulatory corridors, with long-term viability hinging on EMA biological medicines guideline harmonization as the signal to monitor for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Method Development Integration | Machine learning convergence with instrument control software reduces optimization cycles from weeks to days for biopharma labs. |
| Microfluidic Valve Interface Deployment | Decentralized second-dimension column selection bypasses core facility bottlenecks at Johns Hopkins and ETH Zurich proteomics labs. |
| ISO 17025 Accreditation Investment | Hyderabad and Bangalore CDMOs require accredited multidimensional platforms for FDA and EMA export filing compliance. |
| Service Contract Unbundling | Modular component subscriptions align spending with milestone-dependent cash flows for Research Triangle Park biotech firms. |
| Orbitrap Mass Spectrometry Workflow Expansion | Integrated detection configurations reduce method development time for host cell protein analysis in Massachusetts biopharma clusters. |
Methodological Framework
FDA 483 inspection observations, EMA quality guideline documents, and ISO 17025 accreditation registries formed the secondary backbone, supplemented by primary interviews with analytical chemistry directors, biopharma quality control managers, CDMO procurement leads, and academic core facility administrators. Bottom-up instrument shipment tracking from Massachusetts, Basel, and Hyderabad clusters combined with top-down pharmaceutical R&D expenditure analysis across the analysis window.
Historical trendline analysis of HPLC, GC, TLC, and SFC deployment patterns informed segmentation-level growth trajectory modeling across product type, detection technology, application, and end-user dimensions. CAGRs were derived from regression analysis of capital expenditure flows and replacement cycle compression factors, with peptide mapping workflow demand and host cell protein analysis regulatory mandates as chromatography-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-assisted method development would alter the outlook if machine learning integration timelines accelerate beyond instrument control software refresh cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Ultrasonic Testing Market